Stock in Focus: Is Epwin a cash machine?

Sales of UPVC doors, windows and cladding are likely to be a good proxy for the housing market, so the success of Epwin in its first year as a (re)listed company is unsurprising.
Epwin shares have climbed 36% over the last 13 months. This goes against the tendency of newly-floated businesses to deflate after their private owners have cashed out.
But can the strong start continue? It’s obviously a cyclical business, so at some point things will get difficult. That time is probably not upon us yet, however, if recent commentary on the housing market is any indication.

According to the National Association of Estate Agents, the average number of properties listed for sale with each agency rose by 25% to 55 in July, the highest level seen since summer 2013. Elsewhere, the Nationwide House Price Index reported a 0.4% rise in average prices in July, equivalent to a 3.5% annual increase.
In the rental market, a shortage of supply is also pushing up rents, which rose by 4.6% in July compared to July 2014, according to property firm Countrywide.
In need of maintenance
In Epwin’s recent results, the firm emphasised that the UK’s housing stock has a significant maintenance backlog. Epwin cited Office for National Statistics figures suggesting that of the UK’s 27.8m homes, only 60% are maintained to a satisfactory level.
If the UK economy continues its gradual recovery, some of this backlog could be addressed. Epwin believes that there is “a significant pent up demand within the RMI [Retail, Maintenance and Improvement] space.”
One final point is that Epwin’s exposure to both the rented and owner-occupied sectors is attractive, in my view. Under various brands, the firm’s products are sold to homeowners, private landlords, house builders and operators of social housing.
Unlike estate agents, for example, Epwin shouldn’t suffer from a demographic shift away from home ownership and towards renting.
Do the numbers stack up?
While I have a cautious view towards housebuilders and believe it is too late to buy into that sector, I’m more open to investing in Epwin. I believe the firm could enjoy strong trading for a number of years yet, a view shared by Small Cap Editor Paul Scott.
Epwin scores well against Stockopedia’s algorithms, too. The shares boast a StockRank of 99, with both Quality and Momentum ranks of 90 or more.
Open and shut value?
Epwin’s ValueRank of 77 is reassuring. A triple whammy of high ranks suggest that the firm may have the qualities of a Super Stock, capable of delivering sustained outperformance.
The cyclical nature of the business will inevitably put a damper on such gains eventually, but at present the picture is quite appealing:
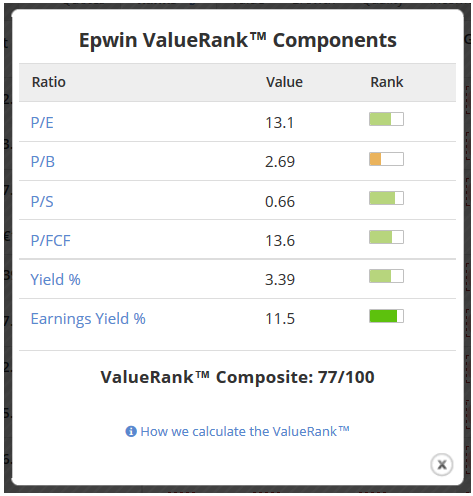
Although Epwin isn’t a traditional value play. It doesn’t have a low P/E or a low valuation relative to its assets, but it does have other value qualities. A trailing price-to-free cash flow ratio of 13.6 is very respectable, as is an earnings yield (EBIT/EV) of 11.5%.
The shares’ trailing yield of 3.4% is expected to rise to more than 4.5% this year, highlighting this firm’s cash-generating credentials.
The only risks I’d highlight are those relating to Epwin’s cyclical nature. The shares are currently valued at 4.4 times tangible book value. As a result, asset backing is unlikely to provide much support if earnings fall away.
These shares could really crumble in a recession, as fixed costs from factories and staff could remain relatively high.
Quality plastic?
A good quality cyclical firm needs to be able to cash when market conditions are strong. That means rising profit margins, rising returns on capital and plenty of free cash flow.
Although we only have access to Epwin’s accounts for the last three years, the signs are good. Net debt has fallen from £23.2m at the end of 2012 to become net cash of £1.1m at the end of 2014.
Last year’s dividend payout of 4.24p was covered more than twice by free cash flow per share of 9.68p, while the firm’s operating margin rose from 3.2% in 2012 to 7.4% in 2014.
Overall, Epwin looks good from a quality viewpoint. This conclusion is supported by a Piotroski F-Score of 8, which would probably be a perfect 9, if the firm hadn’t raised funds by floating last year.
However, I do have a couple of reservations.
Firstly, last year’s rise in operating margin appears to have come from falling costs, not rising sales. Epwin’s sales rose by just 1.6% last year, and have fallen by 12% since 2012. Top-line growth is expected to resume this year, and in my view this is essential. If sales aren’t rising at this stage in the cycle, I’d see that as a warning flag.
My second reservation is that aside from some established brands, this firm doesn’t have much of a defensive moat. There are plenty of UPVC window manufacturers, and most of them are perfectly competent. For this reason, chasing Epwin shares to a high valuation could be risky.
Solid momentum
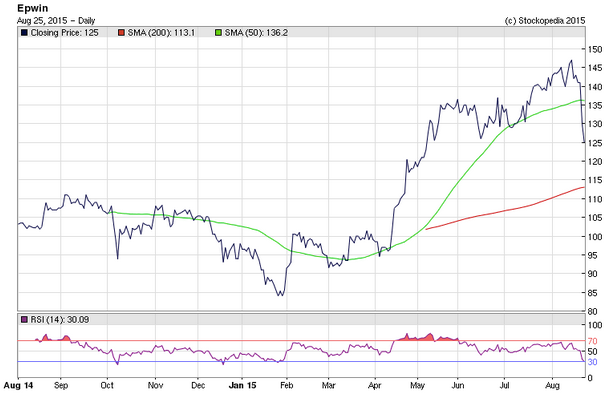
Epwin appears to be reasonably priced on current forecasts. Based on the last seen share price of 138p, current broker forecasts give a 2015 forecast P/E of 11.8, falling to 11.0 in 2016.
Price momentum is strong. The 50-day moving average (dMA) is 120% of the 200dMA and showing plenty of relative strength.
Earnings momentum is slightly less clear.
Although Epwin’s last results were 4.4% above forecasts, consensus estimates have been unchanged now for more than three months. One reason for this, of course, is that Epwin is a small firm. Broker coverage is limited to two smallish firms, so updates will be limited.
A window of opportunity?
Like most UK small companies, Epwin is inexplicably slow at publishing its accounts. The firm’s interim results for the six months to 30 June were not published until 25 September last year. This suggests investors could have another month to wait.
In the meantime, my view is that Epwin is likely to deliver continued growth over the next year or so. Of course, this is only my opinion -- not advice -- and I’d suggest investors DYOR, as always. If you’d like to pitch in with your view on Epwin, please leave a comment below.
Disclosure: Roland has no financial interest in Epwin.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Hi Tonygervis
14k to me seems a large amount of dollar in this company.
I hope its the small change from a lottery win!
However I'm bored with technical I see a stock rate of 98 when it goes..I go.
he follows logic very well, but does the market. I have some 14K in Epwin but could well be selling this Friday as w ends are notoriously bad in uncertain markets.
On house prices August was only up 0.3% making it annual 3.2% rise. Also I read double glazing sales are down 10% over the last year. I was tempted to buy some Epwin (LON:EPWN) shares on Monday but did not, results will be interesting as several peers have reported falling or flat profits. Housebuilding in the last year has surprisingly fallen. With events in China the big question is will the recovery continue or are we heading for a recession.