Stock in Focus: James Latham

I suspect that even the canny investors who bought shares in timber merchant James Latham in the aftermath of the credit crisis did not expect them to rise by 560% in six years.
 This firm’s success has made it one of the most successful and most highly-ranked stocks in the Stockopedia universe. Latham boasts a StockRank of 97 and was one of Stockopedia founder Ed Croft’s top 10 stocks for 2015.
In this article, I’m going to look more closely at the financial characteristics that have made this stock such a successful investment and ask whether it still has upside potential.
A family firm
James Latham started trading as a timber merchant in 1757, importing hardwoods into Liverpool.
It has since become one of the UK’s importers and distributors of wood-based sheet materials, timber and flooring to the building trade. Today, Latham has 10 sites spread across the UK.
Since its foundation, the firm has remained under family control.
The five members of the family whose shareholdings are disclosed on the company website own 17.5% of the company’s shares. Four of these family members currently sit on the board of this £138m AIM-listed firm. Chairman Peter Latham has worked for the firm for 41 years and been on the board since 1983.
Many esteemed investors such as Lord John Lee like to back family-owned firms because the management’s interests are usually closely aligned with those of shareholders. Sustainable growth and a progressive dividend are often priorities, although it’s always worth watching out for excessive remuneration (which doesn’t seem to be a problem here).
Is there any value left?
After delivering a capital return of 315% in five years, you might not expect shares in James Latham to be very good value.
It’s certainly true that Latham’s ValueRank of 69 is the lowest of its ranks, but the shares’ valuation is underpinned by strong free cash flow generation.
Latham currently trades on a trailing P/E of 14.4, or 17.0 if you use the company’s own adjusted figure, which excludes an exceptional £1.8m pension credit. This looks demanding but is expected to fall to 16 for the 2014/15 financial year, which ended on 31 March.
Latham actually looks less expensive when you measure cash flow. According to Stockopedia, the firm’s shares trade on just 14.7 times trailing free cash flow.
Capex has been low over the last couple of years, and 82% of last year’s operating cash flow was converted into free cash flow. The firm’s dividend has been consistently covered by free cash flow in recent years:
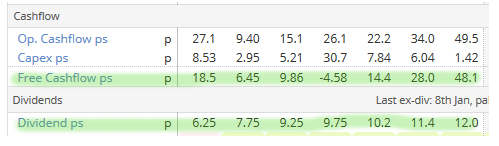
Indeed, Latham’s dividend has grown by an average of 12.8% since 2009, helping it qualify for the Dividend Achievers Screen. Despite this, the firm’s rocketing share price means that the trailing yield is only 1.75%.
Far more impressive is the earnings yield, which is currently 9.5%. Investors sometimes calculate earnings yield by simply inverting the P/E ratio, but Stockopedia uses the Greenblatt definition, enterprise value divided by operating profit.
The advantage of this is that unlike the P/E, it includes the effect of net cash and debt while excluding interest and tax costs. This provides a more neutral and complete view of a firm’s profitability for prospective buyers.
High quality
James Latham’s QualityRank of 92 helps justify its strong valuation, in my view. The firm also appears in the Screen of Screens, which has outperformed the FTSE 100 by 35% over the last two years.
A Piotroski F-Score of 8 out of a possible nine highlights Latham’s cash generation and balance sheet strength. This has improved over the last year, as net cash has risen by 16% to £10.6m. Latham’s pension deficit -- a risk previously flagged up by small cap editor Paul Scott has also now been reduced to a negligible level. As Paul comments, this is good news for shareholders, as more cash may now be available for dividends.
Although Latham’s five-year average operating margin of 5.9% is quite good for a business of this kind, it will be worth looking closely at the firm’s margins when the 2015 results are published this week.
Latham’s year-end trading update implied that profits did not rise as fast as revenue last year. This suggests that some margin pressure, perhaps rising costs, may be creeping in.
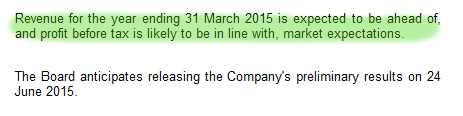
It’s also worth noting that while Latham’s operating margin and return on capital employed have risen since 2009, this is partly a reflection of the cyclical nature of the business. As the housing market has taken off, so have Latham’s sales and profit margins.
However, this cycle will reverse at some point, so it’s probably wise to use a multi-year average of ROCE to value Latham’s business, not single-year figures.
Momentum
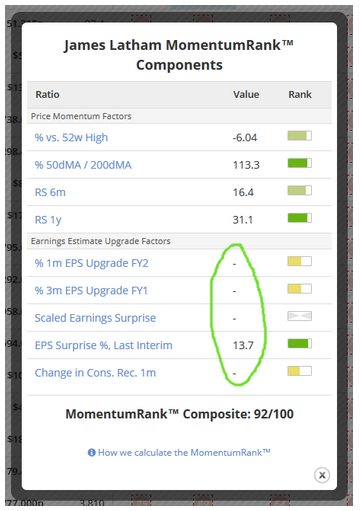
Almost every company connected with the housing market is enjoying strong momentum. Latham is no exception. The company currently has a MomentumRank of 92 and qualifies for two momentum screens, Tiny Titans and the Josef Lakonishok Momentum Screen.
Both of these screens have delivered returns of more than 40% over the last two years, compared to just 6% for the FTSE 100.
On a technical level, Latham’s 50-day moving average is currently 113% of the 200-day moving average. The firm’s 1-year relative strength reading of 31.1 suggests Latham could continue to outperform.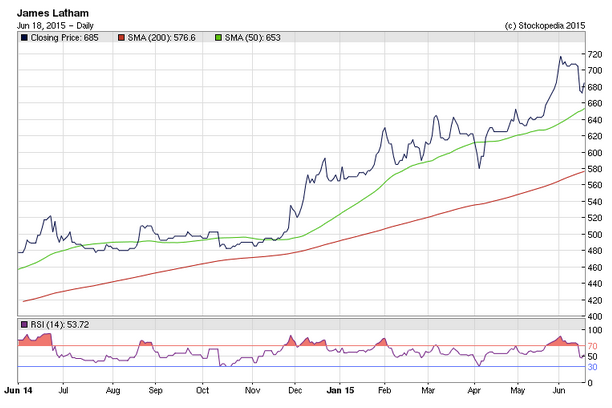
Latham’s MomentumRank is mainly influenced by price action, as broker coverage of the firm is limited to one analyst, and updates are rare. This means that factors such as EPS estimate upgrades are not included in the MomentumRank calculation:
Outlook
Given the booming state of the housing market, further progress seems likely for Latham.
The shares have fallen back from their all-time high of 729p recently, and could move further when the firm’s 2014/15 results are published this week.
For anyone trying to buy and sell Latham shares in size, some patience and flexibility may be required. The stock is illiquid, with an exchange market size of just 200 shares and a 3-month average daily volume of only 9,200.
There’s also the lingering risk that interest rates could rise and put the brakes on the housing market. So waiting for temporary pullbacks could be a smart strategy.
Of course, this is only my opinion, not a recommendation. DYOR as always, and please feel free to share your views in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Solid results from James Latham (LON:LTHM) today as expected, confirmed my original view (in the article) that the valuation remains quite reasonable, as long as the housing market doesn't slow down too much.
.
Very useful-good piece. It isn't Lord John Lee by the way-but we know who you mean. Maybe put John in parenthesis.
Anyway -I'm sure the Board family members are not overly fussed on salaries given their dividend receipts.