The Week Ahead (19-23 Jan): GDP beats expectations, will earnings follow?

Welcome to The Week Ahead. On Thursday, we learned that the UK economy itself beat expectations in November, printing GDP growth of 0.3%. That beat forecasts of 0.1% and erased the 0.1% decline seen in October.
Perhaps more significantly, we also learned that the German economy grew by 0.2% in 2025, after two straight years of recession.
This data is backward-looking, of course, and neither the UK nor German economies seem likely to deliver vigorous growth in 2026. But modest growth is certainly better than the alternative.
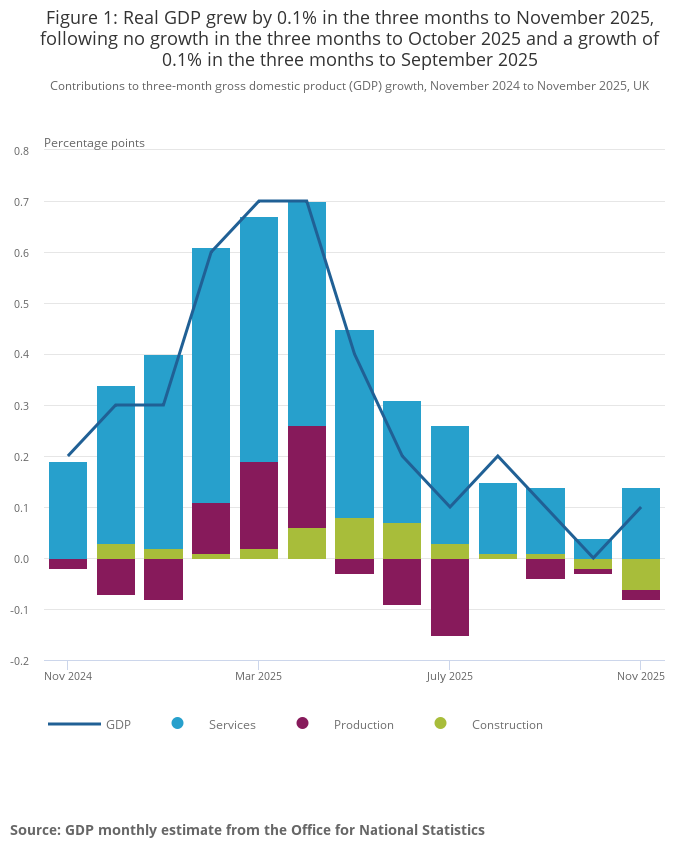
Source: Office for National Statistics
Company news so far this year has suggested that companies operating in economically-sensitive sectors such as retail and hospitality are enjoying mixed fortunes.
While post-Christmas updates from pub chains Mitchells & Butlers and Fuller, Smith & Turner have been relatively upbeat, reports from retailers have been a little more mixed.
The housing market is another area where commentary has remained cautious. FTSE 100 builders Persimmon and Taylor Wimpey both managed to sell more homes last year, despite uncertainty around the impact of November’s Budget. However, social housing and build-to-rent specialist Vistry suffered a fall in output as its partners waited for clarity on government plans (and funding).
Turning to secondhand homes and lettings, London-focused small-cap estate agency M Winkworth warned on profits on Wednesday, blaming a "temporary slowdown in activity". This was followed on Thursday by a cut to broker forecasts for Winkworth’s larger London rival Foxtons.
My overall impression is that homebuyer activity may be stabilising, but is not exactly on fire.
During the coming week, UK economic data is expected to include house prices, inflation and unemployment. These could provide further colour on whether the economy is heating up, cooling down or simply stagnating.
Turning to company news, next week will see a raft of post-Christmas updates from major high street operators.
Retailers B&M, JD Sports Fashion, Currys and Primark owner ABF (which has already warned on profits) are all due to report.
In the adjacent sector of hospitality, pub chain JD Wetherspoon is also due to issue a trading statement, as is travel caterer SSP Group.
Spoon’s chairman Tim Martin rarely misses a chance to lobby for his industry to be treated more fairly on tax relative to supermarkets, so I suspect next week’s update could include some pithy commentary on pubs’ business rates. These are expected to rise sharply as a result of pubs’ rateable values being updated from pandemic lows (in 2021) to reflect more normal trading in 2024.
The impact is going to be tapered in gradually and as always, I expect large chains such as Wetherspoons to handle the changes more easily than smaller independent operators. However, trade body the UK Hospitality claims that by 2028/29 an average pub’s business rates will have increased by 76%, compared with an increase of just 4% for a large supermarket.
Away from retail and hospitality, we’re also expecting updates from building materials suppliers Marshalls and Wickes next week, plus defence group QinetiQ.
International news
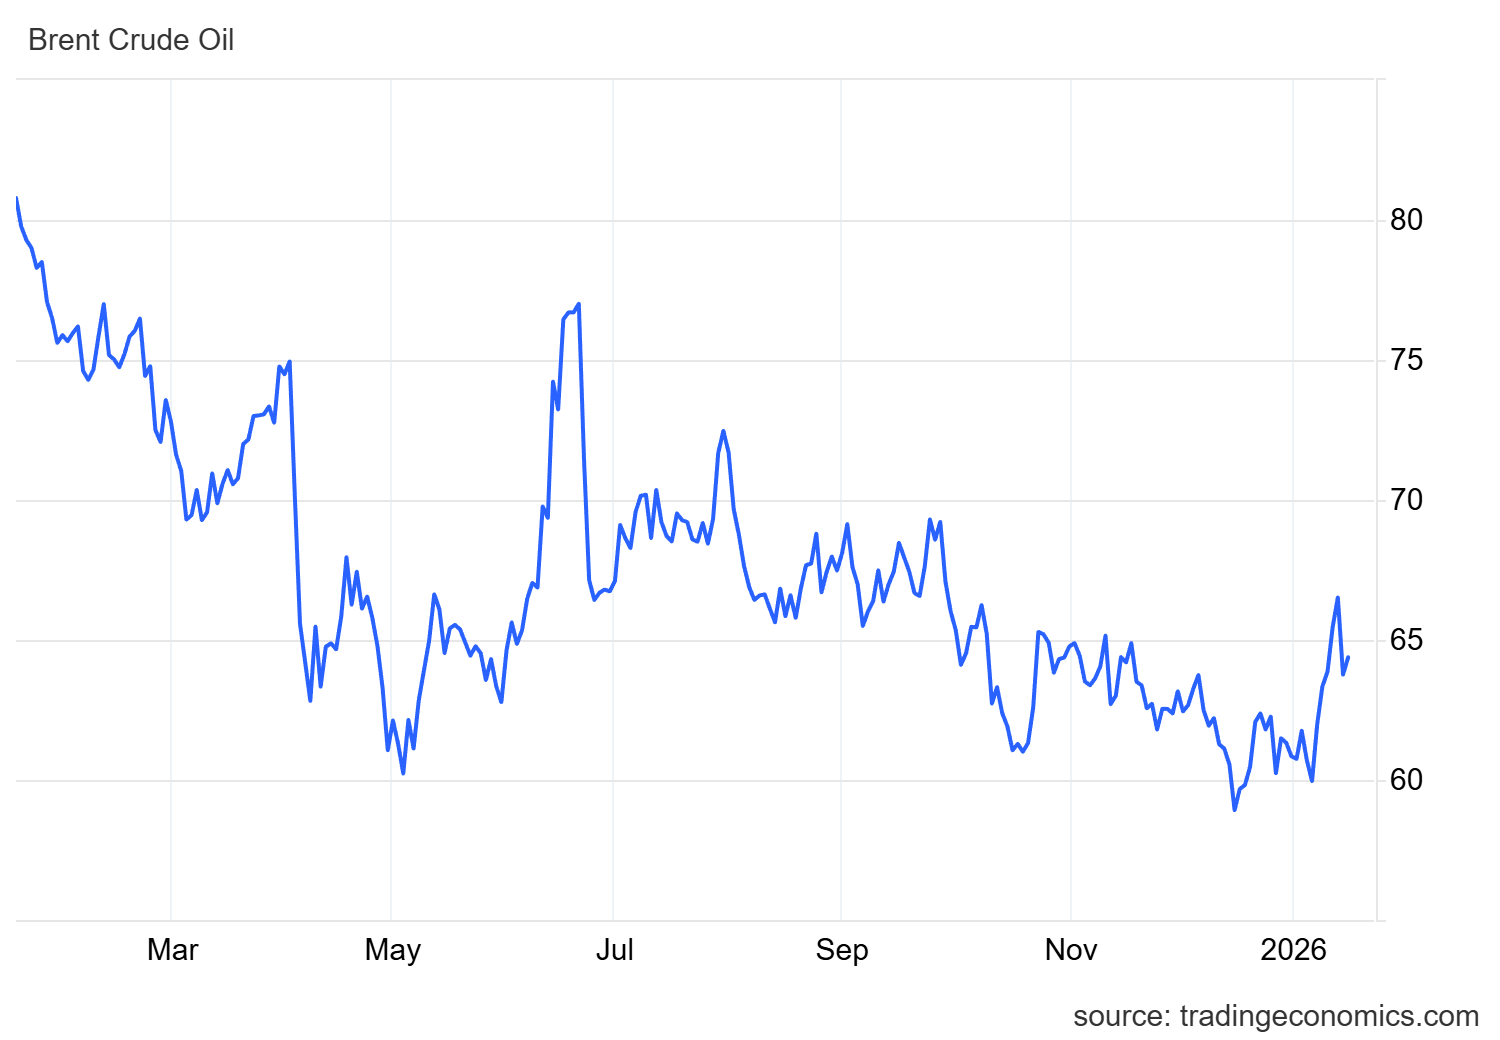
Looking across the pond to the US, rhetoric and tension around Iran eased this week. The likelihood of US strikes has seemingly fallen significantly. Oil prices reacted quickly but remain higher than they were at the end of last year:
However, the US Justice Department’s decision to launch a criminal investigation into Fed chairman Jerome Powell appeared to mark a further escalation in the administration’s campaign to undermine the independence of the US central bank.
Investors certainly seem to be taking a more cautious view on US assets. Emerging market debt specialist Ashmore reported a quarterly net inflow of $2.6bn (5.3%) into its funds on Thursday. CEO Mark Coombs cited investors rebalancing “overweight US positions” and an “increasingly complex geopolitical situation”.
Bond titan Pimco has also commented that it's diversifying portfolios away from US assets. Closer to home, small-cap asset manager Premier Miton reported a staggering 25% net outflow from its US-weighted international equity funds during the quarter.
The US has a public holiday on Monday, but earnings reports later in the week are scheduled to include Netflix, Visa, Intel and United Airlines.
An update from UK-listed promotional goods firm 4Imprint may also provide some insight into the health of SMEs in the US – 4Imprint generates virtually all of its sales in North America. We published a deep dive on this interesting business in November.
Finally, fans of the big European luxury houses will also have plenty to look forward to next week. LVMH and UK-listed Burberry are both expected to update investors over the next seven days.
Enjoy your weekend!
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
19 January | ||
00:01 | UK | Rightmove House Price index |
02:00 | China | GDP |
10:00 | EU | CPI inflation |
20 January | ||
07:00 | UK | Unemployment Rate |
10:00 | Germany | Economic Sentiment Index |
13:15 | US | ADP Employment change |
21:30 | US | API Crude Oil Stocks |
21 January | ||
07:00 | UK | Inflation |
09:00 | US | IEA Monthly Report |
22 January | ||
07:00 | UK | Public Sector Net Borrowing (December) |
13:30 | US | GDP |
13:30 | US | Initial Jobless Claims |
15:00 | US | Core PCE Price Index |
17:00 | US | Gasoline/Crude Oil Stocks |
23 January | ||
00:01 | UK | GfK Consumer Confidence |
07:00 | UK | Retail Sales |
09:30 | UK | S&P Global Services PMI |
09:30 | UK | S&P Global Manufacturing PMI |
14:45 | US | S&P Global Manufacturing PMI |
14:45 | US | S&P Global Services PMI |
18:00 | US | US Baker Hughes Oil Rig Count |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 19 Jan | Marshalls (LON:MSLH) XP Power (LON:XPP) | US public holiday. | |
Tuesday 20 Jan | Big Yellow (LON:BYG) Cairn Homes (LON:CRN) 4imprint (LON:FOUR) Gear4music (HOLDINGS) (LON:G4M) Goldplat (LON:GDP) Kier (LON:KIE) Qinetiq (LON:QQ.) | Kromek (LON:KMK) | Interactive Brokers (NSQ:IBKR) 3M Co (NYQ:MMM) Netflix (NSQ:NFLX) United Airlines Holdings (NSQ:UAL) |
Wednesday 21 Jan | Burberry (LON:BRBY) Currys (LON:CURY) Galliford Try Holdings (LON:GFRD) ICG (LON:ICG) JD Sports Fashion (LON:JD.) J D Wetherspoon (LON:JDW) | Pensionbee (LON:PBEE) | Barry Callebaut AG (SWX:BARN) Citizens Financial (NYQ:CFG) Halliburton Co (NYQ:HAL) Johnson & Johnson (NYQ:JNJ) Charles Schwab (NYQ:SCHW) Prologis (NYQ:PLD) |
Thursday 22 Jan | Associated British Foods (LON:ABF) Auction Technology (LON:ATG) B&M European Value Retail SA (LON:BME) Harbour Energy (LON:HBR) Time Out (LON:TMO) Wickes (LON:WIX) | Hardide (LON:HDD) Ilika (LON:IKA) Works co uk (LON:WRKS) | Abbott Laboratories (NYQ:ABT) Capital One Financial (NYQ:COF) Freeport-McMoRan (NYQ:FCX) General Electric Co (NYQ:GE) Intel (NSQ:INTC) Intuitive Surgical (NSQ:ISRG) LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) Procter & Gamble Co (NYQ:PG) Visa (NYQ:V) |
Friday 23 Jan | SSP (LON:SSPG) | NextEra Energy (NYQ:NEE) Slb NV (NYQ:SLB) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
The GDP figures look rather recessionary to me even though they don't quite meet the official definition but they do seem similar to Germany's poor performance in the last couple of years.
One very large component of GDP is housebuilding. While the Government has taken steps to improve affordable housing and planning they have not in my view addressed the total market. Their stated intention to build 1.5m homes in this Parliament seems to be largely based on wishful thinking rather than specific action. This in my view should include addressing skills shortages, lowering mortgage rates and providing greater help to first time buyers.
In its first year in power the Labour Government built 186,600 homes which is over 110K short of its 300K target, clearly improvements need to be made.
One area which may enhance GDP is the need to increase Defence spending, Tuesday's trading update for Qinetiq (LON:QQ.) may give some indication of how this is going.
XP Power (LON:XPP) might be worth a look on monday q3 was improving profit, bowl on chart?
Mello is back for our first MelloMonday webinar of 2026. We have so much in store for you so do join us on Monday evening from 5pm. Richard Penny will kick off the show sharing some market insights, stock picks for 2026 and so much more. Three companies join us to introduce their business, provide results updates and answer your questions following their presentations. Asset Match will provide an introduction and share some insights on investing in private markets.
We will also introduce our Mello Membership. Mello Membership is the new Annual Pass that will give you access to all our webinars, access to exclusive Mello events and meet-ups, exclusive and best priced tickets to our physical events, our investor content library and so much more. Click here for more details.
Full MelloMonday 19th January schedule below (subject to minor change): https://www.melloevents.com/mm190126
5:00pm: Richard Penny
5:30pm: Company Presentation from MHA (LON:MHA)
6:10pm: Introduction to Mello Membership and 2026 Events
6.15pm: Company Presentation from Newmark Security (LON:NWT)
6:45pm: Hardman & Co Tax Advantaged Forum invitation to a live webinar: Four distinct approaches to EIS investing
6:50pm: Presentation from Asset Match
7:20pm: Company Presentation from Titon Holdings (LON:TON)
8:00pm: MELLO BASH (Buy, Avoid, Sell, Hold) Panel
Don't miss this one... it is going to be an excellent show! Hope to see you on zoom this coming Monday.
Use code MMSTOCKO50 for 50% off our 19th January MelloMonday webinar.
Didnt Associated British Foods update the market on 8th January. Are they updating the market again 2 weeks later?
Real GDP growth of 0.1% for the last 3 months.
This is regarded as 'good' news....what has gone wrong in this country? Technology is storming ahead but growth is probably zero or a rounding error.
Add Wed. 21st. Experian (LON:EXPN) Q3