The Week Ahead (24-28 Nov): it’s all about the Budget (& Nvidia!) + AO., PETS, CBOX

Welcome to this week's edition of The Week Ahead. There’s probably only going to be one piece of news that really grabs UK investors’ attention next week – Wednesday’s Autumn Budget.
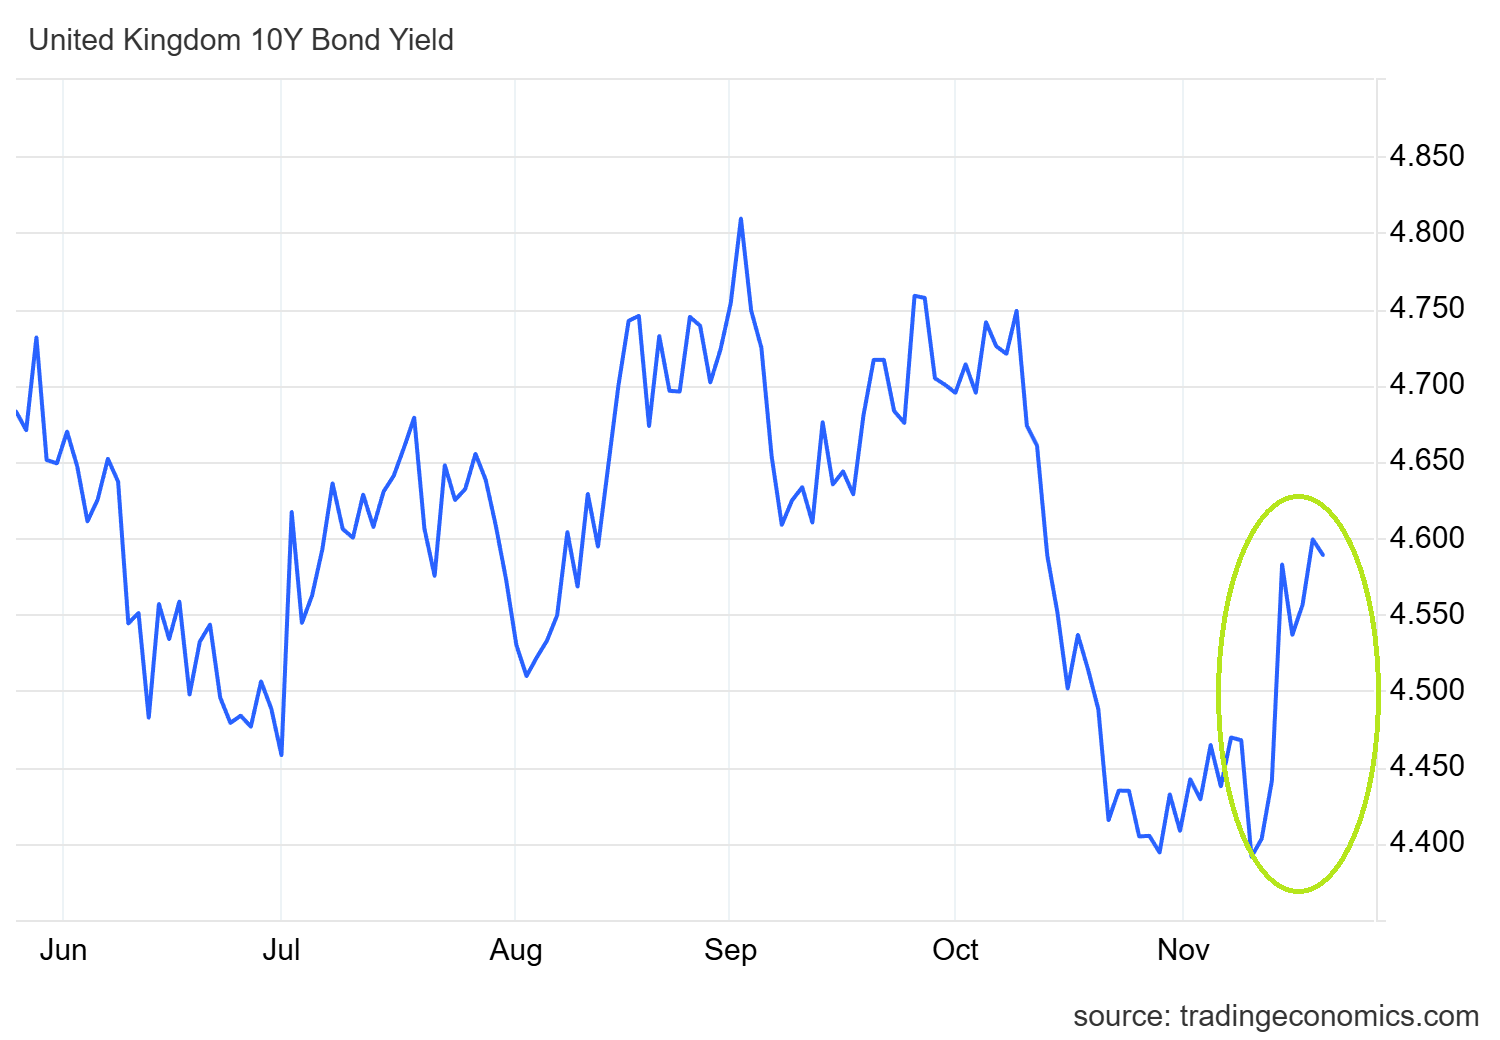
The bond market shuddered at the end of last week when it became clear that plans to raise income tax had been shelved. Bond yields have stabilised this week, but Friday’s news that public sector borrowing overshot forecasts again in October is a painful reminder of the challenges the Chancellor is facing:
We’ll have to wait until Wednesday to see what measures will replace the revenue that might have been generated by an income tax rise. One possible measure that could prove effective against a backdrop of wage inflation is a further freeze in personal tax thresholds.
The difficulty for a government that needs to raise money is that any effective change is likely to be unpopular with someone. So perhaps our best hope is that changes will be effective, even if they are unpopular.
Judging from fellow investors with whom I chatted at Mello this week, expectations are low. Whether it’s ISAs, pensions, dividends, inheritance tax or a new mansion tax, many seemed to be expecting a personal hit from the Budget.
Perhaps fortunately – given how many companies are blaming Budget uncertainty for their indifferent performance – we don’t have long to wait now.
Nvidia knocks it out of the park again
One uncertainty that was resolved – at least temporarily – this week was over whether NVIDIA (NSQ:NVDA) Q3 earnings would disappoint the market.
In the event, the AI chip giant unveiled some crushingly strong quarterly figures.
Nvidia’s third-quarter revenue of $57bn was 62% higher than one year ago and 22% higher than in Q2. Net income for the period rose by 65% year-on-year to $31.9bn, giving a staggering 56% post-tax profit margin.
However, debate continues to rage over whether current AI spending represents a bubble. Unsurprisingly, Nvidia CEO Jensen Huang doesn’t think so, instead pointing to a “virtuous cycle” in his comments this week:
Compute demand keeps accelerating and compounding across training and inference — each growing exponentially. We’ve entered the virtuous cycle of AI. The AI ecosystem is scaling fast — with more new foundation model makers, more AI startups, across more industries, and in more countries. AI is going everywhere, doing everything, all at once.
Nvidia’s AI chip output is apparently fully sold for at least the next year, so a collapse doesn’t seem imminent. But I can’t help feeling concerned about the circular nature of some of the company’s recent deals and the fact – revealed in this week’s filings – that 61% of its Q3 revenue came from just four unnamed large customers.
To me, this feels a little like the situation in financial markets in 2007, when Citigroup’s then-CEO Chuck Prince famously said:
When the music stops, in terms of liquidity, things will be complicated. But as long as the music is playing, you've got to get up and dance.
What happens when the current breakneck rate growth slows – or even reverses? Alternatively, what happens if competitor(s) emerge and Nvidia loses its near-monopoly status on the supply of chips for AI?
The financial strength of the key players means that the current situation could be sustainable for some time yet. But history tells us that something will change eventually.
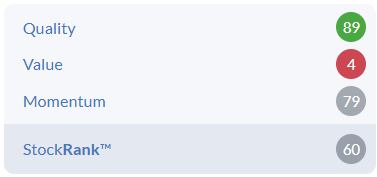
Personally, I would be on the look out for any signs of falling momentum in Nvidia’s StockRank. Right now, strong Quality and Momentum ranks are supporting the company’s High Flyer styling. But if the momentum leg is pulled away, Nvidia might make the uncomfortable transition to a Falling Star – a quality stock that’s gone ex-growth:
Market wobble?
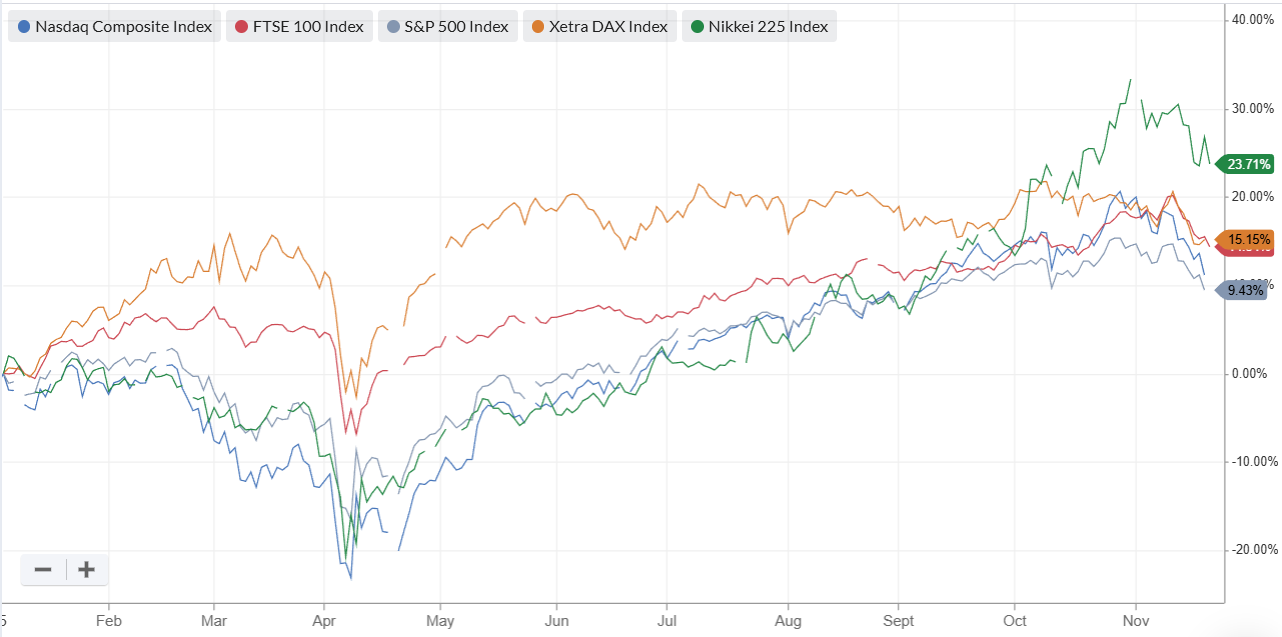
Investor uncertainty over AI bubble risk is one factor being widely blamed for recent market volatility. The US Nasdaq and S&P indices have underperformed other key indices so far this year:
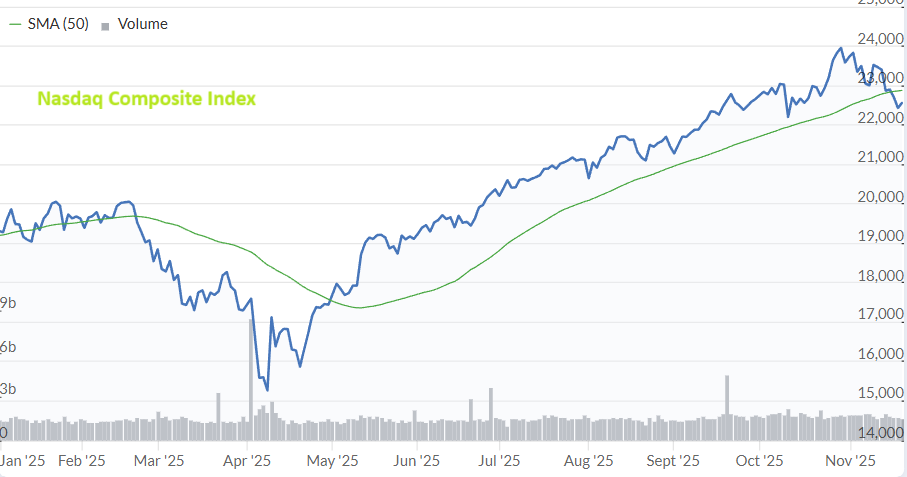
While the Nasdaq is still up by more than 15% so far in 2025, the smooth uptrend seen since May appears to have broken. The index has fallen by c.6% so far in November (at the time of writing!):
UK company news
Personally, I prefer to fish in the more reasonably valued waters of the UK stock market. Among the companies that are expected to issue results this week, several are on my radar as potential coal mine canaries, or simply as interesting businesses.
AO World (LON:AO.)
Our household washing machine suffered a terminal breakdown while I was at Mello this week, so purchasing a new one is on the to-do list for this weekend. There’s a good chance that AO’s competitive pricing, quick delivery and free recycling service will win our business, as it has done previously.
However, while my experience as a customer has been positive, I’ve always been less convinced of AO’s attractions as a potential investment. Ultra low margins, bulky commoditised goods and a dependency on selling high-margin aftermarket warranties don’t seem like a very tempting mixture to me.
I could be wrong, though. We’ve taken a neutral view on AO this year in the DSMR, but the company’s share price has picked up since the summer and earnings forecasts have edged higher:
This improved momentum means the algorithms have swapped the stock’s previous Falling Star styling for a more appealing High Flyer tag:
Against this backdrop, I’ll be interested to see whether this week’s interim results will provide an opportunity for us to take a more positive view of this founder-led business.
Pets at Home (LON:PETS)
Elsewhere in the consumer sector, half-year results from pets-to-vets chain Pets at Home may be worth a look.
The company parted company suddenly with its CEO in September, issuing an unscheduled RNS after the market had opened that also included a(nother) profit warning.
The problem seemed to be that the company’s sales projections for the year had been based on underlying growth in the pet retail market.
Unfortunately what has actually happened – according to the company – is that the overall market has shrunk. This has meant that even though Pets’ retail performance has improved, it hasn’t generated the hoped-for results, with store sales down by 5%.
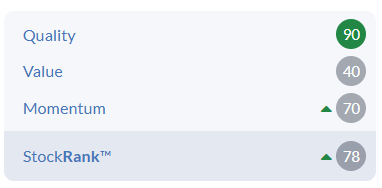
I’ll be keen to see if a contrarian opportunity could be emerging, as suggested by the StockRanks:
After all, the company has already been through a painful cycle of profit downgrades over the last 18 months:
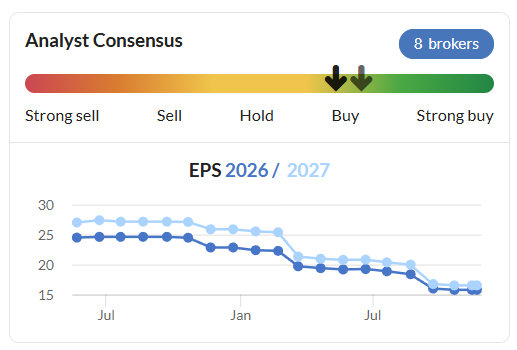
The shares are now trading back at pre-pandemic levels, after a four-year decline that reminds me of the “long-term reversal” momentum pattern Ed discussed in this recent article:
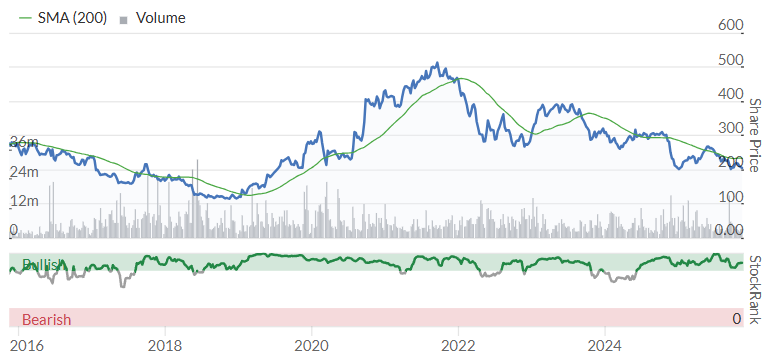
I’ll be watching out for signs that a bowl might be forming – an encouraging update this week could be a good starting point.
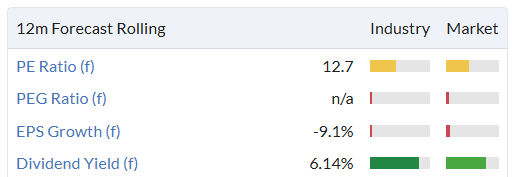
If the company can return to modest earnings growth, then I think the current valuation could be worth considering:
Cake Box Holdings (LON:CBOX)
This dairy-free [correction: egg free] cake retailer is a member of my SIF Folio and a personal holding.
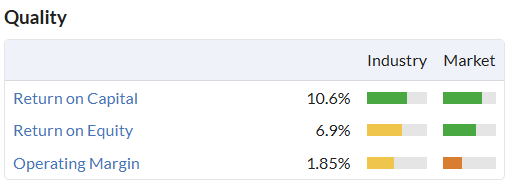
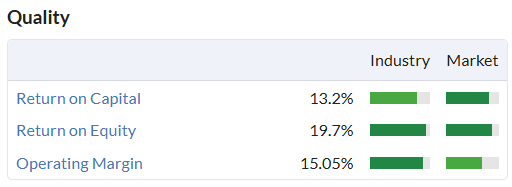
I know that many investors are wary of this sector having been scarred by their experiences with Patisserie Valerie. However, this family-controlled business has delivered fairly solid results since its listing, with its franchise model supporting respectable quality metrics:
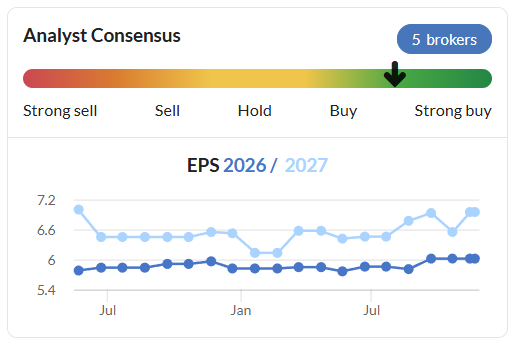
Cake Box has also enjoyed a number of broker upgrades this year:
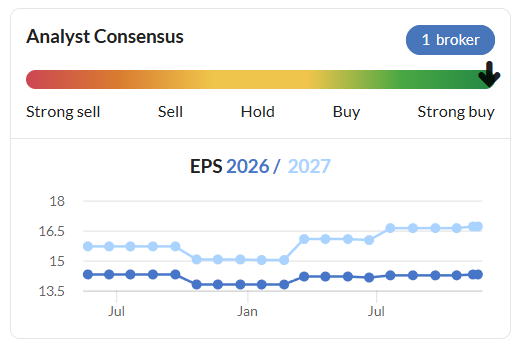
I’ll be keen to see what the company has to say about trading in its core retail business and online during the six months to 30 September.
July’s full-year results showed overall revenue growth of 13%, but like-for-like growth in franchised stores was only 3% – surely barely enough to keep up with basic cost inflation.
One niggling concern for me with this business has always been the extent to which new franchise fees might be supporting profits – 26 new franchise stores opened last year, taking the total to more than 250.
I’m also interested in the progress of the Ambala business, which was acquired in March 2025. Ambala produces and sells traditional Indian sweets through a network of shops. It’s a logical complement to the core Cake Box offering in terms of core market fit, but my impression is that this business may have needed some investment and modernisation.
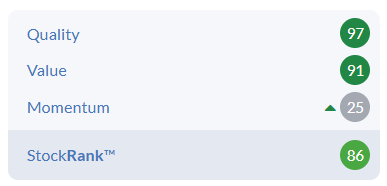
One potential concern for me is that Cake Box’s StockRank appears to have been in steady decline since the summer, despite a rising share price:
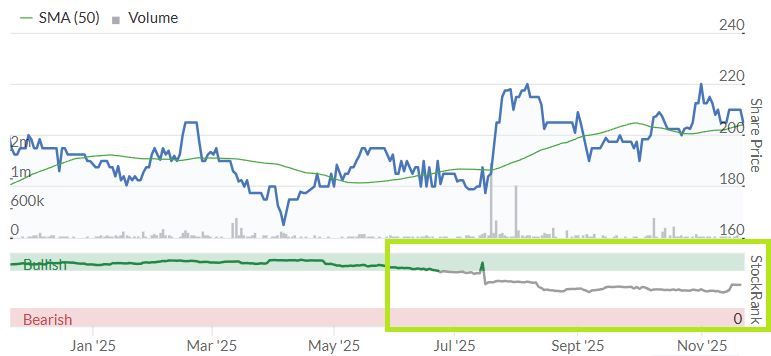
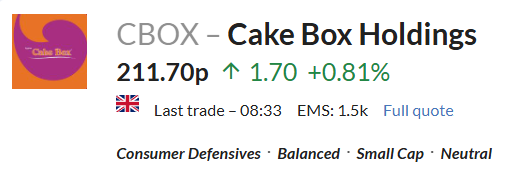
Hopefully, fresh financial data in next week’s results will justify a more positive rating. The other possibility that seems likely to me is that the declining StockRank is an indicator that the share price is now up with events, as reflected in the stock’s Neutral styling:
Cake Box’s results are due on Wednesday next week. Let’s hope the company’s decision to report on the same day as the Budget is not a sign that management is hoping to distract us from the latest figures!
Here’s a summary of what’s expected next week – perhaps unsurprisingly, UK company news seems likely to be heavily weighted to Tuesday (the day before the Budget).
Economic Calendar
Date / Time (BST) | Country | Event |
24 November | ||
09:00 | Germany | IFO Business Climate index |
25 November | ||
05:00 | EU | New car registrations |
07:00 | Germany | Q3 GDP |
13:30 | US | Monthly retail sales |
13:30 | US | Producer Price Index |
15:00 | US | Consumer Confidence |
26 November | ||
12:30 | UK | Autumn Budget 2025 |
13:30 | US | Q3 GDP |
13:30 | US | Durable Goods orders |
13:30 | US | Building Permits |
15:00 | US | Personal Income |
15:00 | US | Inflation (Core PCE Price Index) |
15:30 | US | Crude Oil Inventories |
27 November | ||
n/a | US | US markets closed for Thanksgiving |
07:00 | Germany | Consumer Confidence |
28 November | ||
07:00 | UK | Nationwide House Price Index |
13:00 | Germany | Inflation |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 24 Nov | Supermarket Income REIT (LON:SUPR) | Cerillion (LON:CER) DSW Capital (LON:DSW) | Agilent Technologies (NYQ:A) Symphony Environmental Technologies (LON:SYM) Zoom Communications (NSQ:ZM) |
Tuesday 25 Nov | Intertek (LON:ITRK) Kingfisher (LON:KGF) Transense Technologies (LON:TRT) | AO World (LON:AO.) Accsys Technologies (LON:AXS) Brickability (LON:BRCK) Cordiant Digital Infrastructure (LON:CORD) Compass (LON:CPG) Cranswick (LON:CWK) easyJet (LON:EZJ) GB (LON:GBG) Molten Ventures (LON:GROW) Intercede (LON:IGP) Marstons (LON:MARS) Renew Holdings (LON:RNWH) Sosandar (LON:SOS) Supreme (LON:SUP) Telecom Plus (LON:TEP) | Agilent Technologies (NYQ:A) Autodesk (NSQ:ADSK) Best Buy Co (NYQ:BBY) Alibaba Holding (NYQ:BABA) Dell Technologies (NYQ:DELL) Dicks Sporting Goods (NYQ:DKS) Dollar Tree (NSQ:DLTR) |
Wednesday 26 Nov | Avation (LON:AVAP) Seeing Machines (LON:SEE) | Auction Technology (LON:ATG) Cake Box Holdings (LON:CBOX) Helical (LON:HLCL) Impax Asset Management (LON:IPX) Pets at Home (LON:PETS) | Deere & Co (NYQ:DE) Five Below (NSQ:FIVE) |
Thursday 27 Nov | Aptamer (LON:APTA) Atlantic Lithium (LON:ALL) Bellway (LON:BWY) EnSilica (LON:ENSI) Litigation Capital Management (LON:LIT) Petra Diamonds (LON:PDL) | Altitude (LON:ALT) AO World (LON:AO.) First Property (LON:FPO) Halfords (LON:HFD) James Latham (LON:LTHM) Pennon (LON:PNN) VP (LON:VP.) | |
Friday 28 Nov | Berkeley Energia (LON:BKY) CAP-XX (LON:CPX) New Frontier Minerals (LON:NFM) Wishbone Gold (LON:WSBN) | Foresight Environmental Infrastructure (LON:FGEN) |
Disclosure: Roland owned shares in Cake Box at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
A useful summary of the week ahead. Thanks
Hi Roland, I think Cake Box Holdings (LON:CBOX) is egg-free instead of diary-free, although they offer some diary-free cakes
Hi Abel, thanks for flagging this up. You are correct! I'll amend the article.
Roland
While you are at it Roland, it's dairy (products) . ;-)
Must admit, thinking of selling Cake Box Holdings (LON:CBOX) ahead of results