Volex share price slips on weaker H2 outlook after 41% profit surge

Analyst’s view:
Today's half-year results show a 41% surge in H1 profit, but also flags up that the exceptional Data Centre demand seen over the last 12 months is now normalising. Sales and profits are expected to fall modestly in H2, but I'm encouraged by continuing growth in areas such as EV charging and believe the valuation looks reasonable after the stock's recent de-rating.
Down 7% to 529p (£956m) - Half-Year Report
The Volex share price is down this morning following the publication of the company's results, despite the company reporting a 41% surge in H1 profit and unchanged guidance for the current year.
I think this mild sell-off is mostly a reflection of the possibility that the AI-related growth is slowing, rather than any disappointment in the numbers.
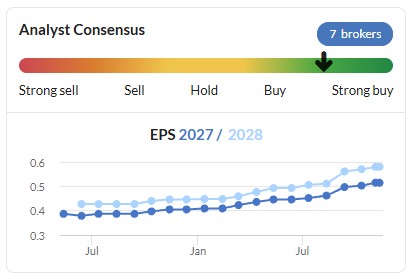
Despite this, I think it's worth remembering that earnings expectations have risen steadily over the last 18 months. Growth isn't solely being driven by data centre demand either - today's results show growth across the business, particularly in EVs.
Let's take a look at the numbers.
Half-year summary
These headline numbers cover the six months to 30 September and are pretty strong, as we were briefed to expect in October's half-year update:
Revenue up 23.9% to $723.6m
Underlying pre-tax profit up 43.1% to $69.4m
Underlying EPS +40.6% to 27.7c
Interim dividend up 6.3% to 1.7p
Net debt excluding leases up 34.7% to $203.7m
Divisional results: gaining share in EV
Complex Industrial Technology (which includes Data Centres) is now Volex's largest business by some margin. Sales in this division rose by 41.2% to $218.3m in H1, with Data Centre revenue climbing by 47% to represent 57.6% of divisional sales (c.$125m), thanks to the company's status as "a trusted supplier to a leading hyperscale customer".
Volex has been supplying the high-speed copper data cabling used to connect equipment within data centres. The company says that over short distances, these products use less power and generate less heat than optical alternatives.
One potential concern is that Data Centre revenue appears to have peaked in H2 FY26, when the company's inventory of components allowed it to meet customer demand "when other suppliers could not" (my emphasis):
Data Centre revenue, which now represents 57.6% of revenue in this sector, was well ahead of the prior-year period, with 47.0% organic growth, but below the second half of FY2026, primarily because of additional volumes in that period that did not repeat.
We're told that market conditions have now normalised, although it's not clear to me how much of this reflects demand and how much is about supply.
Fortunately, growth elsewhere also remains positive, with other customer segments within the Complex Industrial Technology division seeing underlying revenue growth of 20% during the half year.
EV & Electrification: Volex's H1 growth wasn't limited to a surge in demand for data centre products. The largest percentage growth was actually in EV & Electrification, where revenue rose by 46.8% to $133.6m.
The company says it won a "greater share of our largest EV customer's requirements" during the period, driving a one-off step change in demand. Management says most of this came from charging products, so is not directly linked to vehicle production (although I suspect there's some linkage).
Volex says its vertically integrated model provides a number of competitive advantages:
We extrude our own cable, mould our own components and make our own pins, which gives us a cost position and a speed of response that competitors buying in these parts find hard to match.
As with the increase in data centre revenue, EV product sales aren't expected to rise in H2. Today's guidance is for a EV & Electrification to be "broadly in line" with the first half - so potentially slightly lower.
Other divisions: all of Volex's remaining businesses delivered sales growth in H1, in contrast to the more mixed performance seen in FY26.
Off-Highway: organic revenue up 12.6% to $144.3m, although reported growth was hit by an $8.6m currency headwind.
Consumer Electricals: organic revenue up 9.5% to $138.3m. Longstanding OEM partnerships are supporting growth in harness products and the company notes that the increasing complexity and connectivity of domestic appliances is creating more opportunity for the business: "Relationships that started with power cords are developing into internal appliance harnesses worth several times more per unit."
Medical: organic revenue rose by 1.8% to $89.1m, marking a return to growth after last year's customer destocking. The company acquired the remaining 64.3% of medical cabling specialist KST in July for up to $89m. This has since contributed $11.3m of revenue and is expected to be margin accretive, with cross-selling opportunities.
Balance sheet: net debt rose by $82.2m to $203.7m in H1, relative to the end of FY26. This reflects a number of factors, in particular a net initial cash consideration of $35.8m for KST and an underlying working capital outflow of $29.1m to support higher levels of business.
Share buybacks also contributed a small amount to the increase in net debt. While I don't like to see borrowed cash use to buyback shares, it's not something I see as a big issue at this time.
Profitability: these results lift Volex's trailing 12-month operating margin above 10% for the first time, but I'm not sure if we should rely on this being sustainable, given the exceptional contribution from Data Centre products over the last 12-month period.
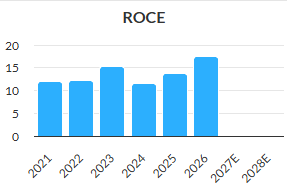
Even so, the trend of steadily improving margins is encouraging, in my view, especially as it's also translated into improvements in return on capital employed:
Outlook
The second half has started well. The Board’s expectations for the full year, as upgraded at the October trading update, are unchanged.
Consensus forecasts following October's update are for revenue of $1,407m and adjusted EPS of 51.5c.
Comparing these estimates with today's H1 figures suggests that both revenue and earnings will be lower in H2:
H1 revenue & EPS: $724m and 27.7c
Implied H2 revenue & EPS: $683m and 23.8c
In some cases I'd be concerned about this, but in this case I don't think it's too much of a worry. It's clear there was an exceptional period of demand for Data Centre products over the last 12 months, which is now easing.
The risk, of course, is that this is the start of a longer decline in Data Centre volumes, as the AI build-out slows. There's no clear sign of this yet, but it's certainly something I will be watching for.
Roland's view
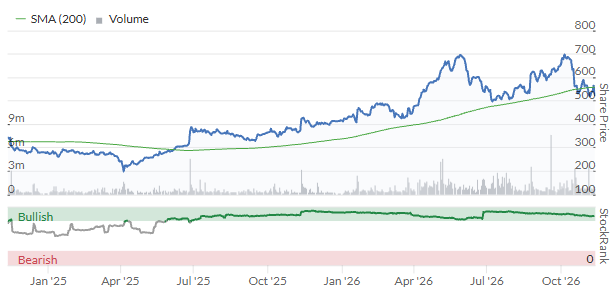
Zooming out slightly on the share price chart, we can see when the AI trade really took off for Volex:
A return to more normal levels of growth will inevitably disappoint some investors, but I don't think it should detract from the company's continuing strong performance.
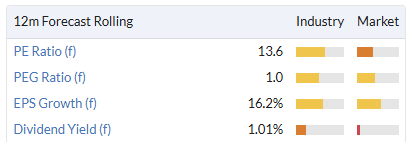
The stock has also now consolidated somewhat, falling by nearly 25% from the 700p highs seen in May and October. This de-rating has left Volex looking quite reasonably priced, in my view, with a PEG ratio of just 1.0x:
Graham left our broadly-positive view unchanged in October and I'm going to do the same today. While Volex's individual product lines will always carry some cyclical risks, my impression is that the business is continuing to grow in a number of attractive markets and is reasonably priced.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Volex (6)
Comments here are also visible in the Daily Stock Market Report
Volex (LON:VLX) I am a long term holder
Thank you for your write up Graham
I am a big fan of the business and have been very impressed with what Nat R and his team have achieved there. It seems to me that they always play a straight bat in communicating what is going on in the business which I find particularly refreshing
However, I am not too surprised by today's market reaction, and I have my own concerns :
I think that one positive from today's report is that the business may well be being pretty conservative with their forecasts for the full year . They would be highly unlikely to have lifted guidance again having done so only a month or so ago. So maybe H2 could be building up for a beat ? Alternatively that might well be my subconscious bias breaking out !
Volex (LON:VLX)
cheers Lochinver your viewpoint isnt too far away from mine
ref the slowdown in sales - all be can really hope is that the broker forecasts for next year - confirm that despite the "headwinds" hopefully they have enough positive stuff to still expect that they can do double digit growth next year ref earnings. We are rally 100% reliant on those forecasts not being loweredm if we want to take the viewpoint company is worth more than whats its value at now.
You would like to think they would be cautious bearing in mind they have been only recently upping expectations for next year - so hopefully there is no bad news to come ? would seem crazy to not act with caution ref upgrading following year - i dont know if brokers sometimes go off on a tangent tho.
ref this bit
Hopefully at some point the working capital build up unwinds and the business can also use its cash flow from future profits to pay it down.
all i would say is that future acquisitions aside we better bloody hope that happens - i kinda get it that it looks bad with the growth they have had h1 -hopefully lower growth changes negative working capital adjusts into positive or neutral at worst.
Ref acquisitions well there will be deferred payments that will take up future cashflow - but i think te latest one is 2 modest tranches
Once they are on stable level you really want to be getting as close as posible to 100% cash conversion - and there is scope for debt to start flying down in a couple of years - or for them to be able to afford acquisitions without debt going up materially as its done till now.
ref buybacks i am generally a fan - but perhaps not at like peak 700p levels - at current levels its a ok by me - if one isnt confident in futiure earnings well you might as well sell up anyway - it is extra risk though that you are nailing your colours to the mast that thne future "must be better" if you are buying back shares now.
Perhaps its not my strongest hold but in the absence of any bad news they are still trending towards their stated aims ref sales margin and roce all of which should do us nicely if acheived. thought i had missed on this one but the recent pullback has allowed me to join the party.
Volex (LON:VLX) is my largest holding so take the below with a pinch of salt:
Fantastic stuff Nurzel, many thanks indeed for that
I better see what pennies I can find under the sofa cushions and put them to better use by adding to my Volex (LON:VLX) holding !
Thank you Roland, we held and sold for a modest profit far too soon. Value at 27 in Stock Ranks is making me hesitant to join in again.
Volex (LON:VLX)
I am a new holder here - results are ok - per Gaia broadly similar h2 is less than what we might have hoped for - a lot of moving parts here - clearly there is an element of splashing the cash to up profits (yiannos and abtan would not like the cash profile here) - clearly they are at the heart of the au boom and benefitting from supply and demand mismatch.
Overall though I am impressed with how they have delivered the last 5 years - they seem not be be afraid to do old school hard work of investing in what customer wants - if their source irgznic growth is Faye and reasonably calculated that’s impressive.
Overall they seem to have clear focus on simple targets - that’s business in a nutshell - deliver higher sales - deliver 12% underlying net profit - deliver 20% roce - and shareholders will be well rewarded.
Their current sweet spot tailwinds perhaps make their Job easy at present - thereal test is when customers cut back on spending - and you have more cheaper competition.
I don’t know how this will pan out but for now I am a happy new holder - a stock to watch uber carefully though as they kinda need to deliver their promised 2 billion 12% margin 20% roce numbers before I can expect material uplift in shareprice