Daily Stock Market Report (Fri 9th Jan 2026) - SBRY, CKN, UTG

Good morning and welcome to Friday's report.
Today's report is now complete (12.30).
Spreadsheet accompanying this report: link (updated to 16th December).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£101bn | SR78) | Rio Tinto confirms it has been discussing a potential combination with Glencore, which could include an all-share merger. Current expectations are that any merger would be effected by Rio acquiring Glencore. | ||
Glencore (LON:GLEN) (£49bn | SR34) | As above from Rio Tinto. | ||
Halma (LON:HLMA) (£13.8bn | SR79) | Acquired Safetec Srl, an Italian fire and gas safety business that designs solutions for large industrial projects. Cash paid €72.5m, Safetec 2025 revenue was c.€30m. | ||
J Sainsbury (LON:SBRY) (£7.5bn | SR90) | Q3 LFL sales +3.4%, with grocery +5.4% LFL. Won market share over Christmas. FY26 retail free cash flow now exp to be >£550m (previously >£500m). Shore Capital forecasts unchanged. | AMBER/GREEN ↓ (Roland) I can’t really fault this update, except to point out that LFL sales growth was slightly below reported grocery price inflation for December. The economics of this business remain tough. My feeling is that any increase in volumes and market share came from more competitive pricing. Today’s upgrade only applies to cash flow, with broker forecasts unchanged. I remain broadly positive on this well-run business, but I am starting to think the re-rating over the last year has left the valuation up with events. Sainsbury’s currently trades on a FY26E P/E of 14 and at a premium to book value. Given the historic profitability of the business, that seems high enough to me. I’m moderating our view by one notch today. | |
Unite (LON:UTG) (£2.8bn | SR48) | Trading update and Q4 Fund Valuations & Launch of £100m share buyback programme | YTD sales progress is “consistent” with guidance for occupancy of 93-96% and rental growth of 2-3% in 26/27 academic year. FY25 guidance unchanged for adj EPS of 47.5-48.25p. | AMBER (Roland) [no section below] Pricing in student property has come under pressure and today’s update confirms the company is using “price adjustments” to secure income in markets with lower occupancy. However, interest rates appear to be on a downward trend and Unite is a large player in this sector in the UK – soon to become larger with the acquisition of Empiric. With the shares trading at a c.45% discount to their last-reported book value, the £100m buyback launched today should be accretive to NAVps, generating value for shareholders. A forecast dividend yield of 6.7% is also attractive, if it proves sustainable. The StockRanks style this specialist REIT as Contrarian and I think Unite could be worth a closer look. While the sector faces challenges including slower sales cycles and a reduction in Chinese overseas students, I think it’s possible that performance is stabilising. I haven’t done enough research to form a strong conviction, so I’m going to take a neutral view today. |
Clarkson (LON:CKN) (£1.2bn | SR85) | Underlying pre-tax profit for 2025 is now expected to be “not less than £90m” following a strong H2. (Panmure Liberum forecast was previously £87.7m). Panmure Liberum forecasts upgraded:- FY26E adj EPS: 219.3p (prev. 213.3p) - FY27E adj EPS: 242.1p (prev. 241.9p) | AMBER/GREEN ↑ (Roland - I hold) Profits have proved resilient after a downgrade in May prompted by the introduction of US tariffs. I think the market-leading global scale of this shipbroker should help it remain successful and continue to generate attractive shareholder returns. While the company’s exposure to geopolitical events and market cycles will always be a risk, these can bring opportunities too. With a high QualityRank and rising MomentumRank, I think Clarkson could grow into a High Flyer profile. While the near-term valuation is probably up with events, I think it has longer-term potential. For these reasons, I’ve upgraded my view by one notch today. | |
Amedeo Air Four Plus (LON:AA4) (£162m | SR65) | Emirates has exercised an option to allow it to return an A380 in minimum ‘half life’ condition with a cash sum, as opposed to delivery in full life condition when its lease expires in August 2027. Does not preclude a lease extension or sale of aircraft to Emirates or others. | ||
Life Science Reit (LON:LABS) (£137m | SR44) | Portfolio valuation down 7.8% to £332.6m in Dec 25 (June 25: £360.6m). NAVps -13% to 57.7p. Seeing higher vacancy rates. | ||
Pulsar Helium (LON:PLSR) (£94m | SR24) | The Jetstream #5 appraisal well has encountered “additional pressurized gas influx” at 871m, the highest yet recorded at Topaz. Testing planned in February 2026. | ||
InvestAcc (LON:INAC) (£93m | SR16) | CFO Vinoy Nursiah has left the company with immediate effect after less than a year. The board remains “entirely confident” in the company’s financial controls. FY results to be in line with expectations. | ||
1Spatial (LON:SPA) (£76m | SR25) | Acquisition talks remain ongoing with VertGIS. Deadline for firm offer extended to 30 January 2026. | ||
Quadrise (LON:QED) (£51m | SR5) | A non-exec has stepped down as a result of late notifications of sharedealings. | ||
Strategic Minerals (LON:SML) (£33m | SR28) | “Exceptional drill results” from 3/9 drill holes completed on Redmoor Tungsten-Tin-Copper project. On target to release updated Mineral Resource Estimates by the end of Q1 26. Cash $780k at end Dec 25. | ||
Eden Research (LON:EDEN) (£16m | SR16) | Fungicide Novellus+ has been approved in Chile for use in wine and table grapes. |
Roland's Section
J Sainsbury (LON:SBRY)
Down 5.9% at 310p (£7.0bn) - Trading Statement - Roland - AMBER/GREEN
Sainsbury’s has released a relatively strong third-quarter update today and upgraded its full-year free cash flow guidance by 10%. But the market has reacted by marking the stock down by c.5%.

This is a repeat of the downbeat reception received by Tesco’s Christmas update yesterday – as Mark commented, it seems investors were expecting more from the UK’s two largest supermarkets.
Market share statistics from Kantar Worldpanel certainly suggest both should be enjoying positive momentum. Both have gained share over the last year, mainly at the expense of struggling third-placed Asda:
Tesco +0.2% to 28.7%
Sainsbury’s +0.3% to 16.3%
Asda -1% to 11.4%
Let’s take a look at today’s update from Sainsbury’s:
Total retail sales (exc. fuel) rose by 3.9% during the 16 weeks to 3 January 2026, or 3.4% on a like-for-like basis. That’s very similar to Tesco, which reported 3.1% Q3 LFL yesterday.
There was a slightly smaller 3.3% rise in retail sales over the six-week Christmas period.
However, sales in the core Grocery business outperformed this figure, offset by a drag from non-food sales:
Q3 Grocery +5.4% (Christmas: +5.1%)
Q3 General Merchandise + Clothing: -1.1% (Christmas: -1.0%)
Q3 Argos: -1.0% (Christmas: -2.2%)
At first glance this suggests General Merchandise and Argos were a drag on the group’s results, but this may not be (entirely) true. In line with the group’s successful food-first strategy. Sainsbury’s is reallocating space from general merchandise (GM) to Grocery.
This helps to explain the segmental sales figures I’ve listed above; Grocery sales benefited from new space while General Merchandise was restricted by “space reallocation”.
Notably, the company says that sales of its Tu clothing ranges “outperformed the clothing market by 10 percentage points”. I think this is one of the more differentiated parts of the GM business.
At Argos, falling sales appear to reflect pressure on consumer spending. Management say volumes were up, but average selling prices were lower due to “subdued spending on higher ticket items” and “a weak gaming market”. Argos is said to have gained market share in Homewares, Electricals and Toys in Q3.
Outlook & Estimates:
The big news from today’s update is that retail free cash flow is expected to be around 10% higher than previously:
Retail free cash flow now expected to be “more than £550m” (previously more than £500m)
I’d say the only slight disappointment here for me is that this improvement is said to be due to “strong working capital performance”, rather than any improvement in profitability.
Supermarkets benefit from negative working capital as customers pay for goods before the retailer’s suppliers need to be paid. This means that managing supplier payments and stock levels carefully can support strong cash generation, even from low-margin businesses. Strong financial controls and stock management are certainly good to have, but they're not the same as rising profits.
Broker forecasts: house broker Shore Capital has published a new note today on Research Tree – many thanks.
While bullish, Shore’s analysts have left their FY26 profit forecasts unchanged. This essentially confirms my view above – stronger cash generation than expected is coming from good financial controls and stock management, not from any improvement in underlying trading or profitability.
Shareholder returns: strong cash generation is not to be sniffed at and Sainsbury’s CEO Simon Roberts is keen to return cash to shareholders. He confirms today that he expects to hand back more than £800m in FY26, through ordinary dividends, a £250m special dividend and a £250m buyback.
Roland’s view
The UK grocery market is highly competitive and very mature. There’s not really much room for growth except by taking market share from rivals. The last few years have seen Tesco and Sainsbury’s easing further ahead and securing their position as the two largest supermarkets.
However, the intense competition from Asda, Morrisons, Aldi and Lidl means that margins will always be under pressure. I think we can see that in today’s update and yesterday’s statement from Tesco.
Both companies reported Q3 LFL growth of over 3%, but this is lower than grocery price inflation, which “eased to 4.3%” in December, according to Reuters. This suggests to me that gains in share or volumes will largely have come from more competitive pricing – a view supported by this statement in today’s update:
We have made balanced choices to invest and sustain the strength of our competitive position through the most important trading period of the year.
Remember that for a retailer, "invest" is usually code for cutting prices.
Graham was GREEN on Sainsbury’s in November, reflecting the company’s previous upgrade and its Super Stock status. I could hang onto this view today, but I’m not quite sure it’s justified.
Today’s upgrade doesn’t affect profits and the share price trend appears to be weakening following a sustained re-rating last year:

The stock’s valuation looks comfortably up with events to me, with the shares on a FY26 P/E of 14 and a dividend yield of 4.7%, excluding this year’s special.
Sainsbury’s StockRank has declined since November and the StockRank Style is now Neutral, rather than the more bullish Super Stock styling we saw for much of last year. Momentum is still strong, but other measures have weakened slightly:
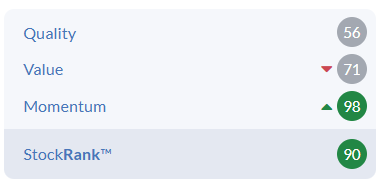
I note also that long-time major shareholder the Qatar Investment Authority recently sold 83.6m shares, cutting its holding from 10.1% to 6.8%. Perhaps they are keen to take some money off the table while the shares are trading at 10-year highs.
I don’t think there’s anything wrong here. But Sainsbury’s return on equity last year was only 6% and the shares are now trading at a modest premium to book value. At its core, this is a fairly low-return business. Personally, I’d want to find a cheaper opportunity to buy in. For this reason, I’m moving our view down by one notch to AMBER/GREEN today.
Clarkson (LON:CKN)
Up 4.6% at 4,170p (£1.3bn) - Trading Statement - Roland - AMBER/GREEN
(At the time of writing, Roland has a long position in CKN.)
Today’s update from this leading global shipping broker is short but positive:
Clarkson PLC, the world's leading provider of integrated shipping services, is pleased to announce that underlying profit before tax for the year ended 31 December 2025, subject to audit, is now expected to be not less than £90m, reflecting stronger results in the second half of the year.
Clarkson’s underlying pre-tax profit for the first half of the year was £39.4m, which tells us that the equivalent figure for the second half should be over £50m. An H2 profit weighting is common with this business, so not a particular concern.
Of course, the key piece of information missing from today’s trading update is the level of previous expectations.
Updated Estimates: checking for broker coverage, I’m grateful to Panmure Liberum for publishing an updated note on Research Tree this morning. From this I can see that the previous forecasts for 2025 pre-tax profit was £87.7m.
Thus we can see today’s upgrade is relatively modest. PanLib helpfully provides the following updated earnings estimates:
FY25E adj EPS: 219.3p (prev. 213.3p)
FY26E adj EPS: 242.1p (prev. 241.9p)
FY27E adj EPS: 280.6p (prev. 280.4p)
Roland’s view
Clarkson’s issued a major profit warning in May last year when it looked like the introduction of US tariffs could throw a spanner in the works for global trade:
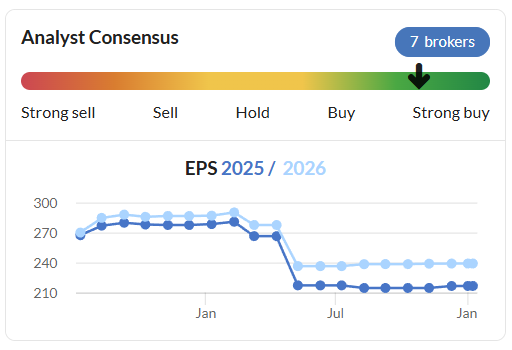
Today’s updated forecasts remain well below pre-tariff levels, but I see today’s upgrade as highlighting the resilience of this company, which has been in business since the 1850s.
Clarkson is considered the leading global shipbroker and operates across all major shipping segments, giving it access to a deep pool of data and relationships. I’m biased, as a shareholder, but I believe this gives the business a somewhat durable competitive advantage.
One criticism that’s often levelled at the firm is the large size of the bonus pool allocated to top-performing brokers. This includes CEO Andi Case, who is seen as the company’s top broker and took home an £11m bonus last year.
Bonuses are indeed large but this kind of profit-share arrangement is typical in this industry (most shipbrokers are privately held). The reason for this is that a large part of the value generated by such experts comes from the relationships they have. This is made explicitly clear in the annual report in the discussion of Case’s remuneration.
Personally, I don’t have an issue with this, as long as shareholder returns remain attractive. In my view, this is true.
Quality metrics are quite strong, with double-digit returns on equity:

… and Clarkson shares have delivered an annualised total return of 9% per year for the last 20 years, during which the dividend has never been cut:

My main concerns as a long-term shareholder are:
Future leadership might be less successful – Case has been CEO since 2008;
Geopolitical events could create dislocations that reduce Clarkson’s addressable share of the global shipping market. An example of this is the volume of oil that’s now transported by Russia’s so-called dark fleet of tankers. Previous commentary from the company has suggested to me that this has had a measurable impact on Clarkson’s activities in the legitimate tanker market.
Graham downgraded Clarkson to AMBER/RED when the company warned on profits in May. I upgraded this view to AMBER when guidance was reiterated in August and Panmure Liberum made a small upgrade to its forecasts.
The shares have risen by 15% since August and aren’t obviously cheap:
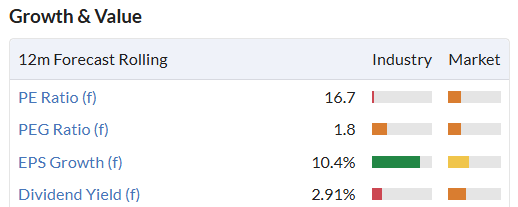
My choice today is whether to stick with our neutral view or upgrade one notch to AMBER/GREEN.
The StockRanks apply a Neutral style but highlight strong quality and improving momentum.
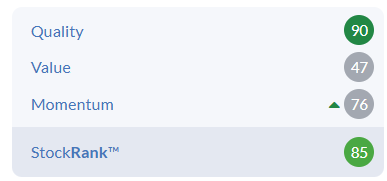
With a recovery in earnings forecast from 2026 onwards, I think there’s a chance this stock could be restyled as a High Flyer. I’m going to stick my neck out today and go with AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
I reckon Unite (LON:UTG) is a buy, students traditionally lived in HMOs but these are being regulated out of existence. Small landlords are being driven out by govt policies and rental demand is robust. The UK will soon be the no. 1 destination for international students thanks to Trump's xenophobic policies. I'm pleasantly surprised that Unite (LON:UTG) has spare cash for a buyback while paying 7% divi and self funding their development pipeline.
Unite (LON:UTG)
Oak Bloke discussed this point (likely demand/supply imbalance) and presented some useful statistics in his sub stack article of 4 Dec (PBSA Unite!https://theoakbloke.substack.c....
Be careful with your assumptions if students coming to the UK. An overseas student tax on being introduced. I think from this next academic year. It won't help.
Sorry for the poor typing.
The Unis will be charged £925 per year per int student. This is relatively low compared to their typical spend at a Russell group Uni of 50-60k per year.
But numbers are well down already and at least one university is closing down because of it: "It also said international student numbers at Southend had fallen by 52% since 2021-22."
24 others are classed as vulnerable.
Many courses are being pulled, which will decrease numbers even more.
I wonder if Chinese students might increase, US is not encouraging them?
As Roland says the UK grocery sector is hypercompetitive so margins will never be fantastic. I prefer to be their landlord by owing Supermarket Income REIT (LON:SUPR)
There was a TU for Quartix Technologies (LON:QTX) yesterday, There was little comment other than at the beginning. It is one of my favourite small companies and I put in an in depth analysis of the company later in the day yesterday. You may like to read it and comment if you wish. I look forward to reading any comments and responding.
The two Pauls mentioned Quartix on their weekly YouTube chat.
Afternoon folks.
For those with an interest in the mounting copper deficit, I said last week I would post the two pieces of analysis written by Will Thomson, CIO of hedge fund, Massif Central on Lundin Mining and their huge 50:50 JV with BHP called Vicuña Corp who own the Filo del Sol copper-gold mine on the Argentinian-Chilean border and the Josemaría — a large copper‑gold project located in San Juan Province, Argentina.
These two deposits together form one of the world’s most significant emerging copper districts, with multibillion‑tonne resource potential.
You can find Will's analysis here:
PART 1: The Transformation of Lundin Mining - Real Asset Handbook
PART 2: The Transformation of Lundin Mining (Part 2)
I forgot to add that Lundin Mining (TSE:LUN) is one of my largest positions.
I'm off to wade through 2 ft of snow to feed the sheep. I hope you have a warmer day than this.
I hold iShares Copper Miners UCITS ETF USD (Acc) (LON:MINE) . Doing OK at the moment.
Another way to get exposure to ICEYE (the driver of Seraphim Space Investment Trust (LON:SSIT) price increase recently)and the space sector is throughMolten Ventures (LON:GROW) About 10.9% of the portfolio is in Space, 6% in ICEYE. More info on the Investment Trust thread if your interested. https://www.stockopedia.com/co...
Roland great piece on Sainsbury's many thanks.
no more profits - let's screw our suppliers' cash flow even more!
I agree - great piece on Sainsbury's. The key issue as Roland rightly points out is the intense competition - against this background I guess an y-o-y increase that's about the same as food inflation is not to be sniffed at.
The stockrank to me is misleadingly high - is there any way of factoring competitive pressures or does that come under the heading, like moats, of do your own research?
Competitive pressure should be reflected in margins. Supermarkets tend to be very low margin suggesting lots of competition.
That has increased with the likes of Aldi and Lidl, opening more stores. I have far more of those near me than Sainsbury's. Until recently the nearest Saninsburys was about 20 miles. I never went there. Now Homebase have gone they have open one there. For years Sainsbury did nothing to grow their estate, Tesco were opening stores in most towns of any size.
At least they have opened quite a few convenience stores.
I thought there may have been some talk about the Govt. U turn on business rates on pubs.
there has been
https://www.bbc.co.uk/news/art...
its crazy that they could be so stupid as to excessively up bills - knowing the implications and bad press - and then for their own mp's to have to intervene for common sense to prevail (now is not the time for excessive rate increases when other sectors get away scott free)
some people will probbaly have made decision to shut up shop here based on the budget - imho if there is a climdown here as the original stuff should never have been levied at penal rates - this kinda demonstrates that RR is incompetent at her job - she should most certainly have avoided this farce. I dont generally like to use the word incompetent as theer are alot of moving parts when doing the budget - but i think imho its fair cop here.
I meant on here.
I heard many pubs were banning Labour MPs.
It did seem a rather clueless move, hammer a sector that is already struggling. Of course many more pubs would have closed.
Is the wider issue a problem with the Treasury and the expertise they provide or lack of it? How could the treasury not project these additional costs to pubs and other recreational businesses were simply astonishing and I think RRs problem is she accepts it and then presents it to the public as a great idea.
Is the wider issue a problem with the Treasury and the expertise they provide or lack of it? How could the treasury not project these additional costs to pubs and other recreational businesses were simply astonishing and I think RRs problem is she accepts it and then presents it to the public as a great idea.
i have no idea - all i do know is that she is the head cheese - its pretty obvious to me that any material changes to rates bills for pubs shops and the like is always going to gather alot of press - if she didnt know she shoudl most certainly have known - if she needed to have soemone who flagged up its her responsibility to have someone who can fact check if she is busy - so it could be civil servanmts created the issue - but her job was to spot it and not rubber stamp it if she didnt realise it was an almight f up.
To be slightly fair to her its happened before with stuff being done and then cancelled (tories did similar with taxation of double cabs - probably pasty tax) - so i am perhaps being slightly unfair singling her out.
there are othe important items going on the go though that are a potential shambles in the making too - mtd for income tax starts 06/04/2026 - thats been 10 years in the making and they have recently announced that beta testing is likely to carry on will after 06/04/2026 start date - unbelievable that having had 10 years they wont have a fully functioning system for the start date - the tricky bit is linking stuff up at year end an dit sounds like they dont have any plan in how to do that which is crazy for anything but super simple cases. And yet they are up to now refusing to delay mandation with relevant politicians saying its all in hand - if they had any courtesey they would admit its not fully tried and tested and delay mandation by 12th Months - if thats going to happen though they are flucking people about forcing them to plan for something thats a mess and may be delayed - even basic stuff like a person being mandated but they have ceased before start date i dont think has been sorted !! thats how much of a mess it is. ok RR isnt hmrc - but she is the one who has the power to delay mandation (or scrap it).
For years we have been hearing about "Zombie" businesses who are just managing to tick over. If a business can't make a profit surely it should stop trading and free up the space for someone else who can. Isn't this what capitalism is all about?
For years we have been hearing about "Zombie" businesses who are just managing to tick over. If a business can't make a profit surely it should stop trading and free up the space for someone else who can. Isn't this what capitalism is all about?
you want fairness in the system if rates bills and suddenly being hiked 66% over 2-3 year period and rates is one of your largest annual bills too start with its too much too quickly imho to be anything like fair.
Note places like spoons pay ridiculous % of turnover in taxes all in- way more than say supermarket. its matter of fact number of pubs is declining - that will directly lead to overall lower tax intake if you replace with something else. eg spoons pay 20% on their microwaved meals for customers whereas tesco pays 0%
at the same time overseas companies can sell goods into uk paying no vat no corp tax no ni and no rates - with almost nothijng levied on them.
multinational companies can extract profits at will paying no corp tax they just dress the extracted money up as an extra cost.
it all just seems a little loaded against this sector at present - hopefully that will be partly rectified to be not as penal.
imho none of this has anything to do with zombie business its just crushing certain sector withn extra costs year after year after year.
I occasionally listen to the Daily T podcast and Labour's attitude to pubs and alcohol is described as Puritanical. Starmer=Oliver Cromwell, aka Lord Protector. I am well aware of the dangers of alcohol and its over indulgence but do we want prohibition and the loss of the community benefit of the "local". I don't invest in the business having seen the damage caused by alcoholism but pricing it out of existence smacks of too much political interference in the same way that many companies were.
Another poor year for Fundsmith, poor excuses as well. 5 years underperformance.
It's doing what it sets out to do, marrying shareholders with companies that demonstrate long term operational outperformance. The market just has its sights on other factors (and AI mostly)
Accept it has not worked, recently. He has pick many wrong ones. His timing of buying and selling has not been good, see Adobe (NSQ:ADBE) Intuit (NSQ:INTU) and PayPal Holdings (NSQ:PYPL). He only held Adobe (NSQ:ADBE) for a short time,nsold at a lost and then the shares went about 60% soon afterwards. One of his stars has plummeted, see Novo Nordisk A/S (NYQ:NVO), l think he has lost his touch, l know he has had personal problems, which has not helped
He does hold one of the magnificent 7, just as well.
I think you must have posted the same about 20 times now. Good that you are getting better returns elsewhere. So what's your beef with TS? It's boring. Time to move on. Sell if you don't believe in the strategy.
We run an unhedged quality fund that has underperformed in 2025 against the usual benchmarks. But that's just a product of different factors attracting the market and USD weakness. The companies are doing fine, however, and we are happy business owners.
20 times? I'm just replying to different people. It is a forum?
I'm talking historically. You say much the same every time Fundsmith comes up on here. At least you know someone's paying attention!
Deleted
Hardly. I’m just bored of hearing about TS’s mistimed Adobe trades, when you could be considering his recent purchases. Is Wolters Kluwer a future victim of AI, as the market fears, or will this be an investing masterstroke? Is the undoubtedly superb business at EssilorLuxotica too expensive? Is the recent purchase of Zoetis simply a matter of pointlessly repeating his existing exposure to higher quality IDEXX Labs?
My view: WK possibly a good move. plenty of proprietary data as a moat. EL one of the best vertically integrated businesses in the world, we’ve been adding slightly above today’s price. ZTS feels like duplication in a weaker franchise.
Terry Smith annual letter
I thought Terry's point about the " Etf and trackers are momentum trading which is powerful while it lasts" was interesting and worth listening to!
Just a name, most PI's probably done just as well
My US folio has done far better in the last 3 years. Fundsmith uses the MSCI World Index for comparison. Over 70% of Fundsmith shares usually are in the US market, against the S&P500, it will look even worse.
Oh, thanks for the heads-up. I'll need to take a look.
The sister company, Smithson Investment Trust (LON:SSON) has had similar travails (-7.8% over 5 years), and might turn itself into an open-end fund.
Another quality investor, Lindsell Train Investment Trust (LON:LTI) is down a whopping 56% over 5 years, which is pretty shocking.
More broadly, I've noticed a number of individual quality shares take a beating (.e.g Greggs (LON:GRG) , but there are many more that escape my immediate recollection).
Hargreaves Lansdown, that was another one, at an astronomical valuation before it reached more sensible valuation.
The moral of the story is that valuation matters. "You pay a high price for a cheery consensus", and all that. Sure, quality companies do deserve higher valuations, but you have to be sensible.
I think that UK quality companies are now at more attractive valuations than they were formerly, so I'm reasonably hopeful. I think you have to dig down below the big-caps. Everybody knows about the like of Experian (LON:EXPN) , Games Workshop (LON:GAW) , etc., and they have valuations to match.
Plus, as well, perhaps these funds had the additional problem that if you didn't own a sizeable chunk of Nvidia, they'd have likely underperformed anyway.
Not sure about having to own NVIDIA (NSQ:NVDA), I have a very small holding but my US folio is way up. I do hold Alphabet (NSQ:GOOG) Apple (NSQ:AAPL) Shopify (NSQ:SHOP) Microsoft (NSQ:MSFT), these have done pretty well in the last few years, especially if bought when they were down. I did holdAdobe (NSQ:ADBE) and made a nice profit, did not sell when Fundsmith did, did not understand why he did that, apart he had just burnt his fingers on PayPal Holdings (NSQ:PYPL) seemed be purely based on the share price. Anyway some rather poor timing.
Problem with Fundsmith and Lindsell Train was that they were willing to pay high valuations for quality. This worked well in the low and falling interest rate environment we had since the dotcom bust but that era is now probably over. Having said that valuations are more reasonable now and rates may trend downwards so these stocks may be worth owning again.
Both Fundsmith and Train repeatedly said in earlier years that valuation did not matter for the best quality companies - this was clearly insane and there has to be an upper limit on what you pay. I suspect that's the main reason for their subsequent underperformance - they simply paid too much (plus one or two bad picks such as Diageo).
Thought his letter was spot on . If you want a tracker and just want to follow blind momentum move on
I want something that at least outperforms inflation. What is the point otherwise? May as well put it in a fixed rate bond.
Fundsmith has been been a very poor investment for me, fortunately it is only a small holding.
Hardly blinding following momentum if you buy the shares near their lows.
Anybody had issues losing watchlists in google finance ? normally I have 8 or 9 tabs with different lists but they have all disappeared and struggling to find the fix. Thnx
"Anybody had issues losing watchlists in google finance ?"
Yes, my watchlists have gone from the google finance app.
German stocks briefly stopped appearing yesterday as well, although they're back now.
I tried to re-install the app (on android), but that hasn't worked.
Now I'm simply accessing my watchlists via chrome.
i think i read recently that they are going away from App based and will be Chrome based only from now on so they could utilise AI better, i could be wrong though
Halma (LON:HLMA) The market likes the acquisition by the looks of it. Shares up 1.4%. Alas, this is one of those "shares that got away from me." Good quality company, but its value score is 7. I'm leery about investing in them.
J Sainsbury (LON:SBRY) Shares down 5.4%. The market obviously didn't like the trading statement. Roland said "Q3 LFL sales +3.4%, with grocery +5.4% LFL. Won market share over Christmas" I don't think there's anything to dislike about that. Shares aren't expensive, at a forward pe of 12.8. Pays a chunky divvie of 4.9%. Bit of a boring share, for sure, so unlikely to appeal to most on this site (including me).
Clarkson (LON:CKN) Shares up 5.4%. The market clearly likes the trading statement. This share appeared on my radar when I heard about it from a Nick Train video. He gets dissed a lot these days, mind. I like Nick, though. It passes my filter as a quality company. Over a decade, income and EPS has at least doubled. Net cash. Stock quality score of 90. Value score is 47, so not sky-high valuation. I don't hold, but I like it.
Hi Mark - Maybe Sains down due to fall in sales at Argos ?
CKN - Paul Scott highlighted this company a while ago - They have a history of channelling too much of the profit to the directors.
Halma - yes a great company but I just can't get my head round the price it commands
Clarkson (LON:CKN) - Paul Scott highlighted this company a while ago - They have a history of channelling too much of the profit to the directors.
Clarkson has returned around 200% over the last decade including dividends, which beats the UK indexes comfortably. The dividend has increased for 22 successive years. It's been a great long term investment.
Yes, employee remuneration is high and if you don't understand the business models they can look excessive, but these are typical of the shipbroking industry, which is still heavily reliant on individuals and relationships. However, that's not a problem if accompanied by these levels of return. The issue is when the money flows to employees and shareholders don't get their share.
timarr
I started buying Clarkson back in 2002. My first purchase was at £1.95 per share. It's made me a lot of money (thankfully in an ISA) as I bed and ISA'd it over a few years some time ago.
Halma - yes a great company but I just can't get my head round the price it commands
You need to value this on an EV/EBITDA basis, when it falls into line with other long term, highest quality industrial compounders like Diploma, Ametek, Lifco to pick one each from UK, US and Europe. But there are several more, all of which have charts you would wish to have owned. If you can't stand the valuation, pounce when markets flip out and then enjoy the probable re-rating if operational excellence continues, hopefully becoming comfortable with the high multiple along the way.
CKN - Paul Scott highlighted this company a while ago - They have a history of channelling too much of the profit to the directors.
It's actually more to the staff, which is a sign that what the company does is very highly skilled and locks the key employees into the business. I see it as evidence of a moat. The long term chart agrees. Perfectly good reason not to invest, of course. It's the reason we don't invest in banks. But I detect something different at play here and we own for the long term.
Clarkson (LON:CKN) It is a massive amount, most of the cash. Paul Scott said "On digging a bit deeper, I’ve found something rather alarming in the notes, right at the end, it says that most of the cash pile is due to be paid out in bonuses, a colossal amount!"
That was in 2022 year, the cash was over £200m.
Clarkson (LON:CKN) It is a massive amount, most of the cash. Paul Scott said "On digging a bit deeper, I’ve found something rather alarming in the notes, right at the end, it says that most of the cash pile is due to be paid out in bonuses, a colossal amount!"
No it's not and no it doesn't.
The accounts state that there's an employee bonus liability of £249.6m but that's a future accounting liability taking into account all of their bonus related obligations, many of them extending into the future, or in shares, or which will never be paid, etc, etc. It's a long-term liability, not a short-term one.
The short-term bonus liability is around £60m, which is typical of Clarksons, so their net cash position is around £150m, maybe a little more or a little less.
timarr
So it is around £60m this year. The net profit forecast is around £67m.
RE: Clarkson (LON:CKN) So it is around £60m this year. The net profit forecast is around £65m.
Yes. And?
Shipbroking agents get staggering bonuses for delivering business. That's the norm, and has been for the past decade while Clarksons' performance has left most other stocks and the UK indexes in the dust. Nothing has changed this year.
timarr
The brokers will get bonuses but most of the staff won't be brokers,
The shares have almost doubled in 10 years and the dividend is modest. Not bad but not exception. I would hardly describe it as leaving the market in the dust.
The shares have almost doubled in 10 years and the dividend is modest. Not bad but not exception. I would hardly describe it as leaving the market in the dust.
Since 2002 Clarkson has returned about 15% per year on a total return basis without dividends being reinvested. Anyone beating that is a very good investor indeed.
timarr
Yes but most people did not buy 24 years ago and still hold them. The last 10% years they have made around 7% pa. I did hold them until l found out about the where the cash was going.
RE : Clarkson (LON:CKN)
I did hold them until l found out about the where the cash was going.
If you bought Clarkson without understanding the business model you were lucky you made anything.
timarr
Well this was only brought to light by Paul Scott, this was never mentioned before. It was took away in the accounts.
lnteresting point you raise, it may help, if have deep understanding of the business, but quite a few successful investors, know liitle about the businesses they invest in, some don't even know what they do,
Well this was only brought to light by Paul Scott, this was never mentioned before. It was took away in the accounts.
No it wasn't, it's been known about for years. There was a shareholder revolt on this, this year, for the eighth year in a row.
https://www.thisismoney.co.uk/...
timarr
Well it was not mentioned on here, in any of the reviews, AFAIK, until Paul found it.
Well it was not mentioned on here, in any of the reviews, AFAIK, until Paul found it.
Which is, of course, why we should do our own research from primary sources rather than relying on second-hand analysis.
It's also worth noting that you wouldn't know about this from reading the RNS's as Clarkson never comment on the issue directly but simply publish raw voting numbers.
timarr
Clarkson (LON:CKN)
is it not a matter of fact that the 2 main directors got £14 million of bonuses last year ?
i understand the need for higher remuration to keep talent - but are we saying that the cpmpany couldnt get similar talent for say £5 mill pa all in £2.5 mill for each of teh tow main peple. Thats ignoring share awards too !!
on the basis "its always been like that and probably always will" i think there is the argument to be made its simply another cost of sales and should perhaps be ignored.
imho i do wander if they do need to pay this uber high amount though.
One danger of upsetting the talent would be that they might walk and setup in competition ? if this company has been trading since the mid 1850's though one would expect it would be able to stand on theior own two feet but that doesn mean it would be good if competition turned up at any sort of scale.
I simply dont understand how the talents of these two are such that they can command £15 million on then open market - surely they could find two people to do a decent job for £5 mill per year all in?
Note i would treat this company slightly different to B.P. Marsh & Partners (LON:BPM) that pay similarly high rewards - for B.P. Marsh & Partners (LON:BPM) the main man still owns large % of the company - so he imho would have the financial muscle to walk and setup in direct competition if he so chose - he could do that without much conflict of interest too with the shares trading below ntav - ie it would be very easy to runoff current investments without ongoing expertse of Mr Marsh - so if he sold up share price should necessarily crater if they went into runoff mode. I am not convinced it would be as easy for CKN directors to do the same - i might be wrong in that assumption though - and any direct competiton from group of ex employees is likley to mean lower profits to some extent.
Halma (LON:HLMA)
"Halma - yes a great company but I just can't get my head round the price it commands"
The valuation does indeed look very steep right now.
As BnB alluded to I believe that we need to look at the valuation of expensive-looking serial acquirers through a slightly different lens.
My own view is that:
That looks very expensive and it's not something that I would usually pay up for.
However, long-term growth is in excess of >10% pa, without any loss in profit margin and with debt looking reasonable (£530m) relative to the aforementioned cash generation.
If they keep doing what they've been doing, and the market believes that the multiple should remain elevated, then this should delivery nice returns in the long run, even at the current valuation.
I personally buy small positions in what I perceive to be quality serial acquirers, including Halma (LON:HLMA) . I find that they provide a strong, underlying foundation for the rest of the portfolio.
As a final point Halma's organic growth in FY26-H1 was +17.6%, which builds on the 9.4% achieved in FY25. Fingers crossed for more of the same.
A
Just some additional thoughts about J Sainsbury (LON:SBRY) . Share prices are down, as were Tesco (LON:TSCO) when it reported its results. None of the summary numbers seemed bad to me.
Sure, very pedestrian companies, but I'm still surprised by the market reaction.
It's interesting that you note that both may have benefited for stealing market share. I think it was Terry Smith that said there's probably only enough space in the UK for two or three supermarkets.
I vaguely heard that Asda was overindebted, so I asked Grok "Does Asda have too much debt?" Highlights:
"Yes, Asda currently has a significant debt burden that is considered high and problematic, especially given its recent financial performance and credit rating downgrades. Asda (owned by TDR Capital following its 2021 leveraged buyout) has been dealing with elevated debt levels since the acquisition."
Ah! That's the kind of thing I want hear if I were a shareholder in TSCO or SBRY.
"Fitch downgraded to 'B' (Negative Outlook) in November 2025,"
Which translates as "material default risk is present."
By the way, I'm really getting into this whole Grok. It's very good at capturing an overview of what's going on, assuming it doesn't give the investing equivalent of adding glue to pizza.
So, maybe TSCO and SBRY can continue to steal market share as Asda runs out of room to manoeuvre. Just a thought.
why doesn't the market cap on Galantas Gold move on Stockopedia? Its been 2 days now. How can your system be lagging so much?? We are paying for this service and we want to be able to rely on the information for our decisions. It has been stuck on £16.35m.
Use the contact support button under the S beige button top right of app
Same for Tungsten West (LON:TUN) new shares in issue take time to update