Daily Stock Market Report (Mon 24 Feb 2025) - BME, MEGP, XPS, TSTL, BPM, SUPR, GHH, PFC

Good morning and welcome back! The Agenda is now complete.
1pm. Wrapping up for today, thank you!
Spreadsheet that accompanies this report: updated to 14/2/2025.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
National Grid (LON:NG.) (£36bn) | Sale of NG Renewables | Sale of US onshore renewables business to Brookfield Asset Mgt for $1.7bn. | |
B&M European Value Retail SA (LON:BME) (£2.9bn) | Update on FY25 guidance | Profit warning: FY25 adjusted EBITDA now exp £605-£625m (prev. £620-£650m). CEO retiring. |
BLACK / AMBER/RED (Roland) |
Supermarket Income REIT (LON:SUPR) (£882m) | Update on Portfolio Initiatives | Tesco disposal & lease renewals above benchmark. Further Carrefour acquisitions in France. | AMBER/GREEN (Roland - I hold) [no section below] |
ME International (LON:MEGP) (£837m) | Final Results | 2024 rev +3.4% to £308m, PBT +9.4% to £73.4m. Laundry driving growth. Key cut service launched. | AMBER/GREEN (Graham) PBT of £76-80m is forecast for the current year. This would continue the path of solid, undramatic growth. I don't view this as a bargain at current levels, but I do retain our moderately positive stance. PER c. 14x. |
| XPS Pensions (LON:XPS) (£806m) | Acquisition of Polaris | Buys an insurance consultancy for £23m cash upfront plus up to £35m payable in three years. | AMBER/GREEN (Roland - I hold) [no section below] |
Georgia Capital (LON:CGEO) (£513m) | Final Results | FY24 NAVps +12% to 27.14p. NCC improved by 3.1% to 12.8%. Positive outlook. | |
CLS Holdings (LON:CLI) (£285m) | TU | 2024 EPRA earnings and NTAV to be in line with market exps. FY portfolio valuation -5.8%. | |
B.P. Marsh & Partners (LON:BPM) (£240m) | TU | Group funds £74.1m (LY: £40.5m). Robust pipeline of potential new & follow-on investments. | GREEN (Graham) A reassuring update. The company might have more cash than it needs but that's a nice problem to have. Now trading much closer to NAV than it did before, so the arguments for remaining positive have to be a little more nuanced. |
Tristel (LON:TSTL) (£167m) | Interim Results | Following a solid first half, trading remains in line with exps for year to June 2025. | AMBER/GREEN (Roland) |
Gooch & Housego (LON:GHH) (£114m) | AGM TU | Closely monitoring impact of tariffs. Assuming success in navigating tariffs, exps are unchanged. | AMBER (Graham) Positive order book improvement (£126m) helped by an acquisition. Further bolt-ons are possible. More flexible now with some manufacturing outsourced. May need to raise prices for customers due to tariff-related inflation. Stock offers some value currently against forecasts, with the adjusted P/E falling to 10x. But the company has been around for a long time and while performance has been ok, it hasn’t been exciting. Quality might be just average at the end of the day. |
Petrofac (LON:PFC) (£38m) | Update on Financial Restructuring | Existing shareholders to be allocated 2.2% of existing share capital (previously 2.5%). | RED (Graham) New equity raise increased by $30m, total equity raise becomes $224m. Some creditors are also offered additional equity ($25m). Court proceedings 28th Feb. Can review my negative stance on this when the dust settles and it’s refinanced. Will be on much more stable footing when this is done. |
Arcontech (LON:ARC) (£14m) | Interim Results | Rev +4%, adj. PBT -7.5%. Net cash £7.2m. Trading in line with exps, confident in full year outturn. | |
Croma Security Solutions (LON:CSSG) (£12m) | Half-Year Report | Solid performance since half-year. Trading well in a challenging environment, confident in outlook. |
Graham's Section
ME International (LON:MEGP)
Down 3% to 215.5p (£810m) - Annual Results - Graham - AMBER/GREEN
Roland already covered the year-end trading update here.
Therefore, many of the financial headlines published today were already known.
One small clarification is that in its year-end update, MEGP said that its full-year EBITDA was “not less than £112m”. The actual result is £114m.
Currency movements were a noteworthy headwind, which we already knew they would be, knocking £10m off revenues and £3m off EBITDA, as the value of Japanese Yen and Euro revenues declined against the pound.
Without the currency headwind, revenues were up 6.8%.
Including the currency headwind, revenues were only up 3.4%.
Similarly, EBITDA was up 10.1% if you adjust out the currency headwind, or up 7.1% including it.
They are “exploring options” to mitigate currency risk. I don’t think they particularly need to: I think their profit margin is wide enough, and their balance sheet healthy enough, that they can afford to ride out currency volatility. But they say they might want to hedge their “large GBP commitments”, such as dividends.
Laundry is the main growth driver at the moment. Revenues in laundry rose from £76m in 2023 to £90.6m in 2024.
Photobooth revenue was about flat, after taking into account the currency headwind. Photobooth is still responsible for the majority (56%) of MEGP’s revenue. This division is just treading water for now.
The KPIs help to summarise the situation: there is ongoing fast growth in laundry units, while the number of photobooths declined (but the company is spending heavily to modernise them).

PBT margin remained very nice at 23.8%, up from 22.5% the previous year. PBT was £73.4m.
Net cash finished the year strongly again at £38m (previous year: £34m).
Historically MEGP has been a strong cash generator. Checking the summary cash flow statement, I see that in 2024 it generated £87m (after-tax) from operations. Capex spend was <£55m, nearly half of which related to growing the laundry business.
CEO comment:
"I am pleased to report a year of strong strategic progress with record profitability for the Group.
"We have continued to deliver on our long-term strategy of expanding our laundry business across new and existing geographies, which is a key focus for the Group, as well as upgrading our well-established estate of photobooths.”
MEGP has launched an automated key-cutting service, Kee.ME, but it doesn’t seem to have a functioning website yet, unless I’m mistaken. Hopefully it will have a website soon?
I live within five minutes of an enormous Tesco that already has a MEGP photo-booth, a set of laundry machines and many (far too many!) of their children’s rides. I’ll be keeping an eye out for a new automated key-cutting service on site. If it arrives, it will compete directly with a Timpsons that has been there for years.
Outlook: the CEO tells us that in 2025, they are planning to install 1,200 laundry machines, costing £28 - 32m. They have signed multi-year agreements with an independent forecourt operator (300 machines) and Morrisons (200 machines).
The Chairman says that the Board is anticipating PBT of £76 - 80m.
Graham’s view
Roland was AMBER/GREEN on this in December at the same share price (215p) and I have to wholeheartedly agree with him.
Some reasons to like the stock:
Excellent competitive position - highly visible and recognisable machines in public spaces, and multi-year agreements with the owners of the sites who are only too happy to host the machines for additional footfall. International scale and expertise. Difficult for competitors to muscle in on this.
Good cash generation historically and a nice net cash position. Negative: maintenance capex is expensive as photobooths are replaced with next-generation machines.
Shareholder-aligned management (three members of the Crasnianski family).
Reasons to be negative:
There will always be concerns that photobooths will become obsolete due to phone cameras. This has been said for years but people continue to use photobooths!
Valuation: stock has 5-bagged since its post-Covid low, and is more expensive now in P/E ratio terms than it usually has been in the past. PER c. 14x.
Limited top-line revenue growth. Demand for photobooths and laundry units is hardly going to outstrip the growth of the economy as a whole?
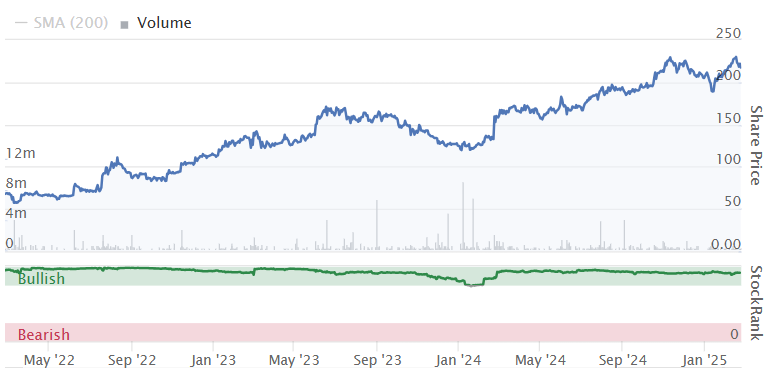
StockRanks love MEGP even more than I do, with Momentum playing a big role in supporting its score:

Well done to those who've been holding it in recent years:
B.P. Marsh & Partners (LON:BPM)
Up 6% to 689p (£255m) - Trading Statement - Graham - GREEN
B.P. Marsh & Partners Plc (AIM: BPM), the specialist venture capital investor in early stage financial services businesses, provides an update on trading for the Group's financial year to 31 January 2025.
This is a reassuring update, although we don’t yet know what the new Net Asset Value calculation will be. NAV as of July 2024 was £253m.
For now, we are reassured that BPM is enjoying “continued strong performance from the portfolio”.
After some large disposals last year, it has an enormous cash balance (as a percentage of NAV) of £74m.
The plan is to reduce this cash balance by paying out £5m in dividends every year for three years, starting in the current year (FY Jan 2026).
It also wanted to buy back a small quantity of its own shares (£1m). The original policy was to do so when the shares were trading at a discount of 20%+ against NAV.
That was modified until only a discount of 10%+ was required.
But even that discount is no longer available:
The current discount of 5.55% to our Net Asset Value per share has now meant the Company is unable to buy back shares under its Share Buy-back programme, but is subject to review
Hopefully, the company will have plenty of productive ways to use its cash balance, rather than leaving it on deposit. There is “a robust pipeline of potential new and follow-on investments”.
Disposals: BPM reviews its highly successful investments, Lilley Plummer and CBC, that it sold last year.
New investments: three new investments were made in the year to Jan 2025. It’s highlighted that “origination continues to be network-driven and management team partners are often well known to B.P. Marsh”. Investment sizes are modest but hopefully can still move the needle given the increased scale of its overall portfolio now.
Follow-on investment sizes were larger: $12.6m into US-based XPT and £12.5m into Pantheon.
There is detail given on performance at certain investees for those who wish to read more.
Insurance market outlook: not much has changed here but it all sounds quite positive and I would say reassuring. Remember that catastrophe insurers have had a lot to deal with recently:
The Group continue to track key trends in the insurance sector in which we operate, with a specific focus on premium rates and mergers and acquisitions (M&A) activity.
Given the portfolio predominantly operates in specialist risk areas, rates tend to be less volatile and therefore we remain confident that our portfolio is suitably prepared to weather a softening market.
The ongoing consolidation trends in the insurance market show no signs of slowing down as we move into 2025. This activity remains a catalyst for substantial prospects for the Group, both in terms of new investments and activity within our core portfolio.
Furthermore, both the Group and its portfolio companies continue to attract interest from entrepreneurial individuals and teams who are seeking to remain outside of this consolidation process, creating further avenues for new investments, strategic partnerships and expansion in the year ahead.
Graham’s view
I tend to be GREEN on this one. Today, however, I have to face the challenge of valuation: the company no longer trades at a discount that makes it very easy for me to think it’s undervalued. It’s up 20% since I covered it in October.
However, I view this company as a long-term winner and a compounder, so I’m inclined to leave my stance unchanged even if it is now trading around its NAV.
All the reasons I liked before still stand: it has specialist expertise and it sticks to its knitting; its culture attracts staff who stay for many years; it invests in areas which aren’t easy for private investors to access.
It does face the same challenge as the likes of JDG and other successful compounders. Due to its past success, it now faces the challenge of deploying more capital. But that’s a nice problem to have.
Some might also think that there is key man risk with Brian Marsh OBE, who owns over 38% of the company.
Personally I have little hesitation in remaining positive on this one. I also note that this stock made it onto Ed’s New Year Naps for 2025 and clearest trending small caps.

Roland's Section
B&M European Value Retail SA (LON:BME)
Down 5% to 275p (£2.7bn) - Directorate Change & Update on FY25 Guidance - Roland - BLACK (AMBER/RED)
Bad news for shareholders in this discount retailer – it’s a profit warning today:
The Company today updates its previously disclosed profit guidance range. FY25 Group adjusted EBITDA (pre-IFRS 16) is now expected to be in the range of £605m to £625m, which reflects the current trading performance of the business, an uncertain economic outlook and the potential impact of exchange rate volatility on the valuation of our stock and creditor balances which is a non-cash item.
Let’s unpack this a little. B&M’s last update was in January, when the company narrowed its EBITDA guidance to £620m-£650m for the year ending in March 2025.
Today’s updated EBITDA guidance of £605m to £625m represents a reduction of 3%, if we take the mid-point of each range.
Estimates: I don’t have access to broker notes, but B&M’s FY24 results showed EBITDA of £629m converting into adjusted earnings of 36.8p per share.
Consensus EPS forecasts were c.35p ahead of today. I’d pencil in revised earnings estimates of perhaps 34p per share.
Comment: B&M has previously commented on consumer spending and the general economic outlook, so I’m not surprised to see these factors stated as reasons for lower guidance.
The comments on exchange rates are said to relate to US dollar stock purchases and are expected to reverse out in FY26 when currency hedges are settled and the stock is sold. I don’t think there’s anything to worry about here.
Overall, this is a relatively small profit warning, but it comes on the back of a sequential reduction in expectations that had already seen FY25 earnings consensus fall by 13% before today’s warning.

CEO Departure: CEO Alex Russo has decided to retire and will leave the business on 30 April 2025.
Russo joined as CFO in 2020 and was appointed CEO in September 2022, taking over from former owner-CEO Simon Arora.
He’s thanked in today’s announcement and the search for a successor is underway. However, an unplanned departure after just over two years in the role suggests to me that the board may also feel that fresh leadership is required.
Roland’s view
I have previously been a fan of this business, viewing it as well run and with significant quality advantages compared to the main supermarkets.
Profitability and cash generation have historically been excellent:

Today’s update isn’t good news, but the shares are now down by 50% in 12 months and trading on a single-digit P/E.

I would argue that plenty of bad news is now priced into the shares.
However, I wonder if there’s now some risk that a broader financial reset may be needed, including a cut to the company’s (fairly generous) ordinary dividend.
Despite negative LFL sales over the last year, the group has continued to expand fairly aggressively in the UK and in France.
As Graham commented in January, B&M uses a little more debt than seems necessary. The recent £150m special dividend could perhaps have been more prudently used to reduce borrowing levels.
Another potential concern is that Trading Director Bobby Arora (former CEO Simon’s brother) will be retiring in March. Historically, he has masterminded B&M’s stock buying and its regularly refreshed seasonal offers.
I’m tempted to stay neutral here, but I feel that prudence dictates a shift to AMBER/RED until we learn more about B&M’s FY25 financial performance and FY26 outlook.
Tristel (LON:TSTL)
Up 0.3% to 348p (£166m) - Interim Results - Roland - AMBER/GREEN
The headline news is that there is no change to full-year expectations for this manufacturer of infection prevention products (my bold):
The Company remains cash generative, debt free, and maintains a progressive dividend policy with an 8% increase in the interim dividend. Following a solid first half, trading remains in line with expectations for the year to 30 June 2025.
This is consistent with the guidance provided with Tristel’s AGM statement in December, which we covered here.
Tristel shares are unmoved today, reflecting the unchanged outlook. But today’s interim results do contain some points that are worth highlighting, in my view.
Half-year results summary: Tristel sells disinfectant products that use a proprietary chlorine dioxide technology for the contamination of medical devices and surfaces under the Tristel and Cache brands, respectively.
Today’s half-year results cover the six months to 31 December 2024. They show solid but unspectacular growth in sales and profits – albeit with one or two niggles.
Revenue up 8% to £22.6m
Reported pre-tax profit up 9% to £3.7m
Adjusted pre-tax profit up 19% to £4.9m
Adjusted EPS down 5.9% to 8.17p per share
Interim dividend up 8% to 5.68p per share
Net debt Cash of £11.7m (2023: £10.8m)
A couple of points are worth highlighting here.
Adjusted PBT: the gap between adjusted and reported PBT relates to remuneration costs, of various kinds. I would be inclined to include these costs in my estimate of profits:
Adjusted for share-based payments (£0.3m) and exceptional succession costs (£0.9m), totalling £1.2m (2023: £0.7m)
EPS fall: despite higher pre-tax profit, earnings per share (calculated post tax) fell.
This was due to an increase in the group’s effective tax rate from 10% to 25%, causing the tax charge to rise to £0.9m (2023: £0.4m).
Tristel’s tax rate seems to vary a lot from year to year. I’d need to do further research to understand why, but I’d probably assume it will stay over 20% unless guided otherwise.
Profitability: this is a profitable business. An 82% gross margin translated into an H1 operating margin of 16.2%, highlighting Tristel’s pricing power.
My sums suggest a trailing 12-month return on capital employed (ROCE) of 19.6%, consistent with prior (non-COVID) years:

Trading commentary: sales growth of 8% (£1.7m) during the period was split between additional volume of £1.3m and £0.4m from price increases.
Management says H1 sales growth was slower than in recent years for two specific reasons:
Higher than usual sales staff turnover in France and Australia
Dilution of sales efforts away from the core Tristel products towards the “less well-known Cache Surface range”. This situation is now being managed to achieve a better balance of effort.
Tristel already has a big market share in the UK, via its NHS footprint. The big story for many years has been the potential for this business to break into the US market.
Having achieved the necessary FDA approval in 2023, hopes were high, but this process has got off to a slower start than expected. I believe this may have contributed to the change of CEO in September 2024.
Previous commentary has seemed to me to suggest a lack of sales resource and know-how on the part of Tristel’s US partner, Parker Laboratories. Today’s commentary suggests the situation is now improving:
Our longstanding partner, Parker Labs, remains deeply committed to the growth plan. It has invested heavily in building a national sales force while leveraging its established distribution network for the USA and Canadian ultrasound markets. This dual approach strengthens our market presence and supports long-term growth.
However, financial results remain limited, with Americas revenue of just £96k during the half year:

The company says it is making meaningful progress and starting to see broader adoption following early wins. Examples are given in Florida and Massachusetts, where health systems are rolling out products across multiple sites after initial adoption at a single site.
However, there’s clearly a long way to go. Australia, a far smaller market, generated £1.9m of revenue in H1.
Outlook & Estimates: CEO Matt Sassone and Chairman Bruno Holthof are both keen to emphasise that Tristel’s focus will remain on international growth:
We are pleased with a solid first six months and the Board remains confident in the outlook for the year, with international expansion continuing to be a key driver of growth.
Tristel says it remains on track to meet its internal target for revenue growth of 10% to 15% CAGR over the three years to 30 June 2025.
House broker Cavendish has provided a more detailed update today – many thanks for this coverage. These updated estimates show revenue growth being trimmed slightly to sit at the lower end of the company’s target range.
Cavendish says this is due to slower US sales growth than expected, but its analysts expect cost control to remain tight, supporting strong margins. As a result, earnings expectations are broadly unchanged for FY25 and have increased for FY26:
FY25E: adj EPS 17.46p (-0.8%)
FY26E: adj EPS 18.08p (+8.3%)
These estimates leave Tristel shares on an unchanged rolling forecast P/E of c.20:

Roland’s view
Earnings forecasts for FY26 have been cut twice over the last year. Today’s update from Cavendish doesn’t reverse this but is a step in the right direction:

It’s clear that achieving volume sales in the US has turned out to be much harder than expected. Aside from any shortcomings in Parker Labs’ sales force, Tristel says it has faced “stringent purchasing bureaucracy”.
Today’s downgraded revenue forecasts are disappointing in my view, as this is ultimately meant to be a sales growth story. Ultimately, cost control isn’t the big issue here.
The risk remains that Tristel will turn out to be another successful British company whose efforts to conquer the US market are unsuccessful.
However, the new CEO seems a good fit and has previous US healthcare experience. Early signs of progress and new sales initiatives – such as targeting “less-bureaucratic physician offices” – may help to get US growth back on track.
I don’t think the story has changed today. But the results are a reminder that the next phase of growth could be a little slower than hoped for.
Strong profitability and a net cash position mean the P/E of 20 and 4%+ dividend yield look plausible to me as a possible entry point for bulls. But slower progress on revenue has prompted me to downgrade my view by one notch to AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Supermarket Income REIT (LON:SUPR)
I see there a lot of holders here, so I hope that someone more knowledgeable than myself can help me understand a couple of things.
Looking at the 2024 Cash Flow Statement, it looks as though:
(I believe any interest rate hedges are already included within the Operating Cash Flow figure, with movements from new hedges listed under Financing Cash Flow.
If this understanding is incorrect, I'd be happy to be corrected #alwayslearning)
Does this imply that the dividend can only sustainably be maintained through asset sales, like the one today?
Another thought I had centred is on the annual rental increase cap included in many of Supermarket Income REIT (LON:SUPR)'s agreements.
Today's announcement stated that new 15-year leases were signed with Tesco, which will be reviewed annually, are RPI-linked and are capped at 4%.
Is there a risk here that returns don't keep up with inflation going forward? RPI in the UK just hit 14%. Who's to say it won't reach these heights again over the next 15 years?
I would be interesting to hear if my understanding above is correct or if I'm missing something obvious.
Many thanks in advance.
A
Hi abtan
I think that's all roughly correct. As a REIT it has to distribute 90% of its earnings so the dividend is only ever just covered. In some years it ain't and some years it is. And the debt means it's doubly interest rate sensitive, with inflation risk thrown is for good measure.
However, I don't really trust (or perhaps it would be truer to say that I don't understand) the cash flow statement due to the adjustments. By the company's own measure of adjusted eps then the dividend is (just) covered by earnings:
The metric adjusts EPRA earnings by deducting one-off items such as debt restructuring costs and adding back finance income on derivatives held at fair value through profit and loss. Adjusted Earnings is considered a better reflection of the measure over which the Board assesses the Group's trading performance and dividend cover.
While I recognise that, for example, the fair value of buildings needs to be accounted for I don't see how that is, in any meaningful way, a cash flow. Yet this is the norm. As ever accounting is its own special kind of magic.
Overall, though, I don't see there's much risk here. The assets are real, the annualised passing rent is increasing (12% last year, through acquisitions and renegotiation), operational costs decreased and interest rates are (slowly) going down.
It's easy to see why this and other REITs are trading at large discounts. In common with a lot of them the only way it can grow is by recycling assets and taking on debt, as there's no possibility of issuing equity, so there's a dependency on the skill of the managers as well.
I don't see much short-term risk here to either capital or income , and there's a reasonable chance of a re-rating. Will it shoot the lights out though?
Nope!
timarr
This year hasn’t started the way I’d hoped, with my portfolio down 2% so far. My largest position Warpaint London (LON:W7L) hasn't been much help. After reviewing my portfolio, I’m still confident in the quality of the companies I hold. However, I’ve started trimming positions when they reach a 20-25% profit- Mortgage Advice Bureau (Holdings) (LON:MAB1) being a prime example. Right or wrong, that’s the approach I’m taking. I would normally hold, but I think I have started to grasp for small bits of some positive return. Keen to hear other peoples approach at the moment.
Warpaint London (LON:W7L) YouGov (LON:YOU) and Solid State (LON:SOLI) have caused damage to my portfolio with typically 30% - 40% down each position and I do topslice. I would normally hold on for as long as I can. The three mentioned have seen 50% to 100% gains however after a shock I do question if I should have trimmed earlier or sold out completely. This is a tough call and for me can work negatively the other way for example Rolls-Royce Holdings (LON:RR.) and with a top slice sometime ago reached 100% gain last week, I now start to think why did I topslice!! Overall this year also has not started the way I had hoped. I think the decision needs to be made on a stock by stock basis particularly with unpredictable AIM stocks.
Thanks Douglas1971, I know exactly what you mean. Luckily I had top sliced Warpaint London (LON:W7L) a few times hitting over 200% gain, so the damage could have been a worse. I think top slicing at those type of gains is probably sensible, but 25% gains is probably not my usual habit. I also have many examples of selling/top slicing too early.
I think you have answered your own question there, Lefty. Top slicing at a 25% gain is probably a recipe for disaster. You will effectively be reducing the impact of your winners whilst still being exposed to all the stocks that go wrong. A 200% gain is a different matter, of course.
I can't disagree, I can only blame the current situation. All we need is everything to go up then we will all be happy.
I guess a few of us have some holdings that are down 25-30% due to shock TU's. I let winnings run until they get too big then slice but only in a BULL UP Trend . With the current market it is better to take decent profits ...there is no real trend and it is struggling. Hence i am cautious.
Ha, what's a BULL UP trend I've forgotten?
I read in the book Unknown Market Wizards, which i thought was interesting, a trader called Richard Bargh sets a target and once reached sells most of the position only leaving a small percentage still in play. If the SP still moves in the desired direction that’s great still making a small profit but if the run is over the risk has already been reduced.
Yes, running your winners, certainly does not always work, especially in this market, l hold Warpaint London (LON:W7L). Mortgage Advice Bureau (Holdings) (LON:MAB1) is another l hold, l did manage to sell half when over 900p. PayPoint (LON:PAY) Is another. CMC Markets (LON:CMCX) another. Time Finance (LON:TIME) also. I'm top slicing many of my winners but not at 25% gains. Although Robbie Burns does often sell for smaller gains.
Very mixed year.
Hi Rusty, I hold all those apart from CMC Markets (LON:CMCX) . Did well on all apart from Time Finance (LON:TIME) , a bit late to the part on that one. Yes Robbie Burns is very strict, but I guess profit is profit.
The one's that normally show Robbie a small profit are generally new (ish) trades if he buys a new stock and it goes up a bit and then starts reversing he's out, having attended a few of his seminars I would say he's in the top 1% on the planet when it comes to stop loss/money management.
I do hold Mortgage Advice Bureau (Holdings) (LON:MAB1) l did average down when it fell below 700p, sold most when they went up. I'm looking at charts to indicate when to sell. Many are falling back, probably due to profit taking.
Rusty if the chart shows Many are falling back, why would you say probably due to profit taking.
Could it be a growing sentiment that markets are overpriced and disrupted by American and Geo politics? Is that bear stirring from hibernation? Warren Buffetts Berkshire Hathaway is reported to be sitting on a recored $334 in cash "probably / possibly" waiting for VALUE?
I know that I am currently looking carefully at all my stocks, but then to be clear - I am rapidly approaching retirement and well aware of that bias on my personal investing strategy
I'm selling before they fall back hopefully. If you look at Mortgage Advice Bureau (Holdings) (LON:MAB1) PayPoint (LON:PAY) Time Finance (LON:TIME) charts, all spiked up a bit then fell back. Sure you can find exceptions such as Audioboom (LON:BOOM) but that seems to be a trend at the moment.
Many US momentum stocks have fallen back, see Ed's article on top trending momentum stocks. Many looked well overpriced to me, high PE but low growth. The folio is down around 12% since it was published.
Zotefoams (LON:ZTF) and Oakley Capital Investments (LON:OCI)
Well either the market has got it wrong or I have. Given patience, I am happy to back my judgement.
I have added to both of the above this morning.
Zotefoams (LON:ZTF) Added at 282p. The new CEO, Ronan Cox took the sensible decision to shelve investment in Rezorce in late 2024, since which time the shares have de-rated significantly. This has removed the froth and the drag on finances and management time that can now be focussed on the core business that is trading well, as evidenced by the recent update.
With Rezorce on the back burner investment metrics, ROCE, ROE and the like should improve. The company has a presence in America where it is investing in a second low pressure vessel and additional warehousing, so tariffs shouldn't be an issue. If the company can reach agreement with other sports shoe manufacturers, similar to that with Nike the shares will look even cheaper. A lot to play for if you will pardon the pun.
Oakley Capital Investments (LON:OCI) Added at 470p. There has been consistent buying by directors above the current share price. One only has to look at director dealings on the stock page to see the extent. The last reported NAV was 695p on 29 January. Given the extent of director purchases and discount to NAV in excess of £2 it just looks too cheap.
All the best
I have mentioned before that I think Schroders is selling down their holding in #ZTF. It is a large holding and they have just reduced by a small amount so far plus it is an illiquid stock and there seems to be very little buying to soak up sells, therefore it is quite possible that the price of these shares could fall for a good while yet, till Schroders reaches the holding they want. With no more Rezorce the investment thesis may have changed for some holders. One to watch for the moment?
*IRAQ MINISTER: HOPE KURDISTAN OIL EXPORTS WILL RESUME IN 2 DAYS
#GKP #GENL
Hi Roland,
In your review of Tristel (LON:TSTL) you highlight
Net debt of £11.7m (2023: £10.8m)
But isn't that their net cash position not net debt. My understanding is they are debt free.
Tristel (LON:TSTL) Yes this is cash not debt: "No debt and cash of £11.7m (2023: £10.8m)"
I think Roland has misread that.
I'll fix that in the report, thanks. G
ME International (LON:MEGP) ( i hold) IMHO is an extraordinary business. It has three things going for it. cashflow cashflow and cashflow. It's so boring it's almost perfect. It's vending with no staff! (relatively). NI increase? No problem. Imagine building 90 mini laundrettes a month every month. 3 a day.
And that's diversifying. Imagine still making £173M from legacy photobooths when everyone now has a camera in their pocket..(have you tried taking your own passport photo ? It's too hard.). . I also like that they got rid of the terrible Pizza vending. Sure - it's good to innovate. But then get rid quickly if it tastes bad. As the Zuck says - fail fast.
If like Munger, you like 'invert' to understand stocks - then it's the polar opposite of Bitcoin & Tesla. It's not sexy, it's low on narrative, high on cash , great margins & good on management. For me at least -the future is vendy not EV paid in BTC.
Today's profit warning from B&M European Value Retail SA (LON:BME) will surely test Ed's ideas on such an instance, I hold. The question is, BME being a Consumer Cyclical will it come back with vengance? Especially if Rachel recants. My better half says BME isn't so busy in Trowbridge or Chippenham (she is a Bargain Hunter) post-Covid as before so I'm thinking of selling out as per the prescription and adding to my Serabi Gold (LON:SRB) which seems to be on an inexorable ascension.
"My better half says BME isn't so busy in Trowbridge or Chippenham"
I have posted a similar story before, one reason perhaps being that it does not seem to offer the value it once did.
The store near where I live is one of the older stores and is a rather drab. Last time I went in only the small kiosk till was being staffed. In fairness to B& M , the store must be one of older units which is difficult to make into modern retail space - but its only the type of place you would go if it was cheaper than elsewhere.
I have mentioned before that I think that B&M is getting squeezed from all sides. My nearest town has an Aldi, Lidl and a Home Bargains which all appear to be very busy in comparison. We have Asda and Morrisons also fighting back for lost market share. It is a very competitive environment.
Selling on this profit warning might be the best action here.
B&M European Value Retail SA (LON:BME) are not cheap for household groceries. Most items are cheaper at home bargains. Also many items they stock such as protein powder etc are miles cheaper on amazon. Not surprised they are struggling
Also many low value items can be purchased from the likes of Temu etc this must be affecting sales
Totally agree, this is akin to Boohoo/Asos communicating poor logistics and/or poor consumer demand while Shien was slowly eating their lunch. Temu is now slowly eating the value retailers lunch, not all product lines but many. Customer wins with lower prices but Govt tax receipts lose (VAT, Corp Tax, UK PAYE/NI all lost).
Re : Supermarket Income REIT Supermarket Income REIT (LON:SUPR) : Today they announce :
- the sale of theNewmarket Tescos for 7.4% above the June'24 valuation, and
- 4 leases renewed "at an average 4% rent to turnover1, 35% above MSCI's supermarket benchmark index and 13% above the Company's valuer's estimated rental values (as at 30 June 2024)".
Does this put to rest the fear that SUPR's estate was "over rented"i.e the current rents would not be achieved if put up for rent afresh in the open market ? Plus assurance on capital values ? [I hold].
Regards
Geoff
Does this put to rest the fear that Supermarket Income REIT (LON:SUPR)'s estate was "over rented"i.e the current rents would not be achieved if put up for rent afresh in the open market ? Plus assurance on capital values ? [I hold].
You would think so, although it never seemed like a real issue to me. Sometimes commentators spend a lot of time looking for reasons for over or underperformance when the real reason is simply people buying or selling, often because other people are buying or selling.
Markets aren't intelligent but humans aren't very good at accepting that sometimes stuff just happens.
Look across the landscape of REITs and SUPR's performance isn't out of line with many others, although its risk profile appears to be lower. Arguably, perhaps, the potential upside is less but it's certainly a decent option for someone looking for inflation protection and potential capital upside as interest rates slowly grind down.
But frankly, the discounts on a lot of REITs at the moment just look wrong.
timarr
Either way I think its a positive announcement.
SUPR bought the Newmarket Tesco in 2020 for £61m and sold 5 years later for £63.5m whilst collecting the yield.
Also think its good to divest away from Tesco which currently makes up almost 50% of their portfolio, not to mention pushing more into Europe.
Look forward to hearing Ken Mitchells thoughts!
JSchoffer.
Thanks for wanting my thoughts too on the Supermarket Income REIT 72p (LON:SUPR) news today, but reading through Roland’s summary and some great posts on it here already, including from timarr, I can only add a bit not already covered, and respond to a couple of questions from posters.
fwiw I agree with others who feel Supermarket Income REIT (LON:SUPR) is oversold and very cheap and that the disposal and lease news today supports that view. At 72p and on a 20% discount and 8.6% dividend it looks a snip. It recently bottomed at an all time 66p low. Note that recent updates from Commercial Property Trusts are at last reporting small increases in NAV again. So clear signs the sector is over the worst.
Bohenie pointed out that big investors have been selling. Yes. But they were buying when Supermarket Income REIT (LON:SUPR) was peaking as high as 130p and when it was overvalued on a big premium to NAV. At that time, when it was getting heavily promoted by commentators and on bulletin boards, I wasn’t remotely tempted when quality Trusts like Aew UK Reit (LON:AEWU) were on big discounts and paying much bigger dividends than SUPR. But now when it’s fallen out of favour I hold and added more on the news today. I’ve posted a link to their most recent Results below, for anyone who wants more info on Carrefour financials.
https://www.carrefour.com/site...
Also for photos of their supermarkets this link:-
https://www.gettyimages.co.uk/...
And (it’s in French) this link:-
https://www.carrefour.fr/
There has already been sector consolidation and there’s likely more to come with Supermarket Income REIT (LON:SUPR) a possible candidate.
Other Trusts on big discounts and like Supermarket Income REIT (LON:SUPR) paying big dividends while we wait for the sector to bounce again include Warehouse Reit (LON:WHR) 84p and on crazy 35% discount and 7.6% dividend.I bought (and it was covered on the Stockopedia Investment Trust thread) just above the recent 75p low. Schroder European Real Estate Investment Trust )LON:SERE) 66p in the Commercial Property. Europe sector and on 36% discount and 7.5% dividend might also, like fellow sector Trust, EBOX , tempt a bidder.
I hold all the REITS in this post and Alternative Income REIT (LON:AIRE) Schroder Real Estate Investment Trust (LON:SREI) Newriver Reit (LON:NRR) and Custodian Property Income Reit (LON:CREI)
Ken,
Thank you for your input.
Alternative Income REIT is an interesting one. A WAULT of about 17 years and 96% of rents index link (with a cap of about 4%)
It is on a discount of about 18%, with NAV starting to rise, and a yield to June 25 of 9.2% with the cover covered 1.1x in the last quarter.
They need to refinance some cheap debt by Sept 25.
I have twice been to the AGM to ask them to get coverage from a paid source e.g Edison or similar. No luck!
The yield numbers on Stockopedia are wrong, which i have endlessly pointed out to Stocko, to no avail.
This seem to me a wonderful individual investor stock for an ISA but with no method of easily being able to access information on it.
It may not surprise you it is my largest ISA holding.
Chris
We’re on the same wavelength with our Investment methods and holdings. I’ve held Alternative Income REIT (LON:AIRE) since 2020. It’s small and don’t know whether too small to tempt a bidder or an easy morsel. Either way it’s yet another cheap REIT.
Supermarket Income REIT (LON:SUPR) I think some of the analysis which claimed that the estate was over-rented (and which has no doubt contributed to the share price weakness) was very poor. The piece I looked at simplistically compared average supermarket yields at an index level with those of SUPR and concluded rents were too high and would need to come down - this completely ignores the fact that yields can vary tremendously depending on the quality, type and location of the store, the length of the lease and of course the supermarket itself (eg Asda or Morrisons will have much higher yields than Tesco or Sainsbury's). Today's announcement is yet more evidence that the market has this completely wrong. In fact, I'm surprised this hasn't been bid for yet - as we saw with Assura (LON:AGR) long-dated, secure cashflows are very attractive to institutional investors.
£SUPR. - 'The Mkt has this completely wrong' - Another intriguing aspect - look at the list of major shareholders - most of the institutions have been reducing their holding over the past year and not one increase !
Supermarket Income REIT (LON:SUPR) Yes, major shareholders have trimmed by 23 Million in past 14 months. Contrast this with Stocko data for director buys/sells, where not one share has been sold in the past 7 years. Anyone care to offer an explanation?? Too difficult for me...
The trimming by major shareholders is institutions i.e. hedge funds, the director buy/sells are directors which work for the business and have not sold.
Institutions maybe forced sellers as investors reduce money from their funds, they have to get the money from somewhere. There has been a drain on funds for 2 years now, in the UK.
Directors can buy when they have the money and think the price is right. They may know what is going on inside the business as well.
Looks like the institutions are mainly wealth managers and I suspect a lot will be forced selling as clients redeem. They're probably also looking to reduce exposure to alternative income trusts (REITs, infrastructure) given the huge falls over last couple of years, although susspect they're selling at the lows.
Gore Street Energy Storage Fund (LON:GSF) ( I hold) have put out an encouraging statement. A significant uplift in capacity. The shares have been rubbish due to fears they will lose the Investment Tax Credits.... they remain hopeful they will still receive this but this isn't confirmed yet. This would be a significant positive if they come through.
Zeus forecast 14.3p (adjusted, diluted) in January. Looks like their forecast was rounded to one decimal place so it could have been 14.25p-14.34p.
Having said that, Zeus isn't a broker to the company and I'm not sure what the individual brokers were forecasting,
In my experience EPS forecasts are usually adjusted for currency headwinds/tailwinds by analysts and so 14.27p would be more relevant than 14.41p.
On Friday Phoenix asked whether the US revaluing Gold would be positive for the gold price? I would say arguably not actually ...as an initial reaction. The detail of how this revalued asset will be monetised will be important. Rumours that it will support a sovereign wealth fund in the US could have positive or negative short term impacts on the price. I would however see this as a move that Gold is being used again as a reserve asset ... which China and Russia are already doing. This renewed demand isn't going away. So Gold is creeping back into the monetary system and I think this is driving current demand and the rise from $2000 to $3000. Silver has lagged this rise but not massively. There is scope for silver to do better although it's understandable it has lagged since it plays only a minor role as a reserve asset.
There is a but though.... because the Mar a Lago Accord idea being floated involves a grand agreement to swap Treasury debt for Zero coupon Century Bonds in exchange for defence services. This would likely involve a devalue of the Dollar .... and I assume if you devalue ... 10-20% seems reasonable. This would obviously be positive for all commodities ... including both Gold and Silver. Given Trump wants to reinvigorate US Industry and correct the trade imbalance it stands to reason he must want a weaker Dollar. This is worth thinking about should you hold US assets since it will be varying degrees of negative for their translation value in contrast to real assets.
Love your macro stuff RD could you explain a bit more around what zero coupon century bonds are and the defence services angle ? Ideally like you are talking to a four year old lol.
Im no expert so bear with me.
IMO a v important macro voices with Jim Bianco highlights this. What is the Mar a Lago accord? Well like Bretton Woods, or Plaza ... these grand reshapes of the monetary system tend to take the name of the location where everyone meets. The US needs a rethink on its debt levels. One idea that seems to be being floated is that the US has provided a defence service to the world for free. So a "clever" solution to the US debt problem "could" be .... to encourage member countries, say Nato, to hold 100 year Treasury bonds that carry a zero coupon instead of their current say, 10 Year Treasury Bonds. This would term out US debt and reduce the interest bill.... alleviating US budget pressure. On its own this sucks money out of the system which is unhelpful. So the solution is to devalue the Dollar ... which is sort of a default without missing a payment. Normally this would push yields up But if you have an agreement to swap 10 year out to zero coupon 100 year debt you have "hopefully" mitigated that issue. ( ie lower debt service cost not higher - and less supply of 10 year ). It raises various questions of course like would the Bonds trade ...or just be held at cost on central bank balance sheets ?
Im not pretending to know the answers....nor what a policy that doesn't exist will look like...but podcasters are all talking about this since with Trump II everything is on the table. DOGE for now is a serious attempt to get the US deficit under control and on a sustainable path. The argument follows that some fresh thinking is needed if we are to break the upwards path of US debt. It's in everyone's interests to achieve a new reset. Clearly if this is to happen it will be in the next 18 months so it will either fade quickly as an idea or gain more airspace. Gillian Tett in the FT is also on this and historically she has been incredibly well informed and prescient regards these types of move.
I agree with what you have said and I believe this may be something that the US is on track of, a slight digression, if I may...
There are ideas that I think could get the UK moving. By simply using money within cash ISA's and dormant bank accounts, requiring banks to act as intermediaries, directing ISA funds into government bonds or National Savings & Investments (NS&I) schemes, with a guaranteed return of, for example, 5%. This would provide a secure savings vehicle while allowing the government to invest in critical infrastructure projects without relying on taxation or additional borrowing. Regional or sector-specific ISAs could also be introduced, allowing savers to allocate funds to projects that benefit their local communities or causes they support. Also, defence spending which desperately needs to go up.
I know Rachel Reeves has been talking about lowering cash ISA's and messing around with the system to push more money into the economy, but my point is the money is already there to use and its simplicity is its key.
Agree and this is along the lines of Russel Napier National Capitalism argument.... which also involves bringing money home ...which a weak $ would encourage.
I'm not sure that cash ISA holders would appreciate the Chancellor using their money in this way, just my honest opinion and an inate distrust of government as we know it. Ooops.
Well, there will be 'patriots' that are anything but who would rather see the country go to the dogs (a la Brexit) than do something supportive, although I'll leave the political point there.
The money that is there could be automatically sent and used, unless you expressly wish to opt out. That's fair enough?
Dormant funds in banks could be nearing the best part of £100B which is more than enough to start with.
We had a defence bond in WW2 which was well subscribed to and we can actually create new ISA's which people can choose where to send their money to which stays in the UK.
It makes no sense that a large part of my portfolio is fuelling US companies which I'm paying no tax on.
A couple of points...
"Dormant funds in banks could be nearing the best part of £100B which is more than enough to start with."
Who decides if they are dormant or not? Just because money is in a perticular account which may not be attracting the the best rate of interest does not automatically mean that the money is "dormant". It can be there for a specific purpose that only the holder of the account knows.
The money that is there could be automatically sent and used, unless you expressly wish to opt out. That's fair enough?
I cant think of anything less fair to be honest.
Who decides if they are dormant or not? Just because money is in a perticular account which may not be attracting the the best rate of interest does not automatically mean that the money is "dormant". It can be there for a specific purpose that only the holder of the account knows.
Having worked in this specific sector - it's very easy. If an account hasn't been used for 10 years and attempts to contact the last known address doesn't bear fruit, then it is dormant. You still can have your money back if and when someone comes and claims it.
I cant think of anything less fair to be honest.
You have an opt out, at which point is that unfair?
You may not like the scheme, fair enough - here is a viable way that we can get the economy moving using UK money for UK purposes. You can always have you taxes raised together with services being reduced if you'd prefer - if that meets your definition of 'fair'.
The easiest way to settle the debate would be for the Government to issue a 6% NSI 2 year bond with no investment limit. Keep this open for a year and we will see how much of this "dormant" money moves. I think you might be surprised.
I am sorry - the idea that someone can take control of your assets and give you the opportunity to "opt out" is ridiculous.
"You may not like the scheme, fair enough - here is a viable way that we can get the economy moving using UK money for UK purposes. You can always have you taxes raised together with services being reduced if you'd prefer - if that meets your definition of 'fair'."
Or the Government could use existing funds more wisely. Or if you are a non dom or a High Net Worth you could simply leave the UK - which is what is happening.
So far the Government has not demonstrated any capability to grow the economy - quite the reverse in fact. Why would you want to trust them with more money?
Off the cuff weren't War Bonds something that one had to donate to if earning over a certain amount, taking the form of a special income tax. The Bonds being repaid decades later if I remember right.
'So bare with me, RDH!.' I'm afraid that in this weather, I'm not taking my clothes off for anyone! Sorry for frivolous comment.
ha ha quite ....corrected
Re: Mar-a-Lago Accord
Here is the document that folks are discussing: https://www.hudsonbaycapital.c...
Jim Bianchi is out on a limb here. If the Americans do swap treasury bonds held by central banks for zero coupon bonds with a 100 year redemption, they will be worthless, untradeable and America will be in default. Make no mistake, this will mark the end of the USD as a reserve currency and gold is likely to go ballistic.
Our own BoE holds over USD 600 billion of US TReasury Bonds, although we cannot be certain as the holding is not declared seperately. That is USD 600 billion that will be worth precisely nothing should this plan come to fruition.
It will mark the end of America's influence through their exhorbitant privilege accorded by virtue of issuing the World's reserve currency.
The reason gold is rising - and I hold 35% of my portfolio in Gold Bullion and Royalty Streaming Company, WPM, is a function of several factors:
First Basel accord places gold bullion as a first tier asset for central bankers;
Second rich Chinese have very little option as to where they place their liquid funds due to capital controls, negative returns in real estate markets and low returns in the bond market .... so they have been accumulating gold which is actually encouraged by the CCP;
Thirdly, the World's central banks have seen how the USD has been weaponised by the Biden administration and have been buying gold heavily. Incidentally, I suspect the Euro will follow the same path when the Germans, French and Brits decide to grab the USD300 billion of Russian central bank assets held in Europe, when Trump walks away from Ukraine and Europe.
Just a couple of points....firstly it need not be all holdings... just an agreed amount. Secondly, why would a zero coupon bond be worthless ? Normally such a bond prices in an implied yield....like say War Loan ? Clearly the price they are issued at should account for this....lots of unknown details here and all I am doing is highlighting what's being discussed. Jim may be out on a limb but Gillian Tett normally has her finger on the pulse.... so im not so sure nothing is on the table....watch this space, and good luck with your gold.
I take a simpler view.
The US trade deficit is caused by them consuming more of world output than they produce. It can only be closed by them consuming less or producing more. This is unlikely.
Tariffs close the gap by making imports more expensive, so that consumers consume fewer imports. But this tax on consumers will boost inflation and will be unpopular. The second downside is that other countries will levy reciprocal tariffs which means that people who work for US exporters will lose their jobs.
After about 6 months of losing a trade war i suspect Trump will get angry with foreign countries for protecting their own interests. The obvious step would be to cancel the US debt held by foreigners. This reduces US debt by a third overnight, reduces interest payments and solves their budget problems at a stroke. Trump having been bankrupt 3 times has done well out of this procedure before.
Only problem is that it crashes the world economy, but i doubt he will be too concerned.
This would make the GFC look like a garden party.... crashing everything... resolving nothing at all. I think it's most unlikely and anything but a simple view.
To be clear though, I wasn't really saying this is something I agree with or not....just that serious commentators are talking about it. So it would seem to carry weight.
It can only be closed by them consuming less or producing more. This is unlikely.
huh - if its now cheaper on lfl basis to produce locally than import is it not likely changes will result in more stuff being produced locally that would not have been. so why wouldnt tariffs work as one would expect they would do ?
The obvious step would be to cancel the US debt held by foreigners.
I suspect trump is playing a game to get deals done that may not be extreme as your proposed solution - ie is it not more likely he simply wants control of his borders or similar deals that will be good for the us and will relent when deals are done rather than destroying the world economy by defaulting on debt? anything is possible but defaulting to them defaulting on debt seems an extreme outcome to me.
I do wonder as a possible if some sort of global debt reset could be coming ie we owe the US say 500 billion they owe us 500 billion just net off against one another but presumably it would need the main developed countries to do it all against each other all at the same time ?
Depending who you listen to the US needs to roll over between 7-12 trillion of government debt this year, this could be a possible ongoing issue because there seems little appetite for longer dated bonds in the US so a lot of the current roll over has been issued at the short end of the curve.
The army for hire idea mentioned by RD is interesting but with Trump the issue will be even if you pay the money will they actually turn up if you need their help in a fight.
I think you've hit the nail on the head in your last sentence Phoenix. Essentially, cheap debt requires trust. The longer dated, the more trust required. If you want cheap, long-term debt you need to cultivate trust, not erode it. The current US administration appears intent on eroding it.
I would not trust Trump. He is a man totally without honour. I work as a case volunteer with a well-known military charity serving veterans. I know honour when i see it, and Trump, the draft dodger, has none.
ME International (LON:MEGP) EPS 14.27p or 14.41p at constant currency. The stock report shows consensus 14.33p. What is the right EPS that should be considered? It could be a light miss or a slight beat
The report reads positively and the new initiative Kee.me could build on the way they are setting up several services in one location that can be maintained easily. Although people don’t need keys cut as often as they wash clothes. Reassuring that the Photo Booth side of the business is stable.
looking forward to the analysis.
I should add that I am nervously awaiting the market reaction as anything other than strong beat seems to get sold off atm.
For as long as I've been holding ME Group, it falls every time it reports, so I'd be surprised if the SP goes up
We'll get a fall I'd suggest. Its a mad market so not easy to predict on these broadly inline results