Daily Stock Market Report (Thu 10th September 2026) - CURY, FEVR, ELCO, SPEC, INPP, SYS1, SDY

Good morning. Brent crude has topped $100 per barrel as Iran claims to be ready to escalate its war with the US, believing it’s an existential struggle.
Meanwhile, Donald Trump is predicting that the war will end after November’s mid-term elections, at which point petrol prices will “be tumbling down”. I would read this as a tacit admission he doesn’t expect to be able to end the conflict anytime soon.
With the cost of living an increasing issue for US voters, Trump is also attempting to bribe voters shore up support for the Republicans by offering a $5,000 payout to every US adult if the Republicans keep control of both houses of Congress in November. With around 270m adults in the US, this could cost well over $1trn.
Recent polling suggests the Democrats may gain control of the House of Representatives.
Also in US markets, the yield on 10-year US Treasury bonds rose to a three-year high of around 4.85% after a $6bn government buyback disappointed investors, who were expecting a larger repurchase.
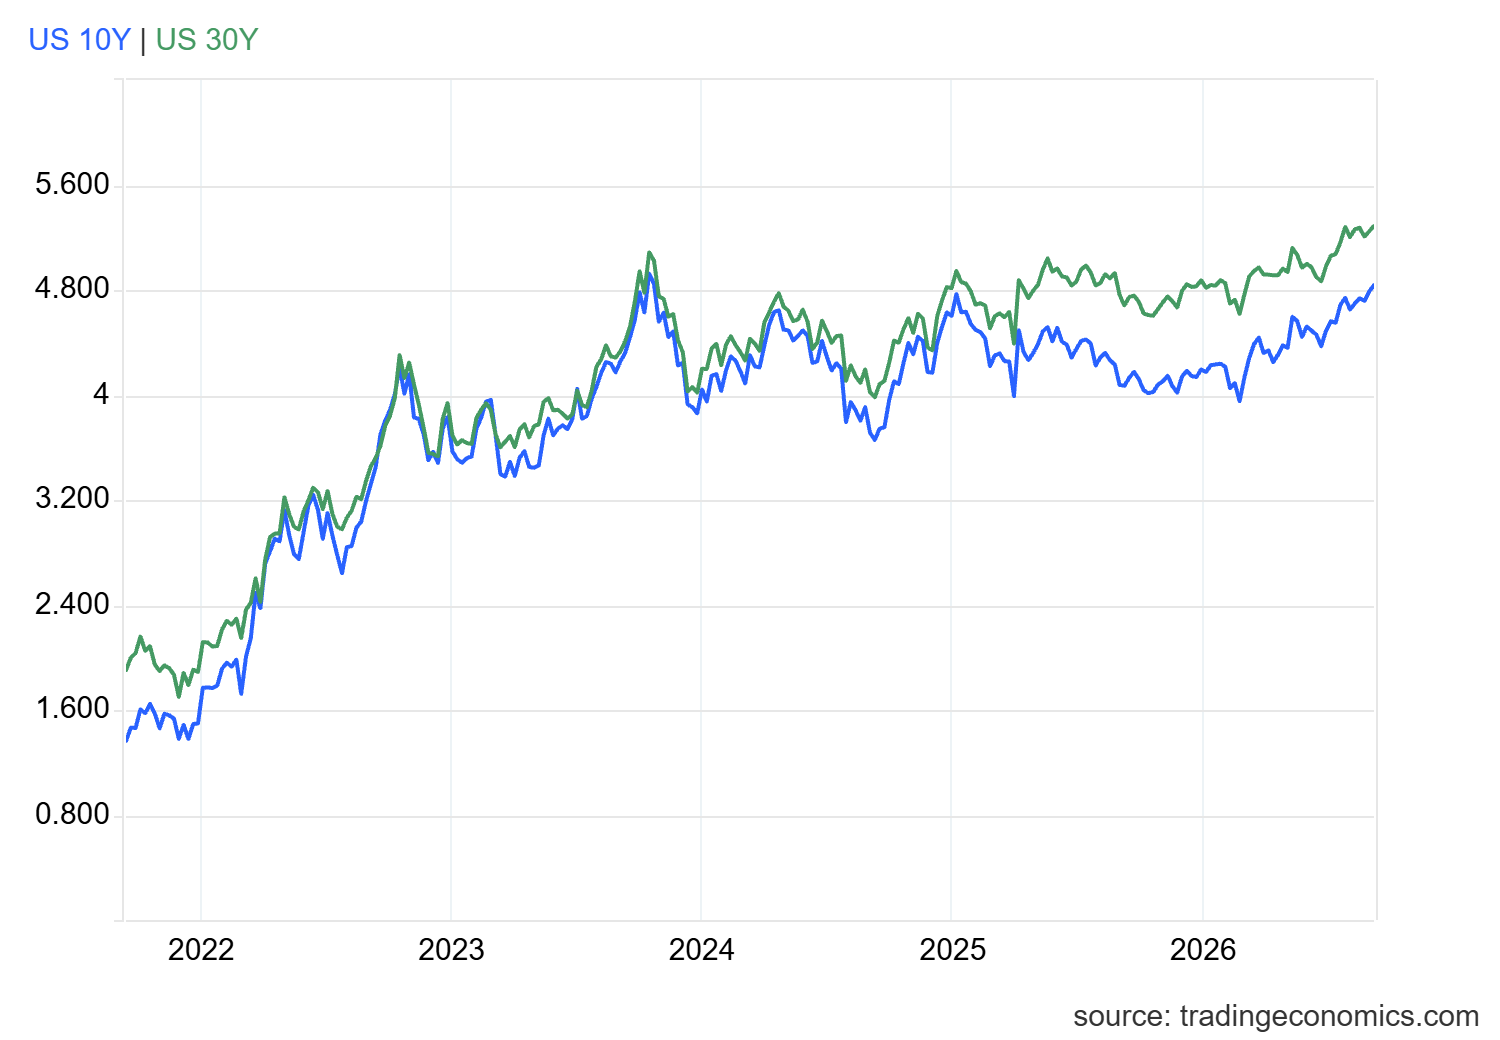
Here in the UK, gilt yields have also risen further this week. 10-year and 30-year yields currently stand at 5.25% and 5.9%, respectively.
Overnight market movements:
The FTSE is down 0.1% at 10,655
S&P 500 is up 0.3% at 7,656
Brent crude (November) is down 0.6% at $100.51/bbl
Gold is up 0.63% at $4,426/oz
Bitcoin is up 0.3% at $78,502
Mark Simpson joins me (Roland) today.
Today's report is now complete.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£73bn | SR81) | Over one million people develop shingles in Japan each year. New presentation offers a more convenient administration of the shingles vaccine, which previously came as two vials that needed to be mixed manually. | ||
Associated British Foods (LON:ABF) (£14.2bn | SR70) | Primark turnaround is underway and plans are in place to offer UK home delivery. Grocery and Ingredients delivered “good growth” in Q4. FY26 Outlook: adjusted operating profit is expected to be “broadly in line” with previous expectations. Adj EPS is expected to be ahead of expectations. | ||
Metlen Energy & Metals (LON:MTLN) (£5.83bn | SR63) | Agreed the sale of the Tamarico II hybrid project, which includes 165MW of solar power and 725MWh of battery storage. No financial details provided. | ||
International Public Partnerships (LON:INPP) (£2.48bn | SR89) | NAVps +1.3% to 153.4p vs Dec 25. Reconfirms dividend targets of 8.79p (2026) and 9.01p (2027) respectively. Dividend was 1.3x covered during H1. c.£480m invested or committed since mid-2023 at a weighted average return of >11%. £225m buyback extended to 2027. | AMBER ↓ (Roland) | |
Currys (LON:CURY) (£1.64bn | SR94) | LFL revenue +7%, with UK +6% LFL. Market share gains “in all major categories” in a flat market overall. Outlook: guidance is unchanged, “we are comfortable with market consensus” (group adj PBT of £199m). | AMBER/GREEN ↑ (Mark) | |
Genus (LON:GNS) (£1.49bn | SR44) | Revenue -2% to £658m with adj pre-tax profit +35% to £100.2m. Adj EPS +35% to 110.3p. FY27 outlook: in line with market expectations (FY27 adj PBT of £93m). | ||
Playtech (LON:PTEC) (£1.23bn | SR73) | H1 revenue +10% to €425.1m with net profit +472% to €95.0m. Adj EPS +513% to €0.331. Strong growth in Americas (+160% YoY). Outlook: in line with July 9 update, expect FY26 adj EBITDA of >€270m. | ||
M P Evans (LON:MPE) (£931m | SR96) | Acquired KWB in East Kalimantan for $2m. Includes 776 hectares planted to oil palm “which require some amount of rehabilitation or replanting” and up to 450 hectares of additional land suitable for planting. Also secured land rights over an adjacent parcel of land of 3,600 (Long Nah). Expect c.2,000 hectares can be developed to oil palm. | ||
Fevertree Drinks (LON:FEVR) (£910m | SR54) | H1 adjusted revenue +7% to £184.2m with adj EBITDA +9% to £20.1m and adj EPS +5% to 11.0p. “US momentum building under Molson Coors partnership”, with a return to growth in the UK. FY26 outlook: expectations unchanged, “well hedged” on glass and aluminium. | AMBER = (Roland) These H1 results look solid enough to me and show continued growth and market share gains in the UK and US. While key quality metrics are starting to recover from the lows seen in recent years, the profitability of the US business was held back by an increase in marketing spend in H1. I don’t have any issue with the company’s argument that this should deliver high profits over time, but given the valuation I’d like to see some evidence of this before taking a more positive view. | |
THG (LON:THG) (£538m | SR39) | H2 revenue +7.2% to £828.7m and adj EBITDA +109% LFL to £42.8m. Operating loss of £(10.5)m (H1 25: £(30)m). Growth driven by “stellar performance” for Myprotein brand. FY26 outlook: in line with expectations. | ||
Griffin Mining (LON:GFM) (£503m | SR66) | H1 revenue +21% to $77.3m with pre-tax profit +100% to $28.5m, despite Caijiaying Mine only running at 50% of full capacity. Improvement reflects higher gold price and lower costs per tonne of ore. Expect reduced throughput to be maintained into 2027 as the company awaits approval for the recommissioning of its Tailings Safety Facility 4. | ||
Guardian Metal Resources (LON:GMET) (£364m | SR10) | Agreement signed with Oritain, a global leader in forensic origin verification, to develop a unique origin fingerprint for Guardian Metal's tungsten projects. | ||
Boohoo (LON:DEBS) (£344m | SR35) | Sold the automation in its Sheffield distribution centre and reassigned the lease to Primark for £90m in cash. (£76.5m on completion and £13.5m on vacant possession early next year.) Entering into an agreement with a global 3PL provider that will enable it to continue to fulfil its stocked product. Now expect net debt to be negligible at our year-end. | ||
Distribution Finance Capital Holdings (LON:DFCH) (£129m | SR64) | H1 PBT +49% to £13.4m, materially ahead of expectations at the start of the year. TNAV +17% to 82.2p. RoTE 15.3% (25H1: 11.4%) Remain on track to deliver 2030 targets. | RH note: guidance was upgraded in June. These results appear to be in line with this previous upgrade. Broker forecasts are unchanged this morning. | |
| Eleco (LON:ELCO) (£114m | SR52) | Recommended Takeover | 235 pence in cash, 75% premium to last night’s close. 20x FY25 EBITDA. | TAKEOVER (Roland) Today’s offer is c.30% above last year’s all-time high, so all shareholders should receive a reasonable premium. Congratulations to shareholders who spotted this multibagger in the past and have held on – clearly our neutral view in January understated the opportunity. |
Inspecs (LON:SPEC) (£105m | SR77) | Revenue +1.6% to £99.1m, U/L EBITDA +13.1% to £10.2m, Statutory PBT -25% to £1.9m, U/L EPS +46% to 3.03p. Net Debt £18.7m (31 Dec: £32.3m), after £7.44m net equity raise. “... remain committed to delivering on our medium-term targets“ | AMBER (Mark) | |
Speedy Hire (LON:SDY) (£73.9m | SR47) | Revenue to the end of July +4.6% on the prior year. Adjusted EBITDA and operating profit margins are improving, reflecting high operational gearing, continued disciplined cost control and efficiency benefit. Expects FY26 revenue to be in line and EBITDA to be broadly in line with market expectations. FY27 Adj. PBT is expected to be towards the lower end of range of current market consensus. | PROFIT WARNING (AMBER/RED =) (Mark) | |
Ilika (LON:IKA) (£46.7m | SR9) | Successful outcome to its grant-supported PRIMED programme to optimise the performance of its Goliath 10Ah prototypes. | ||
System1 (LON:SYS1) (£43.1m | SR64) | 5 Month Revenue +11%, Cash £11.2m (31 Mar: £12.4m). | AMBER/GREEN/TAKEOVER = (Mark) | |
Ariana Resources (LON:AAU) (£41.2m | SR27) | All assay results from the 2026 metallurgical diamond drilling programme at the Dokwe Project have now been received; key intercepts from the programme included 24m @ 4.71g/t Au from 172m. | ||
Corcel (LON:CRCL) (£37.8m | SR3) | Received final Angolan Government approval for the acquisition of an additional 30% participating interest in KON-16 from Intank. Continues to advance the technical and operational work required to move KON-16 towards exploration drilling. | ||
Kendrick Resources (LON:KEN) (£29m | SR17) | Independent laboratory analysis confirms that Teufelskuppe REEs are hosted in fluorominerals commonly associated with major global rare earth deposits. Low thorium and uranium levels, averaging 144ppm and 3.6ppm respectively. | ||
Defence Holdings (LON:ALRT) (£27.3m | SR2) | Three priority MOD use cases identified and completion remaining on track for October 2026. 2nd MOD contract discussion progressing. Actively developing a broader pipeline of commercial opportunities across UK Defence and allied markets. | ||
Genedrive (LON:GDR) (£21.3m | SR20) | Betsi Cadwaladr University Health Board and Cardiff and Vale University Health Board, will extend routine clinical service of the Genedrive® MT-RNR1 ID kit for the prevention of Antibiotic Induced Hearing Loss in neonates admitted to Neonatal Intensive Care Units. | ||
Sunda Energy (LON:SNDA) (£12.6m | SR16) | H1 LBT £1.99m (25H1: £1.13m LBT), Net Debt £243k (31 Dec: £328k net cash). | ||
Mycelx Technologies (LON:MYX) (£12.3m | SR46) | H1 Revenue +24% to $2.1m, LBITDA $1.2m (25H1: $1.8m LBITDA), LBT $1.4m (25H1: $1.9m LBT. Cash $0.5m (25H1: $0.7m) with $1.1m received post period end. The Company expects to meet the market’s FY2026 revenue expectation of $11.0m. |
Roland's Section
Fevertree Drinks (LON:FEVR)
Down 6% at 767p (£858m) - Interim Results - Roland - AMBER =
Today’s half-year results from this premium soft drink and mixer brand appear to have disappointed the market slightly. However, my initial impression is that the business has made positive progress during the half year, especially in the US where its distribution agreement with Molson Coors Beverage Co (NYQ:TAP) is helping the group to expand its footprint.
Headline figures are all moving in the right direction, with a stronger H2 expected:
Revenue up 14% to £165.1m*
Adjusted revenue up 7% to £184.2m*
Adjusted EBITDA up 9% to £20.1m
Adj EBITDA margin: 10.9% (H1 25: 10.7%)
Pre-tax profit up 30% to £14.6m
Adj EPS up 5% to 11.0p
*Adjusted revenue includes US revenue as invoiced by Molson Coors to US customers. This is provided for comparability with past performance, where the company sold its products directly in the US. Fevertree’s reported revenue is different – what the company actually receives in the US is payment at cost for ingredients and finished goods supplied to Molson Coors, plus a royalty on sales.
Revenue growth was positive in all the group’s geographic markets (US revenue shown is adjusted):
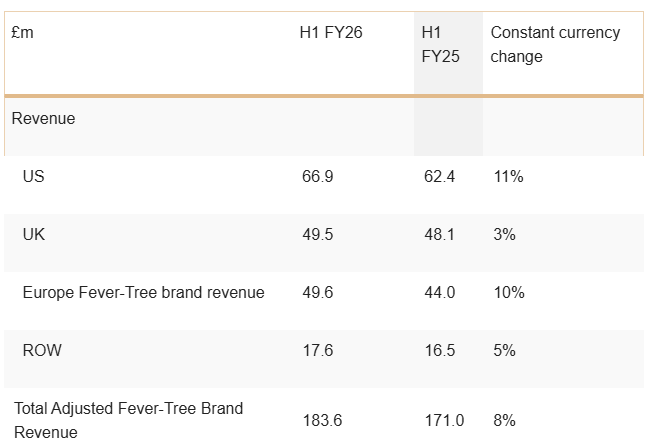
Source: Fevertree Drinks H1 2026 results
US growth is a core focus at the moment as the company attempts to use Molson Coors’s distribution network to target the high level of market penetration it enjoys in the UK:
US sales rose by 11%, with Fevertree achieving the “highest ever Ginger Beer and Tonic market share at retail”, extending its number one position.
First ever US national marketing campaign “Bartender’s Best Kept Secret”.
Improved US on-trade penetration, with additional marketing efforts.
CEO and co-founder Tim Warrillow notes that “these programmes are all on a much larger scale than we were able to achieve prior to the [Molson Coors] partnership”.
In the UK, performance was more measured:
Revenue up 3% year-on-year with strong off-trade performance and a 1.8% increase in market share by value.
A “Straight up or Mixed” marketing campaign continued to build Fevertree’s credibility as a premium soft drink as well as a mixer. Flavours such as Ginger Beer, Mexican Lime Soda and Mediterranean tonic are said to have performed well over the summer.
The on-trade channel “remains challenging” due to pressure on consumer spending. However, Fevertree remains the market leader in “every mixer sub-category”.
Non-tonic drinks now represent 32% of total UK sales, up from 24% three years ago, demonstrating the brand’s expanding market reach.
Profits: H2 weighting expected
Today’s results are said to be in line with expectations, but H1 earnings of 11p are less than half the 27.9p consensus estimate for the full year.
An H2 weighting is normal for this business due to the key festive period, but today’s results suggest H2 will need to deliver 61% of earnings this year (FY25: 57%).
Drilling down into the segmental profits helps explain what’s happening and provides some reassurance, in my view:
US H1 EBITDA down 18% to £4.1m
Rest of Group H1 EBITDA up 10% to £28.8m
The fall in US profits came despite an 11% increase in sales, dropping US EBITDA margins from 8.1% to just 6.2%. While this appears negative at first glance, I think it is adequately explained:
“Step change in marketing investment” during H1
Last year’s H1 results included one month of full US profitability under the previous subsidiary model, before the start of the Molson Coors partnership.
H1 US EBITDA of £4.1m is ahead of the £3.8m estimate published by broker Singer Capital at the start of September, so I’m inclined to accept the company’s explanation that stronger profits should flow through over time:
We continue to anticipate step changes in US profitability being delivered over the medium term as production is on-shored and the incremental marketing investment moderates to more typical levels, with our confidence in this trajectory supported by the commitments in place with Molson Coors.
Is FEVR still a quality business?
Fevertree is having to work hard to offset the declining G&T market and diversify its offering. From what I can see, the company is succeeding. In my view, the next test will be to see if the company’s quality metrics can recover from can return to the above-average levels seen in the past.
It’s too soon to be sure, but taking a longer view of performance suggests that profitability is now improving steadily:
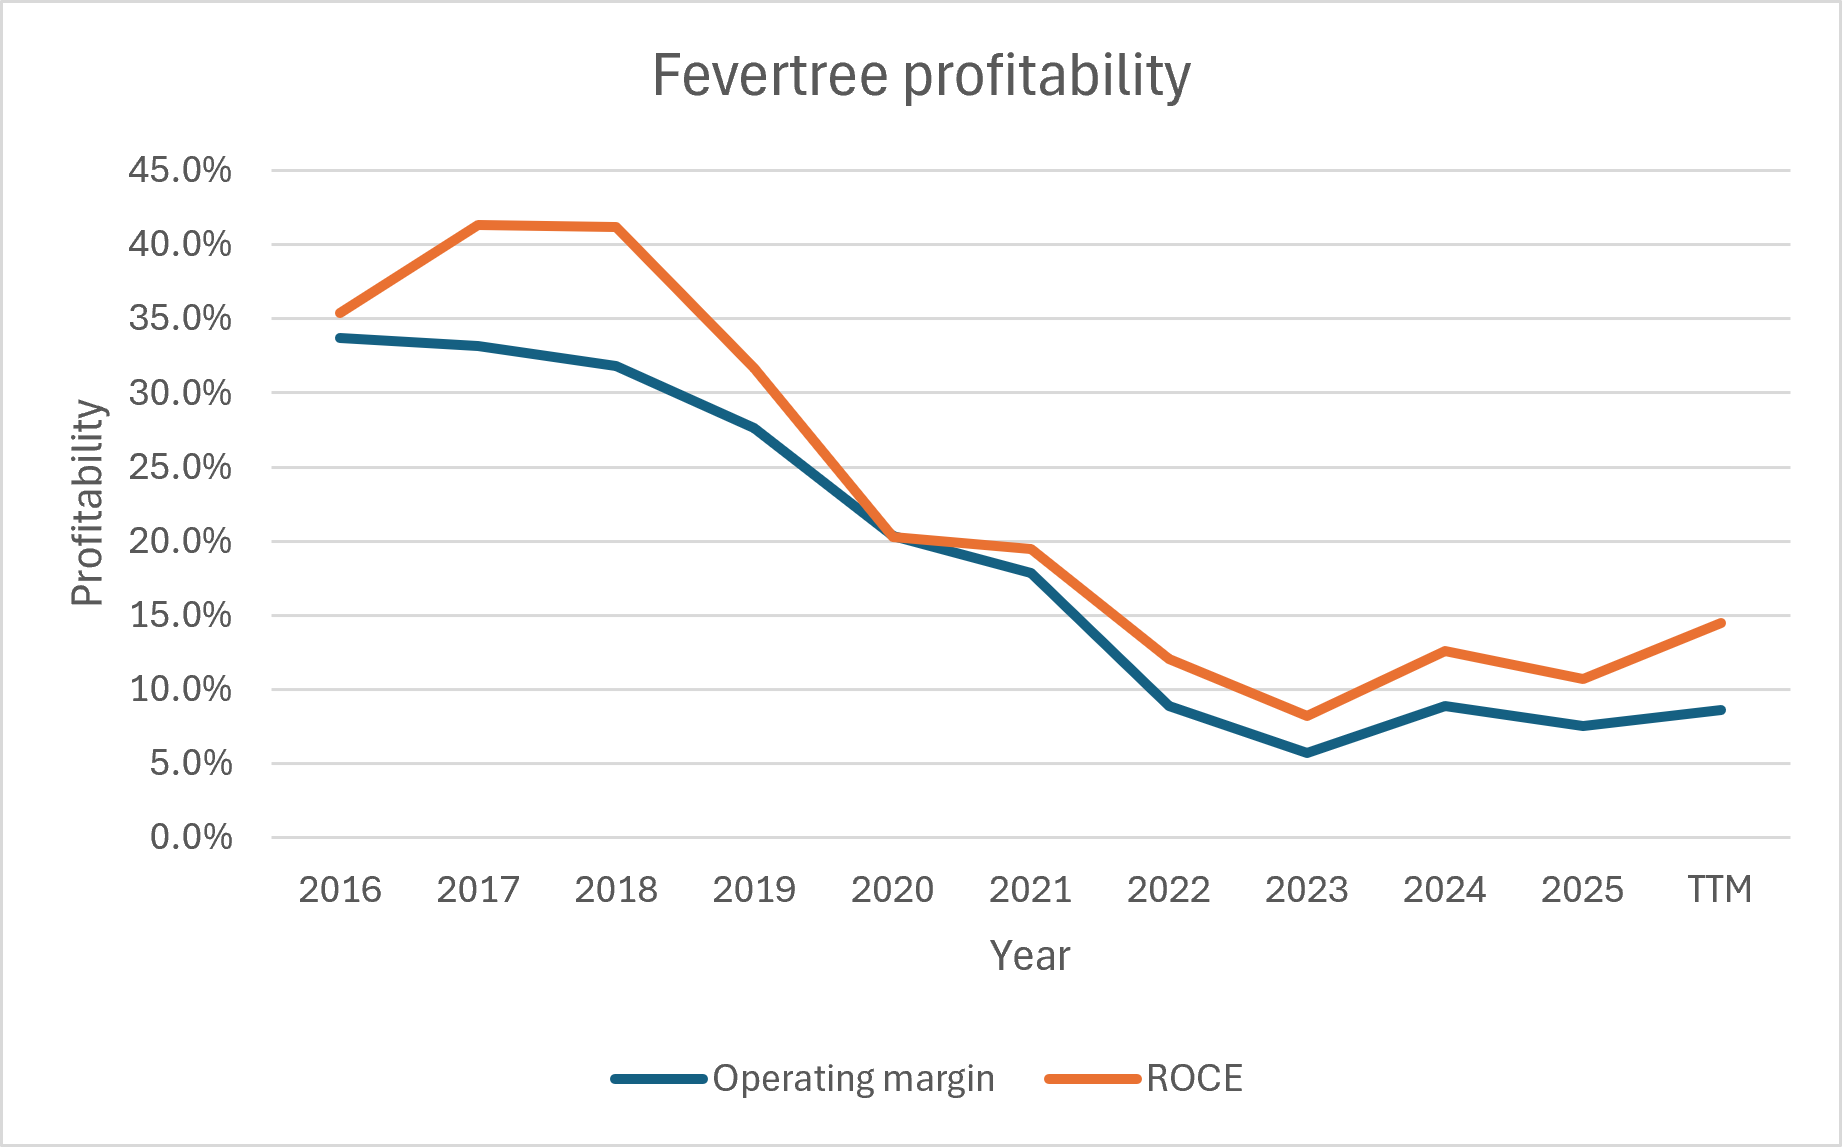
I would hope that there’s still some room for improvement, although I'd guess that returns will plateau somewhere below historical highs.
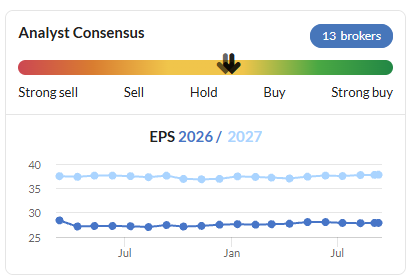
In my view, a key test will be whether the company can deliver on consensus expectations for 2027, which show a c.35% increase in earnings as greater US profits feed through:
Outlook: in line
There’s no change to guidance from the company today:
Our expectations for FY26 remain unchanged and in line with market expectations.
Management also notes that the business is “well hedged with regards to glass and aluminium costs”.
Consensus forecasts suggest earnings of 28p per share this year, putting Fevertree on a P/E of 28x.
This could fall to c.21x in 2027 if forecasts for next year remain unchanged.
Roland’s view
Fevertree has been through a difficult period, but I am increasingly of the view that the business has found a route back to sustainable growth:
Growing diversification into non-tonic mixers and soft drinks
Expanding reach in US market, aided by access to Molson Coors nationwide distribution reach
For me, the question that remains is over valuation, something that’s highlighted by the StockRank:
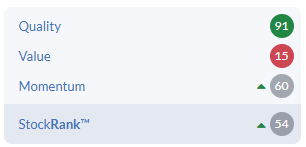
I was neutral on Fevertree in June. I think it’s probably fair to maintain that view today, given that the valuation remains fairly demanding for this sector and we still need to see the evidence of profit growth being delivered.
Eleco (LON:ELCO)
Up 70% at 228p (£193m) - Accel-KKR Recommended Cash Offer for Eleco plc - Roland - TAKEOVER
Today’s acquisition document provides a nice summary of this business from the buyers’ point of view:
… Eleco has transformed its business from its heritage in building and lighting equipment production to a technology business with a strong position in the building lifecycle technology market by providing a differentiated platform that serves stakeholders across the construction value chain.
Today’s offer from private equity group Accel-KKR (a tech focused JV between KKR and Accel) has certainly been made at a generous premium to the prevailing share price.
Here the key details:
Recommended cash offer of 235p per Eleco share valuing Eleco at c.£207.6m
A valuation multiple of 20.2 times Eleco’s 2025 EBITDA
A premium of 74.7% to the closing share price of 134.5p on 9 September 2026
45.2% of Eleco shareholders have already supported the offer
This looks to be a done deal, in my opinion, unless a competing bid emerges. With this offer pitched at 29x FY27E EPS, I’m not sure how likely that is.
Roland’s view
Eleco shares touched an all-time high of c.180p in July 2025, so this offer should mean that all shareholders are receiving a premium of at least 30% on their cost price. That’s a welcome change from some recent bids that have sought to capitalise on depressed share prices.
The last time we looked at Eleco was in January, when I took a neutral view. I noted “impressive long-term growth” and “high levels of recurring revenue” and commented that our sparse coverage of the stock had missed an impressive long-term multibagger:
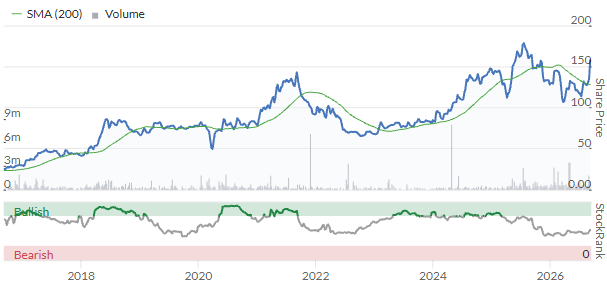
However, I had some concerns about recent cuts to EPS forecasts and noted the stock’s Falling Star styling. My conclusion was that the valuation might be up with events.
Clearly my brief review missed some key attractions – this appears to have been a case where more in-depth research could have paid off. Congratulations to shareholders who spotted the opportunity.
International Public Partnerships (LON:INPP)
Down 0.6% at 138p (£2.5bn) - Half-Year Results - Roland - AMBER ↓
International Public Partnerships, the FTSE 250-listed infrastructure investment company ('INPP' or the 'Company') today announces its half-year results for the six months to 30 June 2026.
This relatively low-profile business owns a portfolio of 130 infrastructure investments in the UK, Europe, North America, Australia and New Zealand.
Around half the group’s revenue comes from regulated investments, including (in the UK) the Cadent gas distribution business, Tideway (the new Thames super sewer), various offshore energy transmission assets and Sizewell C.
Other assets include railway rolling stock, schools and other public facilities.
INPP has an excellent record of maintaining covered dividend payments which now stretches back nearly 20 years:
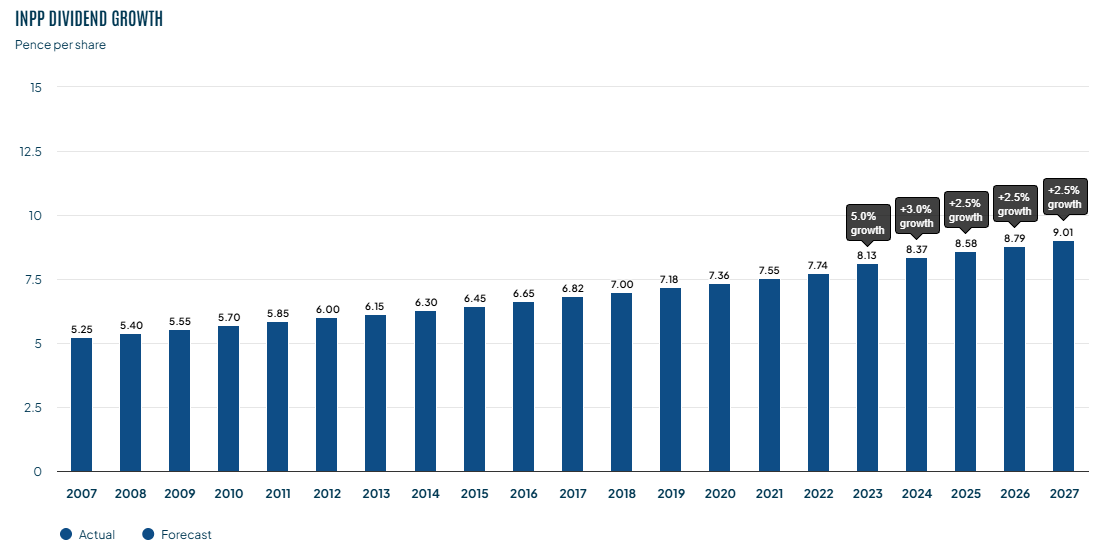
Source: INPP 2026 Half-Year Report
This long-term consistency is the main attraction for investors here and today’s half-year result reflect this, with reiterated dividend guidance for 2026 and 2027 featuring near the top of management commentary:
H1 dividend covered 1.3x;
2026 and 2027 dividend targets confirmed at 8.79p and 9.01p respectively, giving a forward yield of 6.4%.
The company also reiterates this eye-opening claim about ongoing support for the dividend (my emphasis):
On current forecasts, and even without any further investment, the Company expects to meet its existing progressive dividend policy for at least the next 25 years.
Many of the UK’s listed infrastructure trusts are facing problems renewing their portfolios at attractive rates of return or maintaining previously generous dividends.
INPP’s long-term focus appears to provide more certainty on future cash flows than some peers. These metrics are fairly eye-opening, in my view and differentiate INPP from the majority of listed rivals:
The recycling and new investments have enhanced the overall portfolio mix further: a sustained 1% increase in inflation is projected to increase portfolio returns by approximately 0.8% per year (31 December 2025: 0.7%), asset duration at c.41 years (c.37 years) and long-term secure revenues at 99% (98%).
Portfolio performance: it’s not realistically possible for outside investors to assess the performance of each of the company’s assets, so we’re reliant on management commentary for reassurance on the underlying performance of INPP’s portfolio.
Today’s commentary suggests performance was mostly as expected in H1:
NAV performance during the period was driven by strong operational results and resilient valuations despite renewed macroeconomic volatility. Aside from operational underperformance at toob (impacting <1% of NAV), the portfolio delivered a result broadly in line with expectations.
Use of the phrase “broadly in line” often means slightly below, of course.
One example of an investment that hasn’t worked out is toob, which is an altnet operator – a company building a fibre network to compete with BT Openreach. INPP says it’s not committing any further capital to toob and will transfer the majority of its equity interest to debt holders for a minimal amount, while retaining £2.6m of exposure to toob’s senior debt.
toob was previously held on the balance sheet at £24m, so this is a near-90% loss. Fortunately, it represents >1% of NAV and appears to be the exception to the rule for INPP.
Net Asset Value: INPP’s reported net asset value rose by 1.3% to 153.4p during the first half of the year (vs Dec 25), meaning that the stock trades at a 10% discount to NAV.
Management is also confident it can continue to refresh its portfolio while maintaining attractive rates of return:
£440m of disposals “at or above” published book value over the last three years;
c.£480m of new investments and commitments since mid-2023 at a weighted average return of more than 11%, including “a five-year cash yield exceeding 6%”.
A c.£1bn pipeline of new opportunities is expected to allow the group to maintain this record without any significant change to its risk profile.
Like most peers in this sector, the company has been buying back its own shares in order to manage the discount and generate NAV accretion. A £225m buyback is underway and has been extended to September 2027. To date, c.£150m shares have been bought back, generating 1.9p of NAV accretion.
Outlook
Looking ahead, the Board remains confident in INPP's strategy and in the continuity of delivery.
Consensus forecasts have been stable over the last year and suggest INPP will generate 11.3p of earnings, providing 1.3x cover for this year’s 8.8p dividend. That’s consistent with these H1 results and I see no reason to doubt these forecasts.
Roland’s view
INPP’s share price has recovered from the lows seen from 2023 to 2025, when valuations across the whole sector were still recalibrating following the return on interest rates to more normal levels:
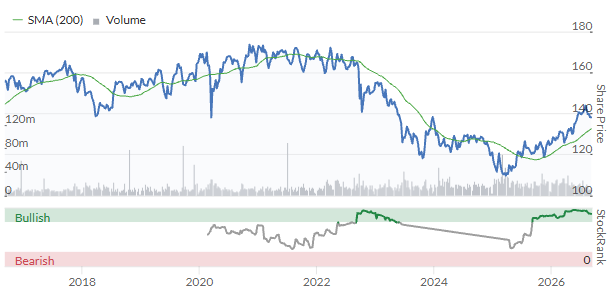
At current levels, I am inclined to think the valuation may be close to fair value:
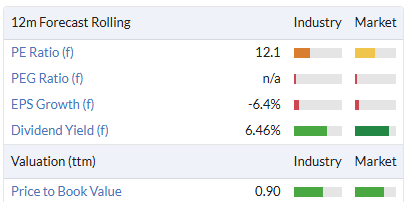
Adding the dividend yield of 6.4% to expected FY27 dividend growth of c.2.3% gives a theoretical expected return of 8.7%.
That’s close to the company’s projected net return of 9.2% from its portfolio and is roughly at the level I’d expect equity investors to seek from an investment of this kind.
I wouldn’t be against buying the stock at current levels for its income yield, but I’d be reluctant to pay much more.
Graham took an AMBER/GREEN view on INPP in March 2025, when the discount to NAV was 23%.
The discount is now just 10% and the dividend yield has also fallen. To reflect this situation I think it’s fair to take a neutral view on INPP today, despite my favourable overall view of this business. AMBER
Mark's Section
Currys (LON:CURY)
Flat at 151p (£1.64bn) - Trading update - Mark - AMBER/GREEN ↑
Curry’s starts off with one of my pet hates: titling their RNS with the promotional headline, “Strong start to the year in UK&I and Nordics”, instead of what this really is, “Trading update for 17 weeks ended 29 August 2026”.
That aside, this looks like a decent update, with UK LFL sales up 6% and Nordics an even more impressive 9%. This appears to have been achieved without giving away gross margin for volume.
When they say this represents market share gains in almost all their categories, I believe them. While the ONS "electrical household appliance stores" series has shown a steady improvement through the year, the July release showed sales volumes up 1.7% year-to-date in the seven months to July 2026 compared with the same period in 2025.
Perhaps most importantly they say:
Planning confidently for the remainder of the year. All guidance for the year remains unchanged and we are comfortable with market consensus.
Their website helpfully give a breakdown of the analysts forecasts:
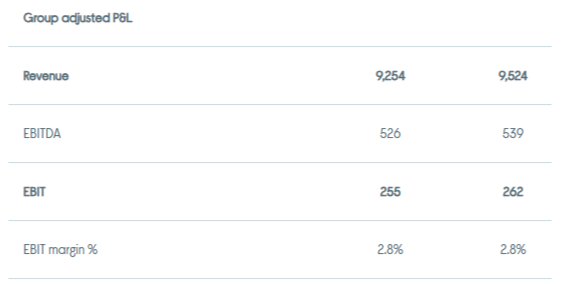
[First column is last year’s actuals. Second, this year’s forecast consensus.]
The key point for me is that these forecasts are for 2.9% revenue growth. 17 weeks in still leaves a lot of the year to go, including the key festive trading period. However, this looks like it could beat forecasts to me.
This also sounds ahead:
Expect year end net cash to finish well above our £100m target.
However, a quick check of their website shows analysts are forecasting £197m net cash (ex-leases). So this doesn’t mean much, apart from perhaps suggesting they see scope to extend their buyback beyond the current £50m (with £27m remaining).
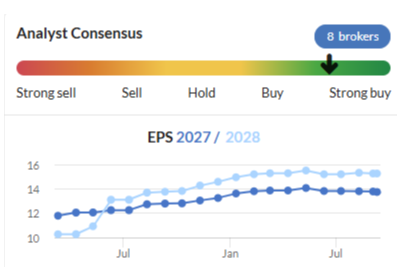
Having had a period where analysts' consensus had been rising, the recent trend has been largely flat:
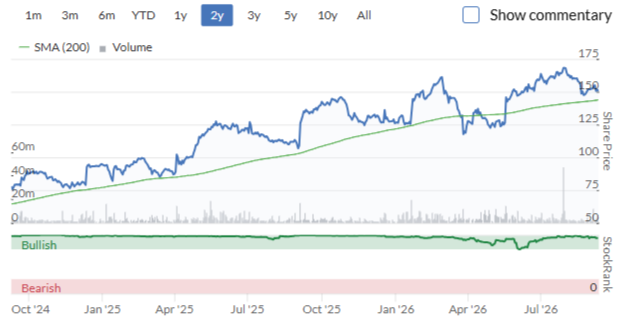
The share price has reflected this, almost doubling from September 2024 to November 2025, but then being largely flat since:
Valuation:
The Stock Report graph is a little confusing due to a strange approach to adjustments from Stockopedia’s data provider. So I’ve created my own graph from the company-provided data:
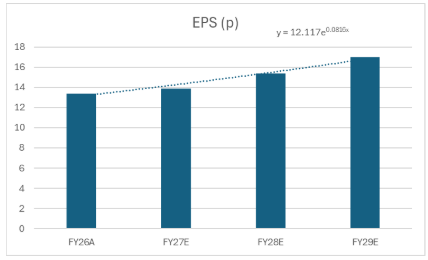
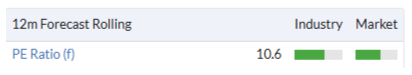
Importantly, this shows that EPS is expected to grow. However, at 8.2% CAGR, this isn’t earth-shattering compared to a forward P/E of 11, even if this compares well to other UK businesses:
Mark’s view
Although 17 weeks is only around a third of the year, the sales trends here look very good compared to the general market. James viewed this company as AMBER a few months ago, noting that the rating looked around average for the sector. I share some of those valuation concerns; 8% medium-term CAGR EPS growth versus a forward P/E of around 11 looks about right. However, these forecasts are based on 2.9% revenue growth, and if the company can deliver anywhere close to the sales growth rates for the first 17 weeks of the year in the rest, then these EPS numbers will almost certainly be beaten. I think we can afford to be a bit more optimistic today, even if the company line is that they are “comfortable with market consensus”. AMBER/GREEN
Background:
This eyewear/spectacle frames manufacturer recently attracted takeover interest from a consortium vehicle indirectly owned by entrepreneurs Luke Johnson and Ian Livingstone, working through Risk Capital Partners.
The offer was declared unconditional after acceptances plus the acquirer’s existing stake passed 50.1% of shares. However, the offer closed with Bidco ending up holding about 69.6 million shares, roughly 68.5% of Inspecs, a clear majority, but well short of the 90% needed to force a compulsory squeeze-out of remaining shareholders. Importantly, this was also below the level at which the acquirer could delist the business.
Today, we have a strange mix: a listed company controlled by a failed acquirer, and quite illiquid for its size given the majority holding. Most investors would demand a discount for investing in this type of set-up.
Results:
The headlines show that revenue is, at best, in line with inflation. However, gross margins have expanded, and a commitment to cost control has reduced operating expenses. The net result is some decent increases in profits:
· Underlying EBITDA2 increased by 13.1% to £10.2m from £9.0m in H1 2025, with the Underlying EBITDA margin increasing to 10.3% from 9.3%
· Diluted Underlying EPS3 increased 46% to 3.03p from 2.08p in H1 2025
· Operating profit before non-underlying items increased to £5.9m from £2.7m in H1 2025
Adjustments:
These are on an underlying basis, though. Here are the adjustments:
Non-underlying costs during the six months ended 30 June 2026 comprised £2,160,000 of professional fees and other transaction-related costs incurred in connection with the proposed acquisition and subsequent offer by Bidco 1125 Limited, which became unconditional on 12 March 2026. A further £310,000 was incurred in relation to restructuring completed across European-based subsidiaries.
I’m not sure independent shareholders should be pleased that they have had to bear significant fees related to an attempted takeover they appear to have not wanted, but at least these look to be a one-off.
Balance sheet:
Net debt has decreased significantly, and is now comfortably within their covenants:
· Net debt excluding leases decreased by £13.6m to £18.7m at 30 June 2026 from £32.3m at 31 December 2025, including £7.4m net proceeds from the issue of new shares
· The Group remained comfortably within its banking covenants at 30 June 2026, with leverage of 1.21x against a maximum covenant of 2.25x, debt service cover of 2.3x against a minimum of 1.1x and interest cover of 6.7x against a minimum of 3.0x.
However, this is aided by a fundraise, not just operating cash flow.
The current ratio looks OK at 1.4 and the business has £40.7m of net working capital. However, this is not a tangible asset play, so the investment case comes down to the future earnings potential of the business.
Outlook:
Strangely for a listed company, they don’t say if they are trading in line or not. Perhaps reflecting the now strange ownership structure. I can’t see the note on Research Tree, but the Stock Report has 6.8p for the FY. This looks probably achievable.
They do give explicit medium-term aims:
o CAGR organic revenue growth 40% above the market rate, which is currently forecast to grow at 3% CAGR
o Double-digit Underlying EBITDA margin - achieved in H1 2026
o Net debt to be 40% - 75% of Underlying EBITDA - on track to deliver in 2027
These don't seem that exciting to me. 4.2% CAGR organic revenue growth, with little to no margin expansion (as the target is already achieved), doesn’t suggest strong growth potential.
Valuation:
The Stock Report shows a forward P/E of 14, falling to 12 for the next year. This doesn’t seem like great value to me compared to the potential growth rates, especially given the remaining net debt.
The company has a fairly inauspicious history of continuous losses. To believe that everything is suddenly great and they will grow continuously from here takes a lot of faith:
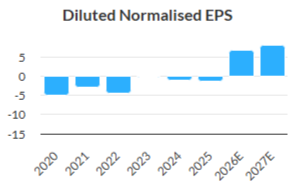
That said, there was clearly enough of an attraction for there to be an offer at 84p and for enough shareholders to reject it for it to remain listed. This perhaps puts a floor on the share price.
Mark’s view
Paying 14x forward earnings for a company with such a chequered past when it comes to profitability looks rich to me. Especially as the net debt and the ownership structure mean that I would demand a discount to the normal sort of multiples.
That said, the 84p bid and partial rejection of it, means that some smart investors saw value at this level. At the current 96p, the shares don’t trade that far in excess of this level. These results show that a turnaround is taking shape. However, the lack of explicit statements saying they are in line with forecasts and rather lacklustre medium-term targets don’t inspire confidence in future delivery. All in all, it probably makes sense to keep our previously neutral stance of AMBER.
System1 (LON:SYS1)
Flat at 340p (£43m) - 5M FY27 Trading Update - Mark - AMBER/GREEN =
Having recently abandoned quarterly updates, in favour of half-yearly ones, it now seems strange that System 1 wants to update us on their 5-month progress. Especially as they gave us two broad-brush trading statements in July and told us to expect another one in August, which then didn’t arrive.
In reality, my guess is that it is the offer from their 28% holder, Brave Bison, that is driving this behaviour. Indeed, the trading update is accompanied by a rejection of the offer.
The figures:
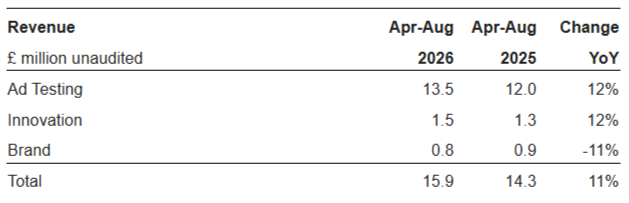
12% Platform revenue growth seems pretty good:
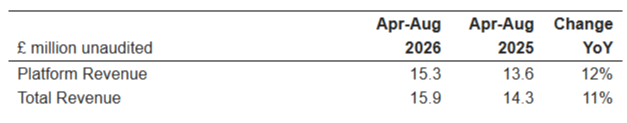
However, it comes against a weak H1 last year. If these trends continue for the final month of the period, then H1 will still be down on H2 last year:
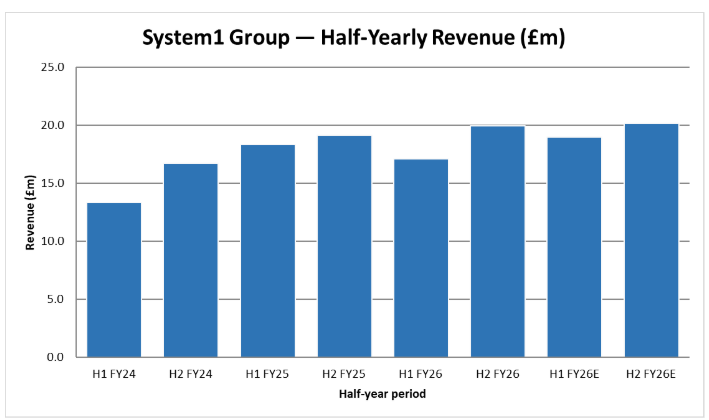
The good news is that it won’t take much of an H2 for the FY estimates to be met. Presumably this is why they say:
The Company remains comfortable with consensus Revenue and Adjusted Profit forecasts for FY27.
The company have strong operational gearing, so if that revenue figure can be beaten, the forward P/E of around 13 will also come down, making this look good value.
Their Innovation Testing also seems to be gaining traction, which looks like good news:
Cash remains at around a quarter of the market cap:
Cash at end of August £11.2m (March 2026: £12.4m); August 2025: £10.8m)
However, it would have been nice to get an explanation as to why this has declined on presumably profitable trading.
The bid rejection:
The main point of the company is that the bid based on the Brave Bison share price is now at a discount to the current share price. However, Brave Bison have argued that it was them acquiring the founder’s stake and their bid interest that has driven up the price.
The System 1 board have come back with:
The Board believes the trading update announcement on 16 March 2026 together with the publication of the Company’s 31 March 2026 year end results, announced on 8 July 2026, have had a sustained positive impact on the System1 share price and should be considered when evaluating any suggested premium by Brave Bison.
In my mind, this would have been a bit more convincing if these announcements had been accompanied by broker upgrades:
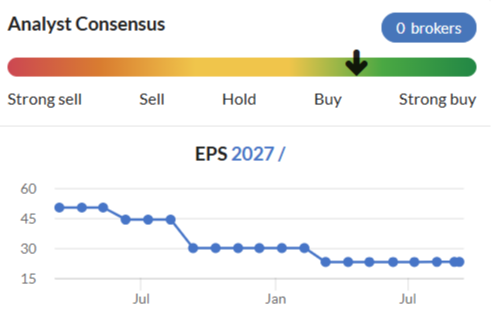
The rules are a little bit strange on this, and brokers often can’t issue new forecasts during an offer period. However, the results on 8 July were pre-offer and didn’t include any changes to forecasts.
What next?
It seems to me that this offer is probably dead in its current form. The Board have several commitments to oppose it. However, I think they need to be careful how they approach a 28% shareholder. This gives them several rights. They can probably appoint a board member. They can block all special resolutions. Even if they keep the offer open indefinitely with no acceptance, it looks like it would cause issues with brokers' ability to issue research. The big question for me is how much Brave Bison want the company, and how much chaos are they willing to cause to get it!?
Mark’s view
Despite weak comparators, current trading seems to be going well, and it won’t require a particularly strong H2 to meet forecasts (which look to have been frozen when the company entered an offer period). This means that the forward P/E of around 13, with a quarter of the market cap in cash, looks like reasonable value, as strong operational gearing will mean that if revenue growth continues, it will lead to rapid EPS growth.
The big uncertainty is around what happens with the proposed bid, and how hard-ball Brave Bison are willing to play to force the issue. Overall, I don’t think this uncertainty should change our mostly positive view of AMBER/GREEN.
Speedy Hire (LON:SDY)
Flat at 16p (£73.9m) - AGM Statement - Mark - AMBER/RED =
It doesn’t look like it was a pleasant AGM experience for all concerned. The company warns of some weakness in trading in the current year:
For the full year, the Board expects revenue to be in line and EBITDA to be broadly in line with market expectations.
Broadly in line is of course slightly below. The problem is that depreciation is a real cost for an equipment hire company, and they follow this up with:
Despite this, the Board is taking a more prudent view of the revenue mix of core hire and services and the level of operating profit margin improvement in FY2027 with increases expected in depreciation as we invest to support the major contract wins.
I’m not entirely clear why mix wouldn’t impact EBITDA, or why investment in not-yet-utilised equipment would cause a big jump in depreciation, but the net result is:
As a result, adjusted profit before tax for the full year is expected to be towards the lower end of range of current market consensus.
Normally, this sort of update is relatively benign. However, the footnote is highly revealing:
Market expectations for FY2027 refer to the analyst consensus compiled by the Company, which as at the date of this announcement stands at Revenue of £459.0m, adjusted EBITDA of £111.6m, adjusted Operating Profit of £33.2m and adjusted Profit before Tax of £14.3m, with a range of £4.6m to £20.0m.
The range of broker expectations is huge, and the implication is that the consensus has just gone from around £14m to around £5m. Let’s be clear. This is a huge profits warning.
Canaccord, who were previously the high-end of consensus, cut FY27 PBT from £20m to £5m. They also more than halve next year’s PBT forecast to £14m, but at this stage we should put little faith in that number.
What looked like a cheap stock on a forward P/E or around 5:
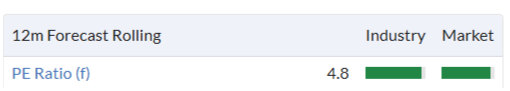
Is now an expensive one on a P/E of around 15.
And it gets worse. Part of the issue with earnings is higher debt and interest costs:
In addition, with leverage still running at the top end of the margin ratchet on the RCF and no expected reduction in UK base rates, the Board also expects interest costs to be higher than market expectations.
This isn’t just an issue with earnings, it also increases the risk of the company. Panmure Liberum put leverage above the target 1.0-2.0x range, which surely puts pressure on the company’s ability to keep paying dividends.
Strangely the market doesn’t appear to have re-priced what appears to be a material downgrade in prospects and increase in risk. One factor may be the possible tangible asset support of the current price:
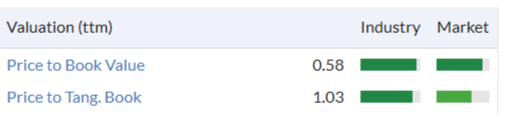
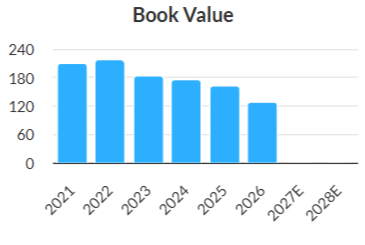
However, book value keeps declining, making reliance on this metric shaky, at best:
This absolutely screams “Value Trap”:
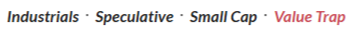
Mark’s view
I reduced our view to AMBER/RED on the last profits warning in April. Despite the share price having been weak since then, it doesn’t appear to have fallen enough to sufficiently reflect the collapse in profits or the increased risk. I remain negative.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Pan African Resources (LON:PAF) put out a trading statement but it is not the table.
Trump says he will issue a $5,000 "dividend" to every adult U.S. citizen if Republicans win both the House and Senate in the midterms. He says the only condition is that the money must be spent in the U.S.
Last thing I would get involved is politics.
But this nonsense, where numbers obviously make no sense is unbelievable.
Are there are people in the US that believe this stuff?
The figure is about $1.3T, when at the same time total revenues are only about $5.6T, interest payments on the debt just over $1.1T with the national debt rising to $48T in 2028.
All the best
"Are there are people in the US that believe this stuff?"
Sadly, yes! Even though he's made several nonsense promises in the past that haven't been kept to. Just look at the adoring MAGAites at his yesterday.
Will it help the Republicans at the mid terms, is unclear, at least to me, at the moment.
Remember the doge cheques that never got sent.
A big thank you to the Subscribers who responded to my post today on Boohoo (LON:DEBS) particularly rmillaree and The Boon Fund. Some very helpful comments and definitely food for thought.
I've just looked back on yesterday's report and answered a post from the evening which probably will go unread so I'm re-posting it here.
Corero Network Security (LON:CNS)
"There is no investment case here and massively overvalued."
In your opinion yiannos1, from a perspective which from your profile apparently involves zero knowledge of Internet security. I worked for the company which invented ethernet and whose hardware built 80% of what became the internet. This company in the mid 80's had a private network using leased telephone lines, of 50000 computers around the world before the US government freed up access to what was a private government network called Arpanet. Recent events have shown the foolishness of abandoning private networks on systems for such as air traffic control and we rely on technology to filter out bad actors but that horse has bolted and internet access covers every aspect of modern life, including our ability to share opinions. I have confidence in the fact that major computer, network and cloud companies are choosing CNS solutions to distributed denial of service attacks* and as a software solution then profits will drop to the bottom line as predicted.
All the best
*A distributed denial of service attack is a result of the public inadvertently installing malware from clickbait. A large volume of remote bots can be simultaneously activated to swamp a target website and legitimate traffic grinds to a halt. The company presentation is available on You-tube here
I have created my wealth over the years by analysing financial statements, especially looking at FCF generation to investigate whether a company can actually make money and return capital to its shareholders.
Narratives (your case!) capture the market's attention in the short term, long-term investment success is ultimately driven by hard financial realities like cash flow, revenue growth, and earnings.
Corero Network Security (LON:CNS) is not one that has proved or has shown any of the above. It is massively overpriced and has no place in my portfolio.
Corero Network Security (LON:CNS) is down 50% in the last 2 years. These last 2 years, I have personally experienced one of the most bullish stock markets in the last 4 decades.
Have you ever heard of CrowdStrike Holdings (NSQ:CRWD) Palo Alto Networks (NSQ:PANW) Fortinet (NSQ:FTNT) Netcall (LON:NET). Just asking as you are an expert in the industry?
You have tried to attack me on numerous occasions in the past. Why? Just because I provide my honest and professional opinion to the forum? Because I spent hours on research?
Serious and successful investors take notice of different views on their investments and not attack them.
GL with your investments. I hope Corero Network Security (LON:CNS) goes up and I am proven wrong.
All the best
I don't recall posting anything in reply to your posts let alone attacking you as you put it and I never professed to be an expert in the industry. I would never be so arrogant, however a lot of experience which I'm willing to share. I'm just sharing information for other members to do with what they will and I credit them with the intelligence and experience to do their own research. I feel your contribution to debate verging on hubris sometimes and I will not apologise for not matching up to your financial standards. Feel free to ignore me and I will you.
You see! You are using words like arrogant etc…personal attacks against the rules of this forum.
I have posted an honest reply as always, based on hours of research.
I hope Corero Network Security (LON:CNS) does well for you.
All the best
No comment!
Gentlemen, as ever, the market will decide.
Absolutely, and hopefully I am completely wrong. Last thing I want is for investors to be losing their hard earned money.
All the best
I found both views useful on this stock so thank you both. Debate informs opinion, if everyone just agrees all the time we’d exist in a world of group think failure.
Trump bribe, much like the $5000 DOGE checks which never happened
Morning Roland..Playtech (PTEC)growth figures especially in America look interesting..if you have time would appreciate your view,
I hope Roland might be able to comment on International Public Partnerships (LON:INPP) Results today?
Results today from International Public Partnerships (LON:INPP) look good, and for anyone keen on ever increasing dividend yield, this section from their statement today is reassuring.
“In INPP's twentieth year since listing, the Company continues to deliver against the same strategy it set out at IPO, underpinned by a stable and diversified portfolio of essential infrastructure assets.
With 99% of the portfolio's revenues derived from long-term public sector or regulated sources, the portfolio provides significant inflation protection: a sustained 1% increase in inflation is projected to increase portfolio returns by approximately 0.8%[iii] per year and to raise net asset value ('NAV') per share by approximately 12p. This protection of real returns supports the continued track record of fully covered dividends since IPO. On current forecasts, and even without any further investment, the Company expects to meet its existing progressive dividend policy for at least the next 25 years[iv].”
Noted Ken, that's on the list.
Roland
Thank you Ken, we should have bought when you first mentioned this but it's a good home in troubled times for some of our expected Ramsden cash.
Currys (LON:CURY)
Positive update this morning.
New CEO recently. I don’t hold but it looks attractive despite the challenging backdrop for retailers. I would welcome the views of Roland and colleagues.
Morning Jonno,
Currys (LON:CURY) is now done!
Roland
Thank you Roland.
I lost a large amount on Boo Hoo now (LON:DEBS) and I am tempted to buy given their deal to sell their Automated Warehouse to Primark for £90 million thus clearing all debt.Am I mad?
Yes! I got out of BooHoo many months ago and have never regretted it. Look at the metrics on here - 'Bankruptcy Risk' = DISTRESS. there are plenty more companies to invest in that are so much better regarding risk & returns than BooHoo...
But are you making investment decisions solely on past performance, and not what the future might hold?
For instance - you quote [Bankruptcy Risk = Distress] as one signal. But that's historic looking. Today's Boohoo (LON:DEBS) news is that they're selling an asset, getting cash, which they will use to pay down debt. Does that not reduce the bankruptcy risk?
Boohoo (LON:DEBS)
For instance - you quote [Bankruptcy Risk = Distress] as one signal. But that's historic looking. Today's Boohoo (LON:DEBS) news is that they're selling an asset, getting cash, which they will use to pay down debt. Does that not reduce the bankruptcy risk?
Obiously getting £90 mill cash now will most certainly reduce short term bankruptcy risk - being frank with company expecting to make £35 mill profit this year and next - most of the grunt work to remove then immediate is already done and dusted "if you accept they will hit forecasts" - obviously one can worry forecasts might be over rosy.
Note does selling ones "tools of the trade" always help long term - well i would generally prefer as shareholder if we are spending £10 mill per year on "necessary" "storage and fulfillment costs" - i would much rather be buying and paying down mortgage to get asset that might go up in value unless that is materially more expensive. Now the warehouse is gone they will have to pay others to host or pay rent costs.
Perhaps with move to marketplace sales the warehouse was more than they needed to run the business at full efficiency i suspect that started plannijng "back in teh day" before recent troubles fully manifested - so it could be a no brainer sale if they can match efficiency overall elsewhere or that facility was larger than tehy needed at basic level . It could be suboptimal long term solution if they are simply selling prime asset that would go up in value simply to keep creditors sweet - cant deny at present the people who give them credit kinda might have had the power here in that relationship.
not sure what their credit rating may be like - for fun i aksed copilot - info below may be nonsense (or not) - figures below wont factory in factory sale so might materiall imrove credit rating.
Based on the FY2026 figures, I'd classify Debenhams Group PLC (DEBS) as a sub-investment-grade/high-yield credit, probably somewhere around a single-B equivalent if it were formally rated, although that is only an analytical estimate, not an agency rating.
Key numbers
Revenue: £917m FY2026.
Adjusted EBITDA: £53.3m.
Net debt: £93.2m.
Leverage
Net debt / EBITDA:
Plain Text
1
£93.2m / £53.3m = 1.75x
Show more lines
On the face of it, 1.75x leverage is not excessive. Many B-rated retailers operate at 3x to 5x leverage. However, leverage is only part of the story.
If dog had fleas it will likely get them again. Boohoo (LON:DEBS)
What about the dog that is Pets at Home (LON:PETS) that had fleas in the past, but is able to prescribe itself flea medication? :)
Does such a dog still get fleas for life?
Don't always trust the metrics on here, make your decisions with the facts..
Boohoo (LON:DEBS)
Rebirth seems to be ignoring literally all of the positive progress the company has made over the last 18 months - its a bit of a shame they needed to do the dilution they did but perhaps that was necessary at the time - it certainly helped ref having a safety net (that creditors may have demanded)
when the facts change we shouldnt just stick our head in the sand and go well that was a craopla company 2 years ago - we should like at what has changed and have an "objective kook again"
Yes Rebirth is 10% correct to point out the Z score is crapola - no surprises there many retailers run with sketchy balance sheets - and its correct to say thnat boohoo was basket case a couple of years back (with potential).
lets look at the balance sheet then at 28/2/2026
inventories £105 mill
recevables £34 mill
cash £52 mill
assets held for sale £26 mill
total of above £217 mill - i have ignored property and plant £117 mill
owed out
trade and other payable £252 mill
interest bearings loans and borrowings £145 mill
total £397 mill - i have ignored lease liabilities
thats defecit if £180 mill - reduce that by warehouse proceeds of £90 mill - so £90 mill now.
and thats £90 mill of negative assets - note i have ignored some stuff on balance sheet that i think aint relevant.
if we accept current broker forecasts - bohoo is now in profut and shoudl be making what i would call "decent profits" next year .
Is the balance sheet sketchy - yes for sure with negative assets well that "can be an issue" - the good news is though the other payables line includes £94 mill accruals- so if we look at the liabilities on which they acvively "need credit" the picture isnt shockingly bad - trade payables are only £75 mill which is pretty modest for a retailer.
So with the £90 cash inflow mentioned above i see zero distress whilst they continue to make profits.
what boohoo have done is gone back to their roots cut out all the nonesense stuff and put themselves back in a position where there is hopes they will make decent profits. - balance sheet has been much simplified too.
Obviously they still have to deliver the bacon but the forecasts and the news has been pretty much 100% great for the past 18 months - so imho anyone calling someone else mad for investing here has most likely been super lazy and not really checked to see that the picture has been changing for the better . Yes its retail and they have debt and credit from suppliers - yes the balance sheet is flakey and tehn downside support is limited. does it look like the company has done then right things to turn it around - yes absolutely so much so that it is an investible business again if someone is happy with the risk. One good thing about retailers making profits is that pretty much always results in good cashflow if one isnt in "super cash invensive expanasion mode" - clearly bohoo is very much going back to basics and concentrating on simple stuff that should make money - similar to when they fisrt started - albeit slight different angle with the marketplace being front and central - the marketplace if it would should be ncely capital light.
Note on value grounds we have market cap of £344 mill - with next expected year profits of £22 mill - not cheap by any means - if they keep trending in right direct ref news it might fall into value territory.
Will be interesting to see if news changes profit expectations much - yes decent proceeds for warehouse sale - but without the warehouse they will have costs that would not have existed. in current enviornment being nimble and flexible perhaps aint the worst thing.
Ref stockranks - well as they have only just started delivering profits i would still have expected ranks to be woeful - rank has been trending in right direction - albeit from super low base. with companies in negative assets delivering profits perhaps cant but help improvingt the ranks all else being equal.
Brilliant summary from someone looking forward, and not sore about their losses...
Maybe the stocko experts will add their view??
One other point worth mentioning is the turnaround is being led by CEO, Dan Finley. You only have to do a cursory search on the internet to see how highly rated he is in the industry.
Good morning Roland and Mark. Yesterday Steppe Cement posted their HY quite late and missed being listed in your early readout. We are long term holders and I'd appreciate any observation if you find time to look at that today. James gave it a cautious Amber on July 7th and said it doesn't pay a dividend which a few subscribers contradicted. It's paying a 2p dividend on better results mainly down to a stronger Tenge against the USD. Their market share is up 2% but FY sales are forecast to be below 2025. Stocks Ranks are showing it's close to be being a possible Ed Croft stock rank winner but as James noted, it's a single product single country company so I doubt if it qualifies.
Morning Roland, would really appreciate your view on the Inspecs (LON:SPEC) results this morning if you get time please. I have a small holding. Thanks.
Eleco (LON:ELCO) takeover at 235p. Decent premium on the current price of 134p.
Thanks for flagging this, Eleco (LON:ELCO) has been added to the table.
Roland
More than decent, I would say!