Daily Stock Market Report (Thu 24th Sep 2026) - AT., RPI, VTY

Good morning. China and the US have agreed to extend their current trade war truce by two months until January following meetings between Donald Trump and China’s President Xi Jinping. The truce had previously been set to expire on November 10.
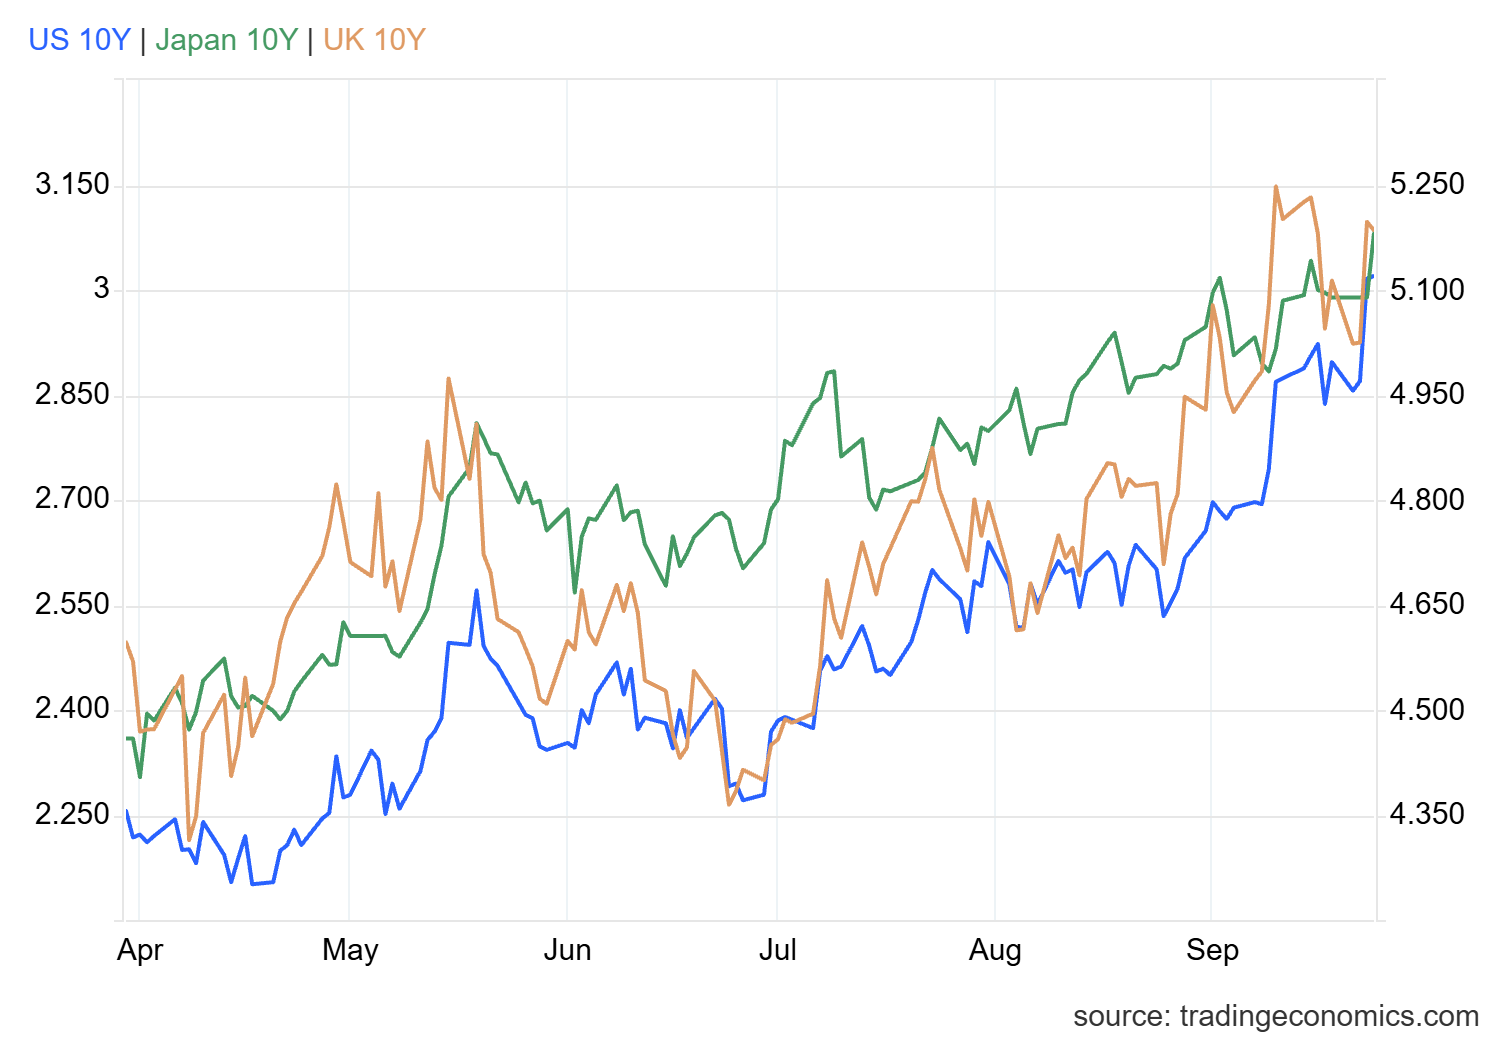
More broadly, oil remains over $100 and government bond yields have continued to rise, with with the yield on 10-year US Treasuries topping 5%. Here in the UK, it’s closer to 5.3%:
Finally, the FT reports that Chancellor John Healey may be willing to consider cutting the size of the UK’s fiscal buffer in order to minimise tax rises without making unnecessary cuts to spending. This is a reference to the headroom the government expects to have for meeting its target of balancing the budget by 2029-30.
Apparently, the Treasury believes bond market investors would accept a reduction in headroom without pushing bond yields up unduly.
Overnight market movements:
The FTSE is down 0.3% at 10,682
S&P 500 is down 0.3% at 7,682
Brent crude (November) is up 0.1% at $103.14/bbl
Gold is down 0.1% at $4,280/oz
Bitcoin is down 0.3% at $84,158
Spreadsheet accompanying this report: link.
Today's report is now complete. Sorry I wasn't able to cover all the stories of interest today.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Halma (LON:HLMA) (£13.6bn | SR64) | Strong progress in the first half; full year Adjusted EBIT margin guidance increased to 23.5% to 24% (previously 22.7%). Revenue growth expectations unchanged. | ||
Zegona Communications (LON:ZEG) (£4.0bn | SR76) | Planning €400m shareholder return, consisting of a €200m buyback and a €200m dividend. Together, these will represent c.10% of Zegona’s market cap. | ||
Hikma Pharmaceuticals (LON:HIK) (£3.3bn | SR94) | Rebecca Hall appointed as CFO from Q1 2027. She joins from ViiV Healthcare (majority owned by GSK), where she is CFO. | ||
Mitchells & Butlers (LON:MAB) (£1.63bn | SR86) | LFL sales +2.1% for the 51 weeks to 19 Sept 26. Q4 LFL +1.4%. Outlook: confident of delivering FY results in line with consensus. | ||
Raspberry PI Holdings (LON:RPI) (£1.22bn | SR42) | H1 revenue +90% to $256.9m with pre-tax profit +216% to $19.6m. Unit volumes +17% to 4.2m during the period. Outlook: expect higher volumes in H2. The “exceptional unit economics” achieved in H1 have moderated, but FY26 adj EBITDA is expected to be ahead of expectations. | AMBER = (Roland) These are super results which show the benefit of rising volumes and Raspberry Pi’s ability to secure much-needed inventories of memory. However, profitability is expected to ease in H2 even as volumes rise and the quality metrics of this business remain somewhat average. I still see this as a differentiated and potentially exceptional long-term story, but with the stock trading on a P/E of 50, I think there’s already plenty of good news priced in. To reflect these conflicting views I’m staying neutral today. | |
CVS (LON:CVSG) (£880m | SR50) | FY26 revenue +5.9% to £713m with LFL sales +2.1%. Adj pre-tax profit +7.6% to £84.9m with adj EPS +6.9% to 85.6p. FY27 outlook: performing in line with market expectations for FY27. | ||
Vistry (LON:VTY) (£852m | SR80) | H1 completions -8% with revenue -9% to £1,730m and an adjusted pre-tax loss of £83.3m. Net debt £468.8m. Has secured covenant waivers for FY26 and H1 FY27. Outlook: do not expect to need to raise equity. Now expect adjusted pre-tax profit to be c.£165m (previous forecast range: £168-283m). | PROFIT WARNING (AMBER/RED =) (Roland) Even with some heavy adjustments, Vistry has still needed to trim profit guidance for the year and will rely on a much stronger H2 performance to meet these forecasts. The 68% discount to tangible net asset value is an obvious attraction here, but I think investors need to recognise the risks entailed in high leverage. Meaningful debt reduction relies on land sales and is expected to take several years. While this could be of interest from a value perspective, I’m maintaining a cautious view today to reflect the risks that come with excess debt. | |
Cohort (LON:CHRT) (£557m | SR47) | Trading performance in the year to date has been consistent with the Board’s expectations. The outlook for growth in FY2027 remains unchanged, with a weighting to the second half as in previous years. As at mid-September, the order book was c.£700m, underpinning nearly 90% of FY27 consensus revenue. | ||
AO World (LON:AO.). (£526m | SR85) | H1 revenue expected to be +5.5%, with pre-tax profit to be +20% to c.£21.5m. Outlook: FY expectations remain unchanged. | ||
Asos (LON:ASC) (£515m | SR75) | FY26 gross merchandise value (GMV) -5%, but GMV returned to growth in Q4. Now expects gross margin to be above 48-50% guided range, with adj EBITDA above the mid-points of the £150-180m guided range. | ||
| Ashtead Technology Holdings (LON:AT.). (£441m | SR42) | Statement re Possible Offer (Wed 23rd 4pm) | Ashtead has received a non-binding proposal from Ember Infrastructure Mgt for a cash offer of 615p per share. The Ashtead board is considering the proposal and providing due diligence information to Ember. | TAKEOVER I flagged up possible value in Ashtead shares at the start of September, while remaining neutral due to macro uncertainty and the recent profit warning. The valuation implied by this offer doesn’t look overly generous to me, but it’s possible that Ember (and Ashtead’s management) are expecting a prolonged period of disruption in the Middle East and perhaps cyclically weaker trading elsewhere. The Board’s decision to allow some due diligence makes me think they might accept a firm offer at this level, potentially leaving some shareholders underwater. |
Living Reit (LON:LIVE) (£346m | SR71) | Net rental income +2.3% to £20.2m with adj EPS +2.2% to 3.42p. EPRA NTA per share “broadly stable” at 95.36p (FY25: 94.23p). | ||
DFS Furniture (LON:DFS) (£342m | SR72) | Revenue +2.6% with pre-tax profit +33% to £43.7m and adj EPS +50% to 13.8p. Leverage 0.9x. Outlook: FY27 YTD order intake is -2.5%, in line with expectations. Expect to deliver “moderate profit growth in FY27 in line with analyst consensus”. | ||
Frp Advisory (LON:FRP) (£301m | SR67) | Outlook: FY27 trading continues to be in line with the Board’s expectations. | ||
Capricorn Energy (LON:CNE) (£277m | SR93) | H1 production of 19,337 boepd with revenue of $100m from production. Net profit for the period of $24m. FY26 outlook: expect production above the mid-points of the 18-22,000 boepd guidance range. | TAKEOVER | |
Empire Metals (LON:EEE) (£277m | SR17) | Rutile pigment successfully produced from Pitfield’s anatase-rich in-situ weathered ores, indicating that the crystal form of the final pigment product is determined by processing conditions rather than by the titanium minerals present in the ore. | ||
On Beach group (LON:OTB) (£231m | SR52) | H1 booking growth of +9%, with total transaction value +6% at c.£1.3bn. Outlook: now expect FY26 adj pre-tax profit of £22-23m, in the top half of guidance (£18-25m). | ||
Rainbow Rare Earths (LON:RBW) (£171m | SR23) | In return for the use of Neo’s SX technology, Rainbow will provide offtake rights to Neo Performance Materials (TSE:NEO) on commercial terms covering 40% of NdPr and 65% of SEG+ production from Phalaborwa. | ||
Mercia Asset Management (LON:MERC) (£116m | SR34) | Mercia has made a positive start to the current financial year. The company has just been appointed to manage a new equity mandate for the British Business Bank, with an initial £63m of new funds under management. Outlook: “optimistic” about continuing profitable growth in H2. | ||
InvestAcc (LON:INAC) (£92m | SR17) | H1 revenue +130% to £13.8m reflecting the acquisition of AJ Bell Platinum and treasury income. H1 adj EBITDA +274% to £4.9m with pre-tax profit of £1.5m. Outlook: confident in the outlook for H2. | ||
NWF (LON:NWF) (£77m | SR96) | Trends reported with the FY26 results resulted in mixed performance across the group. With the seasonally busier winter months still to come, the full-year outlook is unchanged. | ||
Colefax (LON:CFX) (£69m | SR98) | Sales in the core Fabric Division rose by 8.9% during the 20 weeks to 18 Sept 26 (US +14%, Europe +2.5%, UK -4.5%). Current trading “remains challenging in the UK and Europe” and the company expects tougher US comparatives in H2. | ||
Poolbeg Pharma (LON:POLB) (£69m | SR29) | The ongoing TOPICAL clinical trial will proceed as planned following a positive review of data from the interim safety cohort. The completion of this review represents an important milestone for the TOPICAL trial. | ||
80 Mile (LON:80M) (£61m | SR10) | An extension letter has been executed with JV partner March GL Company in relation to the JV agreement concerning the Jameson liquid hydrocarbon project in Greenland. Various details are provided. | TAKEOVER | |
tinyBuild (LON:TBLD) (£60m | SR60) | Revenue +18% to $20m with adj EBITDA -24% to $3.2m reflecting higher marketing and royalty costs. Outlook: H2 remains uncertain but company now expects full-year results to be ahead of expectations. | ||
MTI Wireless Edge (LON:MWE) (£56m | SR90) | Buybacks have been suspended because the total holdings controlled by the Borovitz and Beer families have now reached 44.9%. 45% is a key threshold in Israeli company law after which voting rights are affected. | ||
Cobra Resources (LON:COBR) (£44m | SR8) | Porphyry Indicators Confirmed at Blue Rose: 23m at 0.63% Cu incl. 12.4m at 1.01% Cu. Mineralisation has now been defined to depths beyond 300m and the style of mineralisation and associated geological features support a greater porphyry system. | ||
System1 (LON:SYS1) (£43m | SR74) | Adjusted pre-tax profit of £2.1m for the five months to 31 August 2026. Outlook: increasing full-year adj pre-tax profit guidance to £5.0m (prev. £4.2m). | TAKEOVER | |
European Green Transition (LON:EGT) (£34m | SR21) | Has renewed a five-year operations and maintenance contract renewal across a portfolio of 94 wind turbines in Great Britain and Northern Ireland with Drax. This is a renewal of a 2021 contract and 2026 revenue guidance is unchanged. | ||
iFOREX Financial Trading Holdings (LON:IFRX) (£32m | SR28) | H1 revenue -2.2% to $26.9m with adj EBITDA -74% to $1.4m and an adj pre-tax loss of $(1.9)m. Net cash up 45.7% to $11.8m. FY26 outlook unchanged from guidance on 17 Sept 26. | ||
First Property (LON:FPO) (£22m | SR72) | “The Group's performance continued to recover in the year to 31 March 2026 with profits increasing and our balance sheet strengthening. As a result, the directors are proposing, subject to shareholder approval at today’s AGM, a resumption of dividend payments with a payment of a final dividend of 0.25 pence per share, or some £370,000 in total.” | ||
FIH (LON:FIH) (£19m | SR42) | Disposal for Momart was agreed recently for £7.6m. Following this the company will focus solely on supporting the Falkland Islands Company, where trading is currently challenging, especially in construction. | ||
EMV Capital (LON:EMVC) (£13m | SR30) | AUM +4.4% to £117.5m in H1, driven by fundraising and new investment. Net portfolio fair value movements broadly neutral during the period. NAV per share +145% to 120p in H1, mainly reflecting the deconsolidation of Glycotest and ProAxsis. Adjusted NAV +16% to 123p. |
Roland's Section
Ashtead Technology Holdings (LON:AT.)
Up 59% at 543p (£504m) (yesterday) - Statement re Possible Offer - Roland - TAKEOVER
US private equity firm Ember Infrastructure Management has made a possible offer for subsea equipment hire company Ashtead Technology:
615p per Ashtead Technology share
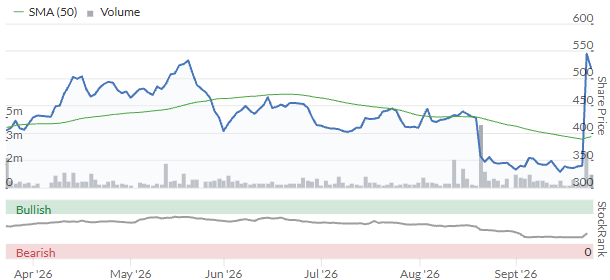
Details of the offer were made public at 4.07pm on Wednesday (yesterday), so this morning’s share price drop actually follows a c.60% rise yesterday:
Multiple proposals
This proposal follows three previous unsolicited offers from Ember, the first two of which were unequivocally rejected by Ashtead’s Board. It looks like there has been a bidding situation ongoing for a while, with Ember’s offers now having reached a level where Ashtead is prepared to consider them.
The company says it is considering the current proposal while also providing Ember with “preliminary due diligence information”.
At this stage, there is no certainty that Ember will make a firm offer, so this could still come to nothing.
Roland’s view
When I reviewed Ashtead’s half-year results at the start of September, I took a neutral view to reflect August’s profit warning and the continuing impact of the conflict in the Middle East.
However, I noted the continuing attractive profitability of the business and suggested that “Ashtead could offer value based on historic profits”.
Perhaps I should have been bolder! Congratulations to shareholders who chose to look through the short-term headwinds and saw an opportunity here.
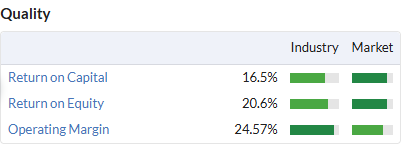
In terms of valuation, 615p is equivalent to 15.6x FY26 EPS forecasts and only 13.2x FY27 estimates, so it doesn’t seem overly ambitious for a company with decent quality metrics:
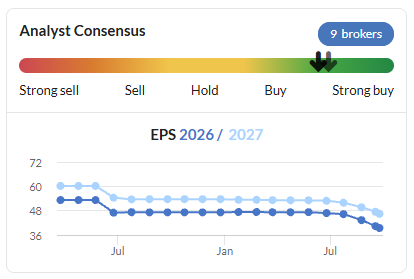
Of course, there is some uncertainty to the outlook and it’s possible this will continue:
It’s worth noting that unlike the recent offer for Eleco, Ember’s proposal to Ashtead is well below the stock’s historic highs. If a firm offer is made, some shareholders could be forced to exit at a loss:
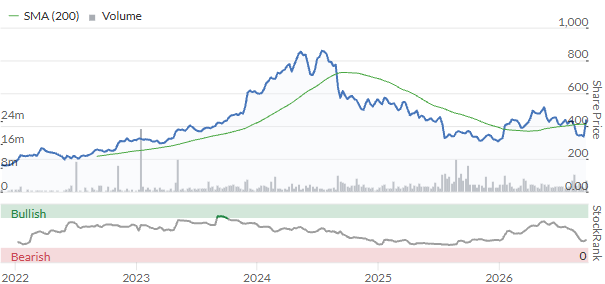
On balance I don’t have a strong view on the valuation here. My guess is that since Ashtead’s board have agreed to due diligence, they may be willing to accept a firm offer at this level if Ember wants to proceed.
Raspberry PI Holdings (LON:RPI)
Up 10% at 698p (£658m) - Interim Results - Roland - AMBER =
This innovative low-cost computer specialist is one of the top three performers in the FTSE 350 so far this year, up 123% year-to-date (the other two are CMC Markets and XP Power). Profit (adj EBITDA) guidance has been upgraded today, but as I’ll explain I think the impact on earnings will probably be fairly modest and potentially hard to forecast.
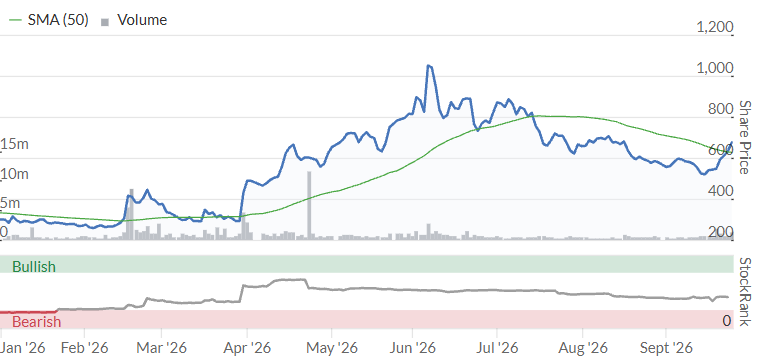
I covered the business in a Stock Pitch in April, following which Graham reviewed the group’s half-year trading update in June. He took a neutral view at the time, noting the valuation was high but that risks relating to component shortages and price increases appeared to have been managed successfully.
Today we have full details of Raspberry Pi’s half-year performance and updated outlook commentary for the remainder of the year. Let’s take a look.
Half-year results summary
We already know that memory shortages have had an impact on the consumer electronics market, as AI system builders hoover up all available supplies at top prices. Raspberry Pi has emerged successfully from this, noting that its existing inventories, scale, financial strength and relationships with suppliers have enabled it to secure inventory and led to an increased level of confidence in being able to continue to do so.
Even so, I am surprised by today’s headline figures and the apparent distortion in Raspberry Pi’s “unit economics” in H1:
Revenue up 90% to $256.9m
Gross profit up 79% to $59.4m
Gross margin down 2% to 23%
Adj EBITDA up 108% to $40.3m
Pre-tax profit up 216% to $19.6m
Adj EPS up 192% to 13.9c
The 90% increase in revenue needs to be seen against the 17% increase in unit volumes, which rose to 4.2m in H1:
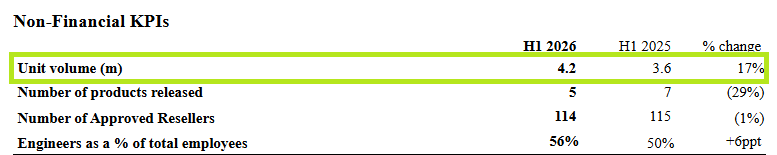
While the product mix within this volume changed somewhat, this tells us that the average price of products sold during the first half of this year rose by 62% to c.$61.
Today’s commentary confirms my figures are in the right ballpark:
[Average Selling Price per board] increased by 42% from $46.4 in H1 2025 to $65.9 in H1 2026 due to increases in the selling price of the product to cover the increases in the cost of component memory.
Profitability: while overall gross margin dipped in H1, the group’s EBITDA margin improved to 15.7% (H1 25: 14.3%) and its operating margin rose to 7.7% (H1 25: 5.9%). That’s quite a significant shift.
CEO Eben Upton notes that what’s happening in the memory industry is ultimately a normal cycle:
The current memory price cycle is a large, but ultimately typical, instance of a phenomenon that periodically affects the industry. As in previous cycles, sustained high prices are encouraging additional investment in foundry capacity, with meaningful new supply expected to come on stream in 2028.
Trading commentary: this business has its roots in supplying educational and hobbyist customers, but these days they form a minority of the customer base. The majority of the company’s output now goes to business customers, either end users or OEMs.
Demand from both classes of buyer was strong in the period and the company’s order backlog doubled in H1.
One key product launch during the period was AI HAT+2, which is an edge AI device that allows users to run LLMs and vision-language models locally, providing benefits in cost, privacy and latency. The company sees edge AI as a big growth area and intuitively this seems right to me.
Another area of emerging growth may be the defence industry. The company has a “Board-to-Board” initiative that’s being used to build relationships with senior decision makers at major OEMs:
Over the past 18 months, we have engaged with more than 50 C-suite leaders and have identified 26 projects, with an increasing focus on defence contractors and national militaries.
Outlook
Unit volumes are expected to increase on H2 as Raspberry Pi works through its backlog, having secured additional contract manufacturing capacity in H2.
However, the company says that the “exceptional unit economics” seen in the first half have moderated. One reason for this is that older stocks of (cheaper) memory are being depleted and replaced with higher-cost memory purchased more recently.
Despite this, adjusted EBITDA is “expected to be ahead of current market consensus”.
I don’t have access to broker forecasts today, but my impression is that previous consensus was for EBITDA of c.$58m – so a beat is not surprising based on H1 EBITDA of $40m.
Without access to any specific financial guidance for H2, it’s hard for me to estimate the likely impact on earnings. However, after an initial pop, the shares are up by less than 10% as I type. This suggests to me that the upgrade to earnings is unlikely to be greater than this.
The longer-term potential for growth could be considerably greater, though, if volumes continued to rise:
A strong pipeline of OEM opportunities and the increasing salience of its offering in key end markets mean that Raspberry Pi is well positioned for rapid growth in unit shipments in 2027 and beyond.
Roland’s view
Raspberry Pi’s half-year figures look remarkable to me. As I speculated with Computacenter (disc: I hold) recently, I can’t help feeling they could suggest that we may be nearing peak spending on AI.
Despite this, profitability is still somewhat average and with the stock trading on a forward P/E of 50, I think there’s already plenty of good news priced in for the near term.
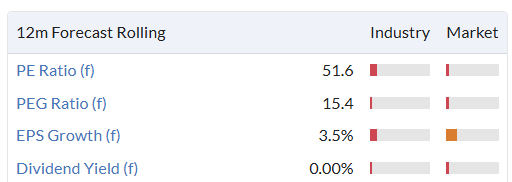
There hasn’t been a consistent trend of broker upgrades, either. Prior to today, at least, expectations were for flat or lower earnings next year:
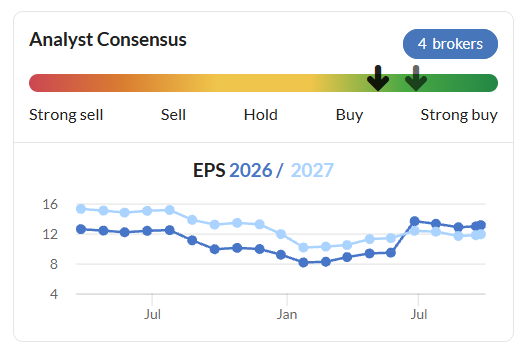
Of course, being too pessimistic is rarely a good way to make money in stocks, especially in a booming sector. So I may be wrong, or at least premature.
On a longer view, I still think Raspberry Pi is a high quality, differentiated business with the potential to deliver impressive growth over time. I also wonder if the company’s focus on edge AI and low-cost devices may also help it escape the impact of any slowdown in the boom in hyperscale AI.
To balance these conflicting views, I’m going to maintain our neutral view today.
Vistry (LON:VTY)
Down 5% at 253p (£811m) - Half-Year Results - Roland - PROFIT WARNING (AMBER/RED =)
Today’s half-year results also include the conclusions of the CEO Review carried out by CEO Adam Daniels following his appointment in April. As expected these are quite poor figures, but the uncertainty they imply is made worse by the fact that Vistry has also warned on profits again today.
Half-Year Results Summary
H1 performance was already expected to be poor, with full-year profit dependent on a stronger performance in H2:
Adjusted revenue (including JVs) down 9% to £1,703.3m
Completions down 8% to 6,304 units
Adjusted pre-tax loss of £(83.3)m (H1 25: profit of £80.6m)
Reported pre-tax loss of £(661.3m)
Adj EPS of (18.8)p
Net debt £468.8m at 30 June 2026
Average daily net debt was £799m in H1
The gap between reported and adjusted profits in H1 was particularly large. There were two main reasons for this:
A £475m goodwill impairment charge relating to past acquisitions;
A £73.2m building safety provision.
I am prepared to adjust out the goodwill impairment, given the circumstances. But as I’ve commented previously, housebuilders’ building safety provisions represent real future cash outflows and are ultimately a cost of doing business for these firms. I don’t see much justification in adjusting them out, especially as they are being incurred over multiple years.
Debt worries: the other point worth noting here is the high level of Vistry’s average daily net debt. This is the figure to monitor, in my view, not the much lower period-end figure.
As a sign of how dependent the company is on leverage, Vistry expects it will take three years (until FY29) to bring average daily net debt below £300m.
One way to accelerate this process might be to raise new equity, but the CEO appears to rule this out today:
We are committed to entering 2027 on the right footing and following the actions taken, do not anticipate any need to raise equity.
Instead, he’s planning to slim down the company’s land bank and streamline its operational structure, making this a slightly smaller but more profitable business than was previously the case.
Vestry’s lenders appear to be happy with this plan and have agreed the necessary covenant waivers to allow the company to progress into 2027:
Our banking group has demonstrated their support for the Group by providing waivers for the interest cover covenants for FY26 and HY27 that were subject to impact from the sizeable charges being taken in connection with the CEO Review
I count 28 mentions of the word covenant in today’s half-year results. It’s explicit that the company would have breached its interest cover covenants as a result of today’s accounts, so we have to assume that the company’s lenders have done the maths and are confident debt can be reduced without fresh equity.
I think this is positive for shareholders, but only in the limited sense of avoiding immediate dilution. There’s a risk that the alternative of several years’ suppressed earnings and cash flow could be equally painful for equity holders, if housing market conditions don’t improve to provide a favourable tailwind.
CEO Review: key points
We are repositioning Vistry as a specialist mixed-tenure housebuilder that will deliver consistent, cash-backed growth in earnings alongside highly attractive returns on capital. To achieve this the Group will need to be smaller, more focused geographically and with increased discipline and control in operational delivery and allocation of capital. Managed realisation of value from our asset base will support further de-leveraging, ensuring the Group has a robust platform from which to operate.
A key element of this will be the reduction of Vistry’s land bank from 51k to 36k plots, reducing capital employed and providing cash to fund debt reduction.
The company also appears to be steering slightly away from its previous goal of becoming a capital-light partnership builder. Daniels’ strategy is now for Vistry to become a leading mixed-tenure builder, with a 60:40 split between partner funded and open market homes.
The reshaped business will have reduced exposure to “underperforming South East areas” and greater exposure to the Midlands and the North of England. The end goal will be a business building c.12,000 homes per year (2025: 15.7k, 2024: 17.2k).
Outlook & Revised Guidance
Order book: Vistry has redefined its forward order book “to comprise only exchanged or otherwise legally contracted orders”, excluding those where formal exchange has not yet taken place.
This seems prudent to me, to say the least. But I can’t help feeling that the timing of this change also helps to mask the exact level of the decline in the group’s order book. I often find that when companies redefine their reporting metrics, the timing of the change is worth considering.
Today we’re given the following numbers, based on the new order book definition:
September 2026 order book: £3.3bn
September 2025 order book: £3.7bn
However, the group’s 2025 results reported a March 2026 order book of £4.5bn, using the old definition of orders. This does seem to suggest that c.£1bn of expected but not contracted work has now disappeared from the order book.
Profit guidance: after a £475m impairment in H1, Vistry expects a similar set of additional costs in H2 (my emphasis):
We are in the process of finalising the classification and quantification of items related to the exit from the South East of England, changing site strategies in the land bank and other strategic actions. We anticipate that the impact of these items in full year will be around £470m.
There will also be a £40m cut to pre-tax profit as a result of delays in certain partnership deals so they can be renegotiated to meet “our revised criteria”.
After all of these costs, Vistry expects FY26 adjusted pre-tax profit of c.£165m.
For contrast, in May the company cited a consensus FY26 forecast range of £168m to £283m.
FY27 adjusted pre-tax profit is now expected to be c.£185m.
While it’s welcome that this uncertainty has been narrowed down, I think it’s fair to say today’s guidance is a profit warning.
Roland’s view
One figure that hasn’t fallen today is Vistry’s tangible net asset value, which actually rises slightly to £2,520.7m or c.790p per share today (FY25: £2,312m).
With the stock trading at 253p as I write, Vistry equity can be purchased at a 68% discount to its tangible net asset value. For a housebuilder whose net assets are essentially homes and land, this is potentially attractive.
The size of the discount hints at the possibility of a distressed valuation. Given the company’s debt levels, I think it’s wise to be cautious. As I mentioned above, even if debt is reduced, equity holders could face a period of very lean returns while lenders take priority.
Even so, for investors with a deep value bent and a favourable view on the outlook for housing, I think this could be a situation worthy of further research.
While I think this business probably will recover over time, I’m going to leave our view at AMBER/RED today, to reflect the high level of leverage and the fact that the company needed a covenant waiver to avoid falling into default. From a factor-based perspective, we can’t ignore these risks.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
I know KGF might be boring for some, but do you think you can cast your eyes over Tuesday's results? Shorters have had a field day with this for a long time, yet it now seems to be turning itself around. I do wonder if a sustained repricing of shares is imminent? Forgive me, I have held for some time!
Fonix (LON:FNX)
Fonix ticked Ed's 'Post Earnings Drift' theory of a 10% plus rise on the day of an 'Ahead Of' RNS. Fonix rose 21.5p to 192p on it's FY26 results released on 22/9. It has moved up a further 5% since and I am expecting further gains. A realistic short term TP would be in the 230's given reasonable market conditions. It will go XD for 6.2p probably on the 18/11 with payment probably on 25/11. Although these dates are yet to be confirmed they would be consistent with past ones.
Fonix (LON:FNX)
Seems a good shout to me Helvellyn. I bought an opening position for my son's ISA at 170p and bought for my own ISA at 184p on reading the prelims.
The post earnings drift thesis did occur to me at the time. Will see if it plays out.
All the best
If Cavendish revises FY27E upward — as they essentially must, given Fonix delivered their FY27E a year early — you might see ~13.5–14p pencilled in. At 230p that's roughly 16.5–17x forward earnings, which is sensible for a business with a 77% EBITDA margin on gross profit and net cash on the balance sheet. FONIX is a rare AIM company that does what it says, charges fairly for it, and has never lost a client.
Not posted for ages as Im pretty much out of UK markets doing other stuff but some might find this interesting.
Halfords / Raleigh / Pillar Gold
Few titbits from bicycle industry .
1/. Halfords
Accel group are bust in Europe and the carcas about to picked apart.
One of my suppliers who will be feasting told me Raleigh had already been sold to Halfords.
Good buy that for a UK centric company to get hold of the most iconic brand in uk “for next to nowt” .
Dont think it will necessarily do anything to sales.
2/ Rapha
Fran Millar steps down as CEO of Rapha who are , and always have been the most ridicolus company making overpriced overlywanked pretentious nonsense .
Never made a profit, was bought by the Walton (walmart family) grandchildren who swallowed the hype and bought a ludicrous company now costing them circa 20 million a year in annual losses .
3/ Bike Industry
Tough as hell
No upswing
Only saving grace less competition
Bike shop owners back to the old days of having little shops doing good services to nice customers .
Good lifetstyle business where you earn the same amount as stacking shelves at tescos.
Maybe thats not so bad .
Glory VC days and consolidation days long gone now reversing to its former mom and pop shops .
Thats a good thing in my book, hopefully vets and dentists end up going the same way.
3/. Pillar gold / Jeremy Grey / Pure Tungsten
Hats off to Jeremy Grey of Chancery royalty .
If you are intersted in owning companies that give a shit about investors then look them up .
I originally spoke to him along the lines
“Im sick of holding shares in lse / aim where i cant engage with the company or share the journey.
Business and investment is about knowledge and experiences not being ignored and treated as an irrelevence”
He got it and promptly asked if i wanted to go with him to Brazil the next week!
That was a year ago
One year later my son has been to pure tungsten in south korea, pillar gold in brazil - hes so engaged in the sector and building his knowledge now in an internship with Chancery.
Even his mate “pat” who invested the minimum 5k went to brazil and they had “our best trip ever” (i did pay for flights as both working for me).
Even more satisfying his knowledge and confidence have skyrocketed and despite declining university hes “bloody running rings round all the univeristy iterns”
Deep Knowledge comes from emgagement and passion and sharing the journey, when you have deep knowledge you often dont realise its value
Took me 35 years life in bike industry and thousands of cock ups to finally realise the value of the journey .
Anyway no idea what that all means other than anyone looking at resource sector plays should think about “risking it” and stepping outside of AIM / LSE and take a look at chancery / pillar etc .
And if you did invest FFS go to brazil down a gold mine .
Nice to read you and family are going strong planetx, I miss your tell it as it is posts.
thanks for the nice comment that made my day
ill try to post a bit more now
yes I’m also pleased to see you back
'And if you did invest FFS go to brazil down a gold mine .'
I keep on buying Serabi Gold (LON:SRB), can't think why. Maybe Planet X has something here too.
i had a big holding in Serabi but sold recently around 330 level after a spike
There are permit issues dragging it back.
Serabi i think has limited upside compared to many others.
There is going to be a huge amount of M/A in next couple years as the big miners who are literally printing cash have to buy the junior minors / late stage explorers .
I was quite deep into the “safe” royalty companies like Wheaton / Franco but have recently been switching to the actual miners .
Its a very volatile market so avoid watching day to day movements .
Personally Im more comfortable having my cash in a pre IPO such as Pillar gold than a traded / mature Serabi .
Pillar is a fraction of the price, and my son/pat have touched it and felt it.
Pillar also has a sum of the parts calculation that tells me its a breakeven even if it never produced an ounce,
yesterday pat messaged his mate at the mine asking if they were on track and got a thumbs up.
And if it goes to shit we learn the lessons but as an investor I trust these guys more than and board of directors i have ever met on AIM / LSE
i once owned 15% of an Aim company and found out the chairman was 85 and was best mates with the founder, whose daughter was CEO and he had been chairman 20 years.
They got rather annoyed when i started asking questions about corporate governance and future direction , she even burst out crying
“why are you doing this”
anyway that was a bloody expensive lesson in value trap microcaps with family control (i forced it private in the end)
Brilliant!
The Rapha comment provided a good laugh!
Absolutely. I tend to avoid the overlywanked pretentious nonsense and stick to moderately or even microwanked nonsense where I can
Good to hear from you PlanetX.
Unlike you I remain fully invested in the UK with few exceptions in small caps and the occasional mid cap
I steer clear of what I don't understand that includes mining companies, although I am happy to invest in the so called 'picks and shovels' providers. Mincon (LON:MCON) being an example. But the best of luck to your son and his friend and of course you.
Your comment about Halfords (LON:HFD) caught my interest. I bought the shares when no one was interested around 140p to 150p. Prompted by the appointment of the new CEO, Henry Birch who in my view has done an excellent job in turning the company around.
On the subject of bikes, I did think that Halfords (LON:HFD) would be interested in Raleigh. It is an iconic British brand with a great heritage and strikes me as an excellent fit provided they have acquired it without paying over the odds.
Cycling and bikes are a relatively small but not insignificant part of Halford's business but the possible acquisition of the Raleigh brand and the arrival of the Grand Depart of the Tour de France (men and women races) next year should provide a tailwind for cycling and bike sales in the UK. This should benefit Halfords who are far and away the country's largest bike retailer, albeit it has a very limited presence in upper end of the bicycle market
All the best
Morning Roland,
Would you mind giving your view on Zegona Communications (LON:ZEG). I hold in my VM portfolio. Surprised to see the drop this morning based on news of buyback and divi. Many thanks.
Morning Roland
Are you able to include InvestAcc (LON:INAC) in your review? I read the statment from Vistry (LON:VTY) CEO and impressed by the detail of the review and its outcome is obviously going to see slimmed down version of the business. There are plenty of caveats, not the least to me being can they achieve the indicative margins on the newly styled business. One wonders given they are obviously hoping to sell lots of land if this will be something of a fire sale and write offs ensue; is this a read across to other housebuilders with large land banks
Poses lots of questions for the sector going forward
Pollen Street (LON:POLN) looking to go private or a buyer
Where is the best place to see buy and sell trades as they happen to get an idea of volumes and the relative buy/sell mix? Thanks
Morning Doctor
Limit your screen time as much as possible and spend more time and energy on digging into financial numbers. That’s where the money is!
All the best
thanks Yiannos. I'm sure you are right. I don't really have the financial nous for the numbers though. I rely on other smart people to tell me when the numbers look interesting!
The problem with relying on other people is they may be wrong. AI can help you understand the numbers but again - double check the answers.
aNewFN.com provides level 2 for free which gives you this info
Wow! How can they do that free?
You need L2. The likes of IG provide it. Typically £40 per month I think. Mixed reviews as to whether its worthwhile or not. I've researched myself but never bothered
Biopharma Credit (LON:BPCR). (I hold)
Morning Roland, would you be able to comment on the 6 month results from Biopharma Credit please?
Many thanks.
I hold, but for income, the price chart doesnt expect growth?
Good morning. Would it be possible to get your thoughts on Tufton Assets (LON:SHIP) please? Final results look decent . I hold.
Hi Roland, if time permits, could you cast your eyes over tinyBuild (LON:TBLD) half year report? A bit of a mixed bag from what I can tell, with a divergence between revenue and gross profit.
Ashtead Technology Holdings (LON:AT.) third takeover offer from Ember.
4th I believe
I can't keep up!
Morning Felix, Thanks for flagging this. I've added Ashtead Technology Holdings (LON:AT.) to the table.
Roland
Asos (LON:ASC) Hoping to see an update on Asos today following trading statement, interesting to see the teams comments on what's starting to look like a recovery story, with many boxes of improvements being ticked....
I'd appreciate wiser heads comments on the Mercia's imminent AGM statement today in the RNS. We hold, I'm
wondering what "the potential divestiture of the direct investment portfolio" would to their static share price?
Most likely they will get 10-15% less than NAV for those assets.