Daily Stock Market Report (Wed 29th July 2026) - GRG, SGE, PAY, HSP, NICL, LRE, ABDN, KOO, AML, SDI

Fed interest rate decision: this evening, in addition to US company earnings, we’ll have an interest rate decision from the Federal Reserve at 7pm.
There are other central bank meetings this week - including the Bank of England tomorrow - but it’s the Federal Reserve decision that is most interesting as it holds the potential for a surprise rate hike.
The new Chairman Kevin Warsh, despite being appointed by President Trump to replace Jerome Powell, hasn’t given any assurances that he will conform to Trump’s rate-cutting bias. On the contrary, Warsh has refused to reveal which direction he believes rates should go in next, and has instead focused on the need for price stability. With inflation still above the Fed’s 2% target, this implies rate hikes and/or other inflation-reducing measures could be called on.
On Polymarket this morning, the probability of a 25 basis point rate hike is seen as 22%, with no change at 78%. The current Federal Reserve target interest rate is 3.5% - 3.75%.
Overnight market movements:
The FTSE is unchanged at 10,870
S&P 500 is down 0.1% at 7,425
Brent crude (October) is up 3.2% at $84.75/bbl
Gold is up 0.2% at $4,035/oz
Bitcoin is up 0.2% at $64,050
All done for today, thank you! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£112bn | SR46) | Revenue +15% to $31.0bn with underlying earnings +43% to $6.9bn. Underlying EPS +42% to 421.4c with interim dividend +43% to 211.0c. Outlook: 2026 production and cost guidance unchanged, but the group’s tax rate is now expected to be c.25% vs c.30% previously. | ||
Glencore (LON:GLEN) (£59bn | SR46) | Expect to report H1 adj EBIT of c.$3.1bn in the Marketing (trading) division. In mining, copper production was +15%, with cobalt -46% and zinc -21%. Outlook: 2026 production guidance largely unchanged. | ||
Standard Chartered (LON:STAN) (£46bn | SR86) | H1 operating income +6% to $11.6bn with pre-tax profit +9% to $4.8bn. RoTE +1.2% to 17.6% with cost-to-income ratio -2.7% to 54.6%. Net interest margin stable at 2.04%. 2026 outlook: revised guidance for operating income growth in the middle of the 5-7% range with RoTE to be >12%. | ||
Reckitt Benckiser (LON:RKT) (£33bn | SR77) | Net revenue -8.1% to $6,411m with LFL growth of 2.6%. Adj operating profit -14% to $1,469m with adj EPS -9.7% to 152.1p. Performance of Core Reckitt improved in Q2 and Mead Johnson returned to growth. 2026 outlook: unchanged guidance for LFL net revenue and “Core Reckitt + MJN” adj op margin. | ||
Valterra Platinum (LON:VALT) (£13.5bn | SR70) | Revenue +93% with adj EBITDA +406% to R33.4bn and headline EPS of R84.02. Sales volumes +18% to 1.7m PGM oz, benefiting from higher PGM prices. Net cash of R23.7bn and dividend of R57/share. Acknowledges three fatalities during the period. 2026 Outlook: full-year guidance unchanged. | ||
Sage (LON:SGE) (£8.5bn | SR42) | Revenue +11% to £2,062m (NAm +13%, UKIA +10% & Europe +7%). Recurring revenue +11% to £2,002m with software subscription penetration improving to 84% (Q3 25 YTD: 83%). Outlook: expect total revenue growth of >9% with operating margins trending upwards. | AMBER/GREEN = (Roland - I hold) I think the risks of AI disruption to this business have been overblown. AI is a new technology Sage must adopt, but I don’t think it will replace the company’s products unless Sage fails to keep up. Fortunately there’s no sign of this yet, with continued double-digit revenue growth and forecast earnings growth of 15% in the current year. Sage’s Falling Star styling and low StockRank have been a useful warning during a period of de-rating for the shares, but I think this stage is now ending. I’m hopeful that the recent re-rating could herald a more positive market for quality software companies. While I am obviously biased, as a shareholder, I’m leaving our broadly-positive view unchanged today. | |
Weir (LON:WEIR) (£6.6bn | SR38) | Revenue +5% with adj pre-tax profit -8% at £196m. Adj EPS -7% to 54.6p. Margins lower due to product mix and timing factors. Cumulative cost savings of £72m achieved. FY26 outlook in line with market expectations with “strong order book at end of June”. | ||
St Jamess Place (LON:STJ) (£5.6bn | SR80) | H1 net inflows of £2.7bn with net investment returns of 16.4% and AUM up 9% to £240.8bn vs FY25. Adjusted pre-tax profit -9% to £278.4m and adj diluted EPS -2% to 42.9p. | ||
Aberdeen (LON:ABDN) (£4.6bn | SR93) | SP -5% Revenue +2% with adj op profit +21% to £151m. Adj EPS +9% to 8.2p with interim dividend held at 7.3p. AUMA +4% to £579.4bn with net outflows of £3bn. Net capital generation +47% to £163m. Outlook: “confident in our ability to deliver our 2026 Group targets.” | AMBER/GREEN = (Graham) [no section below] | |
Greatland Resources (LON:GGP) (£3.5bn | SR82) | FY26 gold production of 328,987oz and AISC of $2,312/oz, ahead of guidance for 260-310koz and $2,400-$,2800/oz. FY27 guidance: gold production of 260-300 koz and AISC of $2,900-3,330/oz. Expect $750-850m of capital expenditure on growth projects and exploration. | ||
Shaftesbury Capital (LON:SHC) (£2.9bn | SR48) | EPRA NTA per share +3.9% to 223p, giving an accounting return of 4.9%. Adj EPS +8% to 2.4p with interim dividend +16% to 2.2p per share. Occupancy high: only 2.6% of ERV available to let. Outlook: confident of achieving medium-term targets. | ||
Plus500 (LON:PLUS) (£2.8bn | SR78) | Partnership to provide US futures access for Canadian firm Wealthsimple, which has 4m customers and c.$150bn AUA. | ||
Rathbones (LON:RAT) (£1.85bn | SR51) | H1 net outflows of £0.9bn, with FUMA +10.7% to £120.7bn vs H1 25. Operating income +9% with adj pre-tax profit +14% to £123.2m. 2026 outlook: H2 will be affected by costs relating to the FCA Skilled Person Review, including a £9m reduction to operating profit relating to the cessation of fees on cash held in portfolios. The Q4 operating margin target has been reduced from 30% to 28.7%. | ||
Greggs (LON:GRG) (£1.73bn | SR87) | Total sales +7.2% to $1,101.5m with pre-tax profit +20% to £76.0m. Company-managed shop LFL sales +2.1 and franchise LFL sales +1.3%. Continue to gain market share, +0.3% to 8.7% during the period. Outlook: full-year expectations unchanged. | AMBER/GREEN ↑ (Roland) I think this is a solid set of results. While costs and pricing power evidently remain under pressure, Greggs is generating growth from new openings and was able to increase sales faster than costs in H1, expanding its profit margins. My previous analysis has suggested the group’s capex is generating suitable returns on capital employed. Today’s figures seem to support that tentative conclusion. With capex now returning to more normal levels, cash available for shareholder returns could improve. The stock isn’t quite as cheap as it was, but I think the outlook is broadly positive, so I’m upgrading our view by one notch today. This is also reflected in the company’s StockRank, which has risen from 70 to 87 over the last two months. | |
Lancashire Holdings (LON:LRE) (£1.60bn | SR79) | Top line and combined ratio “in line with our expectations”. GWP -3% to $1,315m with insurance revenue flat at $930m. Profit after tax +30% to $141.7m with discounted combined ratio of 80.7% (H1 26: 87.4%). H1 return on equity of 9.7%. Outlook: on track to deliver high-teens RoE for FY26. | AMBER/GREEN (Graham) This is a slightly strange situation. The company says that its “stable top line and strong combined ratio” were “in line with our expectations”, but various media outlets have reported that the numbers missed expectations. The market was evidently expecting a little more. The commentary is also fairly downbeat, although nothing it said should be too surprising - insurers will indeed need to be “disciplined” while navigating the “excess capacity” that’s currently available. For what it’s worth, I’m a fan of this business, and I’m going to run with AMBER/GREEN today on the basis that the market wasn’t pricing it for perfection anyway. | |
Paragon Banking (LON:PAG) (£1.53bn | SR49) | Q3 “strong trading” with loan advances +4.3% and the net loan book +3%. Outlook: “full-year guidance reconfirmed”. | ||
Breedon (LON:BREE) (£1.13bn | SR67) | Revenue +5% (LFL +3%). Adj pre-tax profit -16% to £41.3m with adj EPS -16% to 9.4p. Completed £110m of bolt-on acquisitions in US and Ireland. 2026 Outlook: expect performance in line with market expectations. Positive momentum in Ireland and US, weaker in GB. | ||
Firstgroup (LON:FGP) (£991m | SR60) | Sold rail software subsidiary Mistral Data Services to Tracsis for an enterprise value of £48m. In FY26, Mistral generated revenue of c.£13m and operating profit of c.£4m. Updated FY27 guidance: as a result of the sale, expects a c.£4m decrease in FY27 adj op profit and a c.0.6p decrease in adj EPS. | ||
Conduit Holdings (LON:CRE) (£686m | SR69) | GWP -1.8% to $789m with net income of $80.3m. Discounted combined ratio of 80.4% (H1 25: 108.3%) and return on equity of 7.8%. NTAV +1.1% to $7.56. Outlook: continuing to rebalance portfolio to reflect softening market conditions. | ||
International Personal Finance (LON:IPF) (£554m | SR84) | Adj pre-tax profit -5% to £47.4m with adj EPS -6.3% to 13.3p. Customer numbers +5.4% to 1.7m with lending +18.5% to £781.7m. Expect takeover to complete on 4 August 2026. | TAKEOVER | |
Avon Technologies (LON:AVON) (£545m | SR40) | Team Wendy Ceradyne has received a follow-on order worth $20.1m from the US DLA under the Advanced Combat Helmet framework announced in 2022. | ||
PayPoint (LON:PAY) (£374m | SR96) | Net revenue down 6.4%. In Q1, “achieved our primary objective of implementing the changes arising from our business reorganisation… we remain confident in making further progress in FY27 and meeting market expectations.” | GREEN = (Graham)
I’ve been a fan of this one for a long time, and it’s going to be difficult for me to change stance today, after an "in line" outlook statement. The weakness in Q1 revenue does cast some doubt in my mind on the company’s ability to hit its full-year forecasts. But on balance, I’m inclined to stay GREEN on this, as I think the potential for a revenue/profit warning is priced in at a P/E multiple of 7x. PayPoint has a long track record of excellent cash generation and the fact that it’s now applying this cash flow to reducing its share count could help to create significant upward pressure on EPS over time - assuming that business performance is reasonably stable. So I’m staying positive here. | |
Nichols (LON:NICL) (£371m | SR62) | Revenue +4.7%. Operating profit +35.6% (£14.1m). “...we remain confident in our ability to deliver sustainable growth and create long-term shareholder value. The Board's expectations for the full year remain unchanged and we remain confident in achieving our medium-term financial plans." | GREEN = (Graham)
I acknowledge that this share doesn’t excite too many private investors, but I’ve convinced myself that it’s materially undervalued here. It's far from just being a UK business: Vimto is the unofficial drink of Ramadan in the Middle East, and there are significant sales into Africa (£16m in H1, up 17% year-on-year, out of total sales of £89.5m). When we also consider the rock solid balance sheet, I think a trade buyer would pay significantly more than 14x forward earnings for this business. I’m staying GREEN. | |
Aston Martin Lagonda Global Holdings (LON:AML) (£370m | SR38) | Revenue +38%. Adjusted EBIT loss £108.9m. Net debt £1,545m. FY 2026 operational guidance unchanged whilst remaining mindful of the broader macroeconomic and geopolitical backdrop. | RED = (Graham) These results are a car crash with negative adjusted EBIT and rising net debt. The net debt pile is now about four times the market cap. Even with a huge increase in H1 revenue and gross profits, the company was still a very long way from making real profits. The net finance expense in H1 alone was a terrifying £98m, with cash interest paid of £75m. I would only consider investing in the debt here, not the equity, and would need to be very heavily compensated for a debt investment. The rating at Fitch is CCC+. In the words of Fitch (May 2026): "AML will likely require continued shareholder support or additional debt financing in the short-to-medium term." | |
Allergy Therapeutics (LON:AGY) (£341m | SR6) | H2 2026 revenues expected to be £23.6 million (H2 2025: £21.0 million) representing growth of over 12%. Full-year growth 9%. “Group is strongly positioned for a further acceleration in sales momentum… expects to achieve year-over-year double digit revenue growth for the year ending 30 June 2027.” | ||
Ecora Royalties (LON:ECOR) (£326m | SR54) | Total portfolio contribution of $19.0m in Q2 2026, up ~60% v Q2 2025. “Net debt has continued to reduce, down to $75m from $125m this time last year, and we expect further debt reduction throughout the rest of the year providing balance sheet flexibility to fund further royalty acquisitions that meet our investment criteria”. | ||
Franchise Brands (LON:FRAN) (£287m | SR59) | System sales +6.7%. Adjusted PBT +7.8% (£12.6m). Leverage reduced to 1.5x (June 2025: 1.8x). “Confidence that our full year performance will be in line with market expectations.” | ||
Hargreaves Services (LON:HSP) (£241m | SR97) | Revenue +32.9%. Underlying PBT +93.2% to £34m. Net assets £195m. “With a strong order book in Services and promising long-term opportunities ahead, the Group is well-positioned to sustain its positive momentum.” | AMBER/GREEN = (Roland) Last year’s bumper profits are expected to fall to more normal levels this year. Arguably this leaves this industrial group trading at fair value, but I’m inclined to remain broadly positive given the strong tangible asset backing for the balance sheet and Hargreaves’ track record of creating shareholder value. In my view, it’s not too hard to imagine a catalyst emerging over the next 12-18 months – perhaps in the housebuilding sector – to justify an earnings upgrade. In the meantime, I think the 5% yield provides sufficient reward for holding as the company adapts to new management. | |
James Fisher And Sons (LON:FSJ) (£237m | SR65) | Overall HY26 performance in line with expectations. Revenue of c. £190m with strong trading in Defence and Maritime Transport, offsetting softer activity in Energy Board's expectations for the full year remain unchanged. | ||
Jadestone Energy (LON:JSE) (£172m | SR38) | SP -6% H1 2026 average production of 15,281 boepd (H1 2025: 20,368 boepd). Production was primarily impacted by the previously announced shut-in at the Stag field due to the impact of Cyclone Narelle, and planned maintenance activities associated with the CWLH FPSO drydock. 2026 production guidance is revised to 16,000-18,000 boepd (from 18,000-21,000 boepd). | BLACK | |
Mobico (LON:MCG) (£170m | SR61) | Adjusted Revenue of £3.42bn (+5.9% vs. 15 months 2025 period). Adjusted Operating Profit guidance for calendar year 2026 increased from £195 - 210m to £215m - 230m. | ||
Severfield (LON:SFR) (£109m | SR94) | A positive start to FY27, with trading since the beginning of the financial year in line. Guidance for FY27 is unchanged, including underlying profit before tax of £12m-£15m. | ||
Diaceutics (LON:DXRX) (£108m | SR32) | H1 revenue grew 22% at constant currency to £17.5m. ARR +75% to £28.8m. H1 Adjusted EBITDA of £1.1 million. “...confidence that the Company targets for 2026 are on track.” | ||
Tracsis (LON:TRCS) (£99m | SR67) | Mistral Data is a UK rail software provider with a diversified portfolio of business-critical cloud-native software and data solutions. Tracsis to pay £48m on a cash-free, debt-free basis. Subject to clearance from the CMA. | ||
SDI (LON:SDI) (£99m | SR85) | Organic revenue growth 5.5%. Also 7.1% growth from acquisitions. Adjusted PBT +16.8% to £9.9m. Expect to deliver FY27 performance in line with current market expectations. | AMBER/GREEN = (Graham) [no section below] Nice organic growth here, including 6.7% in H2 (higher than the result for the year as a whole). It's easy to forget that these "buy-and-build" companies usually need a healthy mix of both organic and inorganic growth in order to become successful investments. The total growth rate, including the effect of acquisitions, is 12.5%, leading to an attractive increase in profitability. And the net debt figure of £24m should be very manageable in the context of adjusted PBT of £9.9m. One wrinkle for me is that the adjusting items are fairly high at £3.4m: leaving them out inflates operating profit by over 40%, and I'm not sure that all of them are fair. The £2.3m adjustment for amortisation may be reasonable, but I wouldn't assume that the other ones are. I also note that the balance sheet has negative tangible equity. Overall, I think our moderately positive stance continues to make sense on this one. At 12x earnings, I think it still offers upside, but with just enough reasons for doubt to keep me from embracing a fully positive view. | |
Chapel Down (LON:CDGP) (£75m | SR24) | Net sales revenue +19% (£9.4m), in line. Variable weather conditions in Kent. Overall yield to be broadly in line with 5-year average. Board remains focused on delivering strong double-digit growth and is confident in the Company delivering FY26 full-year results in line with market expectations. | ||
Alternative Income REIT (LON:AIRE) (£60m | SR48) | Urges shareholders to take no action in respect of the unsolicited Glenstone offer. Any shareholders who accepted the offer are urged to withdraw their acceptances. | TAKEOVER | |
Rentguarantor Holdings (LON:RGG) (£59m | SR35) | Various changes. Three new NEDs. Business Compliance Manager to become Chief People and Risk Officer (Board Member). NED to become Director of Research and Innovation (Board Member). | ||
Ilika (LON:IKA) (£57m | SR10) | Has continued to develop and commercialise its two solid state battery product lines. Revenue £1.1m, operating loss £9m. Post-period end, raised £5m. Outlook: Increase recognition of Stereax product revenues, through the signed licensing agreement in place with Cirtec. | ||
Kooth (LON:KOO) (£57m | SR67) | H1 in line with expectations. Revenue £30.8m (H1 last year: £32.1m. Adjusted EBITDA £5.0m-£5.4m (H1 2025 £1.6m). Net cash £23.1m. | AMBER/GREEN = (Graham) [no section below] The cash balance stands out here, covering 40% of the market cap. That alone is enough to get me interested, but we also have a profitable core business. At Canaccord Genuity, estimates have been left unchanged today including adjusted EPS of 9.3p this year and 12.5p next year (current share price: 151.5p). If I adjusting for the company's enormous cash balance, I get a Price to Enterprise Value multiple of 10x for this year and 7x for next year. Not bad. Is it a quality business? That's where I'm not sure: success seems to hinge on a small number of contracts with US states (California, Michigan, New Jersey) along with various UK customers. Success with existing contracts could lead to sticky, long-term government revenues and a more diversified customer base as more State governments get on board, reducing risk for investors. But the company is not quite there yet. For example, Canaccord Genuity are forecasting that revenues will slightly reduce both this year and next year, even as profits are rising. So personally, I'll need more evidence of success before upgrading our stance on this one. | |
Hemogenyx Pharmaceuticals (LON:HEMO) (£48m | SR2) | Letter of Intent with the National Cancer Centre at Vilnius University Hospital Santaros Klinikos to establish a scientific and clinical collaboration in FLT3-positive acute myeloid leukemia and myelodysplastic syndromes. | ||
Cobra Resources (LON:COBR) (£43m | SR7) | All assay results from the Sonic core drilling have been received. Mineralisation continuity at the Head Prospect validated. “The team is making strong progress in advancing the Boland project towards economic assessment. We are working to maximise the data delivered into our MRE which will seek to minimise project risk.” | ||
Predator Oil & Gas Holdings (LON:PRD) (£27m | SR4) | Announces the execution of an amendment to the existing rig contract with Intrepid Drilling Limited. It allows for an extension to facilitate MOU-6 well operations for a period from 1 August 2026 to 1 October 2026. | ||
European Green Transition (LON:EGT) (£26m | SR17) | Revenue of c.£6.8 million in the four months since completion of the acquisition of the Wind Energy Services business on 25 February 2026. The Board expects the Wind Energy Services business to generate revenue in the range of £17 million to £18 million for the 12-month period ending 31 December 2026. | ||
Abingdon Health (LON:ABDX) (£25m | SR25) | Revenue (including grant-funded income) for FY26 expected to be up 31% to £11.3m. Profitable at the adjusted EBITDA level in H2.. “Board are confident of further growth in FY27, based on significant programmes previously announced and underway.” | ||
KRM22 (LON:KRM) (£23m | SR15) | ARR £7.9m (H1 2025: £7.2m). Revenue £3.8m (H1 2025: £3.7m). “Whilst there have been delays in conversion of the sales pipeline, the explanation for this has been clear… we look forward to the second half of the year with a clear focus and confidence on achieving market forecasts." | ||
Altitude (LON:ALT) (£19m | SR46) | Results will be announced next week. Previously they anticipated release on 29th July (today). | ||
LMS Capital (LON:LMS) (£13m | SR17) | NAV £26.6m (33p per share). “The Board continues to focus on realising the portfolio. Our ambition remains to have a clear path to liquidity in 2027 in relation to our two main assets.” | ||
LPA (LON:LPA) (£12m | SR79) | New contract award for the supply of inter car jumper systems for a global train builder. The value of the contract is £1.4 million. Delivery begins in February 2027 and ends in May 2028. | ||
Thor Energy (LON:THR) (£11m | SR22) | Q2 has “strengthened our exploration model and confirmed our conviction that the HY-Range Project is a significant geological opportunity for us to explore further. We recorded natural hydrogen concentrations of up to 3% during our Phase-2 geochemistry survey, which surpassed our initial expectations.” | ||
Newmark Security (LON:NWT) (£10m | SR82) | The MD of Safetell buys it from Newmark for £1. Additionally, £300k of the intercompany balance owed by Safetell to Newmark will remain outstanding as a deferred loan, with the balance being waived. |
Graham's Section
PayPoint (LON:PAY)
Down 4% at 600p (£358m) - 1st Quarter Results - Graham - GREEN =
The Q1 revenue numbers here are uninspiring: everything is down except for the small “Digital Payments & Open Banking” division.
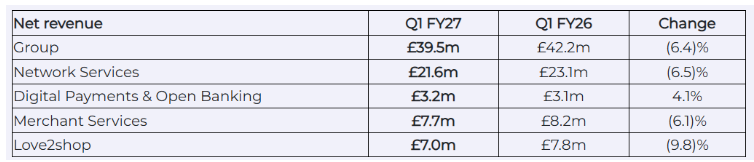
However, PayPoint describes it as “solid” (really?) and that they are “on track to meet market expectations for FY27”.
Market expectations suggest that the company will generate £195m of net revenue this year, so Q1 has only generated 20% of this. But the business is seasonal in nature - e.g. Love2Shop vouchers being bought before Christmas - so I think it’s still entirely plausible that the company can hit these full-year expectations.
Rather than focusing on the weak year-on-year revenue, management commentary focuses on the business reorganisation they’ve been working on:
We have had a busy start to the year and, in the first quarter, achieved our primary objective of implementing the changes arising from our business reorganisation. While it is still early in its implementation, the initial indications are encouraging. We are already seeing clear signs of enhanced ownership and accountability, together with greater focus on product development, go-to-market strategy and business development across each business unit.
This reorganisation saw the company dividing into the four business units shown in the table above: Network Services, Digital Payments & Open Banking, Merchant Services and Love2shop.
Paypoint says that this is more transparent and accountable than the previous structure.
The previous structure didn’t look very different at first glance: Shopping, E-commerce, Payments & Banking, Love2shop.
However, the changes include new operating structures across divisions, with newly-defined management teams. So it seems to be more than just a superficial change in how things are categorised and labelled.
CEO’s comment concludes as follows:
With the business reorganisation largely complete, a solid first quarter performance delivered and a good trading rhythm established across the Group, we remain confident in making further progress in FY27 and meeting market expectations.
Network services (convenience store business): the lower net revenue in this key division relates to the difficulties in the parcel business which first appeared last year. There are “growing volumes from Royal Mail and other carriers continuing to build, but not yet offsetting the impact of the new InPost commercial agreement and lower store to store volumes.” As I recall, PayPoint agreed to new commercial terms that assumed higher volumes, but volumes went on to disappoint.
Share buyback: a £25m buyback is ongoing, which is the third tranche of an overall buyback programme. The first two tranches returned a total of £50m.
There are now fewer than 60 million shares outstanding, compared to 65 million a year ago, and 67 million two years ago. This is going to have a meaningful impact on EPS, assuming that profits can hold up.
Graham’s view
I’ve been a fan of this one for a long time, and it’s going to be difficult for me to change stance today, after an "in line" outlook statement.
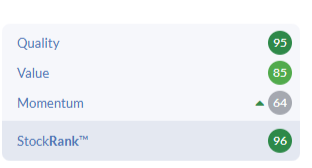
It’s still considered a Super Stock by Stockopedia:
The weakness in Q1 revenue does cast some doubt in my mind on the company’s ability to hit its full-year forecasts. But look how cheaply it’s priced already:
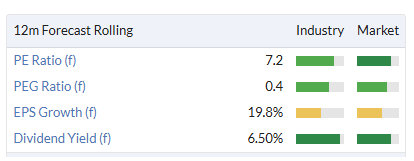
When a stock is trading on a P/E multiple of 7x, there is always going to be some sort of a catch: poor quality, low visibility, some major risk factor, etc.
In the case of PayPoint, there have long been doubts about the company’s growth prospects. Its traditional bill payments business has long been considered to be on the way out. Recent full-year results (covered by Mark here) did show modest growth, in the aggregate, but I must acknowledge that today’s Q1 numbers aren’t too inspiring.
On balance, I’m inclined to stay GREEN on this, as I think the potential for a revenue/profit warning is priced in at this P/E multiple.
PayPoint has a long track record of excellent cash generation and the fact that it’s now applying this cash flow to reducing its share count could help to create significant upward pressure on EPS over time - assuming that business performance is reasonably stable. So I’m staying positive here.
Nichols (LON:NICL)
Up 1% at £10.25 (£375m) - 2026 Interim Results - Graham - GREEN =
This soft drinks group never provokes much controversy or comment, but I think it’s still worth highlighting.
Its interim results are excellent: revenue growth of 4.7% turning into a 35.6% growth in operating profit:
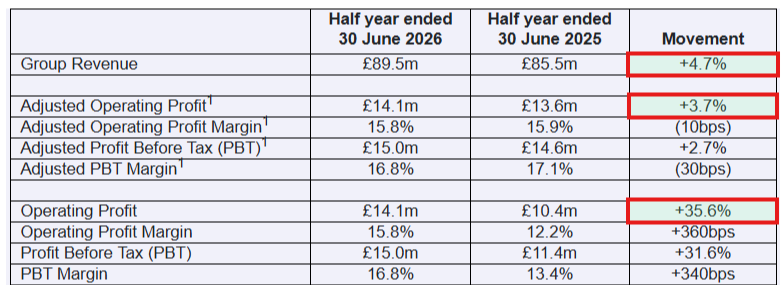
The reason is that there are no exceptional items in this H1 period. In H1 last year, there were £3.2m of adjusting costs to do with the “Business change Programme and Systems Development”.
I always love to see clean results, and it doesn’t get much cleaner than this.
The company also benefits from net finance income, rather than a net finance charge, which means that pre-tax profit (£15m) ends up being higher than operating profit (£14.1m).
That tends to reflect a very strong balance sheet: the cash balance at Nichols is £66.2m. In the words of management, this provides “significant flexibility to support the Group's growth strategy and capital allocation priorities.”
Return on capital: soft drinks companies are capable of producing famously high returns, and that’s the case here. Stockopedia’s calculations:
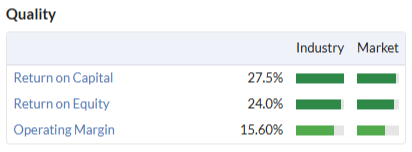
For its most recent calculation, the company gets a ROCE of 27.9%. That’s slightly worse than last year, if you ignore last year’s £3.2m exceptional cost. But it’s better than last year, if you don’t adjust that cost out. I prefer this year's result.
CEO comment:
"We are pleased to have delivered another strong period of strategic and financial progress, with revenue growth accelerating to 4.7% supporting further profit growth and record cash generation. Reflecting our earnings growth and revised dividend cover policy of 1.5 times, the Board has increased the interim dividend by 35%...
Supported by our strong portfolio of brands, geographically diversified model, robust balance sheet and significant financial flexibility, we remain confident in our ability to deliver sustainable growth and create long-term shareholder value. The Board's expectations for the full year remain unchanged and we remain confident in achieving our medium-term financial plans."
The yield here is 5.3%, according to the StockReport.
Outlook: “highly confident” in their ability to deliver further strategic and financial progress in H2. Full-year performance is expected to be in line, with market expectations given as adj. PBT of £35.1m.
Graham’s view
I acknowledge that this share doesn’t excite too many private investors, but I’ve convinced myself that it’s materially undervalued here:
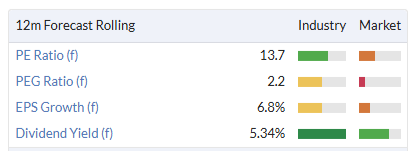
This is far from just being a UK business: Vimto is the unofficial drink of Ramadan in the Middle East, and there are significant sales into Africa (£16m in H1, up 17% year-on-year, out of total sales of £89.5m).
When we also consider the rock solid balance sheet, I think a trade buyer would pay significantly more than 14x forward earnings for this business. I’m staying GREEN.
Lancashire Holdings (LON:LRE)
Down 6.5% at 617p (£1.51bn) - H1 2026 Results - Graham - BLACK (AMBER/GREEN)
Let’s take a quick look at the interim results from this catastrophe insurer.
Highlights:
Gross premiums written $1,315 (down 3%)
Insurance revenue flat at $930m
Insurance service result rises 28% to $198.8m (GN note: this is the operating profit from insurance)
Despite the really nice increase in the insurance service result, these results have reportedly missed expectations. Alliance News says that the combined ratio was supposed to be 77.6%, but it came in at 80.7% (the lower the combined ratio, the better).
CEO Alex Moloney says:
Although the loss environment during the first half was less active than 2025, it was by no means benign. Against this backdrop, Lancashire delivered another strong result.
Rolling forward through the income statement, the main factors are:
High insurance service result, as already stated
Lower net investment return ($51.3m vs. $108.2m in H1 last year), due to higher interest rates and falling bond values.
Lower insurance finance expense ($31.8m vs. $73m last year), which I think is consistent with strong underwriting and/or a favourable claims environment. In plain English, I think a plausible explanation is that the company’s long-term obligations to insured parties were smaller than they were last year.
The end result of all of the above is a strong “net insurance and investment result” of $226m, vs. $207m in H1 last year.
Boosted by some “other income”, PBT ends up at $151m, compared to just $119m in H1 last year.
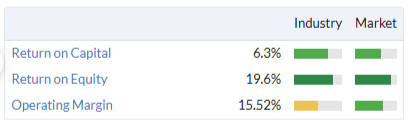
Outlook: “On track to deliver high-teens RoE for full year 2026”.
Stockopedia calculated 19.6% for last year:
Commentary focuses on how the company will deal “excess capacity” in the insurance industry:
Looking ahead, we remain on track to deliver our guidance given at the start of the year of a high-teens RoE for 2026 and we are well positioned to manage the next phase of the cycle, in which we expect rates will continue to reflect the excess capacity in the industry. In this context, we will draw on our considerable experience and expertise to remain disciplined, and we have the agility to deploy capital where we see the best returns. Lancashire’s strong capital base, robust reserves, and more efficient use of reinsurance provide important levers to underpin performance and to manage the business through the cycle.
Graham’s view
This is a slightly strange situation. The company says that its “stable top line and strong combined ratio” were “in line with our expectations”, but various media outlets have reported that the numbers missed expectations. The market was evidently expecting a little more.
The commentary is also fairly downbeat, although nothing it said should be too surprising - insurers will indeed need to be “disciplined” while navigating the “excess capacity” that’s currently available.
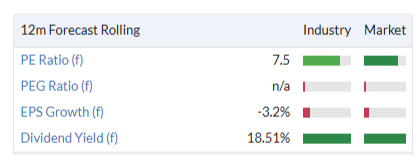
For what it’s worth, I’m a fan of this business, and I’m going to run with AMBER/GREEN today on the basis that the market wasn’t pricing it for perfection anyway:
Specialist insurers can be fabulous long-term investments - think of the likes of Hiscox (LON:HSX) but also Lancashire Holdings (LON:LRE) itself: generous dividends and capital appreciation.
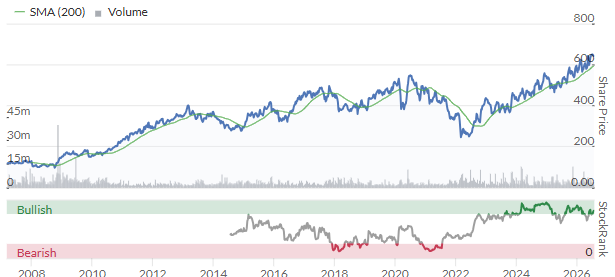
Tangible equity on today’s balance sheet is about £1.25 billion. The stock is only trading at a 20% premium to this, which I think is attractive given the company’s proven ability to earn high ROE:
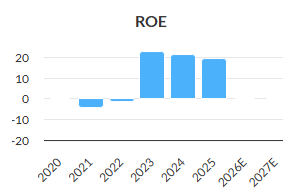
The company will have a bad year from time to time, and I can’t predict the timing of when those bad years will occur, but on a long-term view I have to like the risk:reward this offers
Roland's Section
Greggs (LON:GRG)
Up 12% at 1,888p (£1.89bn) - Interim Results - Roland - AMBER/GREEN ↑
According to Research Tree’s Short Interest Tracker, Greggs is one of the UK’s top-five most shorted stocks, with more than 10% of its shares out on loan to investors who are betting they will fall. Or at least it was, prior to this morning’s results.
I can’t help feeling that this morning’s 10%+ share price rise on in-line results may reflect the closure of some short positions as previously-bearish investors conclude that the worst of Greggs’ problems have now passed.
That’s certainly the feeling I get from today’s results – and it’s a view that’s also been reflected by the StockRanks over the last few months:
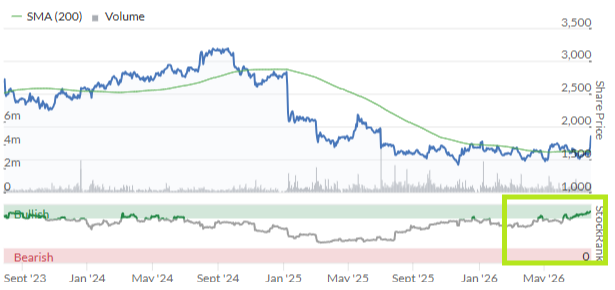
Let’s take a look at what this food-to-go market leader has to say today.
Half-year summary
Greggs says it was able to grow both market share and volumes “in a challenging market”. Market research data cited by the company suggests its share of the relevant market may have risen by 0.3% to 8.7% in H1 – a respectable performance that highlights the group’s leadership in this segment.
Financial results for the period also look pretty solid:
Revenue up 7.2% to £1,101.5m
Pre-tax profit up 19.7% to £76.0m
Diluted earnings per share up 21.2% to 54.9p
Interim dividend unchanged at 19.0p per share
First of all, I commend Greggs for issuing such clean accounts. There are no adjustments to these half-year figures. Accounts for previous recent periods have also been very light on exceptional items. It just proves that heavy use of adjustments is usually a choice by management, not a necessity.
Running through the figures suggests that Greggs’ pricing power and same-store volumes remain under pressure:
Company-managed stores like-for-like sales: +2.1%
Franchise stores LFL sales: +1.3%
The balance of sales growth came from new openings and increased distribution in grocery retailing.
The company says that LFL performance was aided by new menu items including Iced Matcha Lattes, “an enhanced salad range” and the “new Chicken Roll”.
New store formats including bitesize Greggs (a smaller shop format) and Greggs Express (a self-service format in convenience stores) are being trialled. The company opened its first international travel location with a franchise partner at Tenerife South Airport.
Around 100-110 net new shop openings are expected this year, with a further 10 Greggs Express trials.
Profitability improved as sales growth outpaced the 6.3% increase in operating costs during the period:
H1 operating margin: 7.9% (H1 25: 6.9%, FY25: 8.5%)
Trailing 12-month return on capital employed (ROCE): 17.3% (FY25: 16.1%)
Cash generation looks fine to me and the company reported a net cash position of £16m at the end of June, excluding lease liabilities. I don’t have any concerns about the balance sheet.
Capital expenditure also fell to £78m during H1, from £172m during H1 25. The company says it’s now passed the peak of its investment centre with the “substantial completion” of its Derby distribution centre.
Interestingly, full-year capex guidance has been cut from £200 to £180m. No detail is given on this reduction, but it seems a positive change to me, perhaps suggesting the company is maintaining a tight grip on expansion plans to ensure new outlets meet hurdle rates for profitability.
Normalising capital expenditure over the coming years is expected to allow more generous shareholder returns (my emphasis):
[...] capital expenditure will continue to normalise in the coming years as the new supply chain sites in Derby and Kettering are completed and we start to utilise the capacity that this creates. As the business moves to a more cash-generative phase, we expect to be in a position to increase returns to shareholders in line with our capital allocation policy.
Outlook
There’s no change to full-year guidance today:
As previously guided, the cost headwind from this increased capacity is expected to result in profits in the second half reducing year-on-year, absent a recovery in the consumer backdrop. The Board's expectations for the full-year outcome are unchanged.
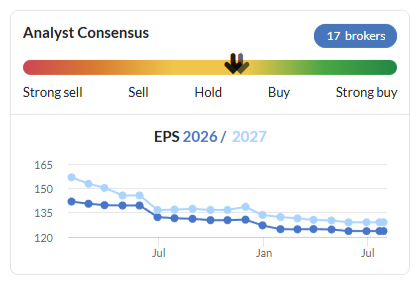
I don’t have access to any broker forecasts for Greggs, but consensus estimates prior to today are for 2026 earnings of 124p per share, rising 4% to 129p per share in 2027.
Following this morning’s gains, this puts Greggs on a forward P/E of around 15x with a dividend yield of around 3.7%.
As we can see from the consensus trend chart, forecasts have also levelled out in recent months. I don’t expect much change after today’s update.
Roland’s view
I think there are two key factors to consider here:
Can Greggs continue to expand?
Can the company maintain current levels of ROCE as the business continues to grow?
If the answer to both of these questions is yes, then profits should continue to rise and the intrinsic value of this business should grow.
In terms of growth, new store openings do seem to be generating material sales growth. While it’s too soon to be sure, new smaller formats may also offer the opportunity to expand in areas where a full store wouldn’t be viable.
When I analysed the returns generated by incremental capital expenditure in July last year, I tentatively concluded that it was generating suitable mid-teens ROCE.
Today’s improved ROCE result (vs last year) suggests to me that this remains true. With capex now normalising after a period of elevated spending, I’d hope to see profitability stabilise if new capacity is utilised as expected.
We’ve been neutral on Greggs in recent reviews. In May Ed Sheldon rightly highlighted potential medium-term headwinds such as weight-loss drugs, UK consumer spending and cost growth.
I share these concerns, but I am inclined to think Greggs’ strong market share, quality and scale will allow the group to adapt. I think this is a fairly strong set of results that bodes well for the future, so I’m going to move our view up by one notch to AMBER/GREEN today.
Sage (LON:SGE)
Up 4% at 976p (£8.8bn) - Trading update for nine months ended 30 June 2026 - Roland - AMBER/GREEN =
(Disclosure: at the time of writing, Roland had a long position in SGE.)
FTSE 100 accounting software group Sage was a High Flyer for many years, but has been a casualty of the AI boom and the vague idea that cheap AI-written software might somehow replace SaaS products:
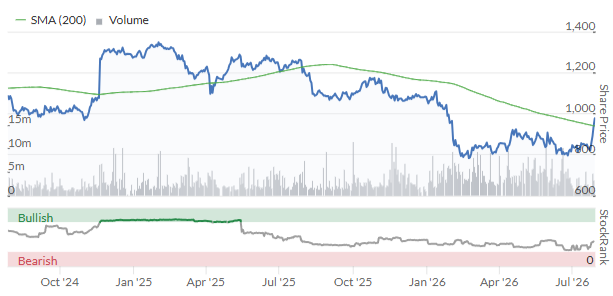
The stock’s Falling Star styling and subdued StockRank have reflected its unloved status, but I think we could soon see a more positive factor profile emerging for this high quality business.
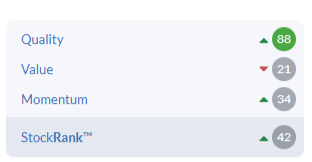
As Ed S reported in May, Sage’s half-year results showed double-digit growth in sales and profits.
Today’s third-quarter update tells us that this performance continued into Q3. These figures cover the nine months to 30 June 2026:
Total revenue up 11% to £2,062m
Sage Business Cloud revenue up 15% to £1,762m
Recurring revenue up 11% to £2,002m
Product development remains a key focus:
This reflects focused execution as we deepen AI capabilities across our platform, scale key products including Sage Intacct, and increase the value customers get from Sage. Demand from new and existing customers remains strong, with small and mid-sized businesses increasingly relying on Sage for finance, HR and payroll workflows, where getting it right is essential.
North America remains both the largest and fastest-growing region and now accounts for 45% of revenue:
North America up 14% to £932m
UKIA up 10% to £602m
Europe up 7% to £528m
Outlook
There’s no change to expectations today:
We continue to expect organic total revenue growth for FY26 to be above 9%, and operating margins to trend upwards in FY26 and beyond, as we focus on efficiently scaling the Group.
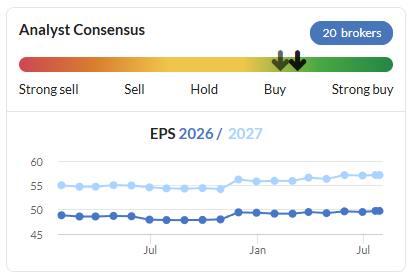
Consensus forecasts have edged higher over the last year and suggest earnings per share will rise by 15% to 49.7p in FY26:
Roland’s view
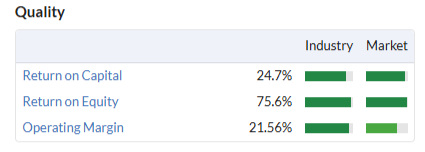
Sage’s share price has recovered somewhat recently but remains below the 1,000p level first seen in 2023. That puts the stock on a forward P/E of 20, falling to 17 in FY27. I don’t think that’s excessive for an £8bn company with double-digit EPS growth and strong quality metrics:
More broadly, I think it’s worth remembering that Sage has a large installed footprint and deep institutional knowledge about accounting software and global tax and accounting rules. It also has the operational capacity needed to support a mission-critical record-keeping service for SMEs all over the world.
I don’t see much risk that these customers will move away from paid software solutions for accounting and payroll – it’s simply too important (and the cost is not really all that significant).
For me, the bigger risks of an investment in Sage are that it will fail to close the market share gap with its larger rival Intuit (NSQ:INTU) – or that it will fall behind smaller, newer rivals in terms of product innovation and service (including the usage and application of AI).
However, these are business-as-usual risks for most technology-focused companies, so I don’t see them as a reason not to invest.
Of course, I am inevitably biased about Sage, which is a top-10 holding in my portfolio. Even so, I remain comfortable with our AMBER/GREEN view, which I’m leaving unchanged today despite Sage’s sub-par StockRank.
Hargreaves Services (LON:HSP)
Up 3.7% at 814p (£281m) - Final Results - Roland - AMBER/GREEN =
Today’s full-year results from this industrial group appear to be in line with consensus expectations, but last year’s profits were boosted by some one-off items and are expected to be lower in FY27.
This week will also see CEO Gordon Banham (and 8.5% shareholder) stand down after 25 years. He’ll take on a new role overseeing the group’s German joint venture. Banham – who I regard very highly – will be replaced by Simon Hicks, who joined Hargreaves as Chief Operating Office in 2025.
Webinar: today’s Investor Meet Company webinar will be presented by Hicks and Banham, together with CFO Stephen Craigen, so might be worth watching for any interested shareholders.
The point I’m making is that this business may be approaching a period of change, after a strong performance in recent years.
FY26 results summary
There’s little to dislike about today’s full-year numbers:
Revenue up 31.9% to £351.4m
Underlying pre-tax profit up 93.2% to £34.0m
Pre-tax profit up 130% to £40.3m
Adjusted EPS up 75% to 79.1p
Total dividend up 8.1% to 40.0p
Net cash down 7% to £21.6m
Net assets up 0.6% to £195.4m
Stripping out exceptional gains, these numbers give a FY26 operating margin of 8.2% and a return on capital employed of 11.6%. That’s above average for this business.
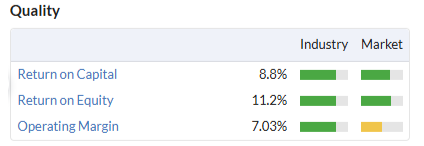
However, last year’s super-sized increase in revenue and profit deserve some explanation. In brief, several factors contributed to this growth:
Additional work on some major infrastructure projects (e.g. HS2 and Sizewell C) where Hargreaves’ role has now also expanded to include supply chain management for “critical building supplies”.
A £13m pre-tax gain relating to the sale of some assets, including renewable energy assets.
A one-time benefit from the settlement with Tungsten West, terminating the previous mining services contract between the companies.
Divisional summary: Hargreaves’ operations are split across three main operating segments.
Services (earthmoving & related logistics): revenue rose by 35% to £329.9m last year, supporting a 27% rise in pre-tax profit to £20.2m. Looking ahead, the company secured its first position on the Lower Thames Crossing last year and also scored contract wins at Drax Power Station and with Fortis IBA (incinerators) for logistics services.
Hargreaves Land (development and sale of land for housebuilding and renewable projects): revenue rose by 7% to £21.5m while underlying pre-tax profit jumped more than 400% to £12.5m (FY25: £2.3m). The disconnect between revenue and profit growth is because the jump in profit was largely driven by the sale of two renewable energy packages for a total of £15.6m. These were held as investment properties, which meant that their sale was not included in revenue. Looking ahead, the company’s housing land pipeline includes 31 schemes containing over 12,000 residential plots over 1,615 acres. These are all at various stages of planning approval, but should gradually generate returns over future years. In renewable energy, the company’s remaining assets have an independent valuation of £9.1m, compared to a book value of £3.3m. So further sales could generate additional one-off gains.
Germany (commodity trading and recycling JV): share of profits from the JV rose by 53.7% to £6.3m last year. Construction of a zinc processing plant is underway, supported by significant government-backed funding.
Outlook & Broker Estimate
Forward-looking commentary from CEO Designate Simon Hicks is positive but non-specific:
Looking ahead, the Group is well positioned for continued progress, supported by strong revenue visibility, a robust balance sheet, and exposure to long-term UK infrastructure, energy and development opportunities, providing confidence in delivering sustainable shareholder value.
Fortunately we have more specific guidance from Hargreaves’ joint broker, Cavendish.
Cavendish forecasts are unchanged today but confirm a significant fall in revenue and profits is expected this year, before a return to more normal growth in FY28:
FY27E revenue: £293m (-16.6% vs FY26)
FY27E adj EPS: 48.8p (-38.3% vs FY26)
FY28E revenue: £301m (+2.7% vs FY27E)
FY28E adj EPS: 50.7p (+3.9% vs FY27E)
These estimates put Hargreaves on a forward P/E of about 16.
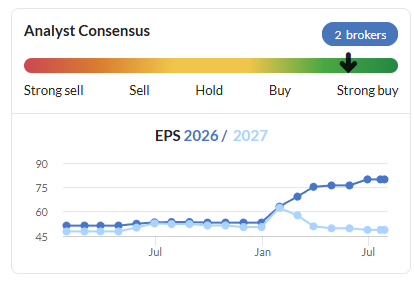
There should be no real surprises here for Stockopedia subscribers: consensus forecasts have been flagging up the divergence between exceptional FY26 earnings and more normal FY27 profits since early this year:
Roland’s view
I’m on record as a long-term fan of this group and have great respect for the way Gordon Banham has managed Hargreaves’ exit from coal services and then gone on to generate a lot of value for shareholders from its land assets and by expanding the services business.
However, as I’ve commented before this is a fairly capital-intensive business. Last year’s bumper profits mean that return on equity peaked at 15.7%, but the average since 2021 is only 12%. Today’s forecasts from Cavendish suggest an adjusted ROE figure of c.8% over the next three years.
On that basis, I would argue that the current valuation of c.1.3x book value is probably high enough.
I’d also note that the change of CEO after nearly 30 years might bring some changes.
However, I think it is fair to argue that Hargreaves is in a good position to continue expanding its infrastructure services business. Any recovery in housebuilding could also accelerate further profits from land disposals – the group’s balance sheet remains strong and is almost entirely backed by tangible assets.
I’m disinclined to take a neutral view without a more concrete reason to do so, given the company’s track record of creating value for shareholders.
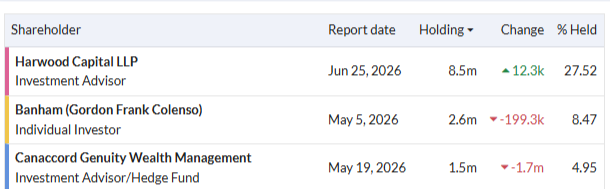
I’d also note that Harwood Capital remains the group’s largest shareholder, at 27.5%, and does not seem to have sold any stock yet.
In my view, it’s not too hard to imagine a catalyst emerging to prompt an upgrade to earnings over the next 12-18 months. In the meantime, dividend forecasts suggest the yield will be maintained at c.5% – not unattractive.
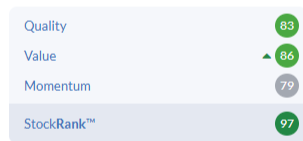
The StockRanks are also positive (although they have not yet digested today’s numbers):
I’m going to retain my previous AMBER/GREEN view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Greggs (LON:GRG) there is an OUTLET near me which I think sells day before leftover sandwiches, and can get a donut and cup of tea as discount prices. It is very busy. It's not always easy to grab food on the go other than Mac's.
Hi guys, not a criticism, a question... Why do so many of reporting companies not have expert reviews anymore, just copy and paste from update?
I think you are losing the plot here - we have had 6 long reviews here today ? yes ?- i am pretty much sure thats above the long term average - i would concede back in the day Paul Scott used to sometimes go on a mega binge of detailed reporting when he was on the wagon for a month :)
So in sumamry its never been the case that most compaines get long review its always tended to be 5 or 6 on average on a "good" day.
note what has improved is that we do get the cut and paste highlights that are really useful - its not the case though that they have ben dowgraded - kinda the oppposite as we didnt always get that info previously (back in the day)
if you wnat to fact check it type Norcros (LON:NXR) - go to that company - it regularly is pinned - go to discussions on that company - and it shows hom many companies had detailed anlaysis back in the day if you count the ticker numbers for that day - i would say that up to 2024 i would guess its average of 4 a day and there was no useful table summary.
Not losing the plot, just asking a simple question, based on facts..
Maybe you should read my question again, you may then understand what I am saying.
Have a good evening
apologies if i misread - i thought you saying were saying there used to be more long reports on average than 6 per day ?
MAN group
This co has never interested Graham but has produced excellent results and share price has reflected that.
I just noticed today that the stocko rank has jumped from 50 to 92. This is of interest to those who follow Ed Croft interest in JUMPERS!
…but it is significantly above the £350m market cap cutoff and above that cutoff the Stockrank jumps have delivered much more mediocre returns.
I wouldn't mind studying Man (LON:EMG), but I admit that it doesn't appeal to me. I've never really understood the appeal of a publicly-listed hedge fund. And I spend most of my time studying smaller companies, anyway. But well done if you've made money out of Man!
EMG CFO/COO sold £1.5m worth this afternoon
Very happy to announce that the Mello Team have now launched Mello London, taking place on the 17th & 18th November. Early bird tickets on sale now and full event details are here: https://www.melloevents.com/mellolondon2026
For those who haven't been before, Mello is a two-day investor event that's built around what we feel matters most to investors... getting direct access to company management teams, learning from some brilliant keynote speakers, and spending time with other serious investors to share ideas or just talk investing in general - something you don't typically do down the pub or in your usual social circles!
To those of you who have been to Mello conferences before (many have attended double digits since the first in 2014), the team will of course try to improve on our Mello2026 and MelloBirmingham events earlier in the year. If you have any companies you would like us to bring along, any panels that may be of interest or areas of investing you would like Mello to cover, please do drop your suggestions below.
Richard Staveley Rockwood Strategic (LON:RKW) & Lord John Lee will be returning to our keynote stage. A handful of our other investing heroes and respected fund managers will be on our Mello Theatre stage. Again, 50+ quality companies will be delivering investor presentations and exhibiting in our main hall (scroll down our Mello London page to see the companies that were on show at our Mello event in June).
As the formal presentations wrap up, and just before investors start to relax in to the evening chats, we will have our ever-popular BASH (Buy, Avoid, Sell, Hold) panels featuring investors such as Richard Crow, Jamie Ward, Paul Scott, Mark Simpson, Lord John Lee and more. The Mello Team will be pulling out all the stops to make this as great a Mello event possible. I hope to see as many of the Stockopedia community at the event with us...
Important to note, tickets are on early bird for few more days until 4th August, making it just £69 for a one day pass or £99 for a two day pass... Booking early particularly helps us with event planning and making Mello as smooth an event as possible! Investors can save up to £100 by booking early and our MelloMembers receive a further 30% discount.
If you miss the early bird, use code Stocko25 for 25% off General Sale & Final Release tickets: https://www.melloevents.com/mellolondon2026
See you in November for Mello London, it is going to be an excellent two days for investors - Mello really is a very open and welcoming investor community so do join us!
Can't understand what the market wanted from Kooth (LON:KOO) today? Half year figures to be 'in line' and net cash very healthy. If the California contract gets renewed next year and the company can win one or two more US State contracts to broaden the revenue base, these shares could start to look very cheap. I hold.
I can only assume its the lack of news around the california contract. There's an expectation if or when thats announced the SP will gain significantly and I guess some people were trading for that to happen now
added this morning Kooth H1 2026 Trading Update ( I hold )
Bull case:
▫️Adj EBITDA guided £5.0m-£5.4m vs just £1.6m H1 2025 massive margin inflection
▫️Net cash up to £23.1m (from £15.3m H1'25) — strong balance sheet, £57m mkt cap = net cash covers ~40% of it
▫️California (Soluna) smashing targets: 187k registrations, independently validated by CA DHCS + Northwestern research
▫️Featured in Gov Newsom's Legacy Report, CA budget now balanced through 2027-28 — de-risks funding
▫️New Michigan contract adding revenue, UK pipeline growing (West Midlands pathfinder, school rollout)
Bear case:
▫️Revenue actually down YoY: £30.8m vs £32.1m , CA product dev revenue tapering + £0.7m FX drag
▫️Full results not due till September limited detail on quality of earnings until then
Verdict: Cash-rich small-cap inflecting on profitability with de-risked US funding backdrop
Hopefully the team have time to pass comment on it
Graham
Your write up for Conduit Holdings (LON:CRE) is referencing another stock i think
can you correct - thanks
Conduit repeats Firstgroup
Greggs (LON:GRG) Interims. Shares up 11%. Nice.
Sales up 7%, 20% rise in profit. This was one of the most shorted stocks earlier this year. Seemed a bit of a daft idea in my mind, but there you go.
Another QGARP stock of mine. EV/EBITDA of 6.2. I usually regard that as cheap.
So, they had their Tenerife shop opened, a new factory, and started selling to Tesco. All seemed pretty positive to me. The market was unimpressed, though.
Sometimes it pays to go for the good boring companies.
Greggs (LON:GRG)
Sometimes it pays to go for the good boring companies.
Indeed slightly annoyed at myself for not scooping up more here - i am uber confident ref the long term prospects of greggs - little thinks like the super uptake of the app for payment is key here. There is a real and meaningful incentive (free sausage roll?) for them to go to greggs rather than try the shop next door. You are missing out on that free one for every nine you buy - if you use alternatives. Hey ho the spike back up may not last if AB adds more woe onto thgeir cost base?
Clearly they have had cost headwinds - will those cost headwinds alwasy be present ? perhaps it may not get materially easier - but the gov needs to keep an active high street - greggs spoons and the like have taken too much of the burden i dont think anyone is denying that even AB himself.
So i get it for anyone that thinks profits may keep edging down on cost worries and swerve it - i personally am more than happy that long term the business is in fine fettle overall even if the current numbers trend confirms "its tough"
Hi RM Have to agree on your Greggs comments I bought in after the management started to look accident prone with some obvious miss steps. I also took the view this was cheap given the company would turn a cash generator once the investment programme was completed and most of it looked entirely sensible given the aim to increase outlets.
I thought the percentage out on Loan for shorts was well over the top and i expected this to pull back which it seems may be the case. Yes this is a ' boring' company but i like these in my portfolio as a counter weight
Golly, a stampede of results etc. Don't envy your job today chaps. I wonder why the smaller companies don't pick a quieter day - unless they want to hide! Don't envy your job today chaps.
Sage (LON:SGE) Nice results. I bought a few in June this year at 823p. My usual QGARP criteria applied: low debt, good returns on capital, steady grower, fwd pe < 16.
I used a bit of gizzard-squeezing (also known as technical analysis) to time my entry.
Shares were in a basing/consolidation period since Feb.
The kind of thing I looked is testing the lows 3 times as an entry point.
To me the most important thing is to have a fundamental view on the company and maybe use a bit of very simple technical analysis to pick a good entry point. That's optional, though. The shares have broken through resistance now, so we should be getting a nice pop out of these.
FWIW I heard that Terry Smith had been buying these.
SGE fell on AI woes. I'm a former chartered accountant and computer programmer. I judged the chance of AI disruption to be minimal.
AI is good at giving fuzzy answers, but not good at stuff requiring mathematical precision. You can't just ask "Grok, write me an accounts package." There are plenty of free software packages out there anyway, so if they haven't rendered SGE obsolete then nothing will.
My mate Dave has been using AI for his programming endeavours. He uses a paid subscription. His verdict is that it's pretty good for this purpose, and often comes up with little tricks and approaches that he didn't think of.
Caution is required, because the results are sometimes wrong, and they don't actually replace a human beings. AI doesn't scale well, though. It can work for small focussed routines, but it introduces a lot of randomness and bugs as you try to expand its remit.
Shares up 0.3% today as I write. It's not that much, although it did receive a boost yesterday.
Sage and Finsbury Growth Trust
I bought the later as it has Sage and many other similar companies , solid but unloved. FGT share price has also is moving up recently. Maybe more big rotation money is coming our way!
I think Nick Train has made his mistakes in the past, but I think the stage is now set for him to do well over the next 5 years. Probably same with Terry Smith. (Mind you, I gave Neil Woodford a pass, but that turned out to have been wrong thinking).
His Lindsell Train Investment Trust (LON:LTI) is trading at a wide discount (about 15%), so holders could well be in for a double-bonus.
The market was handing out a tonne of stuff this year (EXPN, RELX) which has gone up, but there's still a lot of stuff out there like SGE, RMV, BCG (a little risker pick) and AUTO.
I think the narrative is shifting a bit. They all dumped on AI, but their fundamentals have shown to be pretty strong. So bopefully the market will wake up to this and we'll see some significant re-ratings.
Yes I think LTI looks interesting now , albeit on the riskier side versus FGT. The Train funds have really struggled because of their focus on 2 extremely out of favour sectors - consumer staples and software/data. However, the underlying performance of the companies has generally been good, and it wouldn't surprise me if these areas come back into favour.
A lot of the Train holdings have seen a strong recovery in last few days so I would expect LTI to see a decent uptick on the next NAV - I would expect the real-time discount to be over 20% now. The struggling fund management business makes up 17% of LTI, so at the current price you're getting this for free and still leaving a small 5% discount for the rest of the portfolio (5% discount is about standard for a global equity portfolio).
To me this is worth a punt - even if the fund management business dwindles to nothing over the next few years it will still throw off a lot of cash in the meantime, so clearly worth more than zero. On the other hand there is always the possibility that it returns to growth, so you're effectively getting a free option on this scenario.
The key feature to note is the Sage Business Cloud, where revenue climbed 15% to £1,762m, and within that cloud native revenue jumped 25% to £794m. The Cloud Native products, primarily Intacct, now accounts for 38.5% of Total Revenue. As that pace of Cloud Native growth is set to continues it will become a greater proportion of the revenue mix - causing the top-line growth to accelerate - as well as increasing margins.
Sage is also making a success of rolling out AI enhanced features - and more importantly monetizing them.
Intacct, their leading Cloud Native AI enhanced product, is being rolled out geographically. It was a significant growth driver in US/North America and appears to be repeating this success in the UK, France, Germany and elsewhere.
Mr Market has continued the SGE re-rating today up 33.8p to 973.60p +3.6% at
10:37 BST 29/07/26.
The Brokers, as is Roland, are pretty cool on Sage with a consensus share price target 1,096.61p - this is below the fairly recent high of 1336p [pre SaaS-apocalpse c. Jan 2026].
Let's see if they update their spreadsheet models and issue some upgrades.
Am I the only one disappointed by today's numbers from PayPoint (LON:PAY) ? The market seems to have shrugged them off with just a minor negative on the share price. I think this is one of your favourites Graham. What do you think?
Meanwhile CT Automotive (LON:CTA) continues to steam north at a rate of knots. Can't have everything I suppose.
Edit: I think the market has just taken a second look at today's numbers. Now down with a thump.
SK Hynix hammered after its Q2 earnings. Could be another volatile day for chips and AI infrastructure...
They are already taking a hammering in the last few days! Anything remotely related to AI chips/infrastructure has sold of significantly in last week. Apart from the Korean players US companies like Micron Technology (NSQ:MU) , Lam Research (NSQ:LRCX) , Vertiv Holdings Co (NYQ:VRT, Comfort Systems Usa (NYQ:FIX) are all down heavily. Interesting comments from John Authers newsletter this morning that technology momentum trade driven by AI may be over or at best easing. An equal weighted version of the S&P 500 is at an all time high vs. the 10% fall in the Nasdaq 100 from its recent peak.
Would be interested to hear your view on Lancashire Holdings (LON:LRE) , Graham. Insurance for catastrophes - you have to wonder whether this is the best of times, or the worst of times! Nevertheless, they put out a reassuring statement this morning. Tends to be a big dividend payer.
Hi Brucie
Also be worth our commentators having a look at Conduit Holdings (LON:CRE) which had an overlarge loss last year regarding the California wild fires. Ring any bells ??
The UK stock market seems to be behaving in a more "American" way. Maybe there are more Americans fishing in our depleted pond? Both Luceco (LON:LUCE) and Barclays (LON:BARC) yesterday got hit hard for good-but-not-stellar results. Will be interesting today to see what happens with Aberdeen (LON:ABDN) after their fair-to-good results.
Hi G
Could you please put this up on the main page.
Regards
Morning Gutty, not sure why it wouldn't have been on the main page but it should be there now! G
Any chance of running the rule over the Aberdeen (LON:ABDN) update Graham.
Thanks Andy