Daily Stock Market Report (Wed 4 Dec 2024) - ANCR, TET, ZIG, MEGP, PMI, COST

Good morning everyone!
Wrapping this up just before 1pm. Thanks for all the comments!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
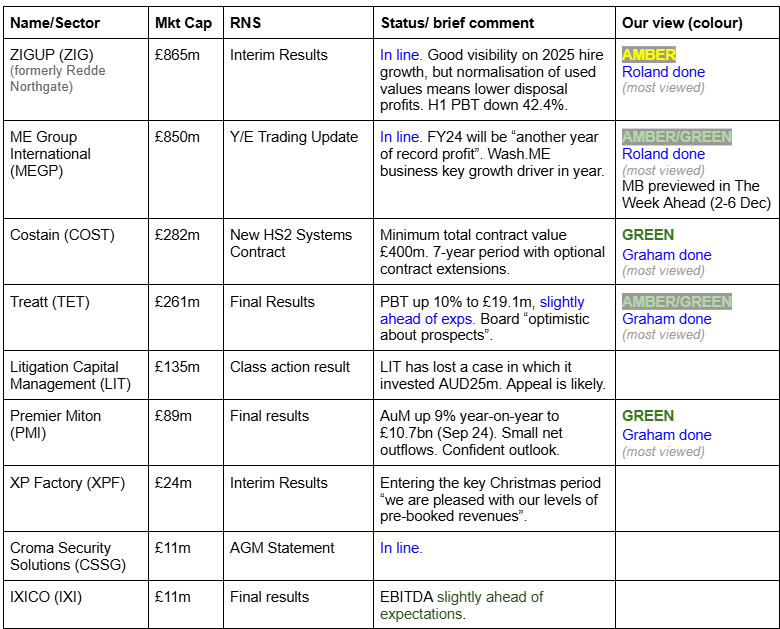
Summaries
Animalcare (LON:ANCR) - down 3% to 238p (£164m based on the new share count) - Conditional Acquisition - Graham - AMBER
Animalcare is buying an Australian equity business for £62m. The target produces medicines and supplements for horses internationally and the deal is both affordable (with the help of £20m of fresh equity) and strategically sound. Let’s hope it marks a fresh beginning for ANCR, which historically has not done well in M&A.
Treatt (LON:TET) - up 7% to 430p (£261m) - Full Year Results - Graham - AMBER/GREEN
A strong set of numbers from Treatt with record revenues, albeit growth only came in at 4% (not helped by currency headwinds). It’s a cleaner set of results than last year. Inventories are lower. At a PER of 16x, I would say that this old name in flavours and ingredients is probably worth looking into.
ZIGUP (LON:ZIG) - down 8% to 352p (£797m) - Interim Results - Roland - AMBER
A mixed set of results from the van hire and claims management business, with profits down sharply due to weaker used vehicle prices. The outlook for the van rental business is positive and the shares might offer value, but the dividend is not supported by free cash flow and I think leverage is creeping up.
ME International (LON:MEGP) - down 4% to 215p (£815m) - Year-end trading update - Roland - AMBER/GREEN
A solid year-end update, showing pre-tax profit up 10% for the y/e 31 October. Good growth in the laundry business is being supported by a continued stable performance from the cash-generative photobooth division. With no update on the outlook for FY25, I’ve moderated my view to reflect the higher valuation.
Premier Miton (LON:PMI) - up 9% to 60p (£86m) - Full Year Results - Graham - GREEN
Profits have taken a hit in FY 2024 due to lower average AUM and a lower fee margin (attributed to a changing mix of AUM). But looking forward, AUM is on the rise and now stands at £10.9 billion. At this earlier stage of the financial year, FY 2025 is shaping up to be noticeably better. Investors get a remarkable £126 of AUM for every £1 invested in the stock at this market cap.
Short Sections
Costain (LON:COST)
Unchanged at 105p (£282m) - HS2 Systems Contract - Graham - GREEN
Today’s news of a £400m HS2 contract for Costain, to be delivered over 7 years, implies c. £60m of revenues annually, starting next year. Is that material?
The company will be “a sole supplier to deliver tunnel and lineside mechanical and electrical (M&E) systems for HS2”.
Costain generates revenues of £1.3 billion annually, so we are talking about c. 5% of revenues.
The announcement is considered to contain inside information, which implies that this news is material to the fortunes of the company. But the announcement itself contains no information on the margins and profits that might be associated with the contract, or how it might affect existing earnings expectations (if at all). Perhaps well-informed readers might be able to make an estimate? We know that the company has been targeting a 5% (pre-tax) operating margin.
I’ll leave the existing GREEN stance unchanged.
Graham's Section
Animalcare (LON:ANCR)
Down 3% to 238p (£164m based on the new share count) - Conditional Acquisition (and Fundraising) - Graham - AMBER
One of yesterday’s announcements was a £62m acquisition by Animalcare, expected to complete early next month.
The last time we mentioned Animalcare in this report was when it sold a “non-core asset” back in February. So it’s interesting to see that it is now acquiring rather than selling.
Back in February, it sold a pet micro-chipping business. The explanation for the sale was that the company wanted to focus on pharma:
As part of the Group's strategy to focus on pharmaceuticals and to drive growth through launching innovative products, Identicare was separated from the UK pharmaceuticals business within Animalcare Ltd in March 2021, with specialist leadership brought in.
Now it’s buying Randlab, “a leading equine veterinary business”. Randlab has an “extensive range of core equine generic pharmaceuticals and some over-the-counter products”. So the rationale adds up.
Randlab's website says “Australian Made - Australian Owned” - this may need to be updated!
Its revenues in FY24 equate to £12m, with EBITDA of £5.7m. It’s said to have “low capital intensity” so hopefully most of that EBITDA was converted to profits.
Free cash conversion is said to be 71%. Perhaps we could estimate real profitability at c. £4m? This would imply a moderate PER paid of about 15x.
The EBITDA multiple paid is 10.9x which also doesn’t strike me as particularly high or low.
Financing: the most recent interim results showed that ANCR had cash of £33m as of June 2024, with zero borrowings aside from a very small lease liability.
That sets them up well to fund this acquisition. They have also raised £20m in a placing at 232.5p (dilution for existing shareholders is 14%).
CEO comment on the acquisition:
This is a transformational deal that provides an excellent fit with our growth strategy and is complementary to our product portfolio. Over the last 20 years the Randlab team has built a sustainable, profitable and cash generative business with an impressive track record in a market that places great importance on knowledge and expertise of equine health and wellbeing. Not only will this acquisition significantly elevate the Group's offering in a growing equine market, it will also open wider opportunities in a commercially and regulatorily aligned business environment…
Trading update: Animalcare has confirmed that its outlook remains unchanged from the interim results. The latest estimates from Panmure I can find, published in October, are for 2024 revenues of £74m and adj. PBT of £9.1m.
Graham’s view
Animalcare is a company that has threatened to be great for investors for a long time. However, I totally lost interest in it after the strange acquisition of Belgian pharma business Ecuphar back in 2017, in a deal that created enormous dilution and seemed to generate very little value.
The shares have been range-bound over the long-term, since that deal:
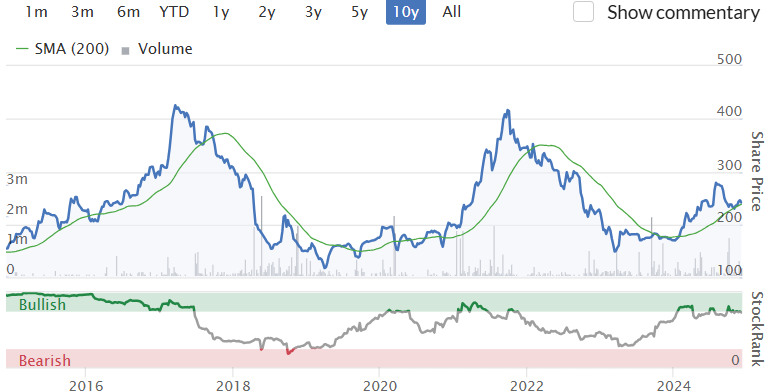
I’m open to the possibility that they’ve cracked the code of how to do M&A successfully now. CEO Jennifer Winter has been in charge since 2018, and so in my mind she is not tainted by that Ecuphar deal.
I’m tempted to upgrade this one to AMBER/GREEN but I have a very strong association in my mind between ANCR and seeing unclean financial results with very little real profitability.
The Randlab acquisition will hopefully be a success but if they have paid fair value for it at 11x EBITDA, does it really change much?
I hope this leopard has changed its spots but I don’t believe it yet.
Treatt (LON:TET)
Up 7% to 430p (£261m) - Full Year Results - Graham - AMBER/GREEN
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, announces today its audited results for the financial year ended 30 September 2024.
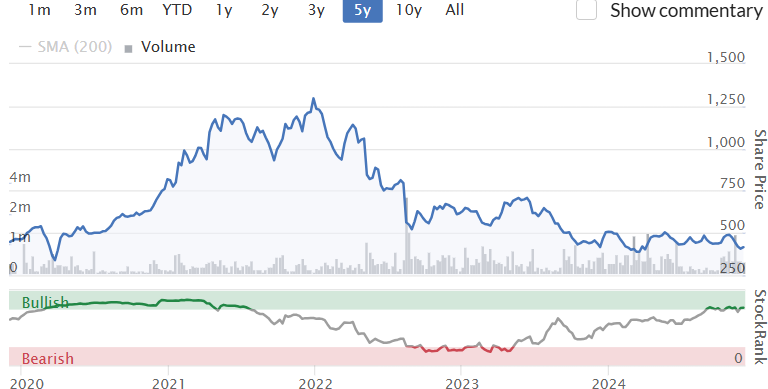
This is a very old company (founded 1886!) and a successful long-term investment for its shareholders, but it hasn’t been a great place to be invested over the past 5 years:
Profitability has been up and down:
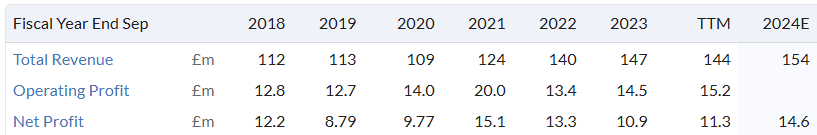
But today’s full-year results show some progress:
Revenue +4% to £153m, marginally lower than anticipated (extreme weather delayed a shipment into 2025).
Adj. PBT +10% to £19m, slightly ahead of Board expectations.
PBT +36% to £18.5m.
I’m pleased to see that the adjustments (“exceptional items”) are minimal this year at only £0.6m (last year: £3.8m). This explains why actual PBT grew by 36%, while adjusted PBT only grew by 10%.
Net debt is immaterial at less than £1m. The balance sheet has net assets of £142m with the biggest entries being PPE (£70m) and inventories (£52m). There has been a helpful £10m+ decrease in the latter: the company explains this reduction but also defends the principle of having a large inventory pile:
This decrease was driven by a reduction in inventory volume, as supply chains normalised, partially offset with higher raw material costs. One factor in the success of the business is our management of risks, such as geographic, political and climatic, to ensure continuity of supply for our customers. Consequently, the overall level of inventory held by the Group is highly significant in cash terms.
Let’s calculate a new inventory turnover ratio to put a metric on TET’s inventory levels.
COGS (cost of goods sold): £109m
Average inventory: £57.1m
2024 inventory turnover = COGS / average inventory = 1.9x.
So they turned over their inventory less than 2x during the year.
From this we can calculate the average time to sell inventory. Intuition says that it should be a little over six months.
Inventory days = 365 / inventory turnover = 191 days.
Objectively I think we can say that this is a very long time to sell inventory (even allowing for the fact that unfinished work in progress is included within this figure). But if management insist that it’s needed to ensure continuity of supply, I’m happy to take their word for it.
Note that the same calculation for 2023 gives inventory days of 233, so at least there has been a downward movement in this metric.
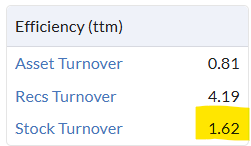
You can find trailing Stock Turnover (same thing as Inventory Turnover) on the StockReport, within the Efficiency section:
Dividend: the full-year dividend increases to 8.4p, for a 2% yield.
Management: a new CEO joined in June from Croda International (LON:CRDA). His first CEO review is in the form of an interview-style “Q&A”. The main takeaway is that he wants to expand beyond US/Western Europe, moving into new geographies in Asia and LatAm. He sees Treatt in the future as “a truly global solutions provider of sustainably led flavour technologies”.
Outlook: no specific info given.
Graham’s view
I’m happy to maintain a mildly positive stance on this one.
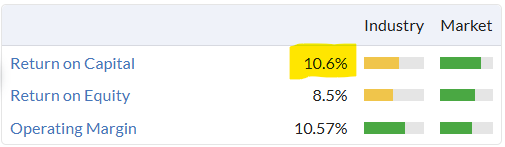
I appreciate the company’s emphasis on ROCE: they calculate an adjusted ROCE of 13.6% in 2024, improved from 12.2%, and their target for this metric remains 15-20%. Getting there will mean being generally disciplined on pricing, costs, working capital and capex.
Unadjusted ROCE is a bit lower than the company’s own calculation, as you’d expect:
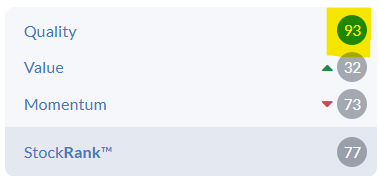
Even so, overall Quality is very high:
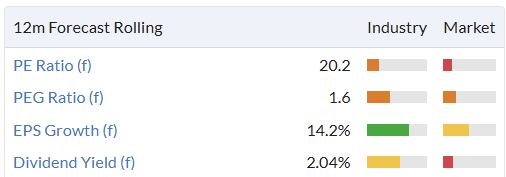
I could consider upgrading this to GREEN but I can hold off on doing this until organic revenue growth picks up to something much better than 4%. The stock is priced at a PER of about 16x which in today’s market is not that cheap. For now I think AMBER/GREEN makes a lot of sense.
Premier Miton (LON:PMI)
Up 9% to 60p (£86m) - Full Year Results - Graham - GREEN
Premier Miton Group plc ('Premier Miton', 'Company' or 'Group'), the AIM quoted fund management group, today announces its final results for the year ended 30 September 2024.
It’s nice to see AUM up by 9% year-on-year at this fund manager, to £10.7 billion.
However, even though year-end AUM was up, average AUM throughout the year was down by 5%.
And it’s average AUM that primarily determines revenues. So PMI’s revenues and gross profits fell:
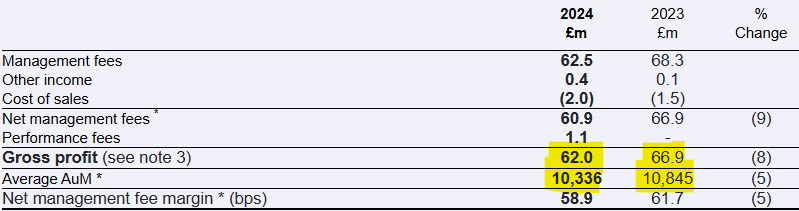
I note that there was also some fee erosion with a decline in the net fee margin of 5% to 59 basis points.
Those are the main factors behind falling profits at PMI in FY Sep 2024 and they don't concern me greatly. I accept that it will have been difficult to maintain average AUM throughout the financial year.
Adj. PBT fell from £15.7m to £12.2m.
Flows
PMI says there were net outflows of only £300m but to arrive at this number they include the positive effect of acquisitions. I don’t think this is right - net outflows should be before the effect of acquisitions and disposals.
The Q4 AuM update showed that net outflows for the year were £760m, with the main withdrawals being from the biggest categories, Equity and Multi-Asset:
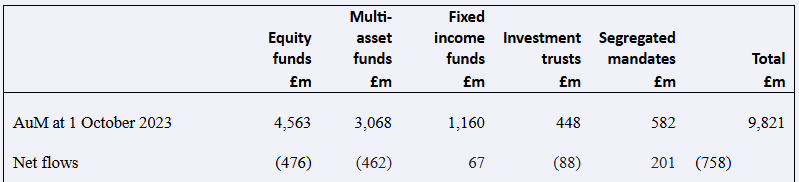
CEO comment is positive on the prospects for Fixed Income and US/global equities. The UK equity market has “remained very much out of favour”.
Looking forward, we see investor demand improving and being focussed on Fixed Income, US & Global equities and Absolute Return strategies post the UK budget and the US election. We also expect demand to remain strong for MPS solutions and low cost, high performance multi-asset strategies where changes to the UK CGT regime will support ongoing interest from advisers.
Cash is worth mentioning as it’s a large chunk of the £86m market cap. The company has tangible balance sheet equity of £30m and this includes a cash balance of £35m. So if you start to do enterprise value calculations, this can look very cheap.
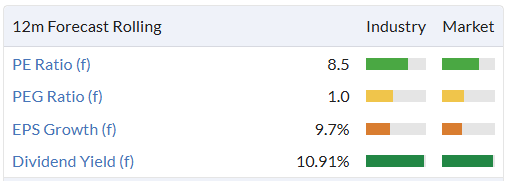
The full-year dividend is unchanged at 60p, for a yield of 10%.
Adjustments
I should spend a moment on these as the company has applied very large adjustments to its earnings.
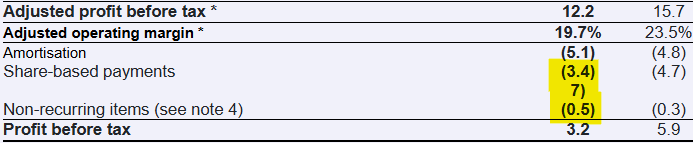
If the company wants to adjust out amortisation I can see the logic behind that, but I do not accept that share-based payments should be adjusted out.
The “non-recurring items” also do not strike me as non-recurring, as they occurred in both 2023 and 2024!
Therefore the way I see it, the real PBT number is £7.1m, allowing only amortisation to be adjusted out. We could apply tax to that for adjusted net income of £5.3m.
Graham’s view
I’m GREEN on most fund managers and PMI is not an exception.
The enterprise value is only about £50m and for that you get a company that has achieved (by my calculations) adj. net income of £5.3m in a very tough year.
AUM has improved to £10.9 billion as of November 2024, and the newly-acquired Tellworth funds are achieving net flows. It seems to me that the current direction of AUM is positive so that FY 2025 should see higher average AUM and the benefits of operational leverage should be seen on next year’s income statement.
In the long-term, familiar themes are at play here: can active UK equity fund managers recover from their current unpopularity? While I don’t expect a return to the easy and high fee generation that was seen before, I do think that active UK equity managers will have a role to play when there is inevitably some weakness in the Magnificent 7 and the global ETFs that robotically follow them. Active investing has to be done by someone and PMI strikes me as capable of offering some interesting and decent-value funds
Roland's Section
ZIGUP (LON:ZIG)
Down 8% to 352p (£797m) - Interim Results - Roland - AMBER
Van hire and claims management group Zigup (formerly Redde Northgate) has issued its half-year results today, revealing a mixed picture of trading over the six months to 31 October 2024.
Our strategy continues to deliver, and we are well placed with our broadening position in the essential market for mobility services. We are pleased to report underlying growth in revenues, and the delivery of PBT in line with expectations, while reflecting normalising disposal profits as previously stated.
Zigup shares have looked decent value for a while, and score highly with the StockRanks.
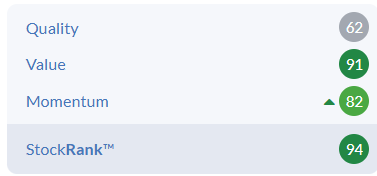
However, the stock has opened lower this morning, which I think may be a reasonable reaction to today’s numbers. Let’s take a look.
Half-year results summary: the first decision investors need to make when reviewing the numbers is whether to use the company’s reported or underlying figures. As we can see in the table I’ve copied in below, there are very substantial differences between the two:
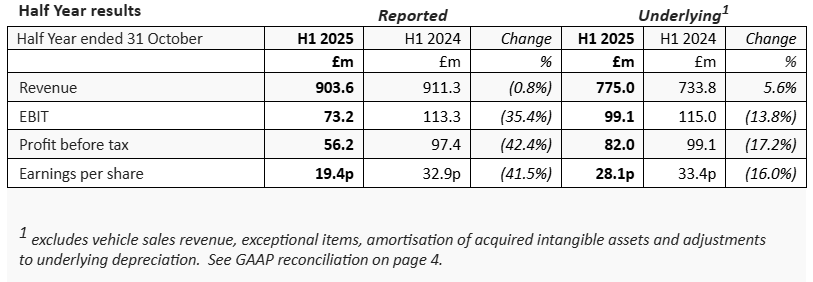
Whichever numbers you prefer, it’s clear that Zigup’s profits fell sharply in H1 when compared to the same period last year.
This business has three main profit centres, and if we split out the results into these segments we can get a better feel for the company’s trading over the last six months. Again, I’ve copied the table below from today’s results to avoid retyping:
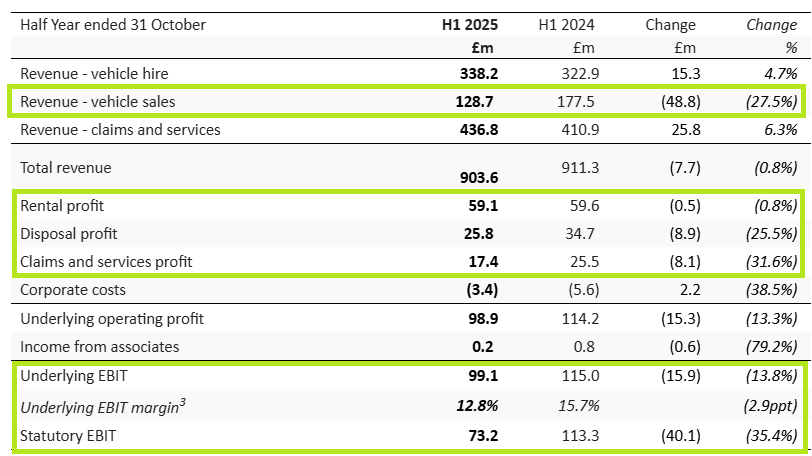
Revenue: vehicle hire and claims services both saw single-digit revenue growth. The company prefers to use an underlying revenue measure that only includes these two business units.
This approach strips out the volatility of revenue from used vehicle sales, which fell by 27.5% to £128.7m during the period. This slump was due to a smaller number of older vehicles being sold, compared to the prior period.
I’m not convinced by the logic of stripping out revenue from used vehicle sales – it’s a core part of the business model, as we can see when we consider the profit breakdown.
Rental Profit: profits were broadly flat at £59.1m. While the Spanish business saw a 7.6% increase in the number of vehicles on hire, this number fell by 4.6% in the UK.
This reflects changes made to the fleet in the latter part of last year, when Zigup defleeted some older vehicles as visibility improved on new vehicle supply.
The outlook for rentals seems reasonably positive. Zigup’s group fleet had risen by 4,300 to 132,500 by the end of the half year, and the company reports “strong demand” including large fleet orders from major customers.
Claims and services profit fell by 31.6% to £17.4m. Profits last year benefited from extended replacement vehicle hire periods caused by supply chain issues (e.g. long delays for replacement car parts).
This situation has now normalised, meaning shorter repair times. In turn, this means demand for replacement vehicles on credit hire has been lower. The company believes hire demand should now be stable through the (busier) winter period.
The claims business was also hit by a cyber attack during the half year, which Zigup estimates had a £4.2m impact on EBIT. This incident also resulted in £2.8m of exceptional costs. It’s probably fair to say these costs were a one-off.
Disposal profits fell by 25.5% as the company sold fewer, older vehicles into a weaker market. We commented on this risk when we looked at Zigup in July.
Used van prices have fallen and the average profit per unit (PPU) fell by 54% to £1,600 (H1 24: £3,500).
Improved new van supply in the UK and Spain has reduced the demand for older vans. The balance will stabilise at some point, but my feeling from today’s commentary is that this process may still be ongoing.
Cash flow & balance sheet: Zigup relies on debt and lease obligations to fund its sizeable fleet. Leverage has crept up a bit in recent years, relative to assets.
Net debt of £782.5m represented 75% of net assets of £1,040.7m at the end of October, up from an equivalent figure of 58% at the end of April 2021.
The company prefers to use an EBITDA-based measure of leverage and says leverage was 1.6x at the end of October, with the target range of 1.0x - 2.0x. For contrast, this ratio was 1.5x at the end of April 2021, so it has remained fairly stable.
Relying on net debt/EBITDA rather than net debt/net assets is arguably more appropriate for a business with a service element to its profits.
However, the vast majority of Zigup’s profit still comes from rentals, if we include the credit hire element of the claims management business and disposal profits. I would probably prefer to monitor debt relative to net assets, so I’m a little wary of the rising leverage here.
On a related note, cash generation remained weak with a free cash outflow of £20.5m, reflecting capex on fleet growth
Net capital expenditure increased by £127.6m to £232.4m (H1 2024: £104.8m) due to a £75.4m increase in net replacement capex and a £52.2m increase in growth capex.
In FY23, company-calculated free cash flow was £30m, compared to reported net profit of £125m.
If fleet size flattens out in the future (or shrinks), cash generation may improve. But at present, I don’t think this business is generating all that much surplus cash, relative to profits.
Dividend: the interim payout has been increased by 6% to 8.8p per share. However, consensus forecasts suggest the full-year payout could be flat at 25.8p per share. That gives a 7.1% yield after this morning’s fall – high, even for this business.
However, this payout would cost around £58m, so seems unlikely to be covered by free cash flow this year. Arguably, the payout is starting to look stretched against a backdrop of rising debt and falling earnings.
Outlook: the outlook for the year ahead sounds positive, with new contracts underpinning demand and increases in UK infrastructure spending also expected to drive future growth.
In Spain, the van hire business continues to enjoy “record demand”.
However, the normalisation in used vehicle residual values is expected to see disposal profits moderate “as expected”.
Overall results are expected to be in line with market expectation. Stockopedia shows earnings forecasts of 53.2p per share for the year ending April 2025, with a sharp fall expected in FY26.
That prices Zigup on a FY25e P/E of less than seven after today’s drop, rising to a P/E of eight in FY26.

Roland’s view
I was never quite convinced by the reasoning behind the merger of claims management group Redde and Northgate van hire. While Northgate is a genuine market leader in its core markets, I don’t see Redde in this way. I’d prefer to invest in Northgate alone, personally.
Today’s results don’t seem too bad to me. But we’re now starting to see the flipside of the bumper profits enjoyed over the last couple of years, when Zigup’s scale and access to vehicles gave it pricing power and boosted disposal profits.
Against this backdrop, I think Zigup’s balance sheet looks slightly less robust than it did. I would also argue that the dividend is starting to look less affordable.
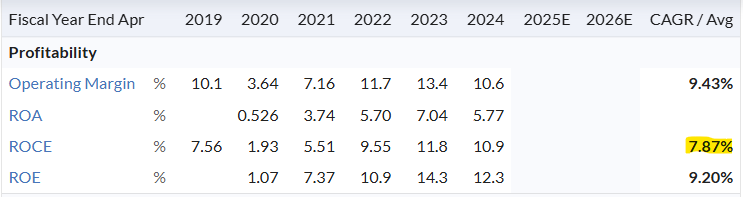
Today’s slump has left the shares trading in line with the tangible net asset value of 364p per share. For a heavily-leveraged business that has generated a five-year average return on capital employed of 8%, I think that could be slightly cheap, but not significantly so.
On balance, I think it makes sense to take a neutral view, so I’m going AMBER.
ME International (LON:MEGP)
Down 4% to 215p (£815m) - Year-end trading update - Roland - AMBER/GREEN
This instant-service equipment specialist has been a multi-bagger over the last three years. The shares are up by more than 70% so far this year:
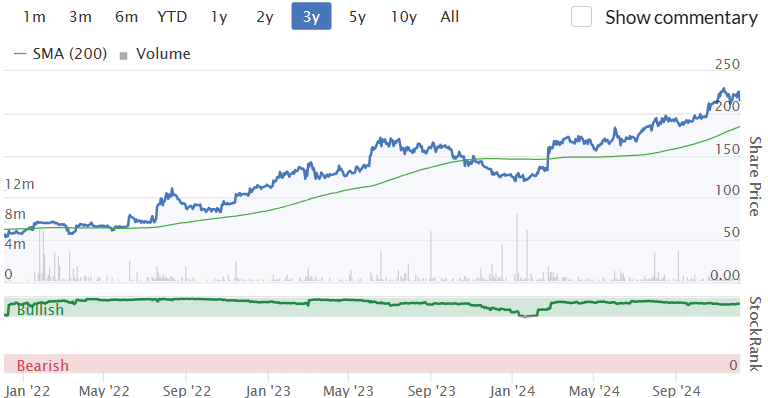
ME Group has now earned Stockopedia’s High Flyer styling, reflecting its strong momentum and more demanding valuation.
Today’s update covers the year to 31 October 2024 and sounds positive to me. But it’s an “in line” statement and the company has not provided any new guidance for FY25. These factors may explain this morning’s mild share price drop:
Building on the positive trading momentum throughout H1 2024, the Group is pleased to report continued growth in H2 2024. As a result, the Board expects to report that FY 2024 will be another year of record profit and financial performance in line with the Board's expectations.
ME Group helpfully provides plenty of detail in today’s update, so we can get an idea of financial performance for the year just ended.
Revenue up 3% to £308m, after £10m of negative currency impact
Adjusted EBITDA up 5% to £112m
Profit before tax up 10% to £73m
Year-end net cash was £38.2m (FY23: £33.9m)
I don’t see too much to worry about here.
The business has achieved an improved pre-tax margin of 23.7% (FY23: 22.5%) and maintained good cash generation – net cash has risen, despite c.£30mm of dividend payments over the last year.
Operationally, ME says that growth was mainly driven by the self-service laundry business, Wash.ME Revolutions.
Net revenue from this division rose by 19% and the company is now operating 1,111 machines in the UK and France. New machines are being installed at a rate of 80-90 per month.
Today’s update doesn’t include the details, but checking back to last year’s final results suggests to me that FY24 revenue from laundry operations may have been c.£97m (FY23: £81.6m). So Wash.ME may now account for around one third of the group, in terms of revenue.
Revenue in the core photobooth operations only rose by 0.4%, but this business generated 58% of revenue last year and is described as “highly cash-generative” today. It remains very important.
The only slight negative in today’s update was that the rollout of new next-generation photobooth machines in France has been “slightly slower than expected” due to some technical issues.
Roland’s view
No new outlook statement was provided in today’s update. However, I don’t see anything to suggest any major changes to current forecasts, which suggest earnings could rise by 8% to 15.4p per share in FY25.
ME Group shares don’t look as cheap as they did…
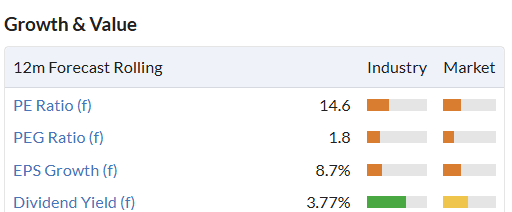
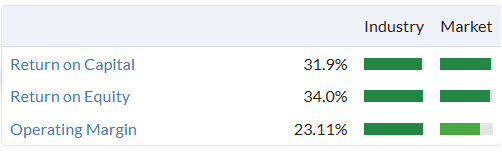
… but I think the valuation is potentially still quite reasonable for a company with a strong balance sheet and excellent quality metrics:
However, ME Group shares have risen by over 20% since we last covered the stock in July, without any corresponding increase in expectations.
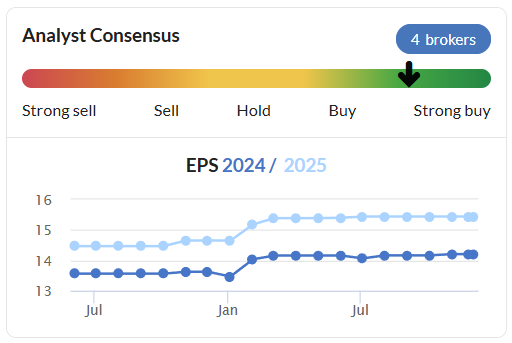
I think it makes sense to moderate our view from GREEN to AMBER/GREEN until the company provides some updated guidance on expectations for the coming year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
ME International (LON:MEGP) Of the 1,111 new Wash.Me installations, I see that 211 were relocations which seems high. I wonder with this relatively new part of the business, whether they installed some machines in the wrong places (unprofitable) and have now learned where best to place them. I can see this growth part of the business gaining more significance and momentum over time.
Some are in some obscere locations, out in tge countryside or in small villages.
Think ME International (LON:MEGP) need to have more in supermarkets. The one near me is a village, nothing in the large supermarkets or town centre. Unless l searched online l would never have known about it. I only did a search because l'm a shareholder and wanted to see what they had in my area.
Camtab I agree about Treatt (LON:TET) FCA should be on the case but is not. Insider trading is rife.
SDCL Energy Efficiency Income Trust (LON:SEIT) - H1 results and directors re-iterate 6.4p dividend which is 12% yield. divi is fully covered 1.1tby CASH profits and directors talk about taking action to rectify the current share price which stands a 40% discount to NAV. NAV was unchanged since the last results (albeit c.6% paid out a divis in 6mths)
disc ihold.
Thankyou for the write up on Treatt today guys. I agree both with your colour coding and remarks. A company I like given its long history and a sector which has proved resilient over time. I think my main gripe is the clear insider trading that has gone on in the week before the announcement.
I'm not sure I know what you mean aboutTreatt (LON:TET), camtab ? The results were in line with the recent trading update and the share price is back where it was at quite recently so who was insider trading and what are they supposed to have known that the rest of us didn't?
Treatt (LON:TET) . The share price went up 7% just before the market closed last night prior to today’s market update, sparkler. Whereupon the market took it another 7% up today. Looks a bit suspicious to me as Camtab says.
I'm not sure Lochinver. At 8:30am this morning the price was briefly back at around 405p and the bounce just echoed what has been happening to other stocks that have been weak recently and then produced in line numbers (e.g. look at Victrex and discoverie yesterday).
Just trying to clarify if the following AIM shares are likely to attract BPR:
(I think Megan has given a view on this topic before)
Finance related: PMI; POLR; TAM; BRK: MERC.
Construction related: SPR; WJG.
Any guidance would be much appreciated.
Hi KBR
Just trying to clarify if the following AIM shares are likely to attract BPR:
You only find out for certain when HMRC decide after your death. There's no definitive list.
However, to quality for BPR on AIM a company’s business must: not be wholly or mainly that of:
— dealing in securities, stocks and shares
— dealing in land or buildings
— making or holding investments (unless that of a marketmaker or discount house)
I think your finance related stocks are all at some risk of not qualifying, you'd need to look at them individually. I hold Polar Capital Holdings (LON:POLR) and have always assumed it didn't qualify (not that I care, I don't hold for BPR).
The construction related ones are hard to call. Watkin Jones (LON:WJG) is OK I think, but with Springfield Properties (LON:SPR) it would depend on whether they're a signficant trader of land. Unfortunately a single "wrong" transaction by these kind of companies can tip them over the BPR edge.
It's probably safer to stick to more straightforward companies that clearly qualify.
timarr
Hello timarr
Thankyou very much for responding with that useful information .
KBR
Zig
Underlying revenue strong, up 5.6% with growth in both Vehicle hire (+4.7%) and Claims and Services (+6.3%); total revenue decreased by 0.8% due to lower vehicle sales revenue
Underlying PBT of £82.0m (H1 2024: £99.1m) mainly due to lower disposal and Claims and Services profits; in addition, Reported PBT of £56.2m (H1 2024: £97.4m) includes non-cash depreciation adjustment of £13.9m cost (H1 2024: £7.6m credit) (see page 14)
Vehicle hire revenue: Spain up over 8% supported by VOH growth of 7.4%, UK&I up 1.7% benefitting from careful pricing actions, while rental VOH down 4.6% reflecting higher defleets in H2 2024
Resilient rental margins for both vehicle rental businesses; Spain at 19.3% (H1 2024: 20.8%) and UK&I at 15.7% (H1 2024: 16.3%) reflecting strong demand and efficiencies supporting high utilisation rates
Disposal profits reduced to £25.8m (H1 2024: £34.7m) as expected, from lower sales volumes totalling 17,200 (H1 2024: 18,800) as well as impact from expected normalising of LCV residual values
ZIGUP (LON:ZIG)
Roland
Net debt of £782.5m represented 75% of net assets of £1,040.7m at the end of October, up from an equivalent figure of 58% at the end of April 2021.The company prefers to use an EBITDA-based measure of leverage and says leverage was 1.6x at the end of October, with the target range of 1.0x - 2.0x. For contrast, this ratio was 1.5x at the end of April 2021, so it has remained fairly stable.I would probably prefer to monitor debt relative to net assets, so I’m a little wary of the rising leverage here.
Why would you (or anyone else) not concentrate on the fleet assets with regard to debt - debt is pretty much to fund the fleet assets only. the fleet assets are perfect liquid assets in that they can be disposed of near to book value without batting an eyelid (if not earning a buck) - so imho if the debt to fleet assets calcs are sound the worry over debt / leverage is imho a somewhat fake worry.
per todays news - net debt is £782 mill and fleet assets** are £1.43 bill - so 55% of fleet assets. To me thats not bad nearly half their fleet is "paid for " practicably speaking which is fine.
note at same time last year net debt was £755 mill and fleet assets £1.23 bill - so 61%
memo figure was 57% at year end
so material improvement over last 12 months
** fleet assets being vehicles for hire so thats perfect liquid resource - if its being hired it will be earning wonga to pay down debt and if itn aint being hired it could be sold.
so deffo improvement last 12 months - exactly the opposite of your suggested "rising leverage" - you are looking at 2021 so its different cross referenced period there - i am looking at the last 12 months. to me the best simple comparison of how they are doing now is with same time last year - albeit its useful to see the long term trend too.
to me in real practical terms leverage has actually gone down looking at my preferred metric - this tallies with net assets per share having increased last 12 months.
To me its clear they have actually done a good job here in last 12 months of having an increased fleet value by £200 mill whilst only inreasing debt a tad
On a related note, cash generation remained weak with a free cash outflow of £20.5m, reflecting capex on fleet growth
If fleet size flattens out in the future (or shrinks), cash generation may improve. But at present, I don’t think this business is generating all that much surplus cash, relative to profits.
Strewth - not sure what you expect here value of fleet assets has risen by £130 mill in 6 months - they arent going to fund that investment without it impacting spare available cashflow in that period. Fleet assets are very liquid resource though.
I was never quite convinced by the reasoning behind the merger of claims management group Redde and Northgate van hire. While Northgate is a genuine market leader in its core markets, I don’t see Redde in this way. I’d prefer to invest in Northgate alone, personally.
I would agree on quality metrics its not the best side of the buisness - but it is so complimentary in nature to the other aspects that imho the sum of the parts that matters - if they have huge fleet of vehicles and locations offering this sideline its complete no brainer to get the most efficiency out of the asset pool. Whether it was good choice for shareholders of northgate back in the day is imho an irrelevance now.
If one does need to have worries here its whether they need to be spending more on vehicles to earn similar profits - in that regard i am 100% happy with everything they are doing in that regard. To me it makes sense that you need to get the new fleet purchases and ready them before you start earning the decent long term paybacks.
Note they had change to depreciation policy in 2023 that benefitted 2023 numbers by £40 odd mill benefited 2024 by £12 mill - and impacted 2025 and 2026 numbers (over £25 mill each year) - this was fully disclosed some time ago and kinda partly explains the headwinds they have vehicles have not been depreciated as much as would have been the case previously on lfl basis. this hits profits at time of sale and depreciation number long term (less depn now = more later)
I wanted to look back at the colour-coded spreadsheet pre 5/11/2024, but I can't find it.
Am I right in thinking Stocko subscribers can no longer access it?
Graham's new spreadsheet is good. Could you add cell links to the comments?
subcribe to pauls substack
Hi Conistons, I'm adding links from the spreadsheet to the StockReport for each stock, with the idea that you can navigate from there to the comments! G
Thanks Graham. And is it correct that Stocko subscribers have lost the access they had to the pre November spreadsheet, ie it belonged to Paul and he's withdrawn it?
Yes. I'm hopeful that we'll have a fix for this with a replacement spreadsheet for pre-November records. G
May I put down a marker for my approval of Graham covering the “toddlers”. There is so very little analysis backed examination of these that a subscription to both Stocko and Paul is my choice and if there is sometimes a good cop/ bad cop pair of views it is all to the good. I hope that the small stuff will continue to get reviewed here and thank you for the efforts so far.
Hi Aislabie, speaking only for myself I'm in favour of continuing to cover the tiddlers! For example I gave NTBR (£8m market cap!) a full section recently. If readers are interested in a tiddler and if I have something to add on it, then I'll want to cover it. G
ZIGUP good detailed write-up, although I think the dividend looks pretty safe - cover looks to be around 2x on adjusted EPS. As Roland point out, if looking at cashflow then it might look a bit stretched this year, since they invested heavily in buying new vehicles as supply normalised - presumably they will not invest so heavily every year and in any case these new vehicles will deliver future cashflow which should in turn support the dividend. The fact they increased dividend by 6% suggest they are fairly confident this can be supported.
Thanks Bouden54, I agree the ZIGUP (LON:ZIG) dividend might remain safe if growth capex generates additional free cash flow.
As things stand, I'm not sure on the timeline for this though. I'd prefer a slightly greater element of caution from management, but perhaps I'm being too cautious!
Roland
Not a UK stock but decent results from Salesforce (NYQ:CRM). Revenue and net income were up 8% and 25% respectively. The company is excited about its AI system, Agentforce. The stock is up 13% in the pre-market. Software as a whole is making a massive comeback right now after a period of underperformance.
Intercede (LON:IGP) Okta (NSQ:OKTA) reported q3 earnings yesterday and beat and upped full year guidance.Revenue increased 14% from $569 million a year ago.
Okta CEO Todd McKinnon said in a statement. “The focused investments we’ve made in our partner ecosystem, the public sector vertical, and large customers are materializing in our business with each of these areas contributing meaningfully to top-line growth.”
Slight beat from Ixico this morning. This is a Paul Hill top pick for '25. Broker Cavendish "IXICO expects to enter a “period of sustained commercial momentum”, & maintains it's TP of 24p. EV £9m - a proper microcap! Cockney Rebel fans might notice a possible bowl formation, or at least a flattening of the 200day MA, which the current SP is above. I'd welcome a comment, I see it's on todays summary table.
another UK business being taken out on the cheap Learning Technologies (LON:LTG)
Supreme (LON:SUP) - Acquisition of Typhoo Tea for £10.2m - new note accessible here: https://www.equitydevelopment....
Supreme PLC has acquired the trade and selected assets of Typhoo Tea out of administration for a total cash consideration of £10.2m, including Typhoo’s stock and trade debtors with a book value of £7.5m.
For the year to 30th September 2024 Typhoo generated revenue of c.£20.0m, and a pre-tax loss of c.£4.6m. Supreme estimates that the acquisition will boost the annualised contribution from non-vape revenue to c.50% of total, and with full integration into Supreme’s cap-ex-light out-sourced manufacturing and distribution model, should contribute a 30% gross margin, which is in line with the Group’s recent Interim 29.6% margin. In August 2023 Typhoo had suffered from what it called “a group of organised trespassers” at its Merseyside factory which caused extensive damage and loss of stock resulting in £24.1m of exceptional costs. Typhoo entered administration on 28th November; Supreme has acted quickly to assess and act upon the opportunity created for its operations.
Supreme recently reported H1 25 results (ED report, ‘H1 25: margin improvement and FY25 outlook raised’) with revenue +8%YoY and a 22%YoY increase in (adj.) EBITDA reflecting cost control and gross margin improvement. As further details of the acquisition of Typhoo Tea emerge we will update our earnings outlook accordingly.
Supreme has once again flexed its acquisitive muscles, snapping up the trade and selected assets of Typhoo Tea for a modest £10.2 million. This latest deal is more than a nostalgic nod to British heritage; it’s a sharp, strategic play that furthers Supreme’s diversification agenda while unlocking significant growth potential across the group’s burgeoning FMCG portfolio.
While the Company’s share price may be off its all-time high of 205p, it’s still a strong brew at 176p, well above our 116p feature price. For those concerned that Supreme might be choking on vaping market fears, the Company’s latest manoeuvres suggest the worst is behind it, and its diversification strategy is picking up steam. https://smallcompanychampion.s...
Good momentum for Ferrexpo (LON:FXPO) … passes 3 long screens stocko ranking 91 … if this continues potential reentry to the ftse 250
Ferrexpo (LON:FXPO) gets promoted tonight on review actually in 2 weeks monday along with Diversified Energy (LON:DEC)
Premier Miton (LON:PMI) results looked interesting. Adj EPS of 6.3p and dividend of 6p (10%) with strong net cash. If you believe in a much better small cap environment over next couple of years then this could be an interesting play. Asset managers tend to trade 13-15* during the cycle and Premier Miton (LON:PMI) are obviously leveraged to small cap performance. So wouldn’t take much to nudge eps of this year up towards 8p and with some re-rating interest maybe 100-120p with a 6-7% divi. Might need to look at this more closely. Anyway got any thoughts on them?
Asset managers used to trade on 13-15* but with the exception of the most successful ones I very much doubt they will again - the sector faces too many headwinds (the rise of passives, huge pressure on fees, lack of interest from retail investors with no sign of government support, etc)
I don’t agree Bouden54. I think the headwinds are precisely why they have re-rated down but inevitably that cycle will change. ETFs have done well because all you have had to do well in the last few years is stick money in a few ETFs and you’ve had more than acceptable returns. If you look at the likes of Goldman research they expect these returns at an ETF level to diminish significantly over the next decade. That likely means that alpha will come back into fashion and the AMs will benefit at that point. When that happens some of these will be multi-baggers - the question of course is timing, which could be some way off. I take the approach that as long as I am buying at a good price, where any AuM decrease is slowing/stopped (like Premier Miton (LON:PMI) ) then with a sustainable divi of 10% I can make a strong compound annual return with potential for a big re-rating at some point in the next few years. It’s a longer term strategy
You might be right, but I've been reading about the demise of tracker funds for well over a decade and no sign of it yet. Even if active investing does make a comeback, fees will remain under pressure as fund selectors now put so much emphasis on costs. In terms of the UK market itself, the government appears to have zero interest in revitalising interest - I was hopeful they might do something like axe stamp duty or incentivise pension funds to invest more in the UK, but clearly nothing on the cards. In this environment I can't see flows picking up in any meaningful way. In terms of the dividend, this looks safe for now but will surely be at risk if they're unable to increase AUM.
ZIGUP (LON:ZIG) slightly surprised at the 5% fall in SP this morning. Results are basically in line and as expected so expect 55p eps normalised earnings for full year and looks like 28p dividend (about 7%).
Slight blip was a slower claims market during the summer but seems that’s normalised now. Lower second hand sales were anticipated - they took advantage of a strong market previously.
NTAV is 365p which is the same as the share price. Basically the entire market cap is covered by its realisable asset value but the business trades on a 6* PER
Never quite understood why - this business has been performing through enough economic macro conditions to support a higher PER than 6! It’s never going to be a high multiple but 10-12 is more realistic. Not sure when that tide will turn. 7% divi and a few % capital growth is enough to hit a decent annualised return though so I will stick with it.
I agree that ZIGUP (LON:ZIG) is a good business but revenue, profit before tax and earnings per share all fell in the first half. They say that full year results should be in line, but a 5% fall seems reasonable to me.
Why John2?
It was all well flagged and as expected. Nothing changed, so why should the stock be down 7%? The whole idea of expectations is that investors know what to expect and therefore the share shouldn’t really move on an in-line as that should all be priced in.
You have to look at the overall value of the business not the fact that revenues/earnings fell in a particular half when the market already knew that. I can only think investors were expecting an upgrade and had pushed the price up on anticipation and that has unwound.
But again you can now technically buy the business for less than the tangible value of its assets which just looks the wrong price to me for a business capable of a strong return on that capital employed.
I agree that it's a harsh reaction for ZIGUP (LON:ZIG) but that's the reality of the current market. I was well pissed off when Warpaint London (LON:W7L) fell 10% after reporting a record first half, even if it had a far higher PE.
I am watching ZIGUP today with the intention of buying when I think it has bottomed out.
Yes - I suspect what’s happening in a lot of these stocks is that they are being driven by retail and there is a lot of illiquidity. People are buying in lead up to results and selling on results. Whilst that has always happened to a degree and is a known phenomena it seems to be more marked due to the lack of relative liquidity. It seems where funds used to mop up cheap stock that isn’t happening.
Warpaint London (LON:W7L) is a super business that I missed and just don’t want to pay a high PER for but if the market presents some relative value at some point I would like to buy. ZIGUP (LON:ZIG) I own but is a misunderstood business. I see Roland views it as a heavily leveraged business and therefore one that shouldn’t trade at more than 8 or 9* earnings but I think he misunderstands the internal dynamics and risk management of vehicle leasing and is looking at the debt and assets in the wrong way (I know from practical experience in leasing). But if investors take the same misconception into their analysis then it doesn’t matter whether I am right or wrong the share just won’t re-rate. So either it will get bought and I will get lucky, or I have to base my investment case on different metrics.
David
ZIGUP (LON:ZIG) - I hold.
"The whole idea of expectations is that investors know what to expect and
therefore the share shouldn’t really move on an in-line as that should
all be priced in."
That assumes the market is efficient, but small cap investors rely on finding market inefficiencies in small caps.
I agree with the rest of your post, especially your point that market cap is below tangible net assets - another inefficiency?
Richard
ZIGUP the fall in revenue and earnings was mainly due to the normalisation in disposal profits and the market was fully aware of this - underlying earnings looks fine, especially for something trading below TNAV and a 6* PER
Couldn't agree more. I bought ZIGUP (LON:ZIG) during COVID and have seen a nice return of nearly 3x since then but its really gone nowhere in the last 18 months despite continuing to operate very well. I'll sit on the dividends for now and wait either for the market to bring it to 10-12 PE it deserves (agree with you on this) or at some point it'd be a very nice fit for a Private Equity company.
ME International (LON:MEGP) solid update. I hold, but as commented Mr Market will no doubt mark the shares down in its now usual asinine way.
Treatt (LON:TET) looks interesting, but again as mentioned the outlook statement is somewhat ‘fluffy’.
I hold both as well and both are slightly down on solid, albeit slightly boring results. We are in a punishing market and UK small caps just keep getting cheaper and cheaper despite progress in the core business.
Jonno, I agree MEGP is a great cash generating business. Achieving in-line is a fantastic achievement. 80 + Wash.Me installed a month. Currently 1111. So nearly doubling next year. (on that 30% revenue stream) Not sure this is reflected in the small drop. Very little NI impact, terrible food vending idea (Pizzas) - i tried- cleverly let go. More Airbnb, hotter weather. more laundry. Boom in travel. passport photos. I hold.
Despite registering their 1st net inflows for 42 months, it appears investor sentiment towards UK equity funds still remains weak.
That said, if one ignores the technicals, & instead purely focuses on the fundamentals. Then I'm more bullish now on smallcaps than I’ve been for the past 4 years - as evidenced by super attractive smallcap valuations (0.7x PEG), accelerating top line growth and a resurgence of M&A.
Looks like an important tipping point to me ..... agree UK small caps looking good for 2025. The bad news is already accounted for.
If you read the commentary they say it's likely to be a reversal of the very strong outflows in October ahead of the budget. They seem to think it's a one-off.
Oh. Sad face emoji. Let's hope they are wrong. Santa rally coming...
SP500 up 32% in last year, FTSE100 up 11%.
The gap between US and UK is large and getting larger. Personally i think the US is heading for a crash, so the UK market represents a safer place to invest.
If the us crashes then so will we. Our bear markets tend to be longer and deeper tgan the US markets. We have much smaller companies and generally more debt. Safer place, not sure about that. Cash and gold would be safer.
Distinct lack of growth in the UK, look at the updates today, only around 5%, yet some shares gone up considerably this year.
From across the pond (and since no individual US stock is mentioned) I believe you should ask Santa -:) to bring you a NON CRASH US MARKET because the impact to the UK market will be bigger than any other time.
This time and if it happens (of course it will at some point) the withdrawals from the UK market to invest in the then US cheap and liquid growing market will create a shockwave.
Innovation in the UK market is basically non existent. In the US they send people and rockets to the moon; the topic here today on this forum is about van hires and tea bags!
US market has outperformed for the last 2 decades and will continue to do so for many more decades. This will accelerate at a fastest pace after a big correction. I think Stockopedia’s management have realised this as there is more coverage about US stocks.
All the best
Tad harsh on UK investment opportunities; we now have Supreme (LON:SUP) tea bags to go into BnBs Portmeirion (LON:PMP) teapots and Strix (LON:KETL) kettles to boil up Severn Trent (LON:SVT) polluted water.
Who needs to fly to the moon Yiannos? ;-)
From across the pond (and since no individual US stock is mentioned) I believe you should ask Santa -:) to bring you a NON CRASH US MARKET because the impact to the UK market will be bigger than any other time.
Very interesting thought Yiannos. It remains to be seen whether the response to a global crash would be a flight to the US at a time when all commentators will be saying that the US pricing has simply become rational, ie not cheap, while UK stocks will then look the bargain of the century. We’re going to find out some time in the future for sure!
In the meantime, I’m finding UK quality is holding up better than the indices - BnB UK Fund 13% YTD vs 11% for FTSE 350 with smaller drawdowns in corrections, meeting its objective of attractive growth with reduced risk albeit at the cost of enduring higher multiples than some (many?) investors can stomach. This is about half the return of the much larger BnB US fund YTD but the point being that it is exposed in the UK to a whole different range of industries and economic conditions (not all of them good) that may have held back performance in recent years but improves the diversification of the overall fund.
There is be a real risk in the whole world lurching into US markets - a risk that I believe we are seeing played out right now.
Hi yiannos
Like others I really enjoy your well informed posts and sometimes we agreed about specific shares too, including Gulf Keystone Petroleum (LON:GKP) where the share looks sure to do well again when (and it surely is when and not if) the closed pipeline is eventually reopened.
But one you disagreed about was when I highlighted Ferrexpo (LON:FXPO) on the Small Company thread a few weeks ago around 45p to point out that the share price was very likely to price in the end of the Ukraine war ahead of the news of it happening.
Ferrexpo (LON:FXPO) has now soared to 110p including another 10% increase today alone and has now imo priced in the expectation of the end of the War. There could be a lot more upside once the big dividends start flowing again, but that will only be when the war is over. At present all that rapid upside is based on the assumption it will be.
Downside is big if the end of war optimism is misplaced. So it’s much riskier buying now than it was then.
Hi Ken,
Haven’t got a clue what your post is all about other than boasting about a company situated in the middle of a conflict against the biggest enemy of the UK!
I don’t invest in war zones and the reason is simple-I do not know the future cash flows-it’s just mad gambling. Sometimes people beat the bank. The other day Ed was talking in one of his articles about a similar situation in Ukraine and the company lost more than half of its value the following week!
But since it’s the boasting national day, you can go on the US stocks thread and you can find some 4X baggers there. But I am sure you have already done that!
Enjoy the rest of the day.
All the best
Costain (LON:COST) with what seems a big contract win on HS2. Is it significant? SP has been treading water for weeks/months. Will this be the catalyst to propel it up to 134p? Opinions welcome.
There's news today of a £400m HS2 contract win for Costain (LON:COST) and a reuters note that Legal & General (LON:LGEN) anticipate a capital return to shareholders but don't know where they got this ?
Graham - FWIW - Is it really worth mentioning (above) toddler companies of less than £25m MktCap - leave them to Paul!
...and a reuters note that Legal & General (LON:LGEN) anticipate a capital return to shareholders but don't know where they got this ?
https://newsfile.refinitiv.com...
"We anticipate returning to shareholders a proportion of the capital not deployed on strain this year. This will form part of the Board's wider consideration of buyback capacity, which will be set out at the FY24 results in March 2025 and would be incremental to the capital return intentions indicated at the Capital Markets Event in June."
timarr
On the Beach bookings hit fresh record
Without committing to a specific timeframe, On the Beach outlined a set of ambitious medium-term targets, including converting 40 per cent of revenue into cash profits of at least £100mn and an adjusted pre-tax profit of at least £85mn.
Chief executive officer Shaun Morton told Investors’ Chronicle these targets are underpinned by doubling the company’s addressable market. This plan is backed by the addition of city break offerings and expansion into Ireland now that the lawsuit with Ryanair has been put aside.
Analysts at Deutsche Numis say these targets imply a 20 per cent compound annual growth rate (CAGR). Shares rallied after the results and are up 70 per cent over the past year, but a valuation of 10.6 times forward earnings fails to reflect the level of headroom for future growth. We stick to buy.
https://www.investorschronicle...
Quite surprising they are doing so well. I dont think their prices are competitive and it is frustrating when you have to start adding bags etc on to the booking.
Pretty standard though in the segment.
When I was still a shareholder in the summer, before I had to sell to fund a transfer, I used them for our holiday. Customer service was fantastic when airlines messed around, and our price for the room type were very competitive when shopping around -not too mention overhearing other guests.
The actual place was also very commendable. So all in all I'm positive on their offering.
If they start to build operational momentum I might reconsider.
Decent results out of Treatt (LON:TET) today. The balance sheet looks good, revenue growth pedestrian but has the potential to speed up, profit growth fine, cash fine. At this stage looks more solid than exciting to me. Got into a bubble but has become more reasonably priced.
The current year will benefit from a pension contribution saving of 450,000 as the scheme is fully funded, which helps
The outlook statement is unnecessarily vague for me, I'm not sure how that will be taken but I guess broker notes will fill in the gap
Don't forget that revenue growth in the second half was 13%, so perhaps accelerating nicely now.
The comment below - reduced full year revenues by circa £2million, so revenue growth unstated in second half - therefore better revenue growth in H2.
Full year revenue was marginally lower than anticipated (by 1.4%) as extreme weather in the US delayed a large shipment at year-end, shifting associated revenue into 2025.
Long term holder
Morning Graham. Many thanks for your excellent write up on Animalcare (LON:ANCR) acquisition and status. A fair balanced view.
Cheers Andy, nice of you to say. Perhaps my view is outdated now, I guess we'll see! G
I certainly hope so Graham, but it looks like the market reacted remembering that awful reverse takeover. I'm hopeful that Jenny has done a much better job on due diligence and good investment of Capital, she has certainly mentioned how diligent and cautious they have been on looking at M&A candidates while presenting on the Investor calls.
Animalcare (LON:ANCR) Perhaps my view is outdated now, I guess we'll see!
Indeed we will. I would note that the acquisition increases the company’s existing presence in the fastest-growing segment of animal medicine, equine care. I hope the current CEO, untainted by the name’s past errors in M&A, would nevertheless have paid good attention to the previous missteps and guard well her burgeoning reputation.
Thank you for covering. I’m a solid fan of your amber ratings, Graham. They tend to denote companies in my wheelhouse - good quality but expensive - although your rationale on this occasion is coloured more by the past than the price. I would argue it is a different company today.
Totally agree. Mr Market also remains to be convinced and so the upside should be significant when they are.
Animalcare (LON:ANCR)
Totally agree. Mr Market also remains to be convinced and so the upside should be significant when they are
To be fair, I find the current price quite rational. It’s expensive on a PER basis relative to growthy pharma but quite reasonable on a FCF yield. Clearly there’s a justified takeover premium to be accounted for, although potential buyers are few (EQT buyers of Dechra? Zoetis?). It may take some time but I’d be very happy with the projected 10%pa earnings growth with a right-sized, well-covered and growing dividend to boot.
Solid results at ME International (LON:MEGP) . Shares will probably drop 10%!!!
Same with Treatt Treatt (LON:TET)
“In line”, for shares that have risen, often gets hit hard by this market. I’m waiting to see what happens today. ME International (LON:MEGP) excellent company.
yep. im looking to buy as the price drops. long term view and have a number of positions in it much lower down. solid company and im anticipating solid growth into 2025
Similar view to myself and nearly 79% of the institutional investors waiting to keep the share price rising.
Yep and down it goes. So predictable