How all-cap diversification can pay off in a market crash

One of the trends in the aftermath of August’s short, sharp market dip is how quickly the UK’s small-cap indices bounced back. The late summer chaos left the FTSE 100 well down on where it started the year. By contrast, the FTSE SmallCap XIT is up by 10.5% in 2015 - and has clawed back much of the ground lost during the mayhem.
A lesson from this strong recovery by the small-caps is that all-cap diversification is a useful option when managing risk in a portfolio. In our previous coverage of portfolio management we’ve explored several ways of diversifying. That’s ranged from figuring out how many stocks it takes to meaningfully reduce risk to diversifying between factors like quality, value, momentum and low volatility. Arguably, diversifying by capitalisation is baked into all of those approaches. But we’ve never explicitly looked at the advantage of mixing large-caps with small-caps.
Different risk profiles
The case for including stocks of varying size has been made quite clear in recent months. Macro issues - ranging from uncertainty about growth in China to low oil prices - have dragged down the performance of blue chip shares. But smaller stocks have been much more resilient - a trend that Paul Scott picked up on here.
It’s an accepted truth that smaller companies often carry more risk for investors, partly because they’re less liquid and more susceptible to unforeseen problems. But on the upside, they are less affected by macro factors and more reliant on a growing domestic economy.
Jason Tannen, a portfolio manager at BNP Paribas, recently wrote that small caps should profit the most from an improving economic outlook because they have higher operating leverage to a domestic recovery than large caps, higher domestic revenue exposure and a higher exposure to cyclical sectors such as consumer discretionary. For those reasons, it’s no surprise that investors have been sanguine after the recent volatility - and quick to buy back in to smaller stocks.
But while small-caps have rebounded strongly from the recent market wobble, they aren’t always so strong. Back in 2008, when market values fell sharply, smaller stocks were panned. The FTSE SmallCap index slumped by 44%, while the FTSE 100 did rather better, falling by 28%.
These differing fortunes of large and small caps are usefully revealed in the following table (borrowed from Ben Carlson). Despite being a US example, it clearly shows that over time the market rewards large and small caps during different periods. As a result, it makes sense to diversify between them to smooth out returns.
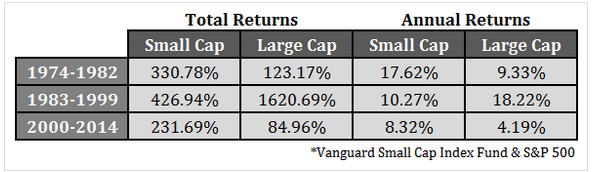
This evidence supports a point made by US growth investor Louis Navellier, that investors should take a common sense approach to diversifying between risk categories. In The Little Book That Makes You Rich, he suggests trying to overcome market risk by finding stocks that zig while others zag.
He explains: “I want to have some stocks in my portfolio that zig in response to market and economic events, while others zag on the same news.”
Navellier’s point is that investors should pick stocks with different risk profiles in order to achieve the lowest possible overall risk in a portfolio.
Small quality stocks outperform
The risks attached to small-caps are likely to deter some investors from buying them. But it’s worth remembering that evidence shows that smaller stocks tend to outperform larger companies over time - as the chart below suggests.
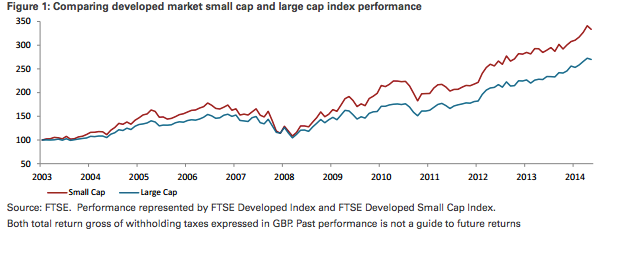
The observation that ‘small beats big’ in the stock market has been documented in academic literature since the early 1980s. Despite question marks over its existence, a paper by Cliff Asness and a team of researchers at US fund management firm AQR Capital, insisted that small-cap-effect still exists. Among their finding was that, with small companies, it's actually the lower volatility, higher quality stocks which produce the best returns. And once you control for quality, what you find is that small quality stocks tend to outperform large quality stocks.
More diversification ideas
It’s been interesting to watch the rebound by small-caps after the market dip of late August. Contrary to what most investors expect, these shares have held up pretty well. While smaller shares don’t always fare so well during a market panic, it seems that investors quickly decided that the underlying fundamentals driving them hadn’t changed. It’s a useful reminder that diversification means more than simply adding extra shares to a portfolio. Mixing up the large and the small caps could be another way of smoothing out the risks and returns.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Ben,
There is an excellent summary of the Arness paper you mention in FT Alphaville which reports that if you screen out "low" quality small companies that are on the verge of death or are a scam, then investors in smaller "high" quality companies consistently do better than investors in similar quality rated larger companies and this effect holds up across industries, time periods, and countries.
Moreover they conclude that the increased price premium paid for "high" Quality companies has historically been too low, resulting in small high quality company outperformance over a 50+ year period. It would be interesting to know if "Quality" small caps have recovered from the summer slump any better than the broader SmallCap XIT, short term?
I have adopted a high quality small cap market portfolio which is a 90+ QVM screen with a 80+ Q bias, since May this year but it's too early to tell how successful it will be? Ian
FT Link http://ftalphaville.ft.com/2015/02/11/2118836/size-matters-if-you-control-your-junk/?