Kainos: Anatomy of a UK Quality Compounder

We’ve recently been pursuing a quality thread in our editorial. In July, Ed shared his research showing that companies with improving quality often delivered more sustainable share price jumps than those without.
Mark followed this with a piece that explored the idea it could be time to take a fresh look at quality strategies following several years of underperformance.
As promised, this Stock Pitch continues the quality theme with a look at one of the new stocks I’ve selected from my quality compounders screen for the year ahead.
I’m particularly interested in this stock because it ties together the quality theme with the software sector. This is an area I think offers some interesting opportunities following the SaaSpocalypse sell-off earlier this year.
The company I’ve chosen is IT services group Kainos (LON:KNOS). Shares in this Belfast-based FTSE 250 group have soared following a recent upgrade, but the stock remains well below historic highs despite an improving outlook.
Share price at the time of publication: 1,179p
Market cap: £1.4bn
Disclosure: at the time of publication, Roland had no position in Kainos.
The Pitch
Kainos was founded in 1986 as a joint venture between ICL and Qubis, the commercialisation arm of Queen's University Belfast. The business floated on the London Stock Exchange in July 2015, since when annual revenue has grown at an impressive 19% annualised. Revenue is expected to top £500m for the first time this year.
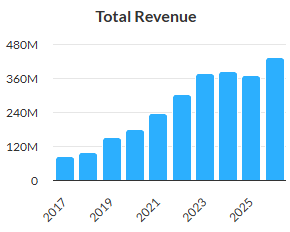
The group operates through three divisions, each of which enjoys attractive market share and scale:
Digital Services (FY26 revenue: £242m): Kainos designs, builds and operates digital services for public sector, healthcare and enterprise customers. These include a range of AI and cloud-based services. The UK is the largest market, with major clients including the NHS and several large government departments. International expansion is a key focus.
Workday Services (FY26 revenue: £108m): Workday (NSQ:WDAY) is a software platform providing a range of HR, finance and planning products to corporate customers. Kainos is one of Workday’s leading accredited partners, serving clients in Europe and North America.
Workday Products (FY26 revenue: £82m): Kainos develops software products that plug into the Workday ecosystem to provide additional functionality. The company’s five products are used by c.700 customers globally. This is the fastest-growing part of the business, with 27% annualised revenue growth since 2022.
The company’s client base includes many well-known names:
Source: Kainos FY26 presentation
Kainos’s capital-light business model, scale and expertise have supported consistently excellent quality metrics in recent years. When combined with a recent momentum jump, this has left the stock with a strong QM High Flyer profile.
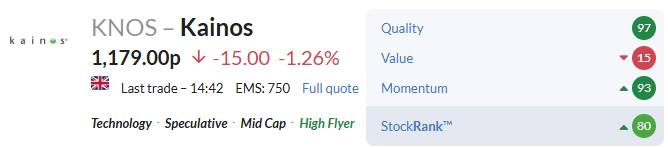
The only potential weakness from a quantitative viewpoint is the low ValueRank. As I’ll explain, I think this is a situation where it could be safe to ignore this metrics. I don’t think Kainos is as expensive as it might seem.
The Big Picture
Taking a broad view, I think there are some good reasons to believe Kainos could continue to become a larger and more profitable business.
“Markets driven by clear structural trends”: I expect expenditure on IT and digital services by public sector bodies and large enterprises to continue rising for the foreseeable future. The company’s recent results support this view. Bookings (contracted sales) rose by 32% to £505.3m last year.
Predictable, repeating cash flow: the SaaS nature of many modern IT services can provide high-margin predictable cash flows. Kainos’s annualised recurring revenue rose by 23% to £89m last year and the company is targeting £200m of ARR over the medium term. More broadly, 86% of revenue came from existing customers last year.
Super quality metrics: the capital-light business model supports high returns on equity and strong cash flows. Kainos has a five-year average return on equity of 33%.
Fantastic cash generation: recent years have seen Kainos converting all of its profit into free cash flow. This can be used to support shareholder returns and reinvested for growth. The dividend has risen by 370% since 2016.
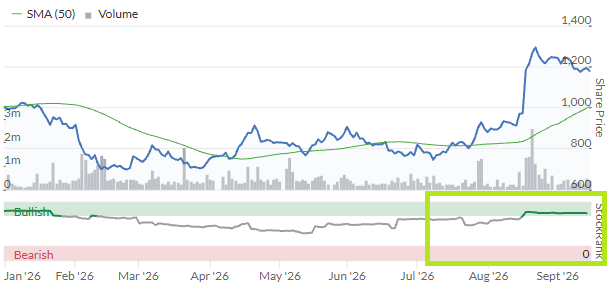
StockRank Jumper: Ed recently did a deep dive into the potential opportunities highlighted by a sudden jump in StockRank. Kainos is a recent jumper, albeit the StockRank hasn’t yet made it above 90:
Going Deeper
Drilling a little further into Kaino’s business and ownership suggests to me that this business has some additional qualities likely to support sustainable long-term growth.
Long-term insider ownership: the shareholder register is unusual for a FTSE 250 company. CEO Brendan Mooney is the top shareholder (9.2%), but what’s even more remarkable is some of the other names on the list. They include the CFO (3.4%) and two former senior staff with 3%+ holdings. The company’s original backer, Qubis, also retains an 8.7% stake and noted long-term tech investor Baillie Gifford is also a major holder. To me, all of this adds up to suggest a long-term culture of value creation and sustainable growth.
A proven compounder: operating profit has risen by an average of 17% annualised since 2016/17. Recent post-pandemic weakness has given the impression of a slowdown. I think the reality is that the Covid period was an exceptional peak, following which growth is now returning to its previous trend.
Takeover target? I hope that Kainos will stay listed. But the reality is that the UK market is hot for takeovers at the moment. We’ve recently seen B2B communications provider Gamma Communications taken out with an offer, together with a plethora of smaller companies. Kainos has scale and a desirable footprint in public sector and enterprise IT. I wouldn’t be surprised to see bid interest, especially if the valuation dips for any reason.
AI value creator? Software stocks were sold off earlier this year on fears that vibe-coded alternatives would displace expensive paid software. The market is now reversing out of this position as it becomes clear that the most desirable businesses may be those which control systems of record and are able to create value for clients by implementing AI solutions. I reckon Kainos could fit that description nicely.
What The Brokers Say
Analysts covering Kainos have become more optimistic about the company’s earnings prospects this year, in particular since the upgrade prompted by August’s trading update:
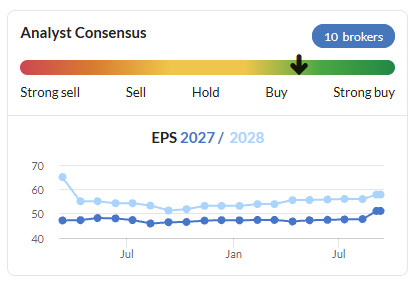
Positive earnings momentum is an important requirement for a re-rating. Kainos’s strength in this area is also reflected in the stocks’ high MomentumRank.
The main risk here is that the good news is already priced in. Some analysts appear to think so: Kainos’s share price is only slightly below brokers’ average target price for the stock:
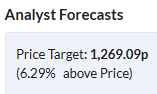
However, a more detailed look at specific recent broker notes suggest that valuation estimates could be climbing:
Canaccord Genuity: “Nudging our target price up to 1,315p” – in a note from 19 August 2026, the broker suggests that the current valuation is “reasonable” and believes there could be “scope for more upgrades over the next 12-18 months”.
The Bear Case
There’s plenty that could go wrong here, of course. Here are some of the main risks I’d want to keep an eye on:
Hidden customer concentration? Kainos reports more than 1,200 active customers. However, my impression is that customer value is less diversified than this, with a fairly heavy weighting to the UK public sector in particular. Although I think IT spending looks fairly assured for the near future, priorities could change under future governments.
This is a service business: while the company does have some intellectual property (e.g. Workday Products), Kainos is essentially a services business where the main assets walk out of the door every night. A future change of leadership could be a concern, although CEO Brendan Mooney is only 59 and could remain at the helm for some time yet.
AI risk? Future iterations of AI may yet create new threats to the software business model. For example, if agentic interaction with systems starts to replace human activity on a large scale, I think that both the economics of software and the value added by system providers could evolve in ways that aren’t yet understood.
Where’s the value? While I see long-term value here, my valuation estimates suggest that current forecasts are probably already fully priced in. In my view, it’s possible that Kainos will need further earnings upgrades to justify short-term share price outperformance. It’s this concern that lies behind our current AMBER/GREEN view in the DSMR.
The Bottom Line
Kainos is a highly-profitable IT services and software provider with a geographically-diversified business across the public, private and healthcare sectors.
I believe it’s a well-run business with a proven culture of long-term management and compound growth.
Although the current valuation looks reasonably full based on existing forecasts, I think structural trends in digital services and software spending could support earnings upgrades and higher margins over time.
Broker sentiment is broadly positive, with at least one broker seeing opportunities for further upgrades within the current forecasts.
This stock has seven-bagged since its 2015 IPO. In my view, it’s a proven example of a quality business that probably does deserve a premium valuation. I’m considering this stock as a possible long-term buy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
After reading this I was surprised to see that the wife of CFO Richard McCann sold nearly £6m worth BEFORE the recent surge in the shares. She could have got another £3m if she'd waited until now. From a quick search, it seems to be explained by his divorce. Maybe Richard is actually chortling about that one..
If you are looking for more subjects for articles: BVS, dual listed on ASX and LSE, CAF and RKN on ASX, are similar to Kainos, in terms of compounding and cash generation. They trade at relatively low valuations, are growing eps, and some also pay dividends. Look closer and see that they are all increasing return on assets using the same technology: AI.
Good article. Who is Ed please?
Hi John, my reference was to the ever helpful CEO of Stockopedia, Ed Croft, who has hosted a number of training sessions to assist me in my progress from fund reliant to DIY private investor.
Thank you Roland for a well researched article. I will continue to hold.
I've taken a holding in Knos myself after it was brought to my attention by Ed's stock jumper article and although the share price has taken some time to cause me any excitement, the holdings by long established investment companies, together with your own summary today, leave me perfectly confident that the stock, momentum and quality ratings will continue to climb, lifting the share price well in due course.