SIF Folio: Lookers profit warning + is this the right time to buy H&T?

When I added car dealership group Lookers to the SIF fund in March, I knew that it carried a fair amount of cyclical risk. What I didn’t expect was that the firm would also become the subject of a FCA investigation into its regulated activities (selling financial products).
When news of the FCA investigation was released at the end of June, I decided not to sell the shares as there hadn’t been an actual profit warning. As if to punish me for my complacency, the firm then issued a profit warning less than three weeks later, last Friday.
What’s gone wrong? In May, Lookers reported positive trading for the first quarter of the year. I found this reassuring following my purchase in March. However, this positive momentum appears to have reversed during the second quarter.
According to last week’s profit warning, new car registrations fell by 4.6% during the second quarter. Lookers also said weaker demand for used cars caused a significant increase in margin pressure. This suggests to me that gross profit and sales may have fallen in the used division.
Against this backdrop, the group says it has continued to experience cost inflation.
As a result, underlying pre-tax profit for the first half of the year is now expected to be c.£32m, down by 25% from £43m last year.
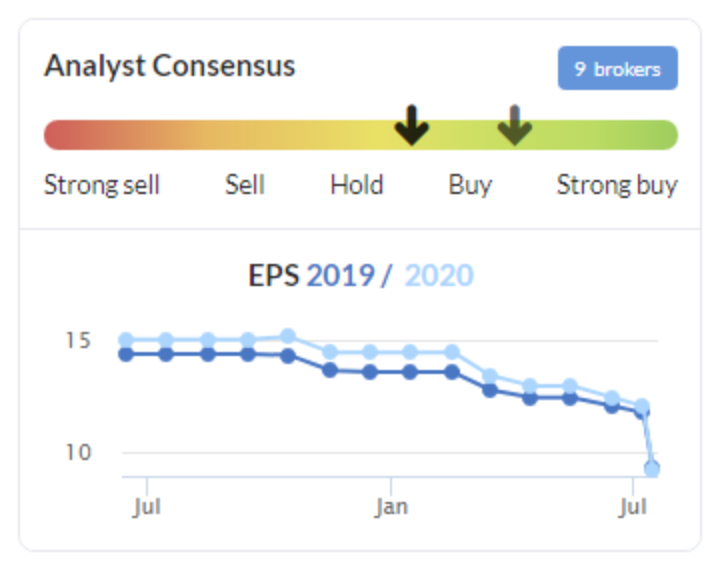
I give full marks for the company for providing clear guidance. But this is a big fall in profit. When combined with the risks posed by the FCA investigation, this warning has resulted in a big cut to broker forecasts:
Director buying: I see that the CEO and COO bought £75k and £78k of shares in the market on Monday. To put this in context, they collected total remuneration of £633k and £484k last year.
Guernsey Investments Limited, which appears to represent the Brammall family, has also added £1.6m (1.1%) to its holding, taking its total interest to 17.38%. Brammall is Lookers largest shareholder, as a legacy of the 2008 deal which saw the company buy the Brammall business.
My decision: I’m generally sceptical about coordinated director buying. But I think the continued support from the Brammall family is reassuring. If I intended to hold the stock indefinitely, I would probably average down at this point myself.
However, as things stand, my rules stipulate that I should sell immediately after a profit warning. So that’s what I’ll do. Unfortunately this means locking in a 55% loss. Will the shares rebound? Perhaps. But the stock is now trading on 4.6 times forecast earnings with a 9.3% dividend yield. That suggests the market is pricing in further bad news in the short term, a view I’d share.
Verdict: Sell
Total return: -55pc
Should I be worried?
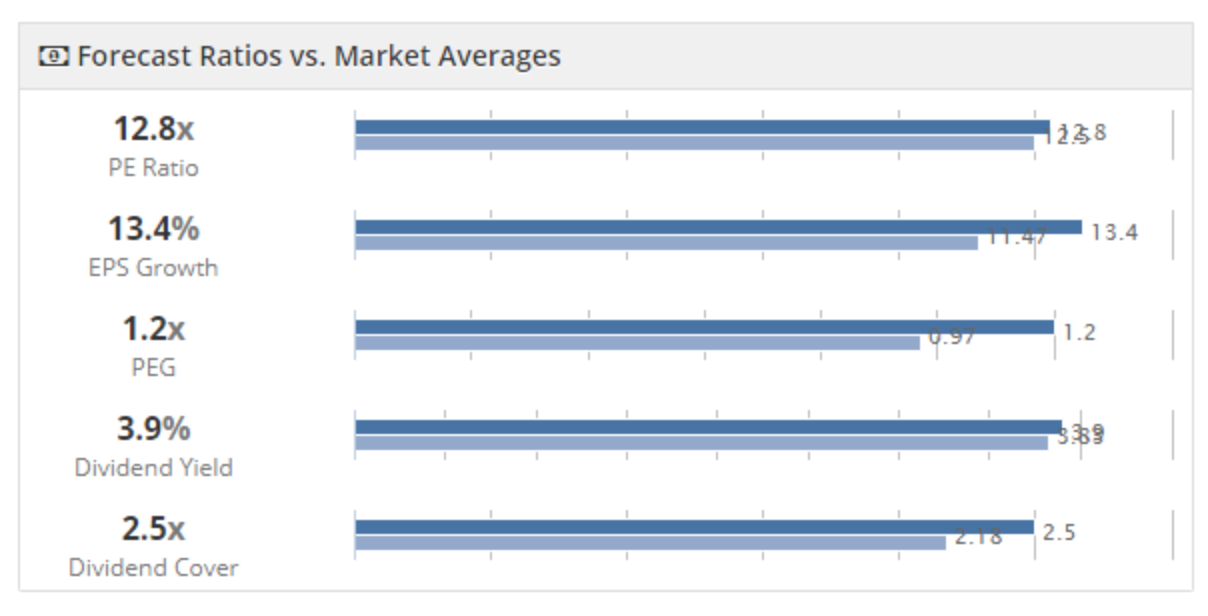
Occasional disappointments like this are inevitable, especially when dealing with cyclical small caps. But I remain comfortable with the overall profile of the SIF folio, which I think has attractive characteristics, in aggregate (SIF is in dark blue):
I think it’s also worth noting that dividends have made a significant contribution to SIF’s real-world performance so far. These aren’t included in the Fantasy Fund performance, but they are included in the normal folios:
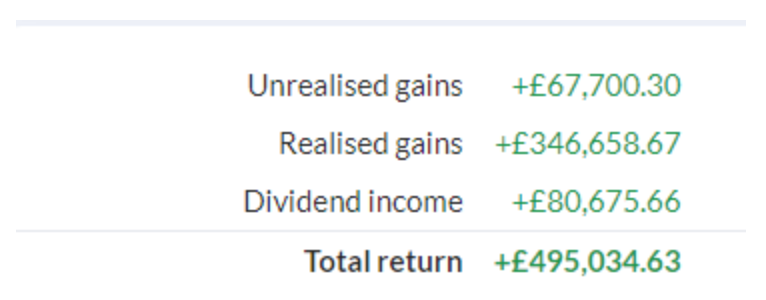
Based on the fantasy fund’s initial (virtual) value of £1m, dividends have added 8.1% to my returns in just over three years. I think that’s a useful boost.
Pawnbroking expansion could boost H&T
I’d also like to consider a possible new addition to the portfolio this week. H&T Group (LON:HAT) is the UK’s largest pawnbroking operator - and it’s just got rather bigger.
News that H&T has struck a deal to buy 65 stores and 29 pledge books from defunct payday lender The Money Shop was covered comprehensively by Graham Neary in the SCVR on 2 July. You can read Graham’s thoughts here. I won’t repeat his comments except to say that I also have a broadly positive view on this £10.6m deal, which seems reasonably priced.
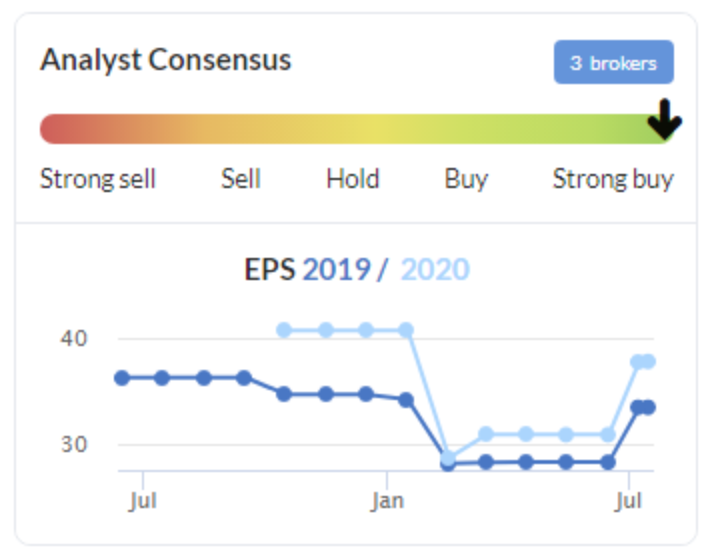
H&T has a decent track record in its chosen areas of pawnbroking, unsecured lending and gold/jewellery trading. The firm’s superior infrastructure and market-leading scale should help make this acquisition a success, in my view. The stock’s reappearance in my SIF screen results appears to have coincided with news of this deal, possibly because analysts have upped their forecasts for the year over the last couple of weeks:
I’ve owned this stock twice before in SIF, in 2016/17 and 2017/18. Since then I’ve admired its steady progress and healthy financials. These have not always been reflected in the share price performance:
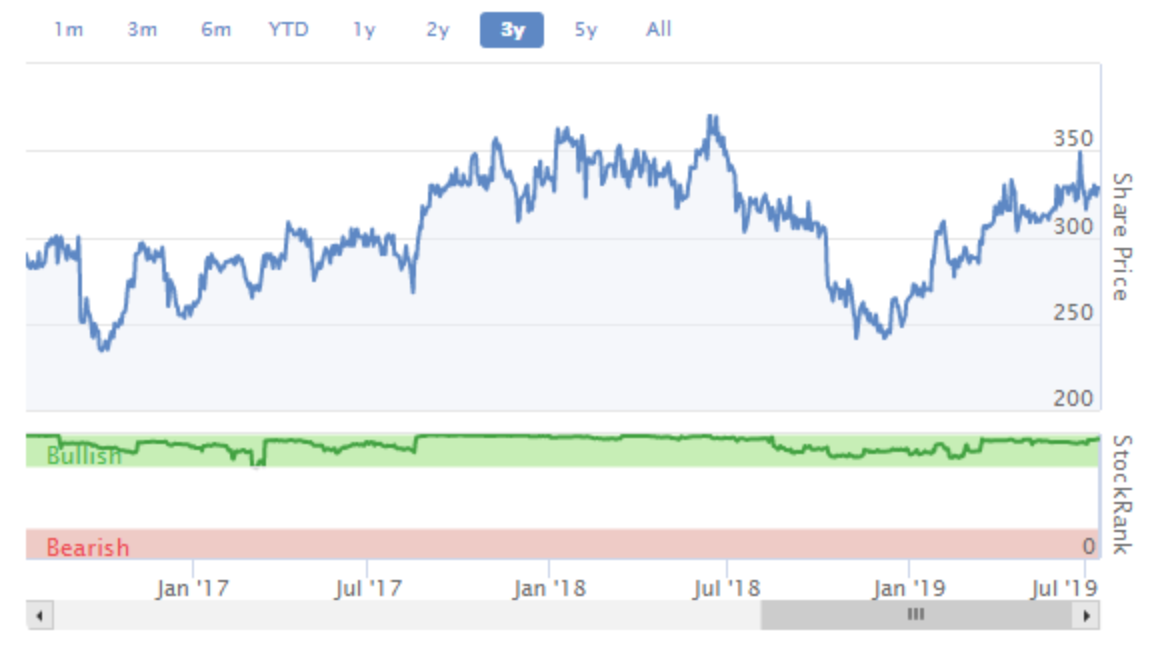
Stockopedia’s algorithms have had a consistently high regard for H&T. It’s currently classified as a Super Stock with a StockRank of 95. That makes it the highest-ranking stock in my screen results that I’m prepared to consider buying. With that in mind, let’s take a closer look at the stock’s factor scores.
Fair value
Here’s how H&T’s ValueRank of 65/100 breaks down into individual components:
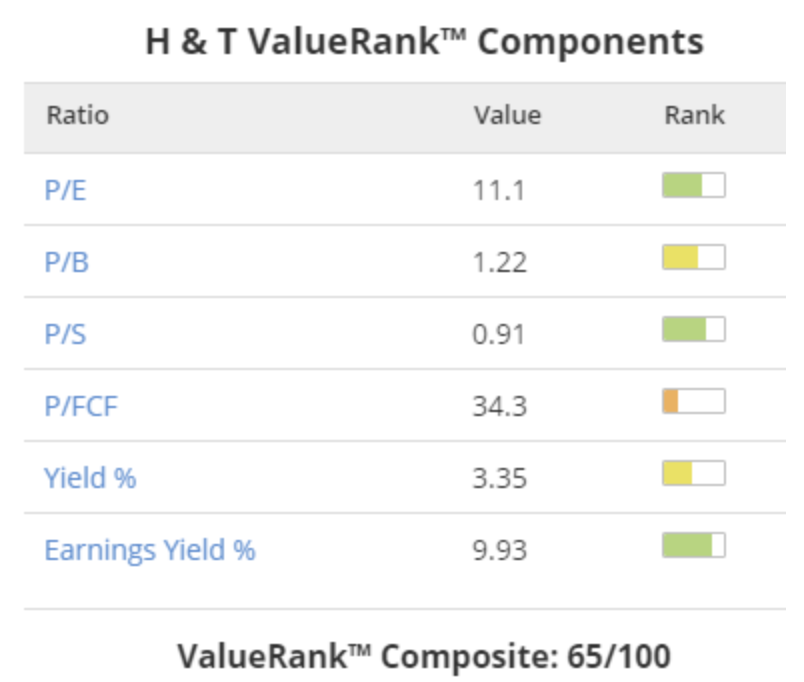
In line with traditional value investing techniques, these figures are based on the firm’s historical figures.
There’s not too much to dislike here, in my view. The stock’s earnings yield of (EBIT/EV) 9.9% suggests an attractive valuation to me, as do the price/book ratio of 1.2, which is largely backed by inventories and loan receivables.
The only possible concern is the price/free cash flow ratio of 34, which appears to imply that last year’s earnings were not supported by cash generation. However, a closer look at the notes to last year’s accounts confirms that weak reported cash flow was caused by the expansion of H&T’s personal loan book. This is represented by a £9.8m increase in receivables:
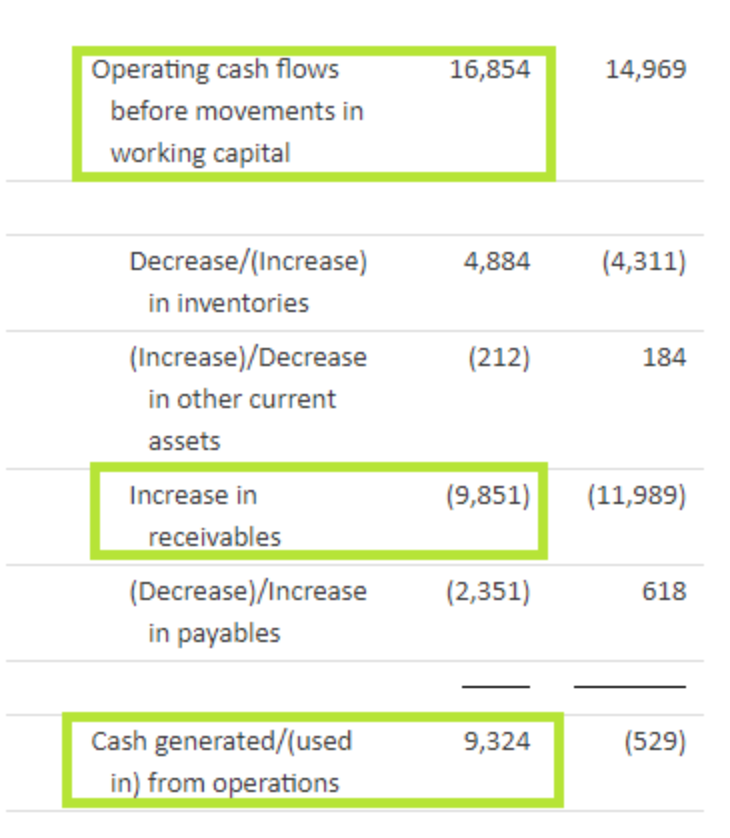
Stripping this out gives a more robust picture of cash generation, so I’m comfortable with this situation, which reflects the company’s stated growth strategy.
Understated quality?
H&T’s quality score is higher. In my view this reflects the consistent profitability and cash generation exhibited by this business in recent years:
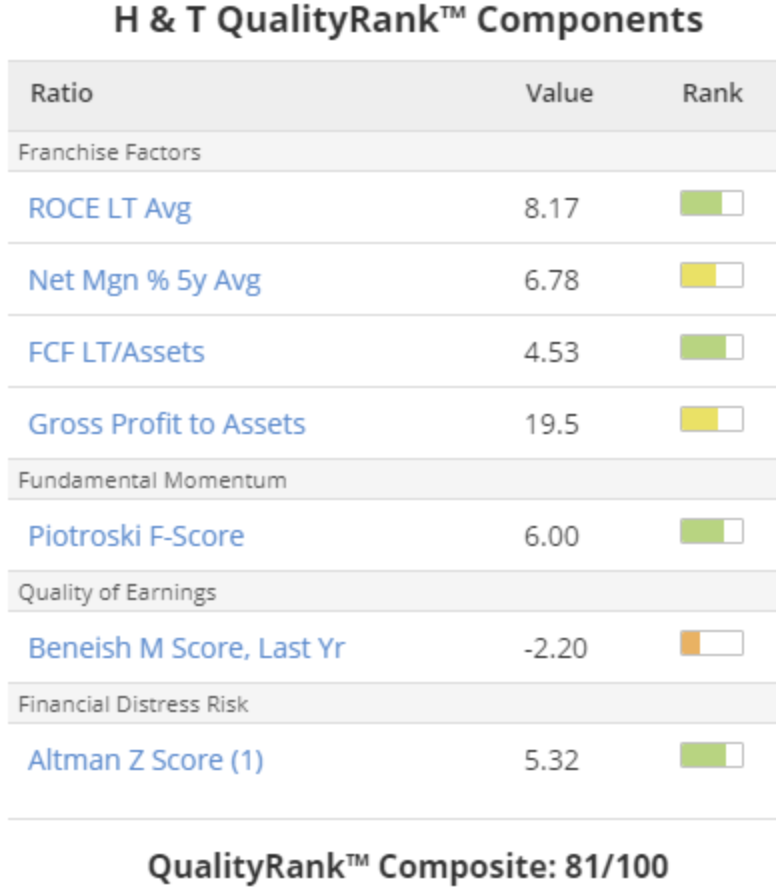
I believe this quality score would be higher were it not for the Piotroski F-Score (fundamental health) of 6/9. The main reason for this is the free cash flow situation I described above. So I think we can give H&T a clean bill of health in the quality department.
Very strong momentum
As my strategy is based around fixed nine-month holding periods, momentum is important. I can’t wait years for value to be realised. Luckily, H&T’s momentum score is its strongest factor ranking:
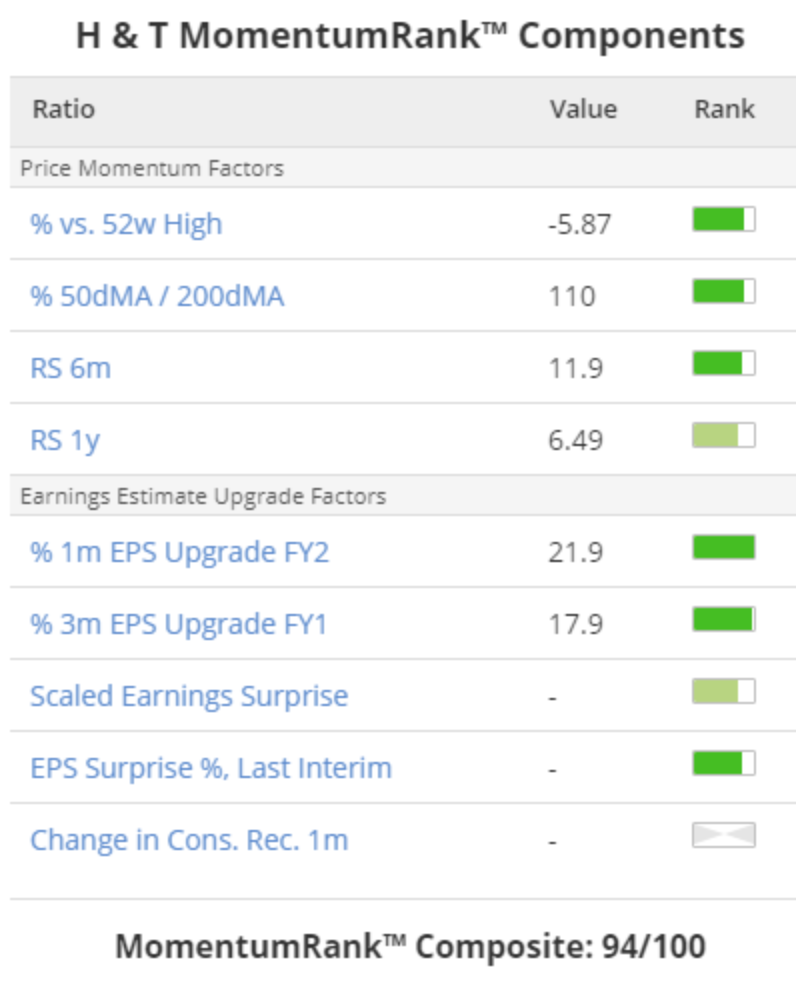
The price momentum picture is positive, but more importantly in my view, it’s supported by strong earnings estimate upgrade factors.
Forecasts for 2019 and 2020 earnings have both received significant upgrades over the last few months. And according to Stockopedia’s data provider, H&T’s most recent results also came in ahead of consensus estimates.
Looking ahead at the current period, recent gains in the price of gold could also help to support further earnings upgrades.
My decision: Trading on 9.2 times forecast earnings and offering a 3.6% yield, I would say the HAT stock looks reasonably priced. When combined with the strong momentum picture we see above and my good impression of the firm’s management, I feel confident buying the stock at this level.
I will be adding H&T to the SIF folio and to my own personal holdings this week, after this article has been published.
Disclosure: At the time of publication, Roland owned shares in Lookers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Rowland - I like your thought process. I see that H & T (LON:HAT) newly passes Richard Driehaus for Momentum and Screen of Screens for Quality. Significant broker upgrades for this year and next year. Counter cyclical nature has attractions also. Almost everything going for it, so have brought in with double my normal initial stake. Ian
I have held H & T (LON:HAT) for a while now, and I know Graham is a fan too; the price seesaws up and down quite a bit (mostly down below my buying price), but the dividends are okay and the rating seems modest for the overall progress being made and spread of activities; the gold price is also very bullish, which I think should help.
One the basis of above and with BoJo as likely PM, I'm now in.