SIF Portfolio May review: Beximco Pharmaceuticals & XLMedia

In my April review of the SIF portfolio’s performance during its first year, I concluded that the six month holding period might be too short. The majority of the stocks I sold last year continued to rise over the following months.
Of course, these gains took place against the backdrop of a strong bull market. So it may simply be that the rising tide has lifted all ships. Notwithstanding this risk, I decided to increase the minimum holding period for each stock from six months to nine months this year.
In order to avoid running out of cash for an extended period and being unable to buy new stocks, I’m phasing this change in gradually. This week I’m reviewing stocks which have been in the portfolio for seven months. In July, I’ll consider selling eight-month old holdings and in September I’ll move to nine months.
Two stocks are up for review this month -- Bangladeshi pharma firm Beximco Pharmaceuticals and Israeli internet marketing group XLMedia. Both are AIM-listed foreign companies that some investors would automatically rule out as potentially high risk. Despite this, both companies appear to have solid accounts and have been strong performers for the portfolio.
Interestingly, both are also rated as Super Stocks by the new StockRank Styles algorithm, with a RiskRating of Speculative. The Super Stocks classification suggests that these shares are statistically likely to outperform the market. However, the speculative tag indicates that even if they’re successful, XLMedia and Beximco could deliver a volatile ride for investors.
Beximco Pharmaceuticals
Bangladeshi firm Beximco Pharmaceuticals specialises in the production of generic products for domestic and international market. It was founded in 1976 and has traded with a dual listing in Dhaka and London since 2005.
One interesting aspect of this stock was highlighted by Graham Neary in a SCVR in April. Beximco’s UK shares (which are GDRs) trade much more cheaply than its Bangladeshi stock. In theory, this should provide an attractive arbitrage opportunity, but in practice this isn’t possible. According to Beximco’s website, the two share classes aren’t fungible. In other words, you can’t exchange GDRs for the underlying shares.
Given the lack of fungibility, I’m not sure how much downside protection this discount really provides for UK shareholders. But fortunately the SIF Portfolio hasn’t needed downside protection for Beximco over the last seven months. The shares have risen by about 68% from their purchase price of 39.75p, to become one of the portfolio’s top performers.
One of the main attractions is the firm’s export activity. As you might expect, Beximco exports a lot of its products to developing market nations in Asia and Africa. But the firm’s factories have also been approved by regulators in most major developed markets. Beximco recently became the first Bangladeshi firm to export pharmaceutical products to the US, opening up a potentially significant channel for long-term growth.
Beximco’s earnings doubled last year, and have grown by an average of almost 20% per year since 2011:
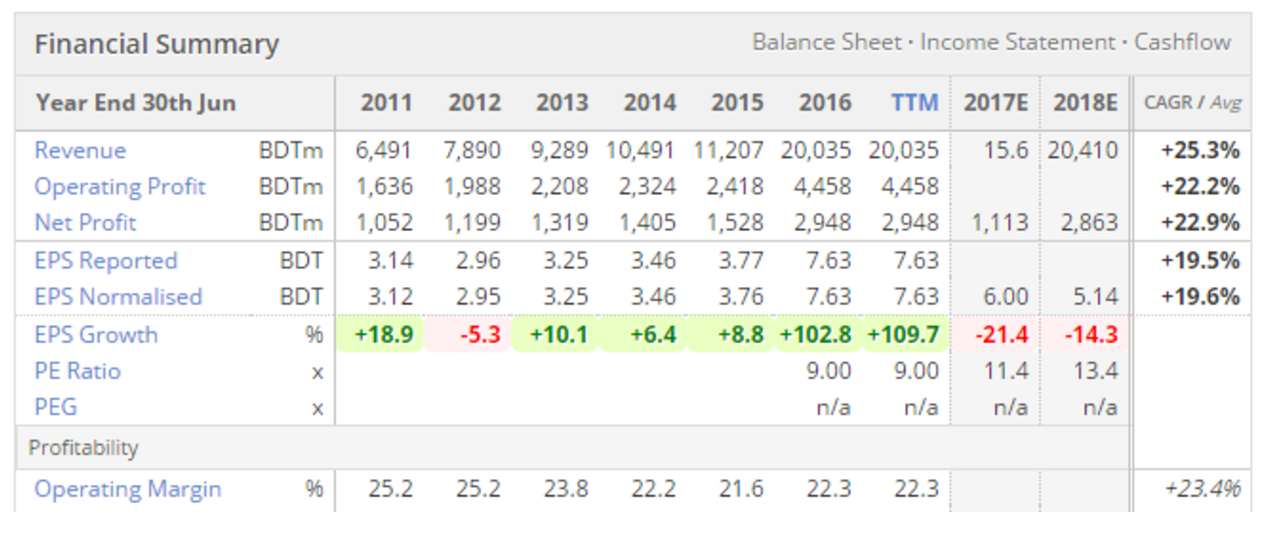
Despite this, investors expecting a repeat performance in 2017 may be disappointed. Although the group’s pre-tax profit rose by 17.8% to £11.6m over the same period, forecasts from house broker Daniel Stewart suggest full-year earnings will fall by 21% this year.
My verdict
Beximco’s rolling forecast P/E of 13 and P/B of 1.1 still look attractive to me. It’s also worth noting from the image above just how consistent Beximco’s operating margin has been over the last six years. In my view, this does appear to be a decent quality company.
However, the falling earnings forecast and reduced dividend yield mean that Beximco no longer qualifies for the Stock in Focus (SIF) screen. This means that I’ll be selling the SIF portfolio’s virtual shares this week.
I’m pretty happy with the returns. During its time in the portfolio, Beximco has provided a dividend return of about 1.2%, in addition to the 68.5% gain on the price of its UK shares.
Verdict: I will be selling from the portfolio.
Total return: +69.7%
XLMedia
XLMedia is one of a group of London-listed Israeli tech stocks with very high profit margins and superb cash generation. The accounts look good to me, and while I have some reservations about the durability and longevity of the group’s business, XLMedia does appear to have scale and to be executing well.
The portfolio’s holding in XLMedia has risen by more than 20% over the last seven months, despite being knocked by news of director selling in both December and March. It’s second-time lucky for the portfolio, as back in May 2016, I opted not to buy XLMedia at a considerably lower valuation. Buying back then would have netted the portfolio a 44% gain in six months, so I’ve since become more reluctant to interfere with the results of the SIF stock screen.
XLMedia’s operating performance during its stint in the portfolio has been good. March’s final results showed that revenue rose by 16% to $103.6m last year, while pre-tax profit was up 28% at $31m:
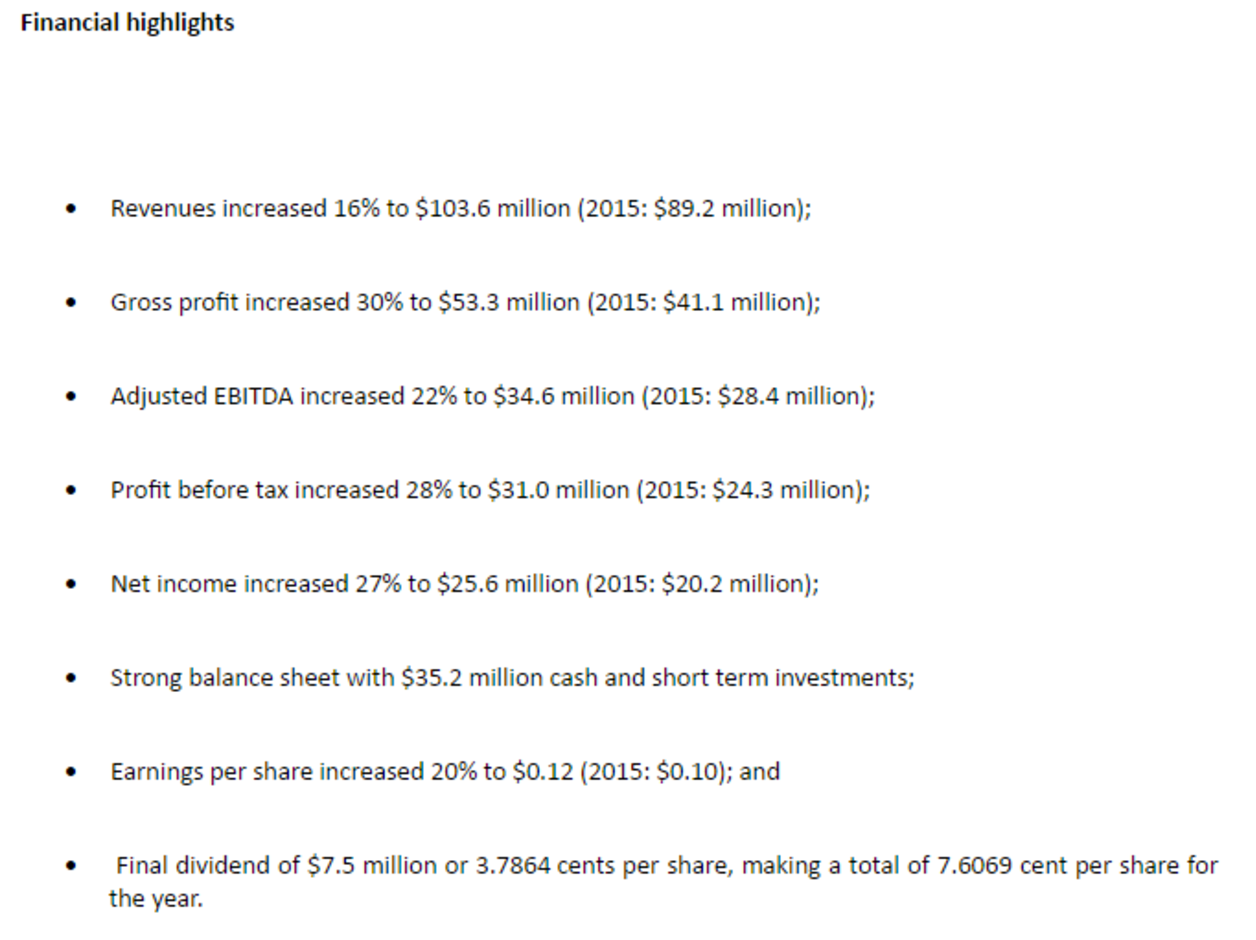
The group ended the year with net cash and equivalents of $35.2m, allowing the board to increase the full-year dividend by 52% to 7.6 US cents per share. During the portfolio’s holding period, dividend receipts have totalled $1,826 or around £1,426, giving a 2.9% yield on cost.
Interestingly, the house broker is forecasting a 5% cut to the total dividend this year, giving a forecast yield of 4.5%. Notwithstanding this earnings are expected to rise by 5.8% to $0.13, putting the stock on a forecast P/E of 12.5.
My verdict
In my view this business remains attractive, but the slowdown in earnings growth means XLMedia’s rolling PEG ratio has risen above my threshold of 1.2x. The forecast dividend cut means that this stock also fails my dividend growth test:
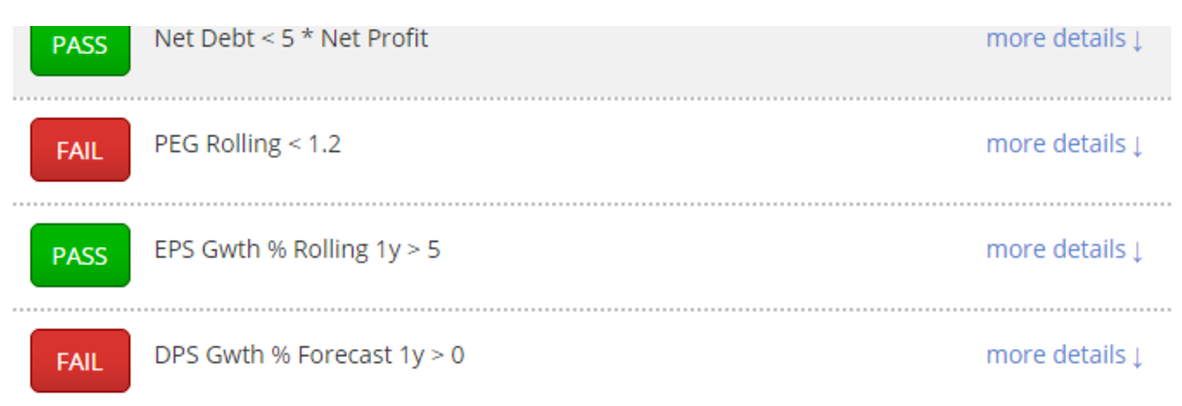
As a result, I’ll sell the portfolio’s XLMedia holding this week. I’ll also sell my personal holding of XLMedia shares after this article has been published.
Verdict: I will be selling from the portfolio.
Total return: +24.3%
Disclosure: Roland owns shares of XLMedia but does not own shares of Beximco Pharmaceuticals.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
This company stated last month that it was extremely confident in its medium term prospects. And re- affirmed its progressive dividend policy. It is cash generative and cash rich with a reasonably well covered dividend. Why any commentator would advise selling it on the basis that it might cut its dividend mystifies me.
HI raigersfield,
I'm not sure whether you're referring to Beximco Pharmaceuticals (LON:BXP) or XLMedia (LON:XLM) in your comment, but my decision to sell both stocks from the SIF portfolio is based on the trading rules for the portfolio. These stipulate that stocks should be sold after a fixed period (currently nine months) if they no longer meet the screening criteria for the portfolio.
I'm not advising anyone to sell these stocks, and my comments are not intended to constitute a sell rating.
Hope this helps,
Roland
Roland, BXP confusingly changed its reporting year during 2016 which might have deceived stockopedia's 2016 figures. The local currency also adds another layer of complexity when trying to decipher the figures in trading statements and reports..
However from its Q3 FY17 statement dated 28/4/17, BXP does appear to be on track to increase both its revenues and earnings compared with the same period the previous year.
Agreed - the quarterly updates show that everything is looking pretty snug at the moment and going in the right direction.
HI Firtashia,
Thanks for flagging up the change of year end at Beximco Pharmaceuticals (LON:BXP).
Looking at the Stockopedia figures, the 2017 forecast revenue and net profit do seem to be a bit confused. But the broker forecast earnings per share of 6 BDT does look about right to me, based on nine-month eps of 4 BDT reported in the Q3 statement.
Multiplying the forecast eps of 6 BDT by the share count implies a forecast of 2,433m BDT for the 12 months to 30 June 2017.
If I've done my sums correctly, the equivalent net profit figure for the 12 months to 30 June 2016 was 1,938m BDT. So you're right, Beximco does seem to be on track to deliver healthy profit growth this year.
Although the quality of Stockopedia's data from Thomson Reuters is high, glitches like this are inevitable in an automated data-driven system. Hence why in my opinion, it's always worth checking the accounts yourself before investing.
For what it's worth, I'd also like to reiterate that my article is not a sell recommendation. I've sold the stock from the portfolio because that's what the rules dictate. Personally, I'd tend to agree that Beximco still looks quite attractive.
Regards,
Roland
Roland, Cenkos are forecasting an unchanged dividend of 7.6c this year, increasing to 8c this year.
Berenberg are forecasting a small fall to 7.2c this year, rising to 8c next year.
IMO those dividend forecasts will likely be proven conservative. Anyway, with dividend yields of around 4.5% I'm quite happy to hold given that I feel the share price is undervalued anyway. With a large cash pile it's likely there will be more earnings-enhancing acquisitions to boost core earnings.
Hi Rivaldo,
Thanks for your comment. I was using the consensus dividend forecast figure in Stockopedia, rather than individual broker forecasts, but it's interesting to see the contrasting views from the two brokers, as both are retained by the firm and so should have good access to management (http://www.xlmedia.com/advisers-and-contacts/).
You may well be right about the scope for dividend growth and acquisitions at XLMedia (LON:XLM). I share your view that the stock remains a hold in general terms, but I'm selling in line with the rules of the SIF Portfolio.
Regards,
Roland