SIF Portfolio: Oil stocks make me question dividend rules

Last week I wrote about the SIF portfolio’s heavy exposure to cyclical stocks. The cyclical companies I was referring to are mostly stocks dependent on consumer spending or the construction market.
One cyclical sector SIF isn’t currently really exposed to is the energy sector. Although the portfolio has made some money from the the mining sector in the past (PAF, CAML, S32 & RIO), it’s never owned an oil and gas stock.
Why is this? When I last looked at oil stocks in October 2016, OPEC and Russia had just agreed on joint production cuts. At the time, I said that my screen “isn’t intended to pick up cyclical stocks exiting a major downturn. The screen is designed to identify companies that are already profitable and have the potential to deliver above-average returns.”
Nearly two years later, oil companies are in a very different place. The OPEC-Russia deal was very successful. The price of a barrel of Brent Crude has since risen by more than 50% to about $74 (at the time of writing). Oil companies’ costs are down, cash is flowing and profits are rising fast.
Russia and OPEC are in the headlines again this week, ahead of a meeting where they’re expected to consider whether to increase production. Despite this, there are still no oil stocks which qualify for my screen. Do I need to consider tweaking my screen so that SIF can invest in oil? Or is this a tricky sector that’s best avoided?
Bad timing or a bad business?
The oil sector doesn’t have a great track record of generating the kind of sustainable, above-average returns I’m looking for.
While oil traded above $100 per barrel almost continuously from 2011 to mid-2014, Royal Dutch Shell’s return on capital employed fell from a peak of 18% in 2011 to 7.5% in 2014.This was accompanied by a fall in operating margin from 9.1% to 4.7%, as both costs and spending ballooned:
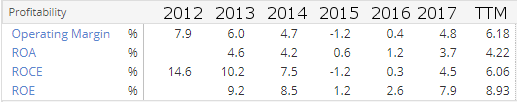
It was a similar (or worse) story elsewhere in the sector. This suggests to me that by 2011, it was probably too late to profit from the last oil bull market. When oil prices flattened out, it was an early sign that the cycle was turning.
This view seems to be supported by StockRank performance date. Energy is the only sector where high StockRanks haven’t outperformed the market since 2013:
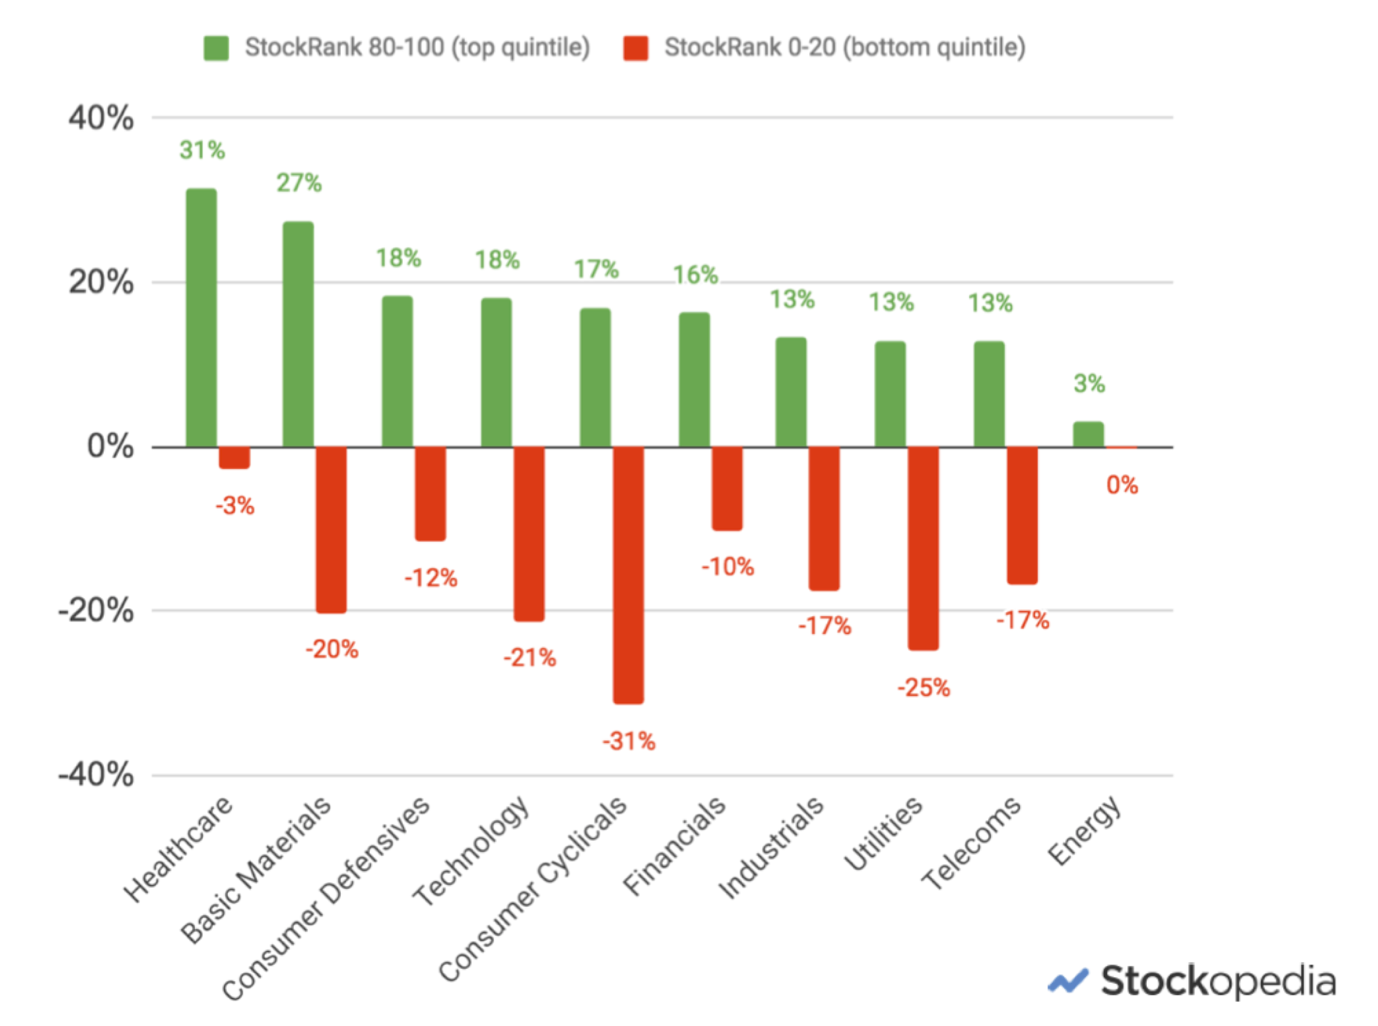
If you’d like to know more about this and nine other insights gained from five years of running the StockRanks system, I strongly recommend Ed Croft’s feature from last week. For anyone who uses StockRanks to help pick stocks, this is essential reading.
Dividend rule blocks oil stocks
I make very few changes to the main Stock in Focus Screen. But I do quite often experiment to see how changing a single rule affects the selection of stocks. Recently I’ve been wondering whether I should consider stocks that don’t pay a dividend.
Personally, I prefer to invest in companies with regular dividends. I view these cash payouts as a good discipline for management. I also think that when combined with a good balance sheet and adequate earnings cover, they provide useful supporting evidence of cash generation. In short, I think that a well-covered dividend helps to de-risk a stock.
My SIF rules for dividends require a forecast yield of at least 1.5% and forecast dividend growth of 0% or more. The problem is that there are some good companies which don’t pay dividends. This is usually because they’re in a growth phase, or because the board’s policy is to use surplus cash in other ways.
Warren Buffett’s firm Berkshire Hathaway has famously never paid a dividend. Mr Buffett’s view is that he can find more profitable ways to invest surplus cash than his shareholders would be able to.
Oddly enough, this is a view shared by most oil industry executives...
But while Mr Buffett invests Berkshire’s surplus cash in profitable, cash-generative enterprises, oil executives prefer to use their cash to drill holes in the ground. Many of these holes turn out to be dry, providing a poor return on investment.
This sweeping judgement leads me a little unfairly to the stock I’d like to consider.
$4.5bn returned to shareholders
Removing the two dividend-related rules from the SIF screen increases the number of qualifying stocks from 16 to 21.
One of these firms is FTSE 250 oil and gas producer Cairn Energy. This business was founded by Sir Bill Gammell in 1980 and listed on the LSE in 1988. Cairn made it big with a major oil discovery in Rajasthan, India, in 1999. By 2012 Cairn had spun out this asset into Cairn India, collecting about $6.8bn, of which $4.5bn was returned to shareholders.
Cairn qualifies for my screen because it generated a net profit of $263.1m in 2017, despite only clocking up revenue of $33m.
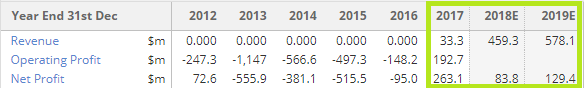
This accounting gain seems to have come from the conversion of the firm’s remaining 5% stake in Cairn India into shares of Vedanta Limited. These are valued at $1.1bn -- but they’re currently inaccessible due to a long-running tax dispute with the Indian authorities.
This paper profit wasn’t backed by cash flow. By the end of 2017, the group’s 2012 net cash balance of $1.6bn had been reduced to a net debt of $113m.
In fairness, this money hasn’t all been squandered. Cairn is now producing 20,000 barrels of oil per day in the North Sea. Longer-term, the firm’s SNE discovery off the shore of Senegal is one of the biggest in recent years. Development plans will target nearly 500m barrels of oil.
Cairn’s 2018 and 2019 profits are expected to be backed by North Sea cash. The stock’s rolling forecast P/E of 15 looks reasonable, and its cyclical timing seems good to me. More value may be on offer if Cairn can release the value of its Indian assets.
This could be a good buy, but there are still many unknowns. In my view, this business carries much more speculative risk than the type of dividend-paying stocks I usually buy for SIF. It doesn’t seem to fit the portfolio’s brief of targeting “affordable growth”.
Do you insist on dividends?
Here are a few of the other stocks which qualify for my screen when I remove the dividend rules:
Central European budget airline Wizz Air Holdings
African miner Gem Diamonds
Kurdistan oil producer Genel Energy
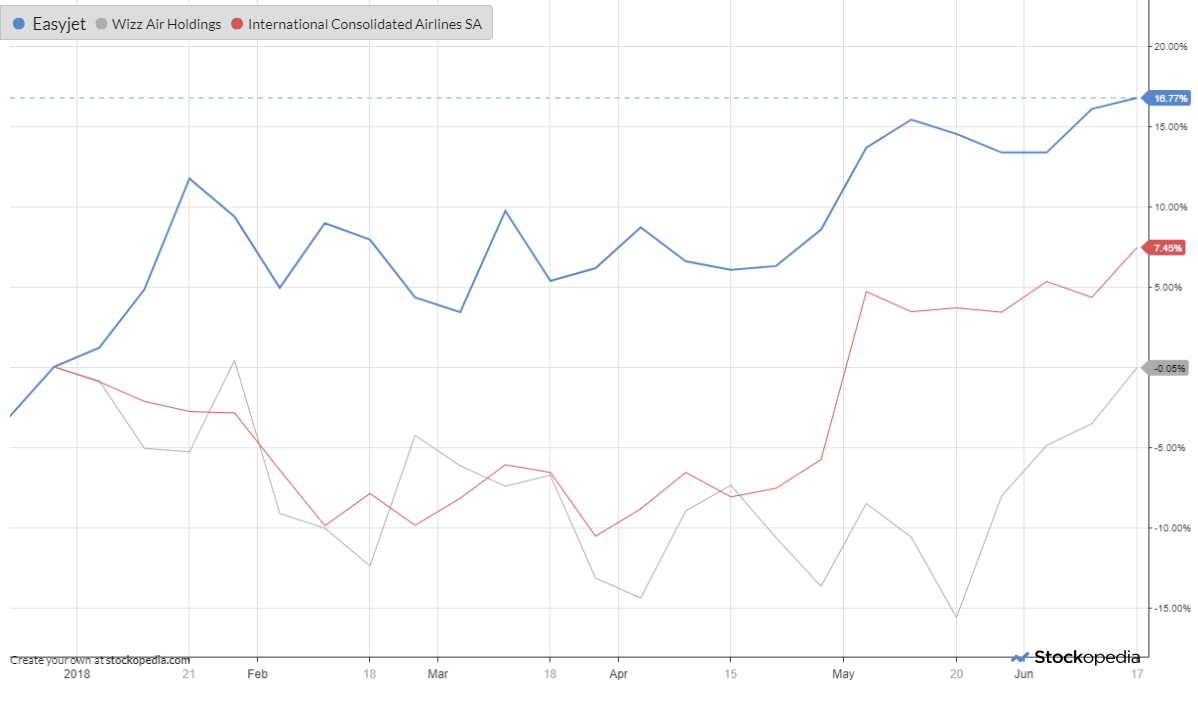
All three firms have StockRanks in excess of 80. However, Wizz Air has lagged portfolio stock easyJet and former holding IAG so far this year.
And while I rate Genel quite highly, I believe that investing in commodity producers operating in developing markets requires extra research, and perhaps a longer timeframe than my default holding period of nine months.
I’ve concluded that my dividend rules help to manage risk in the SIF portfolio. I intend to leave these rules unchanged. But I’d love to know more about your approach to dividends.
Are they a useful bonus or a must-have?
Do they really help to filter out risky stocks?
As always, please let me know what you think in the comments below.
Disclosure: Roland owns shares of Rio Tinto and easyJet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Without wishing to labour the point, I am unsure whether investors are aware of what their Directors are contractually bound to do. There seems to be an implicit assumption that the Executive Directors are working full-time on the company's behalf. However, this may not be the case and I suspect that this is an acute problem with resource stocks. The Directors often appear to act under little or no supervision and have operations in out of the way places where there is a lack of public scrutiny. How much time they actually spend on the company's business is largely unknown. How much overlap there is with their private interests is completely unknown. The NED responsible for the Directors' remuneration may also be on the gravy train.
It's an awful phrase but the term “Lifestyle company” springs to mind. Forget about dividends, forget about profits. For some, it appears to be all about just keeping it going for as long as possible. Putting the shareholders, including institutions, on a promise and then simply milking the company in a variety of ways for personal gain. Maybe as investors, we need to differentiate more clearly the difference between gambling and investing.
Of course, it's a broad generalisation but there seems to be a large proportion of non-dividend paying companies that generously reward senior managers, regardless of the share price performance. Virtually all the resource exploration and production companies that I have come across pay their managers substantial amounts in cash and yet many pay no dividends. They simply leave dangling the carrot of a potential takeover and, therefore, capital gains.
Resource companies such as Cairn Energy (LON:CNE), Central Asia Metals (LON:CAML) and SOCO International (LON:SIA) have all returned a large chunk of their profits to shareholders. But for each of these, there are many resource stocks that provide neither income nor exit route for shareholders. In my view, it's easy to forget that resource stocks will often have depleting reserves. The managers of most of these companies are clearly intent on extracting cash for themselves on an on-going basis. But the rewards for shareholders are largely back-loaded and that's presuming they crystallise at all.
Hi LongValue,
Thanks for your comment. I couldn't agree more re. directors' pay and rewards for shareholders at resource firms. Any money they do make tends to be reinvested in new prospects and directors' yachts. It's rarely returned to shareholders.
The companies you mention are honourable exceptions, but I'd still argue that good research, good timing and a long horizon are needed for investors to have a chance of outperforming the market with these stocks.
Cheers,
Roland
Roland
Like Jamie I look for dividends for my long term portfolio because there is lots of research that concludes that dividend growth when compounded makes up the lions share of stock market returns. Whether companies paying dividends represent a lower risk is open to more conjecture but I would argue that for most companies so long as the dividend is well covered it is a better use of spare capital than going on an acquisition spree!
PS Like you I have tended to avoid O&G shares but recently took a smallish position in BP (LON:BP.) encouraged by the fact that it was gradually putting its problems behind it and was starting to benefit from the increase in the oil price. Not one for the long term however.
Hi Roland, in answer to the questions you posed at the end of your post.
1) Yes I find them essential but also nice to have!
2) I've seen lots of research which suggests focussing on dividend payers and growers tends to offer higher returns with lower risk, although mostly in equally weighted portfolios.
Zero yielders tend to offer lower returns and greater risk, so I'm happy to exclude them, but of course there will always be exceptions to that.
Thus I tend to look for growing yield stocks & I'm happy to exclude zero yielders from my universe of stocks that I Score.
There is also research which suggests that picking yield stocks on the basis of total shareholder yield is more effective - which means factoring the yield from dividends and share buy backs - which is something that you alluded to in your post. Unfortunately this is not easily screenable in Stockopedia apart from having a look at change in shares outstanding as a rough and ready proxy for it.
Regards
Jamie
Website : Compound income
Good article. Very insightful.