Small Cap Value Report (16 May 2017) - KBT, ACRL, ZYT, KOOV, ITQ

Good morning! It's Paul here.
Remarkably buoyant market conditions continue. I really don't know what to make of it. So many smaller company shares are going through the roof at the moment. It feels too good to be true, but I really don't know whether I should be running my winners, top-slicing, or moving into cash?
I'm struggling to remember any similar time, in my investing career (c. 20 years) where mine (and other peoples') portfolios seem to go up almost every day, for weeks & months on end. Personally I've hardly top-sliced anything. I'm letting the winners run. Providing companies keep putting out sufficiently positive newsflow to justify an aggressive valuation, then in a bull market arguably one should just go with the flow.
It's going to end in tears at some point, we just don't know when!
Anyway, there's loads for me to get through today, so here goes.
K3 Business Technology (LON:KBT)
Share price: 154p (down 38.3% today)
No. shares: 36.0m
Market cap: £55.4m
Trading update (profit warning) - bad luck to shareholders here.
This company seems to be a software reseller (mainly Microsoft products), describing itself as;
K3, which provides mission critical software, cloud solutions and managed services to the retail, manufacturing and distribution sectors...
It's a significant profit miss today;
As previously reported, half year results were impacted by Enterprise contract slippages and, although the Company has seen some major deals close, certain large Enterprise contracts have not been secured as expected.
As a result, despite the high seasonality inherent in Q4 trading, the Board now believes that the results for the year to 30 June 2017 will be significantly below current market expectations...
As you can see from my favourite Stockopedia graphic below, this is the second profit warning this year;
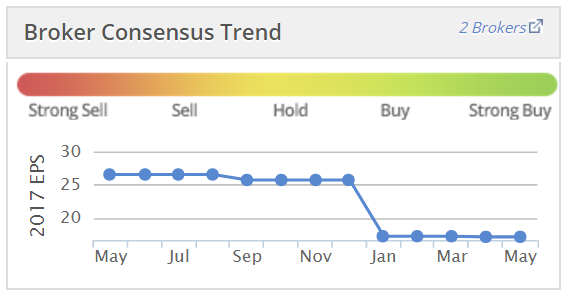
Broker forecasts - I haven't yet seen any revised forecasts, taking into account today's profit warning. FinnCap said that it's suspending its forecasts for now, until there is more clarity after the year end (30 Jun 2017).
Therefore, for now, we're in the realm of complete guesswork as to how bad this profit warning is likely to be. My hunch is that we could be looking at something like 10p EPS? That's just a guess though.
The company goes on to sweeten the pill somewhat, saying this;
Nonetheless, the Group's operations elsewhere are seeing encouraging progress and healthy cashflows. Furthermore, the Company has secured pilot customers for its new cloud-based modular technologies which will generate opportunities for both new and existing customers.
So it doesn't sound like a complete wipe-out.
Review - I don't like the sound of this - the word "review" is usually a sign of more pain to come;
Given trading conditions and the Group's performance to date, the Board has started a review of the Company's resources with the intention of refocusing the growth strategy around the cash generating business units and the large installed customer base. A further update on this will be provided in due course.
That sounds like redundancies & exceptional charges are in the pipeline.
Balance sheet - I've flagged up many times before that this group doesn't have a good balance sheet. It's stuffed full of intangibles - mostly goodwill (of £50.0m at 31 Dec 2016), plus another £27.2m of other intangible assets.
So the NAV of £70.4m reduces down to negative NTAV of -£6.8m.
Personally I tend to usually avoid any share where NTAV is negative. The only exceptions being where the company is highly cash generative, which this isn't.
The c.£17m bank debt at 31 Dec 2016 could become a problem if banking covenants are breached. So holders really need to check out the position re covenants. That £17m is the gross debt. It was partially offset by £4.5m in cash.
Given the size of the company, the bank debt doesn't look particularly alarming, but I'm never comfortable with bank debt at companies which are seeing deteriorating trading.
My opinion - no change really, as I've never rated this share.
My report here on 10 Jan 2017 on K3's earlier profit warning concluded that the share was unattractive.
Graham reported here on 27 Mar 2017 on its underwhelming interim results, deciding that the share was in the "too difficult" tray.
The news today looks worrying. This seems to be a situation where bad news is dribbling out piecemeal. If I owned this stock, I'd have probably sold on the opening bell today. With considerable uncertainty over performance, I can't see any appeal to holding this share.
I suppose some upside could come from the renewed focus on making IT systems more resilient, following recent high profile hacking issues.
Accrol Group (LON:ACRL)
Share price: 155p (down 2.5% today)
No. shares: 93.0m
Market cap: £144.2m
Trading update - this company makes loo rolls & other tissue products, selling to discount retailers mainly.
The company updates us today on its year ended 30 Apr 2017;
The Company has had a strong year of growth in its first year as a publicly listed business following its successful IPO on AIM in June 2016, and is pleased to announce that it has performed in line with market expectations despite some challenging macro-economic factors.
Further details are given about new manufacturing & storage facilities, thus increasing production capacity (although it's not stated by how much).
The CEO comments are brief, but soothing.
"We are pleased to announce that, despite a less favourable macro-economic environment, we have performed in line with expectations in our maiden year as a publicly-listed business.
We have continued to make progress with our growth plans, extending our relationships with both new and existing customers and investing in our infrastructure for the future.
Valuation - the valuation looks about right to me. A business like this is not likely to ever command a premium valuation, so a forward PER of 10.6 looks sensible;

Dividends - there doesn't seem to be any forecast dividend data picked up by Thomson Reuters (Stockopedia's data supplier).
However, the prospectus indicated a planned 6% dividend yield, based on the float price of 100p per share. With the share having since risen to 155p, that translates into a 3.9% yield. So pretty good, assuming that the planned divis happen.
My opinion - I reviewed the prospectus here on 8 Nov 2016, and found lots in it that repelled me.
Specifically, why did the previous shareholders want to cash in a lot of their chips? They couldn't have been particularly optimistic about the future, or why sell?
Forex movements could cause problems, as could input cost volatility.
Customers - are highly concentrated. Yet as we know, the discount retailers aren't known for their generosity towards suppliers. So there is risk here.
A horrible management incentive scheme, that gives away 12% of the share price upside above 130p to management! That's pretty awful, in my view.
Overall then, it's not for me.
Zytronic (LON:ZYT)
Share price: 472p (up 6.2% today)
No. shares: 15.9m
Market cap: £75.0m
Interim results - for the 6 months ended 31 Mar 2017.
Zytronic is a UK-based specialist manufacturer of touch sensors - e.g. bespoke touch-sensitive screens for things like cashpoints, vending & gaming machines.
These are decent figures. Here are a few key numbers for H1;
Revenues up 14.1% to £11.3m
Profit before tax up 38.9% to £2.5m
Basic EPS up 44% to 13.8p
There seems to be a bias towards H2 for profitability, so the company looks set to do around 30p EPS for this year.
Broker consensus is 28.6p EPS for this year, giving a PER of 16.5 - which looks reasonably priced.
Very strong balance sheet, with £12.5m in net cash - so expect a special dividend in the not-too-distant future.
Current trading sounds positive;
"The second half of the year has started well and is in line with expectations and on this basis we expect to make further progress in creating value for shareholders."
Dividend yield is about 4.0%, with scope to pay out more, due to cash pile.
StockRank of 88 is excellent.
My opinion - this is a long-standing favourite of mine. I don't currently hold any stock personally, as I was happy to bank a gain, and recycle the money into faster-growing companies.
Also, last time I reported on it, a reader pointed out the risk factors in the company's Annual Report. This indicated a heavy reliance on a small number of customers. Therefore, there is the ever-present risk of a gap appearing in the order book. That happened a few years ago (in 2013), and it knocked the share price for six.
Since then though, the company has performed well. It's a high net profit margin business, with a very sound balance sheet, paying decent divis. The price certainly doesn't look expensive, even after a very recent run.
A couple of interesting announcements later in the day;
£ITQ
(at the time of writing, I hold a long position in this share)
An announcement has been issued by a newly created company called Chisbridge Ltd. This company has been formed by the Chairman, CEO & CFO of Interquest.
Chisbridge is;
"evaluating making an offer for InterQuest at 42p per share in cash with a full loan note alternative"
This is clearly a derisory offer, and it puts the company in play. So hopefully other bidder(s) may now appear, and offer a more sensible price for the company. I wonder whether that might be the intention of this initial offer?
Just 29 minutes later, the independent Directors of InterQuest issued another RNS, in response, rejecting the approach, saying this;
The Independent Directors, who are being advised by Panmure Gordon, have unanimously concluded that they would be unable to recommend the Proposed Offer to InterQuest shareholders on the basis that it would materially undervalue the Company and its prospects.
So I wonder what happens now? The share price has risen to 46.5p, or 10.7% above the derisory 42p possible bid. So the market is clearly now expecting other bidder(s) to enter the fray at a higher price.
It will be interesting to see how this pans out.
Koovs (LON:KOOV)
Statement re share price - the company says it knows of no specific reason why its share price has been falling. I do - possibly because the company is a massively loss-making load of junk?
The company says it continues to see year-on-year growth, but the last sentence reiterates this company's ongoing problem;
The Company will look to raise additional capital during the course of the year to continue to deliver its growth plans.
They need to keep finding mugs optimists to refill the coffers, as it continues to burn through large amounts of cash in operating losses.
This is a very high risk share, and I think its business model remains a long way from success.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Gromley
Re: K3 Business Technology (LON:KBT)
The common factor I believe that at the time of the first year-end change the Current Chairman was FD. So as it worked the first time, maybe he suggested it might be a good idea now?
The only time I would normally expect to see change of year-end date, is when an acquired company has to slot in with the acquirer's closing period.
Unfortunately, this is a classic case of a highly acquisitive company which was previously a cash generative business, acquiring businesses over time which have generally emasculated its cash generating characteristics. The previous CEO was responsible but he left the business.
As you say a bargepole in its present condition.
Thanks for the thoughts on Zytronic (LON:ZYT) Paul! Happy holder, though wouldn't be upset if they did get taken out by a big 'un.
Have held Zytronic for a number of years, as they are in the forefront of commercial touch screen development, offering growth with an increasing divi. What has surprised me, is that a small company with unique products, in an ever increasing market, has not been the subject of a takeover bid.
ditto and I suspect that is the natural end-game in current market conditions with avaricious M&A and the need for growth. There are several UK tech companies likely to be in the cross-hairs, notwithstanding those already taken out this year
With Interquest (LON:ITQ) I was wondering whether the cheeky 42p bid by management might possibly be a way of putting the company into play. i.e. maybe they're trying to smoke out a better bid, by putting in their own cheeky bid? After all, if it's been rejected already by the NEDs/house broker, then it's difficult to see why they would have done it.
The share price at 46.5p seems to be suggesting that the market is expecting higher competing offer(s)?
I appreciate that ITQ isn't the best company out there, but it does look ridiculously cheap (PER of 6), even after today's rise.
Regards, Paul.
Paul, yes interesting situation. I was also thinking along your lines about management trying to either attract higher bids or failing that buy the company on the cheap. Although, as dangersimpson points out above, only the chairman has a significant holding and not the CEO and CFO, so in the event of a counterbid being successful only the chairman would benefit.
Now here's the ultimate question - what do you think would be a realistic maximum price to expect a bidder to pay? Do you agree with me that Panmure's 100p target is over the top?
And a big thank you for highlighting this share recently, which prompted me to buy. And indeed for all your write-ups, which are extremely helpful and educational. (Just a shame I hadn't come across this blog before buying Globo...)
Oh and another reason that other bidders should hopefully emerge - the management know the business the best and if they want to buy it for 42p then obviously everyone will deduce that it must be worth more than that.
Very interested in hearing your thoughts on the current state of the market, Paul, thank you for that. I am approaching the climax of my first year in trading and reading predictions from both bulls and bears leaves me full of elated terror.
Something I have been pondering, which I haven't seen addressed anywhere, is how a crash might manifest in modern times. Technology has moved in leaps and bounds since then, along with trading behaviour. News travels faster than ever before and potentially calamitous events which may have previously unsettled the market for months seem to recover fast (ie Brexit, Trump).
In addition, the popularity of day trading / spread-betting and the like has increased a lot since 2008 which would have an effect on the markets, good and bad. Could this lessen or worsen a crash? Would it dive further down or recover faster? All questions to which there are no definitive answers, but certainly ones to ponder.
I was very interested to read an interview with Warren Buffet who, when asked about the current bull market couldn't see much change all the while interest rates are so low. With banks and bonds adding very little value to savings, a lot more people are placing their money in the stock market, if not with the buying and selling of shares, but through investing in funds.
Lots of food for thought!
Hi Paul
Do you have any thoughts on the Interquest RNS just before the close?
Any thoughts on Gulf Marine Services Paul LON.GMS ?
Zytronic (LON:ZYT) have a long history in ATMs and have provided NCR with screen for 10 years. they also provide screen to Diebold (used to be Nixdorf for those who remember those ATMS)
25% of their revenue is generated in South Korea , think that is with a forecourt/outdoor vending company.
they have loads of small projects and concepts on the go.think MSFT is one of those
Hello all, there's been an announcement from Interquest (LON:ITQ) at http://www.investegate.co.uk/chisbridge-limited/rns/statement-re-recent-share-price-movement/201705161551053313F/ - it looks like management are trying to buy the company on the cheap (just 42p plus the soon-to-be paid dividend of 1p) - what do people think? Could they get away with offering barely more than the share price and how likely is another bid?
Almost no premium bid for a MBO on Interquest (LON:ITQ) close to the all time low share price is a bit of a joke. You really have to question who the management have really been working for for the last year or so.
Ashworth hold 33% but CEO & CFO next to nothing. So guess he could block another bid but he would be hard pressed to reject something at say 60-70p when he has tried to argue that 42p is a fair price for him to pay. In fact I think he has shot himself in the foot with such a lowball initial bid as it puts the company in play but at a level lower than the long term value in the company once they sort out their current problems and he can no longer block it and keep his reputation.
At least the Non-execs seem to have some character:
http://www.investegate.co.uk/interquest-group-plc--itq-/rns/response-to-chisbridge-announcement/201705161620113362F/
That the market reacted positive to the non-execs rejecting the bid just shows how crazy 42p was.
Thanks for response, I would tend to agree with the bulk of what you say. Although in the event of a counterbid I suppose they could also increase their own bid until they either bought at a higher but still cheap price or sold to someone else for a non-cheap price and well above the current price, so either way they would be doing OK (that is Ashoworth would, as a shareholder).
Panmure set a target price of 100p in March when the price was 36p, they wrote "The rating shows investors are not recognizing the recovered earnings potential of the group. Management are taking the appropriate corrective action and they simply have to deliver on near term forecasts for the shares to deliver significant upside." 100p is a nice thought for holders like me but probably overly optimistic. Either way, hopefully it will end well and I will have Paul to thank once again.
I would be grateful if someone would clarify: if they make a bid, would Ashworth be able to use his 33% to vote for accepting the bid even though he is also one of the bidders? Doesn't seem fair if he could as obviously it makes it easy for him to buy the rest of the company at too low a price.
dgold
It looks like the independent directors and the broker Panmure Gordon say they cannot recommend the MBO vehicle's offer for Interquest, as it undervalues the Company.
Bit odd that the management thought they would get it away. It does not seem as if there has been a big rally in the share price recently, looking at the charts, but perhaps slightly bullish markets have chipped away at the premium they thought they could achieve over market price.
Lots of conflicts and mixed motives arise in a management which wants to bid for a company e.g. did they make it underperform to get it cheap etc? So its a tricky area for all concerned.
Thanks. Your sale was prescient!
I don't think the Water Intelligence results were all that bad bearing in mind that the company is continuing its multinational growth strategy into what are enormous and expanding markets. However, never a good idea to disappoint markets although I have noticed that Water Intelligence shares seem to go up and down by 5-10% on no news so perhaps an overreaction to the results is to be expected. I guess this is the downside of holding an illiquid, low profile microcap. I notice FinnCap increased its share price target to 144p today, for what its worth. I am happy to hold for more ups and downs because the company appears to have access to intellectual property and technical expertise which may enable to it to grow significantly and it already has a significant presence in multiple markets and is definitely a credible operation with some major customers. I am also personally aware of how water leak reduction has significant financial impact on water companies, at least in the UK, as it is an important performance indicator and my recent contact with a senior member of management at our local water company has confirmed this. Perhaps one downside is Water Intelligence's apparently complicated business model as the company is addressing retail, commercial and public utility markets, in some cases with services, products and franchises, but I guess this provides plenty of avenues for growth. I would class this as an unsual AIM listed company because of its roots in the US, but, as we have seen with Somero Enterprises, Aim listed US companies sometimes turn out to be winners. Would be very interested if Paul could run his eye over the financial results as there seems to be plenty of detail given and as far as I can see, most of the figures are moving in the right direction and the company appears reasonably solid.
Hi Paul
Re: your comment
"So many smaller company shares are going through the roof at the moment."
I had the pleasure of reading Gervais Williams "The Future is Small" a couple of years back. An excellent read backed up with some pertinent stats. I took the plunge back then in a number of shares with many of the characteristics Ramridge outlined in comment no.11. Given how small caps have been moving in the last 12-18 months, Williams' writing has been quite prophetic.
Was the best tenner I've spent in a long time. Long may it continue!
Water Intelligence (LON:WATR) reported today. The market doesn't like it, but I'm not clear why.
It's because profits are down significantly against prior year figures. My calculations suggest full year profits decreased 17.63% on a constant currency basis. It also looked like Water Intelligence failed to manage the currency risk from foreign operations, so if you include Forex movements you're looking at 32.3% decrease.
So it looks like a profit warning!
Profits are down due to "one-time" costs relating to investment expenditure. Adjusting for these expenses results in an improved profit position but I guess the market didn't buy into it.
Disclosure: I used to hold Water Intelligence (LON:WATR) but I sold prior to the announcement because they didn't release their results when promised (they said it would be on the 9th May..)
Concerning market jitters, there is increasing chatter that a stock market correction or major fall is highly likely this calendar year. If you believe this, then there is a range of strategies you could adopt, from going cash at one extreme to just carrying on as normal on the basis that you are in it for the long term.
Personally I thought about it and decided to follow Gervais Williams advice that he gave in a presentation earlier this year. Basically any stock in your portfolio should have the following characteristics
1. shares with a very strong balance sheet
2. robust and above average profit margins. They need to take the pressure of falling margins in a downturn
3. companies which have a great reputation for customer delivery and customer satisfaction
4. cash generative
Over the past few weeks I have re-shaped my portfolio accordingly and in the process I have thrown out a few stocks. And as a Minervini follower, I am prepared to sell and go cash around 80% , at the first sign of trouble.
In the meantime, I am watching the canary in the mine more closely than ever.
Hi Ramridge,
I have been doing the same :)
Have you used the risk titles when reshaping your portfolio?
Another thing Gervais Williams does, at least in Diverse Income Trust (LON:DIVI) which I hold, is to own some insurance in the form of FTSE 100 put options.
AVON put out a good report today, though adjusted EPS was static, apparently due to the higher tax charge. Diversified between defence/emergency services (gas masks) and milking machines ! Anyone have any thoughts?
Fishcake,
Vodafone (LON:VOD) and Avon Rubber (LON:AVON) both reported today. Recently sold the last of my Vodafone (LON:VOD) and topped up Avon Rubber (LON:AVON) . Time will tell if that was a good decision but very happy on results (if not the relative movements in share price) today.
A local business, also struggling with his building being grade 2 listed and who has the same stream through his premises, is an agent for AVON (milking side, not a lot of demand for gas masks here in Wales!) He is positive. So am I.
Specific thoughts: On the results, increased pension contributions may not really be needed but still a wise use of profits, as well as increasing the divi by 30%. And in general, this has been a core holding for more than 10 years (perhaps 15?) Original (small) investment was on basis of gas masks and potential of attack in Tokyo around 2000 but the longer I hold the more I have bought. and (after sale of auto pipes, about 5years ago?) Avon Rubber (LON:AVON) became, by organic growth, my biggest by value, it got jumped by DP Poland (LON:DPP) and now by Treatt (LON:TET) but I do not have any plans to sell my holding of Avon Rubber (LON:AVON) though I do think market in general is now overpriced and it is time to sell something. But for me just not yet time to sell any Avon Rubber (LON:AVON).
Regards,
Seadoc
Zytronic (LON:ZYT) I thought the figures were much better than expected, after last years results which were a bit disappointing, I found +44% EPS to be surprisingly good.
Zytronic (LON:ZYT). The numbers were also better than I expected and, while N+1 Singer (NOMaD) did not change their forecasts, they indicated that the risk was now to the upside. The 44% EPS growth is flattered by the reduction in the fx hedging costs but I think it is still high teens growth without this. Zytronic has strong cash flow and an absurdly conservative net cash position - so a special div (especially after the recent capital re-organisation) or an acquisition can not be ruled out. My one concern about this stock is the concentration of the customer base (top 3 clients represent more than half of revenues), does anyone have a feel for who these customers are?
Yes I thought FX would be part of the reason.
Re clients: I believe Coca-Cola is one of the largest, Microsoft is also listed among their clients.
My take on Zytronic (LON:ZYT) was 'steady as she goes'
I didn't expect much price movement, more hoping it would support the recent rise than propel it to new highs.
My only concern was inventories being about 1/3rd of sales, and receivables the same. Not a big problem but does it suggest a certain 'sluggishness'?
Zytronic (LON:ZYT) much more positive news today and price action: nice bullish breakout to new highs
Of a similar view on the market run: the wall of worry seems to be non existent these days. It smacks of a blow off top . Every index is at an all time high while the Vix is at an all time low
I am taking some profits and moving to cash on a few positions , trading aggressively on others but still buying some laggards especially in the UK technology space where there is still good growth potential
GBP weakness was catalyst for UKX strength but the converse doesn't seem to be holding. . A healthy pullback is needed and overdue. 'tis the season after all .. St Leger's day and all that
Hi Paul, do you have time to give us your thoughts on £ZYT? I thin k you've covered them before. Looks like a great update, but SP has slipped back. I like to read about good & turnaround stocks in more depth than failing ones (though the details are juicy!)
Yes, I'll be writing a section about Zytronic (LON:ZYT) interims later today.
PP.
Hi Paul - It may already be on your agenda but if not I wondered if you would consider looking into Jackpotjoy (LON:JPJ) ?
The Naked Fund Manager (Reseach Tree) recently wrote an article on them which piqued my interest. They reported today so would be interested to know what you think. Looks like a mixture of a growth stock and a special situation based on high debt levels which they intend on reducing.
Thanks, Ben
Hi Paul
Probably not the day to ask if you have lots to cover, but noticed you put FEVR in your BMUS portfolio, any quick thoughts to add to what Graham & Damian have said about it on Stockpedia in the last week?
Best regards
Hi Ajay,
Yes, I read the discussion here about Fevertree Drinks (LON:FEVR) with interest.
In my view, the trading update yesterday wasn't punchy enough. It only said "comfortably ahead of current market expectations". To justify the current valuation, I think the company needs to be smashing forecasts, so I was hoping to see a significantly ahead of expectations update.
However, I'm not selling, as I think this is a unique company, with amazing figures.
What particularly interests me, is that I'm seeing FeverTree tonic being served quite often in bars & restaurants as the default tonic water. That surprised me at first, but then I thought through the logic. A lot of places want to present themselves as being a premium quality business. So what better way to do that (at minimal cost) than serving Fever Tree by default? That says to customers that this is a premium bar/restaurant.
For this reason, and the planned move into a much wider range of mixers for other spirits, I think this brand could still have plenty of legs.
Although the forward PER looks nuts, the broker forecasts seem way too pessimistic to me. So I'm expecting to see one or two more out-performance updates from the company in the remainder of 2017.
Obviously I'm kicking myself for not "getting" the Fever Tree concept properly, and being too cautious on valuation in the past. So I'm late to the party here, but have bought some personally (a middle-sized position only), and reflected that with a purchase for BMUS too.
All good, sizzling bull market stuff!
Regards, Paul.
This Company some years back decided to change its accounting reference date (it's year end), and in effect it had an 18mth reporting period instead of 12mths. In my person view this covered a hole in its operating profits for the 12mth period. The reasons given at the time for this change didn't convince me personally, but it could be argued it got away with it as the extra 6 mth period allowed some upside trading to be reported. They also highlighted the 18mth revenues as if that were growth rather than an extended period of reporting.
They recently suggested they might change its accounting reference date again (it was under review I believe). To me this signalled all was not well, and now events have caught up with it with the latest profit warning.
To me changing the accounting reference period is a significant thing to do and shouldn't be done lightly, as it significantly messes up comparative data.
I personally never really trusted their analysis again. I feel their new CEO has been sucked into a bit of a mess not of his making, and I would expect quite large write downs.
(RE K3 Business Technology (LON:KBT) )
This Company some years back decided to change its accounting reference date (it's year end), and in effect it had an 18mth reporting period instead of 12mths. In my person view this covered a hole in its operating profits for the 12mth period. The reasons given at the time for this change didn't convince me personally, but it could be argued it got away with it as the extra 6 mth period allowed some upside trading to be reported. They also highlighted the 18mth revenues as if that were growth rather than an extended period of reporting.
They recently suggested they might change its accounting reference date again (it was under review I believe). To me this signalled all was not well, and now events have caught up with it with the latest profit warning.
Good spot Trident and in fact they confirmed the change a few days ago (from June to November) and the previous change (2009) was from December to June.
In both cases the changes seems to me to be totally bogus (and conveniently timed to obscure poor results?).
I think Paul is right to read "review" as restructuring, redundancies and write-offs - and how will this play with a likely need for more debt to fund this.
It all looks train-wreckish to me.
27-March
"Board remains confident in Group's growth prospects, with delayed deals now starting to come through, and is focused on driving cash generation and further efficiencies"
16-May
"although the Company has seen some major deals close, certain large Enterprise contracts have not been secured as expected."
That's not totally explicit language, but I have to think that if these contracts have just slipped and are still winnable they would have said so.
"Nonetheless, the Group's operations elsewhere are seeing encouraging progress and healthy cashflows."
I'm not totally sure how to interpret "elsehwere" except that this is saying that existing contracts are delivering cash - shame that we don't have too many more of them coming on.
Can I borrow your bargepole? I don't think mine is long enough.