Small Cap Value Report (Fri 31 July 2020) - DTG, EMAN, HMLH, SAG

Good morning, it's Paul here with the SCVR for Friday.
Today's report is now finished.
Terrible publicity last night on the main TV news for Dart (LON:DTG) . Customers holidaying in the Canary Islands reported that DTG's Jet2.com had texted them, cancelling their return flights back to the UK, and telling them an earlier flight home would be an additional £300 each. The reason being that it wasn't economic for the company to send out an empty plane to bring them home. Whoever made that decision is a complete fool, and the damage to the company's reputation is likely to be far more costly than sending out empty planes because something has gone wrong with Govt rules, leaving people stranded. Airlines have a moral obligation to get people home, irrespective of cost.
Talking of airlines, BA's owner, International Consolidated Airlines Sa (LON:IAG) has said that it expects traffic to not fully recover until at least 2023. If they're right, then that surely makes all airline shares look uninvestable?
The on-off-on nature of travel restrictions really puts me off going anywhere near this sector, and that's being reflected in a lot of travel/retail/hospitality shares, some of which are now below the March lows e.g. Greggs (LON:GRG) - but it still looks expensive. Whilst others have reported spectacular rebounds in business, but still look cheap - e.g. Scs (LON:SCS) . So as ever, it's a confusing picture, tricky to navigate. For retailers, I think it's becoming clear that retail parks are recovering much better than town centres. Hence why a focus on companies mainly in retail parks is probably a good idea.
The news is full of stories about fresh covid outbreaks occurring in many countries. Not what we want to hear. It feels like this thing is going to be around for a while.
USA results season - I watched the 9pm onwards CNBC show last night, as several mega-cap tech companies were reporting earnings. Facebook, Apple, and Amazon, all smashed (lowered) forecasts, with big after-hours moves up. This destroyed my theory that the US market is poised to crash because earnings would fall short of forecasts. Therefore I've stopped shorting US indices. It reinforces the point that the US stock market is not the US economy. It's dominated by some of the best companies to have ever existed, with global reach because of the internet. If you have to pay 27 times earnings for a business that dominates its space, is that really expensive, in an era of zero interest rates? Arguably not. It looks like the dominance of big tech is likely to continue for some time to come.
.
Everyman Media (LON:EMAN)
Share price: 84p
No. shares: 91.1m
Market cap: £76.5m
Shares seem to have split into 3 groups due to covid;
1. Resilient, or even improved trading (e.g. some tech/internet businesses)
2. Impacted by covid, but recovering quickly, and impact only temporary
3. Severe impact, recovery slow & uncertain
A good strategy so far would have been to stick with category 1 above. The trouble is, those shares are so expensive now. Hence I'm generally looking for opportunities in category 2 (ScS yesterday was a good example), because they're cheap, and recovering well. I'm trying to avoid category 3 altogether. Cinemas seem to fall firmly in category 3. Who on earth would want to sit in a room, with lots of other people, and watch a film, and possibly be exposed to a nasty virus? If they space out the seats, would a cinema be able to make a profit? It seems to me one of the most obviously terrible places to invest. Also, with huge flat screen TVs now so cheap, you can get a similar immersive view at home, and maybe movies could move to direct-to-streaming, or people just use Netflix instead? I see big structural challenges for cinemas in this regard. I hate going to the cinema, as the experience is ruined by constant rustling of sweet papers, and people coughing, using their mobile phones, etc. . But I despise the uncouth general public mostly, so perhaps I'm not typical?
The upside case relies on the virus being completely eliminated, which is looking a tall order any time soon.
Everyman did a placing, raising £17.5m at 100p per share (a 7% discount at the time) in April 2020 - a sensible move, to raise money early during the pandemic, to shore things up.
Looking at its last balance sheet, at 2 Jan 2020, net debt was fairly modest at £9.8m, so ignoring any subsequent capex, the placing should have at least cleared all the bank debt. Lease liabilities are substantial though. That's not a problem if sites are operating profitably, but since all closed sites will be loss-making, then the lease liabilities would be a millstone now. Quite possibly locked in to uneconomic rents now, if revenue settles at a lower level than pre-covid.
Today's update -
Everyman along with all other cinema operators closed its doors in the middle of March. All venues remained closed for the rest of H1 with no further revenue from that point until 4 July.
Our banking partners have been supportive with appropriate changes to the covenants on the Group credit facility, and the Group will remain within its banking covenants in H2 and beyond.
That sounds OK. Although in my experience, banks are highly averse to funding losses. Therefore if its cinemas have to close, or continue operating at a heavy loss, then the bank probably won't want to cover those losses through a borrowing facility. Therefore, another placing might be necessary if trading doesn't recover.
During the period of closure all but 18 staff were furloughed, and further government support was received in terms of rates relief and the Retail, Hospitality and Leisure Business Grant. In addition, the reduction of VAT from 20% to 5% on admissions and certain food and beverage items will benefit the business in H2.
That's a lot of support from the taxpayer. The VAT reduction is a particular boost, not available to other sectors.
Rents -
Property costs are the second largest overhead in the business and Everyman has worked with all of its landlords throughout the period to agree variations to the lease agreements. Concessions have been agreed on over half of the estate, and further discussions are still ongoing.
"Concessions" may just mean more time to pay - e.g. monthly instead of quarterly payments? I doubt many landlords would reduce the contractually agreed rents - why would they? The only reason to do so, would be if the tenant were about to go bust (not the case here), or if a lease was coming up for expiry, which is usually the only time that landlords think about rent reductions, as the alternative is an empty unit.
New sites - I would have expected this to be zero. But the company is planning on opening 8 new sites, down from 11. That strikes me as very odd. Surely at a time like this, it would make sense to halt all expansion? Possibly there might be signed contracts that make it uneconomic to pull out, but that would be a key question I would want to ask management. Why open new sites, when the future is so uncertain?
Re-opening - 17 sites have started trading;
Whilst current trading has inevitably been soft with no major releases, encouraging numbers of customers are returning. This validates the strength of the business model, which is well positioned to take advantage as the sector recovers. The Group has a strong balance sheet to support its activities during what is expected to be a restricted trading period in H2.
No figures given, so one person's "encouraging" may not be another's.
My opinion - there's not enough information in today's update to enable me to take this any further.
With a second wave of covid seemingly underway, in the UK and abroad, I'd be surprised if cinemas are allowed to continue trading. For that reason, I don't see any attraction to this share. It would need to be a fraction of the current price, to make risk:reward attractive to me. Why pay up-front for a recovery that may not happen?
.
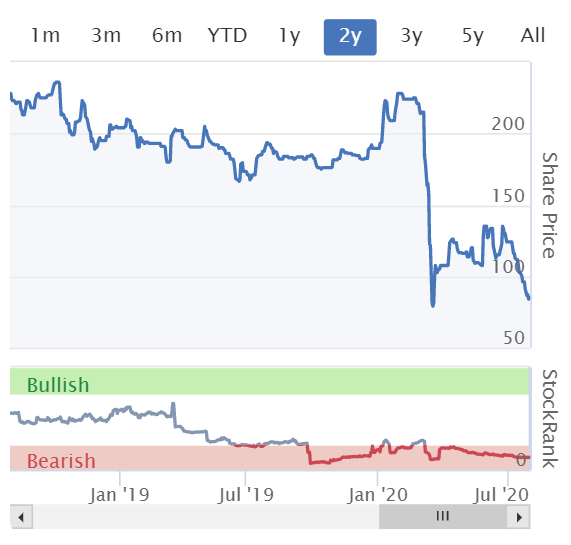
.
Hml Holdings (LON:HMLH)
Recommended offer at 37.5p
Announced yesterday, this offer looks reasonable to me, and provides a cash exit from a disappointing investment.
The bidder is Harwood Capital, which is a very shrewd investor, headed by Christopher Mills. He's an excellent stock-picker in my opinion. The trouble is, he often takes big stakes in small caps, and if he likes them, bids for the whole thing, often at a low valuation, forcing out private investors. Therefore it's a double-edged sword following him into particular listed companies - we might make a bit of a profit, but if there's big upside, he'll grab it for himself.
In this case, I think a lot shareholders in HMLH will be glad to take the money, and let him have the company. It was meant to be a buy & build, in the property services space, with operational efficiencies building from growing scale. A series of acquisitions were made, leading to an increasingly top-heavy balance sheet with a lot of goodwill, but profit didn't seem to budge much. So the failure to gain traction with acquisitions, meant a falling share price, hence difficulty raising equity for more acquisitions. Therefore the stock market listing, and all its costs and hassle, didn't make sense. I don't rate management here, given their lacklustre track record.
HMLH is far better suited to be a private company. Watch it probably come back to the stock market, in 3-5 years time, with new management, and having made some successful acquisitions, and priced at 10 times what Harwood buys it for!(speculation on my part, but it's typical of what Harwood sometimes does, and good for them I suppose)
.
Science (LON:SAG)
Share price: 239p
No. shares: 41.5m
Market cap: £99.2m
It's too hot to even think today in London, 33oC. I was hit by a wall of heat, stepping out of my bedroom after my mid-morning nap (I hate 7am starts!). But I did half-promise a reader that I'd look at SAG, so we'll round off with this one.
Science Group is an international, science-led services and product development organisation with a significant freehold property asset base. Following the Frontier acquisition in 2019 and an organisation restructuring, the Group now comprises three operating divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies.
The group sounds pleased with its H1 performance, helped partly by the acquisition/merger of Frontier in Sept 2019. Checking back through older announcements, Frontier seems to have been a sort out job, with its premises being shed, and operations moved to SAG's large properties (which look like stately homes with modern units built i the grounds, judging by aerial photos on the internet). It also brought with it large tax losses. Looks quite an interesting deal, and it has moved back into profit due to the cost cutting, as planned. Nice to see SAG management able to execute on a deal which required some sorting out, adding value.
Adjusted PBT of £4.6m in H1 (up 59% on H1 LY) - helped by the acquisition of Frontier. It's not clear what organic growth is, but seems to be much lower at 13-15%
Adjusted EPS in H1 is 8.8p, or 8.5p adjusted, up very well from 5.9p LY
Odd structure, with freehold properties, which it says are worth more than book value. £22.6m to £33.9m recent valuation. Partially offset by property debt of £17.1m, annual interest charge of £0.4m is much less than the likely rent, if they were leased. So I like this structure. Also, if you own freeholds, you don't have to worry about upward only rent reviews, that are the undoing of so many companies. This is an old fashioned structure, but I like it.
No divi for now, but sounds like they might pay one later.
Share-based charges seem a bit warm, at £0.7m this half year, and £1.17m last year.
Balance sheet overall is OK, but not amazing. NAV: £39.1m, but that includes £26.5m intangibles, and £4.1m of client funds, which I would deduct, to get £8.5m NTAV. The main reason the balance sheet looks better than £8.5m NTAV implies, is because trade creditors is very large, at £23.9m. I suspect that probably includes a lot of deferred income (where clients pay cash up front) maybe?
My opinion - this is only a quick review of the H1 numbers, I'm not claiming to know the company well.
I very much like that it seems to have sailed through the covid crisis, and still produced excellent H1 figures. Plus I like that it has spare cash for more acquisitions. The unusual freehold/debt combination is interesting.
Overall then, it looks like something that readers might want to take a closer look at. I can't see anything wrong with it anyway!
In summary, the performance of the Group in the first half of 2020 has been ahead of the Board's pre-Covid-19 expectations, despite the operational challenges resulting from the pandemic. The excellent first half provides a solid platform for the rest of the year.
While actively recruiting for key roles to strengthen the Group and to position the organisation in a post-Covid-19 world, the Board recognises the inherent uncertainty and lack of predictability in the months ahead and will therefore remain prudent. However, with a strong balance sheet including significant cash resources, the Board continues to cautiously explore both add-on acquisitions and larger opportunities to increase the scale of the Group.
.
It's far too hot to do any more work today, so I shall sign off & hope you have an enjoyable weekend.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
What is going on? FTSE down 3% yesterday. 2% today.
Are we going down again like in February/March 2020?
It seems the politicians and media are causing the panic by over-reacting to the bug but they don't realise the immense destruction a deepened recession will cause.
I've been buying shares to hold today picking IG Group (LON:IGG) , International Personal Finance (LON:IPF) and a short term position on XLMedia (LON:XLM) .
IG Group (LON:IGG) has figures on the 18th September, ex-divs a 30p Dividend on 22/10/2020, and has been promoted to a StockRank of 99, Broker Target +8% now she has fallen back.
International Personal Finance (LON:IPF) has a trading update next week, has fallen back to 54.6p having been robust against other shares today. International Personal Finance (LON:IPF) has a PE Ratio of just 5.24, Dividends suspended, a (V)alue score of 97, and its last trading update was positive and COVID crisis/recession conscious. This was once a 200p share. I think they will get their crown back. Stocko shows IPF with a 325% broker target, most indicators in the green. ROCE of 11.1%. LIKE!
XLMedia (LON:XLM) . This is a "trade" (no apologies). This share falls to about 23ish p. The Mitterrand family then buy a large tranche about once a month, usually on a Thursday at about 1530 when no one will notice, the price tends to elevate to about 28p. Then the news fizzles out, it falls back. XLM has a price target of 95 cents (about 70p) and was once both a StockRank 90+er and top of the Magic Formula scores. If they turn this company around, I am looking to see this double up. PE of just 2.8. They made a paper loss in their last figures due to right downs but are arguably cash generative with cash in the bank and a restructuring plan being implemented.
CFDs, Loans, Gambling - filthy businesses that people want in recessions and lockdowns.
(Apologies for my bad phrasing. I am badly dyslexic.)
I agree with your comments about cinemas and the uncouth general public, "the Great Unwashed". As for the heat you might want to invest £600-£700 in a proper split system (i.e. not the 'portable' type) air-conditioning system, set the temperature between 16-30c to suit and sit back and enjoy. The outside unit can be walled mounted so suitable for flats if that's what you have. Can be installed DIY but get one at least 12000BTU rating.
https://www.amazon.co.uk/12000-Easy-fit-Inverter-Conditioner-Meters/dp/B089DLYGCY?ref_=Oct_s9_apbd_omwf_hd_bw_bKlq07&pf_rd_r=8Z0DJCGMPQHX6XGH576E&pf_rd_p=7cb2c7a4-7247-513d-a444-78e99aacf529&pf_rd_s=merchandised-search-10&pf_rd_t=BROWSE&pf_rd_i=306928031
or
https://www.amazon.co.uk/18000-easy-fit-Inverter-Conditioner-meters/dp/B0198TKFP8?ref_=Oct_s9_apbd_omwf_hd_bw_bKlq07&pf_rd_r=8Z0DJCGMPQHX6XGH576E&pf_rd_p=7cb2c7a4-7247-513d-a444-78e99aacf529&pf_rd_s=merchandised-search-10&pf_rd_t=BROWSE&pf_rd_i=306928031
Also, with huge flat screen TVs now so cheap, you can get a similar immersive view at home, and maybe movies could move to direct-to-streaming, or people just use Netflix instead?
This is exactly what has been happening during lockdown. Films have been released directly to Netflix, Amazon and Curzon Home Cinema etc.
There are some films which are made for the big screen experience though and some releases have been delayed - TENET (directed by Christopher Nolan) and the new James Bond are examples of this. (I can't wait to see TENET!)
Housebuilders / Estate Agents etc.
I work for a firm of solicitors, and I think about 45% of our revenue is conveyancing. This has really picked up after the Stamp Duty announcement and our conveyancing team have been working flat out for weeks. Today we have had over 25 completions (sale/purchases) and we are flooded with inquiries. This is a positive sign for the housing market - my only concern would be if people are deciding to bring forward their plans to buy before this government scheme finishes in March 2021?
Eat Out to Help Out
I'm really looking forward to taking advantage of 50% off food and non-alcoholic drinks between the 3 August and the 31 August. (Monday to Wednesday, up-to £10) You can search the government website by postcode for participating pubs, restaurants, cafes etc. Most are included (it's a no-brainer for them !) - I already searched for Bray but unfortunately the Fat Duck isn't included yet but then again £10 doesn't go very far there!!
Have a good weekend all.
@BenSharman
Paul, love your honesty! "It's far too hot to do any more work today, so I shall sign off".
I'm going to try this approach with my office; although, I don't think it will work quite as well... :)
Thanks for a great week of reports!
Well, I am freelance! I could never be an employee ever again. I'm cheerfully unemployable :-)
Hi Paul
Thanks for your thoughts on Everyman Media (LON:EMAN)
In case you or anyone else is curious, you can take a look at Box Office trends by country at boxofficemojo.com. Below is the link to France, which looks about 20% of normal levels for this time of year:
https://www.boxofficemojo.com/weekend/by-year/2020/?area=FR
I actually can't wait for cinemas in my area to open. With screens between seats, online only ticket sales and cleanings between screenings, I see no reason why capacity can't return to a reasonable level and losses minimised in the short term .
I've had a pretty good year so far so I have taken very 4-5 small punts on out of favour companies, including Everyman Media (LON:EMAN) , which I believe have enough cash to survive for at least a year and which might rocket if/when things return to normal.
I only need 1-2 of my punts to make it to the "end", whatever that might be, for this to be a profitable strategy. And if things do return to normal quicker than expected, then I'll have 4-5 multi-bag winners.
Fingers crossed.
A
I'd far rather go to the cinema in a relatively controlled environment to watch a film like Tenet than go to a pub where any sort of social distancing goes out of the window after three pints.
Hi,
Sorry for a silly question but what is the difference between a
RNS
BUS
EQS
GNW
PRN
Cheers
RNS is published by the LSE. The others are authorised rival services, an attempt to break the monopoly.
The Intercede phenomenon perhaps a realisation that some UK tech stocks are still very good QVM and that there is no reason why they cannot follow the Icarus FAANG stocks to the sun!
Hi Jim,
I think there's more to it than that. If you work through the numbers, with Intercede (LON:IGP) it's moved into profit, and when the convertible loans disappear in about 18 months time, a substantial interest cost per quarter will disappear, thus moving profits up materially.
Bolt on a few new contract wins, at very high gross margins, and the figures could look really good in a couple of years' time. Meanwhile the existing, recurring & repeating business covers the overheads.
How many other tiny AIM companies do you know, that are winning 10-year contracts with the US State Department?
Regards, Paul.
Smartspace Software (LON:SMRT) has done a deal with Softcat. Looks positive! Strange timing of rns.
Per the BBC: The PM's COVID briefing that just ended announced that "Venues that had been due to open tomorrow will not do so until at least 15 August. These include bowling alleys, skating rinks and casinos, Boris Johnson says. Changes to wedding celebrations will also be postponed, he adds."
Hi Paul
Just to say, I really like your categorisation. Generally speaking, I was trying to identify and buy the 1s during April/May (e.g. Avast (LON:AVST) £JIM). I have then been adding a few 2s during June/July (e.g. Games Workshop (LON:GAW) £ULS) as more info has become available. And like you, I have been avoiding the 3s completely. I’m sure that in the fullness of time there will be some excellent recovery plays in this category but from my perspective, it is too early to say which ones.
It’s great to have you back in full swing. Enjoy your weekend!
Cheers
Simon
P.S. Timar’s COVID lockdown thread really helped with identifying the category 1s back in April/May. I’m not sure I ever got round to saying thank you for that thread, so Thank You timar and all those that contributed!
"But I despise the uncouth general public mostly". Snap. I've noticed a darker tone to your commentaries of late, Paul. I think you're getting grumpy before your time, but welcome to the club.
Paul, this is off topic but please can you tell me the name of the small stockbroking firm you cover with the catchy name that I can't remember?? Thanks in anticipation, Charles
Hi Charles,
I can only think of Cenkos Securities (LON:CNKS) and Finncap, that I've covered here.
Regards, Paul.
Does anyone know what as caused the high volume and hence rise on Strix (LON:KETL) today, I can see nothing on the news and was wondering whether there was things on other bulletin boards that I don't follow, or whether someone has tipped or something?
I hold.
Thanks Tommy
Re: Strix (LON:KETL) (I hold) - I try not to pay too much attention to such things but it looks like it was triggered by a 1m shares trade early doors. I would guess that was an institution (either new or one upping their stake). There is no other news that I am aware of other than a promising trading update last week (institutions are often slow to react to such things which becomes more prevalent in the mid cap space).
Cheers
Simon
"Talking of airlines, BA's owner, International Consolidated Airlines Sa (LON:IAG) has said that it expects traffic to not fully recover until at least 2023. If they're right, then that surely makes all airline shares look uninvestable?"
Is there an argument here to say that depending on your strategy and longevity to the portfolio, that long term, they 'could' yield positive results given the entry level of most of these are prices from 4-5 years ago?
But how do you value the shares? Looking back isn't much help. There must be a case that it wont survive in its present form, e.g. it will be nationalised.
Yes IMO, provided that the company can "hold out" for that long. If you buy in now, S-Hers may expect dilution via potential future new share issuances.
Such a strategy may apply to more financially robust behemoths who have ample cash net assets, to name a few, e.g. Barclays (LON:BARC) , Natwest (LON:NWG) , £RDSB. i.e. Buy at a bargain and bet on the UK/world economy to eventually flourish. Short term wise, you may be wincing. Ultimately DYOR.
P.S. You may want review how the blue chip stocks that went through 2008 crash behaved, although there is no guarantee that this time will be the same.
Hi Paul,
Just a reminder that you said you'd look at Science (LON:SAG) today if you got a chance :-)
Thank you!
It was a struggle, but I covered it today! :-)
Does anyone know why Begbies Traynor (LON:BEG) went down so much yesterday and have shot up today?
It was IG index taking out my stop loss :-(
I am assuming that there were a lot of folks with a Stop Loss at £0.90 and one sale below that triggered a mass dump. I had stop lossed out at £0.95 earlier in the month protecting profit (small) and was watching to buy back in again but saw the email on the downward spike only after market close and should I just bought on open this morning at £0.89 but was waiting to see what happened and obviously missed the opportunity...
Ref: Begbies Traynor (LON:BEG)
The behaviour on Thursday seems very odd. It slowly drifted down to 88.8p, then there was one mysteriously low trade at 85.2p and the closing price was listed at 85.2p.
This is already my largest holding and despite not having topped up since 2017, I made a few checks just to make sure I hadn't missed anything, with a view to buying a few more. Of course, 85.2p was not on offer and now it's all the way back up to 94.6p.
The turnover of the business seems likely to increase drastically in the next few months.
EDIT: No matter how many times I resize the image down, the board software cuts the right end of the graph off. So I lashed it in below.
Massive own goal from Jet2 and Dart. One of the worst examples of incredibly bad customer service ever. Mind boggling. Looks like a few holidaymekers will be taking extended holidays then .
Just wonder if its true or a misunderstanding. For example if you want to return earlier you pay the £300? I haven't got any shares but Dart are quite highly thought of as an airline.
Interesting announcement this am about Beximco Pharmaceuticals (LON:BXP) not reported on Beximco RNS or news. They have set up a PPE Industrial Park in Bangladesh aiming to become a leading player worldwide in the production of PPE. They are working in a strategic partnership with Intertek (a 7 billion value PLC) including a PPE Quality Assurance laboratory. https://www.stockopedia.com/share-prices/intertek-LON:ITRK/news/urn:newsml:reuters.com:20200731:nRSe7352Ua There was also a previous connected announcement in May of a mask making factory being set up in Detroit USA by Beximco https://www.bloomberg.com/news/articles/2020-05-27/detroit-to-get-bangladeshi-investment-for-plant-to-make-masks No financials in the announcements except $20 million being invested in the Detroit mask factory (I hold)
Is this Intertek tie up with the original Beximco (Bangladesh Export Import Co) or Beximco Pharma?
Yes it is. So sorry I thought they were part of same organisation but it seems not.
Could it be that Jet2 introduced some new terms and conditions into the deals they offered just recently to allow them to do this?
I would expect that legal have been heavily consulted and they will use the normal travel clause (Beyond our control - War, pestilence etc) as HMG has just advised against ALL TRAVEL TO SPAIN and their islands. Sounds to me like that is your travel risk
I am wondering if you have any thoughts on Begbie Traynor (LON:BEG) and why the price is so low. He says this after being stopped out yesterday, but the fundamentals and outlook look good.
I got stopped out as well.
Hi Malcolm
Second thread, I stopped earlier due to the previous spike down and had been watching the slow downward trend with a mind to buy back at £0.90(ish) having bought and sold a few times over the last couple of years.
I think there are a large number of folks looking for story shares so hence buying on news and then things just trend downwards as they get bored and book a loss trying to find the next instant profit.
My thoughts, though I missed the opportunity myself, was that a lot of folks at Stop Losses set at the £0.90 value and one trade below that caused the spike down. I do wonder in part if the market makers did their bottom fishing trick of seeing if they could trip the stop losses by pushing through a trade below that.
No real variation on the volume this morning so just feels like the makers are slowly pushing this back up again and booking their nice profit.
I don't hold, but should...
Tommy
Thanks Tommy - makes perfect sense your explanation.
Spot on Tommy.... I hold but the share seems stuck around the 98p mark. It dropped along with most shares yesterday but has recovered.
Why on earth would you use a stop loss on a steady share like Begbies Traynor (LON:BEG) ?
You're just setting a target for day traders & crooks to trigger.
Firstly, many thanks Paul for your efforts and willingness to share. It is much appreciated. I was lucky as my trigger for BEG was set low, but I've been caught out more than once when sudden dips have triggered stops. As a newby investor I've followed the advice and have set stops taking into account volatility, but, while I'm often over cautious, when I review my former holds I find few have recovered to former levels. In some cases these are highly rated and producing good results, yet languishing out of favour., making the job of picking winners that bit more difficult. Still, as I used to say to my team members "If this was easy they could just get monkeys to do it then we'd be out of a job". Enjoy your weekend!
Setting stop losses isn't THE advice, rather it's one of the versions of the advice. With investing, there is always plenty of completely conflicting advice.
Some people use stop losses. Others never use them. I've never used a stop loss for a long position and have no plans to ever use one.
As far as I know, some of the more accomplished investors like Warren Buffet also never use them.
And some of the more accomplished investors do use them.
Jonesj - stop losses.
I'm also not a fan of "retreating". If you Stop Loss you are effectively taking three times the risk. I, to initially buy, 2, to sell at the right time (potentially either too late, too soon or to miss a rebound), and 3, you then have to take another risk on a buy.
If your shares buys are based on a rational and hypotheses (be it StockRank, Data, expectations), this is surely stronger than short term issues.
A lot of people missed the April 2020 rebound.
I am a fan of "doubling down" and backing my good shares that have revealed more value and opportunity.
Morning Paul, Excellent analysis of the macro and bigger picture as usual - Small query re £DART.
The stories I have read seem to imply that the operator is suggesting they have to bring people home early (At no cost). SHOULD they wish to remain they will have to BUY ANY AVAILABLE FLIGHT Is this where the £300 comes from?
Shove a camera and mike is Joe Bloggs face and you eventually get a sound bite to broadcast
In essence from a commercial point of view - ANY booking of a Holiday, restaurant, concert etc being made NOW will have an ongoing risk that later circumstances (Local lockdowns etc ) MAY impact delivery
Like the markets its all about your appetite for risk
Your view on the Bigblu Broadband (LON:BBB) sale would be interesting
I've no opinion on that, sorry.
What does ATOL think of this? And Dart (LON:DTG) was doing so well before Covid.
I'm really surprised to hear this about Jet2 as they're usually very helpful. I had a holiday booked with them which was then cancelled due to a revised flying schedule and I had a full refund within 10 days.
"If you have to pay 27 times earnings for a business that dominates its space, is that really expensive, in an era of zero interest rates?"
Yes. Because a PER of 27x is an earnings yield of 3.7% with some prospect for growth. Or I could hold 10 year Treasuries at 0.55% with some prospect for death by inflation.
My answer to that question is that it all depends on rate of growth of EPS that you expect to see in future years.
Doesn't it also depend on the discount rate that you apply? And if the rate on a 10 year Treasury Bond is 0.5% wont that change the valuation of the share?
Yes I agree it does also depend on interest rates. However, I am unable to predict them, so always only use the current interest rate.
Thanks for your post because it has reminded me that I need to check interest rates much more regularly.
The 10 year Treasury Bond has a PE of 200. Makes Amazon look a bargain. Maybe not £TSLA?
Presumably you mean "No, they are not expensive" at least compared with Treasuries? I would agree with that.
Did you mean "no", instead of "yes"? Looks that way, so I understood your point.
My morning smallcap tweet:
Bigblu Broadband (LON:BBB) Physiomics (LON:PYC) Vela Technologies (LON:VELA) Everyman Media (LON:EMAN) Oncimmune Holdings (LON:ONC) £SOL, YouGov (LON:YOU)
Bigblu Broadband (BBB) to sell UK and European satellite broadband ops for £39.3m (max). Reason "to crystalise an attractive return on invested capital with respect to the Sale Companies, reduce net debt and also to provide additional financial flexibility to support the further progress of the Continuing Group." BBB's remaining operations will consist of its Australian ops, its majority interest in Quickline and its Nordics business.
Physiomics (PYC) wins contract for a modelling project involving Physiomics' Virtual Tumour™ immuno-oncology model worth c. 20% of FY19 rev.
Vela Technologies (VELA) proposed rescue recap. Includes £1m placing at 0.024p, a 66% discount, £550k bond con version and asset sales.
Everyman Media Group (EMAN) cuts new cinema openings to 8 from 11. Admissions since reopening are at 'encouraging levels given the scarcity of new content currently." I'm not terribly encouraged by that.
Oncimmune (ONC) publication of the study that shows detection of lung cancer using its blood-based biomarkers demonstrates a 36% reduction in later stage diagnoses of lung cancer. "This publication will unlock discussions with a number of health systems on implementation."
Collagen Sol (SOL) FY(Mar) rev rev down 1% to £4.46m. Q1 rev £0.9m. Comparative?
In line: YouGov (LON:YOU)
I completely agree on Dart and Jet2.
I was watching thinking “Can they do that?” and “What’s the point of booking a package if they do that to you?” and “The passengers would be treated better if the airline went bust”
Plus of course the Spanish islands are safer than the UK.
I'm pretty sure cancelling flights and advising passengers the alternative is £300 extra would be illegal. As will no doubt be established.
I hadn't seen this story. I had also been under the impression that Dart were a very well managed company, so wouldn't expect them to take action that would damage their reputation and not actually raise any revenue (since they will be forced to refund the money extorted).
Maybe the way it was reported on the BBC news was incorrect. If so, DTG should have been able to clarify things to the BBC, who undoubtedly would have contacted them for an explanation. Either way, it was terrible publicity for DTG.
Also, why no clarification re media comment RNS from Dart (LON:DTG) today?
On Christopher Mills he is a very shrewd investor. NASCIT is the best way to get exposure to his deals in my view and it has an excellent record.