Small Cap Value Report (Fri 5 July 2019) - Monetary Madness, CHH, LVCG, FST

Good morning!
Today's news flow is not particularly exciting, so why don't we have a quick roundup on markets in general?
The FTSE-100 has had a rocket under it since the beginning of June (this is a two-year chart):
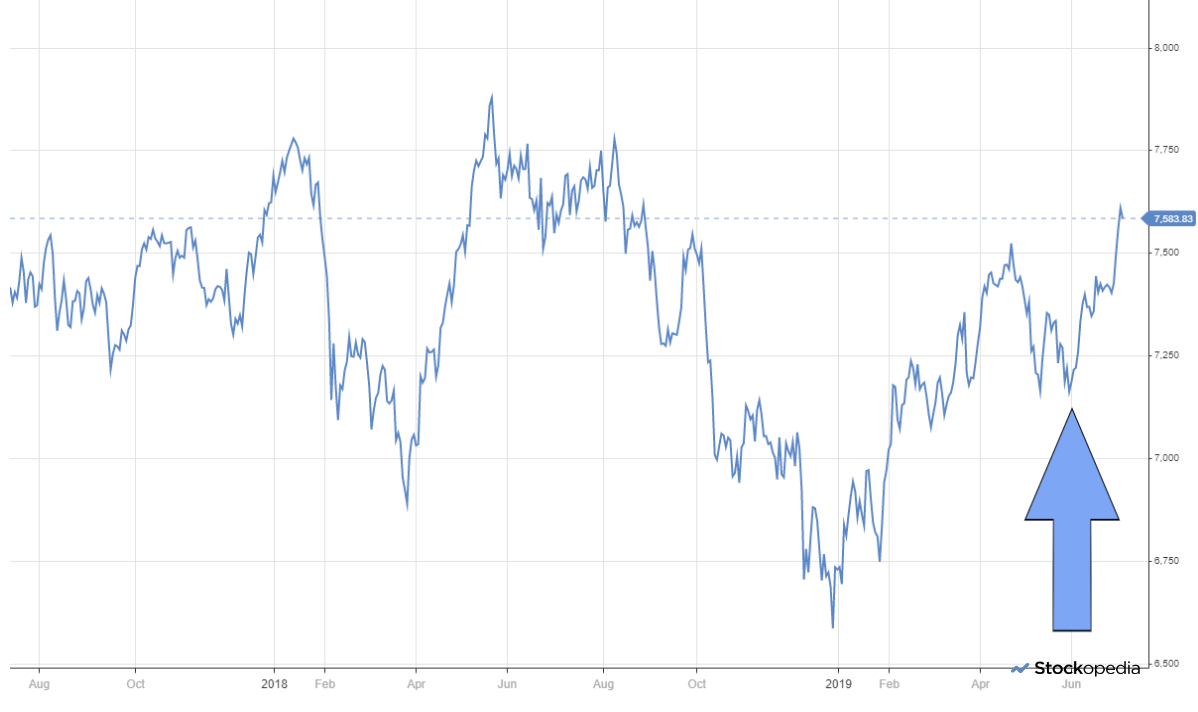
As you can see, we are stll belows the highs of H1 2018. But for how much longer?
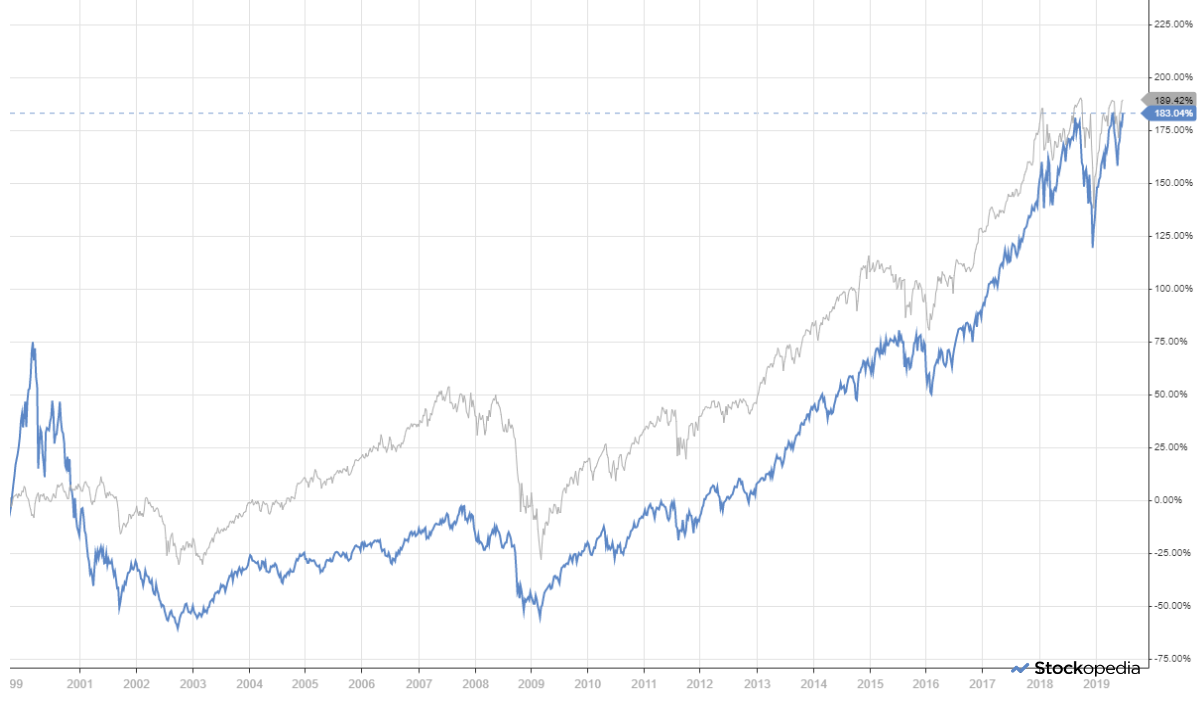
Other equity markets have been creating all-time highs. Here are the long-term charts for the Nasdaq (blue) and the Dow (grey):
One of the hedge fund managers I follow (thanks to his Tesla-related efforts) is Mark Spiegel. I should acknowledge that since inception in 2011, his fund has underperformed the major stock market indices.
But it has been a horrid era in which to run a long-short book, and Spiegel loves shorting: his fund is currently "very net short", according to his June letter!
The reason I mention him is that he has identified the Russell 2000 Index as "the most overvalued of all stock indices". This is the subset of the Russell 3000 (the top 3,000 publicy-traded US companies) that excludes the top 1,000. So we could think of it as a mid-cap index, a bit like the FTSE-250.
According to Spiegel, this index trades on a trailing P/E ratio of 35x, and 35% of its components are unprofitable! Those are quite amazing numbers (at least to me) and they suggest that the overvaluation relative to traditional metrics extends far beyond the FAANGS. So I remain extremely cautious about the valuation of US markets.
Turning closer to home, I'm becoming a lot more comfortable with the valuation of the FTSE.
The FTSE All-Share Index, for example, is on a trailing P/E ratio of 14.6x, while EPS growth of 3.2% is forecast to increase to 8.1%.
The FTSE does not have as many exciting growth companies as the US markets do, but I do think it can serve as a stable source of value.
Indeed, I've been picking up a little bit of extra income this year by making regular long bets on the FTSE. In the last few weeks, however, I've been cautious about placing any more trades - I've been comfortable doing it around 7100-7200, but am more reluctant with the market at 7600. Given the change in the interest rate outlook, and the apparent undervaluation relative to US markets, perhaps I should keep going?
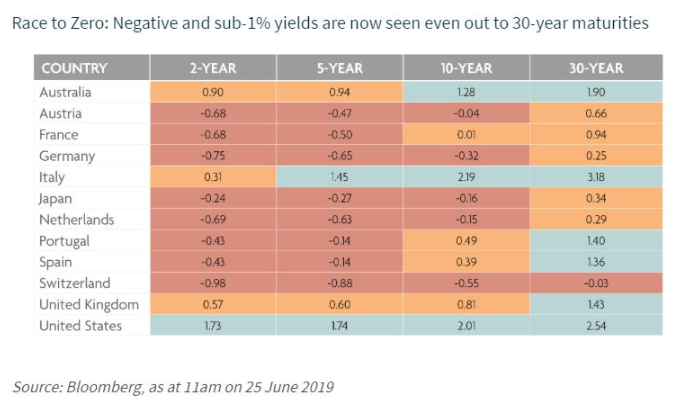
The bond market has also reached all-time highs. Some examples of the absurdity:
- 64% of Eurozone sovereign debt has a negative yield
- Swiss 30 year bond yields negative and Germany 15 year bond yields negative
- Italy 50 year bond yields 2.7%
- Austria 100-year bond yields 1.2%
In Ireland, credit unions have severely limited deposits from customers due to negative yields at banks.
Here's a recent yield table. As you can see, the US is the only market in positive territory for each maturity:
Meanwhile, the ECB still thinks that inflation is unacceptably low (who wants higher inflation?), and looks set to remain extremely dovish for the foreseeable future. The hiring of Christine Lagarde only confirms this.
And as far as the Bank of England is concerned, markets are now pricing in a greater than 50% chance of a rate cut this year.
What to do about this? Extraordinary monetary policy is good for investors in the sense that it pushes the prices up for everything we already own, but it's terrible in the sense that we can't make new investments at these higher prices without accepting a much lower prospective return.
But UK equities are a special situation, thanks to Brexit uncertainty. It seems that international investors are still waiting to see what happens, before embracing the UK markets again.
A resolution to the uncertainty could therefore lead to dramatic shifts in asset values. I think that the FTSE and the Pound Sterling could both rally in a big way, if we get certainty over the Brexit outcome in a few months. Or it might drag on even longer, of course!
In the UK small-cap world, we've seen a lot of the speculative froth get taken out of growth stocks, and there are plenty of stock-specific opportunities, as always.
Conclusion
I'm leaning towards the view that I will continue to make long bets on the FTSE Index (although I'd still love to see some sort of a pullback before going in again).
While I have selectively made a few investments in the US market, I would not currently make any long bets on US indexes.
As far as the bond market is concerned, there is still nothing in it that looks attractive to me at all, except US junk bonds.
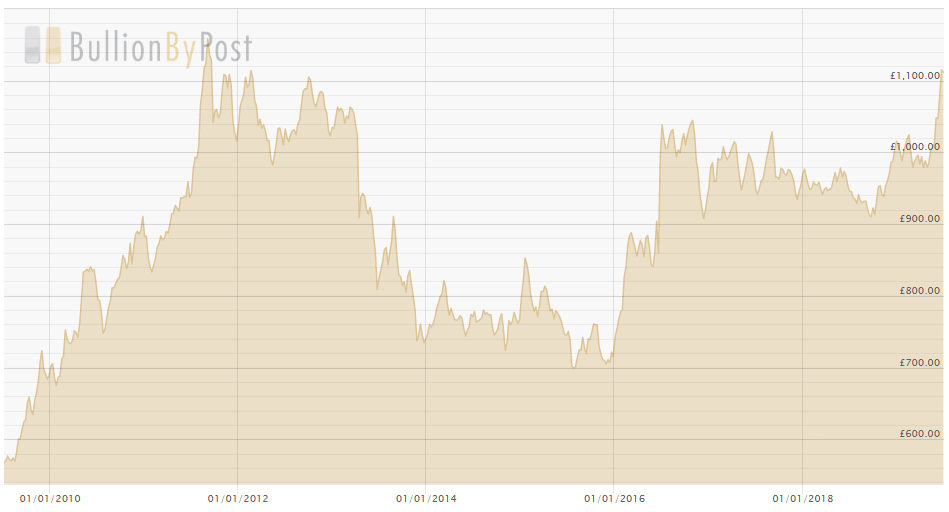
On the currency front, I'm expecting that the monetary madness will see gold break out to new highs versus GBP, going to £1,200/ounce and beyond:
The best way to speculate on the gold price increasing is a difficult question. 8% of my portfolio is currently in H & T (LON:HAT). If anybody can think of other non-mining operating businesses with a positive exposure to gold, please let me know!
Ok, sorry for the interlude!
Today we have trading updates from Churchill China (LON:CHH) and Live (LON:LVCG), and a statement by Frontier Smart Technologies (LON:FST).
Churchill China (LON:CHH)
- Share price: 1647p (+10%)
- No. of shares: 11 million
- Market cap: £181 million
A brief, positive H1 update from this ceramics company:
Hospitality revenue growth has been ahead of our initial expectations, with the majority of this out-performance again being attributable to further progress in Europe. We now anticipate trading performance will be ahead of our earlier expectations for the full year.
Not much info given but for Churchill China to issue a positive trading update is in line with its trend over the past year:
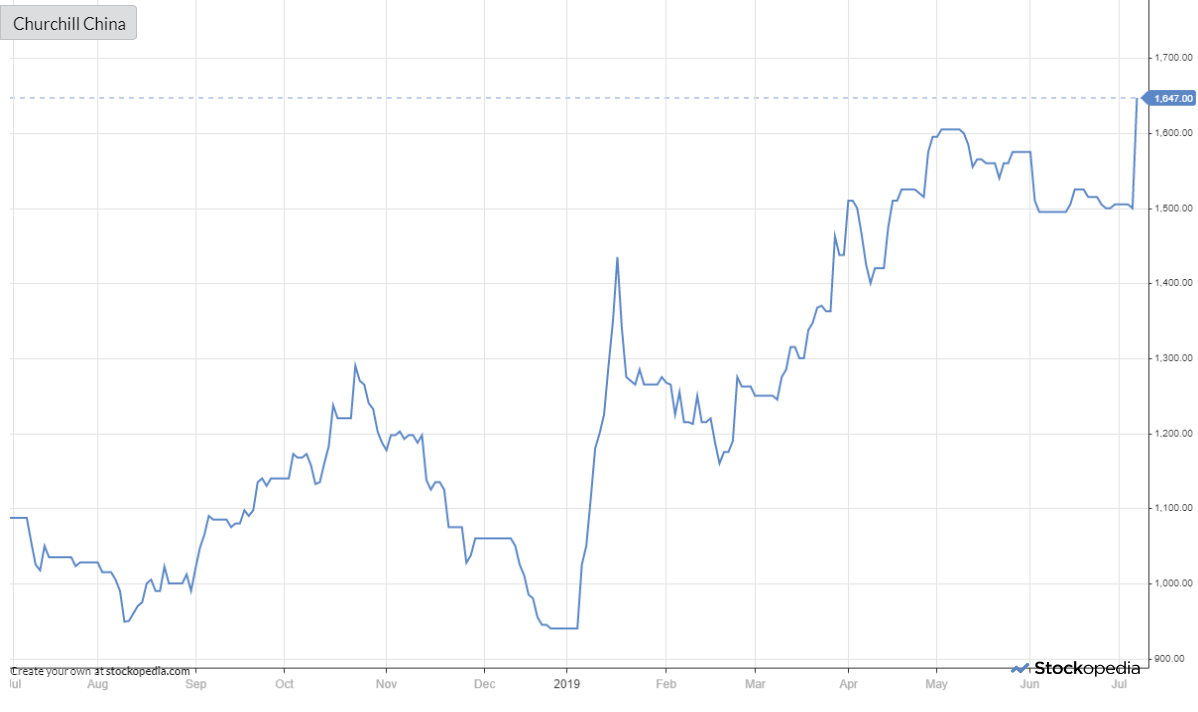
This is one that I've failed to invest in, despite identifying it (along with Paul and many others) as a high-quality business. I was interested in it last August at 1000p, but it didn't stay at those levels for long.
It did drop back to 1000p during the long-forgotten slump of December 2018, but I was buying other things at the time. At a forward P/E multiple of c. 20x (assuming that today's share price increase matches increased EPS expectations), I suspect that it is currently around fair value.
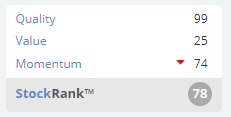
It's a High Flyer, which is a winning Stockopedia style:
Live (LON:LVCG)
- Share price: 50.5p (+4%)
- No. of shares: 70.4 million
- Market cap: £36 million
This is a detailed AGM statement. Trading is in line with expectations so far in 2019.
LVCG produces entertaining shows for children, with a Lego theme. Click here for more info.
Everything seems to be on track.
This bit is unusual. The CEO is refusing his performance-based bonus of 500,000 shares for the current year:
Whilst, I remain fully committed to achieving this performance target and driving value for the Group, I can confirm that should the performance target be achieved, I have decided not to accept the award of the Bonus Shares.
Checking message boards, the decision seems to be a reaction to shareholder anger at the creation of this additional bonus scheme.
I can't see any forecasts but this stock doesn't fit into my investment strategy, so I'm not going to search for them. It has no track record of profitability and the market cap is an aggressive multiple of revenues. Stockopedia calls it a Sucker Stock.
Frontier Smart Technologies (LON:FST)
- Share price: 35.5p (unch.)
- No. of shares: 40.7 million
- Market cap: £14 million
Further response to offer and update on discussion
The Board at FST still thinks that its joint venture negotiations with an unnamed 3rd party could lead to "material incremental value", so it advises shareholders not to do anything with respect to the bid from Science (LON:SAG).
It wants discussions with Science to agree a route forward, and provides reassurances in relation to its cash position, banking covenants and executive compensation.
I'm not sure what is going to happen with the takeover offer at 35p, but FST shareholders seem like a depressed bunch after many years of losses. It looks vulnerable to a bid, especially seeing as Science already owns about 30%.
Ok, I'll call it a wrap there. Have a great weekend everyone!
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Not wanting to jinx it, but the old adage "Sell in May and go away" is looking a bit sorry so far this year.
Long may this run continue......
If anybody can think of other non-mining operating businesses with a positive exposure to gold
There are a few ETFs which hold the gold asset which in theory makes them safer.
Some of the tickers are
SGLD
GBS
My favourite "quote" on gold is - that a couple of thousand years ago an ounce would have bought you a toga and sandals, and today - a nice suit and shoes..
I seem to recall I bought some 1oz gold coins when they were about £360ish each to the ounce. Probably one of my better investments, that I proceeded to dish out to wife/nieces& nephews etc.
Of course since 2009, its hasn't done as well as the stockmarkets by a long way, but post crash has been a reasonably stable store of value overall, in that it hasn't cratered back to previous lows.
https://www.bullionbypost.co.uk/gold-price/gold-price-history/
Since its macro time...here's some pure big picture stuff - money, eurodollar (its what counts not the dollar) politics, power, social - if you don't want a ramble on that then don't read!...
https://medium.com/@mojomogoz/the-unbearable-lightness-of-western-hegemony-8860c413c52c
At heart our issue is a huge amount of unproductive debt. This is near universal on a global basis...except some emerging markets that ain't so bad relative to developed but often don't look good relative to their history. Bad right?..
Well, it's MAD....mutually assured destruction mad. Where and how is the debt bomb going to drop? The truth is we can't afford it to do anywhere really, not even 'evil' China. So ways will be found to ameliorate the pressure and weight of debt...Boris and Jeremy are joining the big JC on that one with promises and magic money trees...this is the direction of travel....MMT and derivatives are inevitable.
It means equity bull is probably going to run. In the US income and taxes related to equity market performance have become super important at the margin and US policy will come to recognise this and supporting the equity market will be an issue of national security! Perhaps The Donald already knows.
Word. ;)
Regarding gold
My preference is to own Gold Producers with a dividend yield. But what is so frustrating in my opinion, is the blatant manipulation of the gold market.
https://www.thetradenews.com/merrill-lynch-fined-25-million-multi-year-spoofing-scheme/
The above link is just one example of many!
For example take a look at today's NY NYMEX cliff edge fall -
https://www.kitco.com/charts/livegold.html
I regularly check Kitco for the latest gold price and on a regular basis NY MYMEX at around 8am ish you can see the same old pattern time and time again. I just hope that strong buying momentum will overwhelm these antics.
Yes, I like gold producers with a dividend yield, though the yield is compensation for enhanced risks like seizure of the mines by the local government, e.g. Caledonia Mining (LON:CMCL) or Highland Gold Mining (LON:HGM). Caledonia Mining (LON:CMCL) (yield 4.7%, trailing P/E 6.16%, ROCE 23.7%) says that it is on track to produce 80,000 ounces of gold per annum by 2022, up from 53,000-56,000 for the current year, thanks to the sinking of a new shaft; surely worth a punt.
Like the market summary - certainly the recent rally has me feeling a little smug and to that end I am not a net buyer. Just under 10% net cash and then another 10% in what I would call cash equivalents, eg gold/govt/Supranational debt
Pure play gold, Ishares Physical Gold ETC (LON:SGLN) is gold in £. I have held since q416, and include as part of my cash. No yield but on current levels, am up slightly above 10%, which is acceptable on cash.
Who wants inflation: over indebted western governments, who calculate debt to (nominal) GDP and generate tax revenue on nominal wage rises, while a substantial portion of their expenses are fixed interest payments
Re multiples, it is my contention that as rates tend to zero, multiples tend to infinity, so in the current environment (monetary madness indeed) to drive valuation lower, we need an increase in risk premium, which is at least in part driven by sentiment. Based on my observation, taking the risk free rate aside, it seems that as the data shows an increase in risk, risk premium actually falls, especially if we assume a reduction in central bank balance sheet equates to a rise in the risk free rate.
On US equities, I am not aware of the Russell multiples, but so far as I know the S&P is around 17x, which is only slightly above the long term average (understandable given rates - see above). I would also be interested to know where the average and median sit. I believe certain pockets of overvaluation are distorting the picture. Finally, if a company is loss making, is the PE infinite or zero. Would be interested to know the PE ratio once all loss making businesses are excluded - assuming of course that the loss makers form part of the initial calculation.
As I type, I received a jobs notification saying above estimate - i.e. no rate cut. If my rate thesis is correct this should be market negative.
#cynic
"If anybody can think of other non-mining operating businesses with a positive exposure to gold, please let me know!"
One option is buy GLD - a physically backed EFT which tracks the gold price fairly closely. Good option if you just want to go long gold. Doesn't pay a dividend or have earnings of course. But good insurance against a meltdown in interest rates, as mining stocks will have a degree of market madness risk if they were swept up in a broad stock market sell off.
Speaking of meltdown, we are in the last innings of the global market bull run. Actually the USA is the only major market to beat its high though.
The FED is ever poised to unleash another round of QE of course. USA economic indicators have been softening. The 3mth/10yr yield curve spread is negative by 0.25pts. Historically this implies a 30% probability of a recession in the USA, four quarters out from today.
Where it goes from here, nobody knows, we haven't had the euphoric peak yet where the last buyers pile in at the top. Possible the FED dropping rates might give us that. Then it can crash in a heap.
Gold has done well this month with the FED signalling lower rates and the bond market driving that.
Note the SPX500 doing well but Russell2000 not so much. The big leaders are going up. This is a last leg bull market signal as well.
As for the FTSE, yes, much better value on a PER and dividend yield basis than the USA. Keep in mind the FTSE100 companies generate 70% of earnings abroad, so the Pound rate will move it around. Funny thing is if Brexit has a good outcome (you decide what that is) then overseas investors are likely come back to chase yield but the Pound FX rate would rise, suppressing earnings. Go figure. Either way yields will compress. If there is a bad Brexit, good luck everybody. Short UK domestic stocks and the Pound. FTSE100 might do ok though, because of the overseas earnings point, as a safe haven.
Late stage bull markets are a pain. The mantra is to invest in large cap stocks if you want to ride the last leg up, as you can sell these quickly if prices start to drop, as liquidity is there. Can get trapped in small caps, so own ones you love to hold, or short the FTSE index if things go badly as a hedge, rather than be a forced seller in a thin market.
Gold is looking up, as the next round of QE could really impact savings. Europe is fighting deflation so expect more QE there. USA will follow. Note the USA grew it's deficit by 6%, which is more than economic growth, so their economy is debt funded now, therefore expect lower rates and more QE to support it. It's a given now MMT (modern monetary theory) is an option to fund increasing budget deficits.
Keep in mind Trump has his re-election next year. His tax cut sugar boost has faded now. So he will push the FED to drive lower rates and QE for an economic burst to support his re-election chances. Also he will magic a solution to the trade war as a bounce, when the timing is right.
If there is a recession next year, he won't get in, so expect him to do what it takes to engineer one last push through next year, if he can keep the debt merry-go-round spinning. That might time in with a last bull market rip, which we haven't seen yet.
So, in the round, you would think markets have another burst yet, dancing to the FED's tune. If the yield curve spread widens, all bets are off.
Interesting times!
Thanks for the strong input, jwebster. Please accept a +1 vote from me. G
The government bond markets are amazing.
It was only about 3 years ago that Argentina managed to get a 100 year bond issued. Unsurprisingly, these are already down.
A 100 year bond from Austria is a better bet, but even before investing in that, one has to note that the maps of central Europe in 1914 and 1939 look quite different to those of today. Who knows what the map would look like when it is time to redeem that one.
Being a little cautious about the stock market, I'm about 78% in stocks, with the remainder in gold, short term US treasuries & cash. Who knows whether this the correct allocation.
Some experts have recommended increasing your bond exposure with age. Even something like (100 - your age) as the percentage in stocks & the remainder in bonds. With current low bond yields and increasing longevity, perhaps it needs a substantial adjustment. I ignore it.
Meanwhile, the ECB still thinks that inflation is unacceptably low
Do you not know, my son, with how little wisdom the world is governed?
-- Axel Oxenstierna
The curious task of economics is to demonstrate to men how little they really know about what they imagine they can design.
-- Friedrich August von Hayek
I have seen all the works that are done under the sun; and indeed, all is vanity and grasping for the wind
-- Eccl 1:14
The curse of wisdom is to know the folly of men.
I'm feeling in a poetic mood today.
Beautiful words, Mark!
On overvaluation and monetary madness:
I believe seasonality is a thing and
-never go long in Feb, July, October, November.
-never go short in April, May, Dec
(disclaimer : based on personal experience only)
Currently gathering cash and tightening stop-losses
Nice roundup of current market situation Graham but I'm a bit uncertain about "avoid America but invest in the FTSE".
Can you really see American stocks plummeting or even just dropping but UK stocks staying where they are or even advancing?
Has it ever happened before?
My memory probably isn't what it was but my recollection is that "when Wall Street sneezes other stock markets catch a cold" or some very similar saying has usually held true.
Hi Laughton - I totally agree with the view that the FTSE will fall if the US does. But I take comfort from the current valuation of the FTSE, i.e. I do not expect the FTSE to crash by anything like the same % that the US markets could. Can't wait to find out!! G
The best way to speculate on the gold price increase is to buy established gold producers with a cap of £100mil or more. This is like buying gold on steroids. There are only about 10 of these in the UK market, Just take a look at their performance from the point of the surge in the yellow metal price and you`ll understand
Not sure I agree. Have a look at the much praised (by Morningstar and just about any commentator you care to read) Black Rock Gold & General fund which holds most of the large cap gold miners. The performance has been dreadful over the last 10 years or more I have held - down about 30% from cost!!
Graham
Re "If anybody can think of other non-mining operating businesses with a positive exposure to gold, please let me know!",
Does WPM Wheaton Precious Metals count? They finance silver and gold mining operations in return for the rights to buy the metals at a discount. Latest earnings call transcript here.
https://seekingalpha.com/article/4262160-wheaton-precious-metals-corp-wpm-ceo-randy-smallwood-q1-2019-results-earnings-call-transcript?part=single
Edit: Or FNV Franco-Nevada for better focus on gold. They say they are the world's largest gold focused royalty and stream company.
Re: WPM (Wheaton) - that's great John, thanks for the suggestion! G
Interesting thoughts about the macro climate Graham.
I do think if the USA markets have a bit of a wobble - the FTSE will be affected too, even though the valuations of both are very different.
I've been taking money out of some shares recently as I think lessons of the 07/08 crash are being played out once again. People taking on more speculative risk, for less return, will in my mind come un-done.
However, it's been proven that no-one can time the markets so I don't know why I bother, but that's my weakness and I'd rather play it safe and be able to sleep soundly at night.
Office of Tax Simplification Inheritance Tax Review
The OTS has this morning published its second report on its review of IHT. The first report focused on admin issues with the tax, but this one makes recommendations for policy change.
https://www.gov.uk/government/...
This review has been of interest to small cap investors due to the concern that the OTS might recommend the removal of Business Property Relief (BPR) on qualifying AIM shares. Even for investors who aren't using AIM stocks as part of an IHT mitigation strategy, the removal of BPR would almost certainly hit the share prices of AIM stocks generally, many of which have large holdings through IHT-related investment vehicles (e.g. Octopus).
The OTS hasn't specifically recommended the removal of BPR on qualifying AIM shares. Reading between the lines it seems apparent that the authors disapprove of the relief and question whether it serves the original purpose of BPR, but they shy away from advocating outright abolishment due to the government's desire to support investment in growth companies (paragraph 5.18 is the key I believe).
There is however a possible catch in the report for investors using AIM stocks for IHT planning, and this comes from the single recommendation that the OTS makes in relation to the interaction of IHT and CGT:
“Where a relief or exemption from Inheritance Tax applies, the government should consider removing the capital gains uplift and instead provide that the recipient is treated as acquiring the assets at the historic base cost of the person who has died.”
If this were enacted, AIM shares which passed free of IHT due to BPR would not receive any uplift in cost value for CGT purposes on death, leaving the beneficiaries potentially exposed to additional CGT liabilities on sale of the shares (assuming the holdings are in profit over the base cost on original purchase). This would also undermine the very generous changes to the tax treatment of ISAs in estate administration which came into effect from 6 April 2018.
Since it was Philip Hammond who initiated the OTS review and there’s now some doubt as to whether he will remain Chancellor after the leadership change, it remains to be seen whether IHT reform simply ends up on a future TODO list at the Treasury, particularly as the next couple of budgets are likely to be consumed with Brexit related considerations.
Thanks for that Luthrin , I do not think it would make any difference if the acquisition cost, rather than actual price on death, was taken into account as many AIM shares go down. In fact it might increase the total relief !
Churchill China (LON:CHH) Nice update from CHH today which i don't hold shares in (doh)
I do hold shares in Portmeirion (LON:PMP) Portmeirion which recently had a proft warning doh. Portmerion sell the same kind of kit.
I guess sometimes when you buy cheap (pe 15 v 19 ish) you get tat - sigh.
The only glimmer of hope is that there is some read across if CHH are doing well - however the shareprice reaction first thing of the two companies suggests there is no read across whatsoever which is understandable based on the most recent news from PMP.
The only slight glimmer of hope is the shareprice has recovered slightly since the day of the profit warning in may - my sell order at 1040p looks slightly optimistic based on where we are. I do sort of still have faith in PMP - but based on where we are i am happy to sell if anyone wants mine for 1040p - come on Mike Ashley you know you haven't made a bid for anything in the last 24 hours - pmp stuff would be perfect for angry gamers to let of steam when they lose in store.
I believe Churchill China (LON:CHH) is more aligned to the hospitality industry (hotels, cafes, etc), whereas Portmeirion (LON:PMP) is more aligned to retail (Christmas ranges, classic dinner sets, smelly candles etc). This might explain the limited read across from CHH to PMP.
Interestingly there is also no correlation to Johnson Service (LON:JSG) covered by Paul yesterday. This surprised me as I was expecting bad news when I noticed the CHH trading update this morning, as I had read across from JSG to CHH.
Disclaimer: holding modest positions in both CHH and PMP. Looking back at my now very old notes at the time of purchase, I couldn't make up my mind so split the investment across both!
Hi rmillaree,
I don't think there's read-across between Churchill China (LON:CHH) and Portmeirion (LON:PMP) because they're mostly targeting different markets.
CHH is mainly practical crockery for the hospitality sector, whereas
PMP is mainly decorative china, for gifts, and collectors. It does other stuff too, but the core market is decorative china.
Regards, Paul.
John Menzies (LON:MNZS) warns on profits as weak cargo volumes and flight schedule reductions bite. This has been on the cards a while and the share price has declined steadily all year.
Seems to be a large pension deficit and plenty of debt but long-term I would have thought there would be plenty of opportunity for them, particularly in Asian markets.
No position.
Viewing for the weekend?
piworld have just published Part 2 of the interview with Keith Ashworth Lord, UK Buffettology Fund where he covers, lessons learned, valuations on good companies, sell discipline, #Woodford and much more.
Both Part 1 and 2 are here.
Tamzin,
Watched part 1 of the interview last night and it was fascinating. Loved the fact he met Buffett & Munger as well as the Buffettologists like Lowenstein and Janet Lowe! He's a fellow down to earth Mancunian, and like Buffett, does not want to be distracted by the City. Interesting to hear his new acquisitions such as Focusrite (£TUNE), because I also hold, in addition to £BVXP and £GAW. I've followed his advice since meeting him at a ShareSoc, Manchester event and his discussion on Buffett type moats. I've tried to follow that philosophy ever since.
Keep the interviews coming, they're really interesting and educational. Well done.
My morning smallcap tweet: Mirada pulls a cash rabbit from hat
Mirada (LON:MIRA), Frontier Smart Technologies (LON:FST), Churchill China (LON:CHH), Ashley House (LON:ASH), Global Ports Holding (LON:GPH)
Mirada (MIRA) relief for its balance sheets as it sells payment subsidiary Mirada Connect for £2.1m. That's 17x pretax.
Frontier Smart Technologies (FST) Alternative to 35p offer from Science Group: discussing a strategic investment by way of a joint venture into which Frontier would roll certain of its smart software assets. It "presents the prospect of material incremental potential value for Frontier."
Churchill China (CHH) guides FY ahead of its earlier expectations due to outperformance in hospitality division.
Ashley House (ASH) warns (as mooted on 25 June) that three Morgan Ashley extra care schemes will fall into FY20. FY19 will show a loss.
Global Ports Holding (GPH) hoists For Sale sign as after receiving a number of preliminary offers for certain assets. Starts strategic review period.