Small Cap Value Report (Fri 6 Apr 2018) - NXT, TET, MOTR, VP.

Good morning, it's Paul here.
Due to jet-lag, I'm up bright & early again, ready to get cracking when the 7am RNS springs into life! As usual, please feel welcome to add your comments on any interesting announcements below.
I was adding this section below to yesterday's report, then decided to move it to today's so that more people see it.
Continuing my macro thoughts earlier this week, here is a summary of recent, detailed outlook comments from Next plc. This is not a small cap, but it provides unique commentary and transparency, which is of wider importance to the sector, and economy as a whole. Hence why I report on Next.
Commentary from Next (LON:NXT)
(at the time of writing, I hold a long position in this share)
Earlier this week, I outlined here my current macro view - which is that I see reasons for a degree of optimism later in 2018, particularly as the squeeze on UK real incomes appears to be coming to an end.
Belatedly, I've been reading the utterly brilliant commentary which retailing bellwether Next plc produced on 23 March 2018. The version with colour charts is here. It makes fascinating reading, and if you get a moment, I strongly recommend reading at least sections 2 & 3.
Here are a few key points;
1) Currency is now becoming helpful - and should drive price deflation in 2019 - which could also feed through to better LFL sales, although Next doesn't mention that;
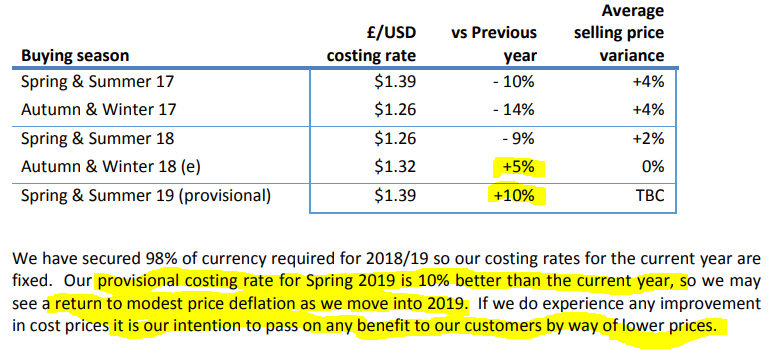
2) Real incomes should stop falling;
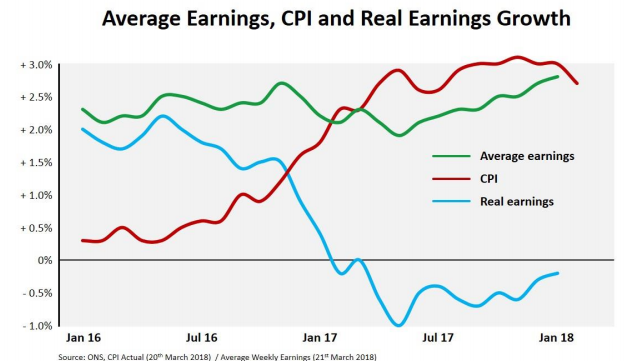
Outlook for Real Income in the Year Ahead
It appears that the easing of inflation in our own sector is being reflected in the wider economy, as other sectors benefit from stabilising currency rates. If that is the case and average nominal income growth remains at current levels, then we should expect to see little or no decline in real incomes during 2018.
EDIT - Many thanks to reader "dfs12", who points out in the comments section below, that big hikes in contributions to auto-enrolment pensions look set to take a bite out of disposable incomes. I've just googled this issue, and the increases are indeed quite steep. Here's a graphic from a BBC article today;
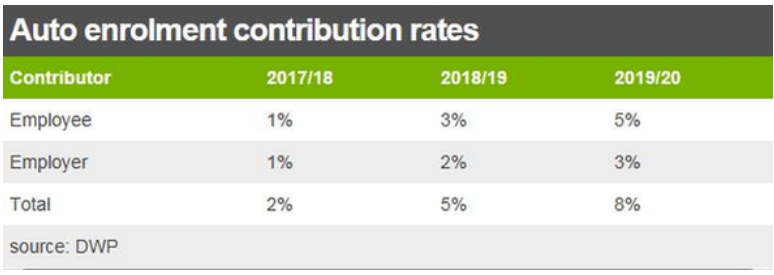
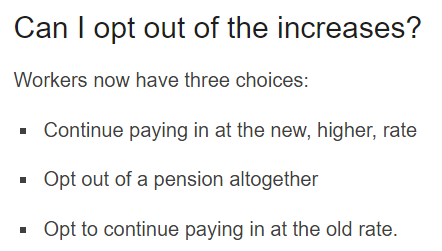
To gauge the impact of this, the key data is to find out what level of take-up there is for these pensions? Given that people can opt out, I wonder how many people will actually want to pay into pensions? Many younger people I talk to haven't even considered a pension, and see them as a bit of a con.
This is also from the BBC article;
(End of edit)
3. Sectorial shift in consumer spending patterns
This data below is from Barclaycard, so has probably been boosted by a tendency for consumers to use contactless cards in preference to cash. Nevertheless, the shift away from clothing is remarkable;
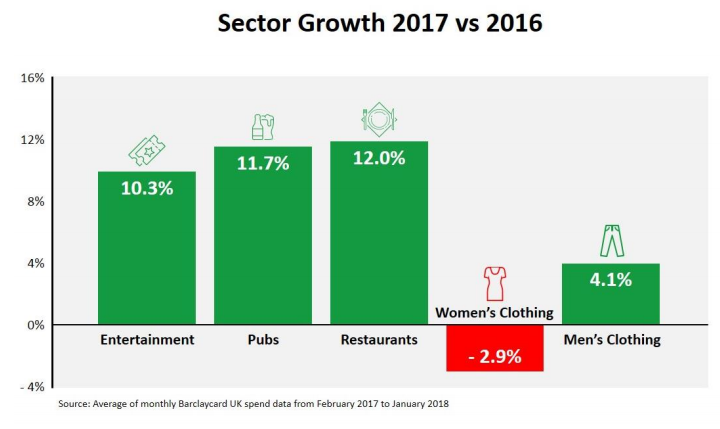
At the moment, people are seeking experiences rather than objects.
Interestingly, Next believes this is cyclical, and at some point should reverse. But it doesn't see that happening in the short term necessarily.
4) Weak Q1 & Q2 last year = soft comparatives for this year
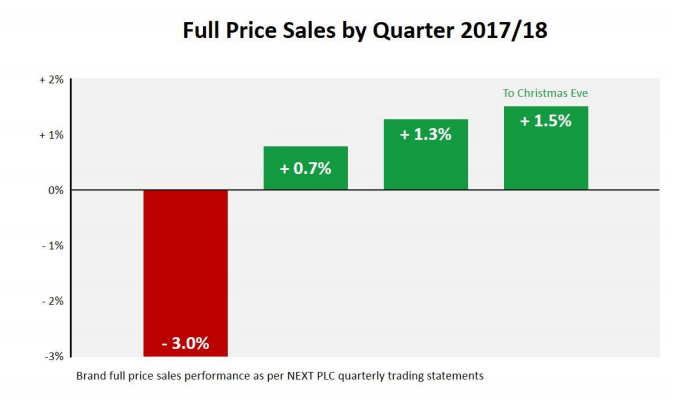
Self-inflicted problems last year (gaps in their product ranges) gives an opportunity to report stronger LFL sales this year. Mind you, the terrible weather in Q1 this year will have negated that, I imagine. However, Next looks set to report stronger figures in Q2 - which could be a good reason to be more optimistic for the share price as this year progresses.
5) The shift towards online sales is accelerating;
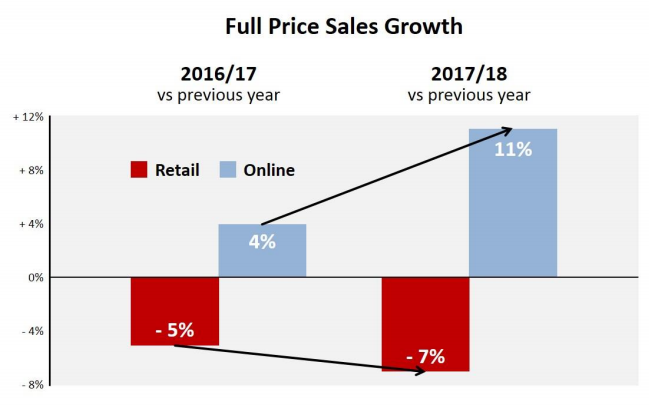
It's a good thing then, that Next is an accomplished online retailer. This is taking up most of the slack from its declining sales in store.
Many people may not be aware of this, but Next now makes more profit online, than it does from physical stores. Note also the significance of its consumer credit division;
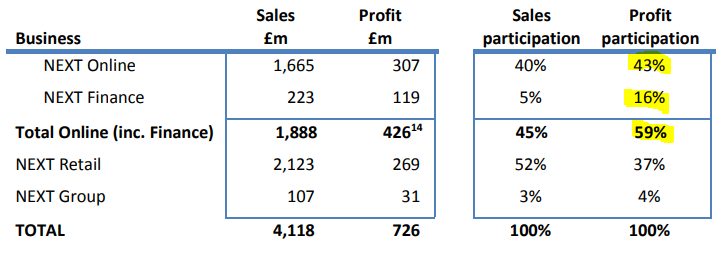
This trend is set to continue. Next's current year forecast a further drop in retail profits of £74m, and a rise of £61m in online profits. However, this is based on an extremely pessimistic forecast of -8.5% LFL sales fall in stores. I think there could perhaps be an upside surprise on that figure.
6) Lower rents are happening
As I've mentioned previously, High Street & shopping mall rents have to come down, by a lot. This is the only major cost which can move down significantly, unless shops start using robots instead of humans (which can't be ruled out, longer term).
Next says that its net rents are reducing by 28% on lease renewal. Plus landlords are funding the bulk of store refits too. Average new leases are only 7 years (whereas not long ago the standard term was 15 years).
So the commercial property market is clearly undergoing major changes. To reiterate, this is definitely not a good time to be investing in REITs which own shopping malls. The rents, and hence capital values, are coming down considerably. Hopefully the inflexible 5 year upward-only rent review system is also coming to an end, as it's simply not fit for purpose any more. To avoid bankrupting their tenants, landlords are going to have to be a lot more flexible in future.
7) Next's store portfolio will not become a liability
The skill with which Next is managing down its lease liabilities is outstanding. It has once again shown figures which demonstrate how, even in extreme conditions of -10% LFL sales compounding for the next 15 years, it could exit from its stores portfolio with ease, and little cost.
I don't believe sales falls of that magnitude are likely, so in my view there is upside potential here. The High Street won't disappear, as clothes shopping is a leisure activity which many people still enjoy.
As Next indicates in the section called "stress test", the impact of the declining High Street should be at least partially offset with lower rents.
8) Developing online sales
Lots of information is given on this. There are a number of initiatives that I really like. In particular, Next plans to merge its inventory management between online are stores. It amazes me that this hasn't been done before. Currently it dispatches all customer online orders from the central warehouse. In future, the computer system will check first to see which stores have excess stock, and give a specific store instructions to dispatch the item(s) to the customer from its surplus stock. The customer is also given the option of being able to collect the item from their nearest store within 1 hour of placing the order. This should help manage overall inventories much better, fulfilling more customer orders (fewer out of stock problems), and should also reduce the amount of discounting needed at end of season sale time. Clever. Obvious, but still clever.
There are lots of other clever initiatives, including the introduction of RFID tages onto all stock, which should greatly speed up the weekly in-store stock count.
Overall
I'm so impressed with all of this, that I've decided to dip my toe back in, with a recent fresh purchase of Next shares. It is clear that Next is successfully morphing into an online fashion business. The retail stores are being skilfully managed, so should not become a liability.
There's no overall net debt, because the store card receivables book is greater than the group's other debt.
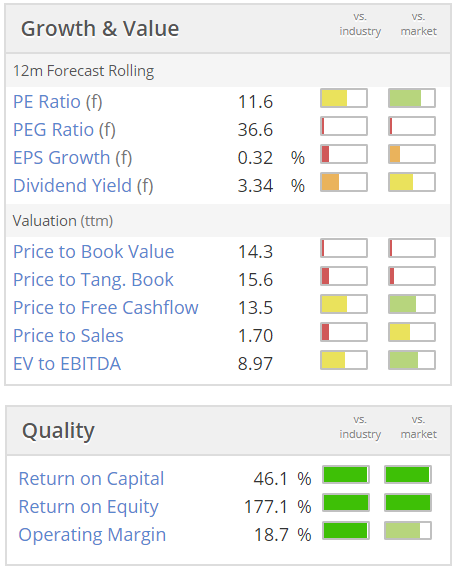
This is undoubtedly the best managed fashion retailer in the UK, and has been for many years. Yet you can pick up the shares on a forward PER of just 11. The share buybacks have resumed in earnest, so EPS should begin rising again, even if profits just remain static. I also think there's potentially quite good upside on the current year forecasts, which don't seem to factor in any benefit from improved product ranges.
Why buy any other retailer, when you can get the best one at this attractive valuation?
Stockopedia agrees, with a "Super Stock" style, and a StockRank of 96.
Just look at the quality scores below!
Treatt (LON:TET)
Share price: 410p (up 1.0% on yesterday's trading update)
No. shares: 57.5m
Market cap: £235.8m
Treatt, the manufacturer and supplier of innovative ingredient solutions for the flavour, fragrance, beverage and consumer product industries today publishes a trading update for the half year ended 31 March 2018.
I'm just re-reading previous coverage here of this share, to refresh my memory. I last looked at it here in May 2017, on publication of impressive interim results. At the time I held the share personally, intending to keep them for the long term. However, I became wary of an increasingly stretched valuation, and subsequently sold them. So it's not one I currently hold, but is on the watch list, as I like the company. I think it was talk of a possible equity raise, to finance large capex, which spooked me a little.
I've just noticed that the company did a placing to raise £21.6m (pre costs) in Nov 2016, at 410p per share. That's a useful strengthening of the balance sheet, which I like.
Graham wrote a useful summary of its trading update, here on 2 Oct 2017, and seemed to like what he saw.
Moving on to yesterday's update, things seem to be going well;
The Board is pleased to confirm that following a strong result for the financial year ended 30 September 2017 in which profit before tax increased by 46%, the business has continued to perform well in the current financial year with revenue for the six months ended 31 March 2018 up by approximately 11% compared to the same period in the prior year.
Echoing my comments above about Next, the forex position has reversed at Treatt too, although the £0.2m impact on H1 2018 doesn't sound material.
Taxation - Trump's recent tax cuts will be beneficial for Treatt;
... it is expected that the Group's overall tax charge will be materially lower than would have been the case under previous US tax law.
That's obviously positive for earnings, which are post-tax profits.
Outlook - is in line with expectations;
The momentum which is being delivered by the Board's Strategic Plan, with its focus on core product categories and key geographical markets, is expected to continue in the second half of the current financial year and beyond.
The Board therefore continues to believe that profit before tax and exceptional items will be in line with its expectations for the financial year ending 30 September 2018.
That sounds fine. Nothing to get excited about, but nothing to worry about either.
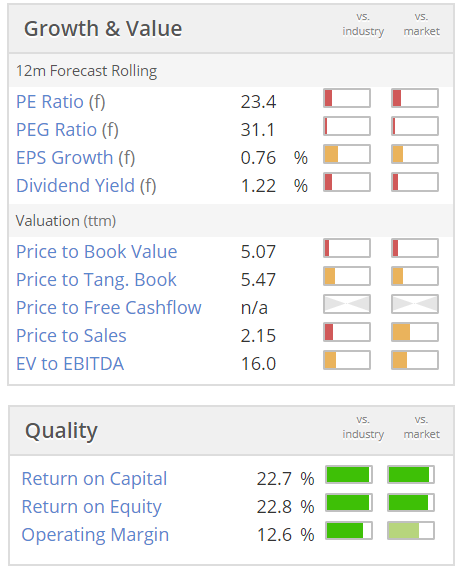
Valuation - for my personal taste, and given that we've had a big sell-off in lots of small caps recently (so there are plenty of bargains around), this looks too pricey;
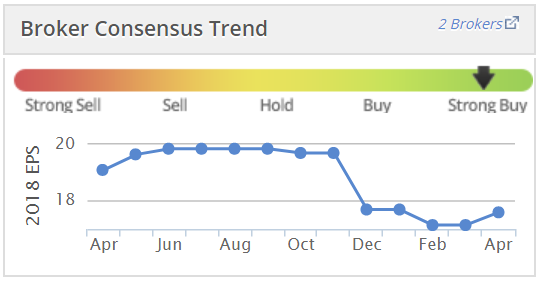
Note that broker forecasts have reduced somewhat, which partially reverses the previous trend of steady increases;
My opinion - this is a company which I regard highly, and in the long run it should prove an excellent investment. I'll probably buy back in, at some future point, but can't see any reason to rush in just yet.
Stockopedia calls it a "Falling Star", which seems a bit harsh. But there again, the computers don't know about the planned increase in capacity, so they may be missing a trick that we humans can spot!
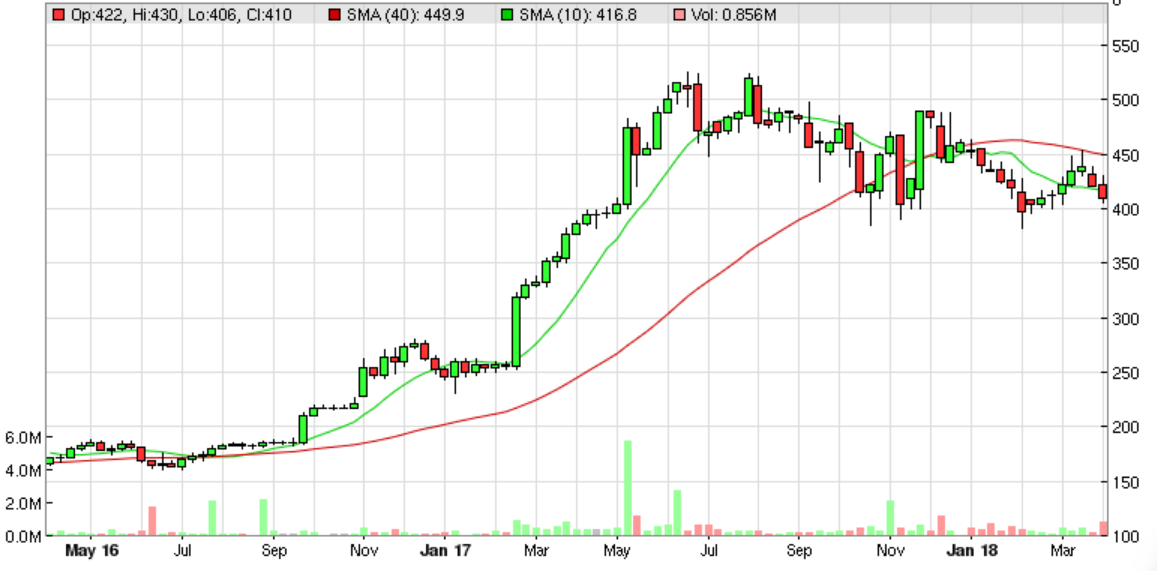
The 2-year chart shows a wonderful re-rating in 2016-17 (along with loads of other small caps), which seems to have run its course for now;
Overall then, nice company, but the price is a bit too rich for me right now.
Motorpoint (LON:MOTR)
Share price: 234p (up 7.8% today, at 10:28)
No. shares: 100.1m
Market cap: £234.2m
Motorpoint Group PLC, the UK's largest independent vehicle retailer, is pleased to announce the following trading update ahead of its preliminary results for the year ended 31 March 2018 ("FY18").
This is a positive update, with the key bullet point being this;
The Board expects to report Underlying Profit Before Tax for FY18 at the upper end of market expectations
The only problem being, that the company doesn't state what those expectations are. On Reuters website, it shows the range as being between 16.3p to 18.6p EPS for 03/2018. So it sounds like we can bank on 18p EPS, or slightly more. That works out at a PER of 13 - cheap by market standards, but expensive for a car dealership - most seem to be on a PER of 7-8.
Is Motorpoint worth the considerable premium to other car dealerships? Possibly, as it has a different model - it only sells secondhand cars (mostly nearly-new) from large, outdoors + sheds premises. Its sites are mostly in the Midlands & North. There are other car supermarket operators, and it's a good way to buy a secondhand car, usually cheaper than from a conventional dealer.
There are other encouraging comments in the RNS, which I won't regurgitate here. It sounds like a business which is firing on all cylinders though.
Outlook - again, encouraging, and revenues/earnings should continue rising from the roll-out to more sites;
Notwithstanding the macroeconomic uncertainty, the Board remains cautiously optimistic about the UK used vehicle market and is confident that Motorpoint's flexible stock sourcing model ensures the Group is well placed to continue to grow market share.
The Group continues to evaluate opportunities for its 13th retail site, with a pipeline of new site options under review.
"We had a good end to our financial year and are pleased that our strong first half trading performance continued into the second half of the year, as we gained further market share across our sites.
"Motorpoint operates a compelling proposition and is well placed to continue building on the competitive advantages of its unique model. With four sites under three years' old and a number of potential new sites currently under review, we remain excited about the Group's prospects and the Board looks to the future with confidence."
Balance sheet - I've had a quick look at the last (interim) balance sheet, and it's not very strong. The business relies on borrowings to fund its inventories.
Net assets was only £19.9m when last reported at 30 Sep 2017. Therefore I question the wisdom of the company's share buyback policy. To my mind, companies should only buy back shares with surplus capital, which this company does not have. Management might rue this decision when the next recession kicks in, and borrowing facilities tighten up.
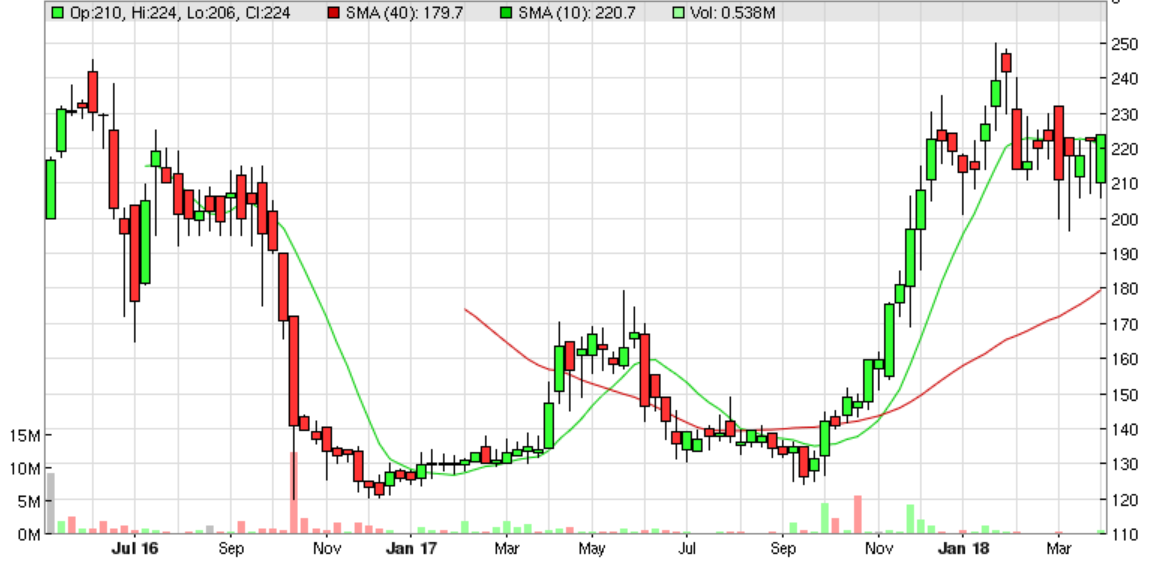
My opinion - overall, I like the business model of car supermarkets. It's a pile it high & sell it cheap type of business, with low overheads. That makes a lot of sense. There are not really barriers to entry, and there is competition. The stock turn with this type of business is usually quite rapid, so falling secondhand car prices shouldn't really matter, as stock comes in & out in about a month.
It's a pity I missed the two dips in share price last year, which would have made a decent purchase. I'm not inclined to chase it any higher now, so will pass. The current price looks justified though, after a decent update today, and positive outlook.
Note the StockRank of 90 is very good.
VP (LON:VP.)
Share price: 866p (up 5.6% today, at 11:46)
No. shares: 40.15m
Market cap: £347.7m
This is an equipment rental group, which operates in various niches.
It's an in line update;
The Board anticipates that the Group will report full year results for the year ended 31 March 2018 in line with current market expectations.
Other points;
The UK division has experienced consistent demand from its key infrastructure, construction and housebuilding markets.
... we have been working closely with the Brandon Hire team on the integration of the business within the Vp Group, a process which has started well.
Within the International division, the offshore oil and gas sector has remained challenging, whilst our Asia Pacific based test and measurement business has continued to perform well.
One of our regulars, gus1065, has posted a neat summary of the risk:rewards of investing in equipment hire companies, comment no.6 in the comments below. Good points, thanks gus!
My opinion - VP has always struck me as one of the better managed hire companies. The track record is excellent, and the balance sheet doesn't seem stretched (unlike say the car crash that HSS Hire (LON:HSS) has always been).
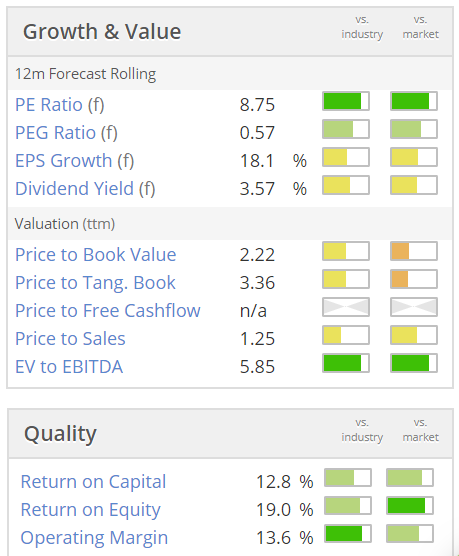
It looks cheap on a PER basis, and you also get a c.3.5% dividend yield.
The trouble is, looking at the chart, after a cracking re-rating in 2013, it hasn't really done much since. That's during a time when there have been plenty of opportunities to make double, or triple your money on other shares.
My concern is that ultra-low interest rates for 10 years, has led to over-investment in numerous sectors. Equipment hire could eventually turn out to be one of them, I don't know. These companies are very cyclical, and earnings tend to collapse in recessions. Therefore, I wonder whether this is the right time to be buying into this sector?
Having said that, if I did want to buy into this sector, then I think VP would probably be my top pick.
Right, that's me done for today, and the week. Sorry I didn't get round to looking at Next Fifteen Communications (LON:NFC) but I've run out of mental bandwidth now, so have to leave it at that.
Have a smashing weekend all!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Treatt - which I continue to hold - is in a major expansion stage, both in the US and the UK, requiring a big investment. Really the still high multiples are a reflection of this - it is a bet on the expansion's success. The fall in price may have started after Lord John Lee publicly disclosed he was reducing his position. The share had gone up so much that I seem to remember he said it had represented 40% of his portfolio at one stage and the bare multiple was very high after a cracking rise. The slowdown in nominal growth is partly a forex reversal though they do hedge substantially. I would suggest that is why the brokers have reduced estimates. I suspect - only suspect - that they may prove to be a major beneficiary of the new 'sugar laws' but am really here as it seems to me to be in a niche but quite rapidly expanding business and to be in safe but smart hands. I hope so.
Re Next (LON:NXT) and pension auto-enrolement: Those who opt-out will sacrifice their employer's contribution - accepting smaller total remuneration. Combine this (i.e. opting-out requires consideration, active decision and then actual follow-through, whereas auto-enrolement - the default - does not) with a contention that apathy is a wide-spread general human attribute (I think most would agree), and I think dfs12 is right to point out that auto-enrolement is likely to produce a significant drag on growth in disposable income for at least the next couple of years.
And, whilst I agree with Paul Scott on the excellence of Next's business model, management and reporting, also salient is that - as JohnEustace pointed out - in their recent Q1 statement, Next (LON:NXT) pointed out that every £1 of lost retail sales incurred, if memory serves, 61p in lost profit (presumably gross profit), whereas every additional £1 of online sales produced 'only' an extra 19p of profit. That sounds a very serious structural headwind given that Next's high online sales growth must at least begin to plateau before too long.
Disclosure: I own a very small number of Next (LON:NXT) shares.
Paul. Thanks for the great summary of Next (LON:NXT) commentary. I should follow it.
Some general questions re retailers (for whoever wants to give a response...thank you in advance). Note, I'm deliberately poking holes trying to be negative. The questions do not represent my view, more they are my lack of view/knowledge:
1) I'm suspicious of the the data that experiences are up a lot but spending on how one looks is down meaningfully. That doesn't seem likely. So more likely is that the spending is being missed in the data presented or there is a 'trade down' (which could be on High St or to online?). This means Next are missing out on the action. Unless its men going out and looking good and the ladies staying at home in their joggers :)
2) Ex finance, the online statistics are interesting. How much is online margin a function of high street shop window? Does c.18% margin head down to c.10% that Boohoo.Com (LON:BOO) (almost) achieves? If so, what price Boo's high growth trajectory relative to Next's more stationary profile? (Online is probably existing customers switching...perhaps partly due to credit inducements)
3) As it moves to online rather than high street does this change the nature of what it must be in a fashion sense? To keep margin must it move to the fast fashion nature of Boo or risk becoming a basics and staples provider?
4) Men are functional, quick and 'safe' shoppers relative to women (crass generalisation but roughly right). Does the increase in men clothes shopping signify something about where the high street (and so Next) is in interesting fashions sense? Is this a threat to Next margins?
5) Finance is the icing on the cake with 5% of revenue but margin of 53%. Good finance business? There have been many examples of retail businesses caught out by negative credit cycles. Next finance will be low down on the list of must pays. Its customer base is likely to be 'squeezed middle' not affluent.
6) Also, on credit, its possible that Next will face pressure either from cyclical effects or FCA investigative heat.
To be overly simplistic, credit quality comes from older and more middle class punter (>30yr old) and not the young or less affluent. Its small sum stuff and comparable in nature to payday or pawnbrokers or catalogue credit (a bad game that tends to have nasty cycles!)...its not like big ticket car credit for example. Its open-ended credit. If this were catalogue credit it would be lowest quality borrowers and the costs of credit checking would be high (ie, need to pay for credit and affordability data per customer but then only the approved customers produce income and so all costs for failed credit checks recouped from them). At 22.9% APR the margins Next are achieving in finance must come from people running credit balances long term. This sort of credit dynamic has FCA's attention. I wouldn't be surprised if Next get some heat on it.
Believe share price fall of Next (LON:NXT) today is due to brokers at Citi who have downgraded Next to sell. I am tempted to buy some as soon as possible. Cheers.
For me Next looks overvalued with a Price to Book value of 14.3, sales growth of just 0.48 and EPS Growth of -4.95. I think the share price needs to come down further to be of interest. Charles
Paul
Great analysis on the Next (LON:NXT) statement - but a small point on the increase in Autoenrolment pension increases. The Government would argue that these have been offset for most people by increased tax allowances, so net income will be broadly neutral. And it's net income that's what really matters in terms of household spending.
I think many companies will suggest to their employees that they take a salary sacrifice equivalent to the required top up of the auto enrolment %. This will deliver a more immediate tax efficient contribution, and would have a lesser effect on reducing net take home pay, than if they had to reclaim this from HMRC individually. This will also reduce Company NIC paid on earnings.
I read the full Next (LON:NXT) statement on the day. Had to sit firmly on my hands not to dash out and buy some. Purely a question of timing for me. Not that the outlook is that rosy ... but the management control! Accountant type management that is; not necessarily retail.
Such a contrast to Conviviality (LON:CVR) who appear to have employed a very different type of accountant.
Excellent macro section again. Many thanks. One spanner in the works with regards the improving disposable income situation... Auto enrolment pension contributions (directly taken from employee wages) go up today. From 1% to 3%. I'm not sure if this has been taken into consideration fully. Just when it looks like disposable income might break through!
Hi dfs12,
That's a great point re auto enrolment pensions. I'll include a comment on this in the main article.
Many thanks, Paul.
Apparently for low earners the drop in disposable income (resulting from the auto enrolment pension hikes) is likely to be compensated by the rise in the minimum wage that also comes in today!
http://www.bbc.co.uk/news/business-43582249
But the situation is complicated with hikes in council tax and other tax/benefit changes that have been highlighted in the comments.
I hope someone in the government has worked this all out!
yes and don't forget the large Council Tax increases starting today...the highest for 14 years. Some huge tax rises are coming in....landlords will be very affected, new sugar tax and so on. If interest rates do rise next month as expected I think any extra income will soon disappear.
Morning Paul,
Any views on why Churchill China (LON:CHH) is down 30% since Jan? Peaks and troughs seem to have got a lot bigger this last year. Someone selling off a lot, or something we aren't hearing about?
Sorry typo - meant ASOS which is ASC not ACS!!!
Paul,
Agree with much of your comments re Next (LON:NXT) quality of analysis but I fear your enthusiasm and additional purchase has sent the share price down 2.5% this morning!! Also the graph from Barclaycard seems a little contradictory given the difficulty that the restaurant and pubs sector are reporting at the moment. Finally women spending less on clothes (and men more to avoid accusations of sexism!) doesn't seem consistent with everyday experience. I suspect this is more to do with with similar volumes at lower prices given the success of the likes of Boohoo.Com (LON:BOO), Ai Claims Solutions (LON:ACS) and other emerging online fashion clothes companies such as Sosandar (LON:SOS).
Anyone in London next Wed and interested in environment, tech and investing might like this Jeremy Grantham presentation (data will be interesting even if you do not agree with him)...
http://www.lse.ac.uk/GranthamInstitute/event/public-lecture-investors-need-know-technology-climate-change-race-lives/?mc_cid=7729f52f23
Thanks for the tip. It is rare chance for private investors to get a chance to listen to one of the smarter global investors who has been around a lot longer than most .
Morning Paul.
Thanks for the Next (LON:NXT) update.
Is there any chance you could have a look at VP (LON:VP.)
My thoughts this morning were...
I still quite like this but there’s 2 stand-outs, a new acquisition integration in progress and Net Debt greater than 30% of Market Cap. The strange one here is the EPS CAGR is circa 15% - That’s almost double the 8.75 PER, the PEG reflects this, it’s 0.57! I’m almost talking myself into investing here but just can’t justify it - I just get the feeling I am missing something the market is not.
Thanks in advance as always.
EDIT - Here's the link to this mornings Trading Update.
Hi Matylda.
Re. VP (LON:VP.) gearing. Given it’s in the equipment hire sector these companies tend to carry a fair bit of debt as part of the general business model. (Buy kit on secured credit, rent it out at a spread sufficient to cover finance charge, Opex and Capex and make a decent profit. Buy more, get bigger, make more money). This tends to make the businesses pretty cyclical (they’re vulnerable to void risk in a downturn) and their Capex needs careful watching (too little and they lose business, too much and their leverage over cooks). If you look at a comparison with the wider peer group ( Aggreko (LON:AGK) , HSS Hire (LON:HSS) , Speedy Hire (LON:SDY) and Ashtead (LON:AHT) ), VP (LON:VP.) is in the middle of the pack on leverage (and most other metrics too). As an investment, it’s largely a call on where you think we are in the cycle for the various sectors VP (LON:VP.) services. I personally rate VP (LON:VP.) management and have been a holder for a couple of years.
https://www.stockopedia.com/compare/?tickers=LON%3AVP.%2C+LON%3AAGK%2C+LON%3AHSS%2C+LON%3ASDY%2C+LON%3AAHT%2C+
Gus.
Much appreciated Gus - Thank you.
My morning smallcap tweet:
Local Shopping Reit (LON:LSR), Quadrise Fuels International (LON:QFI), Abaco Capital (LON:ABA), Motorpoint (LON:MOTR), Shield Therapeutics (LON:STX), Avanti Communications (LON:AVN)
Local Shopping REIT (LSR) has sold 18 properties for £4.6m, 1.7% below book and 5% below after costs. I hold.
Quadrise Fuels (QFI) as expected, Saudi paperwork not signed for MSAR trial. Holds a slim hope will proceed with a delayed timescale. Maybe they were greasing palms with MSAR instead of the normal paper lubricant.
Abaco Capital (ABA) will go ahead with members' voluntary liquidation and delisting.
Motorpoint Group (MOTR) guides FY rev up 18% and U/L pretax at the upper end of market expectations. A great result. I thought they'd struggle with lower new car sales resulting in lower used volumes pushing through.
Shield Therapeutics (STX) FDA has provided Shield with the necessary guidance to progress submission of an NDA for Feraccru without conducting additional pivotal clinical trials. Also Shield is considering a range of partnering structures in the EU that could likely include upfront payments.
Avanti Comms Group (AVN) good news for once as its heavily boosted (geddit?) high data capacity HYLAS4 satellite is launched. It would be churlish to point out that they are only using a fraction of existing data capacity, so I will.
Any chance of a circle back over Next Fifteen Communications (LON:NFC) Paul from Tuesday popular with a lot of private thanks.
Next Fifteen Communications Group plc
Preliminary results for the year ended 31 January 2018
Next Fifteen Communications Group plc (“Next 15” or the “Group”), the digital communications group, today announces its preliminary results for the year ended 31 January 2018.
Adjusted financial results for the year to 31 January 2018
Year ended
31 January 2018
(Unaudited)
Year ended
31 January 2017
(Audited)
Growth
Revenue £196.8m £171.0m 15%
EBITDA £34.4m £29.0m 19%
Operating profit £30.0m £25.0m 20%
Operating profit margin 15.3% 14.6%
Profit before tax £29.3m £24.2m 21%
Diluted EPS 27.8p 23.4p 19%
Dividend per share 6.30p 5.25p 20%
Cash generated from operations £28.9m £32.8m (12%)
Net debt £11.6m £11.4m
In order to help shareholders’ understanding of the underlying performance of the business, adjusted results have been presented. The items that are excluded from adjusted results include acquisition related costs, acquisition related share-based payment charges, amortisation and certain other exceptional items. The adjusted results are reconciled to statutory results within notes 2 and 3.
Highlights
Revenues increased by 15%, with Group organic 1 revenue growth of 5.2%
Adjusted operating profit margin improved to 15.3% from 14.6%
Adjusted profit before tax up 21% to £29.3m
Adjusted diluted earnings per share increased by 19% to 27.8p
20% increase in dividend per share to 6.3p
Significant client wins including Samsung, Slack and Nike
Velocity, a B2B content marketing agency, and Circle, a B2B market research consultancy, acquired in July 2017
Elvis, an integrated digital agency, and Charterhouse, a market research agency, acquired in September 2017
Commenting on the results, Chairman of Next 15, Richard Eyre said :
“Next 15 continues to develop its services against our template of Creativity, Data and Technology, ensuring the Group’s capability to develop with the extra-ordinary pace of technology in our sector. This has driven another good year, with revenues and earnings again reaching record levels. Revenue was 15% up to £196.8m (£171.0m) while adjusted profit before tax rose by 21% to £29.3m. Fully diluted adjusted earnings per share rose to 27.8p.
These results were influenced by three major factors: strong organic growth in the second half of the year and additional well-executed acquisitions, offset by some negative impact from the relative strength of Sterling. Organic growth that had been modest amid the political and economic uncertainty of the first half of the year, grew to more familiar levels in the second, with many of the Group’s businesses turning in strong performances.
This high single-digit organic revenue growth has continued into the new financial year, augmented by strong performances from newly acquired agencies, giving us confidence for another good year ahead.
Clara, I don't know who's reported you for copyright violation (!) but it's best just to post a line or two from an RNS & then a link to it if requesting a stock. £NFC
I came on here to ask exactly the same thing & hoping you might take a look at this one Paul. My main thing is the decrease in net cash. I think I've got my head around it, but would be good to hear an explanation to this from the master.