Small Cap Value Report (Mon 12 April 2021) - TET, BLV, CBOX, VTC, INS, CNC

Good morning, it's Paul & Jack here, with the SCVR for Monday.
Timing - today's report is now finished.
It's re-opening day today, with retailers & outside hospitality opening up again. It will be interesting to see if we get a boom in spending, or not. The problem is, that many share prices seem to have already priced-in a full recovery. So where's the upside going to come from?
I've been stranded in Bournemouth, going slowly mad, over the last 4 months. So I'm looking forward to strolling into the town centre this afternoon, to see what's occurring. I'm not holding out much hope of getting a crisp, cold pint anywhere, as I expect it's likely to be booked up everywhere, but we'll see.
I'm wondering what there is, in town centres, that I actually need? Just Primark really, and that's about it. I now buy everything else online, or from small local shops. Hence I'm a bit sceptical that High Streets and shopping centres would just return to normal.
Mello Monday
Is tonight! Full details here. It starts at the earlier time of 5pm today.
Star of the show is the Queen of Tech, Vin Murria.
I'll be doing a brief results update on Saga (LON:SAGA) (I hold) near the end, in the charity pledge section. As you know here, I jump at any opportunity to promote the wonderful little humanitarian aid charity, ZANE, helping many good causes in impoverished Zimbabwe. Thank you to all the subscribers here who have also shown an interest in, and made donations to ZANE. I tend to bung over a bit of cash whenever I bank a nice profit from something on the stock market, on top of some standing orders. What ZANE needs more than anything, is regular income, as it has regular outgoings, helping destitute individuals often for the remainder of their lives.
Agenda
Paul -
Treatt (LON:TET) - trading update - an in line update, but hints at possible further upgrades. Lovely company, but shares look expensive now (as lots of things do)
Cake Box Holdings (LON:CBOX) - trading update - in line with expectations. Rapid roll out underway, of franchised cake shops. Looks good.
Belvoir (LON:BLV) - Final results - for FY 12/2020. I'm impressed with all aspects of this company's performance, including the balance sheet, which now looks OK (I had previous concerns about it, since resolved). Looks good, and still reasonably priced, I reckon.
Vitec (LON:VTC) - upbeat trading update.
Jack -
Instem (LON:INS) - in-line update from this acquisitive life sciences software group
Concurrent Technologies (LON:CNC) - shares down today but improving conditions for this UK-based computer board manufacturer
.
Paul’s section
Treatt (LON:TET)
958p - mkt cap £571m
Treatt has risen strongly in price, and is a bit above our usual market cap cutoff of c.£400-500m (flexible), but it’s such an interesting company I’m going to keep reporting on it.
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, today publishes a trading update for the half year ended 31 March 2021 (the "Period").
Momentum continues with strong growth in revenue and margins
The highlights today read well, but it’s only an in line update, so not really something to get terrifically excited about, especially given how strong the share price performance has been (along with almost everything else) in the last year.
Here are the highlights from today's update -

There’s more operational detail in the announcement, which I won’t regurgitate here.
New UK facility - sounds like it’s nearing completion. This is a big capex project, that should increase production capacity.
Work on our new UK facility continues apace and we are now a significant way through the operational fit out. We will begin transitioning colleagues across in late April 2021 and will start the commissioning of the new plant and machinery later this calendar year as planned, to enable production to relocate. We believe this site, along with our recently expanded US facility, will provide Treatt with a much stronger platform to support its growth ambitions.
Net debt - seems modest at only £5.1m, with £21.2m undrawn bank facilities. So liquidity sounds fine.
Forex - stronger sterling vs dollar is a small benefit of £0.4m in H1.
Outlook - expecting a boost in H2 from re-opening of hospitality venues. Promising outlook, but “we are taking a conservative approach” - I’m not clear what that means. Possibly it might mean that they’re not raising guidance until it’s clear what the order book looks like for H2?
Diary date - Interim results are due out on 11 May 2021.
Valuation - I’m well aware of the merits of Treatt - it’s a decent company, with a good track record, operating in an interesting niche.
This share does look very expensive though - a forward PER of 37.3. It looks like the market must be anticipating a beat against forecasts, and strong growth when the new production facility starts production. Forecast for next year doesn't seem to factor in much growth, considering a large new production facility is coming on stream later this year. So that could explain why the shares currently look so expensive - i.e. unrealistically low forecasts, possibly?
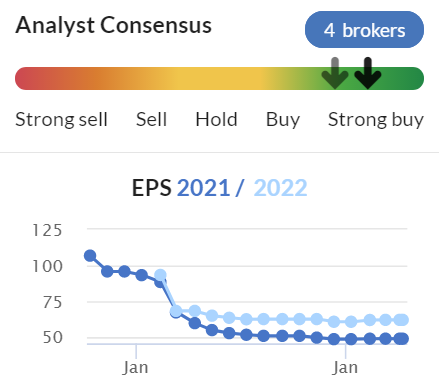
Note that a trading update on 22 Jan 2021 indicated profitability for FY 09/2021 would “materially exceed” market consensus forecasts. As a result, brokers considerably upgraded EPS forecasts, as you can see from the graph below. Reading between the lines today, it sounds as if another upgrade could be in the pipeline for later this year, possibly?
.

.
My opinion - very nice company, but the high valuation is clearly based on expectations that earnings & growth are likely to exceed expectations again.
So many shares have had an amazing run in the last 6 months, that I can’t help feeling it might be a good time to recognise this has been an exceptional period, that can’t last forever, and top slice some positions to raise cash for buying future dips? That's obviously just a personal view. The alternative is to accept market volatility, and ride out any downturns, the best strategy in the long run.
Personally I wouldn’t be interested in buying TET at the current valuation, but recognise that it’s a quality company.
EDIT: There's a new note out today from Edison, which confirms that "risk" to its forecasts are now to the upside, which confirms my inkling that the company is probably on track to beat forecasts (it needs to, to justify the valuation). The Edison note also has an interesting section on international competitors, which suggests that Treatt is priced in line with the competition (i.e. all are expensive!). End of edit.
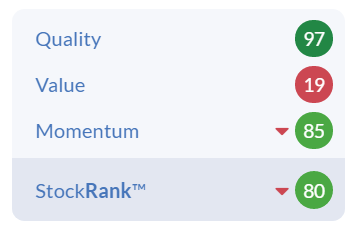
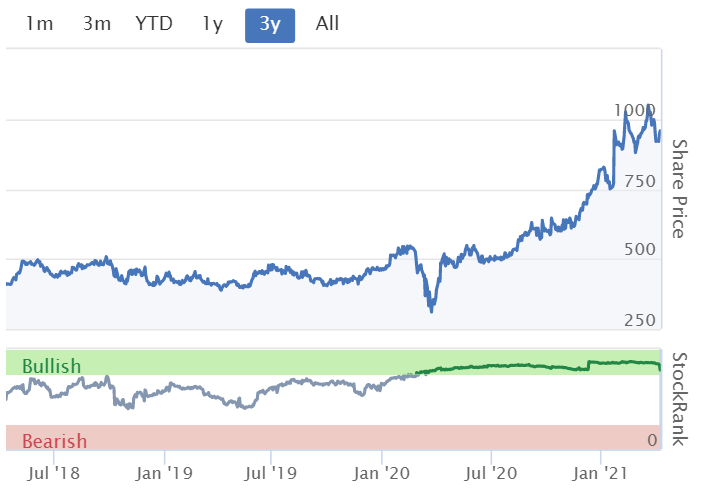
The StockRank system sums it up nicely - a quality company, with good momentum, but expensive:
.
.
Belvoir (LON:BLV)
207.5p (down 1% at 08:49) - mkt cap £73m
There’s an investor presentation being given by Belvoir management at 18:00 tomorrow (13 April) as part of a Shares magazine investor evening - details here.
EDIT: InvestorMeetCompany are also hosting a webinar here today (12 April) at 16:30. End of edit.
Belvoir Group PLC (AIM: BLV), one of the UK's largest property franchise groups, is pleased to announce its Final Results for the year ended 31 December 2020.
Resilient business model delivers another year of strong growth
Revenues up 13% to £21.7m (7% organic, 6% re Lovelle acquisition). Bear in mind revenues look low because the key revenue stream is management fees from the franchisees, which is effectively a profit share.
Profit before tax (continuing ops) - up 17% to £6.5m
EPS (diluted) up 13% to 14.6p. That’s a PER of 14.2 - probably about right. Note that Finncap seems to use a different measure, adjusted EPS of 16.7p is showing as actual for FY 12/2020 in its update today. That’s an adjusted PER of 12.4 - good value.
Can I suggest that the company, and brokers, liaise to report EPS on the same basis in future? That would make things a bit more logical for investors.
Taxpayer support - I did wonder if these figures might have been boosted by Govt support measures (something to bear in mind for all companies reporting). However, it seems not, as Belvoir has done the right thing and repaid taxpayer support -
Full repayment of the £260,000 Government Covid-19 financial support received under the Coronavirus Job Retention Scheme and small business grants
Track record - a very strong statement here -
In 2020 Belvoir achieved its 24th year of uninterrupted profit growth which, when considering the challenges of lockdowns and economic uncertainty, is a tremendous result.
Dividends - impressive to see catch up divis, on top of usual divis. The forecast yield for 2021 is 3.5% - not bad.
Outlook -
- 2021 so far is in line with management expectations.
- Property market is being boosted by the stamp duty holiday (extended to 30 Sept 2021), and new Govt scheme to guarantee 95% mortgages.
- Uncertainty re macro economic picture longer-term
- Resilient business model, as proven in 2020 covid/lockdowns
Acquisition - post year end looks good - buying in £1m additional operating profit, for just £4.0m price paid. That looks an attractive deal, I wonder why the vendor sold?
Balance sheet - NAV is £28.3m. Strip out £29.9m intangibles and £1.4m deferred tax, and NTAV is £(0.2)m. That’s fine for a business with very little in the way of fixed assets - a capital light business model doesn’t need a strong balance sheet. Net debt is now modest relative to profits, so that's OK.
Also the resilience of profits & cashflows demonstrated in 2020, is another reason why it doesn’t need a strong balance sheet.
Therefore, whilst I’ve had concerns about debt, and the generally weak balance sheet in the past, I’m happy to sound the all-clear, in that the figures now look OK to me, hence I no longer have any concerns about Belvoir’s balance sheet.
Cashflow statement - is impressive. This is a genuinely cash generative business, even in a really tough year like no other, in 2020.
The cash generated is used to self-fund bolt on acquisitions, and to pay a respectable dividend too. This looks good.
My opinion - this share gets a thumbs up from me.
Given this strong performance, I think the big rise in Belvoir’s share price looks fully justified.
Further growth in earnings should follow, from good value acquisitions made.
Finncap has upgraded its 2021 forecast EPS by 11% today, to 17.3p, a current year PER of 12.0, and I think the Finncap forecasts look conservative, so we might expect to see a beat against that in due course.
As always, I have no idea what the share price will do in the short term, as that’s purely down to sentiment. But the fundamentals justify further upside on the share price, over time, and I’m increasingly seeing this share as a good one to hold long-term. It's pleasing to actually find something reasonably priced, as most other shares look terribly expensive at the moment.
It’s very unlikely to be a 100-bagger, but could still be a decent share to tuck away forever, a coffee can stock. It seems to have a good business model, and looks well managed. I’ll make a diary note to tune in to the webinar this afternoon, to find out what management are like.
It tickles Stockopedia’s fancy too, with a high StockRank. Note that the value score could improve once higher earnings forecasts feed through in the next few days.
.

.
A strong share price, but the fundamentals reported today do justify this move up, in my opinion:

.
Cake Box Holdings (LON:CBOX)
261p (up 2.7%, at 12:10) - mkt cap £104m
Coincidentally, this is the second franchising business I’ve looked at today.
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces a trading update for the full year period ended 31 March 2021 ("FY21").
Strong recovery in trading sustained through H2
Another period of strong growth in an unprecedented year
Two PR headings, that's just greedy!
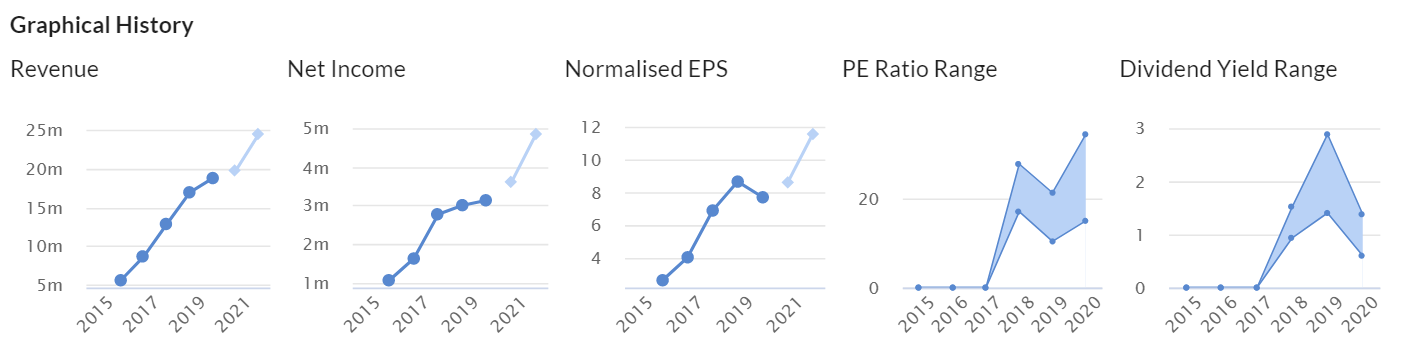
This FY 03/2021 trading update reads positively. Here are my notes & comments -
- Very good like-for-like (LFL) sales up 14.7% for the 40 weeks since lockdown 1 lifted
- Revenues for the year reached a new record, +16% on LY (last year)
- Adj PBT (profit before tax) in line with market expectations (but no figures given)
- Stores roll out has continued, and is fast - 157 stores at year end operated by franchisees. 24 of those opened in the year, 17 in H2. This is such a good time to be rolling out a retail format, as tremendous deals are available from landlords. There must be scope for lots more locations in the UK, as national retail chains can reach a size of 1,000+ sites - assuming that Cake Box has universal appeal, and isn’t just a niche thing for people who don’t eat eggs
- Has deposits from franchisees for 52 new sites - very impressive, and of course with a franchise model, expansion can be extremely rapid, as the franchisees do most of the work.
- Trialling new concept of kiosks in supermarkets, 5 done so far - results so far “very encouraging”
- Own brand delivery platform added to existing third party delivery options
- Online sales up a very impressive +84% year-on-year - so clearly CBOX has been resilient during covid, and the franchise model protects it, providing the franchisees don’t go bust
- Net cash at 03/2021 of £3.6m
- Dividends - Special declared in Sept 2020, Interim declared in Nov 2020. Forecast yield is 2.2%, but expect that to grow as the business expands
- Repaid furlough funds (only applies to central staff, as everyone else is employed by franchisees)
- Results - date TBC, but will be in June 2021
My opinion - assuming the numbers are correct, then this does look really good.
It’s not cheap any more, after a big rise in the last 6 months, but I think the rapid roll-out does justify a premium valuation. So a thumbs up from me.
.
.
Vitec (LON:VTC)
1165p (up 1.3% at 12:42) - mkt cap £527m
Acquisitions - two are announced today, totalling £30.4m in cash and shares.
Trading update -
... despite some uncertainty about when markets will fully reopen and foreign exchange fluctuations, is increasingly confident about delivering a strong recovery in 2021.
Good trading performance in Q1 2021 - order intake & revenue similar to Q1 2019 (i.e. a pre-covid year).
Scanning the StockReport, Vitec doesn't look particularly good value, based on existing broker forecasts. However, if you look at how much forecasts have fallen, and wonder if the company could in time recover to pre-covid forecast profitability, then that would reduce the PER down to not much above 10, which would look cheap. There might be pent-up demand also, when customers do re-open?
.
My opinion - neutral, as I haven't done enough research to form a view either way.
It is striking though how many companies are sounding more upbeat about the future of late. Also, there was a newspaper report over the weekend, saying that finance chiefs in the UK are now much more optimistic, and are in hiring & expanding mode, instead of cash conservation & retrenching. That's bullish for equities.
.
Jack’s section
Instem (LON:INS)
Share price: 690p (+1.47%)
Shares in issue: 21,742,032
Market cap: £150m
Instem (LON:INS) is a leading provider of IT solutions to the life sciences market, with a product suite that handles Study Management and Data Collection; Regulatory Solutions for Submissions and Compliance; and Informatics-based Insight Generation.
It enables clients to bring products to market faster.
The solutions address aspects of the entire drug development value chain and are used by over 600 customers worldwide, including all the largest 25 pharmaceutical companies. In fact, the team estimates that over 50% of all drugs on the market have been through some part of Instem's platform at some stage of their development.
The group recently acquired d-wise via the issue of 868,203, taking its share count up to 21,742,032. Instem has also purchased The Edge recently, and in 2019 it bought Leadscope, so it’s possible that an increase in operating scale can justify the recent strong share price.
As with a lot of tech stocks, valuation is a consideration given that Instem trades on a forecast PE ratio of 32.1 and a forecast PEG of 2.1. That means you are paying up for the Quality Rank of 88, especially with that near 30% increase in the share price over the past few weeks.
The Financial Summary shows good earnings per share progression but if you head over to the Income Statement and check out the Diluted Normalised EPS line you’ll see that earnings fell consistently for a long time before that.

Ultimately, smaller tech stocks are one area where investors can generate outsized returns, so it’s well worth looking at the merits of this company to see what the future might hold.
Highlights:
- Revenue +10% to £28.2m,
- Software as a Service (SaaS) revenues +25% to £8m and recurring revenues (annual support and SaaS) +13% to £16.9m
- Organic revenue growth (excluding Leadscope acquisition in November 2019) of 3% to £26.3m
- Adjusted EBITDA of £5.9m (2019: £4.9m)
- Reported profit before tax of £2.5m (2019: loss of £0.9m)
- Adjusted profit before tax of £4.0m (2019: £3.2m)
- Fully diluted earnings per share of 11.6p (2019: 5.7p loss per share)
- Adjusted fully diluted earnings per share of 19.1p (2019: 18.4p)
- Cash balance as at 31 December 2020 of £26.7m (2019: £6.0m) - reflecting operating cash generation and an oversubscribed placing in July 2020.
The results value Instem shares on 35.6x FY20 adjusted diluted earnings (with the adjustments being £664k in acquisition amortisation, £606k in non-recurring costs, and £208k in intercompany foreign exchange losses).
It’s worth remembering that both The Edge and d-wise were acquired after the reporting period, so the real scale of Instem is not reflected in these results. Instem says these acquisitions extend its reach across the drug discovery and development lifecycle.
The group estimates pro forma unaudited revenues and adjusted EBITDA for the enlarged group in the 12 months ended 31 December 2020 to be approximately £49m and £10m respectively (compared to a £150m market cap).
The current cash position after these two post-period acquisitions is around £14m but with deferred and contingent consideration payable of up to c£11.1m.
Conclusion
All the numbers are travelling the right way and it’s a relatively good performance given the wider market impact of Covid, but with a £150m market cap and a 680p share price, valuation is a consideration.
But there are two ‘strategically significant’ acquisitions to account for in the form of The Edge and d-wise, which together would have almost doubled adjusted EBITDA on a pro forma basis.
The acquisition strategy is interesting. Management competence in this tricky area is an important consideration, but if done responsibly it can add quite a lot of fuel to growth.
Management points to a ‘wealth of opportunity’ here. In fact, it is in discussions with a number of candidates now so we can probably expect more news in future.
As with most tech stocks it’s an asset-light balance sheet with quite a lot of intangible assets (in Instem’s case, intangibles of £18m make up 33.5% of total assets at year-end, although this figure has presumably increased following the use of cash in acquisitions).
Slightly more unusual for a tech stock is the presence of a pension deficit. This has increased year-on-year from £1.8m to £3.9m and is something to account for. To this I would add the acquisitive strategy and valuation as further risks, and I would like to know more about the period of declining earnings leading up to 2015 - particularly what changed, and why.
There was director selling back in July 2020 (presumably in the placing) but this could always be for retirement planning etc.
Life sciences is a good place to be, with global population growth and life expectancy underpinning increased demand for successful innovation here, so Instem looks interesting on a longer term basis. There is a presentation on investormeetcompany at 4pm today.
Concurrent Tech (LON:CNC)
Share price: 95.7p (-8.9%)
Shares in issue: 73,363,490
Market cap: £70.2m
Concurrent Technologies (LON:CNC) designs high performance Intel® processor boards, switches, networking, storage and software products for use in embedded solutions. It’s got a board manufacturing factory in Colchester.
The group’s products are used in the Defense, Security, Aerospace, Telecommunications, Transportation, Medical and Industrial markets and are designed to be operated in a range of temperatures and environments.
The semiconductor space is supposed to be doing well but the group’s shares are down c8% today and Stockopedia classifies Concurrent as a Falling Star with a declining Momentum Rank of just 23, so I’m curious to see what’s going on here.
Highlights:
- Revenue +9% to £21.1m,
- Gross profit +12% to £11.4m,
- Gross margin up 100bps to 53.7%,
- EBITDA down from £5.2m to £5.0m,
- Adjusted PBT down from £3.1m to £2.8m; PBT down from £4.1m to £2.7m,
- Adjusted EPS down from 4.38p to 3.75p
Earnings are down but the company is still operating and investing in R&D. Production and design & development have remained open throughout the COVID-19 pandemic and Concurrent has not needed any help from the government.
Exports made up 91% of group revenue and the group has nearly completed the shutdown of its R&D facility in India, with functions transferred to the UK. Savings made from ceasing operations in the Indian office will largely be reinvested to increase and broaden the skills and technical expertise within the UK team.
Spending on R&D increased to £3.89m in 2020 (2019: £3.51m), of which £1.88m was capitalised (2019: £2.26m). The group is expanding its current range of advanced technology products with a particular focus on the OpenVPX™ bus architecture, featuring the latest Intel processors.
Concurrent's long-standing chairman Michael Collins retired from the board in September 2020 after some 31 years of service and has been replaced by Mark Cubitt. Collins remains a Major Shareholder.
Although short term trading appears to have disappointed the market, longer term there are some characteristics to like here and so the company could be worth monitoring.
The new chairman comments:
The Group's proven ability to adapt to the challenges brought about by the pandemic, the overhead savings from closure of the Indian design office, its ability to provide a well-supported, UK designed and manufactured product, and the current record order book, which has seen a substantial increase during the first quarter of 2021, gives the Board confidence in the Group's continuing solid performance.
The group’s order book has seen a significant increase during the first quarter of the new financial year and its telecoms business is back in growth after last year's second half slowdown.
Conclusion
There are a couple of things I look out for here, namely:
- Founder owner (Collins has now stepped down but he retains a c6% shareholding),
- Stable shares in issue over time,
- Net cash position over time,
- Double digit operating margins and returns on capital,
- Compound annual revenue and earnings growth,
- Steadily increasing and well covered dividend payments.
But there are also some concerns. Obviously, Concurrent has disappointed the market today and it looks like results can be volatile from one year to the next. Profitability metrics look to be trending downwards recently, which is a worry.

The group also consistently spends a fair amount of capex. That’s not always a bad thing, as long as the company is spending on future growth rather than just spending lots of cash to maintain existing operations.
Concurrent is looking to grow organically and via acquisition in order to increase its potential share of the total available market. Its markets are still exposed to Covid disruption but on balance there’s enough about the group to warrant a closer look.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Thanks Paul and Jack, as always, for your succinct and value-add opinions.
I concur with your view that Belvoir is looking like a Coffee Can investment. I would also put Treatt into that can too!
Thanks for that ISAallowance re Concurrent Technologies (LON:CNC)
I had gathered that the £1m (last year) was insurance, but wasn't aware what for. I totally agree though that is is a substantial one off that should be adjusted out.
My point though was rather that the cost of closing the Indian R&D facility in the current year was also one off and should be adjusted out to give true 'underlying' performance and on this basis they managed to increase profits, despite some headwinds.
And on the subject of headwinds - I speculated that the increase in expensed (as opposed to capitalised) R&D costs might just relate to projects delivered in the year. In fact reading back to the interim results, I find this in relation to covid :
So in other words the increase in non-capitalised costs was due (at least in part) to the Indian design team not being so productive during the pandemic period (but still being paid), this should also therefore be considered a one off, although I would need to check that it is not double counted with the stated costs of closing down the Indian operation.Also in the interims they stated the expectation that the India closure would :
Again there is the possibility that this may be in part double counted in the numbers above. It's not clear though if this is the case and I will see if I can get some clarity.
Taken together with the additional impairment related to slower business (during the pandemic?) (which incidentally has nothing to do with gambling group 888 holdings! ) I can potentially (if there are no double counts) a profit swing of up to £2m between FY20 & FY21 .
If that were true i would be hugely significant to a company that has just delivered annual PBT of £2,8m
I think there must be some degree of double count within that, otherwise they would surely be more ebullient, but I will see if I can gauge how much.
Instem (LON; INS)
Jack, thanks for your write up.
The director sales were into the placing. 2 directors were sold some shares as part of their retirement plan whilst a third sold as his options were soon to expire, a close period was likely to ensue due to potential acquisitions and the tax due when options are convert into shares in the US is due immediately.
There is a very good note on Progressive website which shows the significant increase in forcasts the 2 acquisitions in March are expected to make.
I hold
Just a little local reconnaissance feedback from a walk around my "village" (area on the edge of London). Local Indian which has a small garden is fully booked. The men's hairdresser has a huge queue and has had all day. At least one of the pubs has a full beer garden (cannot see into the others from the road). Weather is nice now if a little chilly so that will be encouraging people. The large M&S at Brooklands was very busy this morning with all of the floors now open.
So people seem very keen to get and and buy stuff / do things.
Town Centre where I'm lodging is also very busy and bustling.
People appear to be unlocking themselves. Older people are about but with face nappies on. Its good that the youngsters have their jobs back again. Great to see outdoor bars, restaurants and cafes open with patrons again.
Maybe retail and civic amenities will return?
The last time TET were mentioned in this report, Paul said that they were expensive, and a good quality company, and the price was already factoring in all the good news. That was when the shoe price was roughly 800p. So we are now at 1000p(c) and TET have yet to move into their fantastic new site, and they have managed to do well during not only the construction of this site, but through covid/lockdown as well.
I said when the shares were 800p that I was holding them longer term, and expected them to double, and that is still the case, and my own view is that the more people are focusing on what they are eating and drinking, in terms of flavours and quality ingredients, the more TET will prosper.
As I repeatedly state in these reports, I have absolutely no idea what share prices will do, because that's down to market sentiment. I just examine the fundamentals. By flagging up that a share is expensive, the idea is to stimulate debate & thought. Today, and previously, I've flagged that despite Treatt (LON:TET) looking expensive, the market must believe it will beat forecasts. Hence there could be a good reason why it is expensive, and we've discussed the various points you mention before. For example, I've repeatedly questioned why broker forecasts showed such a small uplift for the new factory coming on stream, which didn't look right.
If readers do your own research, and come to the conclusion that the company's prospects are good, and that it is likely to beat broker forecasts, then that justifies taking a different, and more positive view about the company's valuation.
Your comment reads as if you think this site is a tip sheet. It isn't. We're just looking at the fundamentals, and giving a view on them. Readers then agree or disagree, as you see fit. Also readers can spend more time researching, in more depth, than we can in these reports, because we're trying to cover about 500 companies!
TET shares are expensive, and they were also expensive at 800p. Although the positive update, and big broker upgrades in Jan 2021 reset things, so any opinion I expressed prior to that was obviously no longer relevant, because the fundamentals had sharply improved.
Anyway, you've been very clever, so have a pat on the back.
Paul.
P.S. We're all geniuses at the moment. You could have picked practically any small cap stock 6 months ago, and be crowing about how right you were now, because the entire £SMXX index is up 50% in that time!
"P.S. We're all geniuses at the moment. You could have picked practically any small cap stock 6 months ago, and be crowing about how right you were now, because the entire £SMXX index is up 50% in that time!"
I'M NOT CROWING OR PEACOCKING but
I've made more than 30% (I guess) of my 50 year's lifetime's wealth in the past 16 months.
This doesn't add up.
It is not genius. I think this is an "anomaly" and a statistical aberration.
We were here. Others were not.
It was NOT like this for the first 48 and 3/4 years. It used to be hard to make a 5 figure profit and quite easy to lose 6.
We are not in heaven. There is no free money. Money does not pour down from the Central Bank and Market unending without some counter reaction.
Somebody tell us when the music stops playing.
Sounds about right to me! I fear free money means less valuable money.
I shop at Asda... and walk! ;-)
I wasn't meaning that I was clever, or you had somehow made a mistake, so apologies if that is how it came over. Not my intention at all. I was just adding a vote of confidence in TET really.
Hi Paul
We're all geniuses at the moment. You could have picked practically any small cap stock 6 months ago, and be crowing about how right you were now, because the entire £SMXX index is up 50% in that time!
That is true, but it was predictably true at the end of last year. With vaccines on the way, central banks helicoptering cash and bond yields near zero it was pretty much inevitable that lots of money would find its way into stocks.
Unfortunately, although it was easy to forsee this starting it's pretty much impossible to see how it ends. We do, however, know what happens when it does - a lot of people who've made easy money on the way up will lose it on the way down as they mistake luck for skill.
The trouble is it could take years for normalisation to happen. Or we could see inflation spike and governments forced to raise interest rates, which will make 2013's taper tantrum look like a stroll in the park.
In the end, though, what can we do? Watching markets run away while idiots make money isn't really an option so discipline in terms of balance sheets and real cash flows with the odd exciting side hustle seems to be the name of the game.
No idea how this ends, but presumably it will be spectacular when it does.
timarr
P.S. Usually at this point we start to see companies coming to market and, lo - today alone we have Darktrace, Pension Bee and Semper Fortis Esport. Suddenly PE and VC money is being cashed out, which is always an interesting signal.
Thumbs up Timarr,
Although it is not genius, our current winnings come to us because we invested and took risk with our hard earned.
I so wish all my friends had done the same.
Spot on about the ending:-
We don't really have the choice to sit 100% in cash and we certainly can not take our eyes of the data and news feeds.
At least we are prepared and thinking about the next phase and possible scenarios.
Mossad upset an Iranian nuclear facility over the weekend. It will be something nasty. Maybe China encroaches on Taiwan, Russia on Ukraine.
Another request for some comments on Xpediator (LON:XPD) please. Might be popular with investors here after featuring on Mello a few months ago.
Hi Poker111,
I've updated my evaluation based on today's finals below, if of interest.
https://www.stockopedia.com/co...
BVS
Hi Poker111,
I did a positive review of the trading update from Xpediator (LON:XPD) here on 29 Jan 2021, concluding that it was worth a closer look, with strong trading & a positive outlook.
I'm not interested in low margin haulage type businesses, so it's not something I want to spend more time on again today, with more interesting companies reporting, and we're out of time now too.
Sorry about that.
Regards, Paul.
Mercia Asset Management (LON:MERC) have announced a Mercia Brief for analysts and investors, next Tuesday 20th April at 4pm. To cover Mercia's team, portfolio companies and provide an overview of the Group's recent performance. The presentations will be followed by a Q&A. Register here.
We've just published Ra International (LON:RAI) FY20 results presentation given 30.3.21. Good overview of all the moving parts.
Further to Belvoir (LON:BLV) results today, I'll be interested if there's a read across to Property Franchise (LON:TPFG) who have results the week after next. Property Franchise (LON:TPFG) have a results webinar on 28th April, 11.30. Register here.
Tomorrow, Tracsis (LON:TRCS) give a H1 presentation, as part of their roadshow. The pipeline looks strong, and rail business is starting to evolve in the US and other areas. Traffic Data & Event Traffic Management business should strengthen as CV19 lifts. Register here.
There could well be some read across from Belvoir (LON:BLV) to Property Franchise (LON:TPFG), in case you did not see it Jack did an article on both at end of 2020: https://www.stockopedia.com/content/the-property-franchise-group-and-belvoir-two-high-quality-small-caps-gearing-up-for-growth-55501
Time Out (LON:TMO) another excellent primary bid (PB) offering. The placing was at just 35p at the beginning of the month. New stock received on Friday. The shares are currently 60p. Best Of The Best (LON:BOTB) primary bid secondary offer at £24. The shares should be received tomorrow. Currently around £33 to buy after Slater Investments announced a 9.12% stake.
For balance they also did Deliveroo Holdings (LON:ROO) and that has been a complete disaster although the max investment allowed was just £1000.
More power to PB I say. For years, private investors have been locked out of placings at big discounts.
Vertu Motors (LON:VTU) could grab a tail wind from this :
BERENBERG RAISES LOOKERS PRICE TARGET TO 90 (45) PENCE - 'BUY'
A mere doubling in target price, huge money pouring into cars is the brokers view....
Paul will you let us know what you get in Primark? :-)
Just passed my local Primark and there is a queue of over 200 so he might be gone a while...
Good morning fellow Investors,
OT to The Daily SVCR.
XLMedia (LON:XLM) - There is a RNS up today.
https://www.stockopedia.com/share-prices/xlmedia-LON:XLM/news/xlmedia-plc-holdings-in-company-urn:newsml:reuters.com:20210412:nRSL0576Va/
SAS Premier Investissement (The Mitterands) raises their position from 23.7% to 27.98%.
This 4.18% increase in the no 1 shareholder's holdings, (I would have thought), is a good sign of forward looking confidence in XLMedia (LON:XLM) and partly what's driving the share price upwards.
SR 87 Q 84 V 32 M 98 Broker Target +17%
but
Magic Formula 2 Altman-Z 4 * but with a write down last year in mitigation.
I would expect a re-rating if the FY Results on Monday 19th April 2021 does what it is supposed to do.
+73.94% on my journey.
Have a nice day.
Does anyone have any firm views on Pelatro (LON:PTRO) ? I liked them having seem them at Mello, although many were rightly irked at the news of some director remuneration which was unorthodox but somewhat brushed aside.
The market seems to like the results today, which on a quick skim seem pretty poor. However it's all meant to be about the shift to a recurring revenue model now, and Cenkos today gushes:
"The business model has been transformed by the focus largely on
recurring customer engagements. The higher quality revenue base is
accompanied by very strong growth prospects in both core and new
markets. Increased revenue visibility means that we are upgrading our
FY21E forecasts. Buy".
I'm invested but a starter position, and have been unsure really ever since. Is a bit of patience required or is this always on the cusp of greatness and never quite making it? Cenkos seem to think the former but they are their Broker.
Thanks for the Instem (LON:INS) results write up Jack (I hold)
Please can someone cover the FY results from Vector Capital (LON:VCAP) which floated in December 2020? THey look pretty good with a very undemanding valuation:
· Loan book growth of 8.3% to £36.4m (FY19: £33.6m)
· PBT growth up 19.3% to £2.3m (FY19: £2.0m)
· EPS increase of 19% to 5.58p (FY19: 4.69p)
· Revenue growth of 19.4% to £4.3m (FY19: £3.6m)
· PAT up 18.8% to £1.9m (FY19: £1.6m)
· Proposed final dividend for the year of 1.43p per share
Thanks for the good Instem (LON:INS) write up Jack (I hold)
Please can someone cover Vector Capital (LON:VCAP) which floated in December and has issued what seem to be good FY results today:
· Loan book growth of 8.3% to £36.4m (FY19: £33.6m)
· PBT growth up 19.3% to £2.3m (FY19: £2.0m)
· EPS increase of 19% to 5.58p (FY19: 4.69p)
· Revenue growth of 19.4% to £4.3m (FY19: £3.6m)
· PAT up 18.8% to £1.9m (FY19: £1.6m)
· Proposed final dividend for the year of 1.43p per share
The valuation doesn't look very demanding at all.
Good luck with finding a nice pint Paul. Looking on with with slight envy from north of the border.
Concurrent Technologies (LON:CNC) finals today are positive. Revenue, gross margin, profit, dividend and cash all increased. SP is down 9% as I type this, perhaps because of the comments below
"The Board is taking a cautious approach to revenue
growth in the coming year because of the continuing uncertainty caused
by the COVID-19 outbreak and the delays seen to some programmes
potentially moving revenue from 2021 to 2022. However, the Group's
proven ability to adapt to the challenges brought about by the pandemic,
the overhead savings from closure of the Indian design office, its
ability to provide a well-supported, UK designed and manufactured
product, and the current record order book, which has seen a substantial
increase during the first quarter of 2021, gives the Board confidence
in the Group's continuing solid performance."
Yes my take was earnings delayed so investors just think there is more immediate returns to be had. Great company and I will look to add if it drops into the 80s!
FReng.Re CNC I was a bit shocked at the reaction. I know they say sell on news. I think the main issue despite all the good news is that the EPS has dropped. I dont understand how that is as everything going up but the share price. Is there an accountant out there? The business to me looks as sound as a pound and so long as they keep upping the div and beating expectations I can't imagine it every not being a part of my PF. I started investing when it was about 19p!
re Concurrent Technologies (LON:CNC), the update says that they spent more on R&D this year, and capitalised less of it. That looks to me, a non-accountant, as if it accounts for most of the difference, looking at the adjusted EPS. I agree, the reaction doesn't look very justified to me, though I think the PER is historically on the high side for this company. I don't hold, but it is an interesting company.
Concurrent Technologies (LON:CNC)
So yes revenue and Gross Profit are both up, but actually profit / adjusted profit are both down, aren't they?
The EPS looks like quite a miss, although I don't understand the adjustments on the StockReport.
The company says :
Adjusted EPS for 2020 was 3.75 (2019: 4.38)
Whereas the StockReport ('normalised') has 6.12p for 2019 and 6.10p forecast for 2020.These don't look like for like. Nevertheless the SR suggested broadly flat EPS whereas the outcome is -15%.
Doesn't that explain the share price reaction?
I don't mean that as a comment on Concurrent Technologies (LON:CNC) as an investment , I've not looked before, but tempted from what I've just read to have a look in future.
Actually having had a further look at Concurrent Technologies (LON:CNC) I believe that they are being overly-conservative in their 'adjusted' earnings numbers.
The only adjustment they appear to have made is to exclude £1m of other income (c. £810k net of tax) from the prior year figures.
However in 2020 they spent £690k (assuming c. 560k net) on closing down the Indian R&D facility. Surely it is reasonable to treat this as a "one-off"?
On this basis I believe they have actually delivered a small increase in adjusted EPS (from 4.38p to 4.53p)
There are also a couple of other things to consider though.
1. They expensed £2.01m of R&D in 2020 vs £1.25m in 2019. The fact that is the expensed portion suggests to me that it is proper to revenue of the year in question, so probably should not be consider a one off.
2. In light of the slowdown in the sales of some projects, an unusually large impairment charge of 888 Holdings (LON:888),579 (2019: £483,630) was included during the year to reflect relatively pessimistic cash generating expectations of itemised projects.
Again not something that we should regard as a "one off" as such, but a relatively material change (Pandemic related?) that should be noted. I'm curious why they use the term "pessimistic" rather than "cautious".
The outlook statements are a bit strange, there is the mention of possibly some revenues being pushed out from 2021 to 2022, but on the other hand there are comments suggesting everything is going swimmingly.
I've taken a small cautious initial position here now, maybe too soon, but we shall see.
As there are others here that looked more closely, there are two things that puzzle me, if anyone can answer them.
1. They say the have no debt, yet the incurred finance costs of £84k (double what the faced in the previous year). Do the use factoring?
2. They have declared a second interim dividend for the year, but make the point of telling us "As in previous years, the Directors do not intend to recommend a final dividend."
What is the significance of calling this a second interim dividend rather than a final?
Re. Concurrent Technologies (LON:CNC) , I believe the £1m prior year "other income" was an insurance payout following the death of a director, so very much one-off, and quite material as an adjustment.
Concurrent Technologies (LON:CNC) (no position)
Hi Gromley
"1. They say the have no debt, yet the incurred finance costs of £84k (double what the faced in the previous year). Do the use factoring?"
I believe the finance cost is to do with lease payments. I recall seeing something similar with another company and after doing some digging it seemed legit, though I can't recall the logic behind it.
For added support of my assumption please find below the Concurrent Technologies (LON:CNC) 2019 AR Cash Flow Statement.
You'll see that there were no finance costs or lease payments in 2018, so it probably is to do with the new IFRS16 rules that came into play from 2019 onwards.
Cheers
A
Doh ! I really should have thought of that given how often I go on about IFRS16, but thanks for pointing that out abtan.
That also explains why the figure has doubled in 2020 when compared to 2019. The only seem to have applied IFRS 16 from H2 2019 (odd because the standard should have been applied for the full year 2019 under the regulations - not worth chasing back on that though I suppose.)
Oxford Street: Wooing shoppers back 13% of Oxford St is boarded up or closed.
Oxford Street was a very busy tourist shopping destination, so that's a reminder for me that many shops will need to see a genuine return to normality including tourists and foreign language students etc. coming here to get back to where they were pre-pandemic. So heaven knows when that will be.
And along the way the government has removed the VAT free shopping perks for tourists and fallen out big time with China so they may just go to Paris instead.
The other attraction, of London, Cambridge and Oxford, is learning English, and the history. Paris can provide culture and history, but not English
Regarding Treatt (LON:TET) , I thought that Melwin Mehta made a very interesting point at the recent Mello session. He said that when huge companies such as Pepsi and Coca Cola visit their current head office in Bury St Edmunds, which is a collection of small houses, they immediately write Treatt off as a minor player. Perhaps when the new UK HQ is up and running, it will open up new possibilities of expansion involving much larger customers than they currently serve.
I am a big fan of Treatt and live relatively nearby to Bury St Edmunds. I think you make a great point, and they have managed to deal with building the new HQ and covid and lockdown without any disruption to their financials or performance. Quite the opposite in fact. I really think they are just going to keep growing.
Good FY12/20 results from Belvoir (LON:BLV) this morning, the lettings and financial services agency, against the backdrop of the pandemic. I have held this for a few years now and it has been a nice earner - up 40% so far this year for me and has a 7.2p dividend (c.3.5%). There is a Shares magazine webinar tomorrow evening featuring the company which is a good opportunity for private investors to listen and ask questions.
By way of background, in recent years it is the addition of financial services and some good acquisitions which have driven a re-rating in the share price.
Points to note:
Share price this morning is around 210p. But if adjusted EPS is indeed 19p+ for FY21 that is probably a little cheap, albeit I wouldn't expect this to reach a multiple higher than about 13-14x. With 24 years' profit growth behind it, and continued acquisitions, I am pretty happy continuing to hold this one and may add further with any share price weakness.
Elixirr International (LON:ELIX) might be worth a look as they provided their first maiden FY20 results since IPO. Has been a successful one so far. Slater holds ~9%. Results came in slightly ahead of upgraded expectations. An acquisition has also been announced. The broker has significantly increased the FCs for FY21 and provides FCs until 2023. Available free at FinnCap's website
https://www.stockopedia.com/sh...
Yes I hold as declared on Twitter some time ago
@mginvestor
Yes, I hold too. Very high quality management team, quietly building the next Accenture.
Look forward to your update on Belvoir (LON:BLV) . Its a cracking little company and todays results look pretty impressive in a tricky market last year. There's a great management team at the helm who seem to be able to deliver whatever the market backdrop.
Xpediator (LON:XPD) if you can Paul, final results.
CNC have a decent set of results as forecast. Cautious outlook. Relocating their R&D facility back to UK from India looks like a good decision under the current circumstances, and have managed and negotiated around the pandemic without the need for government support with improving margins, revenue, cash and dividend payments. Hopefully the market will be happy if not exactly exhilarated.
A bit later on = 1010 - the market didnt like it a lot with Concurrent Technologies (LON:CNC) falling around 9%
Morning Paul and Jack.
Instem (LSE: INS) FY Results to 31st Dec 2020 published this morning in line.
'a leading provider of IT solutions to the global life sciences market'
located in the 2 high growth sectors of Software services and life Sciences
Rev + 10%.
Recurring revs up.
Margins up, strong cash generation.
Clear visibility of revs and strong pipeline.
Post period 2 immediately earnings enhancing acquisitions providing scale and cross-selling opportunities.
Further acquisitions under discussion.
Phil Reason, CEO of Instem, commented: "The performance during the Period highlighted our resilience - especially given the COVID-19 backdrop. Our proven model continues to generate strong cash flows while the combination of increasing demand for regulatory-backed solutions and a growing demand for artificial intelligence and in silico solutions in the drug discovery process underpins our confidence in further leveraging our product base. Importantly, we already have good visibility for the current year with growing SaaS revenues and a strong pipeline.
"We are extremely pleased with our continued strong organic growth and increasing ability to cross sell to existing and new clients. Furthermore, we are primed to build on this momentum, having strengthened our proposition post Period end. The recent acquisitions of d-wise and The Edge highlight our ability to add scale and leverage existing customer relationships with a view to further enhancing earnings and profitability, while providing a strong platform for continued growth. In addition, we are continuing discussions with a number of other potential acquisition targets.
Delighted with my number 2 holding.
Presentation on IMC today at 4pm.
FY and outlook worth reading.
Michael
I'd be interested in thoughts on Surface Transforms.
Hi CamRaid,
There's not really anything for me to say about Surface Transforms (LON:SCE) results.
It's still loss-making, and the figures are poor. However, as everyone knows, it's apparently winning big orders to kick in for future years. Plus it recently raised £19m (after fees) to fund production ramp up.
Therefore valuing the share is all about digging into the future potential, estimating what contracts might be worth, etc? That's beyond the scope of these reports, which are mainly about reviewing results. There's no point in doing that for SCE, as it's all about future growth, not historic figures.
Sorry about that.
Regards, Paul.
My morning smallcap tweet:
Batm Advanced Communications (LON:BVC) Dev Clever Holdings (LON:DEV) GYG (LON:GYG) Live (LON:LVCG) Innovaderma (LON:IDP) Cake Box Holdings (LON:CBOX) £C4XD Surface Transforms (LON:SCE) Xpediator (LON:XPD), Belvoir (LON:BLV), Instem (LON:INS)
BATM Advanced Communication (BVC) Telco Systems subsidiary forms strategic partnership with albis-elcon, a supplier of networking products and systems, to jointly offer network function virtualisation. Also BATM has begun to generate revenue under its three-year licensing agreement with PCCW Global. [SP=97.1 Cap=428m]
Dev Clever (DEV) to buy Veative Labs Private Limited, an Indian subsidiary of Veative and buys the immersive education materials that will be utilised during the near-term roll-out of co's existing partnership agreement with Veative Labs. Pays £55m in paper, 20% of enlarged capital. [SP=36 Cap=214m]
GYG (GYG) will consult holders re approach from Harwood. [SP=87 Cap=41m]
Live Company (LVCG) guides FY(Dec) rev £1.9m. No substantial rev expected until Q3/Q4. Chmn says "My personal mission remains to steer the company back into profitability". Yeah, that is your job. [SP=5.4 Cap=6m]
InnovaDerma (IDP) expects to publish prospectus and circularre mooted fundraising later today. [SP=40.25 Cap=7m]
Cake Box (CBOX) guides H2(Mar) LFL up 15%, FY rev up 16% and adj pretax in line. [SP=252 Cap=102m]
C4X Discovery (C4XD) exclusive worldwide licensing agreement with Sanofi worth up to €414m, for oral pre-clinical IL-17A inhibitor programme. €7m upfront, rest is potential development, regulatory and commercialisation milestones plus royalties. Sanofi will develop and commercialise an oral therapy for the treatment of inflammatory diseases. [SP=39.63 Cap=91m]
Surface Transforms (SCE) FY(Dec) rev flat at £1.95m, pretax -£2.9m (-£3m). Outlook "when we go into production on OEM 8 and Aston Martin Valkyrie in 2021, at which point we will be profitable and generating cash from operations, before further capital investment." [SP=73 Cap=142m]. I hold.
Xpediator (XPD) FY(Dec). Current Q1 ahead of management expectations. [SP=56.75 Cap=80m]
In line: Belvoir (LON:BLV) Instem (LON:INS)
It's re-opening day today, with retailers & outside hospitality opening up again.
And as everyone charges out to the pub garden ... it's snowing :-/
Decent results from Belvoir (LON:BLV) - 20% increase in PBT with tiny debt levels. The property franchise model has been very resilient throughout the last year.
Also Treatt (LON:TET) trading update appears good - 14% increase in revenues with new facilities coming on line. Bit expensive, mind.
timarr
Yes Paul,
How the High Street re-emerges will be fascinating. Since taking up online grocery shopping I honestly struggle to think of an area of shopping that I am not perfectly happy doing online.
I think we are light here on the feminine perspective regarding the re-opening of the shops.
I know my feminine partner is sick of sending 'online' jackets and shoes back as they just don't fit or look good enough. She alone has enough pent up demand to support a dozen independent shoe shops...and maybe the odd chain. :-(
re feminine shopping patterns, all the shops used by every woman whose shopping habits I know have gone bust, bar Primark. I would guess the investment opportunity is for anyone able to move into the space. For what it is worth - clothes chains are not an area I follow.
Joules are still trading on the high street, I think New Look are too... albeit not in flippin' Northern Ireland where everything is still locked down :-(
@JohnEustace Don't any of us know someone female we could ask ... ?
My research (sample size 1) delivers a strong preference for online shopping.
@FREng My sample size of 3 can't wait to get back to the shops. I'm happy to leave them to it.
I started buying from Amazon before I even had a web browser, sending the orders to them in Seattle via Compuserve so no prize for guessing my preference!
New Capital Employed episode just published featuring Theron de Ris, Founder and Managing Partner of Eschler Asset Management.
Theron gives an overview of his investment style, and his thesis for investing in two companies. One company in the mineral royalty space, and the other a value orientated asset management firm.
https://open.spotify.com/episo...