Small Cap Value Report (Mon 13 Jan 2020) - QTX, AUG, IND, CPC, INS

Good morning, it's Paul here. Please see the header for companies I'll be covering today.
Estimated time of completion - the bulk of today's report should be finished by 1pm. However, I reserve the right to carry on doing more writing this afternoon, as I've got nothing else specific planned to do today.
Update at 13:59 - today's report is now finished.
A bit of macro stuff to start off with;
Barclaycard - consumer spending data
I've tracked down the Barclaycard consumer spending report for Dec 2019, which is here. It's well worth a look, as there's some useful intelligence in there for investors, relating to consumer spending on debit & credit cards.
In particular, this graphic (below) shows the winners & losers by sector - looks like pubs are a good place to be invested at the moment (hopefully augurs well for the update from Revolution Bars (LON:RBG) - one of my biggest holdings personally - this Wednesday Friday [thanks to Simoan for correction] ).
I hope Barclaycard don't mind me reproducing their very informative graphic here, seeing as it's already available free online;
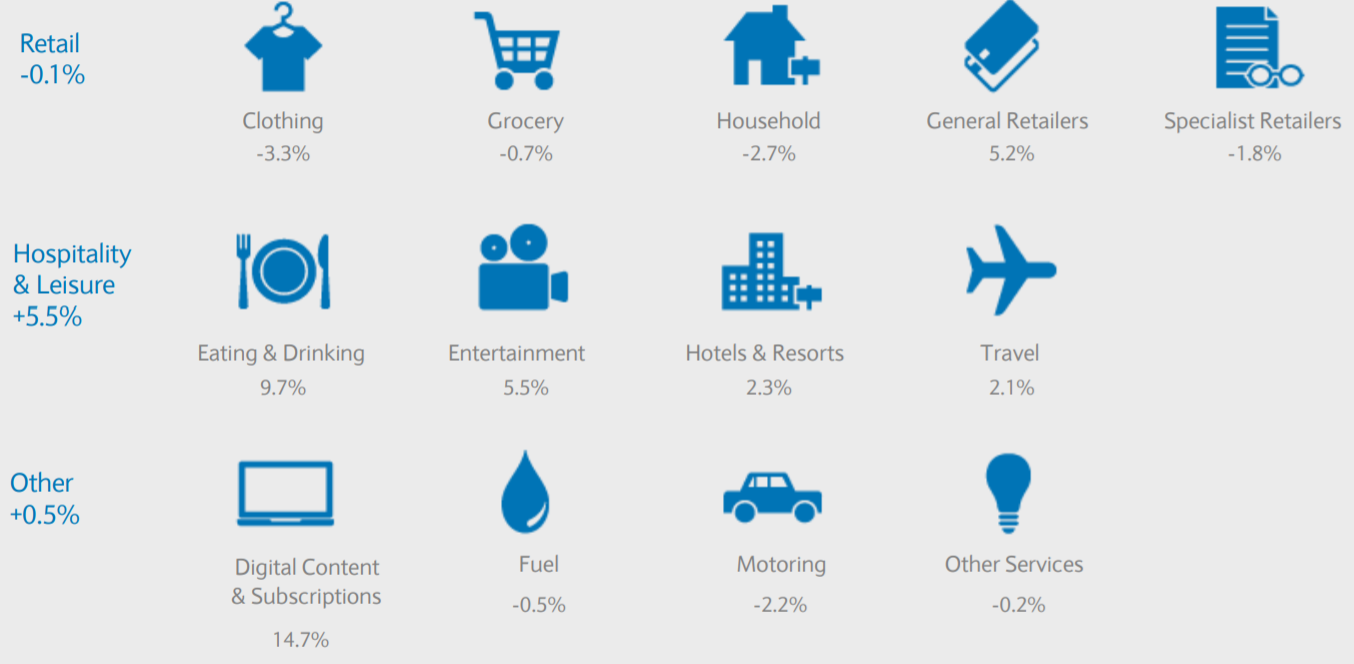
NB. the reason why some of the Barclaycard data might look strange, is that it only covers debit & credit card spend, and hence excludes cash transactions. Given that contactless payments are replacing many cash transactions, then that skews the data.
For example, I sometimes (not in Dry January though) browse my online banking app, and see 5 or 6 consecutive debits labelled "The Lord Clyde", which reminds me that I stopped off at my local on the way home. They're usually £4.50 each, which isn't too bad, but it's when I see the later transactions doubling or tripling, that I groan and think, who was I buying drinks for?! Oh yes, so and so.
My point being, that in previous years, I paid using cash. These days, I rarely use cash at all, instead using contactless for almost everything. This effect is likely to be flattering the growth reported by Barclaycard of 11.7% growth in spending in pubs. Takeaways are up 12.5%, so somebody clearly did say Just Eat!
How long before Governments start abolishing cash altogether, in order to reduce tax avoidance, and exert more control over everybody? Once that happens, it probably won't be long until an electronic payments tax is applied - e.g. in Zimbabwe the Govt imposed a 2% tax on all card payments. It's much easier to collect in than VAT, so could such a tax eventually replace (or more likely supplement) VAT & sales taxes here maybe, potentially set at different rates depending on the type of transaction?
Deloitte CFO survey
This is another data source which I often find referred to in newspaper articles, etc. I've decided to track down the original data sources myself, and share them with you here, so that we can do our own analysis. After all, it's surprising how often mainstream journalists make basic errors, - e.g. muddling up retail sales volume, and retail sales value. And/or headlines which bear little relation to reality - this or that has "slumped", when it's moved about half a percent, is typical!
The latest report, using data gathered between 13 Dec 2019 to 6 Jan 2020 (i.e. immediately after the general election result), shows a remarkably good result;
The latest survey of UK Chief
Financial Officers shows an
unprecedented rise in business
sentiment. The fourth quarter
survey took place in the wake of
the UK general election, between
13th December and 6th January.
Confidence has seen the largest
increase in the 11-year history of
the survey taking it to its highest
ever level.
It will be interesting to see if confidence sticks at this level, or partially slips back again? There could be an element of relief that the extreme left Corbyn threat [Edit: to business profitability, through higher Corp Tax, and stealing 10% of the shares in listed companies from their rightful owners, etc] has disappeared for the time being?
Even so, this is very encouraging news. I had been thinking in terms of the recent large rally in UK small/mid caps being overdone, but maybe it's justified, given this positive outlook survey?
Anyway, well worth a look, so here's the link again.
I'll diarise to comment on this & the Barclaycard reports, as a regular feature here in future SCVRs, as it's useful stuff that can help guide & improve our investing decisions.
Quartix Holdings (LON:QTX)
Share price: 383p (up 5% today, at 08:49)
No. shares: 47.7m
Market cap: £182.7m
Quartix Holdings plc, one of Europe's leading suppliers of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the year ended 31 December 2019 ...
Background - both Graham and I have written positively about Quartix before. Things we like about it are;
- Strongly cash generative
- High margins
- Recurring revenues & low customer churn - therefore great visibility
- International expansion going well, with more to come - should continue driving growth
- Good dividend yield
- Strong management & reliable outlook statements
- Clean accounts (e.g. fully expensing, not capitalising, product development)
My report on the last interim results, is here on 24 Jul 2019.
There was a nice opportunity to buy this share last year, because it looked expensive on a PER basis. However, as we pointed out here at the time, this was because Quartix was incurring short term marketing costs to expand in overseas territories. This suppressed short term profits, for the benefit of the long term.
Another similar factor, was that Quartix has been deliberately winding down its low margin insurance telematics business. This made total growth look anaemic, when in fact the main "fleet" business was growing nicely.
Trading update today - it's moderately good news;
The Board is pleased to report that it expects revenue, profit and free cash flow to be slightly ahead of current market forecasts.
[1] The Board believes that consensus market expectations for 2019, prior to this announcement, were as follows: revenue: £25.3m; adjusted EBITDA £6.8m; free cash flow: £5.7m.
Following best practice, as you can see, the company provides a footnote to tell us what the consensus forecasts are - this is so helpful, as it saves everyone time & hassle.
Memo to all companies, brokers, and PRs: please make sure trading updates for all your companies include consensus forecast details. Why wouldn't you include details that help readers digest the statement more quickly, easily, and accurately? Readers don't want to rummage around elsewhere, trying to find out what the forecasts are. Just tell us in the RNS! Time is really at a premium between 7-8am each weekday, so anything that speeds up the process of analysing a trading update is very much appreciated.
My only slight quibble above is that I would have liked to see the adjusted profit before tax, and adjusted EPS figures, which are the key profit measures for me. Follow up memo: EBITDA is not a figure I particularly want to see, because companies have different policies on capitalising development spend, therefore it's not a reliable comparative.
Adjusted EPS is probably the most useful number from my point of view (as that enables me to quickly value the share using PER), and this hasn't been given in this update either.
Fleet business - this is the core business, and it's doing well;
The Company made excellent progress in its core fleet business in the UK, France and the USA, and entered a range of new territories with encouraging results. Revenues in the fleet business are expected to have grown by around 10%, accounting for approximately 80% of Company revenues.
A table is given with details of growth by region (fleet business only, not insurance telematics), which shows good progress;
- New installations of 43.8k units in 2019 (up 39% on 2018)
- Subscriber base up from 123.2k units to 150.6k units (up 22%)
However, this has only translated into revenue growth of 10%, which seems low. I appreciate that revenue from new customers won would be spread over the year, so that a new client signed up in say November, would only contribute a small amount of additional revenue in 2019. However, that effect would be the same every year, e.g. a new client signed up in late 2018 would have contributed very little to 2018 revenues, but a full year in 2019.
I've emailed the company to query why revenue growth of 10% is lagging behind subscriber growth of 22%, and will edit the article if/when I get a reply. It looks like unit pricing might be under pressure, but nothing is said about pricing in today's update. Broker notes might elaborate on this point, perhaps?
EDIT at 12:23: Quartix has responded to my query re pricing;
- Yes there is pricing pressure in the industry, and always has been.
- Self-install units are sold at a lower price than installed units, hence revenues (but also costs) are lower - so not a problem for profits. [some overseas growth is coming from self-install]
- New installations produce avg 6 months revenues in year 1
End of edit.
International growth - a self-install product means that Quartix can expand overseas without the need for boots on the ground - a key point, and clearly very positive. This has driven expansion in Spain, Germany, Poland, and Italy.
My opinion - as mentioned before, there's a lot I like about Quartix.
The share has re-rated from a PER of about 20, to a forward PER of about 30. The dividend yield is still fairly good at about 3%.
In my view, the price now looks up with, or maybe slightly ahead of events. So it might be a good time to think about possibly banking some profits with a top-slice? Obviously that's for each investor to decide for yourself, I'm only giving my opinion.
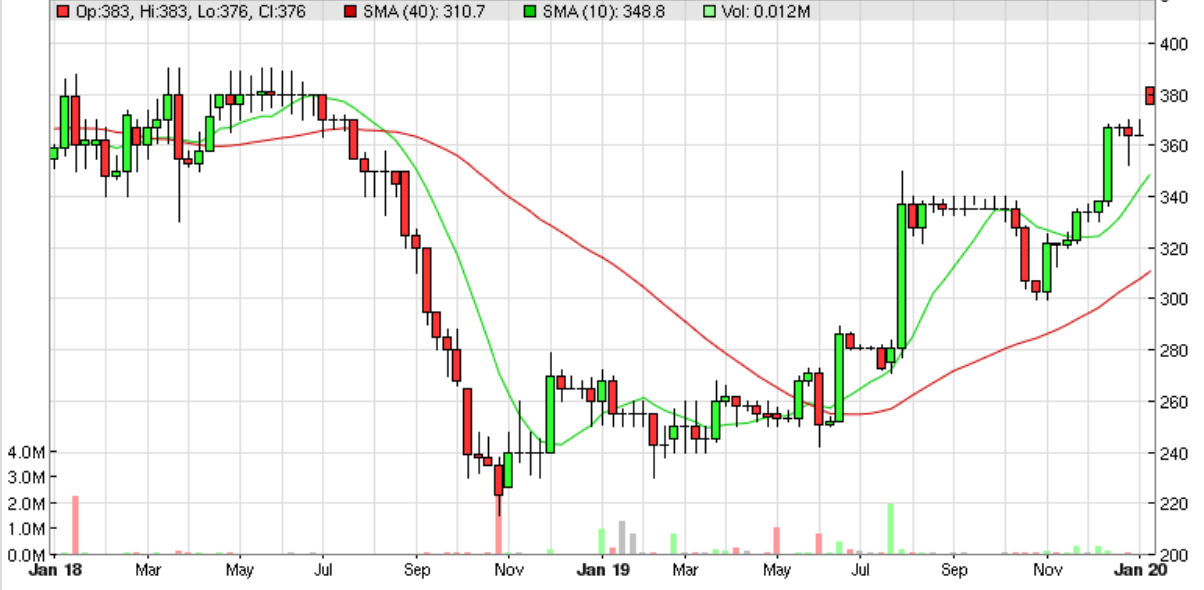
Note that the Stockopedia computers laugh in the face of my caution, giving Quartix a "High Flyer" classification, and a high StockRank. Or more seriously, the StockRank is saying that concerns over valuation are outweighed by very high quality & momentum;
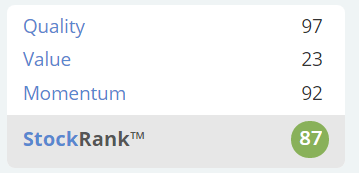
Highly rated shares are often long-term winners. The trouble is that along the way, the market often imposes brutal price corrections. It can be very difficult to keep your nerve during such big pullbacks. Hence why I think there's a lot to be said for top-slicing some of the profits, after a big rise in price, if the valuation is looking stretched. We can always buy back at a later date, and we can't buy the dips if we don't have any cash on the sidelines.
Augean (LON:AUG)
Share price: 211p (up 0.5% today, at 10:32)
No. shares: 104.1m
Market cap: £219.7m
Augean, one of the UK's leading specialist waste management businesses...
I hope some readers managed to take advantage of the very positive update from this company, which I reported positively about here on 16 Oct 2019, with one of my "worth a closer look" conclusions (which means that I really like the look of this, but haven't had time to dig any deeper yet, so am not 100% certain). The share price has risen 57% since that report.
Today it says -
trading has continued to be strong through the final quarter and it expects, subject to audit, to report adjusted PBT for the year ended 31 December 2019 at least in line with recently upgraded consensus market expectations of £18.4m.
Great stuff!
Valuation - the share price is up a lot, so have we missed the boat? Possibly not, as these valuation stats still look good value - as I've highlighted below, we have:
low forward PER of 11.8, NTAV (i.e. Price to Tang. Book) is fine at 4.56, and great quality scores. No divis though. Also note (not highlighted) that the PEG is attractively low, at 0.66, i.e. earnings growing much faster than the PER, implying the share is cheap if that earnings growth can continue.
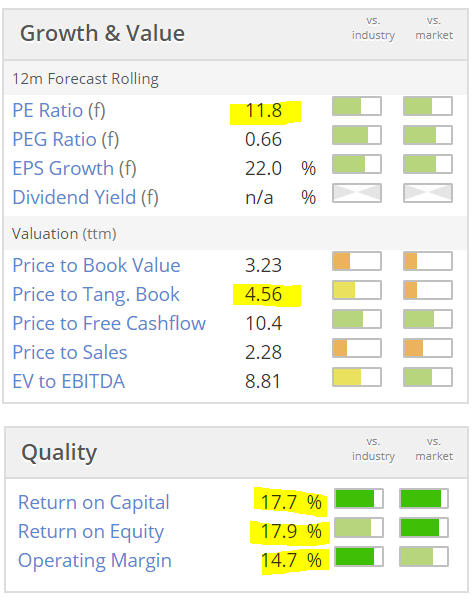
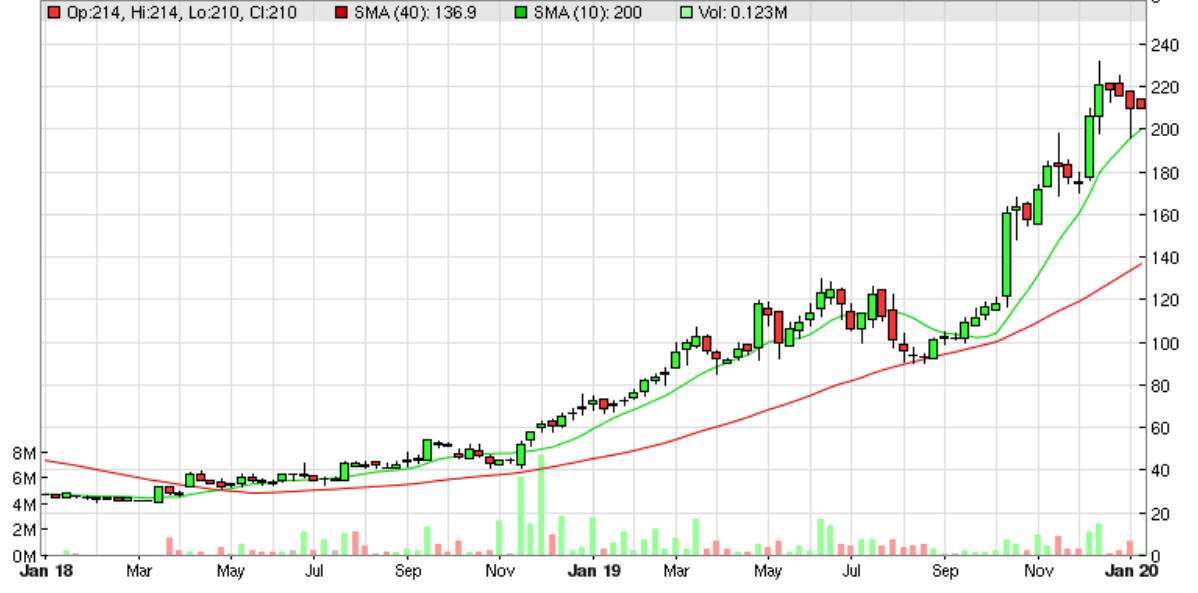
My opinion - I haven't done any in-depth research on this one, so don't understand the business model. However, clearly something really positive is going on - the share price has tripled in the last year, yet the forward PER still looks modest. This is because earnings forecasts have been rising strongly;

Obviously I'm kicking myself for not buying any personally, despite writing up a strongly positive article 4 months ago. The trouble with writing these reports, is that I'm constantly pulled from pillar to post, writing about lots of companies, so often can't see the wood for the trees!
Also, I didn't have any spare cash last autumn anyway. Looking back though, maybe I should have chucked out some laggards in my portfolio and re-deployed the funds into this? Oh well, just something to ponder.
As always with this type of share, the key thing is to find out what is driving the earnings upgrades, and ascertain whether earnings, and earnings growth, are sustainable? If they are, then this share could still be worth a closer look.
It's almost 10-bagged in the last 2 years - wow!
Indigovision (LON:IND)
Share price: 187p (up 5% today, at 11:43)
No. shares: 7.3m
Market cap: £13.7m
IndigoVision is a leader in the design and supply of high performance, highly-intelligent video security systems for security installations of differing sizes and complexity.
An old favourite, puts out a reassuring update today;
The Board of IndigoVision is pleased to report that sales for the financial year ended 31 December 2019 were $50.1m, representing a 9% increase over 2018.
Gross margins were maintained in line with prior year and with strong cost control, the Company expects to report operating profit and EBITDA in line with market expectations.
That reads fairly well. Note that IND reports in US dollars.
The announcement today does not indicate what market expectations are, which is unhelpful particularly for a very small company with hardly any broker coverage.
The last forecast I can find on Research Tree is from Oct 2019. This suggests adj EPS of 29.3 US cents. Divide that by 1.30 arrives at 22.5p EPS, and a PER of 8.3 - quite an attractive valuation. Although very small, illiquid shares like this should be cheap.
EDIT: an updated note came through, from the house broker, via my watchlist on Research Tree. It confirms the forecast figures I have used above, so all good. End of edit.
Net cash - is reported at $2.0m at 31 Dec 2019. It drew down $2.7m on a loan facility to make a small acquisition. Therefore gross cash must be c.$4.7m, to arrive at net cash of £2.0m - which looks a satisfactory position.
My opinion - it looks good value, and has quite a large installed base of digital CCTV systems, having been doing this for many years. Set against that, it's had a lot of false dawns in the past, where growth tailed off, after a spurt.
City Pub (LON:CPC)
Share price: 197.5p (down 9% today, at 12:31)
No. shares: 59.7m
Market cap: £117.9m
Trading Update (mild profit warning)
The City Pub Group, the owner and operator of 47 premium pubs across Southern England and Wales, announces its year end update for the 52 week period to 29 December 2019.
LFL sales were soft over the festive season, "marginally ahead" of a strong 2018 (when LFL was up 7% - so tough to beat).
YTD LFL sales are up +1.7% for the year. It's always useful to look back at the previous update, to see how LFL sales have changed. At the interims, LFL was +2.6%. Since the full year LFL was +1.7%, then this implies that H2 LFL was probably just under 1% - a deteriorating trend, although not a disaster.
My understanding is that bar operators (and retailers) need about 2-3% increases in LFL sales to recoup cost increases (especially labour costs). Although cost savings can trim that figure a bit lower perhaps. The danger of cutting costs too much (esp. staffing rotas) is that it can dent the customer experience, and risk them going elsewhere. Nobody wants to spend 10 minutes waiting at a bar, for a drink they could buy at a quarter of the price from Tesco's.
Reasons given - for subdued H2 trading strike me as stretching credibility in some cases;
- Rugby World Cup did not have expected benefit
- Political uncertainty held back sales - really?! People I know were getting drunk a lot more, due to the agony of the whole political saga. Also, how come other pub groups have been generally reporting more positive updates then?
- Weather - described as "unhelpful" in Nov & Dec - again, I don't buy that explanation at all. it's just an excuse
- Disruptions on S.West trains - really??! On the margins there might have been a few more people working from home, but I cannot see that would make a material difference. And if your train is cancelled or delayed, what do you do - nip for a pint!
- 2 refurbs were delayed, so missed out on Xmas bookings
Actually, having typed it up, that just looks more like a list of excuses, not reasons.
Revised forecasts - FY 12/2019 forecast EPS goes down from 8.1p to 7.2p.
FY 12/2020 drops from 9.5p to 9.0p.
At 197.5p this gives PERs of 27.4 and 21.9 for 2019 & 2020 - which strikes me as expensive, but it depends on what the balance sheet looks like.
Balance sheet - this is vital to how we value pubs. In this case, it looks good - at the last interims, freehold property had a NBV of £92.4m.
Net debt is £30m, part of a £50m facility with Barclays. Assuming that the freeholds are worth around NBV, the the overall loan to value looks reasonable, at about a third. The last results said that its estate of pubs is "predominantly freehold", which I like.
NTAV when last reported at 30 Jun 2019 was £73.5m. The market cap is 1.6 times tangible book value.
My opinion - it looks a reasonably good business. I'm not convinced the shares offer value for money though.
Instem (LON:INS)
Share price: 490p (down 1% today, at 10:22)
No. shares: 16.6m
Market cap: £81.3m
Instem (AIM: INS.L), a leading provider of IT solutions to the global life sciences market, is pleased to announce a trading update for the year ended 31 December 2019 (the "Period").
I flagged up a positive trading update here on 1 Apr 2019.
Graham quite liked the look of it here on 15 July 2019.
Trading update today - this all sounds pretty good;
Organic growth was strong, with revenues c.12% higher than 2018
EBITDA during the Period in line with management's expectations.
Recurring revenue increased as the transition towards Software as a Service (SaaS) continued, resulting in further improved earnings visibility.
Technology-enabled outsourced services grew strongly during the Period.
Net cash at 31 December 2019 was £5.9m.
SaaS - I do like SaaS businesses. There are lots of them at the moment, transitioning from one-off licence fees, to SaaS (i.e. subscription fees). This usually involves depressing short term profitability, but benefiting both long-term profits and revenue visibility. Therefore investors need to allow for this factor when valuing shares (i.e. it might be worth paying more now, to secure a better & more dependable long term profit stream).
Outlook - interesting that operational gearing & highly scaleable are mentioned. Both very promising phrases;
The Company has established a highly scalable platform with improved operational gearing as growth is delivered.
Key opportunities moving forward are centred on continued organic revenue growth, further margin improvement and accretive M&A.
Strong performance across our operations, combined with healthy new business pipelines, underpin management's confidence that the momentum achieved during 2019 will continue into the current year.
My opinion - this looks a really good business. As mentioned last time though, I have no idea how to value it, or assess its future prospects.
So this section is really just to flag up that it looks an interesting company, which readers might want to have a look at, if you understand life sciences (which I don't).
The shares recently shot up from 386p to 490p - I wonder if it was tipped somewhere as a NAP for 2020? I wouldn't want to buy immediately after such a jump on no news, in case it's a speculative spike that might wear off, as often happens with tips.
EDIT: Subscriber veritas has kindly informed us in the comments below that Instem was indeed tipped, a 2020 NAP from Techinvest, apparently. Thanks for the info. End of edit.
I'm tired now, so will leave it there for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
I remain a big fan (and holder) of Instem (LON:INS)
Reasons I remain positive:
Today's update implies 12.5% YOY revenue increase from H2 2018 to H2 2019, vs "only" 7.8% YOY achieved from 2017 to 2018.
Not bad for a growing company, though of course one can't make a firm conclusion of actual cash generation until final numbers are published.
If anyone can see any negatives - preferably qualitative ones as I am certainly no expert in this sector - it would be great to hear them.
Cheers
A
The RNS for Augean over the last two years if read will explain why the share price is up eightfold
Instem was a New Year Nap Tip in Techinvest, Paul.
Thanks, veritas!
I will add that info about Techinvest tipping Instem (LON:INS) into today's report in an edit.
Much appreciated, regards, Paul.
Hi Paul, any reason why we can't track the mfm techinvest fund on stickopeadia?
Steve
Re Augean lack of dividend
The dividend was suspended because of a dispute with HMRC. The company has now made provision for this and there is every reason to believe that dividend payments will be resumed once the issue is officially resolved, whatever the outcome. A core hold for me.
Augean. Knew them well when I worked as a Consultant in Hazardous Waste Disposal. I bought some of their shares. Even though for a few years did not do much realising their aims & ambitions I decided to hold tight. I think they have a lot of energy for the next few years.
The Telegraph tipped Bioventix recently. Maybe that helped to lift the share price.
Just posted an article on Stocko with a look-back at 2019 and some analysis on 10 year/all-time highs and lows across the UK Indices
https://www.stockopedia.com/co...
Given the 2018 bear market in AIM and the 2019 slew of small caps lows., 2020 could prove to be a real turnabout year if , as it appears, we've been through a capitulation low
Indigovision (LON:IND)
Paul
The Board is no longer "accountant heavy", the CEO is sales orientated having been with Avivilon which was bought by Motorola, the CFO was at the helm of an AIM company that was sold, the chairman is a partner in SORBUS wealth management and one of the NEDs was involved in Tesco pension fund investment management.
It seems to me that this might be a team capable of preparing IND for a trade sale.
If that is the case I am puzzled as to what the strategic objective of the share buy-backs in 2019 might have been.
Indigo bought back nearly 3% of the issued shares during 2019 - 210k for £459k - at an average cost of £2.19 (Current bid about £1.80)
This was between August (When the RBS charge was satisfied) and November.
34k of those shares were used in part consideration of the acquisition of Agora.
Does this represent sophisticated and shrewd strategic judgement ?
Your thoughts would be appreciated.
Indigovision (LON:IND)
Paul says "Set against that, it's had a lot of false dawns in the past ". Very true but do not underestimate the board revolution. In April 17 Chairman Hamish Grossart announced that he was retiring after 20 years "quipping that investors will be relieved to have someone “more in tune with technology in the chair”". He was replaced by Max Thowless-Reeves a partner at Sorbus, which has a 6.28% holding. Richard Familoe, another partner there, has a personal holding of 6.82%. The fund says "We will intervene and take board positions if necessary" https://sorbus.com/vector/management/
His first job was to give CEO Marcus Kneen the boot in a Nov. 17 profit warning. Before becoming CEO he had been CFO. He was replaced by Pedro Simoes, who had previously led a global sales force at Avigilon Corporation (TSX: AVO) .
After two years of kitchen-sinking by the new management the company has returned to profit.
Paul also describes the shares as illiquid. How very true - I have tried to add to my holding a couple of times but it is difficult to deal - this morning a buy over 1,000 shares was "negotiation only".
Re Consumer Spending data - What will happen to traditional cash businesses?
I happened to look up a private company the other day at CoHse - Fish and Chip Seaside Business been in the family 3 generations
Balance sheet approx £2.5M of which a shade under £1M is Cash at Bank
Old favourite Bioventix (LON:BVXP) showing some really strong price appreciation in the last few days. Not just noise, it's positively flying! Or I suppose it could be really loud noise?
Has it been tipped or something? Anyone got a clue?
re. Bioventix (LON:BVXP) Tipped in the Telegraph Questor column I believe, although I haven't personally read it.
Yes it was tipped in the Telegraph on the 10th. For Questor's Inheritance Tax portfolio
I see contactless card crime has doubled in the last 10 months in the UK.
I would imagine that cash may follow the trajectory of kindles v books so that there comes a point where cashless ceases to expand. I always use cash(no £20's) with small businesses as cash handing is cheaper than electronic handling (though the gap is narrowing I believe) for them. My main concerns about cashless society are 2 fold. Firstly the ability of the state to track you better and the implications for personal freedom (though it could be argued that personal freedom is overated). Secondly the damage it does to the black economy which is surely a social safety valve in an economic downturn (discuss!)
A couple of points on the great cash debate as I have read a few due diligence reports on the subject over the last few years (for work). They have crunched the numbers and also used qualitative data to work out what is really going behind the scenes.
Bascially the “death of cash” is much further from becoming a reality than MasterCard / Visa would have you believe. Although card use has accelerated, cash is still fundamental to the economy and daily lives of many.
The reason is two-fold:
I) Deep ‘habituation’ of payment methods .
Whilst I try and pay on card as often as possible, I am representative of a generation that is comfortable with this as a payment method. As I now use card for most things, I am unlikely to change to a new payment method (or at least it will take a lot of effort to make me move). As example is, I have an iPhone (for last 8 years) yet I do not use it to make Apple Pay contactless payments and also still have a separate Oyster card for travel,
People get used to a way of paying and it takes years and millions on marketing to change these habits.
The best example of payment inefficiency is the cheque book. This costs banks millions of pounds in processing each year - don’t you think they would phase it out if they could ?! My parents still send money to me via ‘cheques’ due to a mistrust of the e-banking system.
Take a moment and think how silly writing cheques are given societies technical advancements!
2) Unbanked population / grey economy
Given the demographic of the Stocko readership, I doubt there is anyone reading this without a bank account.
However, there is a very large swathe of the population (annoyingly I can’t remember the exact stat but I was shocked at how large it was - a few million I think) that remain “unbanked” and are essentially off the grid. These are often the poorest in society or those dependent on others, and some just have a deep distrust of Banks . Their lives revolve around cash and they spend what they have to survive.
All of their spending for goods / services is cashed based and their is no evidence that this is changing anytime soon. I won’t go into the “ethics” of whether they should be made to open bank accounts or not...
As an aside, I always carry £50 cash in my wallet ‘just in case’ and I can’t tell you the number of times this has been a life saver when my card hasn’t been accepted!
I’m sure there’s a correlation between distance from London and requirement for cash ;)
Maybe, maybe not - London is far from homogenous and I can certainly think of some of my old London haunts that I would imagine to remain predominantly cash economies.
I would wager though there is a correlation between 'requirement for cash' and the likelihood you will have to pay an exorbitant charge to access that cash (if you are lucky enough to be amongst the "banked"). No particular investment narrative there, but it is just one of the UK economic injustices that really rubs me up the wrong way.
Back on an investment related theme though, Paul says :
This based on the apparent 9.7% rise on spending on eating and drinking.
Paul's latter narrative provides the reasoning to debunk this, but I am not entirely sure the dots have been joined. Personally I would say this stat is totally useless in gauging the fortunes of the hospitality industry - It seems to me that the trend of using contactless to pay for even a single drink or a sandwich is very recent - 12-18 months from my observations has seen profound changes so I don't think that figure can be relied upon at all.
Last week Paul mentioned the idea of compiling in a table the views of all of the "retailers" - I had the same thought 2 years ago and again last year, but concluded that it was largely pointless as it was clear the market was dreadful. Despite a (very) few more positives this year, I still cannot prioritise the effort.
However, I do think there might be some merit to do so for the "pubco.s" probably not enough time now to do so before the Revolution Bars (LON:RBG) results but I do think there might be value doing do ongoing; not just for a gauge of the ongoing market trends, but also to get a measure of the much derided "weather effects".
I might be wary though of including City Pub (LON:CPC) in such a table as I fully agree with Paul that they presented a list of (sometimes convoluted) excuses rather than anything I would really recognise as underlying trends,
Another great article by Howard Marks -
https://www.oaktreecapital.com/docs/default-source/memos/you-bet.pdf
Probably a bit outside the scope of most peoples radar or relevance for this board - but i have been looking Funko Inc (NASDAQ: FNKO) ($fnko) the US listed toy making company (market cap £570 mill ish)
They do the collectible type small doll type toys with the big heads that you will no doubt have seen in the background in lots of you tube videos if you watch that stuff)
Other than mention of high directors remuneration the share price seems pretty decent value for this profitable company. Any comments as to whether their products are a flash in the pan or any other useful info on the company would be appreciated.
Its one thing to lose cash when you have known how to handle it all your life, but another for a generation to come to have no experience of handling cash.
When I was young I was aware of the dates of coins that were still in circulation. I have came across a penny which dated back to the Napoleanic era. It said something about continuity and the value of cash. Its debasement has been ongoing. They are increasingly a pile of zeros/ones in an electronic vault, and something is inevitably lost in that.
Sweden seems to have a history of instituting 'values' as if they exist in the ether, and then failing to acknowledge they are working on the ground.
There is a growing problem with violent immigrants in Sweden where bombings and shooting have created apparently created some no go areas. Yet the Govt with its idealised values ploughs on.I cite this as an outcome of naive pursuit of an idealogy in the face of a changed reality, rather than a rant of any political sort.
I suspect there is a bit of nostalgia about my view of cash, but in my view there is a place for physical cash, even if it is only to prevent a dictatorial view by Govt of how it is allocated.
Hi Paul, I think the macro stuff commentary is very useful. great work.
ATB,
NM
Thanks, Nursemaid.
We've taken on board that readers seem to really like macro musings, and personal portfolio comments (judging from the thumbs up system), as long as that doesn't detract from coverage of company results. So expect more of a mix of this in 2020 & beyond.
Best wishes, and thanks for the feedback, Paul.
I believe Sweden plans to be cashless by 2023, not accepting cash from March that year.
BUT, where I live over on the West Coast of Wales, a lot of places will still not take any card payments. Cash only.
i am a cash bod too rather than contactless card - but i think i am a dinosuar in this regard.
I think its just a different way of doing things with plusses and minuses in both directions
Looking at things from the alternative point of view
(1) when you are a cash bod and trollied its easy to lose cash if one isn't very careful - the amount of bods i have seen drop notes in the pub when trollied is a little scary. I have even been the guilty party myself in that regard.
(2) Ref monitoring spending - i am coming to the viewpoint (slowly) that having a weekly/monthly/annual categoristion and totalling of spending on ones card (like the barclaycard summary posted by paul with numbers) - is a much better slap in the face to highlight excess spending than the route being limited to cash in ones wallet per visit to the cashpoint.
Traditionally less disciplined bods using cash don't normally change their spots and can hide behind the ignorance of bliss in that cash is spent in multiple places. If your app tells you that are spending 10k a year in Revolución de Cuba that's probably the best slap in the face that you can get if you are wandering why you have so little cash left at the end of each month.
I haven't paid for anything in cash for the last 6 months, I have had the same £10 note in my wallet since August last year. The last bastion of cash payments for me was parking but now all the car parks I use take contactless so I never carry any coins at all. I usually pay using Applepay on the phone which is very secure requiring facial recognition and I also carry a contactless card for the rare occasions Applepay is not accepted. I can assure you that I am not a millennial!
(hopefully augurs well for the update from Revolution Bars (LON:RBG) - one of my biggest holdings personally - this Friday)
Paul,
The Revolution Bars (LON:RBG) trading update is on Wednesday 15th, not Friday.
All the best, Si
Hi Si,
The Revolution Bars (LON:RBG) trading update is on Wednesday 15th, not Friday.
Thanks for the correction, I'll correct the article now.
Best wishes, Paul.
Problem with contactless cards is lack of security. Some shops/pubs don't take them either. The other issue is if you have loads of payments on your statement is working out what there are all for. As for credit cards ift is becoming increasingly difficult to use them for online payments especially if you are abroad with these new security procedures, so booking Hotels/flights could be an issue.
I guess lack of security applies if someone uses your card for contactless (which is why the £30 limit applies). Like many, I use my phone - that requires a fingerprint or it reads your eye. That's with Apple - but who else provides the technology? Worldpay's gone private. Paypoint? (For as Paul says, more and more people are going contactless - the resistance comes mostly from those sceptical about security, the lower paid and presumably, organised and disorganised crime...)
Well I had my card cloned or skimmed or whatever, I can only think it was when I went up to London, maybe on the underground, fortunately when they tried to use it, it was over £30 so got declined and the bank contacted me within an hour and said I was not anywhere near there and they cancelled it. But if they had used it for under £30s then I could have got a huge bill on my monthly statement, I rarely look online at my statements. It is too easy to spend on cards many people get into debts problems.
You can buy NFC/RFID wallets and card holders that block anyone from trying to skim your card. Would also recommend something similar for storing your car keys, if your car has keyless entry.
Great, what about when you use them?
For car keys you can just use aluminium foil to block the signal.
Do you wear it on your head?
?
Glad to hear that. Many criminals are either stupid, or junkies, or both - that may well explain it.
Looking forward to any further comments on Quartix Holdings (LON:QTX) and XP Power (LON:XPP) which I hold and am encouraged by their price movements in recent months.
Interesting comments there Paul about the use of cards for payments in pubs. (First off I resent contactless cards and have actively moved away from them. How perverse is it that there are more controls and validations to log into your online statement (not to make transactions) than there are to make 4 x £30 transactions without any verification that the person making the transaction is the authorised cardholder!). I see lots of people use cards to pay for rounds in pubs and the more drinks people have then (generally) the more generous and free and easy they are to spend money. Much easier to have the cash in your wallet so you can stick to your budget for your trip to the pub. When the cash is gone you've spent what you capped your visit at. Not so easy to apply this control when your card has no spend limit per day/establishment.
Sorry to be so negative but I'm a frugal soul and cringe at how reckless some (not all) people can be with money management.
Thinking about Paul's comments on Joules (LON:JOUL) last week, I see that Clipper Logistics (LON:CLG) has announced that Joules is a new customer of theirs for web fulfilment. I have a small holding in Clipper.
XP Power (LON:XPP)
"in line" (their words)Trading update today.
Lets cut to the important bit outlook for the new year just started.
Order intake for the fourth quarter was strong and we remain encouraged by the
healthy order book and ongoing new design wins. On this basis we expect
revenue growth in the 2020 financial year.
That seems neutral wording - note Xpp has had a bit of a wobble recently with stocky numbers showing expected lower profits in 2019 (december year end) than 2018 - despite sales being slightly up. Current forecasts show £10 mill increase in sales 2020 over 2019 (expected) - being 5%increase. Note profits are expected to bounce back stongly at present despite modest sales growth.
at present 16% profit growth expected 2020 compared to 9% drop in 2019
Note last year expectations during year were lowered so one may take the viewpoint that expectations here are tricky to manage. There was issues with certain segments last year - probably mostly due to China tariffs and drop in supplies for smartphone type items. i am presuming company is expecting these segments to bounceback somewhat in 2020.
Ref debt - good news debt has come down to £40 mill as the long promised unwinding has happened and currency movements have helped. Xpp is a cash machine normally so i have no debt worries - the sooner it starts to drop to insignificant levels the sooner they will have the firepower to do reasonable acquisitions that will help drive growth. Wouldn't surprise me if they splash out more in this regard sometime this year.
The teething issues with the ERP system seem to be solved thankfully - note as some shipments were delayed i am kinda thinking the 2020 numbers should be bumped up by delayed orders flowing through in 2020. - so this potential contagion seems to have been put to bed.
Ref 2019 confirmed revenues - looks like very slight beat of £1 mill compared current numbers per Stocky.
Seems to be reasonable tickover update with better things to come this year - i recently sold part of my stake and have sold remainder today - purely on shareprice strength (up over 50% from lows of the summer) - current pe is over 19. I am probably selling at the exactly the wrong moment, as now is the time when everyone will be looking at the current year earnings growth and thinking the company is going great guns - the reality is that the company has had a poor 2019 which will flatter the 2020 numbers somewhat. It's a shame to be out of this company as i have always seen them as being one of my most reliable holdings for the last 10 years - shareprice ha roughly tripled in the last 9 years - with returns being even better if one goes back to the days before i had my first holding - like Arnie hopefully i will be back.
I've noticed this morning that Spirent Communications (LON:SPT) (I hold) is down in this mornings open despite reporting:
FOR FULL YEAR, REVENUE GREW BY 5.5 PER CENT TO $503 MILLION
* EXPECT TO DELIVER AN ADJUSTED OPERATING PROFIT IN RANGE OF$91 TO $93 MILLION IN FY, UP FROM $77.1 MILLION IN 2018
* EXPECT TO EXCEED MARKET'S PROFIT EXPECTATIONS FOR FINANCIAL YEAR 2019
The share price over the past few weeks has been steadily moving south from £2.50. Does anyone have any idea why?
Investec had it as a sell with target of £2.00 on it last week,
It is up about 9%, according to my broker.
Don't panic, Spirent Communications (LON:SPT) up 15% at the mo!
Goldman Sachs downgraded to sell last week with a 175p target... uh, what?? Call me sceptical, but I wonder if they were shorting...
Or had a large order to fill?
Absolute price manipulation
That's why I don't trust brokers. I have bought shares when they have fallen because of a broker downgrade with some success, if shares fall and I'm looking to buy and it is the only reason then I will buy. I don't know why markets take so much notice of brokers.
Couldn't agree more - this is very likely price manipulation! Issue a negative analyst report to push the price down knowing full well that the results due to be announced in the next week will be a major beat vs. expectations and the share price will surge as a result. Just as well that it didn't quite fall to my stop loss at 20% (below previous high) at 200p - I would not have been very pleased had this spike downwards led to a sale! Worth watching for similar price manipulation pattern when a stock due to report in next week or so to avoid selling unnecessarily on a stop loss.
My morning smallcap tweet:
City Pub (LON:CPC) Augean (LON:AUG) Diaceutics (LON:DXRX) Instem (LON:INS) Quartix Holdings (LON:QTX) Tiziana Life Sciences (LON:TILS), Vectura (LON:VEC), KRM22 (LON:KRM), Indigovision (LON:IND), Surgical Innovations (LON:SUN)
City Pub Group (CPC) guides FY adj EBITDA £9.1m and £9.2m, lightly below market expectations. Blames amongst other things the general election.
Augean (AUG) guides FY adj pretax at least in line with recently upgraded consensus market expectations of £18.4m.
Diaceutics (DXRX) guides FY ahead of market expectations with rev up 29%, adj EBITDA above £2.1m (£1.5m).
Instem (INS) guides FY rev in lne but no profit guidance.
Quartix (QTX) guides FY rev, profit and FCF slightly ahead of market forecasts.
Tiziana Life Science (TILS) plans to redomicile to Bermuda by Q2-2020. Will cancel AIM listing, cancel its ADR program and list on Nasdaq.
In line: Vectura (LON:VEC) KRM22 (LON:KRM) Indigovision (LON:IND) Surgical Innovations (LON:SUN)