Small Cap Value Report (Mon 8 April 2019) - Market comment, KWS, IPX, LSR/THAL, TLY, AUK

Good morning!
Let's see what the RNS has in store today.
A few announcements worth commenting on:
- Keywords Studios (LON:KWS) - final results
- Impax Asset Management (LON:IPX) - AuM update
- Local Shopping REIT (LON:LSR) / Thalassa Holdings (LON:THAL)
- Totally (LON:TLY)
- Aukett Swanke (LON:AUK)
Graham
Market comment
I thought I'd take a step back for a moment and point out that the FTSE-100 is up by over 700 points this year - what a result! Up by 10.7% so far in 2019, or 12% including dividends.
During this period, GBP has actually appreciated against the US Dollar and the Euro.
So the gains have been spectactular and not caused by currency depreciation.
Also worth noting that retail fund flows have been weak/negative in the first couple of months of the year. This suggests to me that the buyers have been big, institutional money. Retail investors will follow later.
As for the rationale behind all of this bullishness, markets seem to be pricing in a long delay to you-know-what. Since big money loves certainty, I think they are taking the view that nothing is going to happen for the foreseeable future, and maybe never. As far as they are concerned, then, it's "safe" to pile in to UK equities again and return the FTSE to its pre-referendum trajectory.
Please note that this is just speculation on my part! - but I have seen broker notes expressing a lot of confidence that there will be a long delay and/or a second referendum. So I think this is what institutional money currently expects. They have been wrong before, of course!
There's also the small matter of interest rate expectations collapsing, bond yields tightening again, and other major equity markets rallying hard, too. The S&P 500 Index has gone up almost in a straight line over the past three months. According to Stocko, it's now on a (median) trailing P/E ratio of 21x and a forecast P/E ratio of 17.5.
As usual, the US markets carry a significant premium to the FTSE, whose forecast P/E ratio is just 14x.
Life has been tougher in small-caps: the AIM All-Share Index has rallied by just 7.4% year-to-date. On a long-term view it undeperforms major indexes like the FTSE-100 and the S&P500, so I suppose we shouldn't be too surprised.
For what it's worth, I'm happy with my current positioning of 91% equities and 9% fixed income, with a little bit of surplus cash on the sidelines.
Keywords Studios (LON:KWS)
- Share price: £12.955p (-1.9%)
- No. of shares: 64 million
- Market cap: £829 million
Watchers of this share will know that a lot of the air got squeezed out of its valuation in Q4 2018.
Since bottoming out in Febuary, shareholders have witnessed a rally of over 40% from the low.
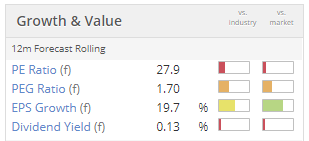
While I wouldn't go so far as to say that I'm a bear on this company, I am a bit of a sceptic as far as the valuation is concerned. It has usually traded at very high multiples, and this is true again today.
Keywords provides outsourced technical services to the video game industry, and has been created via a large,international M&A strategy. As a consequence of all the M&A, there is €154 million of goodwill on its balance sheet and when you strip out intangibles, it has tangible balance sheet value of just €12 million.
Fortunately, the earnings progression has been very good and this is confirmed again today with operating profits of €23 million (up from €16 million).
The company measures and reports its ROCE - this is something I always like to see. It reckons that it achieved ROCE of 19.4% in 2018, up from 15.8% the year before.
Note, however, that this figure is based on ignoring the effects of amortisation - these calculations can get complicated.
Show me the money!
Cash flow from operations, before working capital movements and taxes, was impressive at €44 million. I suppose this is the best and the simplest argument in favour of the company's valuation: it has a good track record of generating plenty of cash from the companies it buys.
The video games industry has strong fundamentals and Keywords enjoyed overall like-for-like revenue growth of 10.1% despite the "Fortnite effect", i.e. the difficulties experienced by all publishers who didn't make Fortnite.
The Fortnite effect was so strong that it has even been blamed on a couple of other publishers going bust, resulting in a few bad debts to Keywords.
Keywords tends to spend all the cash it generates, and more, on internal and external investments, and that was true again in 2018. Whereas in 2017 it mostly raised equity to fund deals, in 2018 the emphasis was on borrowing. Internal capex spending increased signicantly to €9.4 million.
Outlook
Key points:
- Q1 2019 performance is in line with expectations
- 2 deals done already and more in the pipeline
- Capex to reduce in 2019 (meaning that free cash flow should improve)
- "Well placed" to benefit from demand as disruptors Apple, Google and Microsoft roll out video game platforms.
My view
I have a balanced view on this share.
The negatives:
- Provider of outsourced services, not an IP owner.
- Possble disruption from waves of change in the video game industry (e.g. Fortnite in 2018, streaming services in 2019).
- A vast number of M&A transactions leading to complexity and a lot of integration work.
The positives:
- Has generally achieved what it set out to do with acquisitions over the years - excellent track record.
- Cash flow is real.
- Video games industry is undoubtedly fast-growing.
- Great international diversification.
- If the acquisition strategy works as planned, it will see Keywords cement its position as the "partner of choice" to video game publishers.
I have no plans to add this to my personal portfolio, but it is an interesting one to keep an eye on, all the same.
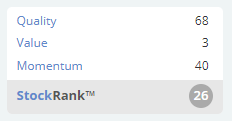
Lastly, I should note that the StockRanks aren't impressed by the lack of value or momentum on offer:
Impax Asset Management (LON:IPX)
- Share price: 240p (+2.1%)
- No. of shares: 130 million
- Market cap: £313 million
Nice work by this environmental asset manager. It grew assets under management by 4.6% of starting AuM (£529 million of net inflows versus starting AuM of £11.6 billion).
It also enjoyed a big uplift from rising markets and the net result was a 15% increase in AuM in just three months, for a total of £13.25 billion by the end of March.
This puts it back on a positive footing for the financial year after it suffered an 8% decline in AuM in the prior period, caused by the market sell-off.
My view - I still have a positive impression of this manager, and so does the market as a whole.
Having watched it do well for almost two years now, I don't hate the idea of owning a few shares in it. Fund managers need a specific area of expertise to survive in today's environment, and Impax certainly has that. So I could see myself owning shares in this at some point in the future.
Looks like it might take a year or two to grow into the current valuation (forward P/E 20x).
Local Shopping REIT (LON:LSR) / Thalassa Holdings (LON:THAL)
The battle between LSR (£23 million market cap) and Thalassa (£14 million market cap) continues.
If you've seen my previous coverage, you might remember that I hope LSR prevails.
Thalassa has just over 25% of LSR's shares, and has blocked LSR's plans to liquidate. Instead, Thalassa wants to take over LSR with an offer of cash and shares.
Latest news is as follows:
- Excluding Thalassa, 99.6% of votes cast at an LSR General Meeting were in favour of LSR continuing its efforts to liquidate, despite the obstacle presented by Thalassa and the overtures of its chairman, Duncan Soukup. A special petition may be presented to the Business and Property Courts.
- Thalassa has promptly fired back with a statement that highlights that there were many LSR shareholders who didn't vote. The Thalassa board has taken its own legal advice, and thinks the prospect of a winding-up order from the Business and Property Courts is "remote".
My view - No change, since we already knew that those LSR shareholders who use their votes (excluding Thalassa) want it to liquidate.
In my view, Thalassa is exploiting the rules in ways which aren't in the best interests of LSR shareholders as a whole, and I hope that the courts will agree.
Totally (LON:TLY)
- Share price: 12.94p (+6%)
- No. of shares: 60 million
- Market cap: £8 million
The Board of Totally plc (AIM: TLY), a leading provider of a range of out-of-hospital services to the healthcare sector in the UK today announces an update on trading for the 12 month period ended 31 March 2019.
I don't know too much about this company, but it seems to be a loss making, very low-margin provider of services to the NHS.
Why bother mentioning it? Well I imagine that some of you like to hunt for deep value among the micro-caps. Totally says that it has cash of £7.5 million in the bank (about the same as the market cap) and has won a bunch of "contract extensions, new business and pilot schemes" in the last few weeks, with a value of £7.7 million.
I don't know if the margin on these new deals is anything to write home about but perhaps someone reading this will be interested to look into it.
Please note that the Stocko algorithms consider it to be a value trap.
Aukett Swanke (LON:AUK)
- Share price: 1.68p (+1.5%)
- No. of shares: 165 million
- Market cap: £3 million
This little architectural practice remains an object of curiosity for me. I want to see if the equity will turn out to be worth more than a nominal sum, or if it will collapse under the weight of its fixed costs.
(To be clear, I don't doubt that the company does high-quality work. I am purely concerned with whether the shares are worth anything - a completely different question!)
Today, it informs us that it has a net cash balance of c. £200k, slightly improved versus six months ago. It has a £500k overdraft in place until November, so I guess it has some headroom.
A short and sweet trading update:
As trading continues to improve during 2019, in line with the guidance re-iterated in the AGM statement, the Board expects to show further improvement in the cash position by the year end.
My view - I remain extremely cautious here due to the paper-thin balance sheet and ongoing losses. See my comments in January, when I noted that tangible equity was just £1.2 milion. A loss is already baked in for H1, with hopes for profits in H2.
On the positive side, I am reliably informed that the company is enjoying its current London premises rent-free for two years, and the rent will be much cheaper after that.
If it can cut costs to the bone and enjoy a bit of luck in terms of growing the top-line, perhaps there is still hope for shareholders? Not something I'd want to bet on, I'm afraid.
The news was light today so I'm going to finish on that note.
Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Hi Fangorn,
Thank you for those links.
I must admit I didn’t see anything there that supports the view that this country will be stronger after Brexit.
A foreign wealth fund taking advantage of a devalued pound and an under valued stock market to buy companies with international earnings that could easily relocate their headquarters.
As a thought experiment, imagine Britain was buying up other country’s companies while they were going through a similar period of domestic turmoil. Would it make sense to declare that as a positive for the country involved?
J
Fair point John
Moreover for liquidity reasons, a £740bn wealth fund would naturally be buying into FTSE-100 companies rather than the mid/small/micro UK companies that will bear the brunt of a hard Brexit.
So this Norwegian inflow has little/nothing to do with Brexit - just a media headline.
Not to deny index performances, but I haven't noticed much improvement in my portfolio recently. Everything I have bought seems to have been ill-timed, or has failed to recover from falls last year. Cases in point being Flowtech Fluidpower (bought just before a market overreaction to weaker-than-expected results), Northern Bear (drifting steadily downwards despite apparent good performance), Treatt (has gone virtually nowhere for the whole time I have owned it) and Air Partner (went great guns at first, knocked down by an accounting error - groan - and has then never really recovered despite its house apparently being put in order).
My only recent successes have been Watkin Jones, Somero and XP Power.
Grumble over
B2V
Martin Lewis has done his best to put financial education into schools. This is the Moneysavingexpert article giving details and where to download the textbook (very good by the way): https://www.moneysavingexpert.com/news/2018/11/financial-education-textbooks-funded-by-martin-land-in-english-s/
Graham, I'm relatively new to this game and since my shares are in a nominee account, probably like many LSR private shareholders, I find it difficult to place a vote on resolutions. I wonder though why it is that the LSR board of directors don't seem to want to make a go of the business. Also, who is going to receive most benefit should the Company achieve its liquidation? I do hold THAL.
The LSR directors made it clear that they were going to liquidate the business a long time ago. they might have seen the writing on the wall for retail back then! So they've been selling off property as they go, everyone knows this, the LSR shareholders voted in favour.
Its only Duncan who is not happy, and frankly I can't see why he'd want the business as a going concern as there are less than a dozen properties left (he'd be better off buying them as they are sold!). It does have a load of cash (28p per share) that it was going to hand over until Duncan started the action.
IIRC all Nominees will let you vote, but some are much better at it that others. Selftrade only lets you if you tell them directly, II has a section with buttons for each resolution to vote directly.
Many thanks gbjbaanb, I'll get on to the Share Centre as it's something I should be engaging in..
A thought on FSCS and apologies if this is sucking eggs, but have some background on regulation (not FSCS specifically) so tend to keep abreast.
FSCS is in the event that a financial services provider goes bust, and covers for 85k (€100k actually), which is why the £ amount changes.
The €100k applied to deposit / savings and the amount for brokerage was £50k, which I believe has been increased to the same as for savings / deposits.
Basically, FSCS is targeting the value of client money / client assets held, not the cost / gains / losses of those assets.
I feel the need to share this in light of recent (what I consider) scams, where sellers of mini-bonds / diamonds / other hideously illiquid assets, have told me that my investment is protected under FSCS (of course they use the term guaranteed!)
As I expect we all know on this thread, the compensation scheme applies to the custodian of the assets, not the assets themselves, so if you lose 50k in bad investments, the FSCS does not care.
Where you were sold an inappropriate investment, the advisor can be held liable, but this would be a matter for the advisor. As far as I am aware, there is no upper / lower limit for this and if people fail to reach agreement, it would be escalated to Ombudsman and then court.
The Ombudsman itself has a cap I believe on what level of pay out they can impose on the advisor / insurer.
Where execution only, obviously no advisor to go after, so if investment goes south, so does your capital.
My sincere apologies if the above is a "how to suck eggs", but I think the clarifications above are important, especially where the community here is probably substantially more knowledgeable than the people FSCS is trying to protect.
I wonder what is the real significance of the 10/12% rise this year - I have read in several places how this or in other markets is a great quarter (is it?).
But in context to me it is no more than a marginal recovery play and not that exciting (yet). In May 2018 the FTSE had an intraday high of 7900 and in Dec a low of 6539 something like a 17%/18% drop the FTSE market today has barely surpassed the 200 moving day.
I am not complaining as the past quarter has been good to me just an observation of context and where the market may head next.
I suspect the ED numbers for Impax Asset Management (LON:IPX) did not assume the market appreciation we have seen so far this year.
Impax Asset Management (LON:IPX) were also awarded a large mandate from West Midlands Pension Fund which will not have been funded yet so is not in the figures (my assumption but it was only in the press mid-March).
So I agree with Jesseowens that $14bn could be exceeded by year-end. Personally I'm also glad to see Pax has stabilised.
Worth pointing out that Impax Asset Management (LON:IPX) forecasts from Equity development were reduced earlier in the year towards a year end AUM of £14bn. Now that end of March AUM is £13.3 bn , net inflows of £520 million in the previous quarter, and a reasonable expectation of 7% market gains in the remaining 9 months of the year, this forecast might now be too conservative. With the operational gearing in the business IPX may well be on a lower rating than appears from current Stocko forecasts
MrContrarian's ever welcome morning report highlights the proposed delisting of Safeland (LON:SAF)
I do not hold and feel sorry for those who do because the offer for those not wishing to hold shares that cannot be traded is at the current price which is 0.3 x NTAV.
A quick glance shows 3 directors - the Lipmans and a solicitor (age 75) with these holdings:
L G Lipman 261,128 E A Lipman 692,442
Mr L G Lipman and Mr E A Lipman each own one-third of the share capital of Safeland Holdings (2008) Corporation (“SHC”), a corporation incorporated in Panama. SHC owned 10,854,386 (2017: 10,854,386) ordinary shares in the company, representing 72.81% (2017: 70.63%) of the Company’s shares in issue as at 31 March 2018
This really is the rough end of AIM!
The following is a good article on index-linked gilts
https://www.investorschronicle.co.uk/funds-etfs/2018/09/20/the-hidden-risk-in-inflation-linked-bonds/
I have been looking for a time to buy them cheaply for years but always failed to do so. When they look cheap, it always feels as if there is a good reason for them doing so!
Here is a ray of good news for those who have not noticed. I checked it with the FSCS this morning, as their website was not clear. This is the response I received in reference to execution-only brokerage firms:
If the investment firm you conducted business with has failed and was authorised by the Financial Conduct Authority, you would be eligible for compensation for up to £85,000 per person per authorised firm.The compensation limits for investments have increased on the 1st of April 2019. This increase in limits will only affect customers of financial services firms that fail on or after this date.
laurie - you're right, it's not very clear. But isn't that compensation only in respect of money or investments where the claimant has received advice?
So, on that basis it would not cover the vast bulk of investments held in nominee accounts with execution only brokers (which by their very nature do not give advice). Which is what is going to be of interest to the majority of people on this site.
Yes, I appreciate that the nominee system is supposed to give protection but it's not cut and dried.
Or maybe I've got it wrong and the FSCS now covers holdings as well as cash??
Re: compensation due to failed brokerage
Yes, the FSCS website does say that the compensation is for bad advice, and the compensation amount for a failed brokerage (e.g. Beaufort) has vanished from the website. This is why I asked specifically about the compensation level available for non-advice, execution only brokerages. The amount guaranteed by the FSCS (in cash and shares) was £50k before April 1st. According to someone at the FSCS, this has been raised to £85k. I asked for a transcript of the conversation but this has not appeared. I am willing to attribute this to technical failings on the site and/or an unwillingness to put anything in writing. (I have had issues with the FSCS being deliberately unclear in the past.)
If enough people ask the folk at the FSCS what the current compensation level is for a failed brokerage, perhaps they will be inspired to publish the amount on their website. https://www.fscs.org.uk/what-we-cover/investments/ is where the missing information should be.
Please let me know if you get a different answer.
Re: compensation due to failed brokerage
Noticeable that:-
"in respect of a UK-authorised bank, building society or credit union that fails, we’ll automatically compensate you".
But, in respect of everything else:- "We may be able to compensate you"
And, the "everything else" doesn't include brokers where no advice was given.
1 As the FSCS do not appear to explicitly say stockbrokers are covered on their website (as flagged by Laurie, above), I have e-mailed them to ask about this, as suggested by Laurie.
This kind of thing should be very clear on their website - ie a definition of what is and what is not covered.
2 As far as I know, schools do not teach subjects like personal finance or economics, but have taught some very questionable & lower value subjects for decades (probably centuries).
Just got an update on this from a colleague:
FSCS does cover investments and as of April 2019, the compensation covers 85k worth of investments. Watch this space for updates to the website.
That said, if a broker / bank ceases to operate, the administrator is not able to use client money to cover administrator fees, BUT THEY CAN USE CLIENT ASSETS.
How the use of client assets to cover fees squares with the £50k (now £85k) guarantee she is not clear - i.e. would only clients with assets above £85k be hit by client asset sales for administrator fees, or how they would select which / who's client assets are to be sold.
jonesj,
As far as education is concerned, personally I find it a travesty of justice (and our taxes) that personal finance / financial management are not part of the national curriculum, while other subjects (insert rant) are.
I think my nephews would benefit more from learning the basics of finance than the intricacies of plant biology, but then again, all my plants are dying!
Re: FSCS
Thank you, all, for confirming the new FSCS £85k compensation limit.
During the administration of Beaufort, the FSCS paid the (shocking) administrator's fees for accounts within the £50k compensation limit. I add some informative paragraphs taken from the FAQ from the Beaufort administration:
Shortfalls will be covered by the FSCS if you are eligible; the FSCS provide compensation for amounts up to £50,000 across client money and client assets taken together, less your share of certain costs
I have a vague memory that this share of certain costs was c. 10% of assets, but this could be incorrect.
There are insufficient resources in the Firms to pay for the costs of returning assets to clients. Therefore these costs will need to be deducted from clients’ portfolios in accordance with Rule 135 of the Investment Bank Special Administration (England and Wales) Rules 2011.
https://www.pwc.co.uk/services...
Before this administration, I assumed that £50k compensation meant that it was reasonable to have £50k in a brokerage account. If fees during administration are 10% of assets held and it takes c. 6 months to regain access to the shares during which time, ideally, they are rising in value, £50k would not keep one under the compensation limit.
"As for the rationale behind all of this bullishness, markets seem to be pricing in a long delay to you-know-what. Since big money loves certainty, I think are taking the view that nothing is going to happen for the foreseeable future, and maybe never. As far as they are concerned, then, it's "safe" to pile in to UK equities again and return the FTSE to its pre-referendum trajectory."
Graham, I don't think there is much evidence that the rally in UK Equities so far in 2019 is due to a possible long delay in signing the Brexit Withdrawal Agreement.
After all, UK Equites have been amongst the worst performing of the major indicies in 2019 to-date:
The FTSE-250, which would be a major casualty of a hard Brexit, has underperformed the S&P-500 by a whopping 10 percentage points so far this year (!)
I think the 2019 rally in global Equities is just a bounce back from 4Q18's sell-off.
Yes, interest rates may well have peaked, but so has economic growth. Equities will struggle to make much further progress this year, in my opinion.
Howard,
I take your point but I hope you'll acknowledge that I did take care to mention the FTSE-100 and small-caps separately, and I acknowledged that small-caps have done poorly!
I also acknowledged the currency appreciation which is a drag on UK equity performance. E.g. if you add on the 4% EURGBP appreciation to the FTSE's performance, it has matched the EUROSTOXX.
Howard -
I have to question your YTD values for AIM-100, and FTSE-250.
For FTSE 250 , on 2/1/19 it was 17587, and on 5/4/19 it was 19538 . That is +11% , not 5.6%
I think the AIM 100 is also around 10% and not 6.2% .
Happy to be corrected.
Hi ram, I have checked the AIM 100 and I also get a result of 10.2% year to date (as of last night), and more than 11% for the FTSE-250.
In support of your comments Graham I read an article a few weeks back and for the life of me I can't remember where, it might have been the FT. But they were saying big money was moving back into UK. They gave 3 reasons, 1) sterling undervalued, 2) underperformance of market relative to other markets and 3) belief that hard Brexit wouldn't occur and therefore business as normal for the foreseeable. Your piece reminded me of it.Let's hope AIM can catch up a bit, but I think Pat Val and Goal have reminded investors of the risk reward balance.
To focus on Brexit ignores other major risks to the UK economy.
Such as the dreadful balance of trade deficit & whether we have a government which keeps a business friendly environment or wants a central state controlled economy, Venezuela style.
I'm holding a lot of index-linked bonds at the moment. RPI linkage gives a return above inflation and it's a hedge against a no-deal Brexit and a change of Government that could change inflationary expectations.
Index linked bonds - and of course the capital gain of an index linked gilt is not subject to Capital Gains Tax (CGT). They should be the bedrock of any personal portfolio outside an ISA or SIPP in my opinion.
Why is buying Index Linked Gilts at a price significantly above par a good idea exactly? Unless you want to guarantee yourself a loss in wealth and purchasing power.
I can think of many better ways of providing for my future than spending a pound to buy fifty pence pieces.
World’s biggest wealth fund piles billions of pounds into Britain after taking 30-year bet that UK economy will be STRONGER after Brexit"
The fund is one of the biggest foreign investors in Britain, as a co-owner of London's Regent Street, as a top five owner in firms such as HSBC and BP among others.
Norway's £740bn sovereign wealth fund has 8% of its total invested in Britain
World’s top wealth fund puts billions into Britain
UK will be stronger after Brexit, Norwegians say
https://www.thetimes.co.uk/article/world-s-top-wealth-fund-puts-billions-into-britain-qswjw8637
UK's biggest investors bet on the British economy in Brexit show of faith
https://www.telegraph.co.uk/business/2019/02/28/uks-biggest-investors-bet-british-economy-post-brexit-show-faith/
All they are betting on is that Britain will make money for them over 30 years. That tells us nothing itself about Brexit. And if we believe May and the Brexiteers it may never happen, so they are perhaps betting on Britain doing better in the EU?
Keywords Studios (LON:KWS) - profits up about 65% but only 10% like for like. Worth a look or already bounced enough at c 1/3 up off recent lows?
My morning smallcap tweet: Debbie's stalker still hot and sweaty
Safeland (LON:SAF), Yourgene Health (LON:YGEN), Debenhams (LON:DEB)
Safeland (SAF) proposes cancellation and nil premium tender offer.
Yourgene Health (YGEN) guides FY rev up 45% ,ahead of mkt exp. Profit ??
Debenhams (DEB) Mashley offers to underwrite placing if lenders wite off £148m. And with all Sports Direct special offers recently, Mashley becomes CEO.