Small Cap Value Report (Thu 22 Feb 2018) - ZYT, D4T4, XPD, MACF, BKS

Hi, it's Paul here.
I'm running a bit late today, due to a Doctor's appointment (nothing serious), so will be updating this article all afternoon & evening. Please see the header for the announcements that I shall be writing about, plus one or two reader requests.
Update: lots of requests today! I've added the ones that look most interesting into the article header, and will work my way through them this afternoon.
Zytronic (LON:ZYT)
Share price: 490p (down 8.1% today, at 12:42)
No. shares: 16.04m
Market cap: £78.6m
Zytronic is a world-renowned developer and manufacturer of a unique range of internationally award winning optically transparent interactive touch sensor overlay products for use with electronic displays in industrial, self-service and public access equipment.
The current financial year will end on 30 Sep 2018.
This is what it says about trading in the 4 months to end Jan 2018;
Further to the outlook statement given in the preliminary results announcement, current revenues and profits over the first four months of this financial year remain broadly in line with the equivalent period last year.
[published today, 22 Feb 2018]
Checking back, this is what the company said on 12 Dec 2017, in the outlook section of its preliminary results;
The current year has started with orders, revenues and trading along similar levels to that of the prior year, which, together with our strong balance sheet and cash generation, provides a sound base for further growth in dividends and shareholder value. The focus on growth this year will be from expansion in local sales representation in the USA and the Far East, and we shall keep shareholders updated on the progress, and any material developments, over the course of the year.
[published on 12 Dec 2017]
Those two statements essentially say the same thing - trading is flat, or slightly below last year. This is reflected in a share price that is about the same, comparing those two dates.
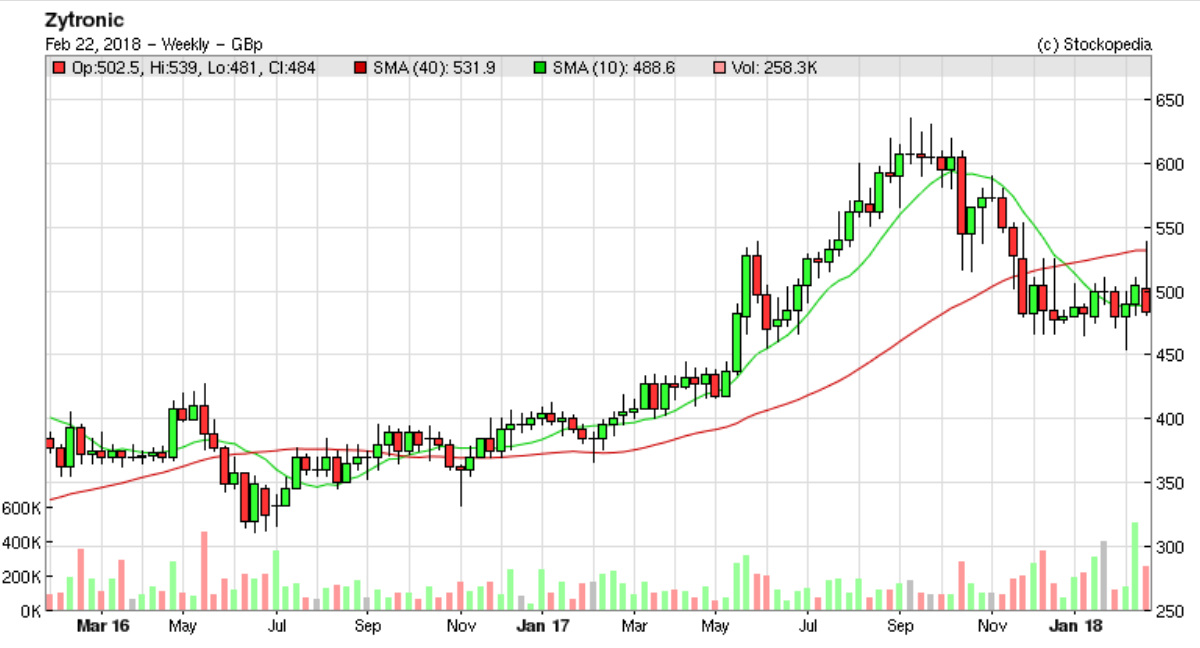
Valuation - last year normalised EPS was 28.7p, and the StockReport is showing broker consensus of 29.9p for this year. So it sounds as if forecasts might need to be edged down a little, given that the company is struggling to better last year's figures so far this year.
The trouble is, we don't have any information on the company's order book. Nor does it give any outlook statement today. So today's update is rather leaving us in the dark, as to this year's likely outcome. That makes it more difficult to value the shares. Uncertainty also makes investors nervous.
I'd say this year looks to be possibly between 27-30p EPS. At the current share price of 490p, that translates into a PER between 16.3 and 18.1. Initially, that strikes me as being perhaps a little warm, for a company that's not generating any growth at the moment.
Cash - no update is given today on the latest cash position, but this company has a history of generating, and hoarding, cash. When last reported, at 30 Sept 2017, cash was £14.1m, and there was no debt (as the £1.1m mortgage had been recently repaid).
This is material to the valuation, and works out at almost 88p per share - or 18% of the market cap. So investors are really only paying 402p per share for the business (i.e. current share price of 490p, less 88p per share net cash).
The cash neutral PER drops to a range of 13.4 to 14.9 - which is much more palatable.
The big question then, is what are the company's intentions with the cash pile? I've asked this question directly in the past, and the Directors don't seem to have any interest in doing acquisitions. I get the impression they like having a big cash pile, as a comfort blanket. Personally I'd rather see them put that cash to work, doing something productive - e.g. buying another profitable, cash generative business. Why couldn't they emulate Tracsis (LON:TRCS) or Judges Scientific (LON:JDG) and use the strong cashflows to build a larger group, with largely autonomous subsidiaries? Maybe there's a lack of ambition at ZYT? Or maybe management & investors are happy to keep small & focused?
Broker comment - there is one brief comment from a good quality broker, on Research Tree. It makes an interesting point that last year started strongly, so is a tough comparative. Therefore, its full year expectations of adjusted, fully diluted EPS of 29.9p remain unchanged.
If they're right, then that means the PER with the net cash stripped out, would be the lower figure above, of 13.4 - which is getting into value territory.
My opinion - I would like to have seen more detail today, in particular giving some guidance for the rest of this year. The lack of detail introduces doubt into my mind. Maybe the outlook isn't very good?
Another point to consider, flagged previously by a reader here, is that Zytronic relies heavily on several major customers. This information can be found on page 48 of the last Annual Report, in note 2;
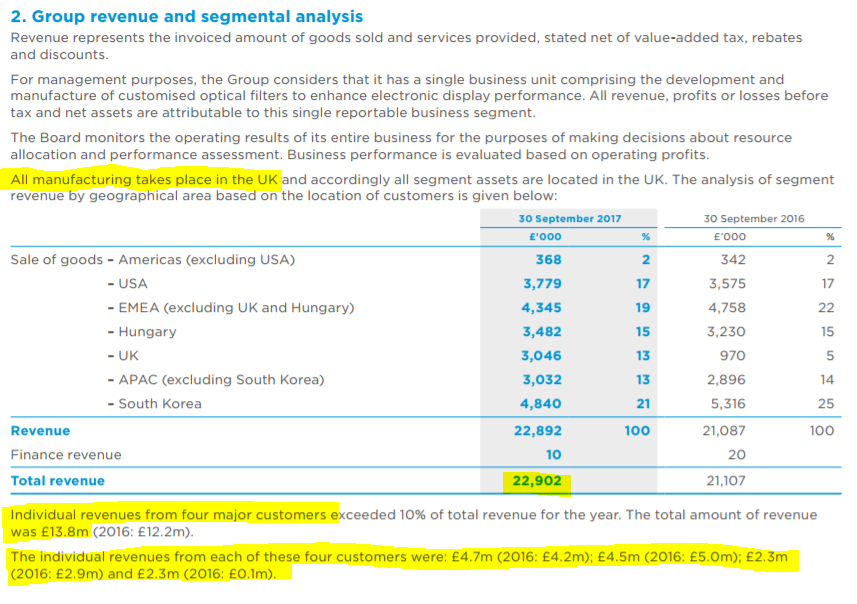
That works out as 60% of revenues coming from the 4 largest customers - a very high concentration, which introduces considerable risk. This could help explain why management likes to hoard cash for a rainy day?
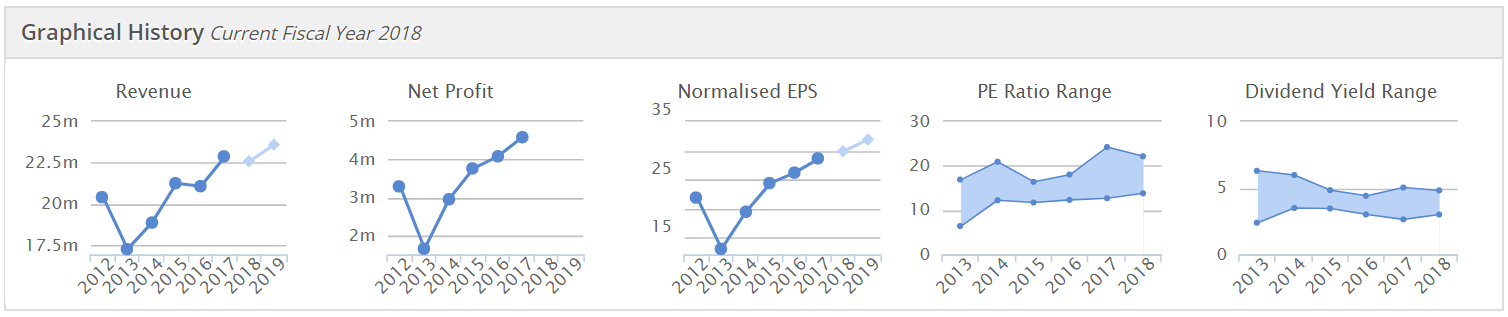
As you can see from the Stockopedia graphs below, the company has really only had one duff year, in the last six, when a gap appeared in the order book in 2013. People who bought that dip (down to about 150p per share) were well rewarded, as the share steadily recovered, and healthy divis were maintained, despite the sharp drop in earnings (another advantage of cash-rich companies).
Overall, I like it. It's not a share I currently hold, but is definitely one that I would buy after a profit warning, if it does run into any problems in future, as problems have been temporary in the past.
The current dividend yield is nearly 5%, and I see that forecasts on which this is based are for dividends to rise considerably. The forecast dividend cover is set to drop from 2 times back in 2014 and 2015, to only 1.16 times forecast for 2019. That makes complete sense - since the company is stuffed full of cash already, it might as well pay out nearly all future earnings in divis.
Therefore, there is considerable appeal to this share - as a reasonably priced, financially strong, high(ish) yielding, high quality niche company.
The main risk is that the price could plummet on a future profit warning, if any of the major 4 customers decide to defer or cancel orders. For this reason, I've decided not to buy any personally for the time being, although that was a finely balanced decision.
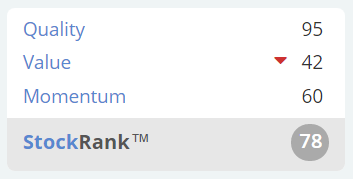
The StockRank is pretty solid too;
D4T4 (LON:D4T4)
Share price: 145p (up 9% today, at market close)
No. shares: 38.1m
Market cap: £55.2m
New contract wins - when I initially read this RNS before 8 am this morning, I incorrectly assumed it was a trading update, but it actually isn't. It's a PR announcement, so is issued via RNS-Reach. Info & click-through link on this from the London Stock Exchange website:
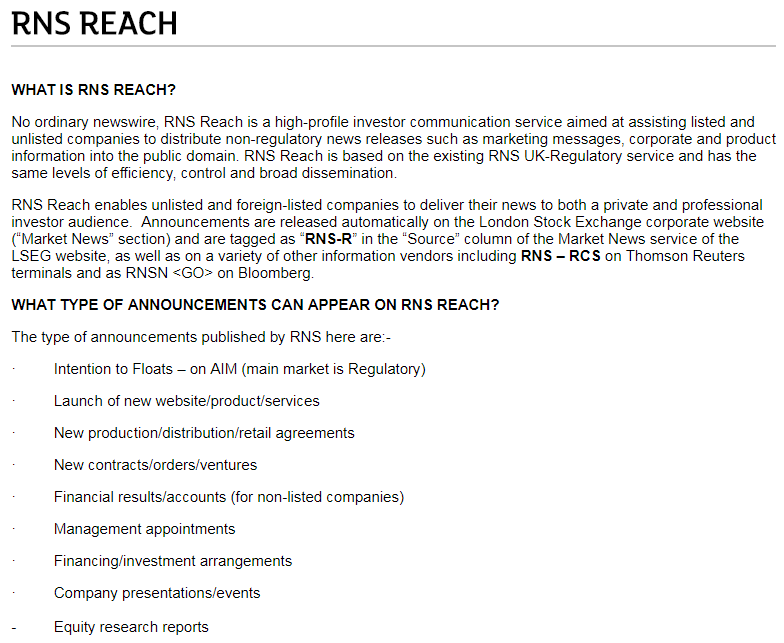
The only way I can see to spot that an announcement is RNS Reach, not RNS, on the investegate website that many of us use each morning, is that the Reach announcements are shown with a grey, not black "RNS" label. The difference is very difficult to spot at 7 am, when lying in bed reviewing announcements on an iPad!
Anyway, as regards this announcement from D4T4, I've started so I'll finish. In any case, I've been meaning to revisit this company for a little while.
Today's update says;
D4t4 Solutions Plc (AIM: D4T4), the AIM-listed data solutions provider, is pleased to report a number of new contract wins in key vertical sectors for its Data Management and Data Collection business areas.
Following the release of D4t4's half year results to 30 September 2017 and the Company's contract wins announcement on 27 December 2017, the Company has recently converted a number of further significant opportunities from its strong pipeline of potential business: ...
This is a very similar announcement to the one in Dec 2017, which I commented on here.
The trouble is, that no mention is made of how trading is versus market expectations. If the company is winning all these new contracts, how come it hasn't said that it's trading ahead of market expectations? The only conclusion I can come to, is that these contract wins must be largely within the existing market forecasts. However, it could be the precursor to increases in broker estimates at a later date, perhaps? That's just guesswork though.
Broker update - the house broker has issued a useful update today. This points out that H1 results (6m to 30 Sept 2017) were poor, and that the company needed a very strong H2 in order to meet full year expectations.
I'm having a quick look now at the H1 results, and they are indeed pretty awful. H1 revenues was less than half that achieved in the prior year H1, at only £4.75m (PY H1: £10.0m). This resulted in an H1 loss before tax of -£581k, versus a PY H1 PBT of £1.92m.
So it seems that the RNS Reach announcements on contract wins in Dec 2017 and Feb 2018 are designed to reassure investors that H2 is indeed seeing the necessary contract wins. Although the fact that the company is holding back on specifically confirming full year performance vs. market expectations, makes me wonder if there is still some doubt perhaps?
Software companies can make tricky investments, as in many cases, performance relies so heavily on clinching contract wins before the year end cut-off date. Smart customers know that too, and hence can increase their negotiating leverage by creating delays.
Valuation - the house broker reckons its 10.1p EPS target for 03/2018 is achievable. That puts the share on a PER of 14.4 - which seems reasonable.
Balance sheet - on a very quick glance, the last reported balance sheet looks absolutely fine to me. There's £3.9m net cash, and a healthy working capital and NTAV position. So no issues there.
My opinion - this looks an interesting software company, and seems worthy of a closer look. I don't understand its product or market, so can't really form a strong view on it either way. However, the valuation looks attractive, if the full year forecasts are met - which is the key issue for now, as a lot has to be achieved in H2 to recoup the poor H1 performance.
Personally, I'd rather play it safe, and wait to see what the full year numbers look like. However, it does look a potentially interesting company, operating in a fashionable space - of data management. If that strong pipeline continues to convert into more contract wins, then the company could see its shares re-rated onto a growth company rating. So I'll keep my eye on this one.
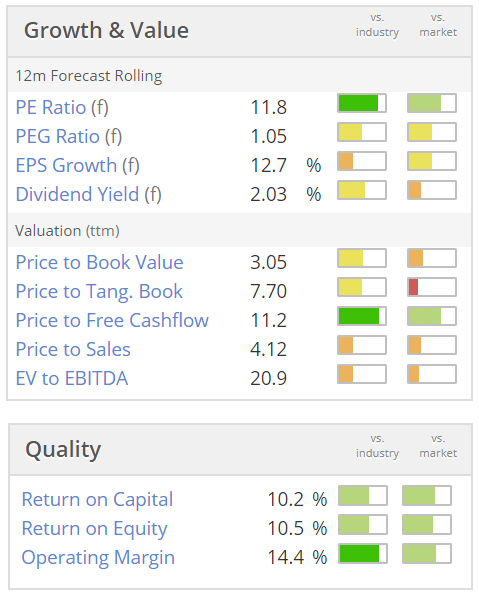
The forecast risk means that, at the moment, the market is being sceptical on valuation, as you can see;
Xpediator (LON:XPD)
Share price: 43.5p (up 13% today)
No. shares: 117.4m
Market cap: £51.1m
Xpediator, (AIM: XPD) a leading provider of freight management services across the UK and Europe, is pleased to announce a trading update for the year ended 31 December 2017 ("FY 2017").
This share listed in August 2017, and it's a new one for me. Thankfully Graham wrote a nice review of the company at the time of its interim results, here on 25 Sep 2017. Thanks Graham, that review has saved me time today!
Today's update says;
Group revenues for FY 2017 will be up by approximately 59% to 116 million (2016: 72.8m) reflecting approximately 10 million of revenue contribution from the three acquisitions completed during 2017, and positive performances from all three of the Group's trading divisions.
Trading profit is also expected to be significantly ahead of the previous year despite investment in strengthening the Company's key operating functions to support the current and future growth of the business.
The Group trading results for FY 2017 are expected to be in line with market expectations.
That section gets less & less exciting as you read it - we end up with just an in line with market expectations outcome. As Graham points out in his earlier report, a lot of revenue is just pass-through revenue, so it's the profit figures that matter.
More acquisitions are in the pipeline. There seems sound logic behind making acquisitions in this area, providing management bandwidth can cope;
We are capitalising on the positive market environment and growing organically whilst executing our strategy of being a market consolidator through acquiring sub-scale business which are immediately earnings enhancing with the potential to flourish as part of the Group.
I'm pleased with the performance of each of the three businesses acquired during the year and their integration within the Group is proceeding in line with management expectations.
I've had a quick look at 2 previous acquisitions, Benfleet Forwarding here in Oct 2017, and Regional Express here in Nov 2017. They look sensibly structured deals, using a mixture of cash, shares, and earn-outs, to buy decently profitable businesses at what seem attractively low prices. I'm starting to warm to this share.
Valaution - the StockReport shows (as always, the data comes from Thomson Reuters) broker consensus of 3.15p EPS for 12/2017, based on profit after tax of £3.15m. That is a 2017 PER of 13.8.
Placing - a small placing raised £2.8m (before expenses) in Nov 2017, being 7m new shares issued at 40p. The purpose of the new funds was to help make more acquisitions, and to increase profits by taking advantage of early payment discounts offered by suppliers.
Balance sheet - I've had a look at the 30 Jun 2017 balance sheet, which looks odd, with enormous debtors and creditors, both of which look too big for the size of business. This was pre-IPO, so I'll reserve judgement on the balance sheet until I've had a chance to properly go through the 31 Dec 2017 post-IPO balance sheet.
Major shareholders - the shareholder register is very concentrated, so little free float means that this share will be extremely illiquid;
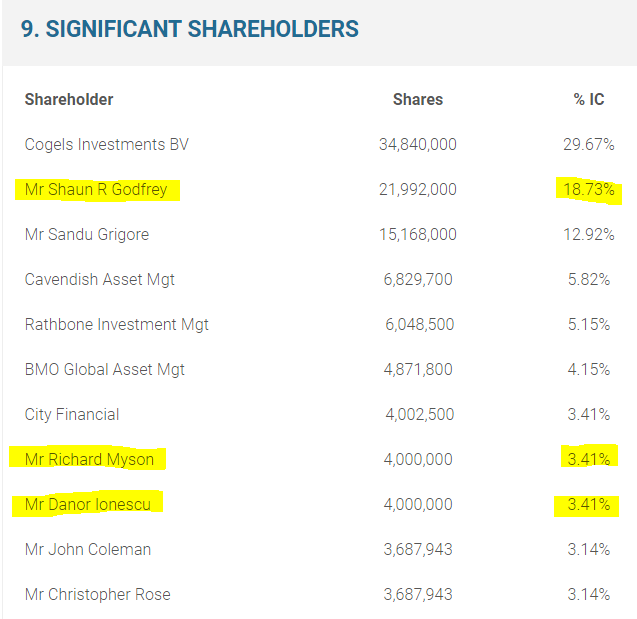
I've compared this list (from the company's website) with the page showing its Directors, and have highlighted the shareholders who are also Directors. Note that Shaun Godfrey is a divisional CEO, not a main Board member.
The impression from the short CVs on the company website, is that management seem experienced in the sector, entrepreneurial, and have a decent amount of skin in the game - which is positive.
My opinion - this is not a sector that I would normally want to venture into. Although it's important to note that this group of companies are middle-men, not actual operators of lorries. It does operate warehouses though, including 10 in Romania. It's cheap and easy to procure, and operate leased warehouses, which usually don't need much capex either.
I like the growth through acquisitions of profitable businesses, at low prices with earn-outs. If lots of acquisitions can be managed and integrated (a difficult task), then this could become a bigger and altogether more interesting group.
So it's going on the watch list as potentially interesting, subject to me having a good rummage through its 2017 accounts, when they are published.
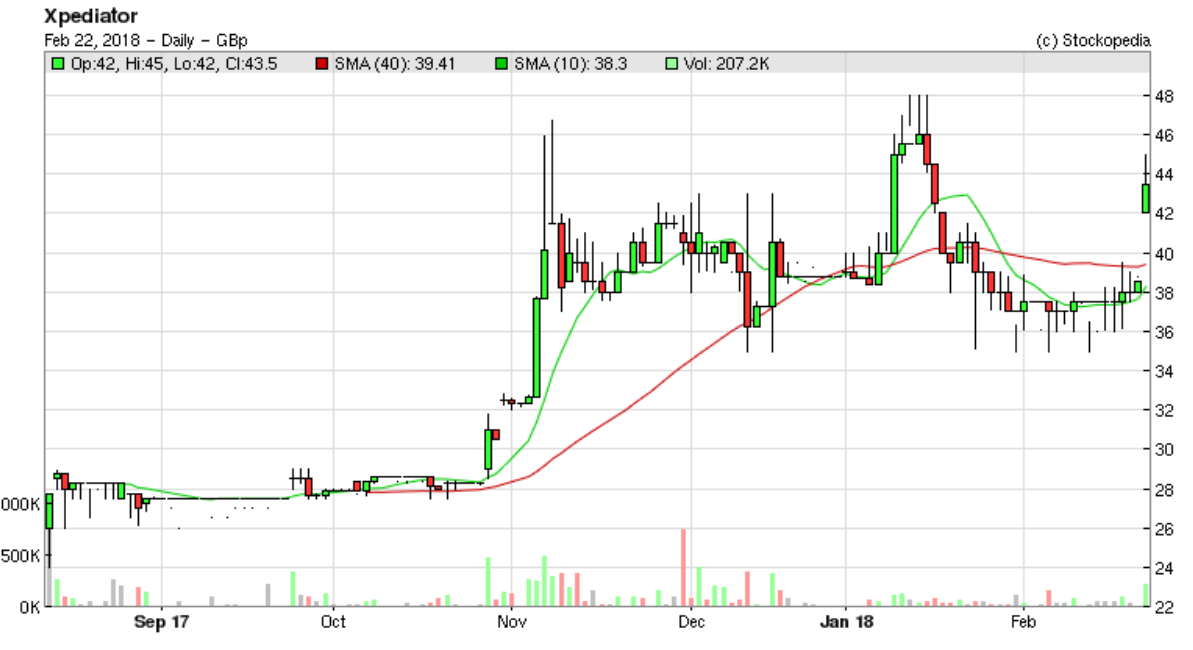
It's still early days, but so far this IPO has been successful;
Macfarlane (LON:MACF)
Share price: 84p (down 2.3% today, at market close)
No. shares: 157.5m
Market cap: £132.3m
Final results - for the year ended 31 Dec 2017.
To save me some typing, here is a copy of the company's self-description given in today's results announcement;
Headline figures look good;
Macfarlane Group PLC achieved another year of growth in 2017 with;
- sales of 196.0m, (2016: 179.8m) 9% ahead of the previous year ,and
- profit before tax of 9.3m (2016: 7.8m), 19% ahead of 2016.
- The trading performance continued the positive trends of recent years and the results were in line with market expectations.
Diluted EPS of 5.22p is up 13% on 2016. Whilst the company says that this is in line with market expectations, I'm seeing a higher figure, of 6.1p on the StockReport (which ties in with a research note from Arden, from Nov 2017).
The difference seems to be due to adjustments made by analysts, but not made in the reported numbers by the company. It would be useful if the company would in future also report adjusted EPS, to make its results more easily comparable with broker forecasts.
Arden show 6.09p adjusted EPS forecast, and 5.02p reported EPS next to it. The reconciling item is probably the £1,580k charge for amortisation of intangibles, which looks to be about the right size for that EPS discrepancy. Analysts usually disregard amortisation of acquisition-related intangibles, so this fits together OK. I just wanted to satisfy myself that the results are indeed in line with market expectations, which it looks like they are.
Consensus is currently for 6.9p EPS for 2018, giving a current year PER of 12.2 - looks good value, at first sight. Although a packaging distribution company wouldn't normally attract a high rating.
Acquisitions - seem to be generating most of the growth in revenues and hence profits. There's nothing wrong with this per se, but we should avoid giving too high a PER to a group that is buying in growth, as opposed to more valuable organic growth;
Packaging Distribution increased sales by 10% to 171.8m (2016: 155.9m) with 3% achieved from organic growth and the remainder from acquisitions, both those in 2017 and the full year benefit of those completed in 2016, all of which continue to perform well.
There is also balance sheet risk from growing via acquisitions, so I'll check that next.
Balance sheet - there are several points of interest here.
NAV has shot up, from £39.3m a year ago, to £57.2m at 31 Dec 2017. There must have been a fundraising, which can be quickly confirmed by seeing that the share capital and share premium lines on the reserves section of the balance sheet have risen considerably;
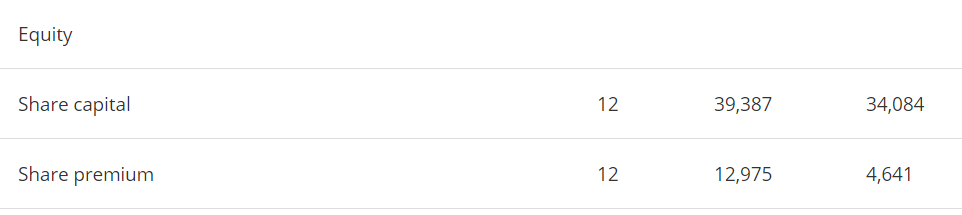
Adding the two lines together, total share capital rose from £38.7m at end 2016, to £52.4m at end 2017. This suggests that an equity fundraising of £13.7m occurred in 2017.
Following this through to note 12, it all reconciles, hooray! There was a fundraising of £8.0m in Sep 2017, issuing 12.1m new shares at 66p each. Then another equity issue of £6.0m occurred also in Sep 2017, being part of the consideration paid to the vendors of Greenwoods. Costs were £363k, which arrives at £13.6m, which allowing for rounding, ties in with the £13.7m figure above.
NTAV is less impressive, since as I suspected, the balance sheet is top-heavy with goodwill related to acquisitions, totalling £57.2m. Deduce that from NAV of (coincidentally) £57.2m, and NTAV drops out at a big fat zero! Not very good at all.
Part of the reason is a pension scheme deficit of £11.8m, within long-term liabilities. This has reduced from £14.5m a year ago. Assets are £81.0m, and liabilities are £92.8m. The word "pension" appears 38 times in today's announcement.
I tend to focus on the cashflow impact of pension schemes. In this case, there seems to have been company contributions into the pension scheme(s) of £3.39m in 2017, and £3.0m in 2016. Those are big numbers, relative to profitability. So it would certainly be wise to adjust the valuation of the shares to reflect this burden of cash outflows which would otherwise had been available for dividends. So the lowish PER isn't such a bargain, when you consider that a lot of the cashflow has to go into the pension scheme. That also explains why divis are rather modest, with a forecast yield of about 2.7%.
Opinions on pension deficits differ. We do seem to be, tentatively, moving into an era of interest rates starting to rise, which could be helpful in reducing pension scheme liabilities in future.
Receivables - look too high, at £52.6m, for a business with revenues of £196m. That would need looking into.
Current ratio - not great, at 1.05. This is not necessarily a concern, providing the bank remains happy to continue extending borrowing facilities. I can't see any reason why they wouldn't.
Outlook - key excepts below;
... Group profitability in the year to date is ahead of the same period in 2017...
Macfarlane Group's performance in 2017 reflects the successful implementation of this strategy and we are confident that the Group will demonstrate further progress in 2018.
My opinion - it looks a good group of businesses. However, I'm not particularly happy about its balance sheet. The big pension deficit recovery payments are sucking quite a bit of cash out of the business at the moment. So I would be more comfortable with a single-digit PER, to compensate for this.
Interestingly, Macfarlane, and Norcros (LON:NXR) are examples of companies which seem to be making acquisitions as a way of diluting the pension deficit into a growing group. That looks a good strategy.
This share has been in a decent, gradual up-trend over the last 5 years. If it can keep growing earnings, whilst keeping debt & pension deficits under control, then that trend could continue.
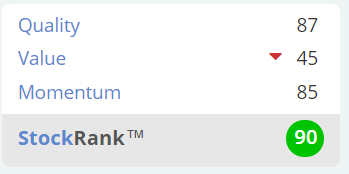
Packaging is a very competitive sector though, so on balance it's probably not for me. I can see why some investors might like this company though. It has a high StockRank too, and a favourable "High Flyer" classification;
Beeks Financial Cloud (LON:BKS)
Share price: 60p (down 7.7% today, at market close)
No. shares: 49.1m
Market cap: £29.5m
Beeks Financial Cloud Group plc (AIM: BKS), a niche cloud computing and connectivity provider for financial markets, is pleased to announce its unaudited results for the six months ended 31 December 2017
I'm having a quick look at this, following some reader requests in the comments section below. This is a new one for me - the company floated on AIM, on 27 Nov 2017.
Here is the AIM Admission Document. I've read through most of it, and have made notes as follows;
- 49m shares listed on AIM at 50p placing price, in Nov 2017 - original market cap £24.5m
- New cash raised in placing 9m new shares - £4.5m gross, £3.76 net of fees - ouch!
- Existing shares sold by employees, including about half by CEO was total of 5m sale shares.
- 30th June financial year end
- Strong revenue growth, but profits going down, reaching losses in 2017 (although exceptional listing costs caused most of the deterioration in profitability)
- CEO is founder (a big plus in my view), and still owns 61.8% of the company post IPO.
- Directors CVs look good - credible people, considering how small the company is.
- Heavy capex - in computer systems (£1.6m capex on computers in 2017) - some financed via finance leases.
- Strapped for cash prior to listing, now resolved - balance sheet OK now.
- Staff costs rising fast.
- Directors pay is very low - which flatters historic figures - total £143k in 2017 (highest paid £59k!) - how refreshing to see modest figures like that, but they will rise rapidly in the future, I imagine, thus absorbing some of the future profit growth.
- Historically didn't capitalise development spend, but I see this has started on a modest scale in today's interims.
- Most revenues overseas, and has a focus on the Far East.
- High level of recurring revenues.
Interim results today don't look great, but perhaps that's to be expected for a small, rapidly growing company?
- H1 revenue up 40% to £2.57m
- H1 operating loss of £44k (2016 H1: loss of -£135k)
- Balance sheet has been fixed by the Nov 2017 placing/IPO, and looks fine. Hopefully growth could be self-funding?
My opinion - I don't know anything about this sector, but can see that there must be a good market for cloud-based, low latency links for financial exchanges. It would be interesting to find out what the competitive situation is? There must be other companies offering the same service?
The market cap of almost £30m looks a bit rich, considering the company is so small, and not yet making meaningful profits. Although at least it's not burning cash.
Overall, I don't have a view on this either way. It could have potential, but I don't know how to assess that. I'd be interested in learning more about the company, and maybe meeting management at some stage. Although with the CEO owning most of the shares, this share would probably be too illiquid for me.
Another worry would be that if the IT fell over catastrophically, then the business could quickly implode. I'm sure their systems are excellent, but everyone thinks that, before they get hacked. It would be good to find out what actual users of the software think of it - that's the crux for this type of business.
That's it for today!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Paul,
Macfarlane (LON:MACF) Took me a whole day to get half way where you are so thanks. Also I hold Norcros (LON:NXR) I had not "compared and contrasted" before but see your point. Next... find other pension deficits.. I hold Avon Rubber (LON:AVON) fully priced despite deficit, 600 (LON:SIXH) the same. Surely some old legacy state companies must be in the loop? Perhaps £BT.A but that might also be a play on the copper they have in ground (I no longer hold) or one I hold a tiny position National Grid (LON:NG.)
Anyone got a small cap screen for improving pension deficits?
Regards,
Seadoc
Hi Seadoc.
Not sure if this is what you had in mind, but a quick and dirty screen that identifies small cap companies (less than £500m) with gearing of more than 20% and gearing including including pension deficit of more than 50% where the ratio of gearing including pension deficit raises the overall gearing by more than 1.5x. Easy enough to change any of the variables to get a different mix. Current settings find 27 companies including Macfarlane (LON:MACF) and Norcros (LON:NXR) .
https://www.stockopedia.com/screens/pension-deficit-388973/
I have previously had a short spread bet open on Devro (LON:DVO) from this screen on concerns about very high, some of it hidden, leverage.
Gus.
nice screen
from this - a bit of manual work shows the following having declining pension deficits
Caffyns (LON:CFYN) ; Chamberlin (LON:CMH) ; Macfarlane (LON:MACF) ; RM (LON:RM.)
only 4 out of the 27
of the names that have the biggest increases in pension deficit y/y
Carclo (LON:CAR) ; Devro (LON:DVO) ; £HVE
Gus,
Many thanks, sold out of Devro (LON:DVO) a little time ago but for under a pound a day it is amazing what you can dig out of Stocko is it not?
Regards,
Seadoc
Xpediator (LON:XPD) Thanks Paul. There is a recording on the Sharesmag website from 19th October 2017
https://www.sharesmagazine.co.uk/video/stephen-blyth-ceo-and-richard-myson-cfo-of-xpediator-xpd
Thanks for that Xpediator (LON:XPD) video - well worth a watch.
As a long term holder of Zytronic I certainly agree with Pauls' analysis and I find the large amount of cash held by the company to be very sensible. The financial characteristics of this company (apart from the exposure to a limited number of customers) remain strong and attractive so I find it an easy decision to remain a holder.
Interesting news coming out regarding £FLYB
sold out of Zytronic (LON:ZYT) in Sep when it hit my target: been watching it though as price was staging ar ecovery from the downtrend: however, it only peeked above the 200DMA yesterday and has now resoundingly rejected that. It is a good ol indicator of confidence the 200.
worth noting the geographical spread of Zytronic (LON:ZYT) 's revenues: earnings may meet expectations but GBP is appreciating relative to post Brexit lows: I assume they are quoting constant currency? If not then earnings may let a GBP appreciation headwind. Back on the watchlist, I'd fancy a bit below 440p .
Good but expected news from £D4T4, it adds to a recent spate of positive news: I bought a few bucket loads after the dip on earnings last November. The director dealings following their commitments on closing sales in their pipeline added to confidence which now seems to be playing out. If sentiment changes then the broker forecasts of 200p might become more achievable. I am bullish on their technology and capability so I'll ride the waves on this one, less of a trade and more of a conviction for me (and a violation of my 200 rule - though this was a reversal play which didn't move towards the stops and was resilient in the recent sell-off with positive RSI)
would be more convinced of an entry in GAME Digital (LON:GMD) around 25p or better at 20p. Would want to see evidence of a turnaround in trend - this could happen with half year results at the end of March
Market responding well to Vitec (LON:VTC) results today. Anyone got any thoughts on this small cap. Have it on my watch list but have not dug into it too deeply yet.
Paul,as I indicated in my answer to bestace,I quite like companies that hoard cash.It tends to provide a valuable prop to their share prices,particularly where a company is unable to grow its earnings.Yes,of course,companies can attempt to grow their earnings through acquisitions,but genuinely earnings-enhancing acquisitions are hard to find.All too often,companies wind up overpaying for poor assets.So hopefully,Zytronic will take its time and get things right.Or get taken over,which would be fine too.
We all know hindsight is a beautiful thing, but looking back on the GAME Digital (LON:GMD) chart I can see a number of obvious pull back zones.
For anyone who is interested in GAME Digital (LON:GMD), today should be a good entry point - with a target of 50p and a stoploss of 20p.
GAME Digital (LON:GMD) - Look at the recent holdings RNSs. One of (if not the) largest holders is selling down their stake. That's the reason the price is dropping constantly. I didn't like the deal with SD and I suspect neither does Elliott Capital Advisors.
It's certainly pertinent to point to the share sales by Elliot Capital (Duodi) as that must be a factor in the current price movements, but I'm not sure one can read them as a verdict on the Game collaboration.
The started selling on the 15th Jan nearly a month before the deal was announced. If the sell off is in anyway linked to the collaboration that would be such a clear example of insider trading as to be unthinkable, surely.
Just for background, Elliott brought GMD to market in 2014 and retained 61% ownership at the IPO, reducing to 43% via a placing a few months later. So you'd think they must have had some form of exit plan albeit at a much lower price than the 200p/share they achieved in the IPO and 260p in the follow up placing.
There was a bit of a storm three years ago when they sold some shares in advance of a profit warning
At the time a spokesperson for the company said
So one would have to presume that they can demonstrate that their selling is not linked to the Sports Direct Deal.
Or am I just being too trusting????
Elliott are said to be in advanced discussions to buy Waterstones, so perhaps the GAME Digital (LON:GMD) sell off just reflects moving on to next big thing?
Macfarlane (LON:MACF) please.
Seems to be repairing the balance sheet substantially and is growing nicely. I'm looking forward to the recalculation of the statistics.
Does anyone know, is the company data updated every day, so will the financial data and the recalculated metrics for Value / PE etc be available tonight?
morning - a tad under £10 mkt cap but could you look at Arcontech, ta.
Arcontech (LON:ARC)
Interim results out today. This has been a steady grower over the years and this morning's update is in a similar vein. IT related business providing real-time data systems for banks and financial institutions. I hold for the steady growth, recurring revenue, low PEG, maiden dividend paid last year, cash generation allowing potential for small acquisitions and clearly prudent management.
The downsides, if they can be called that, are that the nature of the sales cycle is long so contracts can be lumpy and there is always an element of deferred income which always need to be watched for any profit variations.
Market cap is at the low end of your range.
I have a holding in Arcontech (LON:ARC)
Would echo your sensible points. I'm intrigued by the potential of their new desktop product. If it's able to gain some traction, it could eventually appeal to a wider audience than just global investment banks. That could bring a welcome reduction in customer concentration which is extreme at the moment.
Maybe you could tell me why I'm such an idiot that I've managed to go from +60% up on GMD to -30% without any profit-taking or stop-losses.
Or maybe someone could recommend a decent psychologist for that. :-(
Hi Paul,
It would be great if you could comment on Northgate (LON:NTG).
Thanks
Northgate (LON:NTG) announcement this morning was welcome news in my view and thought the negative price movement a significant over-reaction. It was taken as profits warning but wasn't really on a cashflow basis, which let's face it is the most important element of any profit!
The UK has returned to VOH growth and Spain is blowing the lights out. Some margin pressure in the UK but more a re-positioning against competition than anything structurally erosive from what I can glean.
New mgmt very sensible to optimise fleet age and thus cash returns so I take this as significant. Have been impressed so far with the priority in which management have targeted improvements in the business.
Sitting on a 20%+ discount to book value : next year PE of 7* and with a dividend of 5.5% I am happy to hold. Can't figure out why it is hated so much as its target market is growing
Thanks for your comments. I agree with you and in fact I intend to hold too. I was surprised why the market went off to punish this stock. I agree with you with regards to the management too. For quite a while they have been done quite a good job in maximising efficiency, controlling costs and building the business.
Not a small cap request, but I was wondering if any one could help me translate for those that are well versed in director b'speak:
"The combination of political and regulatory intervention in the UK energy market, concerns over the loss of energy customers in the UK, and the performance issue in North America have created material uncertainty around Centrica and, although we delivered on our financial targets for the year, this resulted in very poor shareholder experience. We regret this deeply, and I am determined to restore shareholder value and confidence."
My translation for what its worth, especially in the context of other points:
Things are bad, really bad. The bit that you read about and thought was bad, was bad, but so is everything else apart from our debt (which is not good!)
Not our fault! Even though we have been losing customers for a while, well before the election, its got nothing to do with us.
We hope to fix things, but might not and if we do, it will be by cutting costs not improving revenue. In order to avoid another 40% drop in Q1 18, we are maintaining our dividend (for now but will cut as soon as this material uncertainty manifests).
On a happy note, our debt position is great only costs us 50% of "Adjusted" Op Profit to service and will become better once we sell nuclear, but please ignore our historic losses on disposals as we will adjust them out!
FYI - please ignore pension deficit which costs us 70m a year for next 15 years (at least) and is not included in our net debt - its only an extra 50% of our net debt, which will put us firmly in the upper end of guidance.
Centrica (LON:CNA) is the company if not figured out already -
Not a holder and don't intend to become one.
I sold out of my final chunk of Zytronic (LON:ZYT) first thing. Today's reference to top line and bottom line being "broadly in line" with the prior year sounds like a mild deterioration on the "along similar levels" wording used in December's outlook, and with growth looking like it will be flat to negative this year, there are probably better shares to be in right now.
The hike in dividend is nice, but it will only reduce their £14m cash pile by less than £2.4m. If they can't reinvest the cash in the business or in M&A, they should really be giving it back to shareholders.
I agree that this is a mild profit warning since the forecast is for a slight increase while "broadly in-line" means that they're a little below the current year. I've sold out with just a little regret as this is a fine company with sensibly remunerated management. Still they're a little bit highly rated company when there's no growth to speak of and there are better opportunities out there.
Hi bestace,
I sold out of my final chunk of Zytronic (LON:ZYT) first thing. Today's reference to top line and bottom line being "broadly in line" with the prior year sounds like a mild deterioration on the "along similar levels" wording used in December's outlook, and with growth looking like it will be flat to negative this year, there are probably better shares to be in right now.
Yes, I sold half of mine this morning. I was surprised I was able to sell at 522p given that it closed at 533p last night and I got the 15p dividend (it went ex-div today). The statement is so dull, as per usual, that I worry about anyone attending the AGM falling fast asleep and missing their train home - I can't imagine it will be the most interesting event. Perhaps the lack of revenue growth is caused by the sales technique being as dull and uninformative as the announcements to shareholders...
I'd be interested to know where you're looking to park the proceeds? I have a lot of cash at the moment and so keen on finding new ideas. FWIW I decided not to sell out completely because Zytronic (LON:ZYT) still passes my quality tests in terms of cashflow generation and operating margins, so even in the absence of much revenue growth the balance sheet will remain bullet proof and the cash returns will continue. Hopefully, one day there will be a significant cash return but as things stand it won't be re-invested in Zytronic shares .
All the best, Si
I'm just leaving the proceeds in cash for now, I'm not really in a hurry to recycle the money into something else.
One other thing I noticed from looking at last year's AGM trading update from Zytronic (LON:ZYT) :
There's no reference to management expectations in today's announcement, from which I think it can be inferred that not only is growth flat this year, the drop off is also below management expectations.
I'm just leaving the proceeds in cash for now, I'm not really in a hurry to recycle the money into something else.
Fair enough. I just wondered whether you had anything else in mind because I'm struggling to find much of interest currently that I don't already hold. I just took another small bite of H & T (LON:HAT) at 330p with some of my proceeds from Zytronic but otherwise have cash burning a hole in my pocket. As with Zytronic (LON:ZYT) this morning, I have a great problem completely selling out of fundamentally sound companies when I have more cash than I would like.
There's no reference to management expectations in today's announcement, from which I think it can be inferred that not only is growth flat this year, the drop off is also below management expectations.
This is the problem though, isn't it? We're having to read between the lines and infer all kinds of things from this RNS that only covers 4 months. They really are rubbish at shareholder communication, they clearly put zero effort into it, so I can't really see the point of people wasting shoe leather going to the AGM today - hopefully they'll get a nice biscuit although it'll probably end up being a stale Rich Tea with a lukewarm cuppa from a vending machine! As you can tell, I'm not dreadfully impressed by the Zytronic management.
All the best, Si
Well traded,bestace,but I disagree.When a company is unable to grow its earnings,hoarding a bit of cash can provide valuable support for its share price.If instead the company pays the money out in unsustainable dividends,these attract high rates of tax for many of us and the share price tends to fall.
Of course,there is the alternative of share buybacks,but that can lead to illiquidity in the shares.
I doubt you'll find anyone who is advocating for unsustainable dividends!
I think you might have had a point if the cash pile was a lot smaller than it actually is. This is how the cash has grown over the last 6 years, compared to profits (figures from the Stockopedia company pages):
Paul pointed out in his report how the company had a duff year in 2013, and that's clear from looking at the blue bars in the chart, but note how even in that year the cash pile increased.
So to my mind it is questionable whether the cash is even needed as a rainy day fund, certainly not all £14.1m of it. The company has not engaged in M&A activity in the past, appears to have no interest in doing so in the future, nor does it appear to have opportunities to reinvest the cash back into the business at high returns on capital.
The way I see it, the cash belongs to the shareholders and if the Zytronic (LON:ZYT) directors can't find a good use for it (as appears to be the case), then I'm sure their shareholders certainly can.
GAME Digital Please
Vitec (LON:VTC) please
Me too for GAME Digital (LON:GMD) please. Price drop arguably excessive given net cash of 39p - would love to hear Paul's views. I hold.
Another vote for GAME Digital (LON:GMD) albeit with acknowledgement that you normally don’t comment without a relevant RNS.
I don’t know if GAME Digital (LON:GMD) is really in Paul’s remit for today given that there has been no further news since the announcement of the Sports Direct Partnership on 12th of Feb on which Graham wrote a piece and Paul also responded in the comments https://www.stockopedia.com/co...
However as there seems to be renewed interest I’ll add my further thoughts.
The size of GAME Digital (LON:GMD) ’s cashpile is widely cited, with the inference that the Enterprise Value is virtually zero. This is false an I believe most of the cash needs to be treated as working capital.
We know that the December cash figure is substantially boosted by Christmas sales cash in the tills and probably supplier bills yet to be paid. Nevertheless even the July cash figures look very high (£47.2m at 29-Jul-17 vs current market cap of £57m), however I am pretty sure there is a point in the cycle where cash levels are much lower.
In 2015 GAME Digital (LON:GMD) issued a special dividend of £25m (14.7p) stating that this was “balancing the need to fund growth with the discipline of returning excess capital”. Subsequent to this the cash balance at July 15 was £63m and from this I infer this sum was not regarded as “excess” capital.
Furthermore we should look at available borrowings, in November we were told that the company had access to borrowing facilities of £77m, they also subsequently received £17m cash for the disposal of Multiplay. The Sports Direct deal also opened up borrowing facilities of up to £55m – I presume that this is on better terms (Barclays base rate + 2.5%) than the previously announced £77m so I don’t presume they will use both facilities. This level of potential borrowing however clearly does not speak to a business with a massive pot of unused cash.
I do believe that the balance sheet is strong, but I just don’t accept the “massive cashpot” argument.
The Sports Direct deal however is a real puzzle.
Strategically it looks great, offering the ability to host Belong arenas and/or Game stores in SPD’s stores. Remember that Game have very short leases and therefore have substantial scope to migrate stores into SPD concessions. I believe many of Game’s existing stores are not suitable to include Belong arenas, whereas the SPD stores tend to be much bigger (and potentially SPD’s strategy will free up space). The acceleration that this deal enables may well be very important in stealing a march of Gfinity (LON:GFIN) for the leading e-sports position.
However the financials of the deal don’t seem great, for £3.2m SPD get 50% of BELONG and of any Game stores located in SPD premises although Game will fund the development of the “venues” and retain the fixtures and fittings.
At face value it seems that they have sold 50% of BELONG very much on the cheap and I think this is the reason for the depressed share price.
I suspect that the judgement was that the strategic benefits of the deal are such that even the diminished share of BELONG will be worth much more to the company than had they not done the deal. I’m tentatively inclined to accept that judgement, however I really want to see some proof of the pudding emerge before I act on that view and I feel that “the market” is taking the same view.
So for now, I am watching GAME Digital (LON:GMD) rather than buying.
Thanks for your comment. Looking over the last available figures, as at 7.2017 cash was £47m, which happened to work out the same as net current assets, which will take account of the value of inventories, payables, receivables, cash etc. Total net assets was £109.2m and taking out the intangibles of £47.5m that leaves £61.7m. But then you need to add £19m because of the sale of Multiplay, so that takes us to £80.7m. Of course this doesn't allow for trading losses although I'm not sure how much effect should be expected to net cash. Liberum seems to expect a net cash outflow of £6.1m by 7.2018. So on this basis net tangible assets should be £103.1m at 7.2018. This works out at 60p a share. So the shares are at only half of net assets.
Now I am probably missing something major here and that is why we need Paul's expert eye to tell us if I am and if so what. So Paul, we know there was no RNS, but we all need you to put us out of our misery so please don't let us down!!
Gromley
I totally agree with you about the cash at GAME Digital (LON:GMD) - the fact the management stopped the dividend after the June interim payment indicates they agree too.
As a minor factor, recent weakness maybe due to the surprise £100 million buy-back announcement by Sports Direct on Tuesday. This presumably reduces the chances of it topping up it stakes in Game, or French Connection (LON:FCCN) (also a touch weak recently) and maybe also Debenhams (LON:DEB) (although that has performed well the last few days).
GAME Digital (LON:GMD)
Very insightful post, thanks for sharing!
I have some of my own thoughts, which are probably biased given that I am a holder, but here goes.
VALUATION
For the sake of argument I'm going to assume that:
Last financial year 39 store leases were renegotiated for annualised cost savings of £1.4m.
In the next 18 months, 221 store leases are up for negotiation. A very rough estimate, but that would equate to annualised rental savings of £7-8m.
Contribution from Belong stores is c.£100k (with c.12 month payback periods). Even with 50% profit share agreement in place GAME Digital (LON:GMD) would be looking at £5m annualised contribution once they hit 100 stores (100 stores x £100k per store * 50% profit share).
I originally expected 100 stores to take about 3 years, but maybe things might accelerate with Sports Direct on board?
The 2 bolded figures above already provide enough support to justify the current market cap (£57m) in my opinion.
WORKING CAPITAL REQUIRMENTS
Leaving the above assumption aside for a moment I actually think a lot of the current cash balance is required for peak trading periods. The rationale is as follows:
Experience has taught me to never like debt, however, I'm comfortable with the above as the business is currently cash generative and I want any additional cash to be re-invested into the Belong stores (which is what is happening).
EV
To take things one step further, if we assume that GAME Digital (LON:GMD) were to liquidate post peak trading, then (using July 2017 Y/E figures) after clearing all liabilities the company would have surplus cash of c.£60m. This should, in my opinion, maintain a floor for the share price of c.30p.
Also bear in mind that OCF was positive in both the last years (it was £7.7m in 2016/17) so things would have to go really wrong for this to turn negative.
SPORTS DIRECT
As for the deal with Sports Direct, I don't know why GAME Digital (LON:GMD) would sign up to it if it was a bad deal. If the terms were bad they could (easily?) have walked away and continued as they were. As pointed out above they had/have plenty of cash and unused facilities open to them.
The only thing I was skeptical of was how much in-store rent Sports Direct will charge GAME Digital (LON:GMD). Presumably this will be low but what's to stop SP jacking this up if things take off and they want more than 50% of the bottom line?
GAME Digital (LON:GMD)
Graham raised a flag previously where I think he questioned whether the cash was genuinely representative. I think he was alluding to the idea that this balance may be significantly worse at certain points during the year so a bad key trading period could damage cash significantly.
I also didn't like the Sports Direct partnership. Looked like a big win for SD and rather less so for GD!!!
That said I'd be tempted sub 30p
D4T4 Reports a "number of new contract wins in key vertical sectors for its Data Management and Data Collection business areas" No numbers given. Broker finnCap have reiterated their recomendation and share price target (200p) this morning. Current share price is up 7.5p this morning at 140.5
https://www.investegate.co.uk/d4t4-solutions-plc--d4t4-/rns/new-contract-wins/201802220700085836F/
Also, if you feel like making any further comment on the GAME Digital (LON:GMD) deal with Sports Direct that would be great. The shares have now fallen 25% since it was made so clearly Mrs Market doesn't like it at all. Sucker that I am, I bought back in at 40p just before the deal was announced!
Francis
(Edit: Tripuram got in just before me)
Good Morning Paul,
Although there is no RNS for GAME Digital (LON:GMD) but this stock price seems to be taking a battering everyday... Any views would be appreciated as a general commentary....
I second this request for GAME Digital (LON:GMD) opinion. Thanks Paul
Hi,
There's nothing to report on with GAME Digital (LON:GMD) - I don't want to get sucked into speculating on share price movements. I'll report on it next time there is news.
Other reader requests - I'll try to look at Macfarlane (LON:MACF) , Beeks Financial Cloud (LON:BKS) , and Wilmington (LON:WIL) plus the other shares already in the article header. That's probably enough for today.
Regards, Paul.
Just as an aside here, I'm not in game, having missed that, but I had from the sidelines thought that the idea was to merge the sporty stuff of SD with video games. I think this has awesome potential longer term. Some games are really adictive but going to the gym is really boring, what better way of getting fit than playing gta or whatever floats your boat with a physical element and skill ? However it seems that wasn't the idea at all, I still think that potential exists whether it happens through the SD link or not.
K
Seconding Morgan Sindall (LON:MGNS) unless its too big at £550m market cap. Seems to be bucking the trend of the rest of the construction industry by being more selective when going for contracts.
Thanks,
James
Zytronic (LON:ZYT) Please Paul
Macfarlane (LON:MACF) for me too, please.
Votes for Beeks Financial Cloud (LON:BKS) (Leon Boros likes its prospects) and Zytronic (LON:ZYT) please
Good morning Paul
£D4T4 just posted an update about new business wins but without any numbers attached or any update to profit expectations. So pretty meaningless...
But if you feel like reporting on them, that would be great
cheers
Francis
(PS I did use the pound sign but it won't convert - I think it's the numbers which confuse the system, like £G4M )
Investors should note that FinnCap have maintained their 200p target price on £D4T4 following this mornings news of ‘significant’ contract wins specifically give there is no warning over H2 miss.
thanks for letting me know, cheers
https://www.stockopedia.com/share-prices/beeks-financial-cloud-LON:BKS/
Your thoughts on their maiden interim results would be appreciated- they floated on AIM in November.
Looks like a high margin business - difficult to ascertain cash generation at this stage given investment in the business and float costs. They are presenting at David Stredder's Mello event in Derby in April.
Thanks
Morning Paul.
A new one for me but looks worth a look if you get a chance (even though it seems quite illiquid)...
Xpediator ( Xpediator (LON:XPD) ) – 38.75p – £45.5m – PER 9.92
Trading Update For The 12 Months To End December 2017 – Revenue will be up about 59% to £116m (2016: £72.8m) and Profit will be significantly ahead of last year – In-line with market expectations.
First time I have come across this company and there’s a lot to like. If I don’t pick some up this morning (need to keep an eye on that 7%+ spread) I will keep it on my Watchlist, 38p.
First time I have come across this company and there’s a lot to like. If I don’t pick some up this morning (need to keep an eye on that 7%+ spread) I will keep it on my Watchlist, 38p.
matylda,
FWIW I have a little internal rule whereby I never buy shares where the spread is wider than the operating margins. Having said that, I never buy anything with margins < 5% these days. I'm struggling to see what the attraction of Xpediator (LON:XPD) is tbh? I think the SR looks about right.
All the best, Si
Hi Si,
Re: Xpediator (LON:XPD)
Quite simple (like me), not saying simple is good, but it suits me and my approach - Scanning the fundamentals...
I like Rev 72.8 > 99.0 > 135.0
I like Profits 0.56 > 3.15 > 5.19
I like EPS 1.28 > 3.10 > 3.81
I don't particularly like the Op Margin of 2.44% but it looks like this is based on TTM (which I find annoying (have asked Stocko for the option to remove it)). Anyway, in 2016 it was slightly better (2.5%) but looking at 2017 and 2018 Revenue and Profit forecasts it looks like 5% is a more reasonable Op Margin forecast.
ROCE is stable and above Industry standard.
Not relevant much but the small Dividend is very well covered.
Net Debt is small.
Average Shares in issue stable.
The Spread and NMS is not particularly attractive - As I mentioned it's pretty illiquid.
On the update, I just like this...
Group revenues for FY 2017 will be up by approximately 59% to 116 million (2016: 72.8m) reflecting approximately 10 million of revenue contribution from the three acquisitions completed during 2017, and positive performances from all three of the Group's trading divisions. Trading profit is also expected to be significantly ahead of the previous year despite investment in strengthening the Company's key operating functions to support the current and future growth of the business. The Group trading results for FY 2017 are expected to be in line with market expectations.
If the fundamentals above are met - On the basis the PER is <10 and everything looks set to grow by at least 20% each year (and ROCE is 20%+) it was a no brainer for me.
I know it's a simple approach but was enough for me to open an initial position this morning.
Matylda, I agree on Xpediator (LON:XPD) and taken a small piece.
Not much time to write but I've seen a similar (unlisted) asset light pallet (similar to Pallex) logistic business which is probably best in class utilising 'tech' for efficient logistics. It saw a 12% historical CAGR growth in pallet volume and revenues were only slightly more than Xpediator (LON:XPD) 's is now but the EBITDA margin was 13% (and above 10% in the 3 previous years). Minimal working cap and capex means it's very cash generative (c.90%+ cash conversion).
Xpediator (LON:XPD) looks like it's very much still in growth phase and investing in fixed overheads will pull down the margins short-term but the benefits of scale over time and operating efficiencies should see margins increase to maybe 5% longer term.
The other key growth driver is that it may end up been an acquisition target itself (Pan-European mid-market is fragmented but consolidating) as economies of scale and efficiency can add considerably to the bottom line (i.e. running the logistics volume through a more efficient operators tech / model provides value for the acquirer and the target).
Just my 2p worth and could be totally wrong as not enough time to review the full detail.
One for the long-haul I guess (excuse the pun).
I may be wrong, but I think Xpediator (LON:XPD) used to be Benfleet Haulage, who then shifted into Eastern Europe. Three things make me suspicious, despite the nice figures. First the company has too much interest in the East (Europe not Anglia). Second, as mentioned, the wafer thin margins. Finally, if your head office is is Braintree why not say so on any of your releases?
From a market perspective on Xpediator (LON:XPD), building out a pan-European network is the only way to survive (UK only unfortunately doesn't equal efficiency in logistics). I don't know why European acquisitions alone would necessarily raise suspicion ?
International freight flows is the growth area of the European market and East to West (given the propensity for Western European firms to move to 'near-sourcing' in recent times and e-business / e-commerce) makes a lot of sense. Anecdotally, have you noticed the growth in the number of Polish lories on the road over the last few years?
The trick in their Romanian pallet operation for example is how to send a lorry from Romania to Scotland stopping in Belgium, France and London on the way to pick up / drop off other packages and do this efficiently.
Whether the management has the skill to integrate these businesses and continue to realise efficiencies, I don't know.
As mentioned earlier, I don't know the Company well but I do believe there are certain attractions to the market.
Lots of logic there nicobos, but I will remain sceptical. Wincanton (LON:WIN) were nearly destroyed by meddling in Europe. I still believe the only good things to come out of Benfleet have fins and scales!
I know it's a simple approach but was enough for me to open an initial position this morning.
Well, I wish you luck with it. I don't particularly want to be investing in illiquid stuff with wide spreads at the moment, but that's just me. If it's a very recent IPO with low operating margins and negative NTAV, then even less so. If it's based in Essex, then as a Hertfordshire boy, I've got my bargepole fully extended :-)
All the best, Si
Wilmington (LON:WIL) for me please. Thanks.
My morning smallcap tweet:
Starcom (LON:STAR), Zinc Media (LON:ZIN), Zytronic (LON:ZYT), Sinclair Pharma (LON:SPH)
Starcom (STAR) warns FY post-tax loss "materially higher than the breakeven to small loss previously indicated" due to share-based payment costs, unrealised exchange differences and certain holding company costs.
Zinc Media Group (ZIN) wins four 'significant' TV commissions from BBC, Channel 4 and Channel 5.
Zytronic (ZYT) AGM stmt - rev and profit in the first four months of the FY remain broadly in line with the equivalent period last year. House broker FY f/c was for adj EPS up 4%, reb down 1.5%.
Sinclair Pharma (SPH) drops US distributor for Silhouette InstaLift end March, by mutual agreement. "Sinclair will pay to Thermi a one-off, undisclosed payment for the early termination and will regain the full US distribution rights for the Products." Why the payment if the termination is mutual? "Advanced discussions with potential US partners are ongoing and we expect to enter into an alternative arrangement effective from 1 April".
Zytronic (LON:ZYT) Brief update "current revenues and profits over the first four months of this financial year remain broadly in line with the equivalent period last year."
EDIT: Also ex div today
Macfarlane (LON:MACF) for me too. Thanks
Could you take a look at the first Interims since IPO as posted by Beeks Financial Cloud (LON:BKS) ?
At first read they appear to trounce the forecasts (on stockopedia - Highly Speculative, Micro Cap, Momentum Trap) but would appreciate your take on their definition on 'Underlying' performance. I can readily accept IPO costs being stripped out but question the stripping out of some other costs which are possibly recurring(?).
Hopefully they can keep their costs under control going forward...
Beeks Financial Cloud (LON:BKS) I believe the forecasts shown on stockopedia are wrong - looks like they have the decimal point in the wrong place! . I also use Sharepad and they have eps of 3.4p for y/e june 2018 and 5.0p for y/e June 19 - with modest divis also forecast for both years - 0.3p and 0.5p.
On the basis of these forecasts - recently released but prior to results company needs to achieve just under £1m PBT in current half year to June 2018. Will be interesting to see if there are any changes to forecasts in light of interims.
Macfarlane (LON:MACF) please. Decent update. Debt and pension deficit, two previously identified weaknesses, both reduced. Steady ongoing trading performance.
https://www.investegate.co.uk/macfarlane-group-plc--macf-/rns/final-results/201802220700035822F/
Morgan Sindall (LON:MGNS) of interest too. Strong profit growth reported in today’s final results. Shares have taken a bit of a swipe following Carillion (LON:CLLN) fall out but still identified as a Super Stock.
https://www.investegate.co.uk/morgan-sindall-grp/rns/final-results/201802220700065876F/
Thanks,
Gus.
I posted a mid cap by mistake but unfortunately there does not seem to be a way to unsubmit.