Small Cap Value Report (Thur 25 June 2020) - NXR, TND, VCP, TPFG, WSG, UCG

Good morning!
Graham here to round out this week's SCVR coverage for you.
This morning I've noticed RNS announcements from:
- Norcros (LON:NXR)
- Tandem (LON:TND)
- Victoria (LON:VCP)
- Property Franchise (LON:TPFG)
- Westminster (LON:WSG)
- United Carpets (LON:UCG)
Let me know if you have any other suggestions, though I reckon these will keep me busy!
Cheers
Graham
Thanks for your suggestions. This might be a quickfire report as I attempt to cover as many stories as possible.
Today's report is now finished, as I have to go to the dentist! I have noted your suggestions and will attempt to catch up on them tomorrow. Thank you!
Norcros (LON:NXR)
- Share price: 169.52p (+4%)
- No. of shares: 80.6 million
- Market cap: £137 million
I know this as the owner of Triton showers, but it also owns Merlyn shower doors and a bunch of other bathroom and kitchen brands.
It tends to trade cheaply, which I've explained as being a function of:
- low organic growth.
- exposure to South Africa.
- its net debt and pension scheme.
It issued a warning in February, as the Covid-19 situation was beginning to deteriorate, and then downgraded expectations in April.
Full-year Results
These results (to the end of March), and current trading, are better than the guidance given by the company on April Fool's Day.
Trading is "ahead of our COVID-19 operating scenario".
Underlying operating profit for FY March 2020 is still down 7.5% compared to FY March 2019.
Statutory operating profit is down 31%.
Make sure that you ignore the percentage changes in the highlights table - they aren't comparing like with like.
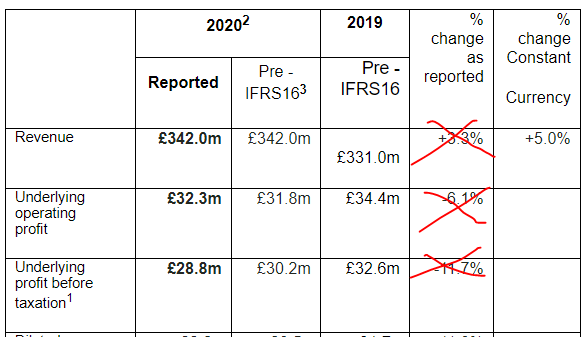
There is simply no point in comparing pre-IFRS 16 numbers with post-IFRS 16 numbers.
Net debt appears manageable at £36.4 million, but trading does need to normalise in order for it to satisfy covenants. Covenant waivers are agreed until March 2021.
Dividend - no final dividend is proposed. An unsurprising decision but I do think it's worth taking note of which companies have continued to pay dividends during this crisis, as they must be particularly resilient!
Pension scheme - the accounting deficit increases from £31.6 million to £48.9 million. That's a significant number for a company of this size. Norcros is paying £3.3 million into it this year.
Current trading
Current trading is gathering momentum and ahead of our COVID-19 operating scenario .Year to date revenues to the end of May were 40% of prior year with June month to date revenues running at c75% of the same period last year.
An encouraging improvement but still some way to go. Fingers crossed for the rest of the year.
Covid impact
The company provides some estimates for the impact of Covid-19 on its results in March.
Without Covid-19, they think that revenue would have been higher by £13.2 million (4% of yearly total) and underlying operating profit would have been higher by £4.6 million (14% of total).
This impact was mostly felt in the core UK business.
My view
Norcros has agreed with its lenders that net debt won't exceed £95 million until June 2021, when the earnings-based covenant tests are scheduled to resume.
That gives headroom of nearly £60 million. Enough? Probably.
For me, the company still has a "Yuck" factor, which will prevent me from investing in it, almost regardless of how cheap it gets.
Revenue growth on a like-for-like, constant currency basis was 2.3% lower. Without Covid-19, it's true that underlying revenue would have increased slightly, but not by enough to get me interested.
And the accounts are always full of adjustments. I like a clean set of numbers. The acquisition strategy has been ambitious and costly.
I will say that if you're bullish on the post-lockdown economic recovery, this would probably be a good way to bet on that.
Tandem (LON:TND)
- Share price: 273.3p (+5%)
- No. of shares: 5 million
- Market cap: £14 million
Please note that I have a long position in TND.
I was talking about this story yesterday. The largest shareholder had a private meeting with the company, in advance of this AGM, and switched from opposing management to supporting them.
There is too much background to get into, but the gist of it is that lots of shareholders have been unhappy with this company. Many shareholders have been agitating for "No" votes at the AGM.
The unhappiness has been on a number of fronts:
A) the weak dividend, relative to earnings.
B) very high management remuneration, relative to dividends, market cap and earnings.
C) a lack of engagement with existing and prospective shareholders.
I'm pleased to see that there has been some progress, at least when it comes to A) and C).
It had previously been announced that this year's final dividend would be increased, and would be supplemented by a special divi.
That makes the total annual payment for the year 6.6p (up from 4.31p in the prior year).
Note that EPS for the year was 40.5p. So there is still a long way to go before we get a generous payout ratio.
Anyway, the final/special dividend are being voted on today.
Tandem has enjoyed some incredible tailwinds in recent months: very fine weather, lockdown forcing people to exercise locally and spend more time in their gardens, and the government telling the population to avoid public transport and get on their bike instead.
The main difficulty has been in the supply chain.
I discussed that at last month's trading update. There were difficulties reported in getting bikes out of China, and I also found that swings were in short supply at Argos (the company provides a wide range of bikes, toys and outdoor products). Tandem said that summer revenue in 2020 was likely to be lower than the prior year, because of these supply chain problems.
Latest news
Today's update contains quite a few interesting snippets.
- Revenue +7% year-to-date
- Mixed performance from licensed products (e.g. Frozen, Peppa Pig). Retailers bought less product but domestic sales were nevertheless strong in certain areas.
- Bike sales +72% versus last year
- B2C revenue from outdoor products "significantly ahead" of 2019
Outlook is "broadly positive". The retailer order book is still down, but is "growing in preparation for the Christmas period".
In bikes, the company is "working hard to restore supply chains as soon as possible".
Management are "confident we will deliver another strong year" - I've been following this company for a while, and it doesn't get much better than that!
Investor Relations
This is fantastic news, and my favourite part of the RNS. The company is holding an Investor Day in September!
This will provide shareholders with the opportunity to visit our Birmingham operation to view some of our products and discuss the business with the Board and management.
I've previously heard it said that management would not allow shareholders to look around HQ at all, not even on AGM day. I'm very glad to see that attitudes have changed.
And that's not all - there will be an interim results presentation, presented on this year's investor day, and at future interim and final results. That's another thing which some shareholders have been crying out for.
My view
I'm very glad to see that there have been positive changes at Tandem. Inviting shareholders to HQ to look at the products and talk to management, and producing a results presentation, are small gestures in the grand scheme of things, but they make a big difference.
After all - it's hard enough to study small companies, even when these facilities are available.
I'd be curious to go to the investor day myself, but getting married in October will make that impossible.
As for the investment merits of the business at the current share price, I'm not sure if I have much to add to what I've already written.
There is a StockRank of 99:
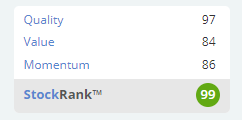
I'm not so bullish on it myself, or I'd have a lot more than 3% of my portfolio in it.
Having been disappointed by the company before, it's difficult for me to get too optimistic about it.
But I am tentatively starting to believe that the company is solving the very real supply chain problems.
If those problems are solved, then this year's results should be fantastic. There is no reason for them not to be, given the strong momentum from last year, the fine weather, and the other reasons for exceptional demand.
Who knows what might happen in 2021 and 2022? But I do think that the balance sheet, even with an increased dividend, should show considerable improvement. Which will make for a safer investment.
So I'm happy to continue holding this one.
Victoria (LON:VCP)
- Share price: 230.46p (+5%)
- No. of shares: 125 million
- Market cap: £289 million
This flooring company reports that trading is ahead of expectations since it reopened.
Manufacturing and distribution operations are back in every country in which it operates, in accordance with the local easing of restrictions.
Revenues are now running at 85% of pre-Covid levels. And "further recovery is expected as orders begin to flow to Victoria from UK retailers, who were the last to start trading as they were only allowed to re-open last week." (Continental Europe has been open for a while.)
There are no supply chain issues.
Net debt is £370 million, and available liquidity is a further £200 million.
Remember that is a debt-fuelled, growth-by-acquisition stock. Much of the debt (€500 million) is in the form of bonds maturing in 2024.
Outlook - the Board is "considerably more optimistic" than it was in March. It highlights that 93% of revenue is to do with redecoration projects, not construction or commercial.
My view
Whether or not you like this company depends on whether or not you buy into the vision of its Chairman, Geoff Wilding, who has been responsible for the aggressive growth and acquisition strategy here for the best part of a decade.
The shares almost reached 900p two years ago, as people bought into the magic.
I think the records will show that I've remained fairly sceptical. Though at 445p, in January (pre-Covid), I thought the valuation was fair.
At 230p, which looks like a discount to book value, I think you might be able to make a good argument that it's cheap (but do remember that book value includes lots of intangible assets, in this case).
This is another one for contrarians who expect our economies to bounce back quickly. It could quickly bounce back to 400p-500p, but the sector (carpets) and the leverage make me nervous.
Property Franchise (LON:TPFG)
- Share price: 167.5p (unch.)
- No. of shares: 26 million
- Market cap: £43 million
These aren't exactly estate agents - they are the owner of estate agency brands (Martin & Co being the largest one). This makes the world of difference to it, as an investment.
I really like TPFG, and owned it until earlier this year. It earns excellent returns (ROCE 22%), generates healthy cash flows and (in my view, deservedly) gets a Quality Rank of 97.
It reports today that April-May revenue was down 20%. Not bad.
Net cash has improved to £5.3 million, which includes the benefit of deferring some VAT.
It sounds like estate agents are making good progress in terms of getting back to normal.
And if there are business casualties in the broader industry, TPFG has indicated that it, and/or its franchisees, might be involved in some acquisitions.
There's not much else worth talking about from this statement, so I'll move on.
Westminster (LON:WSG)
- Share price: 10.81p (+0.6%)
- No. of shares: 160 million
- Market cap: £17 million
This group provides security services to governments, including in airports. The collapse of the aviation industry was presumably a factor in WSG's share price halving from Feb to March.
But the share price and operations are both doing OK now:
Notwithstanding the impact of COVID-19, trading for 2020 started on a positive note and this has continued throughout the first six months of the year. Since the start of the COVID-19 crisis, we have maintained full employment of all our staff and have remained extremely busy, even expanding parts of our business.
It sits outside my circle of competence and I do think it's important to be sceptical when a company has had as many false dawns as this one has.
That having been said, this is a really encouraging AGM statement.
United Carpets (LON:UCG)
- Share price: 3.25p (unch.)
- No. of shares: 81.4 million
- Market cap: £2.6 million
Trading Update and Change to Accounting Year End
This tiddler is still alive, but I'm not sure if it's kicking. Let's read on...
- stores are all open again
- early indications "encouraging", signs of pent-up demand
- negotiating a CBILS loan, which it sounds like it needs to get.
UCG pulls out the old "change the accounting year" trick, which lots of cunning FD's have used in the past.
The reason given? To put the entire Covid-19 mess into one long financial year.
There is another reason given, but I think it's just waffle.
My view - this share multi-bagged before, for investors with nerves of steel who held it through a pre-pack administration. I'm far more comfortable on the sidelines, and won't experience any regret if I see it rising like a phoenix from the ashes yet again.
I'm out of time for today but I do appreciate all your comments and suggestions. I'll read them again later this evening, and see if I can use them as the basis for tomorrow morning's report.
Have a great evening.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
Hi Timarr
Thats true there are vaccines and treatments but it still kills 650,000 and its an accepted risk. For covid surely there isnt any alternative to accepting the risk unless a future of lockdowns and all the implications of that become the norm. This debate could run of course, and is everywhere, but for me its all back to is the response in proportion and the excess death graph will be the one to watch over the coming months. Oh and resurgence too of course and a whole load more probably!
For covid surely there isnt any alternative to accepting the risk unless a future of lockdowns and all the implications of that become the norm
Can't agree with that.
Firstly we can only "accept the risk" when we know what it is. Unlike flu we don't - yet. Part of the reason for the lockdown and social distancing measures is to buy the time to figure that out, and clearly a lot of progress has been made but there's still much more to be done, particularly to figure out the long term impacts, which may well have implications that extend beyond the current high risk groups.
Secondly, there clearly are alternatives to lockdowns which countries are starting to operate now with phased measures while keeping social distancing measures in the place. Another full lockdown is unlikely, although if we get a winter spike along with a flu epidemic we may have to reinstate some measures.
Thirdly, we can already see progress on multiple fronts, We have the first therapeutic treatments which both reduce the amount of time people spend in intensive care and reduce mortality rates. We understand better - although far from perfectly - who the at risk groups are so we can get them to shield if there is a spike. We have widespread testing programs in place so we can rapidly identify people who have the virus - which is particularly important in hospital and care contexts. We now know that a third of the population can effectively work from home. All of these things will reduce the load on the NHS if we get another spike.
Fourthly, the underlying agrument here is that the economic damage is too great to allow another lockdown. That ignores the point that even if we hadn't locked down our economy would still have gone down the pan. Sweden didn't, has the highest (by far) mortaliy rate in the Nordics and now finds all borders closed. We're in a global economy, we can't just do what we want. As the US is about to find out.
Fifthly, most of the economic damage is already done. Most of the larger companies going under were in very poor states anyway and removing them will clear the way for better companies to grow and innovate. The move to online both for shopping and working has only been accelerated, it was an inevitable trend anyway. If it means less unnecessary commuting and more localism then good. Investors who are caught on the wrong side of this trade, at this point, have simply made a mistake. Those who've been waiting for a recovery in some of those zombie stocks will have learned a valuable lesson about mean regression.
Of course, things aren't perfect. I'd like to see a lot more direct support for smaller businesses without the banks intermediating. I'd like to see government investment in research programs that ensure that where highly skilled workers are losing their jobs - as with Rolls Royce for instance - that they have the opportunity to rapidly build new businesses. I'd like to see furlough schemes include mandatory training programs to build skills. We can do things better now we have more time to think.
But I don't think we'll see another lockdown and, if we do, I don't think it'll do much additional damage. The challenge now is to grow out of the coming recession and the best way of doing that is to invest in the future, not throw money into broken business models. And that's as true for private investors as is it for the government.
timarr
The inevitable has to be a change in behaviour for social distancing and hygine to slow the spread but more importantly a change in mentality that we have a new dangerous disease to go with all of lifes other risks. Ask and epidemiologist what to do to stop 650k deaths from the flu each year, lock everyone up.
Yes, if you want to focus on just the flu, but we don't do that, for obvious reasons. But of course the question is, would we have if epidemiologists were in charge...
We accept the risk and the inevitability that the flu may get you, especially if you are already very sick.
https://www.who.int/news-room/detail/14-12-2017-up-to-650-000-people-die-of-respiratory-diseases-linked-to-seasonal-flu-each-year
We accept the risk and the inevitability that the flu may get you, especially if you are already very sick.
True, but we have vaccines and treatments for flu and the risks and long term effects are well understood. None of that is currently true for Covid-19, our understanding of it is still in its infancy.
So, at the moment, no one can accept the risk because no one knows what it is.
timarr
888 Holdings (LON:888)
slightly odd significantly ahead of prior expectations update from 888 today, the tone of the news sort of suggests this good streak may/will not last - headwinds ahead doh. Hopefully they are just being suitably cautious about the future and/or they have a regulator they do not want to upset - its kinda like the news was drafted by lawyers in the knowledge the ceo would be put infront of a treasury select committee next week.
I agree Simoan,
‘People not working, kids not at school, mess’ . Bournemouth also reaffirms my view that i just dont believe the media & surveys where large % dont want to go to work, bars, restaurants until a virus is found etc etc. Today in spain it is 99% back to normal apart from some capacity/social distancing & mandatory masks in confined spaces but those are restriction on what people do when they are doing what they always have done.
If boris opens s up properly, without his whitehall chums & their silly rules the reopen trade will (yep predictions) roar. People haven’t changed overnight, Bournemouth shows that. There is a virus still but free choice needs to be given and people will go back to normal. People didnt stop smoking, having sex, drinking, sitting in the sun because of lung cancer, hiv, Cirrhosis, skin cancer etc etc.
People changed behaviour over time sure, but not a total reset. So Bournemouth to me says when leisure opens is highly likely it wont be empty in-spite of the all the silly little rules, given a chance.
People changed behaviour over time sure, but not a total reset. So Bournemouth to me says when leisure opens is highly likely it wont be empty in-spite of the all the silly little rules, given a chance.
This is not simply a first order equation - that reopening means a burst of economic activity. I think that's pretty obviously going to happen. The second order is crucial - if that burst of economic activity leads to a spike in cases and reimposition of tougher rules then the economic consequences for the leisure industry in particular will be devastating. For that to be avoided then we probably do need to see a change in behaviour.For what it's worth my friends in Bournemouth said that it was chaos - cars everywhere, hoards of people wandering about not socially distancing - but that the beaches themselves weren't too bad, people were taking reasonable care. That's obviously not a representative sample.
Personally, I still think the leisure and entertainment industries are uninvestable, but there's clearly good money to be made there if you can time your entry and exit well.
timarr
Of course most people will go back to normal given the slightest encouragment by the clown in Downing St, but so will an even larger increase in cases than we are already in line for.
From the leader of Bournemouth council on the influx of people to the area: “We are absolutely appalled at the scenes witnessed on our beaches, particularly at Bournemouth and Sandbanks, in the last 24-48 hours...The irresponsible behaviour and actions of so many people is just shocking and our services are stretched to the absolute hilt trying to keep everyone safe. We have had no choice now but to declare a major incident and initiate an emergency response.”
I would trust this account over the "false photo" narrative advocated in the above comments.
But, in a way, isn't this account just confirming that the "false photo" wasn't so false?
Indeed, the "false photo" is not false at all, but the comments on this subject above started with the claim that:
"I think you need to be careful what you read in newspapers. Some of those pictures looked at very convenient angles designed to foreshorten and give a possibly misleading picture. Not that newspapers would want to present a possibly misleading headline of course..."
a view which others seem to endorse.
Is that the same Liberal Democrat leader of Bournemouth Council currently under threat of a Vote of no confidence? I am sure her Motives are entirely honourable.
On United Carpets (LON:UCG) the glaring omission from the trading update is the performance of their new proposition - instalment payment channel - basically carpets on installment finance. The last trading update said that they're selling more carpets because of this prop, but its not profitable yet... and presume the current financial difficulties of many customers might mean lots of missed payments.
London Chamber of Commerce research:
47% expect Covid-19 to be affected their business for more than 6 months,
https://www.londonchamber.co.u...
timarrTimarr
Closing the office permanently seems a great idea - for those that have houses with office/study space that doesn't intrude on their domestic situation - partners, kids, use of the dining room table, etc. I think too many bosses will be looking at this from their own perspectives and not their staff's.
Lots of goodwill has been extended by staff and this is wearing very thin for many. There is a perception that this is the new normal and I believe that this is actually unsustainable. The intrusion of work life into home life and the 'always on' nature of screen based work could cause a lot of problems. And how do you train and develop new staff effectively? Especially at junior levels? Training camps? Stints in the office with line managers/trainers? It's going to be interesting.
And the knock on effects on communities that have historically depended on those workers to make a living could be devastating. Are there opportunities in all this?
Tandem (LON:TND)
"In bikes, the company is "working hard to restore supply chains as soon as possible".
Prompted an ironic smile from me !
...supply of chains...
Re £NXR - in my anecdotal observation, having spent so long at home, many people are using remainder of lock down for DIY and planning for home improvements (using lump sum cash saved from much cheaper / no holidays plus cashflow from not going out?) . Queues out B&Q and other DIY sheds have been long. Getting hold of builders is harder than ever.
In addition to consumer spending, the political wind is turning to 'build, build, build' as a strategy - I expect to see planning relaxations for new houses and redevelopments relaxed as well as Boris' infrastructure splurge. Also a lot of retail is going to be re-purposed. All of this is potentially good for £NXR in the UK. Unlike hospitality, DIY/building can catch up on lost consumption.
My biggest concern is South Africa - 30% of revenue and, as ever it seems, on the edge politically and economically
sady - not sure where you were during the big sell off but Next (LON:NXT) share price went from 7078 on Feb 21 to 3390 on April 3 and Games Workshop (LON:GAW) went from 7115 on Feb 21 to 3724 on March 19. Thos were pretty scary falls (I know, I was sweating).
Re Games Workshop (LON:GAW) - just look at the ROE, ROC and operating margins. If only more companies could come up with figures like those life would be a lot easier for investors.
And not a single adjustment to be found. Kicking myself for selling! Especially since my sale was just to move from one account to another, which later on wasn't necessary anyway.
STUPID ME!!
Graham, I listened to the Non-standard Finance (LON:NSF) online presentation today as well as reading its results. For my sins, this was once my largest position, having followed non-standard finance generally closely for years. I still hold NSF alongside £MCL. I would be interested in your thoughts on NSF and the non-standard sector that is completely beaten up right now.
My key takeout for Non-standard Finance (LON:NSF) was that its 3 underlying businesses are doing OK given the circumstances (ie very badly but better than I feared). All branches have re-opened, collections whilst well down have not dropped off a cliff and remote collection of doorstep lending is now reported as close to 100% - a big cost saving in the long run. Focus on collection means loan book size has dropped 9% but no new lending has meant cashflow being positive in April and May (although tiny new revenue and nearly all the historic cost base). Cash on hand is £60Mn but covenants breached and goodwill writedowns mean a long note about it being a ‘going concern’ on its base case but in trouble in a bad scenario.
A major equity raise is therefore almost certain unless a disposal is made. This option was raised as a question by an analyst but dismissed by the Chairman although he said he was going 'consult with shareholders' (although I doubt he means me!)
I did get to ask via a written question (great opportunity, thanks) if there would be an offer for small shareholders. The Chairman said he was 'mindful' of the many private shareholders on the register which I optimistically took to mean yes....and a further confirmation of an equity raise in prospect.
Note extra equity is also required to unlock the recently announced securitisation facility. The Chairman, van Kueffler, even concluded with a (super bullish !!!) comment on the positive opportunities in 2021 based on historic experience of recession and non-standard finance, concluding that the "larger the equity raise the more exciting the opportunity on offer" !
This was rich and a bit of a scary prospect as he has presided over massive destruction of goodwill over the p5yrs after overpaying for assets to get in the game !! Nevertheless, it is probably true. Non-listed competitors are going bust quickly and demand is increasing fast and will not be met by regular banks.
I continue to believe therefore that there is a big opportunity in non-standard finance for £NSF as so many who need/want to borrow cannot access banks. The unique 73 strong national branch network (Everyday Loans) which effectively offers a face-to-face debt management/ advice is a huge and valuable moat ii) Guarantor loans are a very good financial product (for some with only poor alternate choices) and brokers hated Amigo having a 80% share; so their troubles spell opportunity for no 2 NSF and iii) the home credit business was finally making a good return before Covid hit and many smaller providers will no doubt exit the market now
Despite everything therefore, I might support a Rights Issue but I worry about the company delisting. My concern is that the new largest shareholders, Alchemy Special Opportunities, who replaced Woodford are experienced distressed finance company PE operators. IMHO, this would be a perfect time to take the business private at low cost, recapitalise and refloat in happier times, 5 years from now at many times the multiple.
Any thoughts.
Your assessment is spot on, analyst pack slide deck, slides 30/31 I think tell the potential upside based on Provident history. Totally agree they need a small equity pump to unlock the agreed lending but this looks like a no brainer for Alchemy. Will continue to monitor.
Good morning
Why does Next and Games workshop have such a high share price .The share did not fall when we had the covid crisis.Games workshop I am familiar with its a small niche market. The Market is really small hardly anyone buys it. Similarly Next the quality of the clothing Like Marks are not very good. Sales have dropped over the years Why such a high price.
Does it mean Institutions own the shares or individuals which is why it did not come on the market when we had the covid crisis.
Why does Next and Games workshop have such a high share price .
Good reasonable question sady , not sure why you have the thumbs down (being honest i think we have a few phantom prolific thumbs downers on this site - so don't worry). Note you may not know this but you can give your own post a thumbs up if you want to remove the red.
Next (LON:NXT)
Ref next i would say the simple answer is the share is dwon frok pre covid levels materially. share price was bumbling along at the 7k level pre covid and is now at under 5k level - so it has lost 25% of its marekt capitilsation - if anything that seems a hefty discount if we take the vuiewpoint they won;t need to raise funds (unknown) and will be back to normal in a couple of years. Covid may help Next by removing opposition and allowing them to more aggressively reduce rents. Also there is a steady stream other other businesses that seem to be signing up as a next resellers , so if others are paying next a cut simply due to being desperate to sell their own goods - this bodes well for that segment of the next business.
Finally i think its sensible to presume that people will seek out quality companies to invest in when there is trouble and strife - next isnt without its issues (its debt) but there is no arguing that it is a very well run outfit with regard to the business financials and the like.
The other think to check with Next (LON:NXT) is how much of it's revenue and profit is now coming from the finance that it provides to people to buy their clothes.
I had to pick up a couple of things for the kids pre-Christmas last minute online, great offering and they were happy with the choices they could make, it was quick delivery, but I could not find a way to actually pay for it without taking the "interest free 30 days option" probably my IT skills, but then obviously it kicks into a heft rate at day 31 which how many people end up doing as I was ringing them up asking how on earth do I actually pay this?!?
For anyone following the Wirecard debacle they've just filed for insolvency:
https://www.finextra.com/newsa...
Utter mess.
timarr
"The supervisory institutions worked very hard and did their job, which we see today"
Olaf Scholz, German Finance Minister.
The general news media is on steroids with bad news sells, maybe they have no option as advertising revenues are falling. Either way tomorrow’s chip paper has never been more appropriate with the drivel they spout every day
One million new COVID-19 cases per week globally, and you think it's not newsworthy?
This graph isn't newsworthy?
IncredibleMosesLeroy
I like a good graph - i think everything contained in this graph is reasonably as to be expected.
Note although the US appears to show a spike in covid tests - this graph doesnt confirm there is actually an increase in cases. US are still ramping up the daily tests so the stats should now be "less understated" than was the case previously. We had a similar situation in this country for a while when the level of cases was going down but reported cases was still increasing. Note the daily deaths are well down from the peak in the us - this may be partly for other reasons but it does backup the fact that known reported cases is not the be all and end all and is probably one of the least reliable measures for spotting trends if it does not factor in cases not caught by testing.
Hi incrediblemosesleroy,
Yes that graph is newsworthy but the other 242 articles that day about outliers and ‘jackies personal tragedy’ are, i’d hazard a guess, to most people not useful.
It is of course newsworthy but the problem is that mainstream news media do not put anything into context or give you more granular data. Just a broad brush eyeball grabbing headlines.
Take it to the extreme. If (and I know this is impossible) the UK managed to test all 66.5m inhabitants tomorrow there would be a huge spike in cases (but no increase in excess deaths) or if they were able to test anybody with symptoms (raised temperature for example) tomorrow then cases would spike.
We need to be provided with much more data to be able to have an informed opinion about the cases, deaths etc.
The states does look like a disaster but I don't know whether that is because of more testing? I had read somewhere that they are testing more per head of population than anywhere else?
Kind regards
Michael
"I had read somewhere that they are testing more per head of population than anywhere else?"
You will have read this in reports of a speach by a certain Donald J Trump. It is ofcourse untrue, but we live in a post truth world now, where certain politicians make use of the fact that it doesn't matter if something is true or not. All they have to do is state something for a significant share of the population to believe it and never hear it refuted.
Here it is fact checked at the time:
https://www.bbc.co.uk/news/world-us-canada-52493073
Here are the current data on testing per capita:
https://www.statista.com/statistics/1104645/covid19-testing-rate-select-countries-worldwide/
Edit: this is the key quote from Trump: "We're now conducting well over 100,000 coronavirus tests per day. It's over 100,000 tests a day. And these are accurate tests, and they're moving rapidly, which is more than any other country in the world, both in terms of the raw number and also on a per capita basis, the most."
With that representation of statistics and quotations you could work for the media cmpeckham.
Take a BBC fact check relating to May 11th, match it with a cumulative view on June 24th and put in context of what appears to be a quote from not sure when about run rate testing.
Currently USA appear to be conducting 500,000 test per day. At May 11th USA were indeed conducting over 100,000 tests per day.
I could be wrong but the current daily run rate of testing will probably be the highest per capita in the world or not far off.
If you read the text from his speech on May 11th (you can view on white house website). His context was clearly about current run rate and presenting a positive outlook on direction of travel for testing. BBC choose to fact check run rate numbers against Cumulative numbers to support an anti Trump narrative which is fine as it makes for good click bait.
Post Truth World hey :)
I have no real perspective on Trump or the USA. I don't live there and have no wish to tell the American people who they can and cannot vote for but I am naturally sceptical about any emotion driven headline.
I will not assume to know what you have or have not read but please feel free to correct me if appropriate. Every day is a School day and I do get things wrong and am always eager to learn.
Hi Graham, I know Thursdays are a nightmare with a torrent of news (and today looks par for the course) - but if you have any energy left I'd really appreciate your thoughts on Premier Foods (LON:PFD) - looks like your sort of share(?) They had interims out yesterday and they looked very good. Sales and profit up, big increase in cash flow reducing debt and appears that they've sorted their pensions problem. It's on a very low PE (around 7) and consequently PEG is nice and low. Had a good bounce yesterday and looks like it could be a good hold for a while?
Norcros (LON:NXR)
Mildy positive update today , they are back up an running however alll an unknown how this year will pan out. mention of 10% reduncancies so one has to presume this is them being highly efficient or they dont expect to be back to previous trading anytime soon - might be a bit of both.
Main bad news is the confirmation of increase in pension deficit, when i say bad news it kinda should be expected news and i am happy that as ong as they are anything like decently profitible the pension defecit should be less of an issue going forward all other things remaining equal.
Note the ftse 100 is up over 10% from the 31/3/2020 year end date so i am guessing the defecit may not be as bad now. With the large swings in equities i think this one off adjustment can be ignored - although clearly negative equity returns will mean the copany needs to add to its current ongoing funding - at £3.3 mill per year currently contributions deffo manageable
The net deficit relating to our UK defined benefit pension scheme (as calculated under IAS 19R) has increased to £48.9m at 31 March 2020 from £31.6m at 31 March 2019, primarily as a result of the impact of COVID-19 on the financial markets and asset valuations.
£9 mill covid related covid w/off ref johnson tiles - looks like the right of use and plant values have decreased - so looks like some adjustments that arent particualrly material - albeit never nice to have any nbv pulled away for no reason - not sure if this could help with their tax or not - probably not.
ref the all important financing it seems like thye should have enough - but until we have an estimate of 2020 earnings AND get sepcific confrmation (i may havd missed if it was in there today?) - i am clueless as to the % chances that they will do a sneaky discounted rights issue. I think they are fine - but with covenants being waived i am guesing the bank want be using words of the title of the fasmous denis norden tv show.
I think my new plan of attack when any of my companies announce they are raising funds is to head straight over to you tube and watch some classic european it's a knockout ( or Jeux sans frontières to use the correct name) highlights to cheer myself up -(poor duggie from dunfermline in his penguin costume) - the town almost matching its 60's footballing exploits in europe when they made the cup winners cup semi finals they always had victory assured when they played an english team in europe.
Good afternoon. One broker who researches Norcros is forecasting earnings per share of 14p to March 2021 and 25p to March 2022. In its peak year to March 2019, sales were circa £330 million, EBITDA was circa £41 million , operating margin was 10.4% and EPS was 31.7p. Assuming debt at the current year end of £39 million remains constant, this implies net debt to EBITDA ratio of 1.4 to March 2021 falling to 1 in the following year which I feel is reasonably comfortable. If conditions do not improve over the remainder of this year and debt increases, then I suspect the directors would look to raise additional capital. I hope this is of some help.
If you have time I'd appreciate your view on N Brown results today Paul, market seems a bit undecided, thanks
Sorry, Graham not Paul
I counted at least five different UK placements last night after the market closed raising £838m. Easyjet (LON:EZJ) raised £419m at 703p; Unite (LON:UTG) raised £300m at 870p; Young & Co's Brewery (LON:YNGA) raised £85.5m between its two share classes, issuing the more liquid A shares at 1160p; Velocys (LON:VLS) raised £20m at 5p and Hostelworld (LON:HSW) raised £13.8m at 77.5p. Given the volume of issuance and the weakish markets this morning, may be it is not surprising that early doors three of these shares seem to be trading below last night's issue price.
Hi WimbledonS
Where do you see the placement information please?
John Scrolling through the RNSs - with a word search. Sorry not very sophisticated.
As well as scanning through the RNS's one could use "Highlight This" plugin to highlight the word placing is say yellow.
https://highlightthis.net/
It makes then easier to spot!
Regards
Michael
Can anyone point me in the direction to understand placements more? Who decides the price of the placement and why was Velocys (LON:VLS) placement at 5p when their share price was 3* that a week ago? Many thanks!
To be fair on Velocys (LON:VLS) (I hold) - it was at 5p a couple of weeks ago too. The only “news” that could have driven the stock up from 5p to 15p was the formal approval of the planning permission on 12 June for the Altalto Immingham site. This was not really news as the effective approval was announced on 20 May. So I don’t see any reason why the stock popped up to 15p. Velocys (LON:VLS) is a story stock, where its value is really anyone’s guess.
You ask how the placing price is decided - for a detailed answer you need to ask someone who has worked on a Equity Capital Markets (ECM) desk. I have not - but I have bought hundreds of stocks in placings over the years (mostly when I worked professionally in fund management).
In essence, for a growth company like Velocys (LON:VLS) which clearly will need further financing, I would expect (only guessing - no knowledge) the large institutional shareholders (or maybe prospective shareholders) to be in regular contact with the company and/or the NOMAD saying if you were going to raise more equity, we would be prepared to participate in line with our holding / increase our % holding/ invest £x million as the case may be.
When the company decides it actually wants to go ahead with a placing then the ECM desk can call these large investors who have already indicated an interest and bring them “over the wall” (make them insiders so they cannot trade) and clarify at what price they are prepared to buy.
Theerefore, once the deal will be able to be done with some “cornerstone” investors in place, the bank can announce the deal - that is why you hardly ever see a deal fail. Once the deal is announced, other investors will have a few hours to get their orders in before the book closes.
It is after that you get the “dark arts”. So if the Velocys (LON:VLS) book was oversubscribed and investors were scaled back, why did they issue at 5p (the bottom of the pre-announced range) and not at a higher price, which was clearly possible? The ECM desk will be talking to the company about the “quality” of the book - in other words which investors they see as potential long term holders and which they see as traders/speculators looking to make a quick turn. My suspicion (and it is no more than that) is in this case a number of the key cornerstone investors have refused to budge from 5p and so to maintain the “quality” of the book, the company (who will have the final say - not the ECM desk) has decided to issue at 5p.
All the above is from my general understanding of how placings work. I hope that is helpful. As stated I have no particular knowledge of this Velocys (LON:VLS) placement - nor have I ever worked on an ECM desk.
Thank you for that! I appreciate every word written!
So, if these "cornerstone investors have refused to budge from the 5p placement", does this show that a future takeover bid is extremely unlikely? I know these investors differ from anyone willing to take it over but are they on the same footing?
HS
I have not really thought about Velocys (LON:VLS) as a takeover target - it all seems a bit speculative at this stage.
I don’t think you can read anything into the placing price - other than th board decided to go ahead with a placing and therefore presumably there was no takeover in the wings that the board was aware of - at least at a suitable price.
Looking at the 3 major shareholders: Amati and Lansdowne Partners (as far as I am aware) do not have a history of taking over companies. I do not know the modus operandi of Ervington Investments (Abramovic).
If you are interested - you should look at if there are any strategic shareholders who come on to the register after the placing. Disclosures will need to be made in the coming days.
Obviously BP is interested enough to pay some money to get a look at the technology at Altalto Immingham - but I would imagine for them it is cheap change for them at the moment to see what is going on. I would not expect BP to be interested in/ or have the experience to manage high risk entrepreneurial technology companies.
Thank you for this knowledge! Velocys (LON:VLS) is the most interesting stock to be following at the moment. I just wish the volatility would slow down as my portfolio % change is swinging massively due to this one stock. A long term position for sure! :)
And there was also Stobart (LON:STOB) which not surprisingly did not go down very well - over 40% being left with the Underwriters!
My morning smallcap tweet: Part 2/2
Norcros (LON:NXR) N Brown (LON:BWNG) Westminster (LON:WSG) Northbridge Industrial Services (LON:NBI) Sumo (LON:SUMO) Next Fifteen Communications (LON:NFC) NMCN (LON:NMCN) Non-Standard Finance (LON:NSF)
Norcros (NXR) FY(Mar) U/L EPS down 11% on rev up 5%. Div slashed to 3.1p (8.4p). Current trading is gathering momentum and ahead of our COVID-19 operating scenario.
N Brown (BWNG) FY(Feb) bad as expected. Net debt £497m up 6% but fallento £448m in June improving liquidity headroom to £148.4m. Closed my short.
Westminster Group (WSG) AGM stmt - container screening operations in Ghana have been largely unaffected by covid. Follwing a trial Menzies Aviation is confident it can now offer Westminster solution to their global clients. Upbeat.
Northbridge Industrial Services (NBI) AGM stmt - guides H1 similar to prev H2. EBITDA-ttm (ex IFRS16) to Apr to £7.4m (£5.7m).
Sumo (SUMO) AGM stmt - recent trading comfortably in line with market expectations.
Next Fifteen Communications (NFC) guides modest H1 rev and profit growth. Overall trading remains consistent with last update.
nmcn (NMCN) AGM stmt. Apr-May workload over 75% of pre-covid expectations and continues to trade profitably.
Non Standard Finance (NSF) FY(Dec). Recent loan book level down 9%. Has slowly restarted lending. Expect that any tightening of credit by mainstream lenders will result in increased levels of demand for non-standard finance. Material uncertainty going concern stmt, negotiations with the lender have been positive and temporary relief has been provided until 29 June.
Can you do a piece on BATM advanced communications (BVC)? They have released good results today and share price has hit the 100p mark again. They are involved in producing Covid testing, antibodies and ventilators. Also involved in 5G.
Graham good to have you back. There has been some selling of Volvere (LON:VLE) recently. If you have any thoughts on this, it would be great to hear. Thanks.
Agreed, any comment on Volvere (LON:VLE) - Volvere - if you have thoughts would be welcome. Looks like some institutional selling today.
Hi Graham, any chance of a comment on Non-standard Finance (LON:NSF) who have issued results coupled with a covenant breach resulting in going concern issues.
Interesting results, good at an operational level (although some huge, well flagged adjustments) but clearly uncertainty as a result of breaching covenants on the new loan agreement. Collection rates are fairly strong post covid (better than I expected!) and strong cash generation as they are effectively in run off currenyly.
They have a waiver in place, albeit only till the end of the month, but given the underlying strength of the business I suspect the loan we just be reset at a higher interest rate, thus undoing the good work they did arranging the new loan a few months back. They do say they have the ability to repay in full so no major short term issue. Issue of equity possible but possibly only if the lender pulls the loan.
Big drop at open but recovered a bit now - large discount to ntav suggests value here, with opportunity for decent returns either from return to 'business as usual' or if they just run down the loan book - just need to get through the next week or so........
Non-Standard Finance (LON:NSF)
An interesting one. With gross borrowings of £345m and market cap £36m certainly the bond holders are in the drivers seat here. They talk about being cash generative but they are running down their book.
"Group generated net cash after all expenses of £7.4m in April and £17.2m in May "
But since March the book has shrunk by £35m ? (my calc off the slides) which can be a problem given the debt remains at the same level.
As flagged, an equity raise may be required. But given the market cap is so low, how can they raise a meaningful number?
Good morning Graham. Something a little different.
China New Energy PLC (CNEL). The notification for the move to HKex, is 15th July 2020.
They show good financials. What's the implication's for Share holders 1) Prior to move? 2) Potential benefits after the move? 3) What if the move fails??
We would be interested in your thoughts,
Morning Graham
Good to have you back. Cenkos Securities (LON:CNKS) and Northbridge Industrial Services (LON:NBI) released positive trading statements this morning and in my view are under appreciated. Both have potential for significant re-ratings, subject to the pandemic stabilising. Views on either would be appreciated. I hold.
All the best.
Anpario (LON:ANP) did not offer any numbers this morning, but fellow readers might be able to figure out the direction of earnings from the following in the AGM statement:
"delivered a strong sales performance and a corresponding improvement in our profit margins in the first half"
Nice AGM statement from ANP this morning. They brought out a new product in April Credence: An effective surface disinfectant offering protection against viruses, including Coronavirus. Also made a donation to NHS and sourced some masks through contacts in China to help our government. I first invested when they were called Kiotech. Used to trade between 2.5-4p but then did a consolidation of shares 1 for ten to get out of penny share trap. Progress has been slow but sure. Be interested on your financial thoughts Graham if you get time or another day perhaps. Results September I think. Cheers
Simon - pretty sure ANP only have licence to sell Credence for agricultural purposes. I am also long term investor in ANP and like the way it is going. Very pleased that they are supporting local NHS and Care Homes, made me proud to be a shareholder. Graham's view much appreciated if he has the time.
good morning Graham,
can you please cover your research and technical view on Sylvania Platinum Limited.
thank you
J B
JB - your first post - welcome.
To help you find your way around I would mention that Graham and Paul do not generally cover hole in the ground stocks or ones that have not issued a recent statement. However if you go to the Stock report on Sylvania Platinum (LON:SLP) and click the 'Discuss' button (above the graph) you will find a recent article by Jack Brumby
Thanks for that sharw
I’d second for a look at N Brown if poss
Good morning Graham. I would be interested in your thoughts on Bushveld Minerals (BMN).
Sorry, I don't do resources! G
Hi Graham if there is time maybe you could look at £XPS - a consulting firm in actuarial stuff etc
My morning smallcap tweet: Part 1/2
Transense Technologies (LON:TRT) Kape Technologies (LON:KAPE) Hertsford Capital (LON:OTAQ) Victoria (LON:VCP) Maestrano (LON:MNO) Velocys (LON:VLS) Spectra Systems (LON:SPSY) Property Franchise (LON:TPFG) Tandem (LON:TND) Wilmington (LON:WIL) NAHL (LON:NAH) Eden Research (LON:EDEN) £CKNBS United Carpets (LON:UCG)
Transense Technologies (TRT) sells iTrack operating business to Bridgestone for $1m. Grants it a 10 year license. Leaves 2 businesses. Trading in line, don't expect covid hit.
Kape Technologies (KAPE) launches Intego's endpoint security solution for Windows. It's already on Mac. Also launches privacy browser extension for Chrome, Firefox, and Edge. Doesn't say how that it monetised.
OTAQ (OTAQ) new name for Hertsford Capital.
Victoria (VCP) every geography has exceeded management expectations following the re-start of operations. Last 3 weeks rev 85% of management's pre-Covid-19 budget. £200m cash and undrawn credit.
Maestrano (MNO) selected for a fully funded trial of its automated rail corridor gauging technology for Network Rail. Gauging is mapping the clear gap at the side of tracks. I didn't know that.
Velocys (VLS) £20m 2x oversubscribed placing at 5p, a 563% discount. It ran an ABB last night at 5 to 7p, so why accept the min price of demand was good? £1m OO for holders.
Spectra Systems (SPSY) bought back 225k at 122.5p. SP rose 6p to this level yesterday. I hold.
Property Franchise Group (TPFG) AGM stmt. - No noticeable impact on rent arrears fro covid. Co remained cash generative. May start divs but looking for acquisitions.
Tandem (TND) AGM stmt. Rev in last 25 weeks up 7%. Cycles c. 72% ahead but now a shortage of supply. "As the Company has been unable to meet with shareholders at the AGM we will be holding an investor day in Sept." Co refused to stream or videoconference AGM, claiming it was impractical. BS.
Wilmington (WIL) FY rev and profits will be towards the top end of prev guided ranges. Co would remain within existing facility limits albeit with limited headroom in October under the most pessimistic scenarios. Banks play ball on covenants and extra facility.
NAHL Group (NAH) AGM stmt - trading broadly in line with mgmt early scenario planning. Personal Injury and Residential Property still at only half of pre-covid. Co does not anticipate the need for further bank funding.
Eden Research (EDEN) granted two important patents in USA. A cereal (geddit?) dissapointer. I'm short.
Cenkos (CKNBS) AGM stmt - rev up in first 5 months, cost bas significantly lower with main benefit in H2.
United Carpets (UCG) negotiating covid loan to have sufficient liquidity to meet its requirements. Extends FY from Mar to Sept.
The Cenkos Securities (LON:CNKS) and N Brown (LON:BWNG) updates (results in the latter case) are interesting, may be worthy of a look. Both companies seem to be coping well with the current situation - better than well, perhaps.
On the larger cap side Auto Trader (LON:AUTO) have provided results - mostly historic but the interesting bit is on current trading:
In the first three weeks of June we have seen record levels of audience, with cross platform visits up 28% on the same period last year
This corresponds to what friends in the industry are seeing - very high levels of demand, particularly for low end vehicles, since lockdown. Be interesting to see if that's temporary as we see job losses bite.
And as we can see from the front pages of today's papers, for many social distancing is so last week ...
timarr
And as we can see from the front pages of today's papers, for many social distancing is so last week ...
I think you need to be careful what you read in newspapers. Some of those pictures looked at very convenient angles designed to foreshorten and give a possibly misleading picture. Not that newspapers would want to present a possibly misleading headline of course...
I was up on the North Norfolk coast yesterday. It was busy but everyone I saw seemed to be social distancing and mindful of other people. Mind you it's not difficult on the stretch of beach from Wells to Holkham at low tide, you could lose a small town on it :-)
All the best, Si
Yes, there are a lot of “fake photos” being used. Pictures taken from a distance with a telephoto lens to produce maximum foreshortening. They give a very misleading impression. The photographers know exactly what they are doing.
But because so many people have become addicted to being angry the photos and accompanying articles get lots of clicks, which is what matters to the publishers.
...whereas where I am (Northern Ireland) most people seem to be in their own little inconsiderate world and oblivious of social distancing measures or making any attempt to avoid other people's 2m space :-(
I'm happy to report it's an idyllic day on the Thames Path near Sonning and the few people I met on my walk this morning were perfectly considerate.
Perhaps Paul could tell us whether Bournemouth beach really was as crowded yesterday as the headline photograph on the BBC News website suggests! If so all this stuff about social distancing in pub, restaurants and worst of all in a family members home (taking your own chair, cutlery, not using the toilet, social distancing, etc) is just so much nonsense (to put it politely!). Also how are all these restrictions at all consistent with people being able to stay overnight at another persons property. It just doesn't add up and most of the population will find the various restrictions difficult to understand and impossible to implement in their daily lives - consequently they will just ignore it! No wonder legislation not introduced and the police will not be enforcing! I cannot see how the hospitality industry (cafes, restaurants, pubs, etc.) can return to normal even post July 4th. There is a lot worse to come I fear with major damage to UK stock prices.
Perhaps Best Of The Best (LON:BOTB) will change from 'Spot the ball' to 'Spot Paul'
(Bournemouth Beach yesterday)
Expect it will become more and more difficult to get people to want to go back to work as long as:
Effectively no schools
Weather better than Ibiza
Being paid 80% of regular pay to go to the beach
FWIW - we have a young schoolteacher visiting us today. She's been working for the past 13 weeks, is happy to do so, would be happy to do extra days and says that goes for the vast majority of other teachers in her school. The main thing holding the other teachers back is if they have children of their own who are unable to go to school full time (go figure).
Hi Si
I think you need to be careful what you read in newspapers. Some of those pictures looked at very convenient angles designed to foreshorten and give a possibly misleading picture. Not that newspapers would want to present a possibly misleading headline of course...
Well, it was a bit tongue in cheek, but we now have a major incident declared at Bournemouth. Bit easier to get to than North Norfolk, I'd observe ...
timarr
What I always think when I see photos like that is , 'Who on earth would want to be there?'.
Well, it was a bit tongue in cheek, but we now have a major incident declared at Bournemouth.
Yes, I heard that, however my point remains that the newspaper photos were taken in a way to make the situation look far worse than reality using foreshortening. I have seen other photos from higher viewpoints where it looks nothing like as bad, although still more crowded than most non-cretins would be comfortable with.
What is far worse IMO is just the sheer number of people not working and kids not in school on a Tuesday. Seeing it myself in Wells really brought home how screwed up things are.
All the best, Si
Hi Si,
Interesting I'm in Norfolk also semi retired went to Sea Palling as closer for me than Wells car parks were 90% full early doors way above the norm beach was busy but enough space to social distance.
Lots of youngsters in large groups not bothering though and i will say you get a better class of punter at Wells.
Agreed the normal thought that it wouldn't be to busy as people working and kids at school well off the mark. Would have been interesting to see how much more things peaked people wise if the weekend was in line with last few days but it looks like british weather will get Boris out of jail for the short term.
Regards Andy
And as we can see from the front pages of today's papers, for many social distancing is so last week ...
Yes and no and not what op was referring to really:
I went in to the office for the first time yesterday (bristol). the commute was 30m rather than 1h.
The SHE team had been busy. On the main floor lots of tape showing the one-way paths you can follow and only enter through one door and only exit through another. My smaller area downstairs has a big sign on the door saying entrance only. As the fire doors are alarmed, there are no designated exits. Hummed an Eagles song.
A - things do not change
The aircon engineer was in as was the PAT tester. They managed to switch off some PCs what colleagues were remote connecting to (that and I ran out of A3 paper and laptop had some serious downloads to process and car needed an MOT and oh wanted to go shopping was the reason for being there). Their lives have not changed and they were not overly fussed abuout distancing.
B - Things have changed
The capacity was ~55 when all hot desks are used. There are stickers on the destks that need to be empty. Capacity is now ~18 - about 30-40%.
To properly open the office we need a min of fire warden, first aider, manager and office manager. I may end up wearing 4 hats.
There will not be any hot desks. How that will work I have no idea yet. Some people have DSE needs - like special chairs. Not sure how that will work.
The reason I liked being in an office was that I could see the 6-10 people I work with and walk over and talk to them rather than schedule a teams meeting.
If they are not there, there is little point in me being physically in the office. If office capacity is 18 this is only going to happen by special arrangement once a quarter.
Getting to the point:
Until there is a generally available vaccine and everything really is back to normal, things will not be back to normal.
Specifically, the footfall in city centres like bristol will continue to be very reduced and that is not likely to change.
Not least as almost all of the take aways are shuttered.
Even if the office is opened, as the people who tended to gather for a 'quick one' / go to lunch together are unlikely to be in on the same day, they wont go at all.
If there are not many people around in the day, there will be not many people going to the re-opening bars in the evening - never mind restrictions on entry due to social distancing.
TL;DR;
City centre businesses that rely on commuters as customers may re-open but I am not sure enough commuters will be there