Small Cap Value Report (Wed 13 March 2019) - THAL/LSR, BUR, SOM, FRAN

Good morning!
Today, after the introductory comment on Thalassa Holdings (LON:THAL) / Local Shopping REIT (LON:LSR), we have:
- Burford Capital (LON:BUR)
- Somero Enterprises Inc (LON:SOM)
- Franchise Brands (LON:FRAN)
Thalassa Holdings (LON:THAL)
- Share price: 81p (unch.)
- No. of shares: 17.6 million
- Market cap: £14 million
You could be forgiven for not knowing much about Thalassa. It's a small investment vehicle with a chequered history in terms of its track record and corporate governance.
I have written about it quite a bit, both here and elsewhere.
What's interesting about it at the moment is that it owns over 25% of Local Shopping REIT (LON:LSR), and has blocked, at least temporarily, that company's plans to liquidate. Almost all LSR shareholders, except for Thalassa, wanted to liquidate when it was put to a vote.
Instead, Thalassa wants to take over LSR and has offered its fellow LSR shareholders a mixture of cash and THAL shares.
Well, this has led to a war of words. The LSR Board has hit back at Thalassa's offer document, writing up a comprehensive analysis of Thalassa's corporate governance failings and explaining why LSR shareholders should reject the deal.
In my opinion, the LSR directors have done a good job of handling this situation so far. From an ethical point of view, I hope that that they succeed in fighting off Thalassa and finding a way to liquidate.
If you're interested to see what happens when Boards of Directors of small companies go to war, this is a fine case study.
Here are the links to the respective circulars:
Burford Capital (LON:BUR)
- Share price: 1914p (+5%)
- No. of shares: 219 million
- Market cap: £4.2 billion
Not a small-cap but a well-followed share among readers. It has been a big winner so far - well done to holders.
It is a litigation finance house, financing lawsuits and owning parts of the claims. It also manages 3rd party funds, collecting investment management fees.
Here is the growth profile for income to 2018, most of which is converted to net income. Total income, operating profit and net income are all up by around 23-24% in today's results.
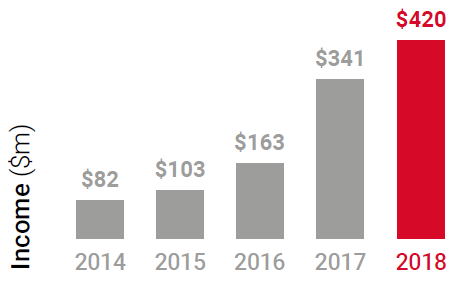
The lion's share (over 90%) of the above derives from investment income.
Most income is unrealised each year, i.e. based on changes in the perceived value of Burford's assets.
Diversification has improved from 20 to 26 investments contributing to performance - I will need to check what the biggest ones are worth.
The company reports ROE of 30%, a decline from 37% in 2017, resulting from the increase in net assets.
Evolution - Burford is branching out from "core litigation finance". It describes itself as "the legal industry's investment bank", and needs to cater to more of its clients' needs than just the most lucrative deals.
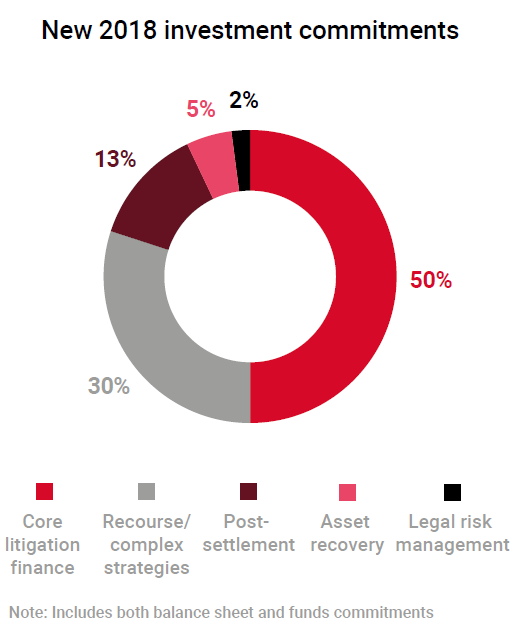
I'm excited by the discussion of Burford becoming a "specialty finance company", rather than just a litigation funder. It sees itself as the investment bank for law, providing a wide range of related services to clients.
Some of these will be less profitable than "core litigation finance", but they will help Burford to become a one-stop shop for its clients and strengthen its competitive position.
Volatility - the company warns that earnings volatility is likely, and that some shareholders may have become complacent after several good years. Great that they are managing expectations in this way.
Competition - why hasn't Burford suffered from increased competition in the space?
The company answers this head on by saying that it has always battled against competition, and has outperformed them.
And it says that the scale it has achieved makes it very difficult for others to compete with it now, as it enjoys economies of scale (see above).
It mentions IMF Bentham as a listed competitor. It has 16 lawyers compared to 55 at Burford. It has net assets of AUD $368 million.
There are private competitors too. They are generally much smaller, lacking the access to the capital markets that Burford enjoys.
Burford says that it rarely loses an attractive deal to the competition.
There is also the point that law is a closed shop, so that margins can remain robust for this kind of activity. (I sort of feel the same way about traditional fund managers - it's not easy to set up without a lot of capital to start with and regulatory approval).
My view
I feel like I've only read about one fifth of the report, but I need to write up some initial thoughts!
If you read the archives, you'll see that my views on litigation finance and Burford have evolved from scepticism to gradual acceptance.
The main things that bothered me about it before were that 1) litigation finance in this format was still very new, 2) Burford's wins seemed too heavily weighted towards a few large successful cases, 3) its valuation.
Based on its track record, exceptionally clear reporting style, the evidence it has shown that litigation finance is widely accepted, and its diversification into different types of activities, I think the first objection is no longer valid.
Diversification also seems to have improved a lot, helping me to look past objection number 2.
All that leaves is the question of valuation. Net assets are $1.36 billion at December 2018 (about £1 billion). So it's trading at about 4.2x book value.
When I looked at it a year ago, it was trading at 5x book value.
The way that I value companies like this is I relate their long-term return on equity to a "fair" book value.
If Burford continues earning ROE in the region of 30%, for a considerable period of time, then it is certainly worth at least 4x book value today.
I might have to capitulate and add this to my portfolio! I will look at it some more.
Somero Enterprises Inc (LON:SOM)
- Share price: 382.5p (+2%)
- No. of shares: 56 million
- Market cap: £215 million
Good numbers from the US-based Somero for 2018.
- revenue +10% to $94 million
- PBT +13% to $29 million
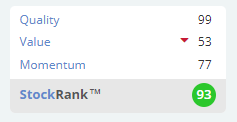
This is a high-margin, high ROCE business with a Quality Rank of 99 according to Stocko.
As we have discussed before, its concrete screeding (flattening) equipment enjoys an apparent lack of competition.
Its long-standing CEO has treated shareholders well with plenty of dividends while also keeping a safe and secure balance sheet.
Capex has been modest over the years, e.g. $2 million in 2017, and then just $800k in 2018. This helps to explain how it generates such high returns and free cash flow.
It has managed to grow and innovate despite the higher free cash flow generation, and this looks set to continue. Since the start of 2019, it has made a $2 million (plus bonuses) bolt-on acquisition, and launched a fresh product.
Outlook - more profitable growth.
My view - no change to my stance on this. It's a very good business with a few specific risks and challenges that we've discussed before.
Somero's Chinese sales fell slightly in 2018, consistent with my view that the Chinese are reluctant buyers of these types of products from a US manufacturer. I don't see why this should change.
Overall, it's a great performer. I'd even consider breaking my rule about avoiding foreign shares for it. It looks like it could fit nicely within a diversified, high-StockRank portfolio.
Franchise Brands (LON:FRAN)
- Share price: 73.5p (+8%)
- No. of shares: 77.5 million
- Market cap: £60 million
Franchise Brands plc (AIM: FRAN), an international multi-brand franchisor, is pleased to announce its full year audited results for the year ended 31 December 2018.
The 2017 numbers aren't directly comparable, as there was a big acquisition in April 2017.
On a pro-forma basis, the aquired company - Metro Rod, a provider of drain clearance and maintenance - did well, growing system sales by 10%.
System sales means sales to customers. This doesn’t correspond to FRAN revenues, because of the franchise system.
The mood at the other brands sounds less upbeat:
ChipsAway, Ovenclean and Barking Mad have all suffered a slow-down in relation to franchisee recruitment, due to the external environment.
This is confirmed by the small or negative percentage changes in EBITDA at these other brands:
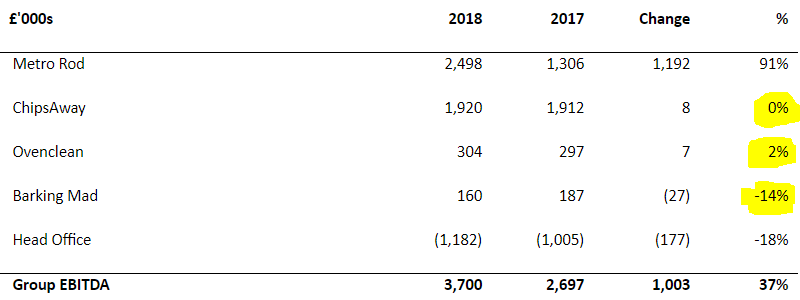
On a pro-forma basis, if it had been owned for the entire year in 2017, EBITDA growth at Metro Road would have been 38%.
Outlook - much more positive than the 2018 commentary, the outlook statement says that 2019 has started "encouragingly". Franchise enquires are said to be up significantly at ChipsAway, Ovenclean and Barking Mad.
My view - I have a positive impression of this group, but am leaning toward the view that it is fully valued.
I have run out of time, not helped by losing half of my Burford article this morning and needing to rewrite it. Sorry about that.
Paul is back tomorrow.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
morning Graham,
either yourself or Paul recently mentioned a small cap in the same line as EPO. I had a look at the time, but thought I'd take another look given today's purchase of worldpay by Fidelity National.
I've had a look through the small cap reports, but cannot find any reference...... can you remind me of the company name.
Many thanks and keep up the great work
Is this a Somero knock off ?
https://sdfuruide.en.made-in-china.com/product/iKHmVLqhhzro/China-Factory-Supply-Concrete-Laser-Screed-FJZP-200-.html
It's good to hear that Burford is in good shape. The interest payments on my 2026 bond look very secure!
However I would draw readers to the excellent results announce by Somero Enterprises reported this morning. Cash generated from this US based business is very high, hence the large and expanding dividend. The final dividend announced (including supplementary) amounts to around 19p/share (approx 5%) which will be paid to shareholders in late April.
Capex is low because the Company is an assembler of bought in parts from third party suppliers, hence very high ROCE figures.
The high margin generated in the business results from their innovative customer led machine designs and great customer service. They have recently embarked on developing machines for use in high rise buildings, where their "flat floor" technology may be exploitable.
I would surmise that the undemanding PE ratio (which belies its financial record) and relates to the fact that Somero is in the construction industry.
Would you agree that their moat comes from :
-customer service
-Innovative design and methods of assembly?
I am worried these moat features are easily eroded by a competitor in the long run. (some firm which does the same activity of assembling parts from third parties)
I believe they have also established patents covering the designs/operating features they have developed. They launch new products with enhanced features on a regular basis.
No moat is a stronghold forever!
SM
The results from SafeCharge International (LON:SCH) today (I hold) seem to underline a continuing problem in their industry; spectacular growth in mobile payments processing offset almost completely by a decline in margin available.
At various levels SafeCharge International (LON:SCH), Bango (LON:BGO), Boku Inc (LON:BOKU), Mi-Pay (LON:MPAY) seem to all demonstrate the difficulty of getting a return while they all try to get market share. Eventually there will be a winner or two but things could get ugly quickly if payment growth declines
First, Full marks and many thanks to Graham for doing the hard graunch of re-writing a lost post. Nothing more frustrating! So, much appreciated.
Burford was a small cap to start with. We are all interested in small caps, particularly when they grow to be mid or large caps.So please keep reporting on them. It's why we invest after all.
Invesco has been a seller for well over a year. Does anyone know why? Perhaps they are just re-balancing. I think they had nearly 30% at one time. So half the holding - roughly £600m - has been seamlessly absorbed by the market.
I love their conservative, lucid, literate annual reports. What else would you expect with an ex-Treasury Chairman?
Quick take on Burford Capital (LON:BUR) -
Understanding the opportunity and why its so potent:
1) IMO the most informative way to think of Burford is as a specialist fundamentally driven event driven hedge fund. I say fundamental to exclude shorter term arbitrage and M&A type event vehicles and compare more to distressed and 'special situations' type investments that often have a heavy legal element to the position taking (and why their is an opportunity for specialist investment vehicles as opposed to ordinary asset managers that run away)
2) But its even better than (1) above as this is the first 'hedge fund' to find the right way to operate in this space by starting with a legal origination, screening and winnowing process. As it is the legal that unlocks the financial event this so much more optimal than the usual approach of starting with financial and newsflow screening and then back ending some legal analysis in to verify the catalyst for financial upside.
3) Effectiveness at exploiting the available opportunity has been demonstrated by past results. There is no reasonable reason to think that these results are not systemic the opportunity set and how Burford exploits it. The only two valid reasons to think that returns could wilt significantly are i) regulatory intervention or ii) economic catastrophe in US and west. Risk (i) is barely plausible as it would be a volte face to our system of government and law...so think political revolution sweeping away current norms....although this could happen in an evolutionary way for a variety of reasons. Risk (ii) is possible but you've got bigger problems to manage than your capital loss on Burford (probably 100% as they wont be able to pay back debt nor roll over). If this risk is your fear probably best stick away from stock market and horde gold etc.
Note, I don't think comparisons to an investment bank are right. They would need to create their own funding capability for that so hedge fund is better. Hedge fund run by old IB traders blow up all the time as they seem unable to realise that they no longer have infinite access to capital to chase down their investment ideas. This is why LTCM went pop and virtually every major hedge fund explosion.
2018 results:
4) The results were ahead of expectations (a tricky concept for Burford as company provides no forecasts and brokers don't know how to forecast it). Nevertheless, its looks like a big beat and multiple comes down to low double digits. This seems remarkably cheap for what is effectively a pool of capital that has proven highly able to make high returns that has a quantum of capital at risk currently that will probably generate very high future returns (that are very hard to imagine disappear any time soon barring political revolution or economic disaster).
But the reaction to results disappointing. Why?:
5) The results and call make it clear that Burford want more capital to go pursue opportunities. They cannot predict timing of cash flows from current cases. From a planning perspective they lack even enough cash at end of 2018 to take up their (very lucrative) share of the SWF partnership announced late last year...its lucrative as for their c.$330m capital commitment they get upside they would get from c.$600m of balance sheet capital!!!
6) So funding is a problem....but in a spectacularly good way.
7) 100% speculation but Invesco have a big inherited position from Woodford and I suspect they are sellers. Perhaps they sold a chunk today into good news and price performance earlier today (when up at £20 area). More generally there's a lot of people who have made a tidy sum from Burford but probably find it hard to appreciate and analyse. In many respects it looks risky as its not a simple widget company or even a bank/lender (its an event driven hedge fund listed on AIM!).
8) The recent high funding needs and significant raises for funds leave some thinking that Burford has growth trouble and an under appreciation of how a significant proportion the cash generation is back ended and comes as a 'surprise' 2-4 years after funds are committed
9) They have committed to a high proportion of single cases after last year trumpeting the relative safety and predictability of portfolio cases. They reported this positively as it indicates growth in new client relationships with legal firms (single cases are the entry level product) but based on last year comment that means their failure rate with cases is a little higher. Note this is balanced by growth in asset recovery business which has protected downside.
My conclusion: Significant upside from both earnings and probability of multiple re-rating. I think they should raise equity again and that shareholders should see that as a good thing as its increases return to them.
That's an excellent summary Mojo on Burford Capital (LON:BUR), thank you. There is not much to add, but I think a possible point (10) or an addition to your point (7) is that the founders' lock-up period for disposing shares is up very shortly. They sold a fair chunk just after the full year results last year; the sale was 20/21 March 2018 and they committed not to sell anymore for 360 days (that deadline must be imminent).
It is possible that they are lining up to sell a further tranche (they still hold over 8% of the company) and the City has caught a wiff of this, hence the fall in the afternoon. Pure speculation on my part, but it seems one possibility. Anyway, I guess we will see in due course.
Off topic but Mike Ashley just upped his stake from 25.75% to 28.43% of GAME Digital (LON:GMD). I noticed the big trades on Monday and took the opportunity to buy some more but was very surprised to read today that it was him.
https://www.investegate.co.uk/game-digital-plc--gmd-/rns/holding-s--in-company/201903131628467949S/
I cannot fathom why unless he's lining up a bid. Anyone else got any thoughts on this?
cheers
Francis
Re Burford Capital (LON:BUR), earlier this afternoon, I sent an email to the CFO contrasting the presentation of EPS in last year's results (front and central) to today's results (not in the RNS and first detailed at p65 of the AR), requesting an explanation for the change in approach.
Rather impressively I received a reply within 40 minutes, The part of the email which relates to EPS reads as follows:
"Your point about EPS is a fair one. We did not include EPS this year because the EPS figures shown in our IFRS statements include non-Burford third party interest noise. Perhaps what we should do going forward is include an EPS line in our reconciliation table (page 51 of our annual report) and then we can have a bullet in the highlights section on EPS. As we have done in our history, we incorporate comments just like yours into our reports going forward to make them more fulsome for our investors so many thanks for your comments here.
An apples to apples comparison of EPS this year to last year (just on Burford only income) would have shown: 2018 at $1.56 EPS vs 2017 at $1.27 EPS, so an increase of 22%."
2018 profit after tax: $327.971 million
Average shares outstanding: 210,776,771 (this figure comes from Note 26)
2018 EPS = $1.56
2017 profit after tax: $264.845 million
Average shares outstanding: 208,237,979
2017 EPS = $1.27"
Hope this is of interest.
Regards, Martin
Yes, Burford Capital (LON:BUR) were very specific that there is currently a shortfall of investment capital in their competitive space.
On the topic of Burford Capital (LON:BUR)
There is a growing and accepted view within legal circles that there is an excess of litigation funding vs the potential available cases. A lot of privately funded competition has entered the fray in very recent times. I know a lawyer working on a specifically funded case now and he was telling me about how a lot of lawyers are actually starting to move away from this area as they simply cannot find the cases. Whilst Burford Capital (LON:BUR) clearly has a first mover advantage, they will undoubtedly be facing competition for the best cases against well funded (PE backed) competition. This has to have a long term impact on them and possibly explains the much heralded diversification.
In the interest of full disclosure I chalked this one up as one of my most disastrous 'looked at and liked but never bought' stocks. I spent ages working on it in 2014 and just never pulled the trigger as I was waiting for a bit of weakness to buy in. So all of the above could well be classed as just trying to make myself feel better. Nevertheless, well done to all the long term holders!
Burford Capital (LON:BUR) hawkipa said "There is a growing and accepted view within legal circles that there is an excess of litigation funding vs the potential available cases."
That's at odds with what Bur say and have been saying for some time. In their annual report they say
"Our “market” is really three areas of legal activity, each of significant size
Each area dwarfs the supply of capital available
We believe we are at an early stage of total"
market penetration"
I'm not at all clear there is a growing and accepted view that there are not enough potential cases. In fact BUR say they were offered 1470 new opportunities to invest last year from which they chose to invest in 87.
If there really was an excess of capital chasing investable business, why did BUR feel the need to raise $1.6bn of additional finance last year?
Just listened to the questions at the end of the Burford Capital (LON:BUR) Conference call where the point about possible litigation finance oversupply was raised. To paraphrase - Burford is not offering a commodity product and there has been no weakness in their pricing power. They believe that there is ample room in the market for the available capital, because it is a growth industry with a lot of opportunities.
Impressive and this from a company who has been able to be very selective with the cases they take on.
I don't doubt what they state, but that is at odds with a practitioner within that specific field, who is working on a funded case right now and is also seeking new profitable opportunities.
So, whilst a holder might choose to discard what he thinks from his vantage point, it is still the kind of information that I would want to know of if I were invested.
Plus, a bear case might be that the quality of cases they are seeing is deteriorating as evidenced by the number they have to sift through.
Anyway, I was only trying to pass on some information I though investors would benefit from knowing.
Hi Hawkipa. Is the practitioner you know talking corporate only or personal? If the latter then I can believe that is a saturated market.
The comment seems at odds with the facts from a non-individual sense as the key providers of capital are known (and Burford Capital (LON:BUR) summarise) and their balance sheets are relatively small compared the US and global scale of litigation fees (I don't know exactly the figure but low single digit percentages and not much above 1%).
It also seems highly unlikely that the highly competitive but low available funding capital legal partnerships that access Burford funding nor their clients that have cases that can be profitable (financially, protection of status and image) but hard to fund for a variety of reasons (both dollar size and how it calls on business capital) will pass on by Burford funding given that it has only upside for them compared to doing nothing. Legal partnerships that make the jump are likely to cement their relationship with Burford as partners monetise their expertise.
Hi Mojomogoz. He's a former magic circle operator now solely focused on litigation funding and his current work is a claim funded by a major HF. His firm is also active in the financing of claims and as a result knows and understands the deal flow. A lot of opportunities are out there, butfrom a legal view are deteriorating in quality.
Without the benefit of knowing Burford Capital (LON:BUR) well, I understand from him that the big easy cases ie Repsol are now in the past and the pool of litigation opportunities is smaller than it was (no idea what quantum that is). In addition a lot of major global HFs and bank desks who have had considerable success in the past realise the value of non-correlated asset plays and therefore are keen to see opportunities. So, if say Elliot or Oaktree know of a 'good' opportunity they have the scale, scope and relationships plus the skills to take it on.
I asked him about Litigation Capital Management (LON:LIT) and he talked about the big hitter Nick somebody, who was a Burford founder and he pointed out that his previous endeavour Chancery Capital had clearly failed.
The upshot is that those operating within the field are concerned about the size of excess capital vs the opportunity set.
Like I say, no view of my own, no position in it, just thought it is the kind of thing I would want to hear as a holder. I appreciate your open minded and constructive response, clearly backed up with an informed view. Its exactly why I value this forum so highly, and want to add value to the discussion if I have something I think is of interest to others.
Regards,
Like I say, no view of my own, no position in it, just thought it is the kind of thing I would want to hear as a holder. I appreciate your open minded and constructive response, clearly backed up with an informed view. Its exactly why I value this forum so highly, and want to add value to the discussion if I have something I think is of interest to others.
I'd just like to make afew comments about the points that hawkipa is making.
Firstly, given that Burford Capital (LON:BUR) is a board favourite I think it's worth noting that the conversation has been entirely respectful. In my experience anyone posting bearish views on a popular stock is liable to be flamed. Stockopedia is a remarkably civil place to exchange views, long may it remain so.
Secondly, with my psychologist's hat on, it's extremely important to accept and accommodate dissenting views. Confirmation bias, where everyone groups together and refuses to accept contradictory information is one of the most dangerous cognitive biases.
Thirdly, I don't think that using information directly from Burford Capital (LON:BUR) provides a full refutation of the points being made. Even with the best will in the world directors will tend to talk their own book. It's positive information, but we need to look for external points of reference.
Fourthly, the business model here is so successful that it will eventually attract deep pocketed competitors. Whether Burford Capital (LON:BUR) has a real moat or not will be determined then, but hawkipa's comments are entirely consistent with what we ought to expect.
I'm a very very happy holder of Burford Capital (LON:BUR) but I think this type of conversation is incredibly important.
timarr
Burford Capital (LON:BUR) it's worth reading the section of the annual report that deals comprehensively with competition starting on page 11. This dispels the notion that competition is a problem, currently or in the foreseeable future.
http://www.burfordcapital.com/wp-content/uploads/2019/03/BUR-31172-Annual-Report-2018-Web.pdf
It's tempting to think that this business is easy money and only requires access to finance as suggested above.
"they will undoubtedly be facing competition for the best cases against well funded (PE backed) competition."
In reality, the factors that limit BUR's competition are extensive and adequate finance is just one element. The legal expertise to do well in a business like this is a major requirement as is the ability to build long term relationships with major law firms and the scale to be able to offer a "one stop shop".
Yes there are competitors but simply having deep pockets will not guarantee success and as BUR point out, it is very unusual for them to lose an investment opportunity to one of their competitors.
Hi Hawkipa, when I've asked lawyer friends (partners in city law firms) about Burford they have been similarly dismissive saying things like "well, the hourly fees model doesn't really exist anymore. All law firms are paid on a contingency basis to some extent." By and large they have been rather negative about Burford and litigation finance, which is agrees with the comments you have got back from your inquiries.
These friends made these comments to me several years ago, and despite the negativity Burford results have gone from strength to strength.
Why is GVC down today about ~6%?? I thought the directors selling was already factored in....
No idea Dhanpal. GVC Holdings (LON:GVC) go ex dividend tomorrow so perhaps sellers are getting out early in anticpation of a further drop? But judging by the 'noisy' bulletin boards elsewhere, PI's seem very unhappy. Luckily (as it turns out) I got out with a tidy profit on Monday and have been watching from the sidelines.
cheers
Francis
EDIT: One other thought, it's about to leave the FT100 index so tracker funds may be selling down?
Brokers at Barclays (LON:BARC) dropped the GVC Holdings (LON:GVC) target price by 20%.
If you ever wonder why this newsletter does not touch mining stocks then the story of Red Emperor RMP today will help. One of the most posted about stocks over the last few weeks on Twitter, news galore, a billion barrels of oil (according to the message boards), life changing etc. Then the news broke last night..a duster. No oil. Abandoned. RMP has crashed nearly 90 per cent today wiping out many punters. Ouch!
As a holder of Somero Enterprises Inc (LON:SOM) I think it is fairly valued as it is while anything that does happen in China can be looked upon as a bonus.
One thing that did jump out at me this morning was "We are particularly encouraged by early signs of increasing demand for quality concrete floors in India, and the investments we have made with in-country leadership and resources are helping to drive these positive results."
Specific figures for India are included in the "Rest Of The World" bucket which is up 36% to US$ 1.7M ... admittedly tiny at this time but management seem very keen on this as noted in the above.
Everyman Media (LON:EMAN) holder here.
I liked the results this morning and thought I would share some thoughts.
Some negatives:
Additional thoughts welcome!
A
Everyman Media (LON:EMAN)
Hi Abtan
Agreed re absence of comments on Newcastle. It looks to be on track for Spring 19 opening per this article in the local paper https://www.chroniclelive.co.u...
It looks like the licence referred to in the article has now been issued.
They have also been advertising for staff for the new venue recently.
Anyone interested in Eagle Eye Solutions (LON:EYE), whose interims are out this morning.
Reasonably impressive growth numbers, losses almost eliminated. Has the feel of a story stock and long term disappointer finally coming good. But what valuation?
Used to hold but sold on the latest run up. Potentially interesting again as the SP moderates again.
Charles Taylor (LON:CTR) final results are curate's egg-ish. I hold, for my sins.
Anyone more successful than I am at figuring out from this how well they are really doing? The price has come down a fair bit over the past year, and rallied on these results. At this level they look cheap - I am considering adding.
I used to hold Charles Taylor (LON:CTR) but sold partly as I was increasingly uncomfortable with the rising debt (including after emailing the FD about it). I remain interested (especially as it gets cheaper..) but I've been equally unsuccessful at working out how well they are really doing/how safe an investment it is. The last full year results mentioned covenant tests then of something like 2.5x ebitda which seemed a bit tight to me, but I can't see anything in this year's other than the directors are 'comfortable with current leverage/debt'. c70m year end/c60m average debt sounds a lot to me for 22m adjusted profits/a statutory loss. My rather simplistic view /conclusion is: Dislike: debt going in wrong direction (will they be ok if any of the businesses run into trouble?), use of adjusted ebitda rather than profits sometimes a red flag, extent of adjustments/statutory loss, trying to buy growth and query if it's really working i.e. producing profits/cash), chart may suggest market is concerned. Like: looks a really interesting and under the radar/steady/boring (good signs) company in a niche area, hoovering up decent businesses, possible takeover potential, no disasters over the years, cheap, nice yield - and Lord lee and mark slater like it/ have increased their holdings I think. Should probably put in too difficult tray/too many ??s and move on but..
Just to add on Charles Taylor (LON:CTR), the more I read the more I am thinking there are maybe too many ??s for my liking. As well as finding it tricky to really understand the numbers and put a value on it, I also think the ceo/fd narratives can be revealing in terms of the impression they give, and whether they can present information clearly and sound straightforward and credible. I just don't feel this report inspires much confidence in that respect (I note another reader above says they don't think much of the chief exec..). Quick illustrations:
"Managed pro-actively financial leverage through a significantly oversubscribed share placing". Sounds a bit like a CV soundbite/obfuscation..
'Our growth in adjusted profit before tax is not reflected in our statutory profits before tax, which unfortunately shows a loss'. Is it 'unfortunate'?
In terms of the debt (which was my concern), the last annual results said:
"The facilities contain two key financial covenants...… leverage..... shall not exceed a target of 1.75: and 2.5:1. The leverage covenant is calculated as Adjusted EBITDA to Net debt, including a full 12 months of any acquired EBITDA. [For] the leverage covenant... we will be able to include the 12-months EBITDA for all acquisitions."
My take is it should read 'Net debt to Ebitda', not the other way round, and it sounds like they are looking to stretch ebitda (and therefore debt) as much as possible. Oddly there's also no mention of covenants (that I can find) in this year's report but they do say "The board is comfortable with the current level of financial leverage and by implication net debt". Again it's oddly phrased and feels to me like it might not be quite as comfortable as they say..
Graham,
....I too hold Somero Enterprises Inc (LON:SOM) and am kicking myself a bit for not buying more on the dips.
Its difficult in these dip situations because its tempting to think - What does the market know about Somero Enterprises Inc (LON:SOM) prospects that I don't?
But in their RNS today the outlook is as confident as we can hope for: ...Board believes the Company has numerous meaningful growth opportunities in 2019 across its broad portfolio of markets and products that is supported by positive non-residential construction market conditions and reinforced by customers reporting project backlogs that extend beyond 2019."
I hold the view that the market in small caps a lot less efficient than we could be lead to believe.
Somero Enterprises Inc (LON:SOM) I am also a holder and this has trebled for me. I picked up some more as a trade when they spiked down on City Inv forced selling recently.
Results were pretty much where I expected them. Some good comments on here already so I won't regurgitate.
Key risk and market cynicism is around the cyclical nature of the business with a number of folk pointing out (all the way up from 150p I would add) that in a global recession this type of business doesn't do well. Ie people hang on to their existing equipment and don't buy new screeds or upgrade. Thus when looking at valuation this one year in x should be taken into account and blended/reduced accordingly.
I don't disagree with this but management appear adept at navigating these downturns. They say they see any reduction in demand almost immediately it start happening (minimal lag) and can react accordingly. They also hold a good cash buffer with no debt which appears most sensible in allowing them to ride out any storms and cut cloth accordingly.
I personally don't see China as a problem. It is true it has taken them a while to start growing there and there is Intellectual property risk operating directly in the region BUT, there is nothing in the price for China at present, and if they do start getting traction it will either act as an accelerator in good times or as a hedge to slowing markets in the event of any recession.
Taking everything into consideration I don't view them as expensive given current management outlook.
I've held Somero Enterprises Inc (LON:SOM) in the past and hope to do so again in the future.
My key concern is the impact of tariffs. I remember Paul asked this question to management recently on my behalf, but if I recall, their answer was not overly re-assuring. They alluded to the "we'll know pretty quickly if things go south" answer (which, incidentally, is why I am responding to this comment, as you have also mentioned this), but if/when they announce this to the market, the damage to the share price would be swift.
I remember researching the impact of the tariffs last year and from what I could see construction costs in the US were going to materially increase - I could only see this having a material negative impact on Somero Enterprises Inc (LON:SOM) .
I'm therefore happy to wait on the sidelines until the US-China trade war is sorted out. A controversial strategy for some, and I'm certainly interested in hearing counter-arguments to my thinking.
Cheers
A
Somero Enterprises Inc (LON:SOM) products increase efficiency and reduce costs of construction and subsequent remediation. It could be argued that tariffs increasing cost of construction will lead to a desire to increase efficiency by construction companies unless impact is big enough to switch off construction.
A risk I agree, but not easy to assess and directly correlate to impact on Somero, hence managements vague answer I suspect. You could construct an analagous risk to pretty much every business/industry though (Housing, Tobacco, Gaming, Financials all spring to mind) and thus there is a danger of missing out on many good businesses.
Somero Enterprises Inc (LON:SOM)
"It could be argued that tariffs increasing cost of construction will lead to a desire to increase efficiency by construction companies unless impact is big enough to switch off construction."
Agreed. I guess my thinking was that aluminium and steel prices increasing 25% and 10% respectively would be material enough to drastically slow everything down. I'm still amazed it hasn't to be honest!
GLAH
A tariff does not cause the average price of the thing within the country that raises it to increase by the nominal amount given various substitution effects, so the net effect is (much) less than the headline rate.
Somero Enterprises Inc (LON:SOM) - I agree the main bear case I have seen is the cyclical nature. Whilst I understand and agree with the sentiment, Somero's products support construction in an area which is not going away any time soon - namely the need for flat floors. There will be an ever growing need for automation/warehouses supporting online businesses for the foreseeable. I think this provides a decent hedge against any wider macro economic concerns.
Their is one other key point that makes Somero Enterprises Inc (LON:SOM) flexible in a upturn or downturn, which is that they are effectively a compoment assembler, which do not carry the huge fixed costs of a primary manufacturer. It’s this aspect that helps create the excellent Return%s too. Ian
I have an interest in Somero Enterprises Inc (LON:SOM) Burford Capital (LON:BUR) and Advanced Medical Solutions (LON:AMS)
The first two are covered and I'm quite happy.
Good results from Advanced Medical Solutions (LON:AMS) and a good company, but possibly not enough to sustain the valuation? But then I've been thinking this for years!
Burford is my biggest holding.
Safecharge my third biggest so I endorse the request by runthejoules.
On Somero Enterprises Inc (LON:SOM) this my fifth largest holding and fourth biggest gainer (I started buying in 2015). And personally missed a trick in not picking up some more in late December in the sell off but my process is not yet very good on picking up on this sort of thing.
There is a risk that I might have fallen in love with the stock and was wondering if anybody has a bear case on £SOM? I can see little not to like.
Is
“At December 31, 2018 and 2017, the Company had two customers which represented 23% and 15% of total accounts receivable, respectively”
In today’s accounts a risk? Does anybody know who the two customers might be?
Thx.
I too hold Somero Enterprises Inc (LON:SOM) and am kicking myself a bit for not buying more on the dips. But I think the bear case is this.
1. No sign of success in China
2. New products for sky scrapers are in their infancy and growth may not be forthcoming here either
3. The large need for vast warehouses with high racking (I.e. those where high precision level flooring has most value) is a sweet spot right now as more and more retail moves from the high street to online but that will abate over time
4. The first three points mean future growth may not be as easy
5. Dividend in dollars so lose some on conversion to pounds
6. US stock so potentially some tax issues
7. Exchange rate risk if pound strengthening against dollar (big if)
For me, none of these are substantial risks or issues. I think the need for warehouses with very level floors has a long way to run yet. China would be great if they can crack it but it is more like icing on the cake if they do. Their initial comments about products for skyscrapers are encouraging.
Thank you Graham for taking the time to put this down. Number 3 had occurred to me but then again I doubt we are anywhere near peek warehouse :-) and I would have thought that there may be other areas where ultr-flat surfaces are required that they might move into?
On China more progress would have been/would be nice but at a 12 PE it does not appear to be priced for stupendous growth in China and there were positive comments on India.
I think I will top up over the next few days once the noise around the results has settled down.
regards
Michael
I too hold £SOM and would add that there is strong growth in the use of Autonomous Guided Vehicles or AGVs, basically warehouse robotics. I work in the industry and companies like Amazon, Ocado etc increasingly use this automation as well as auto makers. AGVs also require level surfaces to operate accurately and effectively. I don’t have the numbers but warehouse automation is a growing trend. I’ll be surprised if other companies aren’t competing with Somero in the not too distant future. For now, it looks like they have first mover advantage. Long may it continue.
Fourth vote for Somero Enterprises Inc (LON:SOM) please
Another vote for Franchise Brands (LON:FRAN) please Graham, they seem to have shifted into another gear on these results; the Stocko picture overall doesn't look marvellous, but maybe things will adjust on these numbers. ROCE is mediocre... but perhaps expected in this type of business?
p.s. Am lovin' the results from Burford Capital (LON:BUR) and glad I topped up after the big institutional fund-raise.
Marshall Motor Holdings (LON:MMH) looks interesting if one follows the maxim of buying something of value when nobody wants it. The conundrum of course is having the ability to recognise the value and the believe and confidence to act.
I would like to add a second request for Charles Taylor (LON:CTR) and Somero Enterprises Inc (LON:SOM). The adjustments in Charles Taylor (LON:CTR) look incredibly vague and a bit catch all to me!
Hi Graham
I would be interested in your view on EKF Diagnostics Holdings (LON:EKF). Growth a little muted, but seems to have potential in US for its products after FDA clearance. I hold.
Greyster
Charles Taylor (LON:CTR) Charles Taylor please. Grown a lot by acquisition. Statutory loss before tax of £3.3m and loss per share of 5p - of course management say that we should focus on the adjusted numbers!
I don't rate the Chief Exec (former McKinsey consultant) but think that it's a good business, as long as he hasn't done too much damage? I'm sitting on my hands for now.
I own Burford Capital (LON:BUR) and Somero Enterprises Inc (LON:SOM) so I'm interested in those too.
Somero Enterprises Inc (LON:SOM) please
I'm also interested to hear views on Burford Capital (LON:BUR) from all comers as 23% profit increase seems to be maintaining momentum well.
Also SafeCharge International (LON:SCH) though it may be a bit too big again, profit up 4% but dividend up 8% to about 5%. I hold moderate amounts of both.
Somero Enterprises Inc (LON:SOM) - Great results and outlook, special dividend details confirmed. However there is no avoiding the fact that EPS of $0.38 misses consensus forecasts of $0.40. While only a 5% miss, this also makes FY2019 forecasts of 0.42c harder to achieve (although still possible).
The share price has run up in the last few days and so may be under pressure this morning. In the medium term I am confident as I think they are cheap, have a good business niche and should be a late cycle performer due to their labour saving attributes and long project lead times. I will try to reduce on the open as a trade with a view to buying back later.
Edit: Brokers note says they were ahead of expectations - anybody know what's up with that?
Thoughts on car dealers Graham?
Pendragon (FY yesterday) - looks like a dog (figures hard to follow)
Lookers - so so figures
Marshall - looks like continued outperformance with increased divi icing on the cake.
IMO Marshall very undervalued should be trading a lot higher (£2+)
Empresaria (LON:EMR) FY results today, here's an overview by Spencer Wreford, CEO and Tim Anderson, Group Finance Director, discussing the results, their strategy and the outlook. Debt down. Dividend up 50%. Now on an historic multiple of 5.
https://www.piworld.co.uk/2019/03/13/empresaria-group-plc-emr-2018-results/
Franchise Brands (LON:FRAN) results look excellent today and a positive outlook statement.
I like the business model and the highly experienced management team have once again shown their capabilities. They also have significant skin in the game with the board and senior management team owning close to 70%.
Not the cheapest share out there but think it will be a strong performer over the next 3-5 years.
Be great to have both your and others views Graham.
Thanks
Owen
I should disclose I hold (plus my daughter) and my wife is a barkingmad franchisee
Morning Graham,
Burford released full year results today.
Looks like another excellent set of figures.
(I hold)
Michael
My morning smallcap tweet: Manx banks 215p for holders.
Manx Telecom (LON:MANX), Staffline (LON:STAF), Franchise Brands (LON:FRAN)
Manx Telecom (MANX) recommended offer 215p (inc. dividend), a 15% premium.
Staffline (STAF) £35m contract wins over 27 months. I hold.
Franchise Brands (FRAN) FY rev up 43% to £35.5m, adj EPS up 21% to 3p, "ahead of expectations". Stockopedia F/C is rev £36m and EPS 2.94p, so in line with that.