Small Cap Value Report (Wed 14 Aug 2019) - Negative interest rates & Gold, DUKE, LOOK, IND, EQLS, XSG

Good morning,
There isn't a whole lot in the RNS today but we do have:
- Duke Royalty (LON:DUKE)
- Lookers (LON:LOOK)
- Indigovision (LON:IND)
- Equals (LON:EQLS)
Negative Interest Rates
Since the RNS doesn't have too many stories which interest me, I thought I'd spend some time reflecting on the fact that 10-year fixed-rate mortgages are now being offered at negative interest rates in Denmark.
If you go to the source for this story, you'll find that there are disclaimers: due to set-up fees and other costs, the Danish bank which is offering this deal says that "you are not exactly going to make money borrowing".
Even so, this feels like an escalation of the "ZIRP/NIRP" phenomenon. It is almost certainly unprecedented.
(For context: the Danish krone is pegged to the euro and its official interest rate is -0.65%.)
Bank shares have achieved little for investors in recent years and when you read stories like this, it's not hard to understand why.
Until recently, many economists thought that negative interests rates weren't possible. Why bother giving money to someone, if they'll give you less back?
That logic is still quite sound, in my view! Low interest rate environments do have real effects on people's decisions. We are discouraged from saving and incentivised to spend the money on present-day consumption, instead.
But even with very low or negative interest rates, not everybody can consume all of their savings straight away. There are plenty of institutions and individuals who need to wait some period of time before consuming their savings, or who are forced to lend their money for some structural reason, and these are the ones forced to suffer negative interest rates.
Rediscovering Gold
These days, almost anything looks like a better investment than cash and bonds. Any real asset is inherently superior to paper assets.
But when you consider the negative interest rates and the unprecedented monetary conditions, there are strong reasons, at least in my mind, to focus on the prospects for gold.
The reason for this is gold's historical basis as a currency and as a foundation of currency strength.
This means that when central banks have stopped debasing their currencies and want to strengthen them again, they might rediscover a love of the yellow metal. Like a pendulum, we could have a massive reversal on our hands, when they change course.
Indeed, there are signs from some central banks that this has started to happen. According to a recent article by the FT, central banks have been buying gold at the fastest rate since 1971.
So I hope I don't sound like a stopped clock when I talk about gold - besides the fundamental reasons for bullishness, the price is currently breaking out when measured in many different currencies, and central banks are buying. So it's a current story!
Some investing ideas
For stock market investors who are bullish on gold, we have a problem. The problem is that gold bullion itself is unlikely to be a very good long-term investment, at least compared to equity investing. Gold simply sits there and shines, while companies actively create wealth for you. Warren Buffett is right about this!
So what I'm looking for are companies which actively create wealth in some way but which also enjoy levered gains from a rising gold price.
I recently asked the readership here for your thoughts. Unfortunately, I didn't phrase the question very well. I was looking for companies which can enjoy levered gains from a rising gold price, but which aren't in the mining sector.
One company which has been brought to my attention is the Toronto-listed Sandstorm Gold (SAND). While this is technically in the mining sector, it's really a financial stock which generates royalty income by financing the companies which do the digging.
Closer to home, readers will know that I am long H & T (LON:HAT) and have a positive view of Ramsdens Holdings (LON:RFX), too (though RFX is more diversified away from pawnbroking and gold-related activities).
There are also some large US stocks which might be worth a look - these are the American versions of H&T.
Firstly, we have the Texas-based EZCORP (EZPW). This was the biggest shareholder in the ill-fated British pawnbroker Albemarle & Bond (ABM), prior to that company's administration. Hopefully it learned a few lessons from that misadventure!
And there is the much larger FirstCash (FCFS), also headquartered in Texas.
For those of us who like H & T (LON:HAT) and Ramsdens Holdings (LON:RFX), and want more ideas in this sector, these stocks could be worth a look.
Duke Royalty (LON:DUKE)
- Share price: 45.1p (+3%)
- No. of shares: 200 million
- Market cap: £90 million
(I have a long position in DUKE.)
Duke's share price had slid quite far recently, from a high at 48.5p to a low at 42p. For a stock which is valued against its (contractually guaranteed) cash flows and which hadn't issued any news, this was unusual.
Today's RNS has evidently calmed a few nerves. The H1 results will be in line with expectations.
This is something I've noticed with a few stocks recently: they are selling off ahead of news, and then bouncing back when they issue an in-line-with-expectations update.
There is no doubt about it - investors are jittery at the moment!
(This is proven by the fact that the VIX, or "Fear Index", recently spiked up to 25. That index relates to the S&P but I've also noticed a significant uplift in volatility pricing on the FTSE.)
Key points from Duke today:
- Q1 of the new financial year (from April to June) saw continued momentum with record quarterly cash revenues.
- all Royalty Partners increasing their payments to Duke
- agreed new terms on debt facility to increase its size and "significantly" reduce its cost
- strong near-term pipeline of investment opportunities. "Late stage investigation" of new partners and negotiating follow-on investments in the current portfolio.
While all of this was baked in to forecast, it's still a great update from the company.
As highlighted by CEO Neil Johnson, shareholders can look forward to operating leverage from rising income and relatively fixed costs:
"...the Board believes the existing investment and operating infrastructure is now able to support the continued growth of the Company for the foreseeable future, which will stabilise group operating costs in FY 2020 and beyond."
Forecasts
The company's broker, Cenkos, has published a note this morning (available on Research Tree). It leaves all the FY 2020 forecasts unchanged, including:
- income of £11.8 million
- operating profit £9.7 million
- adjusted, diluted EPS of 3.9p, with a payout of 3.6p. This implies an average quarterly dividend of 0.9p, rising from the current 0.7p.
My view
If I was happy to hold shares in Duke prior to this update, I'm hardly going to rush for the exits now! It hasn't put a foot wrong yet, which is all we can ask for.
Blackrock is also a happy holder, increasing its stake in the company last month to 10%. There are many institutions on the shareholder register.
To explain once again how it works, Duke is a halfway house between debt and equity investment. Its royalty payments are contractually guaranteed, and they also rise as the investees grow their revenue - so we get an element of inflation protection and we get to participate in the growth of the investees, too.
From time to time, we can expect that investees will suffer declining revenues and will default, but the overall return could still be quite good. One way of thinking about it is that Duke can get payback of its invested amount from an investee within about 7-8 years. And if the company survives and thrives for 30 years, Duke can get multiples of its initial investment back.
This share is currently about 5% of my portfolio, and I don't plan to buy any more. For now, I am simply monitoring its progress. A re-rating of the share price may depend on the company proving that it can get through another year or two with any major problem, and on more risk-reducing portfolio diversification. Thankfully, it sounds like that is on the cards.
Lookers (LON:LOOK)
- Share price: 44p (unch.)
- No. of shares: 389 million
- Market cap: £171 million
This auto retailer reports numbers in line with downgraded expectations and are undeniably rather poor: underlying PBT is down 27.5%,
The company talks about a "very challenging economic backdrop" and declining new car sales, problems which are facing all of the dealerships right now.
It also mentions weak margins in used cars - readers will remember this being a feature of results at Marshall Motor Holdings (LON:MMH), discussed yesterday.
I can't motivate myself to discuss this in more detail, as I don't want to get involved in any car dealership stocks. I'm not the only one who feels this way, so value opportunities could emerge in this sector for those who are willing to do the work to find them.
The ValueRank at Lookers is 97. Could this possibly already be in "deep value" territory? I will leave it up to you to decide.
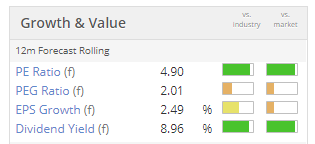
For dividend hunters, watch out:
The Board intends to undertake a review of the current dividend policy in light of the Group's trading performance and future cash flows before the publication of the Group's Annual Report & Accounts.
Indigovision (LON:IND)
- Share price: 182.5p (+3%)
- No. of shares: 7.5 million
- Market cap: £14 million
There have been many false dawns at this Scottish CCTV business - too many to mention.
Today's H1 results show a small operating profit of $0.4 million, which is at least better than the loss it incurred last year. Sales are up by 8%.
Outlook:
The actions taken in 2018 to refocus the Company's strategy continue to drive improvements throughout the business. As in previous years, sales are expected to be weighted towards the second half of the year and the nature of IndigoVision's business is that the precise timing of customer orders is difficult to predict. Nevertheless, the current indicators continue to support the Board's target to return the Group to profitability in the current year and for the business to deliver an acceptable level of profitability from 2020.
My view
I've more or less given up on small, order-driven companies like these, as I think that even the managers are unable to predict the results.
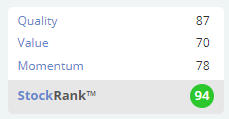
However, the StockRanks love it and categorise it as a Super Stock. If you can get past its lack of visibility, you might find a trading or investing opportunity here.
Equals (LON:EQLS)
- Share price: 111.1p (-5%)
- No. of shares: 164 million
- Market cap: £183 million
Statement re: press speculation
A brief statement:
The Company notes the recent press speculation and confirms that it is in the advanced stages of conducting a fundraising in the region of £14 million at a price of 110 pence per ordinary share in order to accelerate organic growth and to fund potential acquisitions.
An additional £2 million of new shares will be made available in an Open Offer - a nice gesture for small shareholders, although it's only really a gesture when the main fundraising is seven times larger.
According to my sums, we could have an extra 14.5 million new shares, increasing the share count by 9%. Not a terrible amount of dilution to suffer, then, for those who don't take part.
Cash performance - I've just checked the company's financial statements from last year, and they show that the company capitalised nearly £6 million of development spending. It spent a further £6.5 million on acquisitions.
The cash inflow from operations was quite limited, so the company's cash balance ended up declining by £10 million (leaving it with £8 million).
If you believe in the company's potential, this is probably fine: it is investing for its future opportunities. But it's clear that cash is mostly going out the door for now.
We also had an update from Xeros Technology (LON:XSG). This company has an exceptionally poor financial track record and is now attempting to raise money with the help of its Chairman's corporate finance business. Woodford Investment Management is the top shareholder.
Have a good evening, everyone.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Indigovision (LON:IND) I'm struggling to see why this is a superstock, QR is 87 but apart from a Piotroski score of 7, I can't see where the quality is, it hardly makes a profit, over the last 4 years it has made a loss.
It looks like Indigovision (LON:IND) is being flattered by its F score and the "gross profits to assets" score in the Quality Rank. It has a good gross profit which gets completely wiped out every year and very few assets so gross profit/assets does well and the F score loses two points because Indigovision (LON:IND) does not actually make any profit but it is doing OK with the other tests (very little debt and it is losing less than it was!)
OK thanks Nick, where are the gross profit figures? The operating profits are negative. Just surprising that a company that is loss making is a Superstock but I have seen similar ones before.
The gross profit figures are on the income statement under accounts. (Side-note: the operating profit does not seem to be gross profit minus expenses on IND's accounts.)
You can drill down into the quality rank for a stock by clicking on the quality rank value in any table it appears in (but not from the stock report.) (edit to add: does not work on new site.) You can drill down into the Piotroski F score by clicking on the link in the stock report.
But just to be clear I am not endorsing or passing any kind of judgement on the quality rating that Stocko is coming up with - just reporting how it got the number that it did.
I think a minor red flag is whenever the various components of the quality (or other) rank do not broadly agree with each other. When you compute an average but there are widely differing views of how much quality the stock has what does it mean? If all the various factors are roughly similar then clearly the average gives a smoothed view of the situation. But if (for sake of argument) I average 10 and 90 to get 50 that value of 50 is much less informative. It's clear there is more going on if the different valuations differ so much.
Also, on Warren Buffett's point about gold has no value, other than human emotion.
Of course he's correct, it doesn't produce any cash flow, so using his DCF methodologies its value is nil. However, it depends on the next best alternative for your money. Deposits pay no interest either, potentially negative soon. WB keeps his horde in the bank in $USD. For all its woes, he has the might of the world's reserve currency behind him. At the moment, he's sitting on a huge pile, waiting.
For us, Sterling is NOT the world's reserve currency, far from it.
In general, as a safe haven for savings the main, highly liquid options are govt bonds, cash and gold.
Bonds likely will be ok if interest rates keep dropping, you will make a capital gain. But you have to have a view on inflation, if inflation arises your bonds won't do well.
Cash is the ultimate option if you are waiting to pounce on undervalued shares or London property :) Of course, cash is actually risky in a recession. If you have say £1 million cash in the bank, only £85k is covered by the govt protection scheme in the event of a bank failure. Deposit haircuts do happen, would a populist govt bail out 0.1% of wealthy depositors? Probably not in full.
That leaves gold and silver, which have the advantage of a relatively fixed supply and they hold value outside of general currency fluctuations and money supply increases. For me, the real hedge here is that I expect central banks to kick off a huge round of QE in the next downturn aka Modern Monetary Theory (MMT) and use it to fund big govt deficits. The last roll of the dice by our imprudent leaders. More money supply and higher deficits ultimately means paper currency devaluation against hard assets and the currency of any other country which has real resources and a current account surplus. The UK has neither, actually a large current account deficit, funded only by external investment flows, so Sterling has downside risk in such an environment.
Also gold is heavy traded so daily liquidity is good, if you need to raise cash and buy those bombed out stocks. I actually have a recession list, stocks like Rio Tinto, which seem to always crash in the cycle and then rebound on the recovery.
Hard to tell when all this will happen, could be a few years off, the bull market may have another leg left in it. Also Trump is banging on the Fed's door, he needs some stimulus to juice the US economy leading into his Nov 2020 election. And early next year he will 'solve' the trade war he created too, for the same reason.
But you have to position Gold/Silver before the herd arrives and it gets expensive, so I hold some now.
Of course he's correct, it doesn't produce any cash flow, so using his DCF methodologies its value is nil.
Charlie Munger says he's never seen Buffett run a DCF analysis, ever.
Mostly, of course, Buffett is correct - Gold is an unproductive asset. Where's it's really valuable, though, is where you live in a country with a high degree of political uncertainty, the potential for significant currency devaluation and the possibility of asset appropriation by a future government,
If you were unfortunate enough to live in such a country then having a stash of gold as a hedge against uncertainty would be very wise indeed.
timarr
Depends what price you buy the gold at. It's not a hedge to anything if it is overpriced. It holds some negative correlation to a weakening economic environment and high inflation but it isn't perfectly correlated and there isn't actually causation because their are other factors at play too simply because markets are completely global.
there are*
I also hold silver via a physically backed EFT. Reason being the Gold:Silver ratio is near its long term peak so I expect some mean reversion. Possibly silver will, over a year+ timeframe, rise more than gold.
Holding miners is interesting, especially the low debt AAZ discussed above, but I worry about black swan risks on individual companies, so prefer GDX.
I am very bullish on precious metals at the moment for all the reasons mentioned above .
This is an interesting video regarding Gold and the Dollar worth checking out
https://www.youtube.com/watch?v=fjhLp8AHAYc
I hold both physical gold and silver coins as well as interest in the following miners;
Caledonian mining – (which to date has been a poor investment due to the Zimbabwe economy ) , but aside from this my other gold and silver miners that are doing well and I believe have more upside include ;
Shanta gold,
Silvercorp metals,
Pan African resources,
and Trans Siberian gold.
Aside from that with the Brexit worries by investing in gold it provide one with some hedge against the devaluation of the pound that is happening – Just in the last month it dropped from 1.24 Swiss Francs to the £ ( which was low already ) to 1.174 to the £ at one point yesterday.
For reference in 2007 it was 2.47 Swiss Francs to £.
Also whilst Gold has increased in value in dollars terms by just under 17% in the last 3 months it has increased by over 25 % in pounds sterling reflecting the relative loss in value of the pound.
I would have to agree with bsharman on AAZ. I never expected to invest in a resource stock let alone an Azerbaijan based gold miner but this is my “the World is going to hell in a hand basket play” and stands at 20% of my portfolio and has worked out well since I first bought in October.
All this talk of how amazing gold stores value reminds me of a debate I had with an investment manager (at a company that will remain nameless) back around the end of 2011:
This investment manager was adamant gold was going to double again after a huge rally to somewhere above $1,200 (I dont remember the exact value) . He was so sure that he was telling them to put 30-40% in. I told him it is only worth what people view it to be and generates no cashflows.
I remember this so well because a few months after the discussion gold dropped around 30% - not sure what happened to his clients, I never did find out...
A company with exposure to gold (popularity) but not mining:
Augmentum Fintech invested in BullionVault which is an online platform for trading gold and other precious metals.
I have a large percentage of my portfolio currently in decent gold miners. So far with good returns, For some time now the likes of the Chinese, the Russians, major banks and institutions, the list goes on..... have been buying gold like there is no tomorrow and possibly for good reason. Where else could you put your money if the poo really hits the fan globally ?
The absurdity of negative interest rates, as well as the economic and political situation, have driven me into Gold more as insurance rather than an investment. It's there should events really go wrong. However, I have opted for a small portfolio of Gold mining stocks. All, bar one, are dividend payers and geographically dispersed. Gold explorers hold no interest for me. It's all about low-cost (Low All-In Sustaining Costs) and profitable production.
It might be worth mentioning that drilling a hole in the ground is fraught with problems from geology to environmental issues. It's an inherently risky business. And so I would not put all my eggs in one basket.
As Graham rightly points out, in recent years, Central Banks have been avid buyers of Gold. So let's take a step back. Central Banks have access to the most insightful information that the nation can provide. And the one asset they appear to be collectively stocking up on is Gold. Not Bitcoin but Gold. Hopefully, I am wrong but I get the impression that they are signalling that there is something rotten in the state of Denmark.
One for the quants out there, but the whole idea of Gold does not generate an income.
Why can't someone buy gold and sell out of the money put options on the same.
Have gold holding (or some ETF that provides gold exposure);
Get the income from selling the put option;
Option expires worthless - you pocket the income.
Gold rallies and the option is exercised - sell your existing gold to cover the option and then repeat by buying gold.
Cost would be the transaction cost.
I am sure there is a good reason for this, because if it was as simple as I described above, I am sure someone a lot smarter than me would have started a fund deploying that strategy.
Maybe it already exists, but certainly not something I have come across.
1. You probably mean call options, not puts. A put option would not be exercised if the gold price rallies, a call would. Selling an out of money put option simply increases the exposure of your imaginary fund to gold (if the price of gold falls it loses twice). Selling a call option would make slightly more sense as this would replicate the strategy of "covered calls" equity funds.
2. Even if we change your strategy to selling calls, there is no theoretical advantage over simply holding gold. If there was an intrinsic advantage it would be arbitraged away. You might as well hold gold and sell 3% a year as a "dividend". You do get a different return profile (smoother) and a different return in different markets (depending on how volatile / up /down the market is) but no theoretical overall increase in return - hence just hold gold and sell some of your gains (or decreased capital) as income.
Yep - I did mean calls, I realise after your post and realise that I shouldn't discuss or think about options!
Interestingly, option 2 is what I did with my holding (regretting now, but didn't know at the time) - I called it taking profits.
Thanks for the reply - helps me understand - as I say, if it was achievable, then I am sure blackrock would have an ETF for it!
Have a nice evening.
Blackrock may well be interested in implementing your covered call strategy. It would enable them to market a gold fund with yield. Funds with higher yields have high consumer appeal, even if they don't offer higher total return. Covered call equity funds sell very well.
If they don't do it now, it is probably because they can only make money on large funds and the gold option market probably isn't deep enough to support large funds.
Hi Graham
Thank you for your analysis of £DUKE. You refer to the recent sell off in the share price and I wonder whether this was linked to £BUR, in so far as investors perhaps felt there was a read-across.
On DUKE's balance sheet there is Financial Assets Valued Through Income Statement within the current and non-current sections. These total £23.6m at 31/3/18 and represented a movement of £1.6m from the previous year.
This was further broken down between realised gains which were recorded in the cash flow statement of £1.0m and unrealised gains of £0.6m. There aren't that many details around the valuation of these but if i am right, the unrealised value would be driven by the revenue in the underlying businesses.
Nevertheless, it certainly made me sit up and think about how the fair value adjustment was working.
Hi Graham,
Both Wheaton Precious Metals and France Nevada are mining Royalty Companies which should be positively correlated to a rising gold price. Both are large caps with Canadian and New York listings. I don't have the US markets on my Stocko account so haven't delved in too deep but a look at the recent stock charts for each Company indicates a steady rise in share price over the last 6 months or so. May be worth a look?
DG
I have been buying Blackrock Gold and General in my SIPP which has been doing well. It has Wheaton and Franco Nevada in its top ten holdings. It suits me as a cyclical play, not a buy and forget.
I also have £LPMT, a leveraged precious metals ETF but that is closing down in September so the other ideas mentioned in this thread are timely.
Blackrock G&G top ten:
For stocks linked to gold hoe about Codan CDA, an Australian stock with 71%of its revenue in the metal detecting, specifically gold, market.
With a StockRank of 96 and a ROCE of 30.9% its 16.8 p/e is still not too punchy considering its very solid share price gain since the start of the year. Realists about Brexit would also note that even the A$ has managed to look good against the pound.
Lending money at a negative interest rate is 'profitable' when there is deflation. There is always a carrying cost or risk with holding money - mostly disguised in recent times by cross-subsidies in banks and government guarantees. Gold tends to be a good investment when there is hyperinflation.
I've not done my own research but a lot of people selling the idea of buying gold claim it does well in deflation too.
Warren Buffett on gold:
“Gold gets dug out of the ground ... then we melt it down, dig another hole, bury it again and pay people to stand around guarding it. It has no utility. Anyone watching from Mars would be scratching their head.”
It's an amusing saying, but patently not true. Its a store of attributed value, that is convertible to fiat or other currency of your choosing, if the counterparty is willing to recognise it as such.
If you stare too hard at any store of value for too long its apparent worth starts to appear somewhat spectral.
As an aside it has some industrial utility.The fact that many Asian cultures actively value it as a back up source of wealth, and its history in Western society also stretches back hundreds/thousands of years.
Apparently women indepently quite value it in this and many other senses.
I would imagine if Buffet served up his previous wife a convertible bond on their engagement, it wouldn't have quite the same effect as Gold, whether or not it should.
Buffett is great at investing in certain types of companies, but he is hardly a rounded human. He has no interest in spending, so drives a rubbish car, eats burgers every day and lives in a modest house. There is an awful lot about business that he understands and a huge amount about human nature that he is clueless about. And gold always speaks to human nature.
You could just as well say anyone watching from Mars would be astonished that people use paper issued by governments that have no way of ever paying back their debts as a method of exchange. The US has already spent more in 2019 than its 2018 budget. The world is flooded with cheap money. Ray Dalio says that everyone should have 10% in gold at the end of the economic cycle. I think people are massively underinvested in gold and it has a long way to go. £AAZ is my preferred play too: great management, holding 40% of the equity, no debt, and, as Hardman said when the price of gold was $200 lower, "prodigiously cash generative"
Hi Graham. I don't know why you tar all mining companies with the same brush as there are some fantastic opportunities in the sector. I know there are quite a few mining businesses with only a hole and a liar at the top BUT some companies stand head and shoulders above the others in terms of governance, attitude to all stakeholders, strategic planning and communicating with shareholders. £AAZ are IMHO a class above. Perhaps readers should take a look and do their own research on this one!
bsharman - sorry if I was unclear about this, but I certainly don't consider all mining companies to be liars/corrupt/etc. Mining is just one sector which I don't invest in, because I fear that I wouldn't be able to make any money in it. There are plenty of other sectors which I avoid, for the same reason. It's not because all the companies in it are corrupt.
Also, you say "Perhaps readers should take a look and do their own research on this one!" -- that's not strong enough. Readers should always take a look and do their own research!
Best wishes
G
Hi Graham - I was being a bit provocative in my previous comment, sorry! I'd still urge people to do some research into Anglo Asian Mining though, if they see gold as an opportunity or hedge against global economic 'headwinds'. They are throwing off cash and pay a decent dividend and the management haven't really put a foot wrong.
Hi Graham, you can also get leveraged exposure to the price of gold via instruments such as the below, which can be held in SIPP's, and some in ISA's too.
Boost Gold 3x Leverage Daily ETP
SG GOLD X5 DAILY LONG Gold
The Boost ETP comes with GBP and USD versions - pick the GBP version and you can benefit from the fall in Sterling as well as the rise in Gold.
Indeed Martin. Whilst I am not a fan of PMs outside their industrial uses (we dig up gold to clump it together and then put it back underground again; not productive) there are plenty of people who are. Sovereigns and equivalents are portable too, which people in some jurisdictions will find attractive. I'd add £GDXJ to your list. It is a basket of global junior miners, 46% in Canada, 25% in Australia; full breakdown on the VanEck website. It is low cost, TER 0.55%, and there is realistically no single company risk. Juniors should have a higher beta than the handful of majors.
Thanks Andy, already in VanEck fund as well as Direxion 3x Miners and Junior Miners... as well Barrick, Trans-Siberian, Anglo-Asian and Shanta. Half my portfolio is in gold/gold miners at the moment. Very bullish as you can probably tell :)
I think you have that the wrong way round? The point of the GBP hedged version is to cancel out the GBPUSD currency movements. You need to buy the USD denominated units to get the full dollar exposure.
Hi Graham
RNS from Equals (LON:EQLS) which used to be called FAIRFX or FFX, announcing a placing and open offer to fund growth and further acquisitions, akin to the small bolt ons they have made so far. Things seem to be going well
Any thoughts?
I hold
Steve
Thanks, Steve. RNS from £EQLS at 10.19 (following press speculation) says the price will be 110 and there will be at open offer on the same terms. It's a tiny discount to raise £14m which IMHO implies that the institutions have confidence and an appetite to invest.
Equals (LON:EQLS)
Hi Steve, I will see if I can get to that one. Thanks. G
I queried the high level of cap ex on software development at EQUALS at their AGM in June and was told it might be even higher this year. They are building a new front-end across their 3 different platforms. Bearing that in mind and recent acquisition costs, it's not surprising they need to raise some money. More info on their finances on my blog report on the AGM.
Duke Royalty (LON:DUKE)
Interview with Neil Johnson, CEO by James Lynch, Fund Manager, Downing, (March 19).
James elicits the key investment attractions of DUKE, and Neil gives a great overview of DUKE, royalty finance, the market place, risk management and much more, to answer many of the questions investors may have.
https://www.piworld.co.uk/2019/03/19/duke-royaltys-ceo-neil-johnson-interviewed-by-james-lynch-fund-manager-downing/
Morning Graham, Morning All,
I wanted to request coverage of Georgia Healthcare (LON:GHG) if I maybe so bold
- a critical part of the healthcare ecosystem in Georgia - for the long term, I think it is one of the best sectors given demographics.
12% revenue growth with operating cash flow at 73% of EBITDA
Cash generative business who have completed a relatively large CapEx plan - going forward this should improve ROIC and Cash ROIC. Free cash flow has been held back by past CAPEX, but now they are starting to pay down the debt.
Small dividend but expected to double by 2020
Stockranks don't think too highly of it - understandably but I can see the quality rank improving over time.
Many thanks,
V
I didn't notice this RNS-Reach yesterday from £BGO. Might be significant?
"Cambridge, UK, 13 August 2019 - Bango (AIM: BGO), the mobile commerce company, and Spotify, have entered into a business partnership to increase access to the world's most popular audio streaming subscription service. By partnering with Bango, Spotify makes its streaming service available for operators all over the world to bundle with mobile and fixed subscription plans allowing millions more fans to enjoy their favorite artists.
This partnership will enable millions of customers to select a Spotify subscription bundled with their mobile plan, or as a bolt-on. Bango Resale technology delivers a single, powerful solution that will enable Spotify to reach new customers, and ensures active customers enjoy seamless access to their services. In addition, Bango data insights supports with targeting specific customers with new offers to generate higher customer adoption.
Then you didn't see this from andrea341:
https://www.stockopedia.com/content/small-cap-value-report-tue-13-aug-2019-hat-wosg-plus-mmh-card-cnks-503941/?comment=15#15
I hadn't noticed that it was an RNS-Reach announcement (ie not a required regulatory disclosure).
That however reinforces my initial view of it; that it was a typical "story stock announcement" - ie some seemingly quite profound news, that supports the story and you would think should be financially significant, but with no hard numbers as to whether it actually delivers anything towards near term earnings.
That's a general observation, rather than a specific criticism of Bango (LON:BGO) (where I no longer have a position) , but it fits the bill precisely of many similar announcements I have seen.
£SONG has decided to withdraw the proposed extension to their borrowing limits and to raise equity instead. No impact so far on the SP.
" Hipgnosis announces that, following consultation with its major shareholders, it will withdraw the resolution at the General Meeting to be held on 21 August 2019 to increase the Company's borrowing powers and is instead contemplating an equity raise in Q3 of 2019 to finance its growing near-term pipeline of opportunities.
The Company has now committed its available capital resources to catalogue investment opportunities. The Company will therefore use the net proceeds of any equity raise to fund further investments in line with its investment policy, with a view to delivering increased value for its shareholders. A further announcement will follow in due course.
As a result of withdrawing the resolution at the General Meeting to be held on 21 August 2019, the Company will continue to operate under its current investment objective and policy including its current borrowing policy."
Interims from Indigovision (LON:IND) - return to profitability. Looks interesting on forward p/e 7.3 and SR 94. Going for share buyback rather than return to dividend.
Secured Property Developments (OFEX:SPD) Secured property developments.
I feel sorry for this innocent company that has the same ticker symbol as sports direct, seems like even they aren't immune from the bad news that comes with being linked with Mike Ashley in any manner, as the shareprice is down 30% from the recent highs before Stockopedia starting confusing the two ticker symbols. Presumably the shares will be back at 25p once that incorrect default to them being sports direct ticker wise is removed. Perhaps they should have been blaming Ashley rather than brexit in their most recent results.
Promising looking Operational Update from Duke Royalty (LON:DUKE) this morning:
https://www.investegate.co.uk/...
(I hold.)
Gostevie
Duke Royalty (LON:DUKE)
Pleasing steady as you go "on track" update, they seem reasonably confident for the future and a reduction in future financing costs is good news, as is the mention of positive operational leverage - Nice to see Pearl and Dean one of their clients returning to where they were 50 years ago in terms of audience viewership - I always have a smile when the pearl and dean adverts come on in my local micro cinema (its not 100% micropubs in my town but close to it).
I've got a £50 sports direct voucher. Should I be rushing to spend it do you think,or holding on for the closing down sale? :-/
Tempted to say I’ll give you £20 for it, but the deal has to close quickly. But I don’t actually want it.
It’s an adventurous super stock with a stockrank of 93 so I’m sure everyone is worrying about nothing....
My morning smallcap tweet:
Gfinity (LON:GFIN), Green REIT (LON:GRN), Secured Property Developments (OFEX:SPD), Xeros Technology (LON:XSG)
Gfinity (GFIN) gives up on Australian JV. All spending has been expensed so no write-off.
Green REIT (GRN) gets rec cash offer of €1.9135, a 25% premium.
Sports Direct (SPD) Grant Thornton resigns as auditor effective 11 Sept. A FTSE350 co w/o an auditor soon?
Xeros Technology Group (XSG) seeking to raise £5m to £10m. £10m is expected to fund the business through to cash breakeven. Progress on moving to licensing model.
Very pleasing operational update from Duke
Short on numbers but good detail with acquisition bedding in well, improved access to cheaper financing, royalty payments ratcheting upwards and a pipeline of further investments.
DUKE returned 6.4% divi last year and are on schedule for 7.4% this year (paid quarterly which is nice)
Final results September 9th
This increasingly strikes me as a well run, lean and agile investment and I remain a happy holder.
I believe Graham that you are still a holder and with you being a little more prudent and risk averse than myself and my rose tinted specs would welcome your opinion.
Thx for all the hard work you and Paul put in here …. much appreciated
Someone please remind me how to reference tickers here … I thought it was &DUKE but that don't seem to work
I think its £DUKE barney.
But it doesn't always work :(
Not working on the new version.
Testing £DUKE
Does not work on the new system, Duke Royalty (LON:DUKE).
Works on the old if you put a fullstop after it.
$DUKE
#DUKE
Think I need an adult to help.
"£duke" = Duke Royalty (LON:DUKE) but I am writing this on the old site - those who write on the new report that it doesn't work. Also note that it needs a space after.
£ DUKE.