Small Cap Value Report (Wed 14 Nov 2018) - FLYB, ABDP, MMH, RNO

Good morning! It's Paul here.
To get you started today, I added 3 more sections to yesterday's report in the evening, being updates from;
Ideagen (LON:IDEA)
N Brown (LON:BWNG) and
Carclo (LON:CAR)
Here is the link to yesterday's completed report.
Flybe (LON:FLYB)
Share price: 12.1p (up 3% today, at 10:48 - volatile)
No. shares: 216.7m
Market cap: £26.2m
Formal sale process - this regional airline has put itself up for sale. This is part of a strategic review with several options (i.e. Plan B, if nobody wants to buy it);
These options include further capacity and cost saving measures, initiatives to strengthen the balance sheet and preserve cash resources, as well as a potential sale of the Company through the commencement of a "formal sale process"
Discussions are already underway;
The Company confirms that, at the time of this announcement, it is in discussions with a number of strategic operators about a potential sale of the Company.
The question is whether any other airlines will see value in Flybe. The stock market certainly doesn't with the share price down to only 12p. There was a short-lived bounce this morning, that was snuffed out by sellers. Who knows what happens next.
On the one hand, I can see that buying Flybe for peanuts might be attractive, if another airline were able to strip out a lot of duplicated costs, and make Flybe profitable. On the other hand, maybe its legacy issues, such as onerous leases on uneconomic planes, might put off potential buyers?
The fundamental problem with Flybe seems to be simply that not enough people use its flights. Therefore, flying with too many empty seats just doesn't consistently make any money.
Let's have a look at its latest results, announced today.
Interim results - for the 6 months to 30 Sept 2018.
Usually when a company puts itself up for sale, after its share price collapsing, then you expect to see dire results. However, these interim figures actually look quite good - adjusted profit before tax is up from £9.4m last time, to £14.0m this time. That's a profit, not a loss.
The CEO's summary mentions the main points;
"In line with our strategy, we reduced seat capacity in the first half by 9.0% delivering a 7.2% increase in revenue per seat.
Continued improvements are being seen into quarter three which demonstrates the popularity of Flybe for our customers.
However there has been a recent softening in growth in the short-haul market, as well as continued headwinds from higher fuel and currency costs.
We are responding to this by reviewing every aspect of our business, especially further capacity reduction, cash management and cost savings. This is already starting to have a positive impact, as shown by the improved first half adjusted profit before tax; however, we must do more in the coming months. We remain confident in the vital role that Flybe plays in UK connectivity."
Seasonality has to be considered with airlines, too.
In fact, there are so many moving parts to consider, that I've come to the conclusion that it's not possible for a generalist like me to add much value in my commentary. It probably makes more sense to track down some broker research from specialist analysts of airlines.
Balance sheet - this is also tricky to analyse.
Net assets are positive, at £118.6m. If we deduct £12.8m intangibles, then NTAV is £105.8m - that's about 4 times the current market cap.
Fixed assets contain a huge amount of owned aircraft. Note 14 in the last annual report shows aircraft on the balance sheet with a NBV of £286.7m. This is positive, as bank debt can be secured against aircraft.
Large provisions have been made for maintenance costs.
Customers pay cash up-front, which helps cashflow (and is reflected in the cash balance and deferred income creditor).
Net debt of £82.1m looks relatively modest, in comparison with the aircraft assets on the balance sheet.
I could go on forever, but my overall impression is that this looks a solvent business, and does not appear to be in financial distress. Which is strange, considering how bombed out the share price is.
My opinion - it's tempting to file this in the "too difficult" tray. However, given the solid balance sheet, and fairly good interim figures, I am actually going to file it in the "fun money punt" tray - i.e. I wouldn't make a conviction purchase of this, as there are too many uncertainties.
I'm very tempted to take a small long position, with money I can afford to lose. The £26m market cap seems to be suggesting that the company is virtually finished. Yet the figures don't look anywhere near that bad.
The reason I'm only prepared to have a small punt on this, is that the company has a history of disappointing, operates in a very difficult sector, and things could be worse than they appear on the surface. Plus of course, I don't have any sector expertise re airlines. Hence why my position size on something like this would only ever be very small.
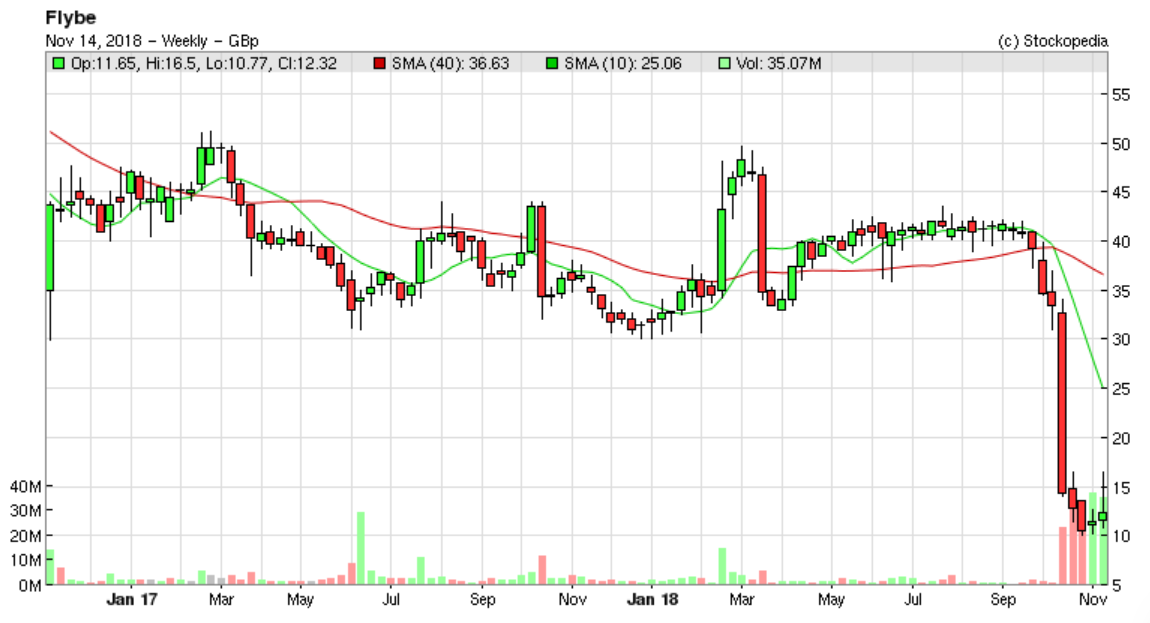
As you can see below, stock market confidence in the company has collapsed. Note the huge volume bars in the recent plunge in price - that looks like institutions dumping their position(s) at any price. Either they know something we don't, or it could be a buying opportunity, who knows? Time will tell.
Ab Dynamics (LON:ABDP)
Share price: 1448p (up 4.3% today, at 12:36)
No. shares: 19.54m
Market cap: £282.9m
AB Dynamics plc (AIM:ABDP), the designer, manufacturer and supplier of advanced testing systems and measurement products to the global automotive industry, is pleased to announce its final results for the year ended 31 August 2018.
These numbers are a pleasure to behold, and I'm not even a shareholder! It looks to be a slight beat against expectations.
The financial highlights section speaks for itself;
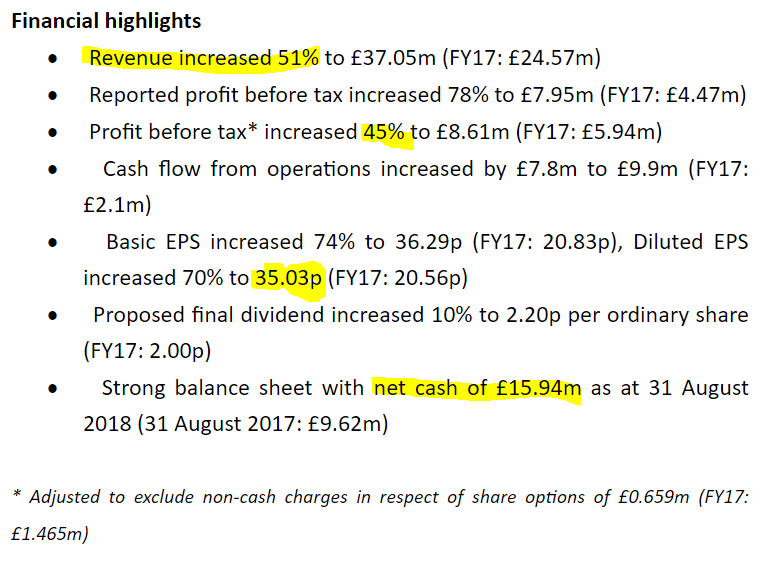
Achieving that level of organic growth (revs up 51%), at high margins, demonstrates that ABDP clearly must have products that are highly desirable to customers. It also suggests that the company's products have competitive advantages of some kind.
On the downside, very high margins tend to attract increased competition, so may not last forever. The narrative today talks about innovating, and investing more in product development, which is reassuring. It sounds like the type of business that has to constantly innovate, to stay ahead.
Balance sheet - looks excellent. Very strong, no concerns here at all.
Net cash of £15.9m looks healthy. Surely the company could be a bit more generous with the divis, which are currently very small?
Cashflow statement - looks great, with profits turning nicely into cash.
Last year saw unfavourable working capital movements, which is always something to keep an eye on. That didn't repeat this year, so it looks a one-off, that came out in the wash. All good.
Capex has dropped from £8.0m last year, to £3.7m this year. This relates to a new factory, I believe. This is an interesting point to note for the future - ABDP said some time ago that it was facing demand that it could not fulfil, due to capacity constraints. It's built a new factory, and now sales & profits are soaring. We must remember to buy any shares in future when a similar situation arises. I didn't fully appreciate how significant that point was, a few years ago.
Outlook - sounds positive. Although note that the company is managing down investor expectations on the net profit margin. The share price suggests investors are happy with this. I agree - if a company is seeing outstanding customer demand & growth, then it makes sense to re-invest some of the profits in useful ways, and hence capitalise on the opportunities.
Despite our very strong growth, order intake has continued to run ahead of sales and this has provided the Group with a healthy order book into our new financial year and, as usual, visibility into our third quarter.
Against this pleasing backdrop, our progress continues to require ever greater investment in systems and our operational capability to ensure that we are fully capable of supporting current and future growth.
In the coming year, we expect to make further investment in new product development, marketing, service and support, our growing overseas footprint and, of course, our people, whose skills and energy remain so important to our future success. Inevitably this investment will provide some constraint to our operating margin, but the Board remains confident that, under the leadership of our new CEO, we are well positioned to deliver a year of solid progress."
Although I would add that, sometimes investors are not quite so sanguine about reduced margins when the figures are actually published, in future. As long as analysts make appropriate adjustments to their forecasts, then it shouldn't be a problem.
My opinion - a smashing company, that seems to be firing on all cylinders.
There's one broker note on Research Tree, pencilling in 45p EPS this year, and 55p next year. At 1448p per share, that equates to a forward PER of 32.2, and 26.3 - quite pricey, but not unreasonable, if present excellent performance & growth can be maintained.
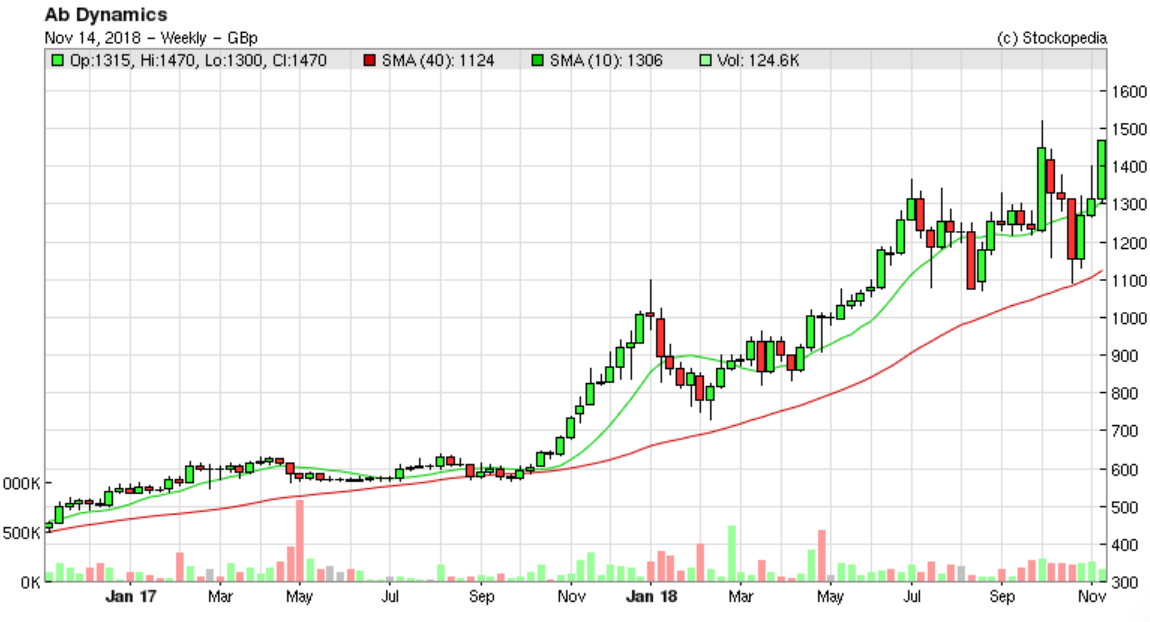
The chart below shows us some interesting lessons. Namely that small caps are becoming particularly volatile in price. As we've seen in the indiscriminate market wobble in Oct-Nov this year, it only takes a few smallish sells, to generate a large spike down in price. It's a pity if people get shaken out of great stocks, through this volatility.
That's why I think stop losses are particularly poorly suited to volatile, illiquid stocks, and I never use them on shares like this. All too often, a stop loss is triggered on a random spike down from some muppet panic selling, or being stopped out on their spread bet. So why would I want my position to be closed in those circumstances? I'd rather be buying their shares at a discount, than having my own shares sold off in sympathy!
Marshall Motor Holdings (LON:MMH)
Share price: 156.5p (up 6.5% today, at 13:58)
No. shares: 77.9m
Market cap: £121.9m
Marshall Motor Holdings Plc, one of the UK's leading automotive retail groups...
This is a turn-up for the books! Car dealer shares have been in the doldrums of late, but things seem to be rebounding;
... better than anticipated trading during October 2018 and a more positive outlook for the remainder of the current financial year.
The following comments echo what another car dealership recently said, and I reported on here. I think it might have been Lookers? Here is what MMH says, which is similar;
As previously announced on 11 October 2018, the introduction of the new Worldwide Harmonised Light Vehicle Test Procedure ("WLTP") had a significant impact on the UK new vehicle market during September 2018 which was expected to continue for the remainder of the year.
Whilst the resultant new car supply imbalance is continuing, growth in our used car volumes and margins given supply constraints in the new car market, combined with further revenue growth achieved in aftersales, has given us more confidence over the expected outcome for the year.
The conclusion below isn't terribly helpful. They should have mentioned market expectations, not last year's figures;
As a result, the Board now expects continuing underlying profit before tax for the year ending 31 December 2018 to be ahead of the Group's record results reported last year.
Still, I suppose it's a given that better than expected trading is likely to flow through into better than market expectations profit. Why couldn't they have just said that? Extra work has been created now, as I have to look back at last year's results.
Adjusted continuing EPS was 26.9p last year. Stockopedia shows 23.7p consensus forecast for this year. So it looks as if we could be looking at say 28p-ish for this year? That's quite a big beat against forecast, if my numbers are correct.
At 156p per share, I make that an estimated PER of 5.6.
I can't find any updated broker forecasts today, so please treat my guesswork above with caution.
My opinion - this looks a potentially excellent opportunity to pick up some bombed out shares in car retailers. We now know that the supply difficulties haven't really had any impact, as margins have increased - makes sense really doesn't it? If supply is constrained, then you don't need to offer discounts to customers.
My sector pick remains Vertu Motors (LON:VTU) (in which I hold a long position). But Marshalls looks an excellent choice too. I don't think there's a lot to choose between the listed car retailers actually.
Consumers seem happy to shell out on big ticket items like cars & houses. So again, I'm scratching my head as to why the media keep telling us that everything is doom & gloom, when it isn't? The answer could be that the pressure on the High Street from internet migration of sales, is dominating the headlines. The negatives get reported, but the positives (of booming sales at internet companies) doesn't get reported.
As regards cars, the market has totally changed in recent years. Most sales are not sales, they're leases - which are available at very attractive prices - e.g. brand new Mercs for £259 per month (plus a deposit). It makes more sense to run a brand new, leased car, than some old jalopy that's costing a fortune in repair bills. For this reason, I'm positive about the prospects for car dealer shares - and they're so cheap right now.
Downside risk? As always, it's supply chaos if Brexit goes wrong. That would only be temporary though. Overall then, this looks a good buying opportunity to me - things are improving (a lot, by the sounds of it), but the stock market hasn't reacted much yet.
Renold (LON:RNO)
Share price: 36.6p (up 5.8% today, at 14:35)
No. shares: 225.4m
Market cap: £82.5m
There seems to be a solid turnaround underway at this industrial chains & gearboxes group.
Interim figures today look good - underlying adjusted operating profit is up from £6.0m to £8.2m - remember this is just for 6 months.
Outlook comments - positive;
The Group is well diversified and order intake has remained stable in the face of an uncertain macro-economic backdrop and order books remain robust.
As a result of continued momentum from the first half of the year, the Group is currently on track to deliver a result for the full year slightly ahead of the Board's previous expectations.
Balance sheet - as previously reported here, this is a major issue. Specifically the huge pension deficit. So you cannot correctly value this share without adjusting for this. Hence the apparently bargain low PER, isn't quite so attractive once adjustments are made.
The pension deficit is swallowing up cash that could otherwise pay divis.
It's quite capex-intensive too.
My opinion - I would love this share if there wasn't such a large pension deficit.
There are no divis at the moment, but the management seem to be signalling that divis should start at some point in the future.
Providing you properly get your head around the pension deficit, then this share is still worth considering, in my view. It looks a fundamentally good business, generating decent profit margins.
I have to leave it there for today, as I have a company meeting in London later this afternoon.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Reacher - thanks for highlighting that re Patisserie Holdings (LON:CAKE).
Lots of emphasis on new CEO being a turnaround specialist so looks (to me) as though the company has NOT been making profits for some time. That would mean the missing funds are a result of largely overstated profits rather than the CFO salting away money for his own benefit.
But how is it possible that more of the board couldn't have been aware of what was going on.
Further development at Patisserie Holdings (LON:CAKE) with the resignation of Paul May CEO and appointment of new CEO. Very little details about Paul May's resignation.
https://www.investegate.co.uk/patisserie-hldgs-plc--cake-/rns/resignation-and-appointment-of-ceo/201811151255045097H/
Does anyone have the address and times for the Learning Technology event today. It is frustrating that it is not shown on their website. I have emailed and called them but am still none the wiser.
Would have really liked to post this on today's placeholder but it has not appeared.
Yeah, good point. With Asia expanding rapidly there must be quite a few airports which suit type of aircraft quite well. Not sure how much can be realised though - a new Q400 has a list price of $32.2m, and the fleet is on average 10 years old. The NBV covers 85 aircraft, which is not much per piece. That said, it would be a significant amount relative to company valuation.
I can see this being a case of all or nothing. Rumours of IAG or Easyjet taking over seem a bit far out of the mark.
Easyjet have already purchased the Gatwick slots. IAG already divested itself a long time ago of its 'BA Connect' type operations.
The thing is no doubt they are very convenient for some people. But that doesn't translate into profitability. If they disappeared overnight, nobody would seek to re-invent them. The marginal routes would simply not run any more, the good routes would be jumped on by others. Airports like Norwich, Exeter, Southampton can accommodate the A319.
It might be better for Easyjet to wait rather than takeover for pittance, and then have the public outcry as they cull a load of jobs.
I agree with Paul though, it might be fun for a punt. The debt position is secured by aircraft values, and somewhere in there there is the core of good routes - I would guess that average load factors are being dragged down by the poor ones.
Have to agree with Paul on his analysis re Ab Dynamics (LON:ABDP) and stop losses. I held the stock at the beginning of the year and had an automatic stop loss in place and was caught out by the volatility in January (evident on Paul's chart). I was still in profit to the tune of c. 100% but am now very frustrated to miss out on another C. £5.00 increase in the share price having not been able to get back in at a decent price! This along with a similar but less damaging stop loss on Computacenter (LON:CCC) prompted me to ditch automatic stop losses altogether replacing it with stock alerts (using Stockopedia) and taking a manual decision as to whether to sell. Downside of that is rapid falls due to profit warnings (Royal Mail (LON:RMG), Keller (LON:KLR), Numis (LON:NUM) to name but 3!) and the current volatility in a downward direction of many apparently solid companies means that a lot of the portfolio is sitting at a significant discount to cost. Stockopedia's 'Profit Warning Guide' advises selling on a profit warning is the best course of action. Unfortunately loss aversion and the hope that thing will improve if you wait long enough is a strong behavioural bias to overcome!
Sorry about the thumbs down, was on train and a jolt caused me to miss the thumbs up.
Great work and interesting reading as usual.
Flybe do fly where we want to go and from where we want to go. The Norwich to Exeter route is a winner for us. Far quicker, far easier and far cheaper than road or rail alternatives. Suits a Turbo Prop aircraft. Niche or what?
Ditto Lord Gnome - us Channel Islanders, especially Jersey, would be stuffed for tourists in the summer without Flybe. It is highly unlikely Easyjet would be able to run any of their summer routes out of Jersey with an Airbus. As for Guernsey, the runway isn't long enough for anything but the aircraft used by Flybe. It's these sort of communities that Flybe is best serving, where their presence is essential. Fingers crossed they are still here next year; aside from being a shareholder, I need them to get off our rock!
Flybe (LON:FLYB) ditto re Isle of Man. 4 x pd to Manchester. Same to Liverpool. Less so to Belfast. Very important to us. Just restarted a base here so the first flights out in the morning are from here, not return flights from somewhere else.
Also remember that the turbopros were supposedly very fuel efficient, getting to cruising heights and speeds quicker than jets .....or so the company claimed, especially significant on shorter regional journeys in UK where a few minutes here or there are less important.
Flybe continue to fly to and from places where customers 1 do not want to fly and at 2 prices that customers do not want to pay. They have an option to go low cost, but, because of 1 they cannot.
I link to Loganair's comments in March 2018 when Flybe stepped away from competing with them https://www.loganair.co.uk/loganair-responds-termination-flybes-competition-across-network/
says it all
Still my Dad always liked the champagne
Just sent this tweet out re Flybe (LON:FLYB) if £50M that's a doubling of sp
Bought #FLYB as #STOB would have had to pay £125-150M in Feb but maybe £50M now? Stobart operate Southend Airport, franchise routes for Flybe/Aer Lingus, aircraft leasing op and ground handling bus inc Easyjet at Stanstead. Synergies obvious. Also hold #STOB up tdy on expectation
3:55 PM - 14 Nov 2018
Great stuff Paul - Thanks.
Re: New factory, I recall but I may be wrong that IQE did something similar recently - Still a valid point of course but one which may not be as clear cut, assuming my memory on IQE is not way off.
Indeed when I read Paul's paragraph on Capex, I mentally added the footnote "unless they happen to be a supplier to Apple!"
More seriously of course that situation is far from played out and whilst I wouldn't be optimistic about the share price in the short term, the medium term potential there remains strong imho.
Just the recap on that this time last year IQE (LON:IQE) raised £95m with a placing at 140p in order to buy a new reactors to meet the growing demand - with the share price now at less than half that level it hasn't been a successful investment so far In truth though that is a multi year investment to meet demand over a longer period.
Zotefoams (LON:ZTF) recently discussed here is another example where they have been investing heavily in capacity to meet growing market demand I am expecting continuing progress over the coming years.
More generically I seem to recall reading something from one of the (other) gurus that looking out for step change increases in capex leads to out performance. I have in mind that it may have been Peter Lynch, but I cannot seem to track down the piece nor much research on the subject.
Is anyone aware of this or any studies on the subject?
Hi Paul,
Whilst reading your piece on ABDP something jumped out at me when you said "Capex has dropped from £8.0m last year, to £3.7m this year. This relates to a new factory, I believe. This is an interesting point to note for the future - ABDP said some time ago that it was facing demand that it could not fulfil, due to capacity constraints. It's built a new factory, and now sales & profits are soaring. We must remember to buy any shares in future when a similar situation arises. I didn't fully appreciate how significant that point was, a few years ago"
Is it not fair to say that Treatt is doing exactly this? i.e building a new factory to increase production efficiencies and increase capacity in the face of increased demand?
I recall in you last review of a recent TET RNS you were not sure why you wold want to invest in the share at this time?
Anyway just food for thought, many thanks for the excellent write - ups.
DG
Ab Dynamics (LON:ABDP) is currently building another new factory (it's in planning) about the same size as, and just over the road from, the one just completed (3000m squared) and has also leased 950m squared in Germany that it is currently optimising.
Thus, when Paul says "Ab Dynamics (LON:ABDP) said some time ago that it was facing demand that it could not fulfil, due to capacity constraints. It's built a new factory, and now sales & profits are soaring. We must remember to buy any shares in future when a similar situation arises", it is worth noting that Ab Dynamics (LON:ABDP) itself is, in fact, in just that similar situation once again.
Effortless - Yes Ab Dynamics (LON:ABDP) are clearly on a roll and are in the right place at the right time. Their latest results indicate a widening moat and the Mr Market is responding accordingly. I note this morning that the Stocko algorithms have produced a significant Quality score upgrade of +25 to 92 too. What a great business and I continue to hold. Ian
Thank you Paul for your thoughts on Flybe.
This Airline is important to UK domestic routes and it is a real puzzle just how low the SP has gone.
The next few days and weeks are going to be fascinating but I am not selling.
Flybe is certainly solvent as you say it is really all about the Management in my opinion.
Agreed. I fly Flybe quite a bit (but then I do live near Exeter). But it does have coverage of large parts of the country that are not otherwise served. It's certainly niche, and that's clearly part of the problem - the volumes are not massive, but it would leave a big hole if it disappeared, which makes me think something is likely to survive.
Problem is for Flybe is that troubles might become self-fulfilling.
Would anyone be booking £300 summer sun flights now when they couldn't be sure if the airline would be around to fly them?
The winter period is a testing one for them.
The only value I can see in them is their fleet. But who would want that many turboprops?
That's a good point Snoo. They really need to manage the media. None of the articles I've read have picked up on the balance sheet of Flybe, which would give customers (and investors!) comfort. It also hasn't helped that they have been subject to negative press in the form of a pilot who developed a fear of flying and sued them for unfair dismissal. Then there's the ridiculous story that one of their aircraft "plunged" 500ft in 18 seconds (most pilots can do this quite easily in a Cessna!)
P.s. thanks Paul - certainly validating my investment (or punt!) case
I would argue thre turbo props are in high demand, for anyone who follows Avation (LON:AVAP) would remember they were being offered an attractive 'above value book offer' for half their fleet of turbo props, at some point last year. Which Avation (LON:AVAP) Declined. Also they seem to have a constant orders placed with ATR to keep up with demand for regional airlines in Asia.
So I would imagine these would be snapped up quite well.
AIM shares are excempt from stamp duty.. Main market shares and foreign shares are liable for it.
https://www.londonstockexchange.com/traders-and-brokers/private-investors/stampdutyexemption/stampdutyexemption.htm
Hope that helps.
Many thanks, Banzii
As it's a dull day, perhaps I may be excused an off topic question. Please could somebody tell me when stamp duty is applied. My broker seems to charge at random - 5 of widely different purchases out of the last 20. ( I don't want to ask him in case he charges them all.)
As well as AIM shares, ETFs are probably the most common case you'll come across.
In addition some overseas shares are exempt from UK Stamp Duty - I think the requirement is that they both have to be incorporated and have their shareholder register abroad. However you may have to pay non-UK stamp duty, e.g. Irish at 1% (except ETFs).
Note that AIM shares avoid stamp duty even if they don't avoid inheritance tax (e.g. dual listed or investment companies), or if withholding tax makes them unappealing for this purpose.
Easier surely to contact the broker and pay what you owe if stamp duty is due on any of the purchases they've not been levied on?
ie Being honest!!
Dull day on mkts. Things I noticed:
Debenhams fell to just 5.5 pence this morning. Sad. Once worked in the buying office. Once star performer IQE fell below 60p today. Europe is not doing very well at the moment:
"Germany's economy slammed hard on the brakes in the third quarter, as car makers struggled to adjust to a new emissions-testing protocol and tussles over trade rules undermined exports.
Fresh data published Wednesday showed that Europe's economic powerhouse registered its worst performance in five-and-a-half years, according to the Federal Statistical Office".
Flybe (LON:FLYB) please. There has been an extraordinary spike this morning, 43% up and then just 2% up.
Great results from AB Dynamics (ABDB) today. Stonking in fact!
Marshall Motor Holdings (LON:MMH)
Unscheduled TU - " the Board now expects continuing underlying profit before tax for the year ending 31 December 2018 to be ahead of the Group's record results reported last year."
The continuing adjusted EPS last year was 26.9p - current forecast on Stockopedia 23.7p so looks like quite an upgrade.
Also there are broker upgrades on Research tree and an interview on Brr - driver is used car and aftersales - some evidence of switching from new to used due to supply problems.
Phil
Seeing Machines (LON:SEE) - AGM Statement. Provides a good summary of (non-financial) progress, but no news. Chairman hasn't quite got the hang of writing in paragraphs (although sentences better than mine). I maintain they will probably need to raise more cash and it could be at an inopportune moment.
Caledonia Mining (LON:CMCL) - 3rd quarter results. Variations in production look like noise to my untrained eye.
Mentions cost inflation and warns over being able to obtain hard currency both for supplies and to pay dividends. The Zimbabwean president's piece in the FT yesterday mentioned the importance of gold miners for exports so perhaps they are safe...?
https://www.ft.com/content/a8f8294e-e689-11e8-8827-ff56e7163c11
Leo. Caledonia Mining (LON:CMCL) are due to present at sharesoc in London this evening, I believe.
Hi Leo, I think we've exchanged on Caledonia Mining (LON:CMCL) before.
I've owned for few years from just above 200p. I plan to hold for longer as I see self-actuated path to significant earnings growth that looks very attractive relative to current valuation and expectations.
That said, CMCL suffers from 2 binary risks: 1) Zim; and 2) It is currently a single shaft mine.
Zim is highly unlikely IMO to repeat exactly the same crisis as before...doesn't mean it won't have crisis of course. At the moment some of the problem seems to be massive embezzlement leading to a shortage of dollars relative to what there should be.
Within a portfolio I can diversify those risks. I actually run a mini portfolio of 3 African gold producers to diversify general African political and economic risk (Shanta Gold (LON:SHG) and Pan African Resources (LON:PAF) too).
I think all 3 have the ability to make good revenue growth, earnings growth, cash flow production and enhance reserves. Admittedly, PAF have been a bit slow and hubristic to that. The other two (and now PAF) are very focused on capital stewardship and making returns for shareholders (partly as they have learned it the hard way). Near term I think SHG have the potential to surprise the most as they clean up balance sheet and (my guess) relations warm with Tanzanian govt. But DOYR...not a stock for the fainthearted plus illiquid.
I'm not a gold bug but I also hold a significant position in Ruffer Gold fund. I generally got interested in gold miners for 2 reasons: 1) I believe 3 years ago gold miners were one of only few industries globally that had gone the cleansing effect of negative capital cycle (strange monetary policy and market impact of that have forestalled cleansing in most industries); and 2) I also hold some gold stocks as I believe the gold price will benefit from the unravelling or denouement of this phase of radical monetary policy following 2008. Its my opinion that we are living through the demise of the USD as financial hegemon.
Excluding dividends I'm up about 60% on this basket (down about 20% SHG, flat PAF, up 110% CMCL and 80% Ruffer). Its been painful for last year plus as at peak I was up about 150%!! (I took the SHG position more recently so it was the other 3)
NB the other obvs problem with gold miners, particularly small ones, is their visible limited life. This means that perpetual hope valuation finds it much harder to find its ways into these stocks than others. It happens every now and then and that is linked to the commodity. A gold price above $1400 would see the hope valuation flood in particularly given the underlying leverage to the price
Would be interested in hearing any thoughts on Renold (LON:RNO). Their share price got hit hard around march time after machine break downs, which seemed like a fixable problem. Interim results this morning are solid but not earth shattering. on a PE of 6.73 looks like good value and a a good chance in recovery. Biggest concern is the big pension deficit though now currently at around £100m? is this enough to keep the share price depressed at this valuation?
With rising interest rates and also longevity rates stalling (and reversing) might we see the pension deficit drastically reduce in the near future with Renold (LON:RNO) ?
My morning smallcap tweet: Flybe sale, the whole lot.
Flybe (LON:FLYB), Science in Sport (LON:SIS), Cambridge Cognition Holdings (LON:COG), Falanx (LON:FLX), Marshall Motor Holdings (LON:MMH), Ab Dynamics (LON:ABDP)
Flybe Group (FLYB) yet another airline sale, of itself this time. Looking at "further capacity and cost saving measures, initiatives to strengthen the balance sheet and preserve cash resources, as well as a potential sale of the Company". Also H1 adj pretax £14m (£9.4m). Excluding the impact of the E195 onerous lease, adjusted pretax £9.9m (£9.2m, slightly ahead of guidance given in the October. Outlook: weak £ and higher fuel prices have driven up the cost per seat, softening of market growth. Despite this, bookings remain up.
Science in Sport (SIS) Buys PhD Nutrition for £32m. £29m placing at 60p, a 14% discount. PhD has rev of £20.8m and adjusted EBITDA of £2.8m PA.
Cambridge Cognition (COG) $750k contract over 1 year. It's the largest eCOA contract won.
Falanx Group (FLX) H1 rev £2.2m up 51%, slightly lower than mgmt expectations. Has regained strong momentum in existing business activities during H2.
Marshall Motor Holdings (MMH) better than anticipated trading during October 2018 and a more positive outlook for the remainder of the current financial year. Now guides continuing underlying FY pretax up YoY.
AB Dynamics (ABDP) FY rev up 51%, adj pretax up 45%, EPS up 74% to 36.29p but a miserly 10% FY div inc to 3.665p.