Small Cap Value Report (Wed 22 Aug 2018) - ALY, RBN, HEAD, PHD, SPO

Good morning everyone!
There were a lot of RNS announcements to sort through this morning. Thanks for the suggestions, and keep them coming, as they help me figure out where to focus on.
My provisional list for today is as follows:
- Laura Ashley Holdings (LON:ALY)
- Robinson (LON:RBN)
- Headlam (LON:HEAD)
- Proactis Holdings (LON:PHD)
- Sportech (LON:SPO)
Cheers,
Graham
Laura Ashley Holdings (LON:ALY)
- Share price: 5.25p (+21.5%)
- No. of shares: 728 million
- Market cap: £38 million
Good news has been scarce for Laura Ashley shareholders. Today makes for a welcome change.
It's amazing how far a share can fall when it suffers is a loss of faith. Collapsing profits don't help either, of course.
For me, the most significant aspect of today's news is the disposal of the Singaporean property. This very strange asset has been an eyesore for existing and prospective investors such as myself (I owned ALY shares from 2014-2015).
When the property was purchased, back in June 2015, ALY's share price was 22p. Most of the value destruction since then has been related to weak trading, but some of it has been due to question marks over the company's move into property ownership.
It has been sold for SGD $54.5 million (£30.3 million), after being valued at SGD $56 million.
It was bought for SGD $66 million (£31.1 million based on exchange rates at the time), having been independently valued at $65 million.
Singapore commercial property prices (for office space) are down by just 4% since June 2015:
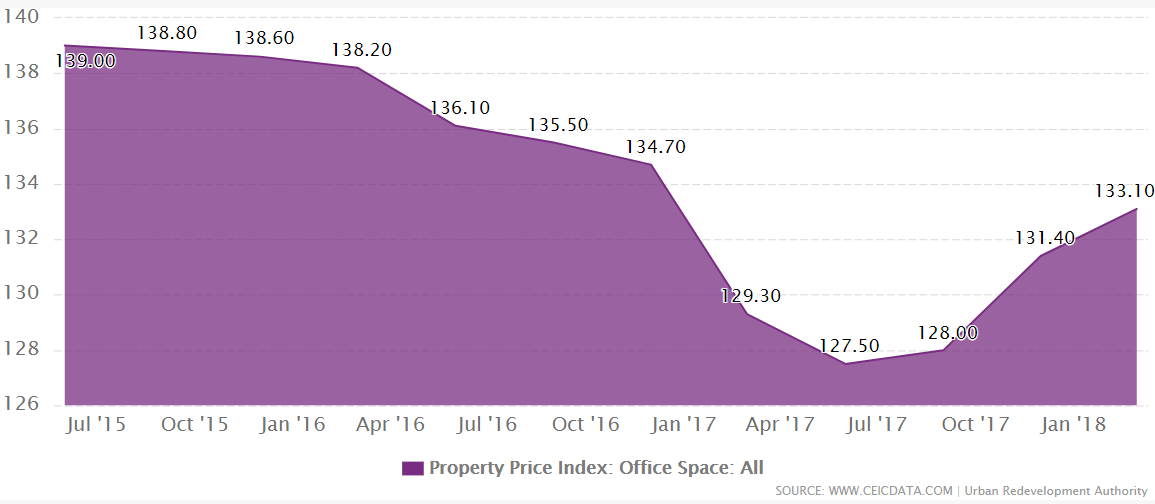
Yet the value of Laura Ashley's property has allegedly fallen by 14%, and it is selling it for 17% less than it paid for it.
Bad luck? I guess we have to conclude that it's just bad luck.
The infusion of £30 million from the sale will make a big difference to the balance sheet, assuming that shareholders vote the deal through (I estimate that 444 million shares are held by the Malaysian chairman's companies).
At June 2018, ALY had bank borrowings of £20.1 million associated with the property and an overdraft balance of £11.4 million.
The disposal should wipe away almost all of this and leave us with a nice clean balance sheet.
Trading
Today's report draws a picture of trading which is weak, but not awful.
- Like-for-like retail sales down 0.4%
Within this, fashion is doing well (+9.7%). But fashion only accounts for 17% of UK sales.
Home accessories, furniture and decorating were all down.
- International sales (franchising and licensing) down 13% to £18 million.
It's a shame to see this going in the wrong direction. Franchise and licensing revenue is high-margin, making a big contribution to profitability, and the Asian expansion is supposed to be a source of growth.
There are signs of growth - new stores in Thailand and a greater presence on Chinese platforms. Hopefully this will turn around.
Outlook
Current trading is in line with expectations.
My view
My view is pretty simple. Along similar lines to the position at French Connection (LON:FCCN), ALY needs to shrink its retail operations, and in particular its stores:
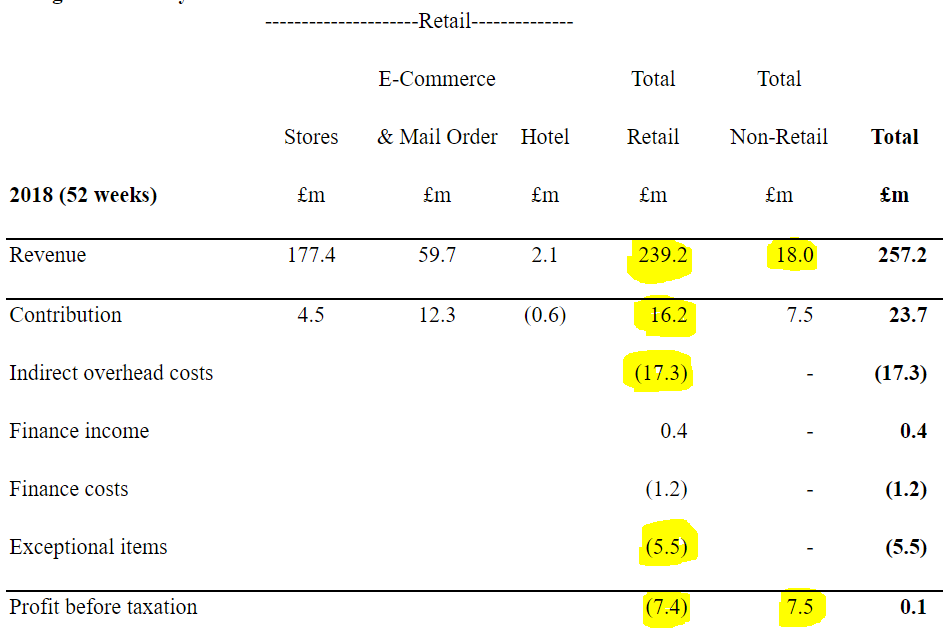
The pre-tax loss from retail is £7.4 million, and is still a loss even if we add back the impairment charge from the sale of the Singapore property (included within exceptional items).
Last year, it was a similar story: retail made a loss even if you added back the exceptional items.
Franchising and licensing, on the other hand ("non-retail"), are consistently and highly profitable.
The number of UK stores has reduced from 205 at January 2015 to 160 at June 2018.
That seems like good headway to me. But the company is promising to open two new stores and close only five stores over the coming year - wouldn't it be better for shareholders if the estate were to shrink much faster than this?
Like-for-like e-commerce sales grew by just 4%. I would have hoped for more, if the websites were really firing on all cylinders.
In summary, I think it is possible to make an argument for investing in this at current levels.
The cloud of the Asian property has been removed, albeit at a loss and with some nasty costs associated with its disposal. But that is a positive development.
The franchising and licensing operations are still profitable and the outlook for them should be good long-term. They require very little capital and are extremely high-margin.
The e-commerce business is growing at a slow pace but has ok margins.
The question for me is whether the retail stores are going to be the dead weight that eventually sink the whole thing.
If I had no UK retail exposure in my portfolio at all, I wouldn't hate the idea of owning a few shares in this, as a contrarian play. But I am carefully limiting my exposure to this sector. There are a lot of cheap retail shares at the moment, for the very good reason that their business models have been disrupted by online shopping and/or their brands are tired.
The StockRanks identify this as a Value Trap.
Robinson (LON:RBN)
- Share price: 75p (unch.)
- No. of shares: 17 million
- Market cap: £12 million
We've occasionally covered this plastic and paper packaging manufacturer. I've suggested that it could be a value play, though probably requiring a lot of patience for value to out.
The underlying business looks solid, but nothing extraordinary. It's hard to imagine that making plastic bottles or paper boxes is going to earn above-average returns on capital.
Reviewing its historical returns, I see that it briefly earned ROCE in excess of 10% during the 2010-2012 period. Apart from that, returns have been very modest.
Let's review the contents of today's update.
Trading:
- revenues up 15% and operating profit before amortisation increases to £530k. Not bad.
- PBT after amortisation and interest costs close to breakeven, a marginal improvement compared to last year.
Looks like solid trading, nothing to write home about but neither is it terrible.
Property:
No property realisations likely in the next 12 months.
The possibility of a big property sale has been the key value attraction with this share. But it sounds like there is going to be a lot more patience required for this to be delivered to shareholders.
Outlook:
Management are confident for 2019, with more capex due in H2 to facilitate new projects. Costs have risen but should be held steady from now:
The recent growth in operating costs (predominantly investment in people capability) has been concluded, so further revenue growth should improve profitability ratios moving forward.
My view
The rating is rather low, and the shares could easily bounce back if sales come through over the next year as anticipated and allow the company to continue paying large dividends.
It's a family business, another positive feature. This explains why it is run so conservatively and has barely diluted shareholders over its entire stock market tenure.
On the other hand, it's hard to imagine that a traditional packaging business is going to consistently earn a high ROCE. Robinson's track record shows how difficult this is.
Consequently, I intend to cease coverage of this stock until there is progress on the property disposals or some other major news.
Headlam (LON:HEAD)
- Share price: 441.8p (-2%)
- No. of shares: 85 million
- Market cap: £374 million
Headlam Group plc (LSE: HEAD), Europe's largest distributor of floorcoverings, is pleased to announce its interim results for the six months ended 30 June 2018
You can check the archives for our previous comments on this share. It's been a frequent topic of discussion!
Let's dive straight into today's numbers:
- like-for-like UK sales down 5.2%, like-for-like continental Europe sales up 1.7%.
- small improvement in margins
- underlying PBT up 0.9% to £17.7 million
Another example for us today of solid trading in tough conditions.
M&A
The company continues to engage in lots of acquisition activity.
Last year, it made three acquisitions, including a £35 million deal. This year, it has made another three acquisitions so far. They aren't terribly big. But the company has a pipeline of further deals it is considering.
Outlook
Headlam has hinted a couple of times already that it could miss 2018 forecasts, if market conditions get any worse.
It is now confirmed that we should expect numbers to come in at the lower end of forecasts:
...given the ongoing softness in the UK floorcovering market and the associated trading impact on the Company's UK businesses coupled with the current indications that these conditions are likely to continue during the second half of the year, the Board now expects that the full year outcome, whilst ahead of the full year 2017 will be towards the lower end of current market expectations.
My view
It's yet another cheap retail-type stock (a distributor to retailers).
Public forecasts are for EPS of 42.6p in the current year. So the multiple is good and cheap.
I like this stock a bit more than others in the general retail space. It has a market-leading position and serves a crucial logistics role for its customers.
When you are buying into Headlam, you are buying into its ability to manage warehouse capacity, commercial vehicles and customer relationships. Its track record suggests that it is good at what it does.
It's another stock I might have considered, but again, I don't want my portfolio to be overly tilted to this sector. Economic conditions could get a lot worse before they get better, and I don't want my portfolio to blow up because I couldn't resist a bunch of cheap retail-oriented stocks just before we had the mother of all consumer recessions.
I'm happy to own a few of them (like Next (LON:NXT) ), but not too many.
I suppose what I'm doing is similar in spirit to what Ed does with the NAPS portfolio. His rules allow for at least 1 company from each sector, but no more than 3. The idea is the same: don't allow your portfolio to get battered if one sector happens to do a lot worse than you expected.
My other slight niggle with regard to Headlam (LON:HEAD) is that acquisitions tend to make me nervous, and Headlam has been doing an awful lot of them, with more to come.
So I maintain a watching brief only.
Proactis Holdings (LON:PHD)
- Share price: 103.5p (+2%)
- No. of shares: 94.5 million
- Market cap: £98 million
Proactis Holdings PLC, the global spend management and B2B eCommerce solution provider, reports a detailed update on trading for the financial year ended 31 July 2018 further to its initial update on 7 August 2018.
This is a tricky one. It provides business software used in sourcing, negotiating and purchasing from suppliers. I've been trying to catch up on the story by watching the video at PIworld.
It had a massive reverse takeover last year, at a racy valuation.
When the deal was announced, its share price shot up from 175p to 196p on initial excitement.
But it then lost two of its three largest customers, and the share price has suffered ever since. Revenue forecasts have been trending lower this year.
Key points from today's announcement:
- Guidance for FY 2018 (ending July) unchanged since the most recent update.
- Customer retention has "improved" and is now at "more normal" levels (probably still worse than average, I'm guessing).
- FY 2019 to show "normal, stronger" revenue growth
My view
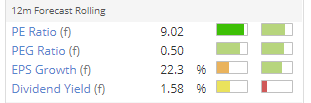
I can't deny that this is cheap relative to prospective earnings.
The CEO made the case in June (in the video linked to above) that the company could make more acquisitions, despite losing those two large customers.
I'm not interested to buy an acquisitive B2B software business, so I'm not going to look into this any further. Lots of research is needed to understand what is going on with this one, I feel.
Sportech (LON:SPO)
- Share price: 66.9p (-3%)
- No. of shares: 187 million
- Market cap: £125 million
There have been all sorts of developments at this international betting software group over the past year or two. It deploys thousands of betting terminals for hundreds of clients around the world.
Let's focus on the present and future:
- New CEO & CFO
- Cash of £12.5 million, no debt, also received £2.5 million post-period end for a disposal.
- Small increase in revenue from continuing operations, using constant FX (£31.6 million).
- Small loss from continuing operations
There is a major US opportunity in sports betting after the law was relaxed at federal level. A direct-to-consumer offering is being built in Connecticut with the help of a data/risk management/technology partner.
The new management team are based in Toronto, helping to reduce corporate costs by 39%. Maybe this could ultimately get bought out by North American investors and/or get listed on that side of the pond?
Tax affairs continue to rumble on:
Following the successful Spot the Ball VAT reclaim, the Group is aware that HMRC are closely examining all the Group's tax affairs. The Board, after taking professional advice, believe the liabilities recorded in the financial statements are correct, and whilst they are open to challenge, the Group's position will be defended robustly.
My view
The numbers aren't pretty yet but with a big US opportunity and an established global business, I think there could be a lot of value that's not immediately apparent. Worth looking into.
Time's up for today, thank you for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Three points regarding ALY.
First, the shrinkage in stores numbers was (I believe) largely to do with the acquisition of Homebase by Australian group Wesfarmers (a value-destructing head case if ever I saw one - and recently disposed of to ?) who ousted the ALY in-store implants. A real Loose-Loose?
The second is the brand's nowadays dependence on frequent "SALES". No patient woman in their right mind pays the sticker price and their sales revenue is now driven by Sales at presumably significantly depressed margins.
The third is their ineffectiveness at on-line Clicks & Mortar trading - and IT in general. My information is three years old but they were hopeless then on leadtime; maybe they have now massively improved?
Hi Graham,
Re Laura Ashley Holdings (LON:ALY)
"That seems like good headway to me. But the company is promising to open two new stores and close only five stores over the coming year - wouldn't it be better for shareholders if the estate were to shrink much faster than this?"
Yes but it aint that easy if they are paying above market rents with lease expiry not in sight. They may be paying £x a year for a store in rent/rates/service charges but if it is losing 20% £x it is still cheaper to keep it trading. The only way to get rid of an over rented store other than a CVA is to pay a very big bung, known as a reverse premium, to an ingoing tenant if they can find one that fulfills the landlords financial criteria/user quality etc.
Interesting if Paul could establish their lease obligations?
I also think that whereas the brand being Old British, goes down well in Asia it does not appeal to the vast majority of UK consumers. So may pick up enough customers in a very large city or an up market ruralised town but probably nowhere else?
Their product being very expensive does not lend itself to online sales as much as say fast fashion does.
Dave
Also looking forward to views on Headlam (LON:HEAD) and Laura Ashley Holdings (LON:ALY)
ALY does seem to have a lot of attractions - there is value in the brand and we could potentially be looking at 4m profit next year, if the disposal losses don't repeat and finance costs removed, which would put them on sub 8 multiple with a solid balance sheet.
Current trading looks OK with room for international expansion and if the franchise model takes off, then can be very lucrative for franchisor.
Separately, may I make a request for Epwin (LON:EPWN) who issued a trading update today. Looks very cheap with no obvious red flags. Further, given the number of residential new builds (at least in London), I agree with their medium term positive views. At 28m EBITDA, they are looking at 5xEV. Dividend covered by earnings, Op Cash and Free cash.
I hold Norcros (LON:NXR) and did a comparison and on metrics - think I prefer this given lower debt and cheaper.
Would welcome any views.
Hi Sharmvr
Epwin (LON:EPWN) - I thought their main focus was replacement windows, not new build? New buildings have to have windows, but one can soldier on with old ones for another year......
My understanding of their business was general repair and maintenance of buildings, and specifically the exterior facades of such buildings. Windows and doors being a big area.
Agree that they can go a while, but building managers make decisions in this regard and they typically have maintenance cycles, and since it is paid through residential service charge, price sensitivity is less of a concern (since payer doesn't negotiate price)
In public housing, there is potential work for cladding replacement off cycle courtesy of Grenfell and what I expect are more stringent health and safety, which could extend to more regular maintenance / replacement.
In private sector, as I say at least in London there are a lot of buildings that have been put up over the last 3-5 years, and might be due a facelift!
Quite new to the company but think there might be some promise there - will reserve judgement until I have done more research, but certainly think it is worthy of research
A previous red flag for Epwin (LON:EPWN) was its relationship with Entu (UK) (LON:ENTU) (maybe read back past SCVR reports if you're not aware of the issue already). It's left a sour taste in my mouth not to be tempted by Epwin (LON:EPWN) for now.
Thanks Paraic - was not aware - appreciate the pointer, will take a look
V
Highly speculative loss making Company Appscatter (LON:APPS) raises £1m in new equity at 70p per share.
Current share price is c.40p per share.
Anyone know how this works!? and why institutions would pay such as premium. Does it make the shares somewhat of a 'bargain' as PIs are able to buy in the market cheaper than the big boys or is there something funny going on !?
Answers on a postcard...
Appscatter (LON:APPS)
Hello nicobos
I have only had a quick look but I am pretty sure this is all related to the acquisition that was announced back in April when handily the share price was much higher. presumably some deferred consideration via share issue type transaction.
I also think ALY is interesting, at 5p you get a lot of shares for very little cash and in say 10 years or so who's to say were they might be?
They are implying this company will be profitable and debt free after the office sale. (rare thing that)
It is a decent if not great brand and if someone good got hold of it....
The market crash was 10 years ago and people still feel that every day, I am scared this could be say 200 and
I look back in 10 years and saying I remember them at 5p.
I'm thinking its got to be worth a small punt, I've done worse things.
TechMarket View comments on Proactis Holdings (LON:PHD) that "The company has the strategy, market reach and the portfolio to regain its momentum, although this will not happen overnight."
Good morning!
Not wishing to pre-empt Graham's comments, but Laura Ashley Holdings (LON:ALY) looks potentially interesting. The bizarre decision to buy a freehold office block in Singapore seems to have been reversed. I like that - it de-gears the balance sheet, as previously there was a mortgage on the property, which created a somewhat lop-sided balance sheet.
My initial skim of today's results statement is quite positive - profits are down, but it's amazing that ALY is still profitable at all. On a recent store visit, the product struck me as outrageously expensive, and nothing special. But there again, I am more of a Primark man, when it comes to fashion, and decor. The one area where I will splash out, is bedding - so John Lewis, or M&S, for duvet sets. Cotton is less scratchy & not prone to bobbling, that you get with the vile polyester - a plague on the house of whoever invented that muck!
I'll do some more digging, but for now, I think ALY looks potentially interesting, at the current bombed out valuation. The brand is worth multiples of the market cap, in my view.
Regards, Paul.
Regarding Robinson (LON:RBN) , the company has a chunk of land that was formerly its manufacturing site, on its books as an asset. This ground is in a not very desirable part of a not very desirable area of a not very desirable town (apologies to all Spireites!). It has been up for sale for around 18 months now, apparently without a sniff of interests. I think it can be largely discounted when considering the balance sheet.
(For both Robinson (LON:RBN) and Empresaria (LON:EMR) it is worth investors considering the very large spread).
Robinson (LON:RBN)
"Property
The sale of surplus properties in Chesterfield has not progressed materially in the six-month period due to the uncertainties in the retail sector and over-supply of housing land. Current market conditions in this sector of the market are now relatively unattractive which is likely to result in any realisations being beyond the next 12 months."
Company seems to agree with you - very unusual to see the phrase "over-supply of housing land".
Another strange thing here is the debt is all bank overdraft - quite unusual as the company seems to be planning another £3m of capx in H2 - but they seem to be paying only @2% in interest - possibly something to do with the surplus land?
Phil
Headlam (LON:HEAD)
Was tempted at the time of Paul's last article but didn't go ahead - which seems, for once, to have been a reasonable decision. A solid, well run company, but it has to run very fast to stay still in its markets.
Also not sure about the appointment of Keith Edelman ( Revolution Bars (LON:RBG) Chairman) as senior independant director.
Phil
Also not sure about the appointment of Keith Edelman ( Revolution Bars (LON:RBG) Chairman) as senior independant director.
Yes, I agree. It's a sell. You can never trust a Gooner!! :-)
Si, a lifelong Spurs fan
Not quite what I had in mind Si - but hey - that might be a good reason as well.
Phil
Hi Graham,
Could you kindly include Sportech in your analysis today?
Thanks Kiewit
Yes, that's the plan! G
I think the following may be worth comment:
Headlam (LON:HEAD) seems static and should get cheaper from here. Company has made some acquisitions, but still has cash in the bank.
Empresaria (LON:EMR) also seems stagnant. The figures make it seem cheap, but they always do!
Laura Ashley Holdings (LON:ALY) online sales increased, but LFL is down. Property sold, but at less than book value. Owner is still having serious marital problems, and may be looking to minimise his assets!
Thanks
Empresaria (LON:EMR) too please, result commentary looks quite positive in parts. P/e of 6.7, debt reduced, good cashflow. It is a recruiter but seems unduly cheap.
Empresaria (LON:EMR) H1 results today. This video gives more detail (c10mins): Spencer CEO and Tim FD talking through.
Challenges: Germany and Japan legislation changes & UK prof services
Stronger: UK domestic services & marketing. Offshore rec services business India. Chile retail.
Acquisitions doing well, strong performance from: Rishworth Aviation, ConSol Ptnrs & Pharmaceutical Strategies.
https://www.piworld.co.uk/2018/08/22/empresaria-group-emr-h1-results-august-2018/
Another one for Headlam (LON:HEAD) Graham please sounds like ground being laid for mild profit warning further down the line, net cash seems to have halved but guessing thats gone on the recent aquisitions.
Thanks
Proactis Holdings (LON:PHD) Proactis Holdings PLC
Proactis Holdings PLC, the global spend management and B2B eCommerce solution provider, reports a detailed update on trading for the financial year ended 31 July 2018 further to its initial update on 7 August 2018.
This re-organisation has delivered net annualised cost savings of approximately GBP5.0m at 31 July 2018 and were anticipated at the time of the acquisition of Perfect Commerce, LLC on 4 August 2017 (the "Acquisition").
Deal intake for the year was strong. Proactis secured 64 new names with a total initial contract value of GBP8.7m (2017: 54; GBP4.1m) and 120 upsell deals with a total contract value of GBP3.6m (2017: 110; GBP2.8m). 55 of the 64 new names (2017: 44 of the 54) were subscription deals with the remainder being perpetual licence deals. This performance was at the Board's expected levels across all territories.
Any thoughts welcome.
Jon
Proactis Holdings (LON:PHD) has approximately 1,000 customers
So with 120 upsell deals it looks as it 12% of existing customers bought more product, which is encouraging
Most encouraging is the huge increase in average deal size for new names, from £76K to £135K
My only concern is the Balance Sheet - the next acquisition will have to be Equity financed
Proactis Holdings (LON:PHD)
Could this be in value territory now?
I don't hold, and have felt negative about it previously - it didn't seem to be making progress, free cash flow seemed low. The reverse of Perfect Commerce into it is transformative - potentially for the better. Are the historic figures misleading? SP rates it a "sucker stock".
Putting it back on the watchlist.
SundayTrader
Proactis Holdings (LON:PHD) does indeed have huge upside from here, in my view.
The StockRank will catapult upwards in October when the July18 numbers are released. Currently the Valuation rank is suppressed by the 2017 figures which were lossmaking due to £6m+ of 'non-recurring acquisition related expenses'.
As I mentioned above, the business continued it's operational momentum in the past 12 months:
"So with 120 upsell deals it looks as it 12% of existing customers bought more product, which is encouraging
Most encouraging is the huge increase in average deal size for new names, from £76K to £135K
My only concern is the Balance Sheet - the next acquisition will have to be Equity financed"
Looking forwards, I'd expect business to do as well in an economic downturn as in the current economic climate - I'd guess it will prove to be contra-cyclical.
Either the shares get re-rated else the company will likely be acquired in my opinion - the company operates in a rapidly consolidating space.
Hi Graham
Another request to hear your views on Headlam (LON:HEAD) I hold.
You weren’t so keen on their growth through acquisition when you covered them in July. Today they note an improvement in margins being helped in part by their acquisitions.
Do you see that as material?
Thanks
Jon
Hi Jon
Thanks for the comment re: Headlam (LON:HEAD)
I would say they only deserve credit for the margin expansion delivered by the pre-existing business, which was 68 basis points. Not bad, that's an extra £2.3 million of gross profits to play with. A good achievement. G
Cut and paste to today’s report given its an announcement from today.
——————-
Not sure if there is much interest remaining in Laura Ashley Holdings (LON:ALY) but came out this morning with mixed results announcement and news of the expected disposal of their Singapore trophy property/white elephant depending on your point of view. Trading results are not great in line with much of the retail market although they make a good fist of talking up their on line business.
Focusing on the property disposal, this has been sold for just over £30m representing a loss of about £1m on original acquisition cost (about £4m against carried book value) before costs with proceeds being used to reduce debt by about £20m and the rest being retained. Looking back at the original acquisition in 2015, they indicated the expected running cost of funding the property through debt which suggests the exercise has cost them perhaps a further £5m (plus the opportunity cost of tying up about £9m of their own cash in the interim). Not the best use of shareholder funds in hindsight.
https://www.stockopedia.com/share-prices/laura-ashley-holdings-LON:ALY/news/ashley-laura-hldgs-acquisition-of-property-in-singapore-urn:newsml:reuters.com:20150630:nRSd6423Ra/
Interesting brand maybe, but hard to make a case for it as a viable investment under its current dominant single shareholder ownership/management.
Gus.
Wanted to request Koovs (LON:KOOV) please - still a steaming crock or a potential turnaround situation? Depends if the dilution from today's concluded 4-year shares-for-ads media deal is priced in yet. Also Paul might be interested in commenting on Laura Ashley Holdings (LON:ALY) for good or bad - bad results, div suspended bu tthey're selling the Singapore millstone and online is up to 25%.
Thanks for the suggestion RTJ, I will try to fit Koovs (LON:KOOV) in. G
Half year results out today from Headlam (LON:HEAD). This is sometimes covered on here so would like to see more comment if you can please Graham. Revenue is up slightly but the market is tough. Market share has increased but this appears to be mostly driven by acquisitions. The UK sales numbers are down whilst Europe is up. Expectations for the rest of the year are for the lower end of market expectations (whatever they are) and the interim dividend is held. Whilst I hold this position and Paul has been keen on it in the past I don't think it is a buy at the moment.