Small Cap Value Report (Wed 5 April 2023) - NTBR, DFCH, LOOK, SDY, FRAN, DLAR, TPT

Good morning from Roland and Graham!
Today's report is now finished (10.30am). See you tomorrow!
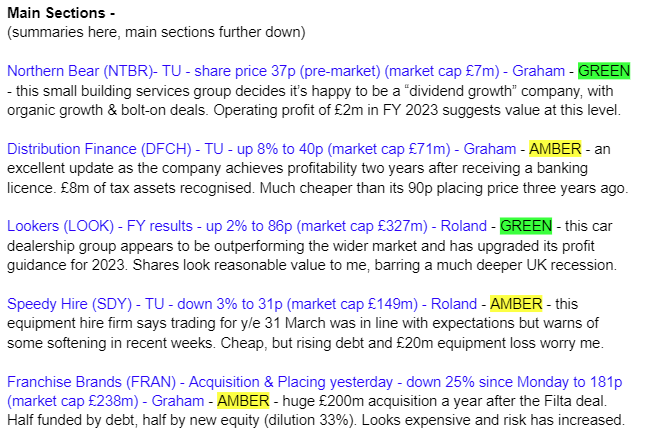
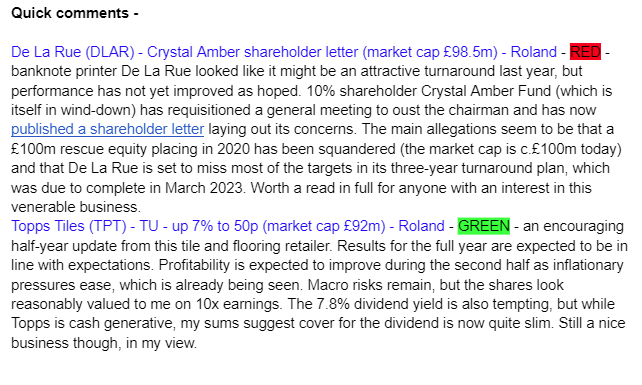
Other companies reporting today -
- Hilton Foods (HFG) - FY results/CEO £622m
- Airea (AIEA) - FY results £15m
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's Section
Northern Bear (LON:NTBR)
- Share price: 37p (pre-market)
- Market cap: £7m
I covered this building services group in some detail at its full-year results last year. Unfortunately the share price has gone backwards since then, and it’s now below our £10m cut-off. So I’ll try to keep these comments brief.
I do still want to cover this one though, because it has shown signs in the past of being a better-than-average micro-cap. However, in recent years it has written down the goodwill associated with some acquisitions, and this has impacted its official results:
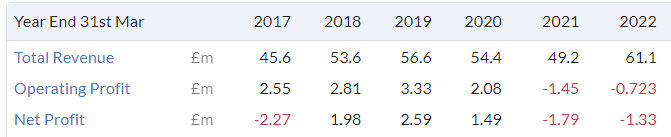
Since 2020, Northern Bear’s Chairman has been the Canadian investor Jeff Baryshnik, who has a 25% stake in the company.
When the company declined to pay a dividend last year, and said that it was studying larger acquisitions than it had made before, I assumed that Mr. Baryshnik had aggressive plans for the business. But today’s update strikes a different tone:
After a review of strategy and dividend policy, the Board is pleased to report that the Group will pursue a dividend growth strategy supported by the organic progress of the Group's businesses and, to the extent accretive, bolt-on acquisitions.
There will be a 4p ordinary dividend plus a special dividend of 1p for FY March 2023. Not bad on a 37p share price! (last night’s close).
Trading update:
…the Group has traded ahead of the prior year's results except for a provision at our Northern Bear Building Services Limited subsidiary, anticipated to be in the range of £500-£750k, to account for certain unprofitable contracts. The Board expects that operating profit for FY23, stated before amortisation, one-off costs, and other adjustments (in the format used in prior years' results, "adjusted operating profit") should exceed £2.75 million (or £2.0-£2.25 million of reported operating profit net of the provision)...
So we again have c. £2m of operating profit, or £2.75m if you’re willing to look past a few mishaps.
The company guides for a net cash position at year-end, but reminds us that this position changes dramatically throughout the year.
My view
I’ve noted many times before that this sector tends to be accident-prone, and the “certain unprofitable contracts” mentioned above are another reminder of this. It’s a low-margin, labour-intensive and highly competitive industry.
But having said all that, I still think these shares are interesting. I’m actually relieved that they are going for organic growth with bolt-on acquisitions, and dividend payments, rather than more aggressive plans. At a £7m market cap, I think investors should be more than happy with £2m of operating profit - no need to take extra risks to earn more than that!
Distribution Finance Capital Holdings (LON:DFCH)
- Share price: 40p (+8%)
- Market cap: £71m
It has been three years since we last mentioned this one, and it has achieved bank status since then.
It helps a variety of sectors by funding the purchase of goods from manufacturers to dealers, e.g. trucks, trailers and caravans.
Today’s update sounds excellent:
…the Board is pleased to confirm that it expects to announce full year results for the year ended 31 December 2022 that materially exceed management expectations, predominantly due to increased net interest income and effective cost management. The Group now expects to report a maiden full year profit before tax of not less than £1m.
As an added bonus, the company has losses that it can offset against future profits, so it will be able to recognise an £8m tax asset in its accounts.
Other nuggets included in this update:
Loan book up 15% since year-end to £505m
100 new dealers were added. It now has 1,079 active dealers.
My view
The 40p share price has piqued my interest - this initially listed at 90p when it demerged from Trufin (LON:TRU) .
I’ve just quickly checked the interim report. Tangible net assets as of June 2022 were c. £85m in a highly geared balance sheet (total assets over £400m).
I’ll stay neutral for now, but this one could be worth studying in further detail as a new, already- profitable bank in a niche sector. Let’s hope that it doesn’t turn into another PCF!
Unlike PCF, this one does not have a majority shareholder who is based offshore. My initial impressions are that governance is better here - the Board and management can be reviewed here.
Franchise Brands (LON:FRAN)
- Share price: 181p (down 25% since Monday)
- Market cap: £238m
This share has seen a big reaction to an announcement on Monday night regarding a proposed acquisition, and the placing associated with it. The share price is now around the placing price, which is to be expected.
The target is “Hydraulic Authority I Limited, the owner of Pirtek Europe, an established European provider of on-site hydraulic hose replacement and associated services”.
And the price is enormous: £200m for the business plus an additional £12m for various adjustments.
For context, the acquisition of commercial kitchen services company Filta last year seemed like a big deal at the time (and it was!). That deal was valued at £50m.
In July 2022, FRAN said:
"In the near term, we are focussed on integration to capitalise on the opportunities the (Filta) acquisition presents.”
I can’t have been the only one who thought that FRAN was going to take some time to digest Filta and focus on organic growth for a while!
The new Pirtek deal is financed by:
Bank debt of £110m
A minimum of £110m in new equity, of which £90m to be raised via a placing at 180p.
As announced yesterday, the company managed to raise nearly £92m in the placing (gross), so the total new equity is £114m.
New shares represent 33% of the enlarged share capital. That’s very serious dilution for anyone who didn’t take part in the fundraising, but let’s think about the rationale.
Pirtek is a van-based business providing essential services - exactly the type of thing that FRAN wants to own.
It had system sales of £164m and adjusted EBITDA of £15m in 2022 (both figures unaudited).
It operates in eight countries, including the UK, “with the right to operate in an additional eight European countries”.
The logic behind the deal is as follows:
The Acquisition is highly complementary to the Group's existing businesses and, by expanding its operations to ten countries, will significantly advance the Board's aim to create a market leading international B2B multi-brand franchisor in the UK, Europe and North America.
The Board believes that the size and diversification of the Enlarged Group will provide greater resilience in the services provided, customer base, end markets and franchise networks and geographically.
Pirtek Europe's established overhead will provide a low-cost platform from which to launch the Group's current brands into new markets where Pirtek operates currently.
Etc., etc.
Forecast revenues for the enlarged group are £155m in 2023 and £168m in 2024 (pro forma basis).
My view
I’m going to have to take a neutral view on this stock this morning, with some very mixed feelings.
On the one hand I’ve always said that I like the franchising business model.
But with this stock, we now have a leveraged balance sheet thanks to the Pirtek deal. And I can’t say that it sounds like very good value. They are paying £200m+ for a company that earned an unaudited adjusted EBITDA of £15m last year: the bottom line is likely to be much, much smaller than that figure.
Of course the deal is predicated on synergies between Pirtek and the existing businesses. However, if the management of Franchise Brands are happy to issue 63 million shares at 180p (there were only 130 million shares outstanding as of last week), then it would be a reach for me to think that the shares were worth much more than 180p at the company’s current stage of development.
I thought that FRAN would take more time to digest Filta, generate some healthy profits, and then recycle its cash flow into its next deal. Instead, they are shooting for the moon: it might work out, but risk levels have definitely gone up a notch.
Roland's Section
Lookers (LON:LOOK)
Share price: 85p (pre-open)
Market cap: £327m
Strong growth momentum leading to higher profit expectations for 2023
Car dealership group Lookers has issued a solid set of numbers for 2022 and upgraded its guidance for 2023 profits. Earnings were previously expected to fall sharply this year as supply shortages eased.
It now seems that this reduction will be smaller than previously expected, continuing a trend that’s seen several upgraded to 2022 forecasts since last summer:

Lookers has had some problems in recent years, but appears to be performing well now and may not be unreasonably valued. Let’s take a look at today’s results.
Financial highlights
Earnings peaked in 2021, when new car shortages were at their worst. Lookers’ 2022 results reflect this, with a reduction in profit margins compared to the prior year:
Revenue: up 6% to £4,300.9m
Underlying pre-tax profit: down 8% to £82.7m
Statutory pre-tax profit: down 6.2% to £84.4m
Underlying earnings earnings per share: down 9.3% to 18.2p
Dividend: up 20% to 3.0p per share
Net cash: up £63.5m to £66.5m
Operating margin: 2.5% (2021: 2.8%)
Return on capital employed: 16.4%
I can’t really see anything to be worried about here.
The dividend gives a useful 4% yield and while retailing cars is a low-margin business, Lookers appears to be generating attractive returns on its assets, with ROCE of 16%. That’s at the upper end of the range of comparable listed rivals.
Free cash flow: Cash generation for the year was strong, with free cash flow of c.£55m. However, most of this seems to have come from favourable working capital movements and disposals, so I suspect cash generation might be slightly weaker this year.
Adjustments: Looking through the accounting notes, the adjusting items in this year’s results mainly relate to the proceeds of property sales and the costs of site closures. So I think it’s probably useful to adjust these out in assessing the performance of the core trading business.
Pension deficit: It’s also worth noting that Lookers has a pension deficit that required a £14.2m contribution last year. This year’s payment will be £13.6m.These are material amounts for a business of this size, but the scheme is undergoing its triennial review at the moment. So it’s likely that payments will change from 2024 onwards.
Operational/market commentary
New vehicles: The order book for the year ahead is said to be robust. At the end of Q1, Lookers had 18,000 vehicles on order for retail customers and 24,000 vehicles for fleets.
Lookers says that it outperformed the market last year with a reduction in new car volumes of 1.1%, versus a UK market total of 2.0%.
New car supply levels are now said to be returning to more normal levels, after heavy disruption. The UK market is expected to see 2.1m new car and van registrations this year, compared to 1.9m in 2022.
Used vehicles: used vehicle volumes fell by 4.9% last year, but again the firm outperformed the wider market, where volumes fell by 8.5%.
Strong margins are expected to continue into 2023, as supply of used vehicles remains limited.
Aftersales: Lookers is continuing to focus on customer retention to drive profits in this higher-margin business.
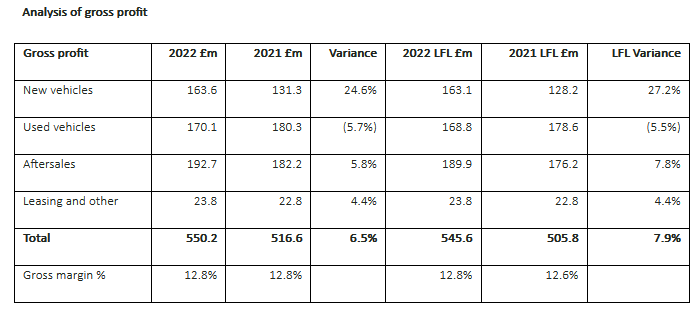
I think it’s only a slight exaggeration to say that the main purpose of selling cars seems to be to secure the aftersales revenue they generate! The profit breakdown below shows that aftersales generates more gross profit than either new or used car retailing for Lookers.
Outlook
Management says that underlying pre-tax profit during the first quarter was ahead of the same period in 2022. However, they warn of continued inflationary pressures and risks to consumer confidence.
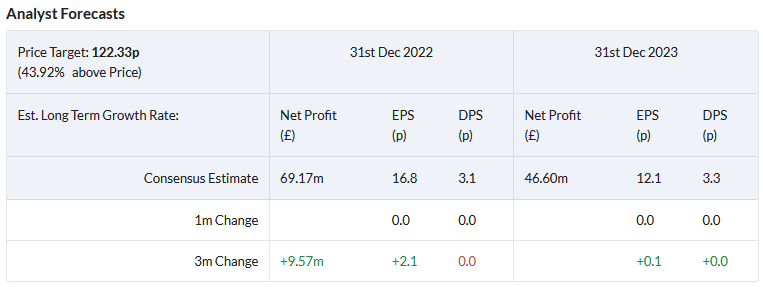
Profit for the full year should now be higher than expected, but frustratingly management doesn't provide any specific guidance on how this updated guidance compares to current consensus estimates.
My view
It was always obvious that car dealers’ profits would have to ease back from the record levels seen in 2021. However, Lookers (and most rivals) seem to be handling the cyclical shift successfully, so far at least.
Lookers also seems to have fixed the management and governance issues it suffered before the pandemic. There’s a notable emphasis on risk management and other governance areas in the results.
The shares don’t look expensive to me on seven times forecast earnings and the share price is also supported by a property portfolio that’s said to be worth £290m (versus a market cap of £327m).

On balance, I think Lookers is executing well and in good financial health. The short-term risks facing the business mostly seem to relate to macro factors outside management’s control.
Investors who are reasonably optimistic about the outlook for the UK economy might find an opportunity here. I’m cautiously positive, although I’d probably lack the conviction to buy.
Speedy Hire (LON:SDY)
Share price: 32p (-3% at 09.40)
Market cap: £149m
… we enter FY2024 with confidence.
Equipment hire group Speedy Hire embarrassed itself in February when the company admitted it had lost around £20m of equipment – nearly 10% of the total book value of its hire equipment assets.
Today’s year-end trading update covers the 12 months to 31 March. Fortunately, it does not reveal any further cringe moments for the company.
With the shares trading at possible bargain levels and offering a forecast yield of 7%, is this business worth considering as a contrarian buy?
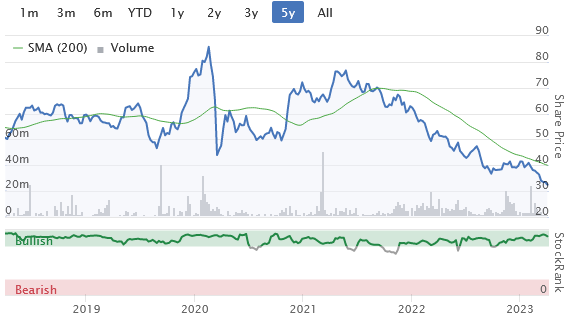
22/23 trading update: lost equipment aside, Speedy Hire seems to have traded reasonably well last year.
Revenue for the full year is expected to be 14% higher, which is slightly ahead of consensus forecasts for 12% shown in Stockopedia. Customer rate increases were successfully applied to offset the impact of inflation.
Adjusted pre-tax profit for the year is expected to be in line with the Board’s expectations.
Unfortunately the company doesn’t confirm what these are, but we can probably assume they’ll be reflected by current consensus forecasts. That would price Speedy Hire stock on just six times forecast earnings:

Net debt: Speedy Hire expects to report net debt of less than £94m at the end of the year, excluding lease liabilities.
Equipment hire businesses tend to carry a reasonable amount of debt to fund their hire fleets. I estimate this figure is around half the value of Speedy Hire’s hire fleet, after the expected write-off relating to the missing items.
As a rule of thumb, I tend to look for debt to be no more than 50% of the value of hire equipment. So this falls within my risk tolerance, just.
However, Speedy Hire’s net debt has risen from just £67.5m over the last year – an increase of £26.5m. This increase appears to be directly linked to the £30m share buyback completed over the last year. I consider this a poor use of capital, given the uncertain macro outlook.
Current year trading: the company says there has been “some softening of demand in recent weeks”, but that its pipeline of new business remains strong.
On balance, management expects to report revenue growth this year.
Cost-cutting initiatives are underway, including depot consolidations. These measures are expected to cost £6.6m and generate benefits “in the region of £5m per annum”.
An update on the missing equipment will be provided with the full-year results in June. Reassuringly, a further asset count at the end of March “did not identify the need for an increase in existing provisions”.
My view
Speedy Hire has a mixed track record as a listing company, but the shares do seem reasonably valued at current levels.
After a series of broker downgrades last year, forecasts have recently turned up, but profit growth this year is expected to be minimal:

However, I’m slightly concerned by the increase in debt last year, especially as it’s resulted from buybacks, rather than investment in the business.
I’m also concerned about the wider management controls and culture within the group, given the asset loss reported in February.
I think Speedy Hire shares might offer value at current levels. But it’s too speculative and low quality for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Re Distribution Finance Capital Holdings (LON:DFCH) - I like it and business model. But I think its priced quite highly for what's visible and some uncertainty what their non-dilutive growth trajectory is beyond 2-3 years and then what happens re earnings (returned to shareholders or re-invested to expand). My hope is some meaningful cheapening then this is an interesting share...and if you want something similar at a better price...well Time Finance (LON:TIME) is a bargain. I don't believe external finance is an issue and in some respects is 'higher quality' as it means they can focus much more on the credit quality-arbitrage decision for small corporates and reflect through NIM rather than be caught by the restrictions of bank regulations which force a focus on 'higher quality credit'...which often just means bigger companies that credit data can get a read on but often lower actual credit quality...but you got to lend at lower NIM as its officially higher credit quality. This is why non prime as long as you are not too non prime is a rich space.
*I acknowledge some hair on Time and hard for many to stomach...its not a recommendation just a point (I do own tho...and would like to own DFCH at the right price...strategically I desire exposure to business lenders as I believe there will be quite a boom in it through rest of decade)
Fancy this: Market is worried about recession and one of my recession proof share is dropping too!
Not sure what to make of Begbies. It has been touted as a company which benefits from the difficult economic climate. Maybe it has become more aligned with the property market now!
With CGT limits changing next year is there some profit taking going on today, or even bed and ISA'ing?
Chris, since I have no new cash I'll be bed & Isa-ing later on in the New Tax Year, at least it will help deflect Hunt's attack on potential savers who carry risk and get no reward from lawmakers.
Silver
looking at the share price of TUI possibly yes.
In that case we should expect a bounce tomorrow!
Just a comment on Industrials Reit Industrials REIT (LON:MLI) which I hold. The price jumped on the Blackstone takeover bid 2 days ago and in theory I should be happy but I am not. I was holding this stock as a long term source of income in retirement. Also, if Blackstone are paying 168 per share then they obviously think it is worth more. As investors we have lost a very decent stock from our pool of potential investments. How many other UK stocks are seriously undervalued and how many are we going to lose in this process? It looks like our stock market and perhaps our currency are undervalued.
Hi Whatmore1951
Income is very important with respect to my mum's portfolio (pension/life savings held in ISA form).
I would concur that there has been a big sell off in many areas over the last few months, especially around the various REIT holdings, with concerns about asset values at book and what they may decline to, and also about the overall leverage used by some of them and what the term and what revised interest rates mean for each business and the longer term business model for some.
In a simple world you would say recycling profits to pay down debt given the changed nature of interest rates in the last 18 months, or to invest in additional assets for future profits, but with the REIT structure there is obviously a payout requirement.
There is also the direction of government forcing owners to improve EPC ratings of existing stock and the capability of market (products, supplies, capabilities), then the cost and disruption for doing these works. You can reinsulate the loft or change all the light fittings in most houses in a day, not so with a warehouse or factory.
Sorry slightly off track. I have been spending more time researching the broader world of income options, after all the Bank of Hunt & Sunak (NS&I) now offer 3.9% monthly, but diversifying with smaller holdings (~1-2%) so accepting the fractional dealing costs, versus a good return for an 80 year old to live her life to the full.
Currently there are only a very few REIT type holdings left in the portfolio such as Ediston Property Investment (LON:EPIC) , mostly as the decline in value has triggered a manual capital protection sell. But I am prepared to buy back in again, as they are good source of income.
With regards to opportunistic investment and purchase, I think we are going to see more of these coming around, there are a lot of companies, and people, who are sat with cash and thinking longer term, so unfortunately a bomb out share price is going to mean things are taken out and as small private investors, we loose another option to us.
Good luck
Tommy
Tommy,
Have a look at Alternative Income REIT (LON:AIRE)
Are going to pay 5.7p dividend (and I suspect a bit more) on a 68p price.
The portfolio has an average lease length of over 17 years with 90% plus linked to inflation but with a cap of about 4%.
There is no research on it and the Stockopedia dividend numbers are wrong.
A hidden gem.
Airea (LON:AIEA) (I hold) FY results (annual report available from website this morning)
Tiny, carpet basher from Ossett (Wakefield) with good results for FY22 which specialises in carpet tiles, for commercial and public sector. Airea also owns and operates an investment property - was a disused mill - now a multiuse business/retail park. Which adds significantly to the net asset value and has supported operating profits through the pandemic whilst commercial carpet tile markets were depressed.
Revenue £18.5m (+16.5%)
Operating profit £1.7m (+25.8% - before last years valuation gain on investment property)
Pbt £1.4m (+11%)
Net cash £2.8m (+53%)
Dividend 0.5p (+20%)
There are no forecasts for this tiny AIM listed company. Revenue is higher than my own expectations, whilst profit is slightly below where I'd hoped. Though profit in previous years has been propped up by gains in the valuation of the investment property - so the operating profit grwoth excluding property revaluation looks good.
The commercial market for floor tiles in the UK has not seen the softening in demand that has affected the residential sector - not yet anyway - quite the reverse as its been in recovery from the effects of lockdown and supply constraints. Plus Airea's investment in new machinery and product launches is aimed directly at the architects and contractors, for example the carbon neutral range launched post year-end. Which bodes well for continued growth in sales in the current year?
There is a new CEO - following on from the sad death in service following an illness of the previous CEO who led the turnaround of the company. In the interim the chairman stepped down to take the reins. It's too soon to tell, but the new CEO looks to be a good choice and appears to be wasting no time in building on the achievements of his predecessor.
On reflection - perhaps these results are somewhat better than good? It seems that sales momentum has continued/increased though H2 as revenue has grown strongly. Poland was the main export market prior to the pandemic and is probably still affected by the current conflict - sales growth in the UK seems to have more than compensated - and continuing product launches.
Although I've seen it as a turnaround the impact of the lockdowns, energy prices, conflict and inflation on the share price have meant that for the last couple of years Airea (LON:AIEA) has been a value play - today the shareprice is not far from Tangible Net Asset Value (flat yoy as the pension scheme moved into deficit according to the IFRS method, though there are no payments required under the last agreement with the actuary). So not so much value anymore but is there growth on the horizon?
Based upon current revenue growth it might be. The company has invested in new efficient machinery enabling new product launches. Despite passing on price increases and maintaining gross margins (impressive?) the fall in energy prices. coupled with the companies investment in solar panels, reducing usage and cutting waster - could also improve future operating margins as energy costs and inflation subside into 2024?
Worth mentioning that in Dec2022 the Newlands (noted private investors) raised their holding to 10.25%. It's fairly much unfolding as I expected, maybe a tad later than I'd hoped (it always is!) but growth looks to be slightly better than I'd expected - so I'm happy to hold, take the dividend and see how things progress from here,
cheers
Mark
Thank you Mark. This stock was on my watch list a few years ago but life and the pandemic got in the way. I shall start a new file and your notes here are a very good starting point. Thanks again.
Thanks Mark!
I had a quick look at Airea results first thing, and my very brief notes are -
£16m market cap (pre market open), a 3-year high (recent surge). 3.36p EPS, but note the low tax charge which boosts this figure somewhat. £4.0m investment property, generating rental income, so if you adjust it out, remember to also adjust out that income. Nice balance sheet. Pension deficit of £1.3m on an accounting basis, need to check actuarial & overpayments (if any).
My conclusion - seems OK, probably priced about right.
I'm trying to avoid getting sucked into new positions in tiny, illiquid, wide spread type shares.
Please could we have comments on Franchise Brands (LON:FRAN) ? They had a placing yesterday to raise funds for a large acquisition. Their share price fell significantly.
Thanks for the suggestion, WS - I'm taking a look. G
Franchise Brands (LON:FRAN)
Hi Graham
Thanks for your write-up which paints the picture well.
I have held FRAN shares since end 2019. Management and the share price have done very well since then. I think the shares have been highly rated in part because management hold a lot of shares - both number of shares and also number of directors with large holdings. With 17% each, shareholders Helmsley and Wray are experts in operating a franchise model and also very experienced. They enjoyed tremendous success with Dominos Pizza, have done very well with FRAN to date and the Filta acquisition last year has done exceptionally well.
As with all acquisitions, especially large ones such as Hydraulic Authority I Limited' there are risks. For me this one boils down to your perception of management. With the track record I have described, large shareholdings and also participation in the placing, I will continue to back them.
I preferred the "slow and steady wins the race" approach. Hope the management haven't gotten over confident following the Filta deal and bitten off more than they can chew with this one. Pretty miffed with a 25% fall on one of my biggest holdings but I'll stick with it for the long term given their previous record, keeping a close eye out for any warning signals.
The way Fran management have cut private shareholders out of the placing is shocking but one can see the case for the acquisition.It will fit with their existing drainage business and give them the scope to expand their businesses into 7 'Safe European' countries.Only time will tell if Fran have overpaid but like you willing to trust the management until they make a mistake with acquisitions and continue to hold shares.They go xd next week.
The way Fran management have cut private shareholders out of the placing is shocking
That would be true if shares had quickly spiked from the placing level. But you can buy the shares at a discount to the placing today. So, putting ethics to one side and focusing on expediency, what's the problem?
In my experience of placings, the vast majority of the time the share price drops below the placing price. So although disappointing that retail are often not included, it could actually work in our favour.
For background, here's the Franchise Brands (LON:FRAN) FY22 analyst presentation from about a month ago, which is very comprehensive. It covers Filta's integration and their strategy video & podcast.
Northern Bear (LON:NTBR)
I’m actually relieved that they are going for organic growth with bolt-on acquisitions, and dividend payments, rather than more aggressive plans. At a £7m market cap, I think investors should be more than happy with £2m of operating profit - no need to take extra risks to earn more than that!
I would agree - historically NTBR's balance sheet has not been the best - reality used to be they had large value of payables that didnt show up as debt - although it was covered by a similar receiveables line - in hard times that may not install confidence in customers. To my eyes without taking risks they have probably been somewhat limited ref spending owt sensibly when better capitalisation made sense - safety net deffo warranted in their line of business. Hopefully thats becoming less of an issue now (as net tangible assets have mostly improved yoy) so they do have some more options - particualrly ifn they are confident churning out 2 mill plus pa. I kinda hoped they would just grow well organically being good at what theyu do with small bolt ons - progress i must admit hasnt really been great while i have held - although to me £2 mill profits plus is decent watermark they didnt always hit in the past.
Note if anyone is looking at the 2021 numbers pasted thninking the company was loss making last year - that wasnt really the case - the £1.45 mill operating loss quoted on strocky is after including £2.8 mill intangibles w/off - so from my viewpoint the company actually made decent operating profit last year not losses. From memroy ignoring intangible w/offs this company has pretty much delivered operating profit every year since the last recession - which is no mean acheivement for the industry they are in
Further re Rathbones (LON:RAT) and the acquisition of Invested Wealth. Before this announcement Rathbones (LON:RAT) had underperformed due to banking sector woes. In April 2022 Brewin dolphin was acquired by royal Bank of Canada at a hefty premium 60%.... a deal that made Rathbones (LON:RAT) look relatively cheap. Historically Rathbones (LON:RAT) was seen by the market as the better business.
I'm sure the deal is great for Rathbones (LON:RAT) management and most employees. Im also sure the clients will not be worse off. Although systems integration etc are a nightmare for clients. The synergies should be easy enough because all these businesses carry far too many people. Also the Rathbones (LON:RAT) bank is ultra conservative and should be making much better deposit margins these days. On the face of it there should be plenty to like.
Technically however a deal for the combination will likely not emerge for some time even if it's the end game . So those that piled in after the Brewin transaction may well move on. Rallies will likely attract sellers.... and so net net Im a lot less interested in it for now. Any market weakness and this is the sort of stock that will get launched IMO. For those happier to harvest a reasonable divi yield there isn't much wrong with it.... and the natural balance between bonds and equities will mitigate market weakness in the earnings.
RE: Rathbones (LON:RAT)
Technically however a deal for the combination will likely not emerge for some time even if it's the end game . So those that piled in after the Brewin transaction may well move on. Rallies will likely attract sellers.
Noting that it's not a small cap stock ... if nothing else, Rathbones is now in play. Rumours of potential buyers have been swirling around ever since the Brewin Dolphin deal so this will flush them out if they're there. If not, well, it's another one to stick away and forget about for another five years ...
timarr
Eagle Eye Solutions (LON:EYE) - announces growth shares plan. I hate these, they're unethical - creating an intermediate holding company to hive off partial ownership to management.
However, in this case, the stretch targets look exciting, and the dilution is quite reasonable I think. Sets an aspiration to become a £1bn market cap company.
Looks interesting, I think this is quite an exciting growth company, although the valuation strains my value/GARP sinews almost to breaking point, it is demonstrating very good organic growth, big name clients internationally, and it's now profitable. I should probably buy a few to tuck away for 5 years.
Paul, if you really want one to tuck away, try Crimson Tide.
Turnover growth rate according to Finncap, is twice that of Eye. Gross margins are about the same.
Valuation on an ev/sales basis on current year t/o is, for Eye, about 3.9x for TIDE is 2.6.
All very rough estimates of course and TIDE is less liquid.
Finncap have TIDE on a p/e of 9.6x for Dec 24, Shore have EYE on a p/e of 33.8 for June 25.
Just a thought.
Hi ChrisW,
Yes I'm aware of Crimson Tide (LON:TIDE) - have been following it for years, and did own some for a while.
It's very, very small. That's the main issue. So valuation metrics don't necessarily make a lot of sense for stuff that tiny. Also it's been doing what it does for many years, and progress seems painfully slow.
Looks potentially interesting though. Could be a multibagger if they manage to really accelerate growth. C.£5m revenues isn't anywhere near enough yet.
I'll keep an eye on it though, thanks for reminding me!
Regards, Paul.
P.S. It's a bit overcast this morning in Gozo, so am not in a rush to get out & about!
Paul. I could not agree with you more on Eagle Eye Solutions (LON:EYE) - I have owned in the past but do not own at present.
These growth share plans are not justified, I feel. In this case, Eagle Eye’s senior management is quite well remunerated already. From the announcement, it seems that the the Growth Plan is just on top of what is already in place - not instead of bonuses. (In that sense I would prefer a scheme like Brave Bison (LON:BBSN) . Also while the targets might look stretching, they have 10 years to be reached - so a doubling in share price in 10 years (target 2) is really only the minimal acceptable for a non-dividend paying stock (c7%pa).
CEO Tim Mason’s all-in comp in FY22 was £1.68m (salary,bonus and LTIP) while CFO Lucy Sharman-Munday’s all-in comp was £990k. I think both are excellent but adding a Growth Plan on top of these already high comp levels is taking the biscuit.
One factor I had always liked with Eagle Eye Solutions (LON:EYE) was that with large and long standing shareholders Terry Leahy and Bill Currie on the board, I felt that shareholder interests would be protected. I wonder if it is coincidence that Bill Currie stepped down from the board (after more than a decade) only 3 weeks ago.
And Bill Currie has sold about 1.9m shares since Nov if my sums are correct.
He bought about 3.5% of Sosander in Feb.
Just FYI
Lookers (LON:LOOK) worth a look - Zeus note this morning shows a whopping 22% upgrade to 2023 forecast profit. Nice asset backing. Small cap car dealers remain very cheap, in my opinion (no personal holdings in the sector).
Good morning Paul, Re Lookers, I'm hoping for a read across to Vertu, currently our biggest holding. I look forward to Roland's coverage of Lookers.
Thanks JASVFS,
Apologies to Roland if I jumped the gun & stole his thunder re Lookers (LON:LOOK)
I've not looked at the actual results, but got the Zeus note through by email from RT, and thought it worth flagging such a large upgrade to 2023 forecasts.
Regards, Paul.
Interesting article in Telegraph today, saying that UBS is forecasting a glut of new cars, as rising production likely to meet reduced demand. Hence lower prices, and dealers competing to cut prices. Prices of electric cars have plummeted (I sold my Taycan to a dealer for £85k about 6 months ago, and the trade value is now only £55k - a lucky escape!)
What we learned about this sector during the pandemic, is that restricted supply is actually good for the dealers, increasing margins, especially on used cars.
All of this is probably in the forecasts though. Most car dealers I've looked at are already forecasting (or rather brokers are) normalised level of profitability this year, after a couple of bonanza profit years in the pandemic, so it looks as if all this news is baked into share prices already.
Regards, Paul.
Does anyone here (including Paul Scott?) anticipate additonal (0r a revival of) M&A activity in this sector, with Lookers (LON:LOOK) and a large invested (blocking???) shareholding here with TDR Capital, as also with Pendragon (LON:PDG) (with Hedin taking a 28% share (invested or blocking, as with TDR and Lookers?).
Is PDG really worth approximately half of what the Hedin shareholding took it to in late autumn last year, or again are retail investors really being messed about yet again.
I have to say I blame myself with Pendragon (LON:PDG) because the writing was on the wall when Hedin asked for an extension to the access to the accounts. I believe the board should have said to them at the time, put up or shut up. Did they really expect to get a better offer. On the other hand, it's my own fault. I should have taken the 28/29p and ran. Should've/could've!
Hi JASVFS,
My comments on Lookers (LON:LOOK) should be up now. I'm confident about the business but slightly wary about the macro outlook -- very much a personal decision for investors at this point, I think.
Regards,
Roland
I thought your coverage and comments on Lookers excellent Roland, I have been an optimistic bear since 2016 and remain so, I share your wariness. I agree totally with your observation about servicing and repairs becoming an increasingly important contributor to Franchised dealers, which of course many used car retailers do not have (Cazoo anyone?). I don't think TDR Capital through Constellation have finished their empire building yet, that might add spice to to already good value and decent yields in Lookers and Vertu (we hold) to name two groups in their sights.
Just an fyi Cazoo (NYQ:CZOO) does have 7 service centres dotted around the country. I own Lookers (LON:LOOK)
Great piece on Lookers Roland many thanks
Hi JASVFS,
My comments on Lookers (LON:LOOK) should be up now. I'm confident about the business but slightly wary about the macro outlook -- very much a personal decision for investors at this point, I think.
Regards,
Roland
Recommended cash bid for Fulham Shore (LON:FUL) at 14.15p - a 35% premium, but looks opportunistic to me - management (big shareholders, owning nearly half the co) whipping away the long-term upside for themselves, when share price depressed.
What's the point in owning shares like this, if our upside is capped, but we take all the downside risk?!
P.S. Pity, as I've recently been mystery shopping both Franco Manca and The Real Greek (excellent lunch deal for c.£10) with a view to possibly buying a few shares if they dipped a bit further. Won't happen now.
The bidder, Toridoll seems to be a listed Japanese food group. It feels as if foreign buyers are cherry-picking the best UK companies, leaving us with everything they don't want!!
Annoyed. I have held them in the past and planned to do so again. I knew they would sell the whole kit and keboodle at some point, but now?
Fulham Shore (LON:FUL)
I heard rumblings some time ago that this company would be sold . If the directors are keen to take away listing status i would be slightly worried that shareholders may lose if they fight the peeps that matter - if there is a genuine premium offer they turn down are minor sharholders going to come on top if they kick up a fuss and block a deal at a decent premium ? - just look at what happened when revolution bars takeover was turned down. This company does appear to be doing solid behind the scenes so probably no need for everyone to sell up but there are many ways in which shareholders can be shafted in small caps like this - and that woudl be my slight worry if reasonable deal is blocked agaisnt the interest of the power players here . Reality is mr market has valued this company at 10-11p on average over the last 3 months.
could Revolution Bars be an opportunity at these levels?
Revolution Bars (LON:RBG) XP Factory (LON:XPF) pubs e.g. J D Wetherspoon (LON:JDW) maybe not as grim as the share prices look.
Fulham Shore (LON:FUL) I own but at a higher price than take over - Is that not the conundrum we face with smaller companies, I look for companies where management have skin in the game but then they can do this to smaller shareholders. I have had it with Talktalk Telecom (LON:TALK^C21) and we saw an attempt by ME International (LON:MEGP) to try a low ball bid. Maybe too much skin in the game is a risk too?
That's the downside of being a small shareholder I'm afraid. Only participating in share price gains and dividends. But no say or sway in strategic decisions.
On the other hand, easy to buy in and out as you please. Albeit, you give up this benefit, if you're a "coffee can" type investor.
My morning smallcap tweet: Shareholders to get Bear hug
Distribution Finance Capital Holdings (LON:DFCH) £TPT_ Crimson Tide (LON:TIDE) Northern Bear (LON:NTBR) Airea (LON:AIEA) Drumz (LON:DRUM), Speedy Hire (LON:SDY)
◄Distribution Finance Capital (DFCH)► guides FY-Dec materially ahead of management expectations, CItes increased net interest income and cost management. Expects pretax £1m+. End Q1 loan book up 15%. [SP=36.6 Cap=66m]
◄Topps Tiles (TPT_ Q2 LFL rev up 3.5% but gross margin down.but expects to see gross margin increase sequentially in H2."Our continued growth gives us confidence that we will deliver our market share goal of '1 in 5 by 2025' ahead of schedule" [SP=NA Cap=NA]
◄Crimson Tide (TIDE)► c£250k contract over 3 yrs. "The project is anticipated to increase in size and contracted revenue later in the year." [SP=2.59 Cap=17m]
◄Northern Bear (NTBR)► to pursue a "dividend growth strategy". FY div 4p + 1p special. Co "intends to further increase its engagement [from nothing at all!] with the broader investment community" Guides 'strong' FY op profit (before amortisation & one-off costs) £2.75m before £500-£750k write-down, to account for certain unprofitable contracts. [SP=36 Cap=7m]. I hold.
◄Airea (AIEA)► FY-Dec rev up 16.5%, pretax up 11%. In line? No trading stmt since July! Vaguely positive outlook stmt. [SP=39.99 Cap=17m]
◄Drumz (DRUM)► conditionally agreed RTO of Acuity Risk Management. Currently owns 25% for £3.6m, mostly in shares. Share consolidation. £1.45m placing at 4.55p, a 33% discount to last traded price (adj for consolidation). Acquiree has monthly ARR of only £0.14m. WIll be re-admitted to AIM with name Acuity RM and ticker ACRM. [SP=0.66 Cap=3m]
In line: SDY
[edit] Fulham Shore (LON:FUL) rec takeover at 14.15p, 35% premium.
Northern Bear (LON:NTBR)
Decent enough update this morning considering the shareprice is pretty much in the gutter which suggests no one wants to pay much to own shares in this company. There seems to be constant b itching from the sidelines here but ultimately the company is at its core delivering decent results year after year which if continued do kinda deserve a higher shareprice. I have always said if they keep delivering balance sheet keeps strengthening and thus will sort itself out. Perhaps a chomping dividend may help. Deffo not really a quality company you would want to go out of your way to invest in but if they can consistently deliver 2 mill profits per year plus should be with more than it is now imho.
Northern Bear (LON:NTBR) - i agree with that summary. with 10% yield and no debt, defo seems lowly priced even with the illiquidity.
i am intrigued what the non exec chairman will do. he is successful entrepeneur, but is based on canada i think, is non exec, tried to take over the company and then tender bid for his 29% staked at 72p.
i think the increased shareholder engagement will help the price rise from these levels.
Northern Bear (LON:NTBR) , does have a spread of 9 or 10 subsidaries which seems to have provided diversification and profit stability over the years. i hold and hopeful in their words to make the new 4p dividend strategy sustainable. i hold.
Thanks for the comment on Northern Bear (LON:NTBR)
I've covered the stock - remarkable that there's so much interest and yet it's only worth £7m (as of last night)