Small Cap Value Report (Weds 14 Dec 2022) - TWD, FAN, STEM, BILN, CHRT, PROC, MIRI, LOOP, CYAN, GETB

Good morning, it's Paul & Graham here.
Here's the written summary of last weekend's podcast.
Agenda
Paul’s Section:
Trackwise Designs (LON:TWD) - Horrendous news for shareholders, with a 92% discount on a fundraise at just 1p. More details below, to avoid cluttering up this section. No.1 priority right now - we need to avoid holding anything that has run out of cash, as existing shareholders are lambs to the slaughter, as demonstrated by this news.
SThree (LON:STEM) - one of my favourite value shares - a decent quality business, on an attractively low valuation, with a strong balance sheet and no debt. Although today's year end update does mention softer market conditions emerging in Q4, so I ponder whether we might have seen peak earnings for the time being? Thumbs up for the long-term, but shorter term, we might see a wobble in 2023 possibly?
Billington Holdings (LON:BILN) [quick comment] - shares are up 26% to 290p on a strong trading update for FY 12/2022. Trading has “continued to improve”. Adj PBT now “significantly ahead of the Board’s previous expectations”, on unchanged revenue. Order book & pipeline give confidence for 2023, also now expected to be ahead of expectations. Says it has made efficiency gains. This looks an impressive turnaround, I haven’t looked at it since a profit warning a year ago, so didn’t spot that things were on the mend. Good balance sheet, with net cash. Looks interesting, but I’m wary of the economic cycle, which could cause trouble ahead. Severfield (LON:SFR) looks similar, but larger.
Mirriad Advertising (LON:MIRI) [quick comment] - this has come up on the top fallers list, down 24% today on a trading update, so we just need to get a quick comment into the system here, for future reference. I can scarcely believe the numbers - guidance for FY 12/2022 is revenues c.£1.6m, EBITDA loss of £(15.5)m! Cash remaining is £11.5m (down from £24.5m a year ago). Costs to be trimmed by £2.5m in 2023. Unless something drastically changes for the better, this share looks to be heading to zero before 2023 is out. This is one of the worst things I’ve ever seen, based on these numbers.
Loopup (LON:LOOP) [quick comment] - a positive-sounding update, as usual from LOOP, but it glosses over the vital bits of information we need - how much are the losses, and how much cash is left? Figures from Cenkos (many thanks) show heavy losses, and negative cashflows (it capitalises a lot of the payroll into intangibles). This share will almost certainly need another fundraise, and/or be taken private, or go bust, in my opinion. So it goes into the category similar to Trackwise - i.e. the products sound a good idea and are intriguing, but it needs more cash, hence is uninvestable unless it manages to refinance. Could easily be a wipe-out I think, so why take the risk?
Getbusy (LON:GETB) [quick comment] - up 6% today on a positive trading update - FY 12/2022 expected to be “slightly ahead of market expectations”. Impressive revenue growth of +24% to £19.1m (at least). Loss-making though, c. £(1.0)m for 2022, if I’m interpreting the announcement correctly. Net cash of £2.2m, and undrawn £2m facility, so liquidity looks OK. My view - quite an interesting share. It has a reliable cash cow software business, that is generating the funding for some blue sky projects. We don’t know at this stage if the new projects will work or not, but at least investors have the value of the core business to fall back on.
Cyanconnode Holdings (LON:CYAN) - lousy H1 numbers (loss-making, again, same every year), but it claims big orders are kicking in, and Q3 will see much higher revenues. Balance sheet doesn’t look good to me. Tight for cash, and receivables of £4.6m is over 3x H1 revenues - how does that make sense? Although it says £2.3m has been collected since the period end. Shareholders here have to hope that management is telling the truth, because on the basis of the historic numbers, I would value this share at nil. Too risky.
Graham's Section:
Volution (LON:FAN) (£700m) - today’s AGM statement lets us know that Volution continues to achieve an adjusted operating margin of over 20%, which is consistent with its long-term goals. I like this KPI so I’m enthused by its continued success on that front. The company’s organic revenue growth rate of 5.5% is not bad, but I’d like to see some improvement there, considering the pace of general inflation. Overall, this stock continues to strike me as potentially offering decent value, having sold off significantly since mid-2021. Of course, the same can be said about quite a few other stocks!
Cohort (LON:CHRT) (£183m) - good H1 numbers from this small defence group. Adjusted operating profit bounces back after last year’s H1 disappointment. The outlook for the full year is unchanged but management are very positive about the demand for their systems from NATO countries and in the Asia-Pacific. I can’t find much to criticise here - the main question for investors is perhaps whether they believe in the long-term demand story, and if they are happy to underwrite the risks involved with low-ish margins and lumpy orders.
PROCOOK (LON:PROC) (£30m) (+0.35%) [no section below] - these shares have fallen by a third since July. They had another profit warning last week. They are now down by over 80% since their IPO, which was only thirteen months ago! Today’s interim results show revenues down by 14.5% to £27.4m, a reduction in gross margin from 66.6% to 61%, and an underlying loss of £2.8m. This is despite growing their customer base by over a third (customers on their database who made a purchase in the last year). Their sales numbers have underperformed the UK kitchenware market, which itself is shrinking. Additionally, cost pressures have hurt margins: the company has chosen not to, or been unable, to raise prices sufficiently to offset increased shipping costs. While the net debt position is modest at only £1.3m, I don’t view this company as having much credibility after I discovered that it spent £9.4m on its IPO, and included nearly £7m of employees bonuses within its “IPO costs”. In the latest H1 period, it has made another £0.6m of IPO awards to employees, and included them within “non-underlying operating expenses”. For that reason alone, I would avoid this one with vigour.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Trackwise Designs (LON:TWD)
Horrible news today, of a massively discounted fundraise.
It’s doing a placing to raise £3.65m (before fees) at just 1p per share. The price last night was 12.65p, so the fundraise is a 92% discount.
The share count will rise from 37.5m in issue now, to 402m after this placing, an increase of 972%.
Then there’s likely additional dilution of 150m new shares if the open offer is fully taken up, so 552m shares in total.Existing shareholders can participate in an Open Offer, with 4 new shares (also priced at 1p) for each existing share. So that’s something, although it would still cause significant dilution even if shareholders do take up the open offer, because the placing is bigger.
PLUS there’s more potential dilution from warrants being issued, although I wouldn’t worry about that, because the exercise price is 6p, which would be a delight to achieve a share price of 6p or above. Management express “deep regret”.
As we keep discussing here, you don’t want to be holding anything that needs to raise fresh cash. Balance sheet strength is absolutely key right now, as it's so tough to raise fresh cash. This announcement is another reminder of the risk of being almost wiped out if the institutions don’t really want to support a fundraise. Be careful out there, conditions are really grim for small caps that run out of cash.
Graham flagged the high risk of a funding shortfall here in July, and marked it as uninvestable, so a hat tip there to Graham. Management reassurances about being able to find funding, turned out to be worthless.
The other question is whether this is going to be enough fresh cash? Will it need to raise again? Still too risky I think, even at 1p/share.
SThree (LON:STEM)
385p (down 3% at 08:34)
Market cap £518m
SThree plc (‘SThree’ or the ‘Group’), the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics (‘STEM’), is pleased to issue a trading update for the financial year ended 30 November 2022.
Record performance for the year with double-digit growth across all regions
There’s a lot of detail in this update, but it’s ambiguous about whether or not it’s hit market expectations. Liberum’s update note today helps clarify things (many thanks), leaving both FY 11/2022 and FY 11/2023 forecasts unchanged.
Note from the Stockopedia graph below how estimates for FY 11/2022 have been gradually rising, although next year’s forecasts (the lighter line) are now dipping down below this year. I think that’s sensible, given the macro picture and tough comparatives, and am wondering whether we need to be taking a more cautious view for earnings in FY 11/2023? We might have seen peak earnings in FY 11/2022 possibly? Especially as there are also well flagged increased costs which have been taken on in the last 6 months.

Market conditions - are softening, hardly surprising, but adds weight to my hunch that earnings may have peaked for now -
“Towards the end of the year we started to see a softer trading environment, reflecting the uncertain macro-economic conditions, and we continue to monitor the trends across our regions. However, the strength of our contract order book, robust balance sheet and a diverse customer base underpins our business. Our well-established strategy focused on STEM skills and flexible talent is supported by global megatrends, reaffirming our belief that we have the right vision with a unique and resilient business model for the mid to long-term.”
Financial strength - is excellent, with £65m net cash at Nov 2022 year end.
I’d like all companies to report average daily net cash/debt, which is much more meaningful than a one day snapshot at the year end.
For more detail, I reviewed STEM’s interim results in some detail here on 26 July 2022. It passes my balance sheet testing with flying colours, so there’s little to no solvency rise in my opinion - a safe share to hold in a downturn, although obviously the share price might fall temporarily if there’s a nasty recession, as with almost everything.
Some other key points -
- Geographical spread - I like this, with Germany, USA, and Netherlands being the 3 largest markets, totalling 73% of revenues. That means it’s not too dependent on any one country, or currency.
- Repeating revenues - STEM mainly earns it revenues/profits from contractors, being 78% of net fees. I see this as higher quality income, because it repeats for the length of a staffing contract, rather than being a one-off placement fee.
- Order book looks good, being up 19% vs a year ago, hence decent visibility.
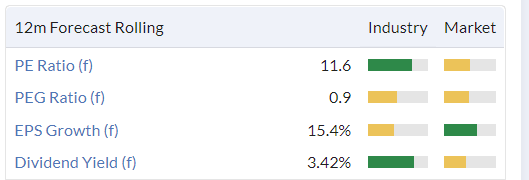
My opinion - I remain positive about this company. It looks a quality outfit, reasonably priced (fwd PER of about 10), paying decent divis of about 4%, and with very good financial strength including net cash.
That said, it sounds as if earnings have probably peaked for now, with softer market conditions noted for the first time today, in Q4. It’s now up against very strong comparatives too, so the next few quarters could prove challenging.
It’s forecast to achieve c.39p EPS for FY 11/2022, a PER of only 9.9, but what if that’s peak earnings, and 2023 delivers say 30p? The PER would only rise to 12.8, which still looks good value for a decent quality, well-run business.
Overall then, I’d say for patient, long-term investors, this share should do well. Shorter-term? It’s possible there might be some bumps in the road, if economies slow sharply, and earnings forecasts are lowered. Just a suggestion - it might be a good idea to hold a smallish position for the long-term, and keep some powder dry to buy any dips which might occur in 2023? But that’s up to you obviously, your money, your choice!
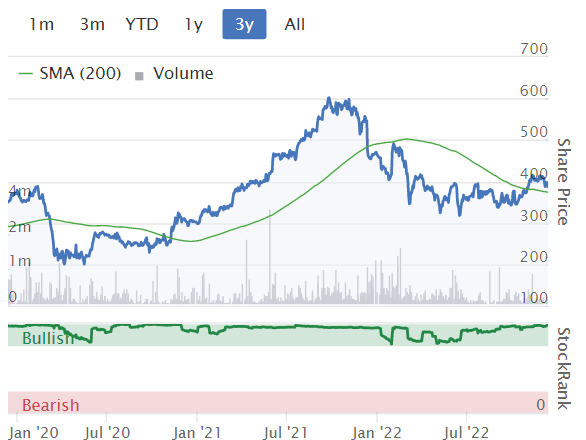
Consistently very high StockRank too, as you can see from the StockRank chart below the share price chart -
EDIT: I spoke to the CEO & CFO here on 6 Oct 2022 - audio here.
Graham’s Section:
Volution (LON:FAN)
Share price: 354p (+1%)
Market cap: £700m
This is “a leading international designer and manufacturer of energy efficient indoor air quality solutions”.
It has a year-end in July, so today’s AGM statement covers trading in the first four months of the financial year (August to November).
Group revenue for the four months to 30 November 2022 increased by 7% year-on-year at constant currency ("cc") to c.£112 million with organic growth of 5.5% (cc), delivered through a combination of both volume and price increases. All three geographic regions grew organically.
In inflationary times, and even in normal times, it would be helpful if more companies broke out how their revenue was growing. Is it mostly through volume increases, or mostly through price increases? But normally we are left to figure that out for ourselves.
With organic revenue growth of 5.5%, the price increases at Volution are very unlikely to be keeping up with consumer price inflation, but at least they are moving in the right direction.
UK: organic growth 3.8%. Weakness in the commercial market.
Continental Europe: organic growth 6.4%.
Australasia: organic growth 8.5%, with “market share gains in Australia”.
Performance overview:
Our excellent levels of customer service, focus on operational excellence, strong brands, attractive product portfolio and pricing power have all underpinned our ability to deliver on the Group's operating margin target. Given the economic environment it is pleasing that since the year end we have continued to see sales and profits track ahead of the same period last year.
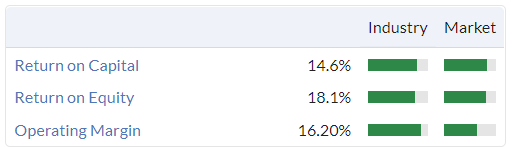
Note that Volution’s long-term target is to achieve an adjusted operating profit margin of greater than 20%. It did this in FY July 2022 (21.1%), and is doing it so far in FY 2023, too.
I agree with the company that this is a good financial KPI, so this definitely gets the thumbs up from me.
We should note that the actual (unadjusted) operating margin is not quite at the 20% level:
Regulatory drivers - “We continue to see strong regulatory initiatives driven by the need to decarbonise buildings, drive improvements in air quality, and reduce damp and mould in residential homes.”.
My view
Every time I come across this one, it strikes me as a decent-quality business. Stockopedia computers agree:
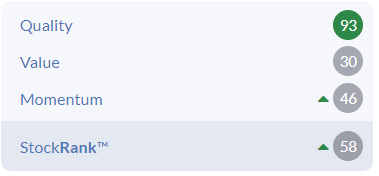
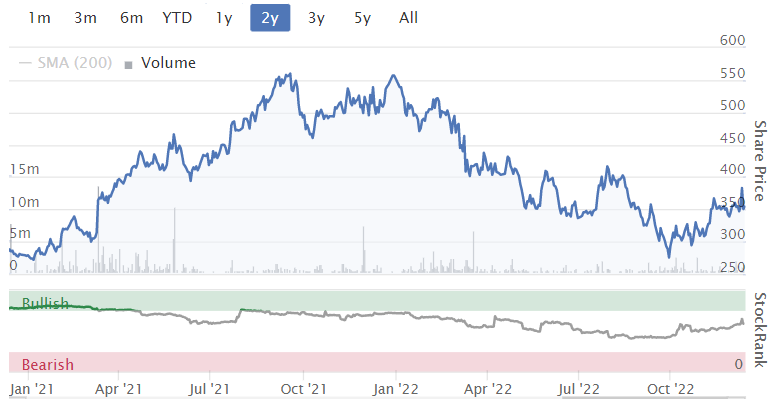
Before the crash in small-caps, it was trading at 550p. It is now down at a PER of 15x, offering the prospect of nice returns if it continues to execute. What’s not to like and what have I missed?
As I noted last time, net debt has risen to £85.8m, but the company considers this to represent “leverage at historically low levels, providing us with opportunity for potential earnings enhancing acquisitions”.
Net debt to EBITDA (the leverage multiple) was less than 1x for FY July 2022, so I can see where they are coming from. At that multiple, they will feel free to do more deals.
I’ll continue to keep an eye on this one, as it seems to have good potential for a recovery:
Cohort (LON:CHRT)
Share price: 443p (+8%)
Market cap: £183m
This is a small defence group - its businesses can be reviewed here. They provide surveillance, communications, sonar and data management systems.
Let’s see how the company has performed in H1 (the period to October 2022). The key point is that the current year outlook is unchanged.
- Revenue +29% to £77.5m
- Adj. operating profit £5m (last year: £1.7m).
The sharp increase in H1 adj. operating profit stands out. Covering the company exactly a year ago, Paul noted that H1 adj. operating profit had collapsed. It fell from £4.3m to £1.7m. But now it has bounced back again.
But we also need to bear in mind the strong H2 weighting. Last year, the full-year result was £15.5m.
This year, we have a recovery in H1 profits, with the help of a great increase in revenues, so maybe the full-year result is going to be stronger again?
In the last few days, the researchers at Edison have terminated their coverage of this company - I don’t know why. But for what it’s worth, their most recently published forecast was for Cohort’s FY April 2023 adj. operating profit to be £18.5m. This forecast is considered redundant now, since it can’t be updated, but I thought I would mention it anyway.
If that forecast remained valid, then the stock would be trading at about 10x its adjusted operating profits - not bad.
Order intake is smaller than last year but is still higher than revenue. So the order book keeps growing and hits a new record high (£304m). “Over £80m of revenue deliverable in the second half”, so that over 95% of this financial year’s revenue is already baked in.
Net funds: £7.6m (as of last week).
Outlook is unchanged for the current year, and there is “a positive outlook for organic growth in the medium term”.
Chairman comment:
"The Group's order book has steadily increased over the last few years to what is now a record high. Its longevity has also increased with revenue now deliverable out to 2032. The pipeline of order opportunities for the remainder of the year also looks strong. Demand for our solutions and services continues to be driven by the UK's increased spending on defence and security and by international tensions in the Asia-Pacific region and Europe.
Unadjusted results - I’d like to mention that the amortisation of intangibles and other factors cause a significant difference between adjusted profits and actual profits:
- FY April 2022: adjusted operating profit £15.5m, actual operating profit £11.1m
- H1 of the current year: adjusted operating profit £5m, actual operating profit £1.6m.
My view
I’ve skimmed the performance of Cohort’s subsidiaries, but there is too much detail in them to share with you here. With six subsidiaries, there is quite a lot of work required for investors to study each of them in turn. The big picture is that order intake remains broadly very strong, and the pipeline of opportunities is good, but there are challenges when it comes to margins, the revenue mix and supply chain delays.
Personally, I don’t invest in defence shares. This is not for philosophical reasons: I simply found that I had no clue what defence companies would earn in any given year! I tried investing in Chemring (LON:CHG) during a period of takeover rumours and when the takeover fell through, I was left holding shares in a company whose EPS might as well have been produced by a random number generator.
That having been said, the signals from management here are positive and the valuation does not look terribly stretched. Demand from NATO countries and from Asia-Pacific countries concerned about China is perhaps going to remain strong for the next several years. And the balance sheet looks ok: £10m of cash has been sucked into inventories, but a similar amount has been released from receivables.
Overall, therefore, this looks priced about right to me, and perhaps on the cheap end of the spectrum, given the positive trading momentum.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
£etp interesting couple of RNS at close, directors selling to support a new II, Charles Stanley Group.
Bodes well
Sureserve
One of my key holdings that was underperforming has staged a big recovery in the past three days .
Anything going on or just a recovery from oversold ?
Christopher Mills gave it a plug on a vox market interview with Paul hill .
Other than that nothing has changed, Still looks cheap but it looked cheaper at 67/68p.
Maybe some of the Crrestchic money is being reinvested into small cap value shares that were oversold and illiquid, market has been caught short with no stock and hence a strong bounce ?
Puzzled , but still too cheap .
Fackelmann GmbH + Co. KG have been buying into £PROC. They have a similar business in Germany.
LON:GMS. On the topic of fundraising and how difficult it is under the current circumstances I am wondering whether the latest RNS from Gulf Marine looks like it may soon be in that position - or am I misunderstanding the situation.? The RNS details are below.
Warrant Calculation
As previously reported, the Company is obliged to issue warrants to the
Company's consortium of lending banks ("Lenders") by 2 January 2023 pursuant
to the terms of the 2021 common terms agreement ("CTA"), in the absence of the
Company raising at least U.S.$50 million in new equity by 31 December 2022.
In anticipation of the issuance of the warrants in January, and pursuant to
the terms of the CTA and the warrant instrument, the Company has appointed a
calculation agent who has reported on the final exercise price of the
warrants, and the total number of ordinary shares that would be issued to the
Lenders if all of the warrants were exercised.
As determined by the calculation agent: the exercise price is £0.0711; and the total number of ordinary shares to be issued if all of the warrants are exercised is 110,964,433
@Berksbee,
My reading of today's RNS from Gulf Marine Services (LON:GMS) is that the company doesn't expect to be able to raise equity before the end of the year, so is preparing to issue the warrants instead. This is a fallback plan that's been previously agreed with its lenders.
In effect, the lenders are being given an equity option in place of a debt repayment. Exercising the warrants would give them a stake of around 11%, I think.
If the warrants are issued, the equity raise will then no longer be required. However, headroom under the firm's debt covenants will be more limited than it might have been, and debt service costs will be higher.
My sums suggest GMS is heading for a net debt/EBITDA multiple of around 4.5x at year end. That's not exactly comfortable, although it would be within covenants, I believe.
Much will depend on whether GMS can continue to trade well and repay debt on schedule over the next couple of years. There's certainly no room for disappointment, in my view.
Not a stock for widows and orphans...Thanks Roland - they seem to be generating cash right now so perhaps no immediate concern - but as you say, no room for disappointment!
Having another look at brick manufacturer Forterra (LON:FORT) this morning. Paul highlighted this a few weeks ago after a solid trading udpate and I put it on my watchlist - it's since fallen from around 220p to 190p so starting to look really good value now (especially since Michelmersh Brick Holdings (LON:MBH) has shot up around 20% over the same period). I like the sector as pricing power seems to be quite strong. Brick supply is very constrained in the UK and imports are expensive, so this should help cushion any fall in demand from the housebuilders.
SThree (LON:STEM)
I don’t see a lot of operational/earnings risk here RELATIVE TO VALUATION. There are still 1.7 vacancies for each worker in the US. Imagine how much bigger is the structural deficit in IT and engineering. The contractor order book is big enough to ride profitably through any coming slowdown. Yet the market will still push the price down if a US recession eventuates - a DACH one is already broadly expected. I’d say this is a good entry long term, short term - depends whether you expect a soft or hard landing. Fed speaks tonight but yesterday’s inflation print was helpful.
If I were to home in on a weakness, staff churn is unhealthily high and this, counterintuitively, is one of the reasons for the high and enduring productivity numbers. They will be struggling to bed down the next generation of high fee earners, while the well-entrenched old pros are cashing in. This is not unusual but it does point to a potential pause in the growth rate though I would not be worried long term as this is a business that trades on brand more than service quality.
Paul
it's really no surprise that Liberum estimates for SThree (LON:STEM) remain unchanged since the growth reported today largely repeats that of the Q3 TU. The quantum of profit may dip slightly as the year progresses but margins and cash generation will keep ship ploughing ahead. One of my favourites
I hold
UK inflation increased by just 0.4% in November (around 5% if you annualise this monthly rise), so does seem to be finally easing. Pound is a lot stronger recently, so that should help too by reducing import prices.
Seraphine (Bump)
I was picking up a few Bump shares recently as I figured it has a chance of some sort of recovery .
Just a stock reduction and get back to the day job .
Just had a quick look at trust pilot and that is not good reading at all . Refunds don’t seem to be getting sone promptly which is not ok .
Hi planetx
The UK Trustpilot reviews were what put me off purchasing £BUMP. If i have it correct they have a central operation in mainland Europe working from one location. I wonder if that's what causes the delay in refunds for UK customers. It seems that on Trustpilot European customers don't have the same gripes.
Hi planetx,
You're right, refunds have been a problem at £BUMP (I hold), as reflected in the complaints on TrustPilot. I've discussed this with the company, and they very much acknowledge refunds have been far too slow, caused by various logistics problems (e.g. US postal system in total chaos apparently), operating from a central warehouse in Belgium, for UK, EU, and USA.
But, I understand that reverse logistics companies have now been set up to handle returns, and bulk ship them (by air actually) back to the central distribution warehouse in Belgium. That went live very recently, and mgt hope that in 6-8 weeks the problems should be resolved, and negative reviews should then stop, or greatly reduce.
The CEO said that slow returns & hence refunds has been his biggest headache, and they're very aware of poor customer service, "I want to shoot myself in the head every time I look at TrustPilot". But it sounds like a solution has been found, and is being implemented.
Regards, Paul.
P.S. Bear in mind that BUMP average selling price is high, and the gross margin very high. Therefore cost of returns is not such an issue as with the low value fast fashion companies like BOO. So the issue has been logistics, creating slowness of refunds.
P.P.S. I should again emphasise, as mentioned here before, that BUMP should be considered a high risk share. So personally I've only invested money I can afford to lose.
Paul
Trust me I been in that exact situation when my at the time CEO did the genius move of moving warehouse and implementing a new warehouse system the result total operational meltdown .
I am not a fan of third party logistics and it does result in both a loss of control and more importantly a loss of ownership, Very easy to blame “our warehouse” or “our 3rd party logistics “
I’m tempted to give the Bump CEO a call as I have that train ticket well and truly stamped .
I’m still holding some Bump Shares but that’s not going to a quick fix for sure.
They do not seem very “lean” with an LSE listing , logistics in Europe , USA , and UK , presumably customer service in UK .
CS staff will probably be leaving by droves as no staff member wants to be dealing with upset customers all day, They then have to replace and new staff don’t quite care as much etc .
Does feel on a slightly slippery slope .
Having said that “cometh the hour cometh the man” and time for a CEO to stay the course and get his team to the other side .
Looks super high risk and the share price doesn’t have much underpinning it with wild swings as no liquidity at all apart from everyone bailing out who bought at 100 plus million valuation .
If they remember the key point to sort their customers out probably has hope .
As a one-time cheerleader for Trackwise, I apologise if I encouraged anyone to invest. They have been over ambitious rather than dishonest, and unwisely over reliant on one client. But this is a disaster and, as Paul says, this is not the time to be needing cash.
Losses aside, I hope this raise is sufficient to keep the company alive. The country needs innovative engineers.
jonthetourist,
What a gentleman you are, that's very kind to post an apology, but it's really not necessary. You simply gave your honest opinions, and we could all see TWD was high risk. So it's definitely not your fault in any way. We're all grown-ups, and do our own research, and make our own buy/sell decisions. So please don't feel in any way responsible for share ideas that go wrong - we all have plenty of them!
Best wishes, Paul.
Afraid I too have been a cheerleader. Very sad day. Despite losing quite a bit on this one I'm also feeling sorry for the founder who must have had the majority of his paper wealth wiped out over the last year or so. Previous CFO got a lot of flack but he too has lost a significant sum buying shares £2plus. I really hope this survives because the tech is excellent and unique and the UK economy needs more manufacturing tec companies.
Hareorth
I met a friend yesterday with 15 year experience running a wind farm company for Danish owners and subsequently sold to a bog pension fund .
Is striking out on his own as “it’s now or never” and the push to allow England to develop its onshore wind was finally getting government backing .
Anyway the two names that popped up holding land in suitable locations were Hargreaves and Harworth .
He did say both were a nightmare to work with .
Hateorth looks interesting to tuck away in a pension but I’m not totally familiar with it but my fag packet slide tile liked it last night .
Sny Hayworth holders got an opinion !
Harworth (LON:HWG) are a land developer (previously part of British coal) that regenerates old industrial sites and sell plots on to housebuilders. It also has an industrial/warehouse portfolio. Good long term track record in terms of NAV growth, but trading on a roughly 50% discount so looks very cheap on paper. Only thing I'm not keen on is they don't pay any meaningful dividends and seem to have ruled out buybacks, so would like a bit more focus on retuning money to shareholders.
Thanks planetx. I wondered why Hargreaves Services jumped 11% a few days ago so perhaps this may explain why. Developing its land as sites for renewable energy is very much part of the company's plans. I don't know if they are a nightmare to work with but my impression is that they are capable negotiators, hence the cost-plus contract on HS2 earthworks. I am surprised that, as far as I am aware, the UK does not have companies which are global players in the wind farm industry, it is amazing how concentrated this expertise is in another windy country, Denmark. A wind farm development I am helping to fund, together with another 5,000 members of the co-operative, has engaged a German company (Enercon) to supply its turbines.
Sorry to bring a slight note of caution to the discussion of Harworth & Hargreaves, but there are a few things worth remembering with both companies.
The vast majority of the original landholdings of both are old opencast mines with a few much smaller areas of either deep mine surface enclosures or opencast disposal points and routes. The problem with the old opencast sites is that they were normally backfilled without compaction often to a depth of 100 metres or more. The state and depth of that backfill was also very variable depending on where coal seams were and differences in plant used (eg. huge dragline with bucket capacity of up to 40m3, motor scrapers which would provide reasonable compaction by their operating method or shovel and truck with rock size very dependent on size of excavator and truck - but trucks carrying 200 tonnes were common). Settlement periods to be reasonably confident for subsequent use of these areas without remedial works is measured in decades, and even then some investigative work is needed. It is worth reading in the ARs the costs associated with the work needed to fix Blindwells before sales began for housing areas.
Perhaps the negotiations about necessary investigative or remedial work costs are the reason for the "nightmare" comment. I would think that building a huge wind turbine on uncertain ground needs a lot more assurance than housing.
Hargreaves do not own or build any wind farms after they floated off the subsidiary they had starting up in that field a few years ago, and I haven't read their recent ARs to see what deals they may have achieved with WF owners. The size of areas "rented" by WF owners will be interesting as the really big opencast sites often had very substantial areas for soils and overburden storage, offices and workshops, which were never excavated and would be prime areas after being effectively compacted from normal state by an overburden heap perhaps 40m high.
Just as a matter of fact the "cost - plus" nature of the HS2 contract would have been absolutely the normal contract conditions, not negotiated ones.
Thank you muckshifter .... this is gold.
Re Harworth (LON:HWG) did you mean your friend is looking for land from Harworth/Hargreaves or the government? Harworth seem quite a solid company and are trading at 50% of NAV as Bouden54 mentions. Their CEO is experienced and moved from Town Centre Securities (and before that Manchester Airports). They come across very capably on the Investor Meet Company presentations. I have held their stock for a couple of years and am not selling.
From memory Harworth (LON:HWG) had a lot of land along the HS2 route, think M42, M1 and M6 corridors, so looking at the big industrial park sites next to junctions type stuff, for which there was a structural deficit for a long time with outline planning on, so they were buying and then trying to get the planning and agreements.
From interactions with developers in this area over the years, they have to be very hard skinned as they are often taking on legacy sites and issues and planning on the 10-30 year period of how they can get remediation, re-zoning, planning approvals for land which sometimes has significant historic issues and is in the "too difficult" box for councils. Thinking of legacy British Steel, British Coal and such like, or even Teesside, or Stratford / Kings Cross for those south east based. Without getting into the other Statutory Undertakers and Authorities involved.
Should we also mention that everyone wants to get the best of the deal! So I can think of several reasons why a potential developer describe the existing landowner as "hard nosed" when trying to strike a deal, obviously I want to pay £x and they want me to pay £xx++.
Having worked at Ebbsfleet Station, how long has it taken the development in the former chalk quarries away around the station, when right next to a fast train to Kings Cross, slow train to Charing Cross and the A2 and M25? Just an example of prime development which got government zoning support and a government agency support and still took years and years!
Cohort (LON:CHRT)
Decent in-line trading update with this defence contractor with a record order book. Expecting further revenue growth for H2 with 95% covered by orders, and an order book of over £300 million stretching to 2032. Supply chains still a little tight.
Revenue up 29% to £77.5m (2021: £60.0m).
Adjusted operating profit up significantly to £5.0m (2021:£1.7m)
Strong adjusted earnings per share of 10.12 pence (2021: 3.04 pence).
Its an ugly truth that the need for defence spending, particularly in the electronics sphere, will be a growing requirement for years to come and Cohort (LON:CHRT) and Concurrent Technologies (LON:CNC) (also with a partnership update this morning) give British small cap exposure to what IMHO is a growth area.
(I Hold Both)
Hooray, we got the whole lot done!
Volution (LON:FAN)
Further to yesterday’s discussion, here’s a company that has perhaps received only passing attention on the SCVR, helpfully putting out a positive TU this morning. I mentioned it two days ago when bid speculation briefly lifted the shares but that quickly reversed yesterday.
Excellent operating numbers - gross margins almost 50%, operating margins >20%, ROICs >20%, regulatory and energy transition drivers (ventilation and heat recovery), diverse geographical exposure, low leverage so M&A optionality, organic and inorganic growth without share dilution. And good value for a quality issue. What’s not to like?
Please can you look at today gents (previously only covered in a “no section below” fashion)?
EDIT: Thanks for covering Graham. I wouldn’t watch for too long but I do think markets might hit a cyclical low in Q2 ‘23 representing an optimal entry point. Alternatively, investors might stay buoyed by data like yesterday’s helpful inflation print, which the Fed will try to quash this afternoon, and that extra -20% may not present itself! Who knows?
BnB the rising Debt has always put me off Volution (LON:FAN) but looking at broker forecasts this looks to be coming down significantly over the next few years, into cash which is good News if they can deliver..
Net Cash/(debt)
2022 - (61)
2023 - (30)
2024 - 2
2025 - 22
2026 - 60
Feeling more bullish on this one.
Got the ticker for Mirriad Advertising (LON:MIRI) wrong. Reading Paul's comments got me to look at the Stocko report for Apr 21. The PSR was an amazing 91. Losses expected for years. The only broker (Canaccord?) rated it a strong buy. https://s3.eu-west-1.amazonaws... Found a broker rating history at https://www.lse.co.uk/ShareBro...
Trackwise Designs (LON:TWD)
Mr. C - you were right! 24/6/22:
"TWD did a placing and token OO in Jan at 80p, a disgusting 45% discount. The rev f/c at the time (and until yesterday) turned out to be fantasy at £21.5m. Now the SP is 50p
Holders should not be surprised to be shafted again".
https://www.stockopedia.com/co...
Yes, they have been and what is more the company was "pleased" to tell them that. I can only think that the pleasure was at not having to tell them that they were going into administration.
Mercifully although I followed this I never bought but will continue to follow because I think the product has potential.
In September finnCap said: "We still consider the group’s IHT technology has substantial medium-term prospects, especially in the burgeoning EV battery cell connection systems (CCS) area, however the short-term outlook looks unclear. We therefore remove our forecasts and take our price target under review".
Theirs was the only forecast so why does Stocko still lure us with eps to 12/22 of 5p and PT 315p? The last time I moaned about this I was told "As we go forward, we plan to handle stale estimates differently, for example, by highlighting them in a different colour - eg. a light shade of amber. Removing them completely may be jarring for users". I find it jarring leaving them in!
re Trackwise Designs (LON:TWD)
Hadn't previously looked at this one before but noticed that the CEO (who bought the company in 2000) is basically a clever inventor (per his CV on the company website).
Did he ever possess the skills required to be a successful CEO? Seems like a potential major red flag (in hindsight of course).
Snazzy
Just wanted to say, that for me personally, the mix of short comments and longer investigations, really works. I also like the focus on small caps, with the occasional digression into macro conditions. Having brief post mortems on failures and shares to avoid also helps, as it gives warning signs to look out for.
So thanks again Paul and Graham.
I do agree with some contributors, that foreign stocks and mid caps would be interesting, but I think that would require new dedicated writers. It is too much to ask of Paul and Graham and would dilute their focus.
But remember that the community comments , on mid and large caps as well as non-UK shares, are equally useful. Paul needs to start a dialogue and others may like to pick up where he drops.
Elio has been recently covering Australian stocks and Roland has just focused on large and medium cap stocks in the packaging sector. I think the balance is pretty good at the moment. If you're a private investor struggling to make progress in a bear market a small cap focus seems about right.
I do agree with some contributors, that foreign stocks and mid caps would be interesting, but I think that would require new dedicated writers
As I mentioned yesterday, there is Megan already installed. The frustration is that she’s covering yesterday’s winners (Vodafone, Facebook), not tomorrow’s. I would steer her towards life sciences, digital health, digital transformation/security and the energy transition.
The frustration is that she’s covering yesterday’s winners (Vodafone, Facebook), not tomorrow’s. I would steer her towards life sciences, digital health, digital transformation/security and the energy transition.
Given Stockopedia has limited resources - people can check out their accounts at Company's House if they like - then it would be better that they focus on areas that aren't well covered elsewhere. I can't see any informational advantage in Stockopedia covering large cap UK stocks of any kind.
I also think it would be useful when people suggest that Stockopedia (or Paul or Graham) do additional things that they also indicate how much extra they'd be willing to increase their subscriptions to pay for the extra content.
As it stands I think the SCVR authors do a good job, although personally I'd prefer they cover a few less companies and in more detail. Most posters seem happy enough with the existing approach however. Whatever they do they won't please everyone.
timarr
Well if you’re not happy with what anyone else is doing, as seems to be the case why don’t you do it yourself then you could decide exactly what is covered?
The point is not whether I’m happy. It’s that Paul has complained at how many grumblers there are. Check also the number of thumbs up to my post yesterday which started the conversation. You don’t seem to have picked up on that.
Furthermore, Paul asked me for specific names and this morning I gave him one of my neglected (by SCVR) mid-cap holdings together with a brief précis. The guys kindly picked up on it and give the name a deeper dive than it had enjoyed previously, coming out with thumbs up. So hopefully we’re all winners for a bit of polite debate.
Volution (LON:FAN) is a 600m company which is within Paul's remit of <700m for the small cap report and has been covered before.
Volution (LON:FAN) is a 600m company which is within Paul's remit of <700m for the small cap report
Yet it hasn’t had a proper report in over 3 years, during which period it has doubled its profits and dividends without any share dilution. Thank you for highlighting my point.
Meanwhile we’ve had umpteen reports on shitshows like Joules and Made.com. Yes, they make entertaining watching but I personally feel a refocusing towards higher quality is in everyone’s interests. You may disagree.
I think there are lessons to be learnt from the reports on Joules and Made.com.
I welcome these reports, if only to learn what went wrong with them.
I think there are lessons to be learnt from the reports on Joules and Made.com.
I welcome these reports, if only to learn what went wrong with them
So do I. But such was their preponderance that I’m willing to bet there are those here who got sucked in to their considerable cost. To be clear, I’m not blaming Paul or Graham for investors’ mistakes but they are arbiters of the forum’s focus. Meanwhile, you could have doubled your money on Volution (LON:FAN) and hopefully look forward to further attractive returns when current cyclical fears abate.
Far too much coverage on the retail sector, most stocks have gone wrong, Motorpoint (LON:MOTR), ASOS (LON:ASC), Joules (LON:JOUL), £BOO Why is Stockopedia spending so much time one sector?
Yet better performing companies get little coverage. No coverage of £YU for 3 years on SCVR. Maybe the emphasis is too much on value rather than momentum?
Totally agree. I read and keep track of Paul and Graham's daily SCVRs religiously every trading day and - as I have said before on here - they are worth the price of subscription to Stocko alone.
Consistently excellent work Paul and Graham.
Dear Paul, Graham, Ed, & The Stocko Team,
Just want to say a BIG thank you for all of the hard work you guys put into providing excellent thought provoking and inspirational content every day. Even during the hard times when the bear is mauling at our portfolios and the tide is low for all boats you are continually on the look out for good value opportunities for us. Most importantly you're brave enough to put them out there and share your thoughts with the reasoning behind them. Respect to you all for that and to all of the good people in the community that regularly take the time to post brilliant content and share their knowledge. It's very much appreciated.
All the best,
Uncle G
£ BILN Billington (I hold) issues a promising trading update.
"The Company is pleased to report that trading has continued to improve. Consequently, the Company now expects adjusted profit before tax for the year ending 31 December 2022 to be significantly ahead of the Board's previous expectations, with revenue remaining unchanged.
The order book, combined with further opportunities also provides increased confidence for 2023 and the Company now expects adjusted profit before tax for the year ending 31 December 2023 to also be significantly ahead of the Board's
previous expectations."
Hoping for a nice price increase today.
£BILD is first on my list to check out. Held shares in it years ago but not currently.
£BILN was also on my shortlist for a while, but I held off investing because it is a big energy consumer, and from next April onwards, the govt support for business energy is gone. So there is uncertainty there, about a big jump in electricity costs.
Today, they upgraded forecasts for next year. Presumably, they include the assumption of higher energy costs? Or not? Hard to tell definitively. And no mention at all about mitigating inflationary costs of energy or steel prices.
Any thoughts from anyone?