Daily Stock Market Report (Thur 22nd Oct 2026) - BMY, ARBB, CAM, REC, ESNT

No major financial news overnight, so I thought I’d mention something less serious: the news that AirBnB won’t let hosts require their guests to clean their properties any more.
I’ve never had a really bad AirBnB experience, but it’s also been a few years since the last time I used one.
I think my issue with the platform is that you end up spending hotel-like prices, but then you don’t get an experience that matches up with hotel expectations. I’d rather stay in an average hotel.
So I’m pleased to see that the platform is now requiring hosts to treat its guests more like the paying customers they are: from next month they can no longer tell guests to wash and put away dishes, strip beds and do laundry, or carry garbage to outside bins.
The funny thing is that in most cases, customers have already paid something called a “cleaning fee”! Why did hotels never think of that?
Overnight market movements:
The FTSE is down 0.4% at 10,700
S&P 500 is down 0.8% at 7,700
Brent crude (December) is up 2.5% at $110.50/bbl
Gold is down 1.2% at $4,090oz
Bitcoin is down 2.2% at $82,700
Mark Simpson and Dr. James Fox are writing the company analysis today.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£196bn | SR55) | Ultomiris has been approved in the US to reduce proteinuria in adults with primary immunoglobulin A nephropathy (IgAN) at risk for disease progression. | ||
Barclays (LON:BARC) (£55.9bn | SR65) | Return on tangible equity of 11.7%, on track to deliver 2026 and 2028 targets. Q326 EPS of 12.3p, up 18% year-on-year and 43.0p year-to-date, up 23% year-on-year. | ||
Relx (LON:REL) (£51.8bn | SR58) | Underlying revenue growth year-to-date 7%. “Expect another year of strong underlying growth in revenue and adjusted operating profit, as well as strong growth in adjusted earnings per share on a constant currency basis.” | ||
London Stock Exchange (LON:LSEG) (£42.3bn | SR43) | Q3 total income +8.8%. Raising revenue, margin and cash flow guidance: expecting full year growth of at least 8.0%, EBITDA margin expansion of 100-120bps, and equity free cash flow of at least £2.8 billion. Acquiring Octus (provider of credit solutions) for $3.535 billion. | ||
Intercontinental Hotels (LON:IHG) (£18.7bn | SR60) | YTD global RevPAR +4.6%. Confident of achieving consensus expectations for the year. | ||
Pearson (LON:PSON) (£8.19bn | SR73) | On track to deliver 2026 guidance of mid-single digit underlying revenue growth with a narrowed adjusted operating profit range of £650m-£675m (previously £640m-£685m). | ||
J Sainsbury (LON:SBRY) (£7.97bn | SR48) | Argos sale to complete by end of Feb 2027. Previous profit guidance would be equivalent to a range of £965 million to £1,065 million on a continuing operations basis. SBRY raises the lower end of this range: new range is between £1,025 million and £1,065 million. | ||
Rentokil Initial (LON:RTO) (£7.95bn | SR47) | Organic Revenue growth of 3.4%. Expect to deliver FY 2026 profit in line with current market expectations. CFO to retire from full-time role from Jan 2027 for family health reasons. | ||
Renishaw (LON:RSW) (£3.89bn | SR75) | Q1 revenue 47% higher than a weak comparator in the prior year. 3% higher than Q4 2026. “We continue to expect strong progress on revenue and operating margin for FY2027 as a whole.” | ||
Inchcape (LON:INCH) (£2.32bn | SR60) | Q3 volumes up 3%. Organic revenue growth 1%. Expecting FY 2026 adjusted EPS growth of c.10% despite lower operating margins. Organic volume growth expectation unchanged. Adjusted operating margin 5.5% due to underperformance in Australia. | ||
AJ Bell (LON:AJB) (£2.3bn | SR84) | Customers +24% to 796k, AUA +225 to £126bn. “Our long-term growth opportunity remains significant, with the structural drivers supporting the platform market firmly in place. We look forward to announcing our annual results in December for what has been another successful year.” | ||
Harbourvest Global Private Equity (LON:HVPE) (£2.29bn | SR67) | Results for the Six Months Ended 31 July 2026 & Launch of Tender Offer | NAV ps +2.4% to $60.82. Net portfolio cash flow of $234m including secondary sale proceeds. Net debt down $107m to $340m. Tender offer for $400m, at NAV. | |
Rathbones (LON:RAT) (£1.73bn | SR37) | FuMA +7.2% YoY to £121.1bn and nine-month operating income +6.7% YoY £731.1m. Continue to expect to meet underlying operating margin target of 28.7% in Q4. | ||
IP (LON:IPO) (£620m | SR81) | Revenue and adjusted EBITDA performance in FY26 is expected to be slightly ahead of current market expectations ($249.9m revenue, $86.3m Adj. EBITDA.) | ||
Auction Technology (LON:ATG) (£588m | SR52) | Revenue and adjusted EBITDA performance in FY26 is expected to be slightly ahead of current market expectations ($249.9m revenue, $86.3m Adj. EBITDA.) | ||
Bloomsbury Publishing (LON:BMY) (£548m | SR81) | H1 Revenue -5% to £151.6m, Adj PBT -30% to £16.8m. Net cash £22.8m (26H1: £2.4m). Confidence in delivering record results in line with Adjusted Profit expectations. (£354.3m revenue, £49.9m Adj. Profit). | AMBER/GREEN ↓ (Mark) | |
Essentra (LON:ESNT) (£320m | SR62) | Q3 Revenue +14.6% CCY. FY26 adjusted operating profit expected towards the upper end of market expectations. (Consensus Range: £32.3m to £34.3m.) | AMBER = (Mark) | |
Secure Trust Bank (LON:STB) (£268m | SR84) | Q3 Loan Book +1.4% to £3.5bn. Customer deposits remained broadly stable. Credit performance has remained robust. “While softer market conditions in asset-based lending have impacted fee income in Business Finance, we remain on track to deliver consensus FY 2026 profit before tax expectations, supported by growth across the broader business.” | ||
Cab Payments Holdings (LON:CABP) (£211m | SR43) | 9m total income +22% to £102m. The Group looks forward to completing a successful year notwithstanding a particularly strong comparator in the fourth quarter last year. | ||
Synthomer (LON:SYNT) (£186m | SR90) | Q3 performance in line with previously upgraded expectations for the full year. | ||
Camellia (LON:CAM) (£145m | SR75) | Trading result for 2026 is expected to be weaker than previously anticipated. Forecasts full-year revenue to be £255-£26m, compared with £268m in 2025. The reduction principally reflects the sale of some Indian tea gardens and lower macadamia and avocado sales. The current forecast is for a full-year trading loss of between £3-5m compared with a trading profit of £1.0m in 2025. | AMBER ↓ (Mark) | |
Arbuthnot Banking (LON:ARBB) (£131m | SR74) | Customer loans and leased assets +12% to £2.5bn. FuMA +21% to £3.1bn. Customer deposits +10% to £4.9bn. | GREEN ↑ (James) The shares trade at less than half of book value and yield about 7%, before brokers update their forecasts for today’s upgrade. | |
Arrow Exploration (LON:AXL) (£111m | SR88) | Current total corporate production is over 6,500 boe/d, including production from Icaco 8 (IC-8) and Icaco 7 (IC-7). 1 Oct estimated cash balance is over US$28 million | ||
Record (LON:REC) (£86.6m | SR83) | AUM +7% in Q2 to $130.3bn, incl. $10.4bn net flows. Performance across the Group remains in line with expectations for the full year. | AMBER ↑ (Mark) | |
KRM22 (LON:KRM) (£20.5m | SR19) | Two new 3-yr customer contracts for the Risk Manager application worth $1.3m total. Total ARR goes up to £8.5m. | ||
IXICO (LON:IXI) (£18.6m | SR25) | two contracts with a combined value of approximately £1.5 million. 1st is with a biotechnology company to manage and analyse neuroimaging for a Phase 2b clinical trial in AD. Revenue over 3 years. 2nd is a contract extension with an existing large international life sciences and diagnostics client. Revenue over 1 year. | ||
Kakuzi (LON:KAKU) (£18.1m | SR67) | Expects net earnings to be significantly below the previous year as a result of the continued downturn in the macadamia market and a lower macadamia crop.
| ||
Metals One (LON:MET1) (£16.3m | SR16) | Entered into a binding term sheet for the proposed acquisition of the remaining interests in LBR that Metals One does not already own. | ||
ARC Minerals (LON:ARCM) (£14.8m | SR27) | "We have moved to an important stage both in Botswana and Zambia. At the Virgo project, the ambitious drilling campaign has now started and is progressing well. In Zambia, we are moving the dual strategy at the Kabompo project to an advanced phase with a number of active discussions being pursued" |
Mark's Section
Bloomsbury Publishing (LON:BMY)
Down 9% at 615p (£548m) - Interim Results - Mark - AMBER/GREEN ↓
Context:
Bllomsbury was a big winner for holders coming out of the COVID period, with the shares delivering 3x returns to the end of 2024. However, the recent share price performance has been choppy:
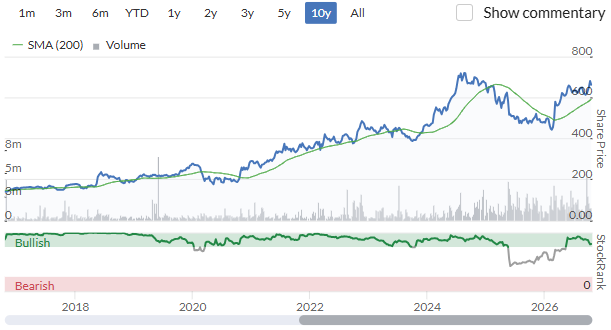
Interest in the stock has been reinvigorated by an upgrade to FY27 forecasts earlier this year:
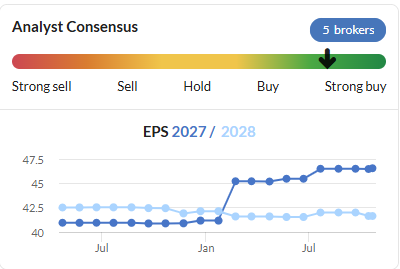
This trend led Roland to upgrade our view to GREEN when the FY26 results were published in May.
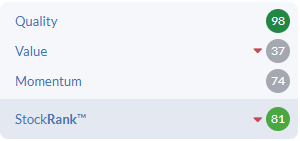
However, going into the H1 results, the share price had risen over 40% on a FY27 consensus that had only risen by 13%. The FY28 consensus had been slightly downgraded during this time. The net result is that the stock doesn't look particularly cheap, and the company goes into these results with high expectations from investors for further upgrades:
H1 Headlines:
While not an upgrade, the in-line headline gives initial reassurance:
Bloomsbury is pleased to report first half revenue of £151.6m with profit of £16.8m and a strong start to the second half of the year, underpinning the Board’s confidence in delivering record results for the full year.
However, I am always a little suspicious when no comparatives are quoted.
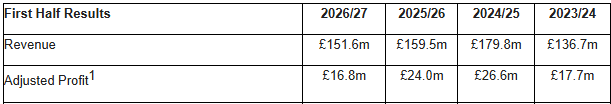
Percentages are still missing from the comparative table, but my maths suggests that revenue is down 5% and Adjusted PBT down 30%.
The context suggests that this was a weak half for both the Consumer division and the Academic & Professional one:
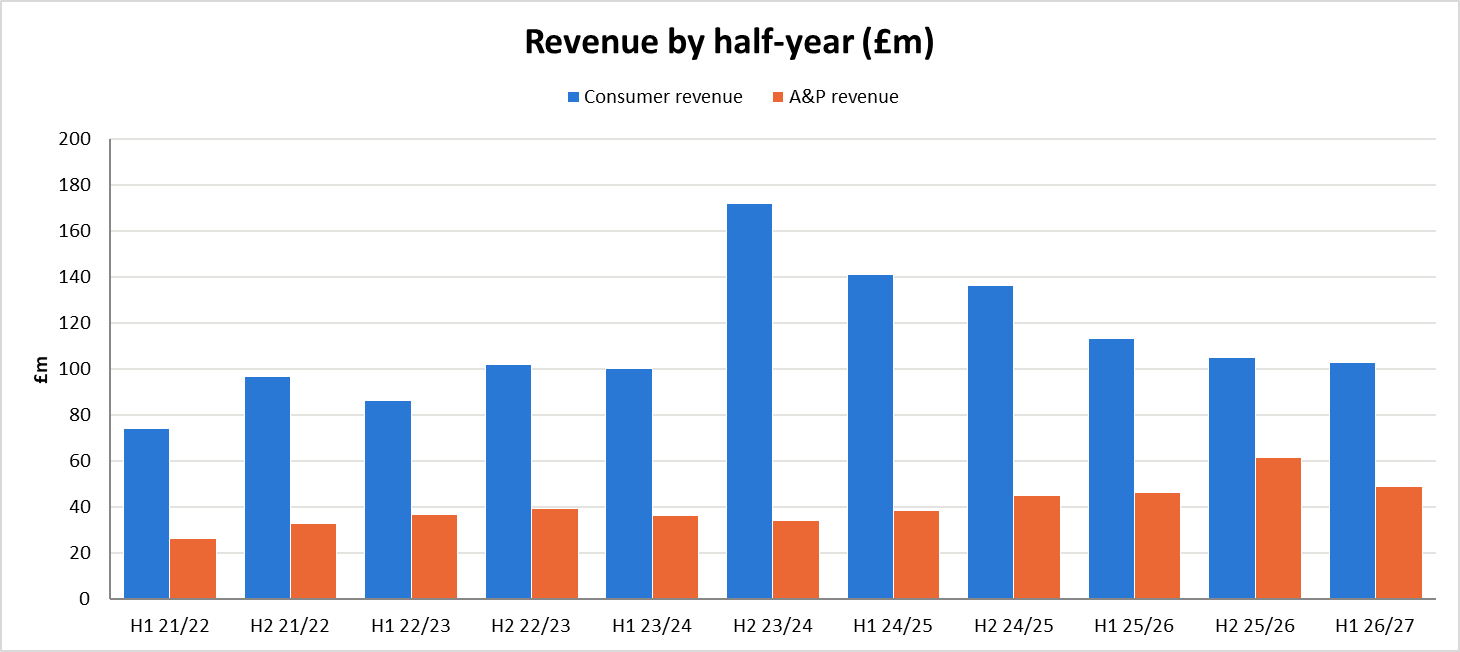
While they say:
A&P revenue is up 5.9% to £48.8m (H1 2025/26: £46.1m), showing encouraging signs of recovery
Operating profit in this division is down significantly:
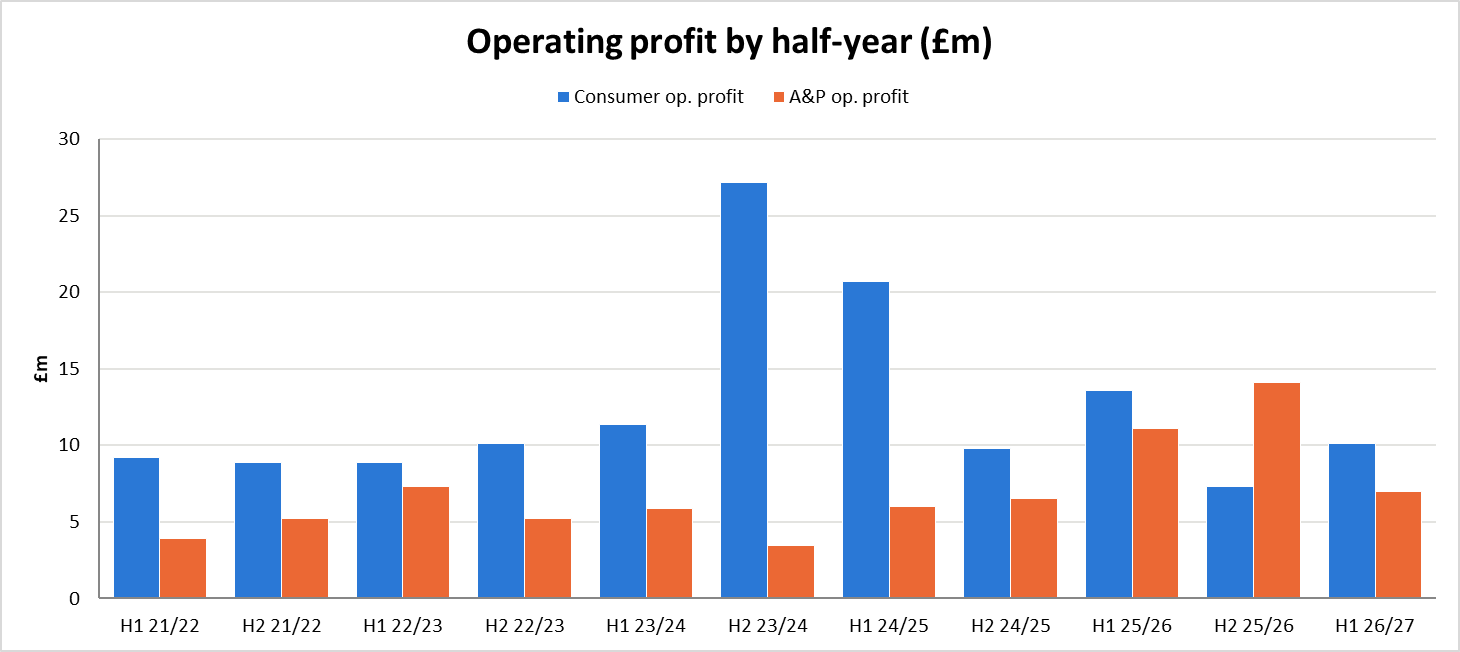
Caused by much lower margins:
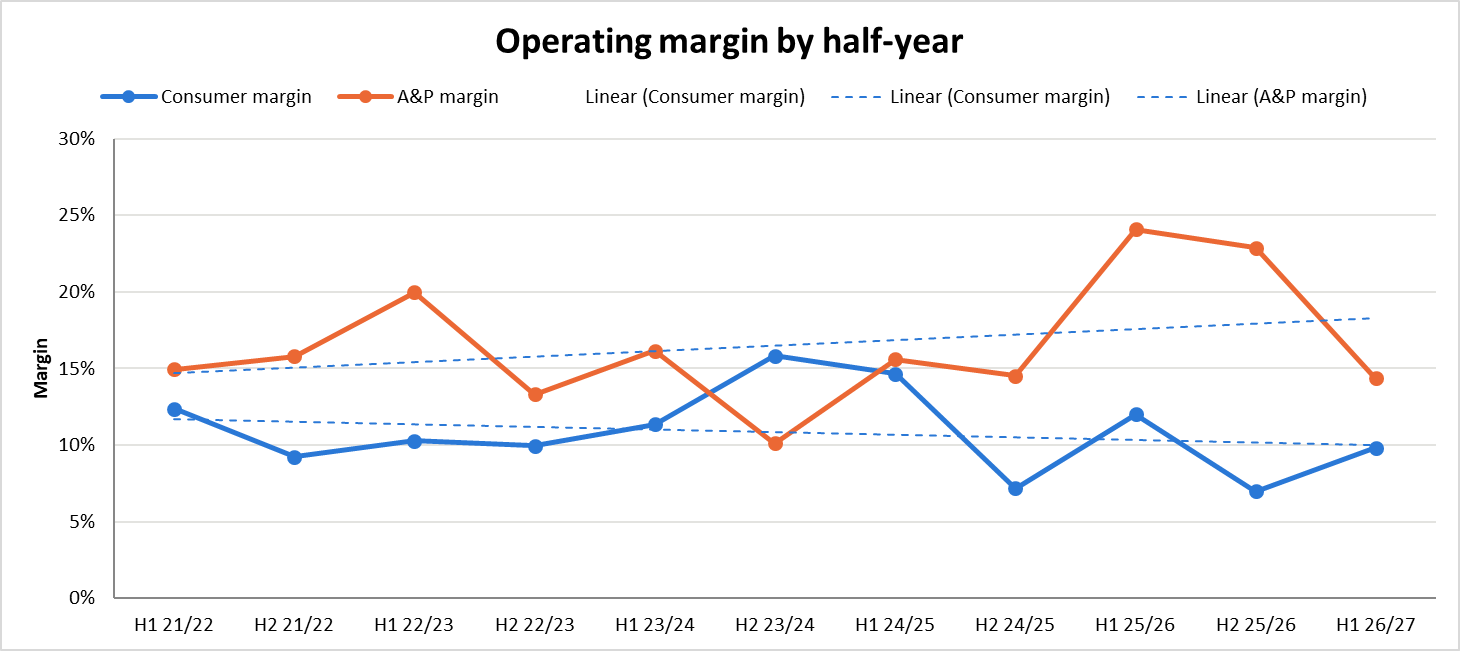
It may be too soon to conclude that the recent upward trend in margins in the A&P division is about to reverse. However, the risk that the previous two halves were anomalously high increases.
Adjustments:
As well as profits being down, the level of adjustments required to get there has also increased:
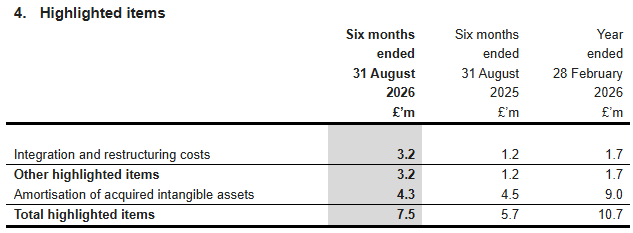
While amortisation of acquired intangibles is largely flat, there has been a big jump in restructuring costs. While these are probably the right thing to do and should drive improved profitability in the future, this doesn't suggest a business firing on all cylinders. Their narrative around this doesn't suggest that this process is complete:
We are progressing with key operational changes to support growth and enhance profitability through financial efficiencies. In April 2026, we announced a restructuring, and we have taken the first steps to simplify and streamline our structure. This has enhanced agility, accountability and positions the Company for continued expansion.
[my emphasis]
That the company appears to have repeated integration and restructuring costs, and is guiding for these to continue, makes these look far from one-off.
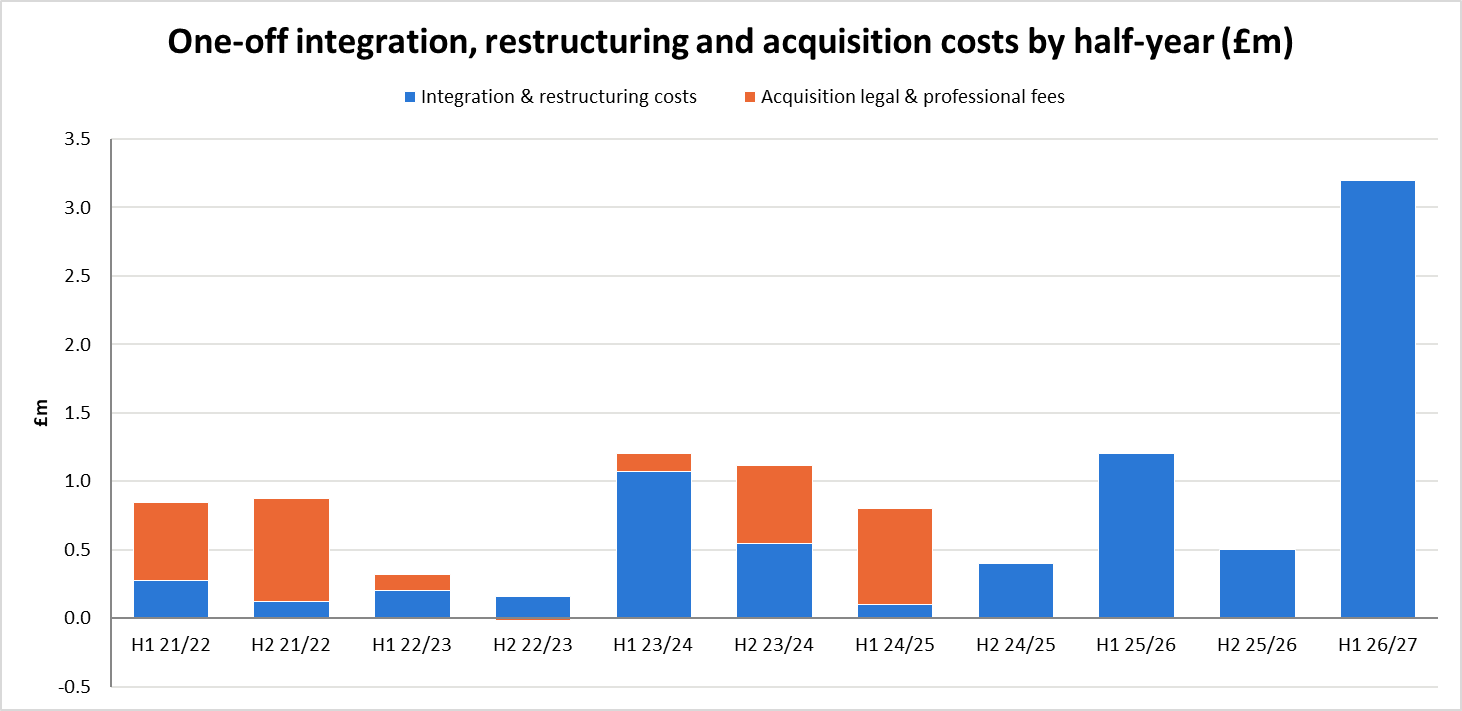
At the very least, the company wants us to give them the benefit of all the cost savings without counting any of the costs of achieving those savings against them.
Outlook:
Despite the weak half, the company say they are in line for a record year:
The Board looks to the current year with confidence in delivering record results in line with Adjusted Profit expectations....Bloomsbury’s portfolio of portfolios strategy, our authors, customers and the scale and resilience of our business continue to underpin the confidence we have in the future.
And helpfully, give us the consensus:
The Board considers consensus market expectation (before this publication) for the year ending 28 February 2027 to be revenue of £354.3m and Adjusted Profit of £49.9m.
There are reasons to think that the second half will be stronger for the consumer division:
Growth is second half weighted and the new novels for H2 2026/27 include many of our bestselling authors. In September, Gillian Anderson’s follow-up to Want, titled More, and Stephen Graham’s Letters to Our Sons, became instant Sunday Times bestsellers. Sarah J. Maas’ much anticipated next two novels in the A Court of Thorns and Roses (‘ACOTAR’) series, A Court of Splintered Harmony and A Court of Forgotten Melody, will be published on 27 October 2026 and 12 January 2027, respectively.
Forecasts:
I can't see any updated note from their broker, Singer. Still, taking the FY27 revenue forecast from earlier in the year, where Singer provides the split between Consumer and A&P revenue, then this is the implied H2:
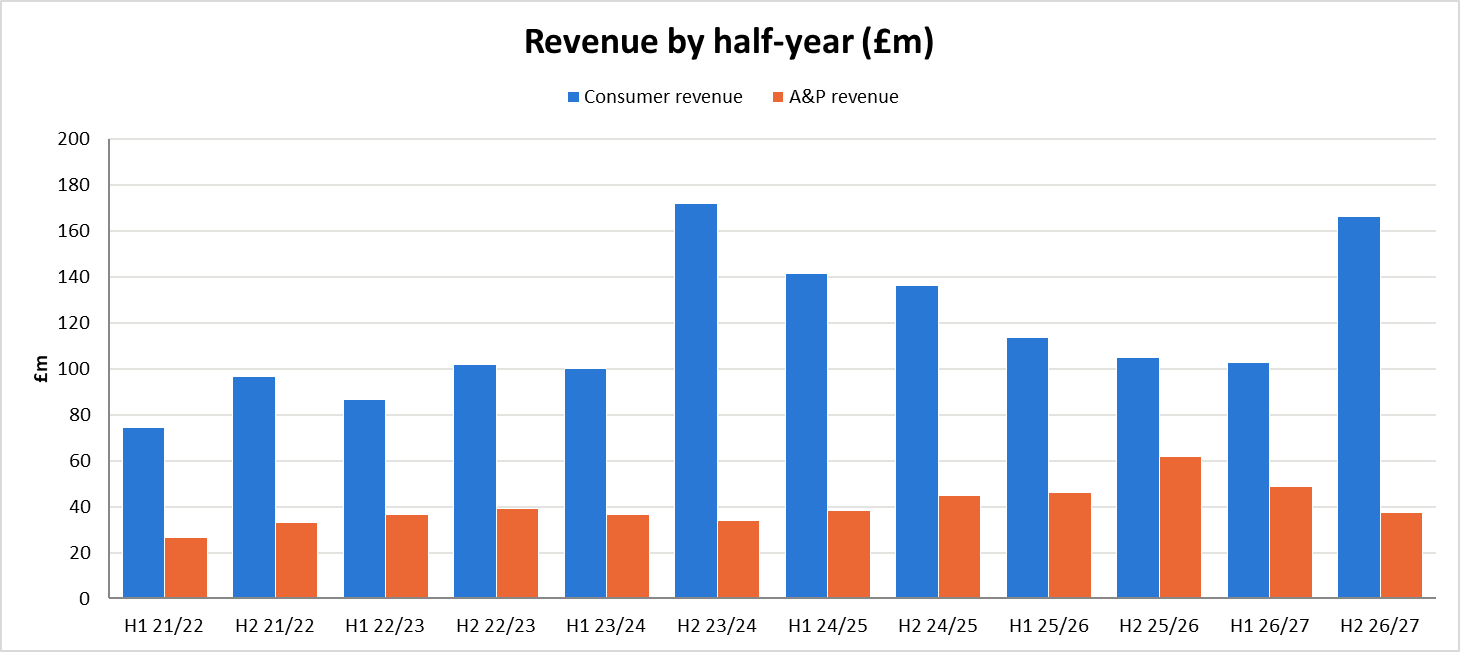
While these don't look impossible, they need to be on for a near-best-ever H2 in the consumer division to hit forecasts.
More worryingly, to hit forecast PBT in my calculations, they would need to reach near-record 15% operating profit margins in H2 for Consumer, while also increasing H2 A&P margins back to around 20%, something that may prove challenging on declining revenue forecasts.
Balance sheet:
The better news is that the company is generating strong cash flow with net cash rising to £22.8m. Although this is down from the FY number, it is largely due to dividend payments. They will also get some cash from the Anthropic settlement, although teh exact figure is unknown.
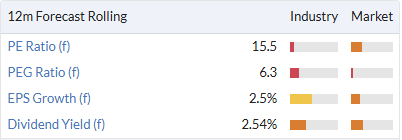
The interim dividend increased by 5% year on year to 4.28p. However, the problem with being such a highly rated stock is that the actual yield is low, and net cash is only 4% of the market cap. This doesn't really move the needle on valuation.
Mark's view
While it seems too soon to say the company will miss expectations, they have left themselves needing a pretty big H2 to hit the numbers. They need sales to deliver in their consumer division, and they'll need near-record operating margins in both BUs to hit forecasts. It would be particularly embarrassing if they upgraded forecasts earlier in the year, only to miss them, even slightly.
Increasing teh risk is that FY28 is not currently forecast to benefit from such a strong pipeline of book releases, which means that profits are currently forecast to decline. Unless, there are upgrades to come, a 16x multiple for a company with flat EPS and sales on four years previously may look a bit punchy, despite some excellent quality metrics.
Despite these risks, the company has executed very well over the last few years. It would probably be foolish to bet against that continuing. However, with the risk of a profits warning for FY27, or at least no upgrade for FY28, rising given today's results, I don't think we can remain fully positive. AMBER/GREEN
Camellia (LON:CAM)
Down 9% to 5250p - Trading Update - Mark - AMBER ↓
Bad news from the now-mainly agricultural conglomerate: they say their "...trading result for 2026 is expected to be weaker than previously anticipated." The blame is put on:
The Group has seen stronger trading performances in the Bangladesh, India and Eastern Produce Kenya tea businesses and the Brazilian arable business is performing in line with expectations. This has been more than offset by weaker results from Kakuzi, as reflected in their announcement on the 22 October, and from Malawi and South Africa. JING has continued to make good progress towards achieving positive trading profits despite the downturn in its important Gulf States markets. Weaker North Sea activity is expected to result in disappointing trading results at AJT.
Today's announcement from separately listed (but very thinly traded) Kakuzi, in which Camellia has a 50.7% interest, gives some more background to this part of the underperformance:
Further to our profit warning announcement of 25th August 2026, in which we advised that earnings for the year may be at least 25% lower than the previous year, the Board in its latest review expects net earnings to be significantly below the previous year as a result of the continued downturn in the macadamia market and a lower macadamia crop.
Helpfully, they quantify the impact:
The current forecast is for a full-year trading loss of between £3-5 million, compared with a trading profit of £1.0 million in 2025. The final trading result for the full year will be influenced by the phasing and seasonality of agricultural production and sales in the fourth quarter.
This undoes the upgrade earlier this year, which saw profitability forecast for the first time in many years:
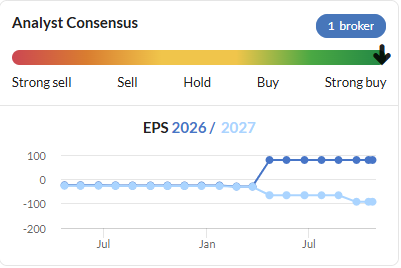
The long-term track record here is pretty woeful:
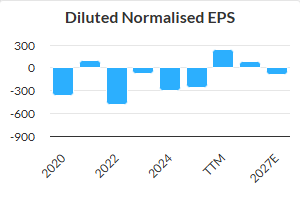
Such is the nature of agricultural production; it is highly variable and subject to many unpredictable factors, such as teh weather or commodity pricing for inputs and outputs.
Asset disposals:
The better news is that the company has done a good job rationalising its operations over the last few years under a new management team. It has a long history and built up holdings and subsidiaries in diverse areas such as engineering and insurance, which were much more valuable outside the current mish-mash of a corporate structure.
They also have property assets and "heritage assets", including manuscripts and documents of historical significance. Again, these are being sold over time and typically achieve far beyond their book value. Something they re-confirm today:
The Board currently forecasts profits of approximately £23 million from disposals of property, plant and equipment, and assets classified as held for sale, principally reflecting disposals of artwork and tea gardens undertaken during the year. The resulting EBITDA for the year is expected to be in the range of £25-28 million.
The impact of these sales can be seen on the growing cash balance, which now stands at £82m, despite £18.9m returned via tender offer in 2025.
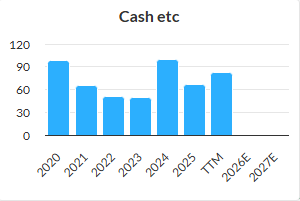
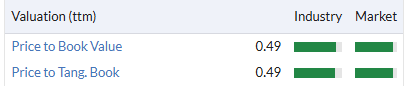
When you include liquid assets such as treasuries and money market funds, the £133m figure covers the current market cap. Overall, the company trades at less than half TBV, despite signs that some assets are worth more than book, and half the assets are in cash or cash-like funds:
The problem is what the company intends to do with these assets. So far, the strategy has been to invest the cash in additional agricultural assets. Their track record of doing this has been poor (though under a previous CEO). Typical returns on agricultural assets are poor unless one takes more risk than average. In their annual report, they say:
Invest in agricultural businesses, primarily in emerging markets where our expertise enables us to generate a return commensurate with the risks taken and where local communities benefit from our business activities.
However, so far their existing agricultural assets have been more risk than return, as today's updated guidance shows. Do shareholders really want more of the same?
Mark's view
Graham gave the company the benefit of the doubt after its August profit warning, keeping the AMBER/GREEN view and citing the significant amount of liquid assets the company has.
If the company committed to returning, say, 80% of that cash to shareholders and investing it to improve the currently held loss-making assets, I would be tempted to keep the same rating. After all, a company trading pretty close to its cash balance and at half TBV is usually a value investor's dream. However, while the stated strategy is to reinvest that cash into more agricultural assets, and the existing ones keep underperforming, I'm not sure where the long-term returns will come from, and with the second warning in a row, AMBER seems more sensible.
Record (LON:REC)
Up 7% to 46.5p - Q2 Trading Update - Mark - AMBER ↑
This seems to be a strong quarter for this currency hedging and investment specialist, with AUM up 7%:
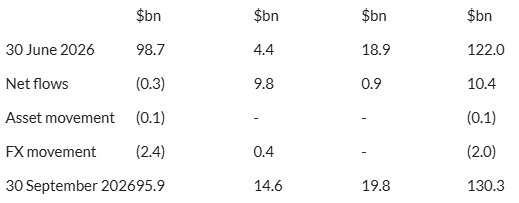
Unlike the Q1 update, which credited Passive Hedging for growth, we don't get any guidance on the relative performance of the low-margin Passive and high-margin Dynamic hedging stratgies.
We may get more insight on this in November's interims. However, I expect no major deviation from recent trends, which show passive products increasing their share of what they call their Risk Management Pillar.
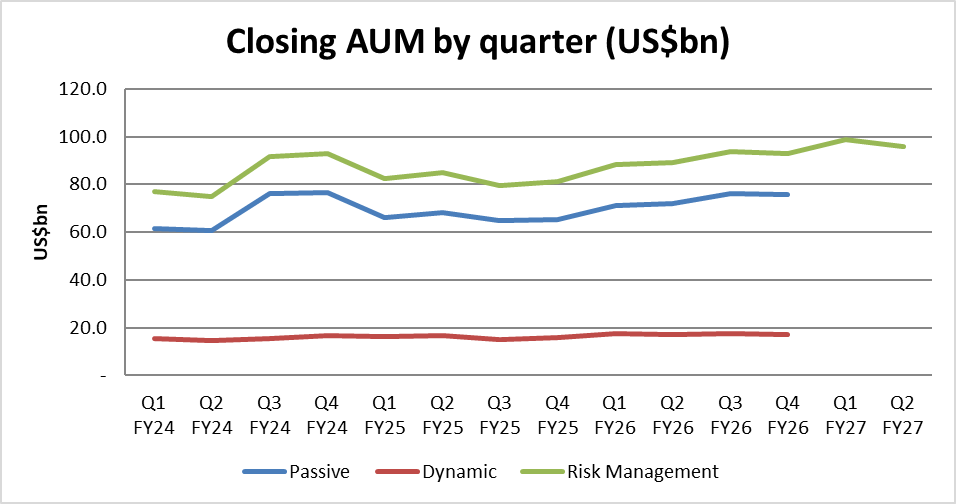
Almost all of the group’s $10.4bn inflows came from the new Absolute Return strategy, not hedging. That pillar’s AUM more than tripled in the quarter, and is starting to make a meaningful contribution to AUM.
Perhaps the most interesting development is the return of performance fees, after they didn't generate any in Q1:
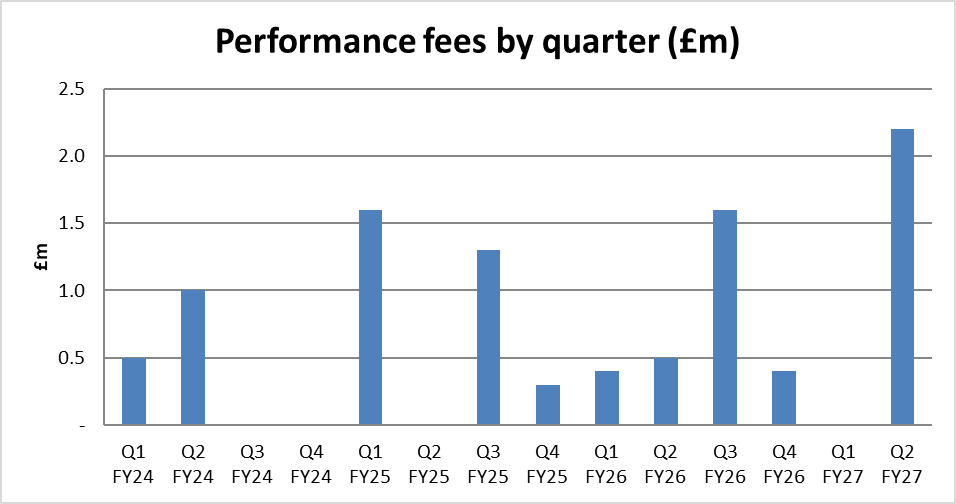
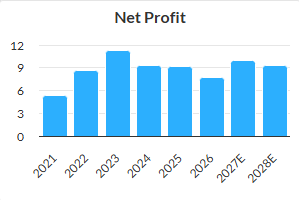
At £2.2m, this is their best quarter in recent times, and is material for a company that has struggled to grow the bottom line recently, and is forecast to deliver just short of £10m PAT for the full year:
Ultimately, they say "Performance across the Group remains in line with expectations for the full year." Future performance fees, of course, depend on performance through the rest of the year. However, it gives some confidence that the current forecasts may be achievable.
Mark's view
Graham reduced our view on this company to AMBER/RED following a second profits warning in a row earlier this year. I am still wary that they aren't completely out of the woods. However, strong flows into their new Absolute Return Strategy, combined with a recent high in performance fees this quarter, suggest things are getting easier rather than harder.
At an 11x forward multiple and with a decent yield (even if it is forecast to be a bit lower this year), I think we can afford to be a bit more generous. AMBER
Essentra (LON:ESNT)
Up 6% to 120p (£320m) - Q3 2026 Trading Update - Mark - AMBER =
These are decent revenue growth rates for Q3:
Essentra delivered strong Q3 revenue growth, supported by increased volumes and disciplined pricing. Revenue increased by 14.6% at constant currency on a working day adjusted basis, comprising like-for-like revenue growth of 10.8% and a 3.8% contribution from the acquisitions of Device Technologies and Boteco.
Acquisitions have played their part, but almost 11% LFL revenue growth remains strong in the current global macro environment. This has led to:
The Group's underlying performance continues to improve, and revenue growth for the full year is now expected to exceed previous guidance, reflecting increased volume growth and disciplined pricing actions, which are expected to recover elevated inflationary costs.
It seems cost-cutting and price increases are playing their part:
Execution of the Growth and Simplification programme, as outlined at Essentra's HY26 results in July, continues to sharpen the Group's commercial focus and is beginning to deliver results.
This may make this growth less sustainable than pure volume growth, although you sometimes get a lag effect where inflationary price increases lag costs and lead to gains once inflation subsides.
It hasn't all been plain sailing, as these pressures have led to some significant downgrades at the end of last year, and recent performance strength hasn't yet recovered from this:
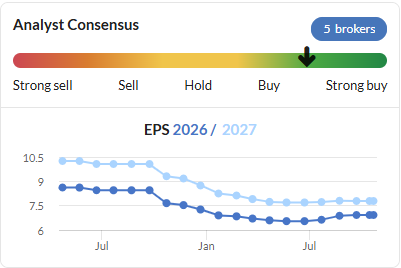
The helpfully quantify the range of forecasts:
The Company-compiled range of market expectations for FY26 adjusted operating profit, as at 21 October 2026, is £32.3m to £34.3m.
But this is a tight range, so the shift from the middle to the upper end of forecasts is just a 3% upgrade. Assuming this feeds into a similar EPS rise, the FY26 consensus will still be 15% below where it was when the downgrades began last year. The share price is 20% higher than then, making it look about 30% more expensive.
Adding to the feeling that the rating may have got ahead of itself is a quick look at the half-year results, which show some fairly chunky adjustments required to hit the numbers:
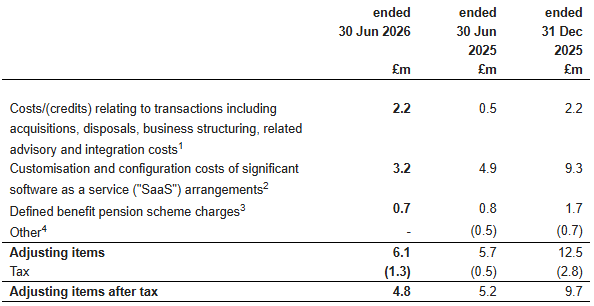
None of these I personally consider exceptional, and it is perhaps easy to be trading at the upper end of expectations if you choose to exclude some key costs that appear to be ongoing.
Then the Half Year results reveal that the company has net debt:
Net debt of £70.7m excluding IFRS16 lease liabilities (30 June 2025 £68.7m), representing leverage of 1.6x adjusted EBITDA following the completion of the acquisition of Boteco
While 1.6x leverage isn't high enough to worry about solvency, it should make us adjust down the earnings multiple we are willing to pay. A TTM EV/EBITDA of 10 doesn't scream value in the current UK markets.

Mark's view
I think there is an argument to be made that earnings here are on a recovery trajectory, driven by cost-cutting and delays in passing on inflationary cost rises to customers. However, I struggle to get behind a 16x forward earnings multiple, even if earnings are forecast to grow in future years, when earnings are heavily adjusted, and there is reasonable net debt to factor into any valuation.
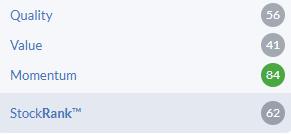
Roland called this AMBER after the H1 results in the summer, and the middling Stock Rank suggests I should stick with this view.
Dr's Section
Arbuthnot Banking (LON:ARBB)
Up 6.5% to 855p (£131m) - Third Quarter 2026 Trading Update - James - GREEN
Arbuthnot Banking features in my portfolio, and when reviewing the StockReport data recently, I wondered whether it could soon be a Super Stock. Today’s third quarter trading update and the market’s reaction brought that a little closer.
Lending was the main driver for this private bank. Customer loans and leased assets rose 12% year on year to £2.5bn, and the specialist lending businesses grew 26%. Renaissance Asset Finance's book is up 45% to £409.5m – most of the growth coming from wealthy individuals buying high-value cars -- and Arbuthnot Commercial Asset Based Lending's is up 39% since December to £305.6m.
Deposits were up 10% to £4.9bn, although they barely moved in the quarter as the bank chose not to compete for rate-sensitive money. Funds under management and administration rose 21% to £3.1bn, and the long loss-making wealth arm turned a profit in the quarter.
There aren’t many weak points here. The quarter-on-quarter data isn’t as strong as the annual comparisons suggest: deposits and total loans each rose only about 2% in Q3, gross wealth inflows slowed to around £115m from roughly £170m a quarter in the first half, and Asset Alliance’s leasing book was broadly flat.
The Board now expects full-year profit before tax to come in ahead of expectations, and it says any rate rise would be a further tailwind.
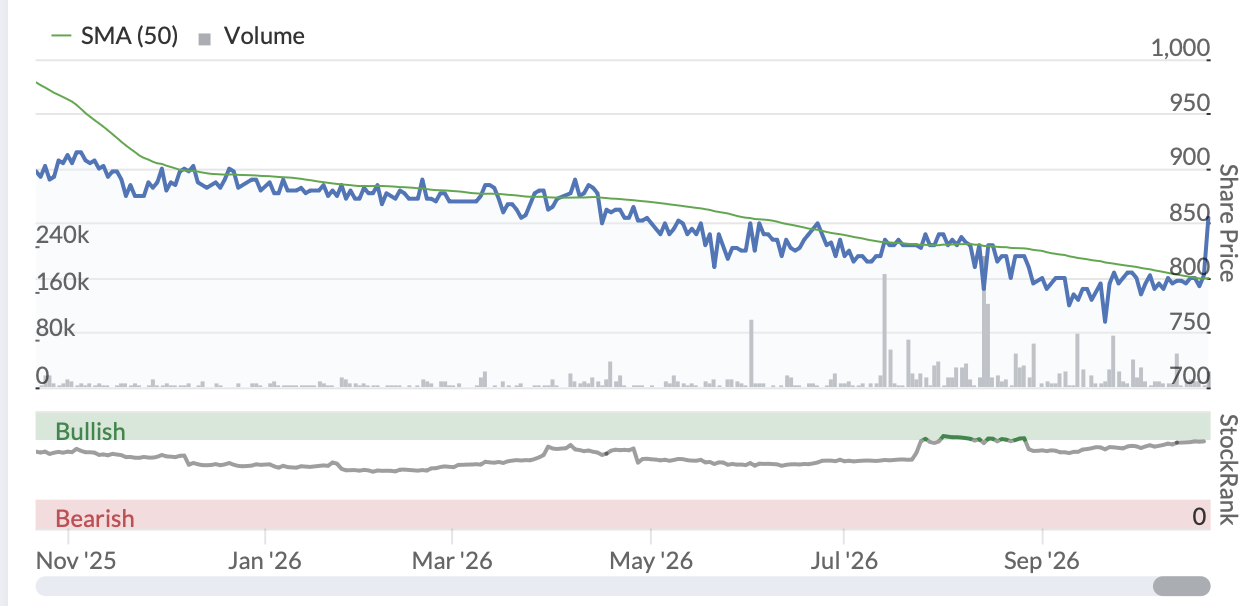
Interest rates have traditionally mattered more to Arbuthnot and this is seemingly why the stock was punished more as interest rates fell through 2024 and 2025.
It holds £4.9bn of customer deposits but has lent out only £2.5bn. Much of the difference sits with the Bank of England or in short-dated gilts and Treasury bills, with returns linked to interest rates. Arbuthnot doesn’t hedge the earnings on £523m of this “free cash” (as at June), calling the cost prohibitive. When rates fall, the return on its Bank of England cash falls straight away, while the gilts and Treasury bills delay part of the hit by three to 12 months.
Last year shows the effect. The Bank of England cut four times in 2025, ending at 3.75%. Lower rates were a big part of why profit before tax fell from £35.1m to £24.2m, and the net interest margin narrowed from 5.1% to 4.7%. The drag continued into this year: the average base rate in H1 2026 was 3.75%, against 4.48% a year earlier, and pre-tax profit was flat at £11m even though the loan book grew.
Of course, higher rates don’t help every part of the group. The company expects growth at Renaissance Asset Finance to slow in Q4 as financing costs are expected to increase.
Capital and credit
Capital ratios have come down a little. The CET1 ratio was 12.0% at June, against 13.3% at December, as the growing loan book increases capital requirements. The total capital ratio of 13.9% is still well above the regulatory minimum of 8.05% before buffers, although rule changes are expected to add about £20m to Arbuthnot's capital requirements.
Credit quality looks steady. Impaired (Stage 3) loans fell from £64m to £60m over the first half, and the impairment charge was less than 0.2% of the loan book on an annualised basis. One thing to watch is Stage 2, loans where credit risk has risen significantly, which grew from £53m to £74m.
Metrics and rates
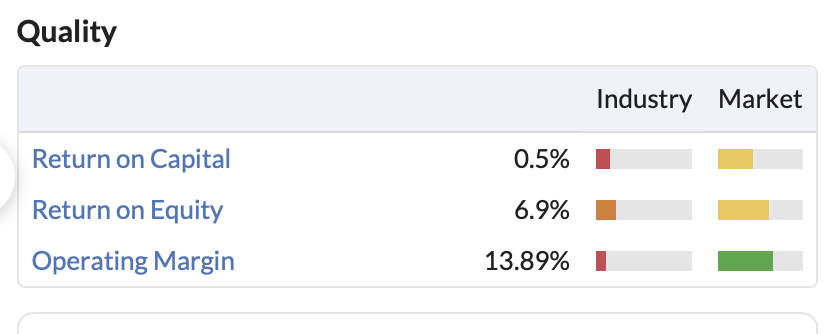
When I put an offer in on my house in late 2023, amid peak rates, Arbuthnot’s return on equity was 15.2%. Today’s StockReport shows a figure of 6.9%. The difference is largely interest rates, and that’s why I’ve been adding to my holding with the market pricing two rate hikes by the end of the year, and possibly more in 2027.
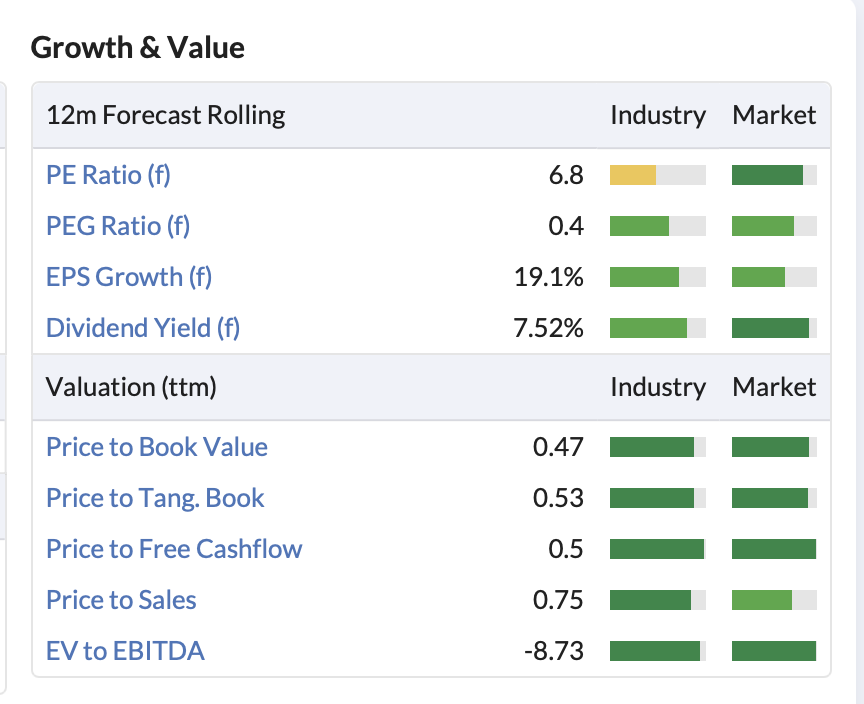
The Value Rank of 98 suggests this stock may be somewhat overlooked. Arbuthnot is valued at £131m, or 0.47 times book value (1,712p a share at June) and 0.53 times tangible book.
Consensus forecasts, from just two brokers, put the shares on 8.5 times 2026 earnings of 96.6p, falling to 6.6 times on 2027’s 123p. The forecast dividends of 57.5p and 61p give yields of 7.0% and 7.5%. Those forecasts haven’t yet been updated for today’s upgrade, so the multiples should come down further.
James’s take
It’s been a while since we last had a look at Arbuthnot, and the stock, for the most part, moved in the opposite direction to major UK high street banks. I definitely don’t see this as a risk-free opportunity, but I’m drawn by the valuation metrics, and the dividends. I’m also attracted because I feel Arbuthnot’s rate sensitivity looks like it might be a real tailwind over the next year.
There’s another very macro consideration, which I don’t know whether it’s worth factoring in (let me know in the comments). Arbuthnot is performing well despite record outflows of wealthy individuals, according to some sources. If that trend reverses, you’d expect Arbuthnot to be well positioned.
But on the valuation, rate forecast, and broad performance of the business, I’m shifting Arbuthnot to GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Arbuthnot Banking (LON:ARBB) note not much of a rise today despite being ahead of expectations, are the budgetary potential tax on banks a potential headwind ?
Volex (LON:VLX) Theres a lesson here somewhere. RNS today states that the £20m buyback programme has just been completed at an average price of 543p which is a smidgeon below todays price - which has itself dropped in a matter of days from 700p. Can’t complain at that, but where next ?
Bloomsbury Publishing (LON:BMY) I hold here and was a little disappointed in H1 numbers.. *however*.. it's worth investigating why H2 23/24 and H1 24/25 cumulatively generated c 30mm excess profit in the consumer division and that was of course the Sarah J Mass Crescent City release in Jan 2024.. of course she has two books from her more popular ACOTAR series coming in H2 this year which is probably why they're so confident.. it is no coincidence that they raised FY estimates on BD5 this year the morning after she revealed the release date of these books.. if both books combined generate the same bump in thie FY then they will still outperform current estimates.. the Harry Potter series too should provide a boost...
Hargreaves Services (LON:HSP)
https://www.stockopedia.com/a/share-prices/hargreaves-services-LON:HSP/news/01a1630e-28a2-7745-bc15-cafc8c7adcb1
Announce the award of a 15year contract for the UK Deposit Return Scheme.
Broker Cavendish ups FC EPS by 3.2% and 4.2% for 28 and 29 with a TP of 940p.
EDIT Stockopedia link not working properly!!
You have to add the link in the little box above the post-make sure you select some test to link from otherwise will create a hyperlink for whole post.
If you recall - the Scottish Greens pushed for this not so long ago - at first it was hailed as a brilliant idea until the full details came out. When shopkeepers (esp small corner shops)realised that they would have to allocate space for and expense of running the scheme they made a noise - then the public realised that the bottles were not going to be re-filled but simply crushed as they have been for years and IrnBru among others said if the scheme goes ahead - we will stop supplies to Scotland. End of story.
James ref Arbuthnot Banking (LON:ARBB) thanks for the report and was interested until I noticed the directors are heavy buyers, normally a good sign, until I realised there's only a 15% free float. Have you ever tried to sell any and do you think it may be a problem?
Then read Yiannos write up on Earnz (LON:EARN) have owned both Mears (LON:MER) and sureserve, and impressed with Bob Holt, everyone needs a speculative play, so dipped in. Thanks for highlighting.
Rws which has been rising a lot recently suddenly declines almost 10 per cent.yet it gets no mention from you today in spite of having a 92 stockrank rating. Why is this ?
Ref RWS Holdings (LON:RWS) except for saying the price has dropped, with no news, what else can be reported.
Use your brain! There are 1,534 companies traded in the UK and without news, why should there be a comment on a company's individual share price?
In 2000-2001, without realising, and alerted by by my HSBC broker, I ended up just below the 3% threshold in Mears (LON:MER). Made very good money and moved on, although I wish I held the shares.
Bob Holt was the mastermind behind the early success of Mears (LON:MER) . At the time Mears (LON:MER) was a little known Gloucestershire contractor with just 83 employees and a £12 million turnover. Holt's leadership, following the public listing in 1996, transformed the business into a major social housing repairs, maintenance, and homecare provider, eventually growing it into a £900 million turnover group!
Holt has also been involved along Peter Smith in SURESERVE plc, where their leadership was marked by record financial metrics and a major corporate exit, taken public at a market cap of £214M.
Bob Holt and Peter Smith are now both involved in Earnz (LON:EARN) with Elizabeth Lake as the CFO. Same industry, same strategy!
I hold Earnz (LON:EARN) shares around current market prices. Projected revenue for 2027 is £57m and around £70m for 2028. Should be an easy multibagger in 12-18 months.
Recent IMC meeting is interesting to watch and learn more about Earnz (LON:EARN) .
All the best
PS. Apologise for going off topic, but not an expert in emptying bins and cleaning AirBnb rooms-:)
Yiannos slightly random one but can i ask if you have had a look at Hardide recently Hardide (LON:HDD) ?- i was very impressed with trading update yesterday - its always hard to know how long sweet spots will last but they certainly seem to be delivering good numbers at present (albeit we have only had ye trading update and not the final accounts yet that will be then proof of then pudding)
also were you recently positive on Somero or did i make that up?
Somero Enterprises (LON:SOM) yes at 245p-Posted at the time here.
Hardide (LON:HDD) not getting involved in something that has already gone up 1000%, and obviously on what you are saying about actually proof and able to dig into their accounts.
All the best
Hardide (LON:HDD) not getting involved in something that has already gone up 1000%, and obviously on what you are saying about actually proof and able to dig into their accounts.
thanks for that - i think the rise to date is simply reflective of that fact prior to the year just finished it hadnt made a bean of profits for 5 years so was treated as a complete basket case by then market (probbaly rightly so at the time)
For year just finished they should be delivering £4.6 mill of bottom line profit and for year just started they should be delivering £6.6 mil of bottom line profit and they seem uber confident ref the future as they are ramping up capacity materially - factoring in that growth trend i dont think a p/e of under 15 for the current year seems expensive despite the great rise up to now - imho thats just reflective of it no longer being a complere failure. anyway as you say the year end accounts will have the detail to confirm of deny if its all uber clean ref profits not being pimped up.
Not for me, thanks
All the best
One heck of a quarterly update fromTufton Assets (LON:SHIP) this morning. NAV up 5%, confirmation of the 10% increase in the quarterly dividend, cover of 2.2x plus a positive outlook. Oh, and a chart to die for. What’s not to like?
This has come up on my quality garp screen last week I've never heard of it before but as you say brilliant chart, noticed also its priced in dollars.
Bioventix (LON:BVXP) Following on yesterday's comments - the uplift continues - up again today. Seems someone knows something ahead of next weeks results ?
AirBnB Graham, could you advise me where I can book a hotel in the Dordogne Region in a beautiful village such as Bourdeilles with a property that is on the banks of the Dronne, has beautifully appointed lounge, bedrooms and bathroom, sleeps 4, with canoe and fishing, and two terraces for relaxing in the sunshine for the high season rate of €150 per night? Oh, and by the way, will the cleaner also make sure that it is spotless for the next guests regardless of the state it is left in? I don’t think it was in any way an unreasonable request to tidy up and leave a property in a reasonable state upon departure. Pricing has to be adjusted accordingly for the standard of service and if guests don’t want to do it there will be plenty of takers prepared to pay.
Relx (LON:REL) I hold
In case anyone is interested in talking about stocks, it would be good to have some coverage of todays 3rd quarter trading update which concludes
"Full year outlook
Fears that AI would eat their lunch, the shares have struggled to make headway this year and are down about 14%. I thought these fears were overblown and bought more. What do the community and the team think?
Relx (LON:REL) I hold. The results look excellent. The open questions for me are
(1) how exactly does Relx protect their database against scraping?
(2) Will Open Access erode future earnings at Elsevier?
The summary of the IP (LON:IPO) RNS is incorrect.
I apologise for going off topic and talking about stocks :-))
Somero Enterprises (LON:SOM) I hold these and although I was not surprised by the steady rise, 15%, after interims released on 8/9/26, the 15% rise in the last week has surprised me, I am wondering if there is a trade buyer building a position here or whether this mirrors Mobico (LON:MCG) 20% move up in a few days before an obviously leaked bid is anounced. Does anyone have any views?
TIA
Off topic indeed!!!!
All the best
Somero Enterprises (LON:SOM)
I am wondering if there is a trade buyer building a position here
perhaps thats the Yiannos effect?.
I would agree somero is trading on a lofty pe compared to where it normally trades - their buisness has always been cyclicial though - like builders in the old days often they are best value when they look most expensive - so if they can have a purple patch over the next 12-24 months without any signs of that running dry , well the bar is still set reasonably low right now compared to their prior historical earnings. So i think the market just expects its more likley then next update wil be good rather than bad or nuetral. i think most stale sellers that wanted an exit probbaly have left the building.
Somero Enterprises (LON:SOM) Is it just the need for absolutely level floors in data centres ? Maybe.
perhaps thats the Yiannos effect?. What have I missed?
Somero Enterprises (LON:SOM) Is it just the need for absolutely level floors in data centres ? Maybe.
agreed the need for data centres has to be positive - and i kindfa thgink that there is probbaly still the need for large warehouse space anyway - i think that may have dipped from prior spikes though. so thats te slight worry if everyone wants to do stuff at the same time does that generate a mini boom that wil susbside - its clear data centres are all the rage and it sems likely that investment might not carry on at such high levels - medium term though ai aint going away and then need for data centres will still be on the up - its just whether there is a mini bubbble.
This share has served me ok as i bought in years ago at about 200p and i have had some very decent divis - i did actually sell out at like 470p temporarily but they had an ahead of trading update i think the day after i sold the shares and before i has spent the money i could but back in at 450p with improved outlook - with the benefit of hindsight i shouldnt have bought back in despite the otlook being fine and dandy then. Its always easy with hindsight though as to what the correct decision should have been.
Interesting re Airbnb - they have already moved their internal costs which were paid by customers into external pricing - so it is now deducted from room price - which I think puts a little downward pressure on price to drive bookings. This is a similar move and to me - suggests occupancy is disappointing and already weak..... which suggests weakness in the economy is raising its head. I run an Airbnb and occupancy is behind last year which can be for a variety of reasons but has never caught up the post covid boom .... which was artificially high IMO..... Airbnb as a business want to push weakness on to hosts which may or may not be successful depending on how much slack there is in the system. Never-the-less its a sign of weakness out there not being captured in unemployment nor inflation data yet.
VRBO who we use as an owner has just increased the commission by 4.5% (a 30% increase approx I believe) on the grounds of making all thier (Experian) platforms consistent, do I really believe this NOPE. They already charge a huge amount the owners do all the work but we have no choice but to use them
Just adding a note here to emphasise that I'm leaving the company analysis today in the capable hands of Mark Simpson and James Fox. Cheers!
The other big news overnight is regarding the cyber security threat identified by a firm using AI.
Without meaning to sound too mercenary, I was wondering if anyone thinks any UK listed cyber security firm looks particularly attractive right now? I can of course just ask AI, but thought I'd fish in the community's expertise!
I own Shearwater (LON:SWG) which even after the strong recent rise still looks attractively priced and is due to report next Tuesday.
Shearwater (LON:SWG)
Should be trading at much higher prices.
I do not hold.
All the best
Shearwater (LON:SWG)
they should 100% be in the sweetest of sweet spots right now (they have probably been a sweet spot though for the last couple of years plus) - pretty sad that depsite over a decade of doing what they do and beating expectations that only resulted in £500k uptick in cash last year. They are making the right noises here though but with them i would only want to look at what they actually deliver as they are great as promises - valuation now somewhat reflects their piss poor history of losing millions of shareholders money whilst drawing £1 mill plus salary for directors. contract updates give fans hope though and i would say valuation is low so upside potential is good here if they get it right.
There's the behemoth cyber security consultants NCC (LON:NCC) .... but I don't think they look attractive in terms of share price.
The cyber security play on AI is already well known, don't think you'll find any hidden gem shares with a good cyber security offering that hasn't already seen their SP go up.
I have latched on to CNS – Corero Network Security recently. Director buying and decent institutional holdings make me think their focus is right on point; Its technology protects against external and internal DDoS threats in complex edge and subscriber environments and ensures Internet service availability.
Graham, can you please have a look at Essentra (LON:ESNT) as I believe the turnaround is in full swing here and significant upside to be realized. I hold.
Graham - for someone who has a family holiday home which we run also as an Airbnb to cover costs, I’d suggest you might be missing the target here. As I’m sure you will appreciate, running a single property as an Airbnb does not have the economies of scale of a hotel and the clean / turnaround costs can be a significant expense, when you take into account laundry, rubbish removal and the cost of having a reliable turnaround company to manage everything. We always ask guests to load the dishwasher and leave rubbish in a spot so it’s easy for our cleaners to do their job. I’m really not sure why that’s too much of an ask. If guests start leaving dirty dishes and plates all over the place it becomes a nightmare for the cleaner and ultimately mean we have to pay the cleaners extra time, the cost of which will ultimately end up being passed onto the guest.
Don’t forget these are people’s homes Graham, and all we ask as a host is that people treat it with respect and leaves things relatively tidy when they leave.
I appreciate your daily macro comments, but I’m not sure this sort of commentary is particularly relevant or helpful
why should guest pay your cleaners fee?
They don’t in our case as we just charge an all inclusive price, but ultimately the turnaround costs form part of the fee. Some hosts decide to charge a lower nightly rate and then and additional fee to cover the clean.
You do realise that your hotel cost includes paying towards the cleaners? The amount is just hidden within the amount you are charged.
You do realise that wherever you stay, hotel or Airbnb, you are paying for the cost to clean right? Unfortunately we haven’t managed to locate the cleaning fairy yet!
Harves Most air bb are not people's homes but investments. But I agree its not the right forum.
The advantage of having a separate cleaning fee is it can be used as a pricing barrier to reflect the cost of the preparation and admin a change necessitates. Without it single units could be unprofitable for one and two night stays, making hosts busy fools.
Airbnb (NSQ:ABNB)
I'm not really a fan of talking about anything other than stocks on this platform, but as Airbnb is a grey area I'll briefly mention 2 things:
Hotels are also most likely using a service like Elis SA (EPA:ELIS) who are able to take advantage of the huge volumes being cleaned every day.
Unless I've misunderstood I believe you were talking about Airbnb's fees now being wholly included within the Hosts room price instead of being split between Host and Guests.
I don't think this matters to Airbnb - they're getting their 15% either way.
But I do believe from a business perspective that this is a good thing - prices will be much more transparent, especially for hosts who are, as previously mentioned, competing with hotels and primarily only see the fee that they are charging, not what the end guest is actually paying.
Couldn't agree more but unfortunately these days respect is in short reply.
Well said and I totally agree, the thought of guests scarpering from my Gite in France leaving dirty dishes, pots and pans, bins full of rubbish, toilet bins full of soiled tissue etc horrifies me. It is entirely reasonable to request these tasks are done and the property left in good order, its our home. Also remember it takes me around 5hrs already to totally clean a 3 bed house after 1 week, make the beds etc and make sure its as good as it can be.
Gite owner
The rule of thumb should always be 'leave it as you find it'. This means that if the cleaners have done their job they won't have much to do next time.
If you rent it out, everyone, in general, will regard it as a business. No one cares what you think - they compare it to other businesses and see what they can get. It's not personal, it really is just business.
Swings and roundabouts I guess. I'd always leave any holiday accommodation as I found it taking out the rubbish and putting the dishwasher on and emptying it before I left. Two weeks ago I paid £170 per night to stay in an Airbnb in Norfolk which wasn't that clean, everywhere needing painting, stains on all the settee's, absolutely filthy windows which rather made me not wish to check the condition of the mattress! And a professional cleaning company were waiting outside when we left. They complimented us on how tidy we'd left the property!
Surprises me people even complain in the first place about having to tidy up before check out. We regularly use AirBNB and wouldn't occur to us not to clean up before leaving the property.
IG group (LON:IGG) have released an update today ahead of their ‘Strategic Review’ meeting at UBS in London this afternoon. Hopefully they can reassure the market after their recent steep share price decline. I unfortunately hold
The more granular detail on revenue was not (for me) encouraging. Both Freetrade and TastyTrade disappointed me.
A bigger question for me however is how/why are the sellers of underdog going to accept several hundreds of millions less for their company now that the 24.1m IGG shares are worth a whole lot less. Or are IGG, god forbid, going to increase the number of shares to be issued and paid over?
IG group (LON:IGG)
Or are IGG, god forbid, going to increase the number of shares to be issued and paid over?
i dont know for certain but others have stated that its a fixed number of shares end of - if those assertions are true then its plain fact that "thats the deal they took"
rememer there was cash upfront and their is potentially some very generous backend extras here.
If anyone has any clarification if they can adcvise cheers.
IG group (LON:IGG)
Hi Richard
The company has confirmed that the 24.1m IGG shares is fixed - there's a presentation deck from a few weeks ago that I believe also mentions this in case you want to check it out.
The cash outlay, if the transaction went through today, is just over £300m, which for context is less than 1 year of profit for the company.
The Supreme Court is expected to rule on the dynamics of the prediction market industry in the middle of 2027, so there's also window to recoup a material amount of this original outlay before any decision is made.
The share dilution isn't great, but if Underdog does turn out to be successful then it could look like a bargain in hindsight.
I wasn't against either the TastyTrade or Freetrade acquisitions and I believe the former has turned out quite well, albeit helped by rising interest rates. So I'll give the company the benefit of the doubt for now and hope that over the long term this will continue to be a good share to hold.
IG group (LON:IGG)
thanks abtan - do you have any thoughts ref the latest update - q3 seemed particualrly poor and it did not seem well communciated as to the reasons why specifically , if thats just temporary bad luck ref hedging volumes etc thats fine - or may be some sign that core profits arent likely to hold up too well - imho core profits are still key and then communciation didnt seem great ref last update - i havent looked at the presentation yet though if thats up and out in the open.
IG group (LON:IGG)
I don't really have anything useful to add on the Q3 update that wasn't already said on the day in the DSMR I'm afraid.
There have been many material falls in the IGG share price over the space of 1 year (see screenshot below, from 2022-2023 which took me about 5 seconds to find), but over the long term i.e. more than 5 years, it's been a wonderful hold with an IRR (for me) of >15%.
So for now I'll keep holding and only look to sell if I see anything worrying in the core numbers as they are released.
IG group (LON:IGG)
its very messy here - if its a fact that the latest trading update fell only due to unlucky hedging stuff (lack of) that could go either way well i would not actually take that as a huge negative. It was obviously a huge negative for that period - but its probbaly as likely to go the other way - so that short term unluckiness should unwind. its messy ass IGG have kinda avoided these sharp swings - take a look at older stuff from plus markets i think and that will confirm the luck can be good or bad.
the messy bit is that the wording used in the update made no sense to me - so i had to rely on Grahams most excellent summary of what they were trying to say.
unhelpfully on stocky i dont have next years numebrs up yet - so i cant see if next years earnings took a chop after the recent update - that would be key question here to see if they are on track - thats if they even have forecasts ?
as you say hopefolly its mostly business as usual - not sure if this event will simply reguritate info already in the public domain.
If one does want to worry there are two worries
(1) are customers leaving - i have heard a few comments that the platform updates are not going down well - its not great if you cant keep punters happy ref platform - times do change though and the good old days dont always last particualrly if IGG arent making a margin off you (you just have to look at what bookies do to customers who dont lose sufficient margin)
(2) has there been some sort of fundamental shift ref their ability to churn out core profits - not sure what this would be but if you are making great easy margins of punters could someone out compete on costs - or from regulatory perspective can they be blocked from making easy money of their customers. its always game of cat and mouse when you have spreads and are holding onto soemones elses assets that you can pimp out for your benefit.
IG group (LON:IGG) has been a very dependable core business over the years - i sole previously when they had short term weakness and guided on lower expected profits - those lower profits never came as they did fine and dandy despite guiding lower. this kinda evidences that with not brilliant transparency if they are simply being conservative and dont know well that may may them look shit when they arent reallky shit.
Must admit i was very unimpressed with the communication in thne latest trading update - being frank it was gibbersh nonsense that 95% of people cannot make sense of - poor form. stuff like that makes me worry if the current people in charge have lost common sense and gone on some sort of global domination game - that doesnt always end well perhaps one could go as far as saying rarely when uk trys to make it big in USA.
Note i only bought in recently after large drop before recent trading update drop - so ref latest acquisition that was already kinda w/off due to price drop after that acquisition news. the previous us acquisition did ok so i am slightly surprised that holders didnt pay heed and exit stage at then peak the groundwork for the second acquisition was already set.
Certainly plenty of mixed messages here and some red flags - i havent sold out though
Like you I bought (back in) after the drop on the acquisition news. The trading update was a bit of a downer but, like you, I won´t be surprised if retained revenue picks up again rapidly, although no comment on that in todays release.
Good morning rmillaree, found your post interesting and agreed with most of it, but had to laugh at "hopefolly" a bit of bad spelling which joined two words into one perfectly describing a shareholding mistake that I, and I'm sure many others, often make.
Good morning Graham, if time permits, please could you look at Bloomsbury Publishing (LON:BMY) interims today?
Yes - will be interesting to see how the Mkt reacts - actuals are down but theres plenty of jam tomorrow - lots of it!
I find this statement somewhat confusing:
"Confidence in delivering record results in line with Adjusted Profit expectations."
Get excited but don't get too excited.
Seems the market does not like the figures share currently off nearly 9% ( I hold as well for ' jam tomorrow' )