James Cropper: H1 earnings climb 80%, but H2 looks weaker and the paper business remains a potential drag

Analyst’s view:
I'm going to maintain our AMBER/GREEN view today out of respect for October's large upgrade and the stock's high MomentumRank. But my concerns over slow revenue growth and weak underlying profitability in the paper business mean I'm getting close to the point where I'd move back to a neutral view.
Down 1% to 832p (£80m) - Interim Results
The market had already been briefed on the good news from advanced materials, paper and packaging group James Cropper ahead of today's results: Ed Sheldon covered the company's recent upgrade to profit guidance three weeks ago.
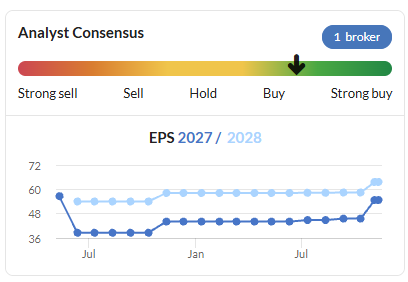
This upgrade has since filtered through to the StockReport, with a very respectable 20% upgrade to FY27 EPS forecasts:
Today's half-year results give us an opportunity to take a closer look at what's happening in the business and at its financial performance. James Cropper's share price has risen by 150% over the last year, so I'm interested to see if the valuation still stacks up.
Half-Year results: key points
Today's accounts cover the six months ended 26 September 2026. The headline numbers are all moving in the right direction, with profits up and debt levels down:
Revenue +18% to £61.2m
Adj pre-tax profit +176% to £5.8m
Reported pre-tax profit +85% to £5.0m
Diluted EPS +80% to 38.8p
Interim dividend reinstated at 5.0p
Net debt of £2.7m (FY26: £8.1m)
Debt leverage reduced to 0.2x EBITDA
Divisional results: James Cropper operates with two divisions, Advanced Materials and Paper & Packaging. Both were profitable during the first half, in a welcome reversal of the situation last year, but today's guidance suggests we shouldn't necessarily expect a repeat of this in H2:
Paper & Packaging: revenue up 29% to £42.2m, adj EBITDA of +£3.9m (H1 26: £(0.7)m)
Advanced Materials: revenue flat at £19.0m, adj EBITDA -7.3% to £5.1m
Paper & Packaging: The longstanding issue we've had with this group is whether Cropper's legacy Paper & Packaging division can return to profitability and earn its keep. The paper business reported an EBITDA loss of £0.5m last year, despite generating £63m in sales.
The good news is that Paper & Packaging returned to profitability in H1, at least an EBITDA level. However, today's commentary indicates that H1 benefited from some one-off factors and that H2 is likely to be weaker:
"Revenue growth was positively impacted by seasonal factors and also a one-off inventory build by a major customer extending their distribution channels."
Trading in Paper & Packaging "is expected to return to more normal seasonally adjusted levels" over the remainder of FY27.
FY27 guidance is for high-single-digit full-year revenue growth and a mid-single-digit adjusted EBITDA margin.
Using this guidance, my sums suggest that Paper & Packaging could deliver FY27 revenue of c.£68m and adj EBITDA of c.£3.4m (8.5% revenue growth and a 5% EBITDA margin).
If I'm right, this implies H2 revenue could be c.£26m, potentially with a small adj EBITDA loss.
Cropper hasn't broken out operating profit for each of its divisions today. But this guidance suggests to me that an an operating level, the profitability of the Paper & Packaging business is probably still quite weak.
If I factor in the division's (unknown) share of group central costs, I would speculate that the Paper & Packaging business may still only be marginally profitable, at best.
Advanced Materials: this division develops "nonwoven materials and electrochemical coatings" for sectors including aerospace and defence. It's a nice business with decent margins and seemingly strong growth prospects.
Despite this, progress slowed during the first half of the year, with profits down after a strong performance in Hydrogen last during the same period last year:
Established markets, such as aerospace, defence, construction and medical, which accounted for around 80% of Advanced Materials business unit revenue in the period, delivered low single-digit percentage growth overall. In nascent markets, the Group experienced an anticipated decline in revenues in Hydrogen Coatings against a strong comparative performance in H1 FY26.
Management guidance is for H2 revenue and adj EBITDA to be "similar to H1". I'd model this as c.£38m of revenue and c.£10m of adj EBITDA.
Outlook
Full-year guidance is unchanged from October today, with management guidance for adj EBITDA of £10.3m to £11.3m.
Reverse engineering this into my estimates above allows me to sanity-check my guesswork:
Paper & Packaging adj EBITDA: c.£3.4m
Advanced Materials adj EBITDA: c.£10m
Estimate of group central costs (based on FY26): c.£2m
Netting these off gives me a FY27 adjusted EBITDA estimate of £11.4m, so it looks like my estimates are in the right ballpark, albeit towards the upper end of guidance.
Checking the Singer Capital note from October shows that Cropper's broker is estimating £3.1m of adj EBITDA for the paper business this year. So it looks like that's where the main weakness might be.
Roland's view
I am not yet convinced that the Paper & Packaging business will be consistently profitable at an operating level, especially when group costs are factored in.
While it could make economic sense for the group to sell the paper business, Cropper's family ownership and long heritage in this sector suggests to me that there's a strong attachment to paper that won't easily be broken.
In the meantime, it looks like Advanced Materials may have to continue supporting the profitability of the wider group.
Valuation: Cropper has proved an excellent turnaround buy over the last year and I'm happy that we picked up this opportunity in January and then in April.
However, when looking ahead I don't think the valuation is as compelling as it was even a few months ago. Revenue is forecasts to rise by just 4% this year and by less than 2% in FY28, according to Singer.
While earnings growth is expected to be stronger than this, the lack of top line growth suggests to me that higher profits will come from cost savings and perhaps some small level of operating leverage.
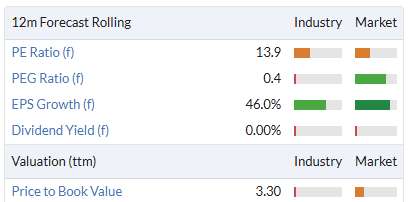
With James Cropper now trading on a mid-teens P/E with High Flyer styling, I'm not sure how much near-term upside is left.
I'm going to maintain our AMBER/GREEN view today out of respect for October's large upgrade and the stock's high MomentumRank. But I'm getting close to the point where I think it could make sense to retreat to a neutral view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on James Cropper (4)
Comments here are also visible in the Daily Stock Market Report
James Cropper (LON:CRPR)
Good to see that there are investors around, giving their valuable insights after actually spending time researching and digging into the numbers.
All the best
James Cropper (LON:CRPR) And not great reviews at the plant level on Glassdoors, although to be fair not many recent reviews have been left
James Cropper (LON:CRPR)
I have had a quick look here - to me its not really about the numbers delivered so much - its all about the outlook statement.
As they have gone to the trouble of updating expectations we know te numbers we have are going to be decent.
So what i am looking for is whether that good momentum can be carried on for the rest of the year (further upgrades?) and into next year.
ref outlook for the current year thatsa solid B its pretty much as to be expected that they are still on track with what they said 3 weeks ago - no further upgrades and i would expect anything - exactly as you would expect really.
Outlook
Trading since the period end has remained strong and in line with the Board’s expectations. The Board expects full-year Group revenue to show mid-single-digit growth over FY26.
As announced on 20 October 2026, the Board now expects full-year Group Adjusted EBITDA to be in the range £10.3-£11.3m, being 10-20% higher than previous market guidance and approximately 15-25% above FY26.
Do we get any clues into next year here - yes we most certainly do and they are the company slapping us in the face telling us they have had what i would describe as "really purple patch fisrt half" and that some normalisation is happening - ie there its some element of one off good news in the good news we have just had.
we have
Following a strong six months, trading in Paper & Packaging during the remainder of FY27 is expected to return to more normal seasonally adjusted levels to deliver high-single-digit full-year revenue growth and a mid-single-digit Adjusted EBITDA margin.
Advanced Materials revenue and Adjusted EBITDA in H2 FY27 are expected to be similar to H1 FY27.
Following a strong six months, trading in Paper & Packaging during the remainder of FY27 is expected to return to more normal seasonally adjusted levels to deliver high-single-digit full-year revenue growth and a mid-single-digit Adjusted EBITDA margin.
there is also warning about energy costs -thats to be expected though.
Advanced Materials revenue and Adjusted EBITDA in H2 FY27 are expected to be similar to H1 FY27.
The Group actively monitors the impact of input costs, most notably the volatility of energy costs which will continue to be managed through customer surcharge arrangements.
My outake
whilst its all fine and dandy it seems like they have admitted that come h1 next year those figures will be up against hard comparatives - perhaps less so h2 next year.
Bearing in mind the current expectations are for next years profits to jump 40% over this years profits - thats a big ask normally. But if they need to do that with headwinds going into h1 and higher energy prices its an even bigger ask.
Note in % terms 40% seems like large number but the reality is they only need to eak out £1.5 millioin extra profit on £110 million of sales - so if they can improve bottom line numbers by 2% of sales well that s job more than done.
I dont really have a handle on the business to know whether the current numbers are as sustainably good or not.
If we say tehy wil hit £5.1 mill net profit 2028 - and can show sustainable growth in profits going forward current price looks absolutely fine and dandy. Especially if company can eak more on margins - they are well placed.
Whats happens if they are simply in apurple patch though - as they have kinda admitted in one of their sectors - say we only get minor growth and say we end up with £4 mill profits 2028 - and no evidence they are pushing for more ? pe of 20 woukld seem damn expensive.
Looking at the history of deliverance well they have hit over £4 mill net profit 3 times since 2017 - thats never stuck though previously and thats mostly been folled back to more dross.
Thats perhaps a symptom of the industry they are in - sometimes you will get sweet spot ref contracts pricing etc. the problem is do you have the power - if you dont have teh power the customer then expects a cut of that windfall or they would go elsewhere.
It may be different this time (i am constantly amazed that listed companies dont concentrate more on good solid margin stufff) but i would be wary that their sweet spot may not last and that may be them doing nothing wrong - it seems based on history that it aint easy to make good consistent margins multiple years in a row.
How confident are company ref next year forecasts - i have been very unimpressed how many cxompanies seem to put "anything up" for next year - and well if it aint great well they dont really tell you the full bad news until you are 1-3 months into the year. Perhaps a broker note can explicitly state that they can make up ground in other poarts of the business next year so that they are still firmly on track despite moderating comparatives in packaging - thats the comfort blanket i would want as holder. Without comfort bl;anket i might be tempted to bak profit here despite that going coimpletely against the grain that one should never fight positive newsflow. I would say in tehn absence of specific bad news my views here could be wide of the mark - they might be uber confident ref next year still.
Excellent results from James Cropper (LON:CRPR) and Fuller Smith & Turner (LON:FSTA)
I hold both and was fortunate to buy when nobody was interested. More to come from both I would suggest. Paul Barber who leads the paper division at the former has together with his team done an excellent job in turning the business around. As for advanced materials there is a significant runway for growth. Substantial increase in EPS, debt down and dividend reinstated. An awful lot to like.
Fuller Smith & Turner (LON:FSTA) Together with Young & Co's Brewery (LON:YNGA) are in my view by some distance the best among their peer group. Both have good management and a predominantly freehold estate. Debt is a little on the high side at Fuller Smith & Turner (LON:FSTA) but this is offset by the freehold value of the estate. Simon Emeny and his team are in my opinion good allocators of capital and the results show the benefit, an example being the scheduled refurbishment of the The Barrow Boy and Banker on London Bridge, an iconic site.
Young & Co's Brewery (LON:YNGA) that I also hold reports interims tomorrow that will hopefully be equally positive.
Views frm Graham and the team on James Cropper (LON:CRPR) and/or Fuller Smith & Turner (LON:FSTA) would be welcome.