SIF Folio: Lookers update + a closer look at Capital Drilling

The ink was barely dry on last week’s article when another SIF folio stock was hit by a massive sell off. The culprit this time was FTSE-listed car dealership group Lookers, which shocked the market with news of an FCA investigation.
I’m going to cover this news and then take a look at mining services group Capital Drilling. Is this a suitable stock to replace last week’s departure, Sylvania Platinum?
Dealer profits could suffer
LOOK shares fell by about 25% last Tuesday, as Paul reported here. The subject of the investigation is the firm’s regulated activities between 1 January 2016 and 13 June 2019.
I think the main risk this flags up is that dealers’ profits may have become too dependent on big commissions from finance and insurance products. One estimate I’ve seen suggests that around a third of the profit on each car may have come from financial products.
In its 2018 annual report, Lookers flagged up a contingent liability in this area, warning that it had identified “certain matters requiring review” in its regulated activities. However, at the time, the company said it wasn’t yet practicable to estimate the potential size of any financial liabilities that might arise.
I don’t have any insight into this situation. My rules allow me discretion to sell in situations like this. But when I’ve done so in the past, I would often have done better to sit tight. Stocks hit by regulatory news sometimes recover strongly when more information becomes available.
Lookers only joined the SIF fund in March, but the fund’s position is now down by 50%. It’s not a great start, but the stock is still scheduled to spend at least six more months in the portfolio. Until we have more concrete information -- or a formal profit warning -- I’m inclined to sit tight and await further developments. I won’t be selling Lookers for now.
Mining opportunities?
I have had some good investment results with mining stocks over the years and maintain an ongoing interest in this sector. However, I do have some ground rules.
Mining companies must have a profitable business model, a proven track record and a sound balance sheet. As a general rule, I also prefer dividend-paying companies. I believe this provides useful evidence of cash generation and boardroom focus on shareholder returns.
What I’ve found recently is that mining stocks are almost the only companies qualifying for my Stock in Focus Screen:
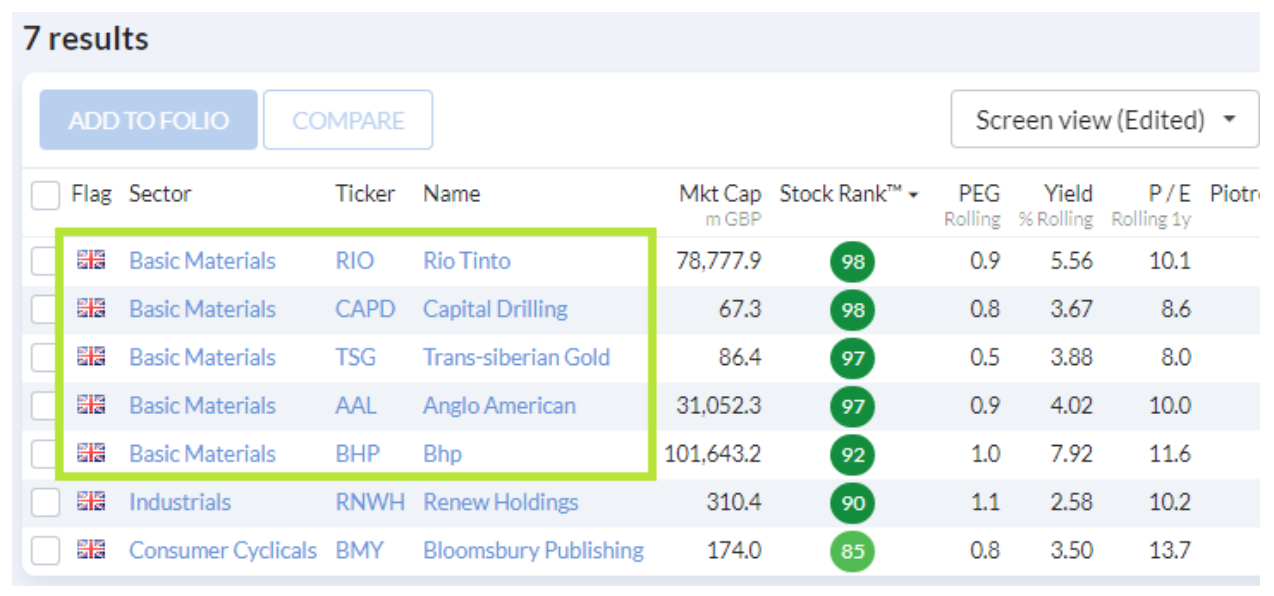
The top-ranked stocks are FTSE 100 firm Rio Tinto and AIM small cap Capital Drilling. As its name suggests, Capital is a drilling contractor, rather than a miner.
I’m a big fan of Rio Tinto and have held the stock profitably in SIF before. I also rate the business as a long-term income investment. However, the shares are currently at a post-2008 high and are trading at 2.5 times tangible net asset value. I’m not completely comfortable with this valuation.
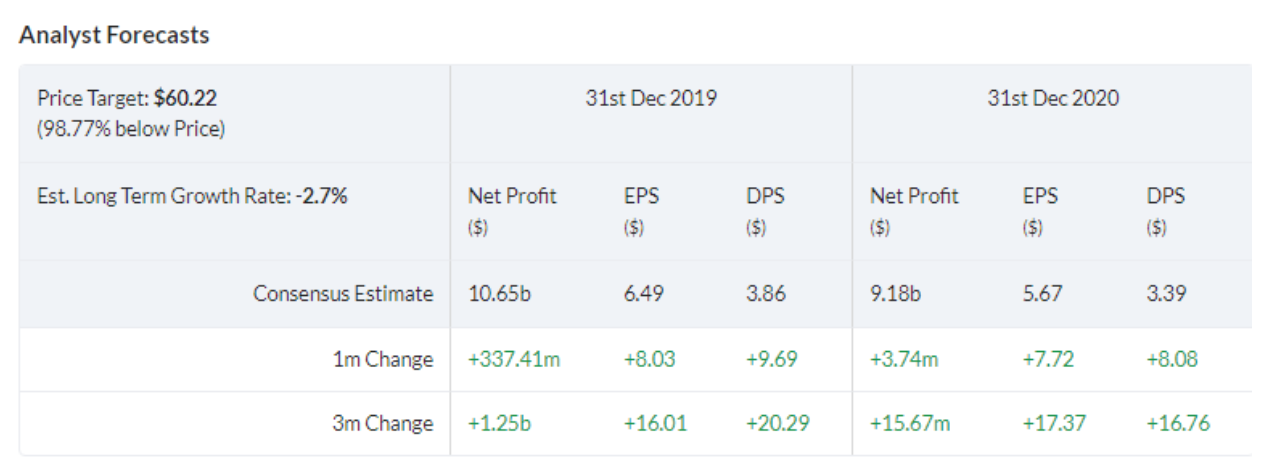
Although Rio is in a sweet spot in terms of profitability and free cash flow, it’s also benefiting from production disruption elsewhere in the sector and iron ore prices that are at five-year highs. I don’t see much opportunity for structural growth. Consensus forecasts suggest profits will be lower next year, too:
Late-cycle opportunity?
For these reasons, I’ve opted to consider Capital Drilling (LON:CAPD) for the SIF fund this week. As a service provider, I think it’s well positioned to benefit later in the cycle, as miners start to relax their purse strings and consider new capex projects.
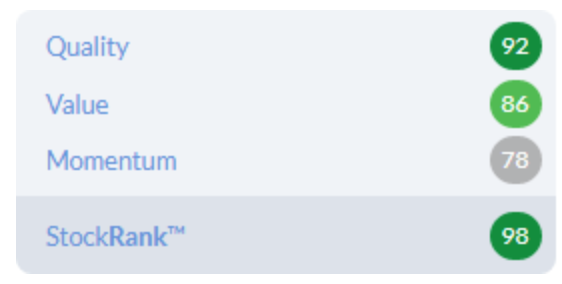
I’m also tempted by CAPD’s modest valuation and strong balance sheet. Stockopedia rates this £67m firm quite highly, too:
Capital Drilling is an Africa-focused drilling contractor that’s particularly active in the gold market. The majority of its current operations are in Tanzania, Egypt, Mauritania, Botswana and Kenya.
If you follow African gold miners, you may spot a risk here. The Tanzanian government is going through a period of resource nationalism and demanding a bigger levy on gold miners’ profits. One of the main casualties of this process has been Acacia Mining, which Capital Drilling lists as a major client.
Capital’s current contract with Acacia runs until the end of the year. I’d normally expect it to be renewed. However, Acacia’s majority shareholder, Barrick Gold, is trying to buy Acacia as part of a settlement with the Tanzanian authorities.
If this deal goes through, would Barrick renew Capital’s contract? The company lists Barrick as a former client, but doesn’t list Randgold Resources. That could be significant, as Barrick is now run by Randgold founder Mark Bristow, following a merger between the two firms last year.
This kind of risk is rife in the mining sector and isn’t necessarily a deal breaker. But I think it’s worth bearing in mind.
Founder share sale: A second risk I feel obligated to point out is that one of Capital Drilling’s founders, Craig Burton, stood down from the board (he was a non exec) in 2018. In April 2019, he sold half his shareholding, reducing his stake to 7.9%.
The firm’s two remaining founders are both still on the board in executive roles, with significant shareholdings.
I don’t think these two risks are sufficient to rule out Capital Drilling, although they have tempered my enthusiasm. However, I’m keeping an open mind, pending a review of the firm’s financial performance.
Fair value?
The stock’s ValueRank score of 86/100 suggests to me that the price tag, at least, may be attractive:
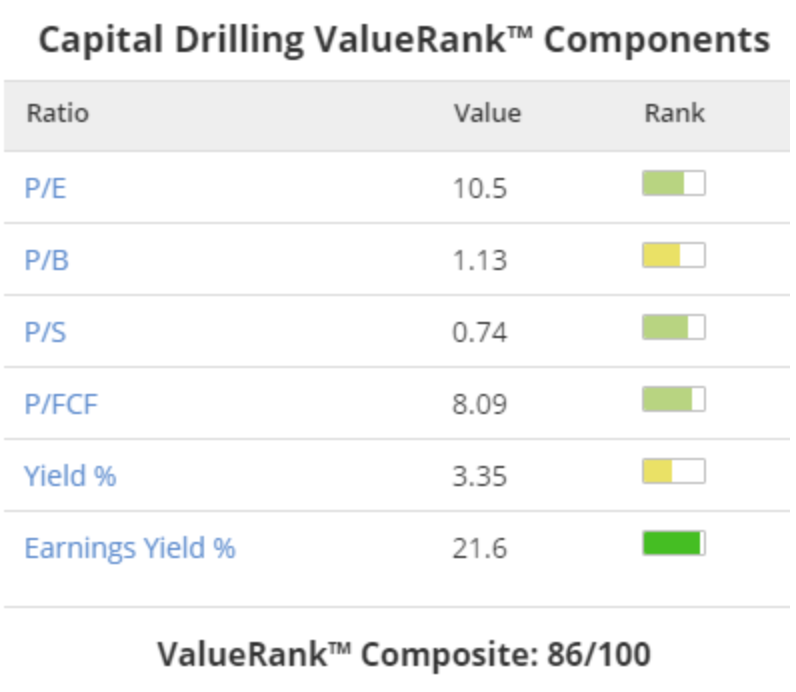
Strong free cash flow, a well-covered dividend yield and a modest price/book ratio paint an attractive picture. But the highlight here is CAPD’s earnings yield (EBIT/EV) of 21.6%. That’s an outstanding figure which indicates that based on last year’s results, anyone buying the company outright would receive an annual operating return on their investment of 21.6%.
This metric lies behind the excellent Greenblatt Magic Formula Score:
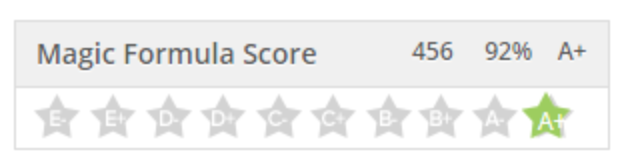
One reason why earnings yield is so high is that the group ended last year with net cash of $10.9m. Net cash is subtracted from the market cap to give enterprise value. This strong balance sheet reassures me. If the firm isn’t cashed-up now, then when will it be?
Improving quality
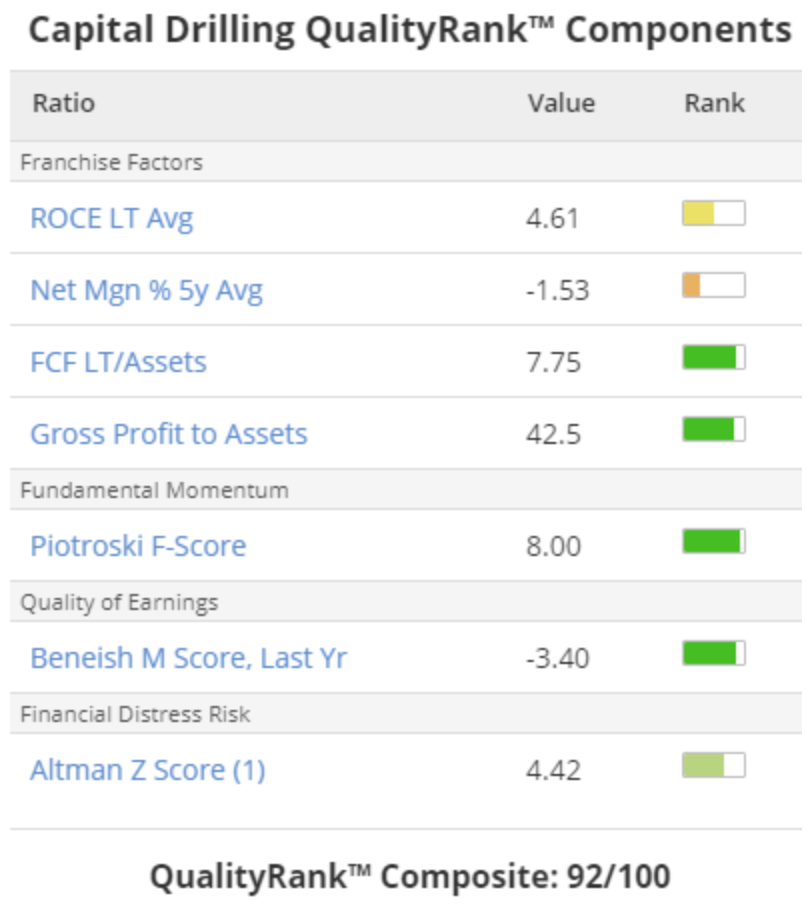
The effects of the 2015/16 downturn are still lingering in Capital Drilling’s five-year average return figures. Although the company’s QualityRank of 92 is underpinned by an excellent Piotroski F-Score of 8/9, the average return on capital (ROCE) and 5y net margin figures are poor:
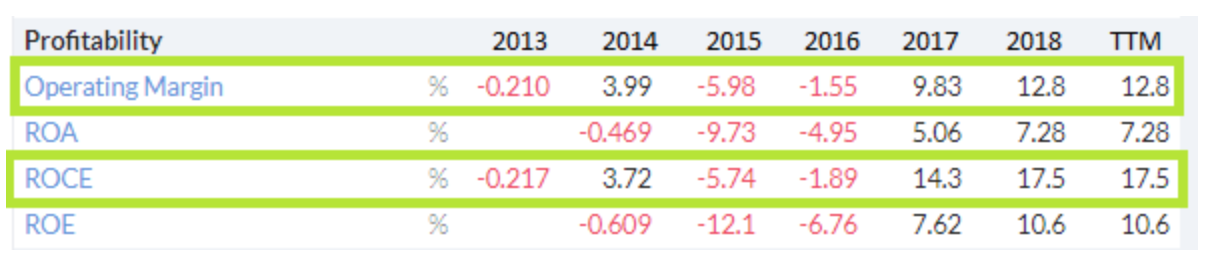
However, these numbers reflect the vicious cyclical downturn seen in 2015/16. Profitability is now improving significantly:
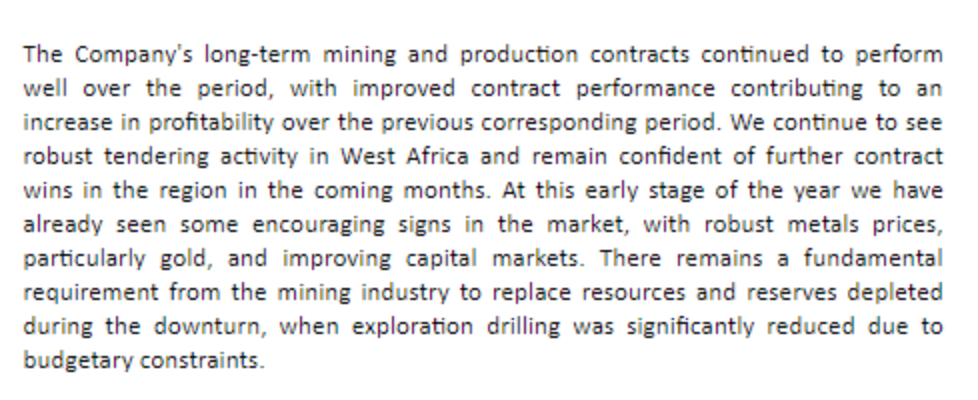
In my view, the investment thesis here is that the mining cycle is now likely to move into a more expansionary phase in order to replace depleting resources. This could generate new work for Capital Drilling.
The company expects to see evidence of this during the year ahead, based on comments made in April’s trading update:
Intangible quality: As an industry outsider, it’s hard to know just how good Capital Drilling’s reputation is, and how much direct competition it faces in its core markets. The firm’s strong balance sheet and rapid post-downturn recovery suggest to me that it is respected by clients and well run. Another positive point is that 70% of revenue comes from production projects, so doesn’t rely on speculative cash.
On the other hand, the company warned in its 2018 annual report that it’s dependent on a few key customers:
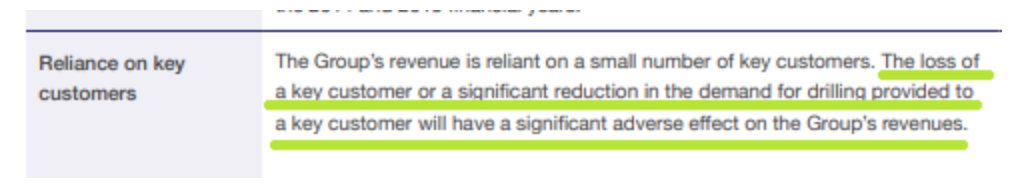
This is always going to be a risk.
Positive momentum
Capital Drilling qualifies for one of Stockopedia’s top-performing momentum strategies, Tiny Titans. This screen has delivered an annualised return of 21.5% since inception and has provided me with a number of good ideas over the years.
Looking at the MomentumRank, I see a fairly positive picture:
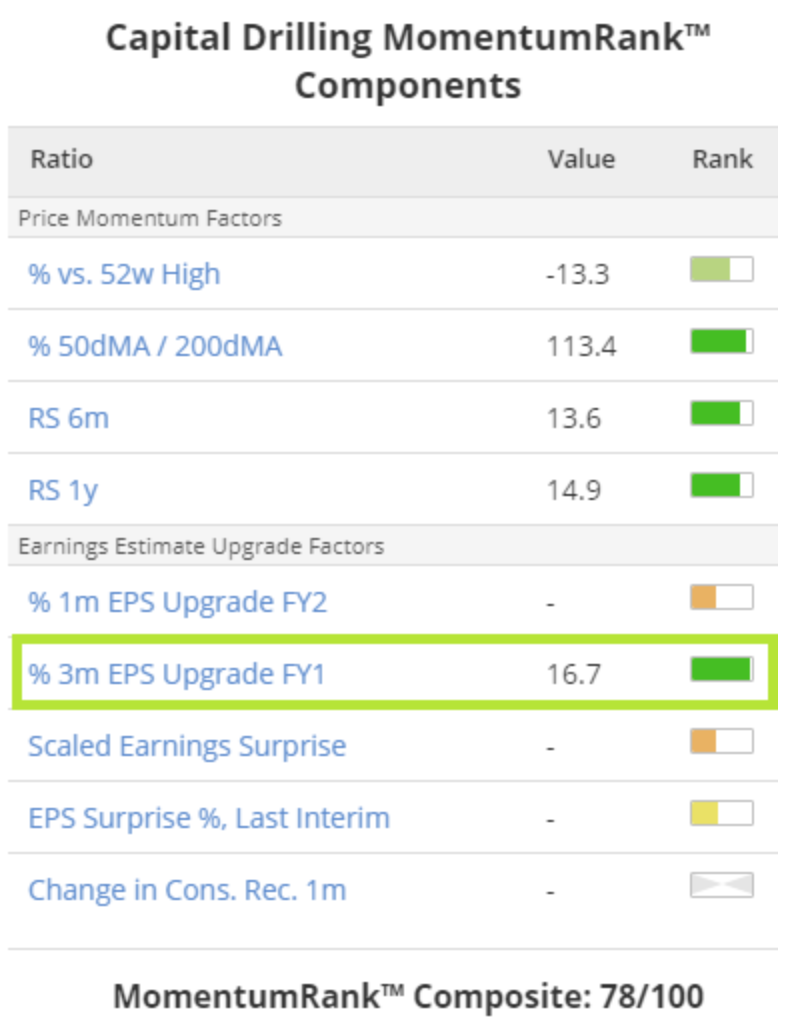
April’s trading update appears to have triggered a 16.7% increase to broker consensus forecasts for the year, which seems encouraging. The technical picture looks quite positive too, with the shares trading close to their 52-week high and outperforming the wider market, as indicated by a relative strength greater than zero.
My decision
I’ve tried to highlight some of the main risks I can see for investors in Capital Drilling. However, I don’t think there are any smoking guns that should cause major alarm. The only factor that really does worry me is that risk that the firm could lose its Acacia contract if that company changes hands.
Notwithstanding this, I think the broader market environment should be supportive for CAPD. So I’ve decided to add the stock to the SIF folio and my own holdings this week, after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
And a further 8% fall so far today?
Any idea why CAPD share price fell 10% yesterday on a fairly neutral trading update?
Capital Drilling (LON:CAPD) was my Stockopedia StockSlam pick at November's Mello London and I rate it highly. A couple of additional thoughts:
You are right to highlight the cyclical nature of the business, which shows up in their profit figures, however, it is also worth looking at their operational cash flow, which has remained positive during the last downturn. Effectively, when the market is weak they just turn off some of the capex and the business still generates cash, then in an upswing they invest again.
They have been building a small portfolio of investments in junior miners that they drill for. Usually via placings but the net effect is that they have been providing drilling services for shares. Not everyone likes this given its increased risk profile, but if you trust that their on-the-ground management knows the good prospects better than the average mining investor then you are also getting some option-like exposure to a sector that may be entering the cyclical upswing.
Where I would like them to improve is being more aggressive with their cash holdings. Cash is piling up on the balance sheet and they have limited opportunities at this stage to deploy the capital into the business, only Blast Hole rigs are really at capacity in their fleet. I'd really like them to use their buyback authority or pay a special dividend. They could have taken a good chunk of the Burton stake into treasury if they had wanted to and would have been earnings enhancing given their lowly rating.
Hi dangersimpson,
Thanks for your comments and additional insight on Capital Drilling (LON:CAPD).
Re. the rising net cash balance, I agree that investing in new capacity doesn't appear to make sense, given reported fleet utilisation. I'd be happy to see a small shareholder return, but I would prefer to see this company maintain a fortress-like balance sheet.
Given the firm's customer concentration and its exposure to political, operational and commodity price risks, this isn't a business I'd want to own if it became substantially indebted. The experience of Gulf Marine Services (LON:GMS) over the last five years, although not directly comparable, is educational, in my view.
Regards,
Roland
Fantastic write-up on Capital Drilling (LON:CAPD) Roland. It’s in my watchlist but not sufficiently compelling for me to take the plunge. Nonetheless, it was a great presentation of the investment thesis, thanks.
I'm still a relative novice in this stocks and shared lark, but I've been watching Capital Drilling for a few months and spookily took a small position only yesterday so your article is very timely/welcome. I also like the cyclical play, there was also a nice update and interview on proactiveinvestors a few days ago which finally prompted me to 'press the button'.