SIF Folio May review: Capital Drilling, Medica, Bloomsbury and H&T

Over the last couple of weeks, we’ve seen a number of well-respected businesses raise cash by issuing new shares. These have included Compass Group (£2bn), Premier Inn owner Whitbread (£1bn) and Jet2 owner Dart Group (£172m).
None of these businesses are in financial distress, as far as I can see. Instead, the common theme in these fundraisings is that management are taking steps to protect their companies against an uncertain outlook.
By raising cash now, these businesses should be able to survive a more prolonged downturn without running into issues with debt covenants and leverage. If things improve more quickly, they’ll be in a strong position to take market share from weaker rivals.
The fundraising announcements I’ve linked to above make it clear how uncertain the outlook is for individual companies. Even experienced business leaders who’ve worked through several economic cycles admit that they don’t have any idea what will happen next. Things could get better quickly, or they might not.
How I’ve adapted the SIF strategy
Since February, I’ve suspended all planned share sales from my SIF folio. With valuations at distressed levels, I thought the risks of holding were less than the risks of selling.
But the situation has changed. Although the uncertainty continues, lockdown is gradually being unwound. The FTSE 100 is up by more than 20% from its March low of 4,993. On a long-term view, I still think that many stocks offer decent value. But I don’t think valuations are distressed, and in the short term I think we could see further sharp falls.
Based on this view, I’m planning to follow through on my promise last month and resume my normal selling process for SIF stocks. I think it’s important to try and maintain the integrity of my systematic strategy, even in unusual circumstances.
To bring the portfolio up to date, this week I’ll be reviewing all stocks that have been in the portfolio for at least nine months - my default holding period. Companies that still pass my screening rules (here) will stay, others will go, unless I choose to exercise my right to discretion.
Portfolio review
Four companies are up for review and possible sale this month:
Capital Drilling (LON:CAPD)
H&T Group (LON:HAT)
Medica Group (LON:MGP)
Bloomsbury Publishing (LON:BMY)
I’ll come to these shortly. First, let’s take a quick look at how the SIF folio has performed over the last month:
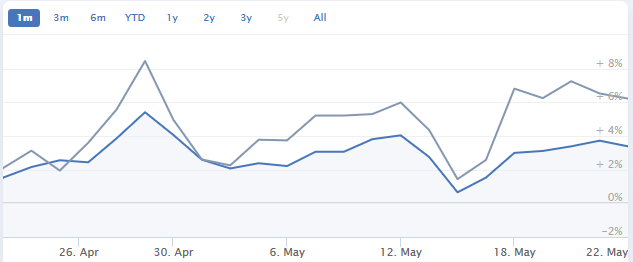
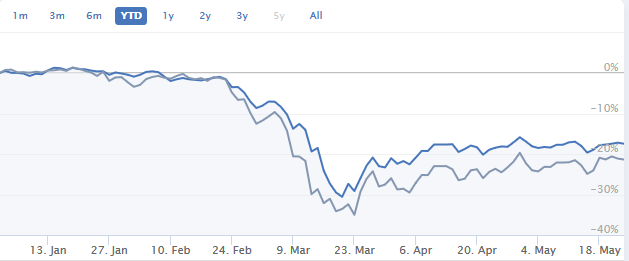
SIF (blue line) has underperformed the FTSE All-Share index (grey line) over the last month. But the folio remains ahead of the index so far this year and suffered a smaller drawdown in March’s crash:
Here’s how the portfolio looks at the time of writing. These figures reflect closing prices on 22 May. I’ve highlighted the four stocks I’m going to look at this week.
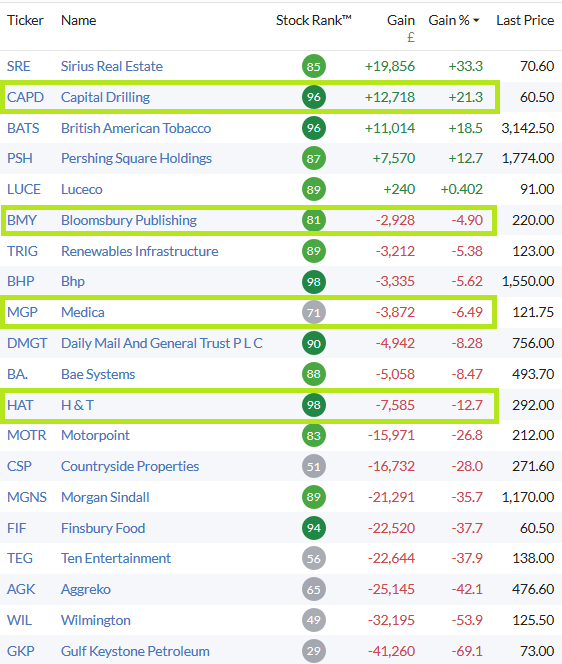
It’s a pretty mixed picture, but as far as I can see, none of these businesses are currently likely to suffer financial distress. So I remain happy to hold and see what happens.
Capital Drilling (LON:CAPD)
(Original coverage: 02/07/2019)
My exposure to this gold mining services group has definitely been a help during the pandemic. The price of gold has risen by 35% over the last year to around $1,725/oz, supporting investment in gold mines. At the same time, most African gold miners have been able to operate more or less as normal, despite the coronavirus.
Capital Drilling’s client list includes well-known Africa mining names such as Barrick Gold, AngloGold Ashanti and FTSE 250 firm Centamin. Despite its small size, this business appears to have a solid market share and decent reputation.
I covered Capital Drilling’s latest trading update in April, so I won’t repeat myself here. The only comment I’d make is that co-founder Craig Burton has continued to sell down his holding, most recently reducing it to 3.8%.
However, executive chairman Jamie Boyton has a 15% shareholding in the business and co-founder and executive director Brian Rudd owns 10.9%. I’m comfortable that management interests should be aligned with those of shareholders.
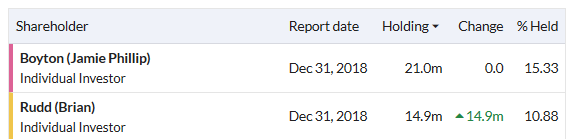
Does CAPD pass my screen? Slightly to my surprise, Capital Drilling passes my screening rules without any serious problems.
The only two tests that this stock fails relate to its spread and to the dividend, which is expected to fall this year. I don’t see any mileage in selling a successful holding because it’s become illiquid.
Similarly, I’m happy to overlook dividend cuts in the current climate, assuming the underlying business is still performing well. Capital drilling is, so this stock will stay in SIF for at least one more month.
Verdict: Hold
Total return to date: +24.5%
Medica Group (LON:MGP)
(Original coverage: 23/07/2019)
Medica Group provides outsourced radiology services to the NHS, using trained NHS radiologists working in their own time at home (using suitable workstations).
The business has grown strongly in recent years but has been hit hard by the coronavirus pandemic, which has resulted in a sharp drop in routine and emergency work.
In my April update I discussed some concerns relating to management changes, possible margin pressure and aggressive growth targets. Last week’s AGM statement didn’t do much to reassure me, flagging up a 95% reduction in routine activity and still-depressed levels of emergency out-of-hours reporting.
The firm says a full recovery in routine activity could take some time, due in part to the impact of distancing and cleaning requirements on appointment levels.
My feeling is that the group’s current valuation is up with events, despite last year’s 21% operating margin and an £8m net cash balance.
Does MGP pass my screen? Sadly not. Medica fails several key tests of valuation and growth:
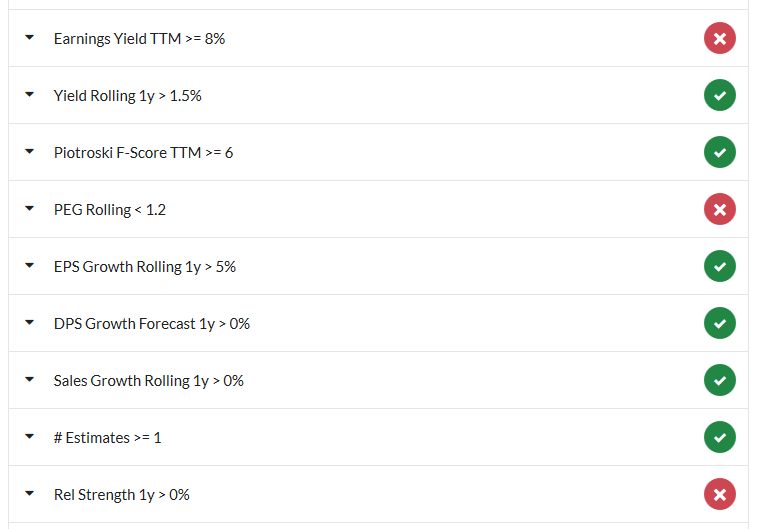
As a result, I’m going to sell this stock from the SIF Folio and my own holdings later this week, after this article has been published.
Verdict: Sell
Total return: -6%
H&T Group (LON:HAT)
(Original coverage: 16/07/2019)
This pawnbroking, retail and lending group has suffered from the closure of its shops during lockdown. However, I think it remains in good financial health with attractive long-term prospects.
I covered the latest statement from H&T in my April update. Graham Neary has also covered this stock recently in the SCVR. There’s been no further news in May. My view that this is a good business at an attractive valuation remains unchanged.
Stockopedia’s algorithms also seem to agree, awarding a StockRank of 98 and a Super Stock style rating.
Does H&T pass my screen? After making some adjustments for the current situation, I find that H&T does still pass my screening tests. So I’ll keep this stock in the SIF folio for at least one more month.
Verdict: Hold
Total return to date: -11%
Bloomsbury Publishing (LON:BMY)
(Original coverage: 06/08/2019)
Last week’s full-year results emphasised the high level of uncertainty about performance this year. Paul discussed this in more depth in the SCVR on 20 May, so I won’t reiterate these comments.
I still like this business and am attracted to the growing digital and academic divisions, which performed well last year.
But although I think Bloomsbury shares could be cheap at current levels, I’m more inclined to think they are fairly valued.
Does BMY pass my screen? Almost. Bloomsbury only fails one of my screen tests:
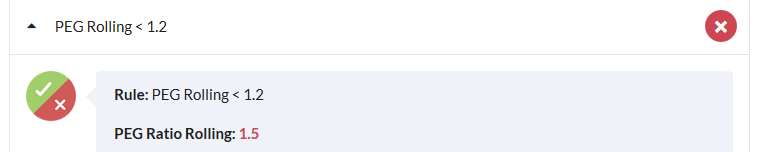
I will abide by the results of my screening test and sell Bloomsbury from SIF this week.
Verdict: Sell
Total return: -4.4%
Disclosure: At the time of publication, Roland owned shares in Capital Drilling, Medica Group, H&T Group and Bloomsbury Publishing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
I am going the other direction in Medica. Bought some last week. Passes through my key screen based on Oakley quality factors....fcf dynamics really. Always feels a little strange going in the opposite direction to respected analysts.
I also sold Medica last week. I also took some profits from Naked Wines on which I was up 90 % and bought more of Motorpoint. I think this has more upside in the short to medium term.
Interested to know if Globaltrans (GLTR) meets your SIF criteria at the moment as I am considering buying more at sub $6.
Hi Will,
Forecasts for falling sales and earnings in 2021 rule Globaltrans Investment (LON:GLTR) out for the SIF screen at the moment. I also have a self-imposed ban on Russian stocks, but I do agree that it seems cheap.
Interesting to see the top institutional shareholder is now Schroders (LON:SDR)
https://www.stockopedia.com/sh...
Roland
Great article Roland always enjoy your rambles keep them coming
Thank you Roland I agree with you re Medica. Good article Tim B
You are are hard man Roland but thats what we are here to read. I have to confess to 'emotional' attachment to Bloomsbury Publishing (LON:BMY) and Yes, I too have been concerned about progress within this company - but I am content that they do have financial strength and believe that as things get back to 'normal' (whatever that turns out to be) this company will do well so for me its a Hold! - But appreciate your analysis.