Small Cap Value Report (Fri 1 Dec 2017) - PURP, GAW, RM2, PAM

Morning,
Paul added some additional companies to yesterday's report, so it now covers:
- Lamprell (LON:LAM)
- James Latham (LON:LTHM)
- ST Ives (LON:SIV)
- On The Beach (LON:OTB)
- HML Holdings (LON:HMLH)
It's at this link.
Cheers
Graham
Purplebricks (LON:PURP)
- Share price: 356.6p (unch.)
- No. of shares: 273 million
- Market cap: £973 million
Purplebricks adds Feefo to customer review choices
This online estate agency has had a few issues with customer reviews.
Allagents suspended its reviews of Purplebricks in September, with the following notice:
Due to repeated threats of legal action forcing the removal of content and negative reviews from our website, we have regrettably taken the unprecedented step in suspending the PurpleBricks profile page until further notice (as of the 18th September 2017).
This was a huge red flag for me (see SCVR here).
Today, Purplebricks announces a new initiative which is supposed to ease concerns on the review front:
Purplebricks Group plc ('Purplebricks' or 'the Group') is pleased to announce a new partnership with customer review site Feefo, providing customers with even more opportunities to review the Purplebricks' service.
Feefo is widely regarded as being transparent, independent and secure, and is trusted by consumers as a vocal advocate of honesty in the reviews industry. It is only available to genuine customers, who are provided with a unique review link, ensuring only authentic reviews.
This all looks like suspiciously too much effort to me.
Fake reviews and bad reviews are a hazard to every company, not just Purplebricks. What makes Purplebricks different that it needs to pay a special company to verify its reviews?
As to the claim that Feefo "is widely regarded as being transparent, independent and secure, and is trusted by consumers as a vocal advocate of honesty in the reviews industry".
The funny thing about that that is, that Feefo itself has been reviewed by 39 people on trustpilot. See for yourself at this link. It is rated as "bad".
Examples:
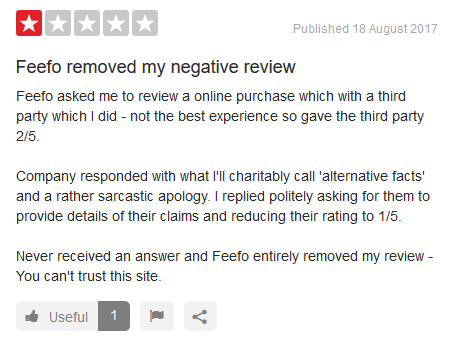
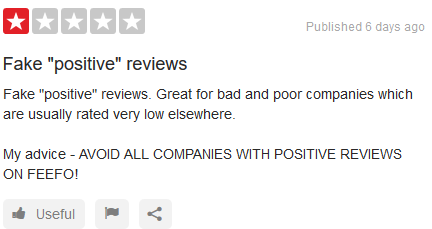
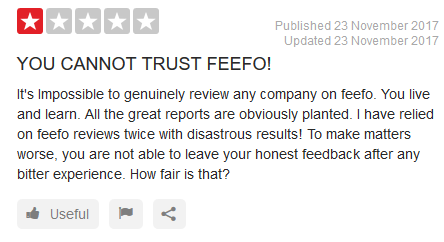
There is a 5-star review from someone who reckons that the poor reviews are by trustpilot themselves, trying to do in a competitor.
I wouldn't rule that out, in the same way I wouldn't rule out the conspiracy theory that Purplebricks was unfairly treated on Allagents, and targeted by its rivals for bad reviews.
But in general, it is safer to assume that reviews are poor when products are poor. For now, I'm going to assume that the products are poor.
Games Workshop (LON:GAW)
- Share price: 2105.5p (+7.5%)
- No. of shares: 32 million
- Market cap: £676 million
Games Workshop, creator of Warhammer, has a fiscal year ending in May. So the H1 period has just ended, and it issues a H1 trading update. Results are in line with expectations.
Preliminary estimates indicate sales of c. £109 million in the first six months of 2017/18 and an operating profit of c. £38 million for the period.
Over the first half we have seen sales and profit growth in all channels in constant currency terms with the momentum continuing throughout period. These results are in line with expectations for the year ending 3 June 2018 although the Board is aware that it is still early in the 2017/18 financial year.
The share price has more than trebled this year, thanks to a surge in momentum flowing from newly-released kit.
In August, Ben Hobson published a nice article showing how the company evolved from a value play to a "super stock"!
The company has a huge gross margin of c. 70%. Combine this with the largely fixed expenses of running a portfolio of physical stores, and you get a turbo-charged increase in operating profit from incremental sales.
Warhammer ran a huge and highly successful summer campaign this year.
And it's important to note that the product release cycle is somewhat lumpy. Customers can buy a piece of kit and enjoy it for six months, and then its up to Games Workshop to motivate new purchases with an update to the storyline and new characters.
So brokers are forecasting that profits will dip over the next few years. They reckon it will be hard for the company to match the huge performance this summer.
I can see forecasts for pre-tax profits of £65 in 2018 million, then £55 million in 2019, and £58 million in 2020.
That said, there is no denying the uniqueness of the franchise.
When I was a teenager, the choice was to play either Warhammer or Magic: The Gathering (owned by Hasbro, $HAS). I never played Warhammer, but it was a close run thing!
Clearly, some people continue to play these games long after their teens. They have an enduring appeal.
As Paul has pointed out, Games Workshop (LON:GAW) shares have appreciated mostly due to earnings upgrades, and not due to multiple expansion.
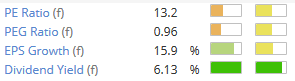
So they are arguably still "cheap", but bear in mind that unless another amazing new campaign is launched, there is unlikely to be much earnings growth for the next few years.
But for a long-term buy-and-hold, given the strength of its reputation (and the loyalty of its fans), it looks reasonable to me.
£RM2
- Share price: 2.625p (-16%)
- No. of shares: 407 million
- Market cap: £11 million
Update on trading and financial position
This is a pallet designer which I called as a sell/avoid earlier this year. I do occasionally get things right, as it is down by over 90% since then.
In simple terms: it designed a product which has received very few orders, and it has no money with which to pay its outsourced manufacturer, who isn't going to make any of them if there is no way it is going to get paid.
On 27 September 2017, the Company stated it intended to confirm, subject to securing the necessary funding, a 12-month production forecast for its Chinese contract manufacturing partner, Zhenshi, by the end of November 2017. The Company today announces that it has not yet been able to secure the necessary funding to confirm this forecast.
It is forecast to run out of money in February, and I continue to suspect that this company has zero value beyond its quickly diminishing cash pile.
The cornerstone shareholder is a well-known fund manager - perhaps they will recapitalise it.
Premier Asset Management (LON:PAM)
- Share price: 213p (unch.)
- No. of shares: 106 million
- Market cap: £225 million
This is a mid-tier asset manager which has been listed since October 2016. The share price has done extremely well for investors so far.
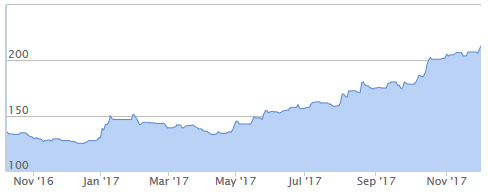
Assets under management (AuM) have again increased by 22%, and are now at £6.1 billion. So the compounded gain in two years is pushing 50%.
Performance remains strong. Over 90% of AuM is above the median performance for comparable funds, and over 70% of AuM is in the first quartile, over both three and five years.
These types of statistic can mislead when poorly performing funds are closed or merged, but I don't think Premier Asset Management (LON:PAM) has done this.
The continued strong fund flows suggest that customers are happy. The year-end result is that £750 million (net) flowed in, a small reduction compared to the previous year.
This means inflows represented about 75% of the asset growth. It probably doesn't make much of a difference in terms of fees, but I prefer asset growth from inflows (i.e. from paying customers taking action) rather than from market movements.
These two things do tend to be positively correlated. Usually, both of them are favourable or both of them are unfavourable!
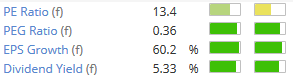
Dividends - Premier pays four quarterly dividends, with a total payout this year of 8p. The forecast yield, and other valuation metrics, are certainly attractive:
Browsing the company's list of funds (see here), we can see they are heavily income-oriented. The Chief Executive writes:
Many of our multi-asset and equity funds have income as a primary objective. Over the year, these funds have been able to grow their dividend distributions and continue to offer attractive yields against their comparative benchmarks and cash interest rates.
Given the low interest rate environment, maybe the income focus is what has helped to propel the assets under management over the past few years, as investors scramble for yield?
The only problem with this, of course, is that it's not going to last forever. If/when interest rates rise, then equities will go back to being equities, and income-oriented investors will go back to investing in bonds.
For now, though, investing in the likes of Royal Dutch Shell, HSBC, BP and Lloyds Banking Group (the top 4 holdings in the Premier Monthly Income Fund), is the most straightforward way to generate an acceptable income.
Reading through the commentary, most funds referred to are income funds of one form or another. Maybe we are at the top in terms of the demand for income funds?
Outlook statement is positive:
As always we face many challenges but we are performing strongly and believe we are well positioned for the future. We recognise that there is hard work ahead, but we have every reason to look forward with confidence.
Management fees are responsible for the vast bulk of revenue, and we can see how they have evolved:
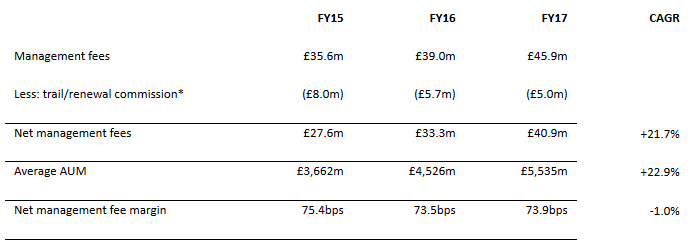
So the fees only increased by 18%, but net of commission they are up by 23%.
The impact of all the new AuM won't have been felt yet, so we can reasonably anticipate another uplift in 2018.
My opinion
Premier Asset Management (LON:PAM) is now significantly more expensive than Impax Asset Management (LON:IPX), the other mid-tier asset management I've been writing about recently, on an AuM basis. Premier's market cap is c. 3.6% of AuM, versus 2.7% for Impax.
Impax only earned 52bps of revenue on its AuM this year, however, while Premier earned 74bps (see the table above).
What I'm struggling to understand is the niche which Premier is filling. Are customers simply hungry for something new? Is it the distribution capabilities which have powered inflows? Or is it all about the performance achieved over the last five years or so, in which case how do we know it can continue to be so good?
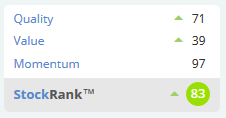
I don't know the answers to these questions but the company is certainly firing on all cylinders, and the shares aren't expensive by any means, relative to how it's doing at the moment. Worthy of further research.
I'm afraid that's all I've got for this week, see you next time!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Don't think top managers want to work for Woodford as it's his show.
the thing with woodford hes been in a bad run in a bull market. there's no excuses for a fund manager like him to be performing like this. understandable if hes fund did that in a bad market but a bull market like we had this year, cmonnn woodie...
Toys r US closing stores. not ideal for £CCT
Sadly not great news for Character (LON:CCT) this http://www.bbc.co.uk/news/business-42204182
Just as they look to put out a new update (next week alongside FYs) they get hit with a second batch of uncertainty. Rotten luck
Regarding £RM2 you’ve got to almost feel sorry for Neil Woodford. He’s investing more in small early stage companies now and so a fair number will get into trouble but he seems to be having a very difficult run of luck at the moment. I’m sure many investors were swayed in the past by his holdings- if Woodford is in then it must be ok. Now the reverse is almost becoming true. He has had a big success with Purplebricks (LON:PURP) but now the price of that is going through a difficult period too.
Are we too overawed by the high performance of star managers and traders?
Now Neil Woodford "warns of stock market ‘bubble’" "‘There are so many lights flashing red, I’m losing count’" : https://www.ft.com/content/64bfef5c-d5d0-11e7-8c9a-d9c0a5c8d5c9
Neil woodford is a idiot. hes gambled with investors money on high risk start up companies. he has no one to blame but himself. he change his investing style and it no longer worked for him and he thought he was smart but obviously not.
his now warning of a stock market bubble, but if the tax bill is passed in the US the stocks will fly all the way again next year. If this is the case Japan is the place to be next year.
this is just my prediction I don't think the bubble if any will occur till the year of brexit.
"but if the tax bill is passed in the US the stocks will fly all the way again next year."
Well, I guess it's possible. It's also possible they might not. Minervini on Twitter seems to think the markets are buying the rumour now and will sell the news if it passes, and sell the disappointment if it fails.
I guess we'll see one way or another soon enough...
Hi vik2001.
Re. Neil Woodford, he’s one of the ultimate contrarian investors and made his reputation by shouting the odds about the emperor having no clothes when most saw his dot com wardrobe as the only game in town. Over a long career his performance has generally been very good. To date the performance of his new funds, Patient Capital Trust in particular, has been both absolutely and relatively poor as a number of large holdings in “new economy” companies have gone spectacularly wrong. (That said some of his “old” ones like Provident Financial have been pretty sick too.) To be fair to him, however, the WPCT fund is being managed in line with its original mandate and it was always sold as being a 5 year or more investment. Most cakes look messy half way through the making.
Smart and lucky are not the same thing and he’s clearly on a bad run at the moment. Like Antony Bolton who also made a radical late career shift (moving from UK Special Situations to China) he may have misplaced his investing mojo but I suspect this is temporary rather than permanent. Unlike Bolton, however, Woodford is now running his own fund company and doesn’t have the behemoth of Fidelity behind him. My concern for Woodford’s investors (I have a small WPCT holding in my SIPP) is that investors lose faith and look to draw out their capital in the near term and he becomes a forced seller of some of his large holdings in illiquid small caps which becomes a rout. This possibly has wider implications for investors in any of the companies where he becomes a distressed holder.
Gus.
Gus, Woodford Patient Capital Trust plc is a closed-ended investment company. The outflow of funds forcing asset sales is a risk associated with open ended funds not closed ended funds. The choice of a closed ended fund is absolutely correct for long term VC/start up type investments.
Hi N1ck.
As you say WPCT is closed ended but the two income funds are open ended and also have relatively big holdings in companies such as Provident Financial (LON:PFG) and Purplebricks (LON:PURP) which might come under pressure if investment outflows make Woodford a forced seller. I agree the WPCT fund is shielded from this by being closed ended although recent poor performance might make it harder to raise fresh funds if he wants to pump more capital in to support his holdings.
Gus.
I've been invested with Woodford, in one fund or another, since 2005. My Woodford rant:
What perplexes me is that there are at least two instances where monumental falls in value should have been forseeable. I can't find the article anymore, but I'm certain that Woodford (or a representative) stated that their analyst had studied the Utilitywise (LON:UTW) accounting policies and that they understood and were comfortable with them. We've since learned that Utilitywise was declaring revenue from contracts that didn't commence for, in some cases, several years. Either they didn't review the accounting policies or they didn't understand them. Neither is a good answer.
The second one is Provident Financial (LON:PFG). I attended a presentation by Cattles some number of years ago. They also did doorstep lending. The Cattles management team touted their competitive advantage as being their agents who (usually) lived in very close proximity to their customers (eg on the same estate). A good agent was one who maximised the lending potential from every day events like weddings, graduations and car trouble amongst a large circle of acquaintances. A good agent also maximised collections because they often had line of sight to the comings and goings of the customer or knew the schedule well enough to maximise the likelihood of interacting with them (eg the local youth football match). Why didn't Woodford understand the business model well enough to see that firing 50% of the agents would significantly disrupt both origination and collections? Maybe he knew it thought the short-term pain was worth long-term gain. If he did see it, why not sell down at least some and re-buy when the price inevitably drops?
By way of contrast, Keith Ashworth-Lloyd sold out of Provident Financial (LON:PFG) in his Buffetology fund ahead of the last profit warning at around 2040 - 2100p citing the reasons you mention.
He since bought back in at an average of 770p because he thought it oversold and believes they now have the right people in place to fix things.
Time will tell. I hold Buffetology but not any Woodford funds.
I think Neil Woodford needs to sack his team and start over because it's okay to make two or three investment mistakes, but to invest in RM2 is unforgivable, ordinary investors would have spotted five to six red flags in under an hour.
Or, he needs to start reading the Stockopedia discussion page for investment ideas! IMO
Interesting analysis of Premier Asset Management (LON:PAM). Thanks, Graham.
I think the net fee margin is probably explained by their retail focus where 75bps (net) seems in line with other retail funds (or, at least, the ones I have). Almost all of their AuM are retail funds with a small amount of discretionary managed. As at 30 Sep, the sum total of AuM drawn from the monthly retail fund factsheets amounts to £5,750m as compared to corporate AuM of £6,087.8m. The difference was £162m in investment trusts and, I'm assuming, the remaining £170m in discretionary managed.
I think your mkt cap % AuM is useful but needs to be cross checked against fee margin. A bit like comparing EV/EBITDA multiples for two companies without looking at tax rates.
I quite like the fact that I can check the monthly fund fact sheets to see how they're doing in between the quarterly AuM announcements (a bit like CML stats for Mortgage Advice Bureau). They've had 23 funds each month since May (except June which was 24) having closed Strategic High Income Bond in July and opened Diversified Income in June. Since May, AuM increased in 13/23 funds in May, 19/24 in July, 17/23 in Aug, 16/23 in Sep and 22/23 in Oct. Thus, they don't appear overly reliant on any one fund (or fund manager) increasing AuM. The monthly AuM performance is despite the fact that many of the funds pay dividends very regularly (sometimes monthly).
The AIM listing document suggested (from memory) that "income" had been the leading fund inflow category in 7 of the 10 past years. Trustnet says that Woodford Income Focus, which opened in April, has AuM of £717m, about half of which came after launch. For the time being at least, "income" continues to attract assets.
The distribution platform does seem quite strong. It's almost exclusively through IFAs. They've attracted >£500m (gross) in each of the last four quarters. If they could cut down on the outflows they'd be growing even faster!
forecasts for pre-tax profits of £65 in 2018 million, then £55 million in 2019, and £58 million in 2020.
Broker forecasts have been completely wrong for GAW, 12 months ago consensus EPS forecasts for 2017/2018 were 45p/46p. 2017 EPS was 93p and EPS in H1 2018 alone looks like its over 90p.
I don't think GAW can maintain EPS growth rates of 150%+ but growth could slow to a quarter of what it is now in 2019 and it would still look cheap.
Unwise2
Games Workshop (LON:GAW)
Totally agree with your comments on broker forecasts. I'm not really one for graphs but am interested in number patterns and these seem to suggest earnings figures way in excess of the broker figures mentioned by Graham.
Sales pattern
If you look a the interim profit and loss figures for the last 3 years the second half revenues are always greater than the first half. The average for these three years in 46% in the first half and 54% in the second half. Logical? I would have thought that Xmas is a factor - if you have a relative that is mad keen on this product I guess the entire family breathes a sigh of relief and buys vouchers/gives money to buy.
This would suggest revenues of £128m in the second half and a total for the 2018 year of £237m.
Gross margin
The gross margin for the second half of 2017 was 74% - higher than previous @ 70% but there is some logic in higher turnover bringing manufacturing discounts/ efficiencies. This gives a gross margin of £175m.
SGA/ Royalty Income
SGA is rising but not by the same amount as revenue. Lets be cautious and assume it rises from its H2 2017 level of £44.5m to £48m in H1 and £50m in H2 - £98m for the year. Equally assume royalty income up from £4.5m a half to £5m - £10m for year.
This gives operating profits of £87m for the 2018 year.
Net profit after tax of 19% is £70m - given shares in issue of 32.1m an EPS of 218p arises along with a forward PER of 9.6 at todays closing price.
I would therefore suggest that the current brokers estimates are not up to date with current events.
Looking to the future, whilst I can see a possible breather in 2019, the base from which the company is operating is vastly improved for recurring sales. On the other hand, also equally possibly, this could mark the start of even greater expansion.
Even though this is my biggest holding I'm very tempted to add at this level.
(One final point with reference to my figures above as a check to my basic logic:-
If you take revenue of £109m per the trading statement at 74% a gross profit of £81m arises. Add £5m in royalties and take of £48m in SGA and you get £38m in operating profit which agrees with the statement.)
As always, my opinion, not advice and DYOR.
Phil
Hope everyone has a good weekend
Phil,
Interesting analysis. Just how much out the house broker has been playing catch up can be seen in their recent target prices.
July - Peel Hunt raised its price target to 1500p, (from 1350p)
Sept - Peel Hunt today reaffirms its buy and raised its price target to 2000p.
Oct - Peel Hunt raised its price target to 2400p.
It doesn't give me confidence that they can accurately predict Games Workshop (LON:GAW) profitability in this financial year, let alone into the future. Ian
Games Workshop (LON:GAW) have hit 2500 without a peep from Peel Hunt. This is on massive volume today which must be institutional.
I guess we'll get the update in January - catching up once again!
Being a broker must be a really stressful job.
Phil
Purplebricks (LON:PURP) Personally I hate the whole online published "review" culture. You get all sorts of anomalies and games. In my opinion it ends up a marketing / mudslinging exercise, heavily skewed to local biases and for me at least, largely a waste of effort. For example I've lost count of the times I've been to a restaurant abroad that is 4.5* rated to find it horribly poor and a 2* rated alternative offering excellent local cuisine.
I can quite believe that competitors put all sorts of fake reviews up and I can equally believe that some people felt they ended up with a genuinely poor service, or had not read T&Cs properly and thus had an expectation mismatch.
I don't think the company handled the situation particularly well. All felt a little bit school playground to me, though I do understand why the company might feel angry......but then what do you expect when you disrupt an otherwise cosy industry so dramatically.
so, my approach is to broadly ignore this type of noise. I think it is a red herring. I look instead at sales growth, repeatability and global scalability. Very interested to see how the US does........feels like the valuation is skewed to achieving critical mass there
David,
Yes, I agree with you. I think review sites of this nature are of very dubious reliability.
There can be circumstances where this kind of thing is useful. For example, net promoter scores and similar metrics can, I think, be useful tools. However, they're only useful if a company uses them honestly to properly assess their own performance. Once they start being external or used as marketing tools, they're highly dubious and prone to being gamed.
Purplebricks' problem is that they have trumpeted their Trustpilot scores to investors (and also to customers?) - using them as marketing - so, they've brought this problem on themselves.
Having said that, I very much doubt they worse or more promotional than most estate agents and much of the criticism of them is basically born out of competitors worrying about their competitive position weakening, IMHO.
Rgds
Phil
p.s. I've no doubt that the agents hate Rightmove as well, for example. Unfortunately for them they've got to live with it!
On the topic of review veracity and attempts to game the system, I spent some time earlier this year researching Purplebricks (LON:PURP). From reading through the Trustpilot reviews that weren't 5 stars, it appeared that 1) Purplebricks invited reviews on Trustpilot only on the day of an agreed sale maximising their chance of a positive review. Obviously, no one who didn't agree a sale received an invitation for a review. Other commenters have speculated this is about 35%ish of total customers. 2) reviews that were not 5 stars were routinely (always?) challenged even if Purplebricks already knew that they were a legitimate customer (ie the reviewer claimed to be using their real name). This forced the customer to demonstrate a contractual relationship to Trustpilot before their review could be "undisappeared". I don't understand how being deliberately antagonistic of known legitimate customers is useful to Purplebricks.
Great article I came across on Blue Prism (LON:PRSM) which some of the readers might hold and Paul has commented on previously..
https://www.hfsresearch.com/pointsofview/blue-prism-hits-%C2%A31bn-market-value-but-is-it-sustainable
I am very familiar with Feefo as I use it myself.
It works like this ...
You buy a product/service from me and I collect your email address
I upload your email address to the Feefo server
They email you and request feedback
You enter feedback and it is held on Feefo's server, displayed on their websire and can be piped onto my website
my agreement with Feefo is that I invite all of my customers to leave a review.
Feefo can be 'gamed' as follows:
1) I upload false sales and use friends to provide reviews. Feefo counter this by monitoring IP addresses of reviewers
2) I don't upload sales of problematic interactions
Offering a personal service as a I do, I don't have an auotmated sales system, so I have to upload sales manually to Feefo and so personally I can drop the ball in this respect. Also given that my service is confidential I'll only provide client's email addresses if they give me permission.
So one thing to note is ... a random individual cannot just rock up and provide a Feefo review. They have to be invited by the vendor.
Not sure if that helps
Phil
Very interesting direct insight Phil (re Purplebricks (LON:PURP) or more specifically Feefo)
I'd be interested if you have any views on the trustpilot reviews of Feefo (strewth) that Graham pointed to. Do you think the claim; (not Graham's claim I should clarify) that Feefo will disappear reviews if the client asks them to; has any credibility?
Re: Feefo
Well first of all, for better or for worse, anyone can rock up on the TrustPilot website and leave a review of Feefo.
Secondly it's entirely possible for someone to leave a negative review using Feefo.
Here's my most frank feedback to date ...
I have no ability to edit, remove, hide that comment and actually I don't want to. To me it demonstrates that my reviews are genuine, that I'm transparent and open to feedback from my clients. At no point have I thought or even considered that I could approach Feefo to have a review removed.
I hope you don't mind Graham, but I've posted my survey findings about trading and information systems people use here: https://www.stockopedia.com/content/report-on-trading-and-information-systems-248248/
Thanks to everyone who took part - 120 of you did within 24 hrs of me setting this up so clearly an area of interest to many
have a great weekend
Francis
Hi guys, clearly I will be taking a look at £GAW! Thanks for the requests so far.
Games Workshop (LON:GAW) vote from me too, thanks (hoping for reassurance my impulse buy this morning wasn't too crazy a punt :)
Re .Midwich (LON:MIDW) This company today announced the acquisition of Sound Technology.
However the RNS provides no details about the terms of the acquisition whatsoever. Here is what they say
" The consideration is in line with the Group's traditional model, with an initial cash sum paid on completion and a fixed deferred element paid in cash six months post completion, both financed out of the Group's existing resources. " That's it.
I think this is arrogant and contemptuous of the management. Shareholders are stakeholders and they have a right to be told a lot more than "trust us, we know what we are doing"
(Andy1861 - message 3)
FYI, might be helpful...
https://www.sharesmagazine.co.uk/article/insurer-opens-doors-to-retail-investors-with-600m-ipo
Thanks for the link i had read the article and looks postitive, IC have an article out today and rate it as a 'speculative buy'.
Hi Graham, another vote for Games Workshop (LON:GAW).
Another vote for Games Workshop (LON:GAW) and the likely effect of a bumper H1 on the valuation.
Hi. Games Workshop (LON:GAW) issued a quite startling trading statement today. "Preliminary estimates indicate sales of @ £109m in the first 6 months of 2017/18 and an operating profit of @ £38m for the period". The operating profit for the whole of 2016/17 was £38m - so they've covered that in 6 months.
The earnings momentum of GAW seems to be incredible at the moment.
Any views?
Phil
I know its not a small cap but would be interested to hear any thoughts on the upcoming Sabre Insurance IPO that will be open to public investors.
My morning smallcap tweet:
Simigon (LON:SIM), Thalassa Holdings (LON:THAL), £RM2, Torotrak (LON:TRK)
SimiGon (SIM) share buyback up to $106k. That's <1% of cap!
Thalassa (THAL) sells main opco WGP Group for $20m + $10m earn out as proposed in August. Will leave up to $2,500,000 of cash in the business to meet its working capital requirements during the first five months of 2018. "Any revenue received post completion in relation to certain sales made, services provided and work undertaken by WGP Group prior to completion will be repayable by FFN against this working capital amount." Will use the cash for acquisitions. aka The Soukup Empire.
RM2 (RMS) still hasn't got new funding. Has enough cash till end Jan.
Torotrak (TRK) fails to get refinancing. FIre sale to try to dodge going bust.
Not a very exciting set of RNS's, was it MrC?!
G
If it's excitement you are after I recommend a Jack Russel and a stick.
Not that I have one.
Graham, since you're more the "financials" person, would welcome your thoughts on yesterday's Premier Asset Management (LON:PAM) full-year results.
re: Premier Asset Management (LON:PAM)
Good call, I'll do that next. Cheers.