Small Cap Value Report (Thu 23 May 2024) - MKS, HL., BMY, CAL, QQ., AJB, CHRT

Good morning, it's Paul & Graham here!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting Today
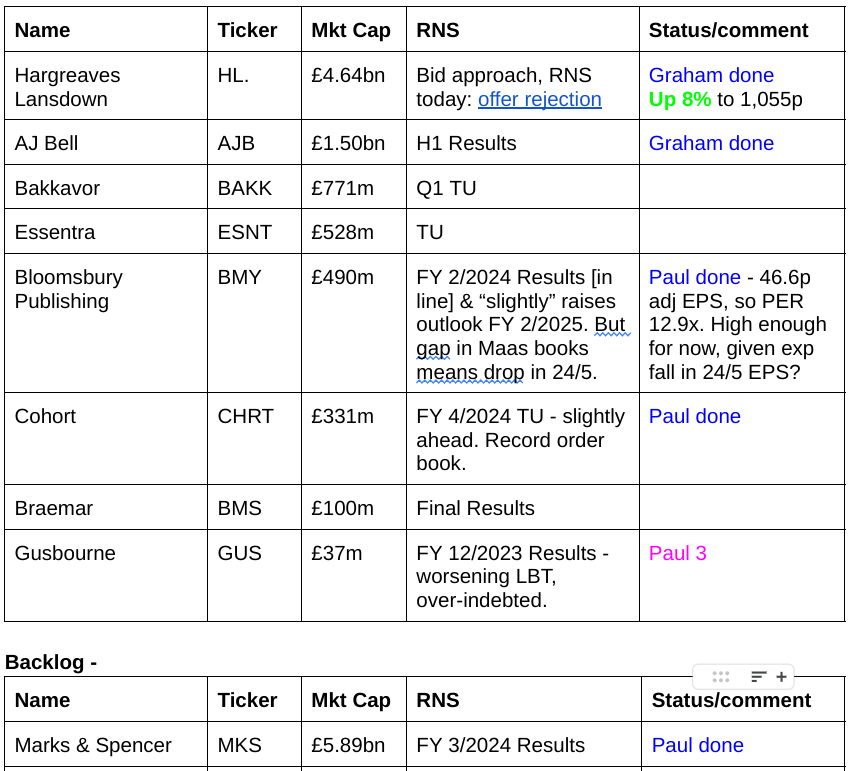
Other Mid-Morning Movers (with news)
Capital & Regional (LON:CAL) - up 13% to 58p (£131m) - Possible takeover interest - Paul - PINK
CAL it has received potential bidding interest from two suitors -
Vukile - property co approached CAL on 19/4/2024 with an indicative proposal in cash & shares. Vukile seems to be based, and its shares listed, in South Africa - would UK investors want shares listed on the Johannesburg Stock Exchange? Vukile issues a statement here confirming it is in the early stages of considering a bid & has submitted an indicative proposal.
Growthpoint Properties Ltd owns 68% of CAL, so it’s their decision what happens next. CAL says it is aware that Newriver Reit (LON:NRR) has also approached Growthpoint about a possible cash & shares bid for CAL.
NRR has issued a statement today, confirming its possible interest in acquiring CAL, and explains the rationale, things like increased scale, cost synergies, more liquidity in its shares, etc. Makes sense to me, given CAL being sub-scale at £131m mkt cap.
Paul’s view - none, as property investment companies are quite a specialised area, requiring careful assessment of the properties owned, the terms of the tenant leases, borrowings - terms and LTV, interest rate hedging, covenants, etc. There’s also the issue of portfolios of older properties possibly requiring very expensive renovations in order to meet environmental requirements. So well above my ability to assess quickly. The discount to NTAV at CAL does look intriguing though, and is a good starting point. I think selectively there could be rich pickings in the property sector, as interest rates seem likely to have peaked, people are returning to offices, and the economy is now growing again - never mind "soft landing", it's already landed, and it taking off again! Some of the smartest (and most successful) professional investors I know are taking a keen interest in the investment property sector, so I like the idea of looking into these.
Qinetiq (LON:QQ.) - up 13% to 423p (£2.42bn) - FY 3/2024 Results - Paul - GREEN
I’ve not looked at this mid-cap before, but on a very quick skim of the results, and the outlook, plus the StockReport figures, it looks interesting I’d say - well worth a closer look. The market clearly likes its FY 3/2024 results, which are strong, with adj EPS up from 26.5p LY, to 29.4p this time (PER 14.4x) - doesn’t sound expensive for a quality business (good profit margins), with an OK balance sheet (c.£200m NTAV), and a strong outlook. It raises guidance for the new financial year.
Paul’s view - obviously this is not a proper in-depth analysis, but I’m just flagging up that the basics look interesting, and worth you researching in more detail. Quite a few US investors on the major shareholder list - what’s the betting this becomes a bid target? Although as it’s defence-related, I wonder if regulatory hurdles might be a consideration? I’d be interested in hearing from any readers who’ve looked at this interesting company. I’m happy to flag up interesting mid-caps for discussion when we spot them.
Summaries of Main Sections
Quick comment -
Marks and Spencer (LON:MKS) - up 5% to 288p y’day (£5.89bn) - FY 3/2024 Results - Paul - GREEN
Lovely results from MKS yesterday. Brief notes I jotted down - adj EPS 24.6p, PER 11.7x. Lots of adjustments totalling £124m, so there are still problems being worked through. Dispute with Ocado. Modest divis (should rise in future though), as focus has been on debt reduction, which has been substantial - borrowings (excl leases) down £401m to a net cash position of £46m. Also announced tender offer yesterday, to buy back its bonds, which should save interest charges & de-risk the balance sheet. Pension schemes are huge, but look fine, with both accounting and actuarial surpluses, so no deficit cash payments required. Balance sheet is strong, with £2.6bn NTAV. Headwind of wage increases, but other inflation offset by energy cost savings.
Paul’s view - I think these numbers fully justify the big bull run in MKS shares. If it can keep up this out-performance, then there could be further upside. Isn’t it great to see this national institution coming back from years of under-performance? The stores just somehow feel special again when I visit them. [no further section below]
Hargreaves Lansdown (LON:HL.) - up 5% yesterday to 979p (£4.6 billion) - Offer Rejection - Graham holds HL - GREEN
It is revealed that private equity groups, and Abu Dhabi, are interested in HL and made a proposal last month at 985p. I agree with the Board that this undervalues the company; I think HL is a uniquely powerful financial institution and a high quality share that should not be sold at a meagre 14-15x earnings.
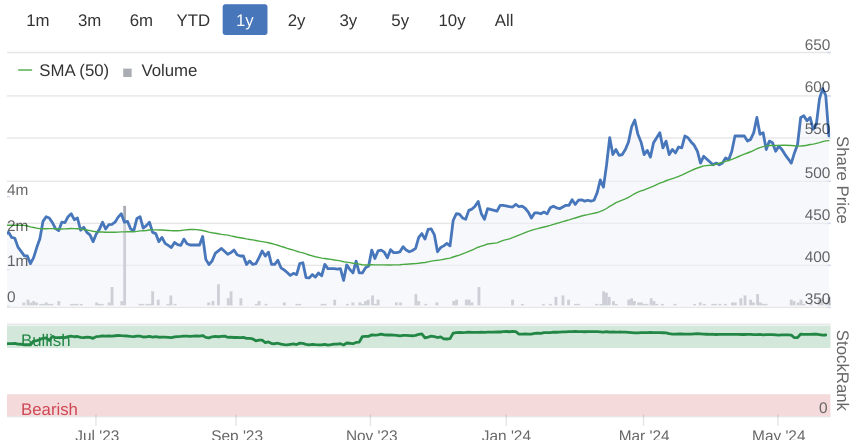
Bloomsbury Publishing (LON:BMY) - down 7% to 555p (£456m) - Audited Results FY 2/2024 - Paul - GREEN
Gives back a bit of the recent gains, with a "slightly ahead" update to FY 2/2025 (low) forecasts arguably not being enough to continue the long bull run for now. There's a gap in the schedule of Sarah J Maas books, meaning FY 2/2025 skips any new released from this highly successful author. Balance sheet & cashflow look good. Overall I'm happy to remain at GREEN.
AJ Bell (LON:AJB) - up 11% to 401.5p (£1.66 billion) - Interim Results - Graham - GREEN
It’s a strong interim results statement from AJ Bell with inflows converting to excellent revenue growth and even better profit growth. The full-year outlook seems to have improved and the business is firing on all cylinders with increasing brand awareness, an automated pension product and very competitive charges.
Bloomsbury Publishing (LON:BMY)
Down 7% to 555p (£456m) - Audited Results FY 2/2024 - Paul - GREEN
Bloomsbury Publishing Plc (LSE: BMY), the leading independent publisher, today announces audited results for the year ended 29 February 2024.
Chairman to retire at July’s AGM. Being replaced with an experienced existing NED. Doesn’t seem any cause for concern to me.
Great headlines initially got me excited, which faded when digging into the detail -
Success of portfolio of portfolios strategy leads to exceptional sales up 30% and profits up 57% with full year dividend up 25%
Revenue and profit for 2024/25 upgraded
FY 2/2024 Results - are indeed superb, as expected, with 46.6p adj EPS (PER 11.9x at 555p/share) being a whisker ahead of the 46.4p broker consensus shown on the StockReport. Note that this forecast was upped 4 times since first being introduced in late 2022 at 25.1p, so this has been a terrific year, no doubt about that. We already knew this though, so it’s already in the share price -

Note above how the FY 2/2025 forecasts are now a long way below the FY 2/2024 forecast (and now actual), so the focus needs to turn to whether the forecasts are being set too low and we can look forward to BMY once again beating them, or whether there’s a more fundamental reason for earnings to fall - was FY 2/2024 a bit of a one-off bumper year, thanks to the success of Sarah J Maas’s fantasy books?
If BMY only hits 32p forecast for FY 2/2025, then the PER would be 17.3x, difficult to justify when earnings are falling.
Recent success has been principally driven by the increasing demand for fantasy fiction. Sarah J. Maas is a publishing phenomenon and we are very fortunate to have signed her up with her first book 14 years ago. Her books have captivated a huge audience…
Outlook - there’s a gap in the Maas schedule - good or bad? Some might see this as just a dip in earnings, with a rebound to follow in FY 2/2026 perhaps? -
Trading for 2024/25 is expected to be slightly ahead of current consensus expectation1. Expectations for 2024/25 reflect the exceptional performance in 2023/24, and that we are not expecting to publish a new Sarah J. Maas title in the year ending 28 February 2025.
1. The Board considers consensus market expectation (before this publication) for the year ending 28 February 2025 to be revenue of £283.6m and profit before taxation and highlighted items of £35.4m.
Helpful footnote, thank you. “Slightly ahead” might perhaps point to £36m adj PBT. We don’t have any broker notes available, a recurring bugbear with this share. My figures suggest c.33p is roughly the current guidance for FY 2/2025, a PER of 16.8x - probably enough for the time being. Unless of course you think they’re under-forecasting, and are likely to beat this?
A bad mark for saying “upgraded” in the headline, but reducing this to “slightly ahead” in the detail further down. That strikes me as somewhat misleading, never a good look.
Dividends - interim + final = 14.69p, up 25%. Yield = only 2.6%. It has capacity to pay much larger divis, I reckon, so there could be upside on this.
Balance sheet - very robust, as usual. NAV £202m, less intangible assets of £80m, gives NTAV of £122m. Receivables look very high at £165m, but that reflects increased revenues, and £35m of that is royalty advances to authors, which is usual here. Cash is a very healthy £66m, and no interest-bearing debt. All looks very healthy to me, no concerns.
Cashflow statement - seems OK to me. There are large working capital movements, but they broadly net off, so not a concern. Note that the increase in cash pile of £16m means that the dividends paid of £11.3m could have been more than doubled, and still left an increased cash pile. So my point above that BMY could be much more generous with the divis is supported by the cashflow statement. It has dividend paying capacity of >5% yield.
Queries - it capitalised £5.1m into intangibles, so more detail on this would be useful. Purchasing shares for the employee benefit trust cost £2.8m, which in the context of £37.6m post-tax cash inflow is fairly significant.
Overall I don’t see any problems here, it's a nicely cash generative business.
Paul’s opinion - BMY is a long-standing favourite of ours here at the SCVRs. Shares have had a superb run, and I think it makes sense to see it pause for breath, with some people obviously profit-taking this morning. Where does it go from here? I’d say long-term it should be fine, as the business model seems very robust. The big hits from JK Rowling and now Sarah J Maas seem to generate very long-term returns for BMY, with people buying the back catalogues even if there aren’t any new titles. Hence I think BMY is a very good candidate to include in a buy & hold forever type of portfolio.
Shorter term stuff won’t matter to long-term holders. However, the “slightly ahead” (on low forecasts) today wasn’t good enough to propel it to new highs, so holders might have to be patient, and hope for the (now customary) ahead of expectations updates. With new Sarah J Maas titles expected for FY 2/2026, at some point investors might start to get excited again, and it might require some patience until then, who knows?
Could BMY become a bid target? It doesn’t have any blocking stakes from founders, so it’s entirely possible. The financial performance, growth, and sticky nature of the big franchises like Rowling & Maas must have been noticed by the American private equity people.
Overall I think the fundamentals still look strong, so it has to be another GREEN from me.
Cohort (LON:CHRT)
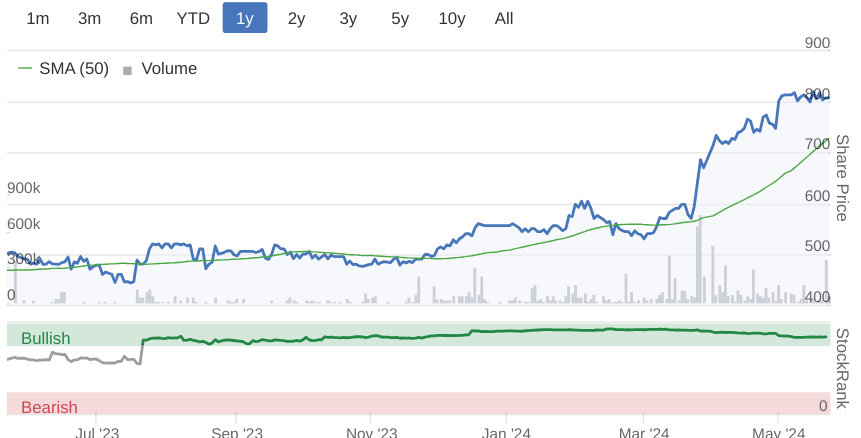
Unch 807p (£336m) - FY 4/2024 Trading Update - Paul - GREEN
Cohort, the independent technology Group, today provides an unaudited trading update for its financial year ended 30 April 2024.
Performance slightly ahead of expectations
Record closing order book
Previously, I was GREEN on CHRT shares, but at much lower valuations compared to its 807p share price now, so the question is whether to moderate to amber or amber/green, given the substantial rise in valuation?
There’s not really anything new in today’s update, confirming what we’d previously been told that the order book has greatly increased to over £0.5bn. This bit in the commentary has caught my eye though, and seems to suggest earnings upgrades might be likely -
The Royal Navy's recent order for the Ancilia Trainable Decoy Launcher System, was a significant milestone for the Group. It represents a strong vote of confidence in the product; a fully UK designed and built solution for which we see encouraging export prospects. As stated in our announcement of 26 March 2024, this together with other recent order wins, is expected to materially enhance the Group's earnings.
We have an encouraging pipeline of order opportunities for the current year, providing a positive outlook for organic growth in the years ahead.
Overall, our expectations for the coming financial year remain unchanged.
Equity Development today says it sees 36.2p adj EPS for FY 4/2024, and 40.4p for FY 4/2025. To my mind, that modest forecast growth sounds quite cautious compared with management commentary, and the very large increase in order book this year.
It’s also got superb visibility for FY 4/2025 -
The year end order book underpins c.£180m (90%) of the current consensus market revenue expectations for 2024/25, an improvement on the year just finished.
Paul’s opinion - it’s encouraging to see this share re-rate to a more appropriate valuation. It’s tempting to bank profits once an irrationally low valuation turns into a fair valuation. So individual investors have to make up your own minds about what to do. Sticking my neck out a bit here, I reckon this is looking like it could beat forecasts, and please the market with more contract win announcements. The group is clearly on a roll, and my hunch is to stay positive on it, despite the big rise in valuation recently, so I’m going with GREEN again. More cautious investors might want to top-slice - your money, your decision!
Graham’s Section:
Hargreaves Lansdown (LON:HL.)
Up 5% yesterday to 979p (£4.6 billion) - Offer Rejection - Graham - GREEN
At the time of writing, Graham holds a long position in HL.
It has been a busy week for takeover offers with the latest one relating to Hargreaves Lansdown.
This one looks like a poorly kept secret:
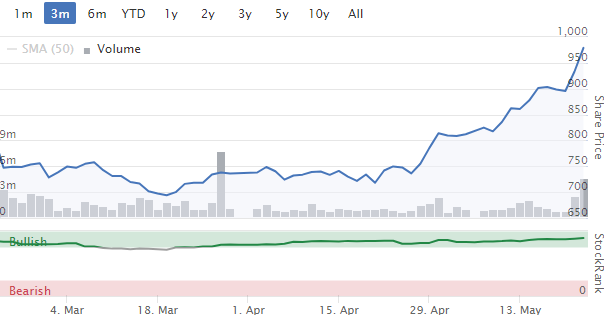
Last night, a private equity consortium consisting of funds managed by CVC, Nordic Capital and the Abu Dhabi Investment Authority confirmed that it was a possible buyer of HL.
They made a proposal at 985p per share on 26th April, which the board of HL rejected.
With last night’s disclosure, the clock has started ticking under the rules of the Takeover Code. The consortium has until 19th June to make up its mind on an improved offer.
This morning, the HL Board responds and discloses that the consortium made two proposals, the most recent one being at 985p. Here is the view from HL:
The Board confirms that it unanimously rejected the Proposal on the basis it substantially undervalues Hargreaves Lansdown and its future prospects. The Board is focused on executing its strategy and looks forward to updating the market at the full year results on 9th August 2024. In the meantime, shareholders are advised to take no action.
Graham’s view
I own HL because I think it’s too cheap, so my view is pretty clear! I’ve been bullish on it since around 800p. And I’m not surprised at all that private equity groups would like to buy it for less than 1000p.
In Feb 2024, I reviewed the company’s interim results. As I said then, I do have a few quibbles with the company’s presentation of its numbers. It passes off huge “strategic investment costs” as non-underlying items. Similarly, the costs associated with past abandoned projects are described as non-underlying.
But it’s probably still too early to pass much comment on the work of HL’s relatively new CEO and CSO (Chief Strategy Officer).
I’m invested in this share because I think the company and its brand are bigger than any individual: it’s an institution with tremendous market share (40%) that finds it very easy to grow and to churn out extremely high returns. Although the ease with which it generates profits has, it seems, been accompanied by some degree of excessive spending.
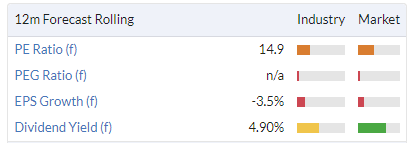
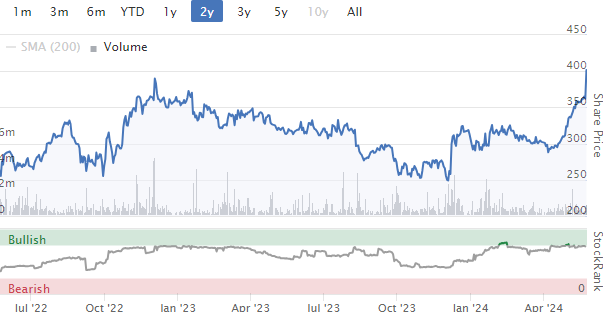
Picking up a unique company like this at an earnings multiple of 14-15x would, in my view, be a bargain for private equity. So I’m glad that the Board rejected the offer.
The way I see things, the bid would need to be about 50% higher to be worth considering. I don’t think that HL shareholders should even consider giving it away for anything less than 20x earnings.
While the cheap UK market has been a great place to pick up bargains, the risk is that we end up losing too many high-quality businesses to opportunistic bids like this.
AJ Bell (LON:AJB)
Up 11% to 401.5p (£1.66 billion) - Interim Results - Graham - GREEN
AJ Bell plc ('AJ Bell' or the 'Company'), one of the UK's largest investment platforms, today announces its interim results for the six-month period ended 31 March 2024.
This is also not a small-cap, but it’s thematic to give it a look on the same day we have bid interest in Hargreaves Lansdown.
Here are the key bullet points for the six-month period:
Revenue up 27% to £131m
PBT up 47% to £61m
27,000 new customers, total 503,000
Assets under administration up 13% to £80.3 billion
It’s a very pleasing progression with 13% growth in AuA translating to even faster revenue growth, which in turn translates to even faster PBT growth.
The growth in AuA was mostly driven by market movements (£6.5 billion) rather than by net inflows (£2.9 billion).
There is a slight drop-off in customer retention, falling to 94.5% from 95.5%.
The CEO’s comments contain many important points, here are some snippets:
"Our continued strong business performance led us to review our approach to capital allocation and the Board has recently approved a new capital allocation framework which reaffirms our commitment to a progressive annual ordinary dividend.
AJ Bell is no longer going to pay out 65% of profits to shareholders; instead it is going to try to increase the dividend progressively every year.
I do prefer the fixed percentage payout model, as it helps companies avoid getting stuck with a payout ratio that’s too high when profits come under pressure.
However, for companies that are very confident in their outlook, such as AJ Bell, they often prefer to go with the progressive dividend model.
Such companies are typically in a mature stage of life, not enjoying the rapid profit growth of AJ Bell!
Continuing:
We are in the second year of our multi-channel brand campaign and are now reaping some of the benefits of this investment, with our brand awareness showing a meaningful improvement over the course of the last year…
I’d be curious to know what readers think: do you feel that the AJ Bell brand is catching up with Hargreaves Lansdown? HL has £140 billion+ of AuA, vs £80 billion at AJ Bell, and I still think that the HL brand is significantly more powerful. But AJ Bell’s TV adverts are trying to address this. According to the company, they are working!
Continuing:
We are delighted to have launched our new Ready-made pension to help people easily consolidate their existing pensions with AJ Bell and invest them automatically via our low-cost, in-house investment solutions.
This is a fantastic initiative, taking on highly-valued fintech start-ups with a product that benefits from AJ Bell’s economies of scale.
And as for the full-year outlook:
"The recent pricing changes were implemented later than originally planned due to regulatory uncertainty around retention of interest margin at the tail end of 2023. Whilst the changes are now live, the delay resulted in particularly strong financial performance in the first half as revenue margins and PBT margin were elevated. These metrics will moderate in the second half as customers begin to benefit from lower overall charges, however our updated full-year guidance reflects our expectation that both revenue and PBT will be higher than we had anticipated back in December.
New guidance from the CEO suggests that revenue from interest on cash (this is currently the biggest source of revenue) will be at the top end of guidance, while share trading will be at the lower end “given continued muted dealing volumes”. Client cash will continue to decline as customers put their funds to work or withdraw it from the platform.
Graham’s view
As noted by Roland recently, AJ Bell offers excellent value compared to Hargreaves Lansdown, e.g. with a new £5 dealing charge (you must trade 20 times in a month to get the £5.95 charge from Hargreaves, otherwise the charge is £11.95). If you trade 10 times in a month with AJ Bell, the charge falls to £3.50!
And AuA growth is very impressive at AJ Bell, e.g. HL generated net inflows of £1 billion in the six months to Dec 2023, while AJB has generated net inflows of £2.9 billion in the six months to March 2024.
Given the faster growth and the strong product offering, it’s a consensus opinion (one with which I agree) that AJ Bell deserves to trade at a substantially richer valuation compared with HL.
AJ Bell’s net income forecast for FY Sep 2025 is £79m per the StockReport, but I’ve also seen forecasts as high as £89m. If we applied a 20x multiple to an £89m forecast, that gives us a value of c. £1.8 billion. Current market cap: £1.66 billion. Of course in a takeover situation, all bets would be off.
I’ll give this one the green light as I think it’s another high-quality financial stock that may appeal as an alternative to HL, for investors who prefer the growth story at AJB or who dislike the recent history at HL.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

136 comments
Qinetiq QQ - Paul you asked for any insight on this defense stock. I have been invested for a couple of years now. Bought as a defensive stock that has grown steadily year on year and was likely to perform well given all the geo political fall out! Has been steady state for a while and share price has lagged other defense stocks. They made an american defense company acquisition but that hasn't yet really delivered mainly because funding has been held back until recently and promises of greater things to come. Cash Generative, can't find other suitable acquisitions so has started a share buy back that was well received and despite the us defense element has delivered a good set of results. Order book keeps filling up. I am holding mid term as it should rerate to other defense stock levels. Hope this helps, all IMHO
AJ Bell (LON:AJB)
I posted this on 2 Feb 2024 when the price was around 315p:
"AJ Bell (LON:AJB) seem to have been on my watchlist for ever. But I haven't pulled the trigger on investing in them."
AJB chart looking quite bullish at the moment
I bought on that day but didn't mage to stick with my convictions and sold out way too early. There's a lesson in there somewhere....
Sorry can't help myself.
A wet end to a wet end.
Why can't you help yourself? Pathetic comment, IMHO.
Coral Products (LON:CRU) Joe Grimmond, the Company's Non-Executive Chair has a history of making small window-dressing share purchases but today's RNS that he has bought 4,000 at 11.33 pence (£453.20) seems somewhat pointless. (I hold)
I use AJ Bell, the only problem I have noticed is the web page will lose the scroll bar and lock in the current position, but a refresh of the page solves that.
On May 20th, there was a massive spike in volume traded in YouGov (LON:YOU) with 5% (5.9m shares) of the company changing hands (https://uk.finance.yahoo.com/q...) and price up by 9%. With an election just announced in the UK their polling is going to be widely publicised in media at large raising their profile considerably in the next couple of months.
Current trading and outlook
- While we continue to experience longer sales cycles and a slower-than-expected Q1, our sales momentum has accelerated in Q2 underpinned by clients' continued focus on high-quality, data-driven solutions.
- The Group's sales pipeline remains healthy and, with over 75% of the stand-alone revenue expectation already committed, it provides good visibility as we go into the second half of the financial year.
- While the overall weakness in macro sentiment may impact the speed and level of some client spending, we remain confident in achieving current market expectations for the full year.
- We remain disciplined in our investment approach as we continue to optimise our cost base to ensure we are poised for further margin improvement.
- Our focus on our commercial rigour, supported by the recent appointment of a Chief Commercial Officer, will be central to our operations and in further strengthening the Group's foundations to deliver on our third long-term strategic plan.
Revised medium term targets
Following the completion of the CPS transaction, the Group revises its medium-term guidance to include the contribution from CPS as follows:
- Medium-term revenue of £650 million (previously £500m); and
- Medium-term adjusted operating profit margin of 25% (unchanged).
Peel Hunt forecasts:
2024 - 46p
2025 - 57.9p
2026 - 68p
US elections in November should keep the pot boiling nicely. Plenty of info on the investors' web page - https://corporate.yougov.com/i...
I've grabbed a few.
Yea, obviously some wise and intelligent investing on the 20th May.
And on a completely unrelated topic, the founder of YouGov was Nadhim Zahawi, until very recently the Chairman of the Conservative Party and Minister without Portfolio.
https://en.wikipedia.org/wiki/...
re Hargreaves Lansdown (LON:HL.) and AJ Bell (LON:AJB) I think they are both fantastic platforms... Hargreaves has 1.858m customers with £79,000 .... AJB 503k customers with £160,000..... I don't know what the total addressable mkt is ? about a £1tn excl private banks incl Financial Advisors, Wealth managers and Execution Only platforms.
So Hargreaves has about 15%.... the question I always had, was how many people have £80,000 to invest? c30m households ... St James place estimate about 13m individuals have £50k or more ... so Hargreaves share at their portfolio size looks about 10% ... so more growth can clearly come from retirees ... take their 25% tax free and enter drawdown and /or consolidate defined contribution policies. I think over time AJB has better growth prospects and both are over earning on cash at the moment. I don't think AJB give us the actual number ...as a customer I don't really mind, Im getting 3% plus on cash and my balance is never that high....HL margins are higher and make £200 a customer Vs AJB £170..... more similar than different I would argue. So maybe more long term growth for these platforms as they naturally take share through retirement.
I am a customer of both II and AJB but not HL. I like them both. Their mkt volume grows all the time.... so their ability to add service making DIY investment easier and easier..... think 501k in the US. I observe that Aberdeen acquired II .... and at first I thought a strange move. BUT Aberdeen get all this city research anyway ... and they can kind of feed it into the II platform as editorial ... improving service.... So my Q is are these platform a natural fit for fund management and/or life assurance businesses. Could this be CVC thinking ... because they must have some sort of plan .... to bolster Hargreaves Lansdown (LON:HL.) and return it to the market better.... off the top of my head I wonder if may be Legal & General (LON:LGEN) or Rathbones (LON:RAT) could be good fits, or other businesses actually... Man (LON:EMG) even? since this whole space will surely naturally consolidate into much bigger businesses. Lindsell Train, Peter Hargreaves and Stephen Lansdowne were no doubt unhappy with Hargreaves Lansdown (LON:HL.) performance but unlikely sellers I guess. Now they have the share price up some more does it pave the way for a big deal with Aviva (LON:AV.) or Legal & General (LON:LGEN) ?
Just my rambling thoughts.... no current holdings....
Interesting points in Woodford's latest blog on macroeconomics, which echoes points made here by some of our macro experts too - that Bank of England policy has not curtailed demand, it's actually pumped money into the economy (I think RDHowarth made that exact point a few months ago here).
As I've mentioned before, I think this absurd fantasy that central banks somehow fine tune the economy to "control" inflation needs to be called out, which Woodford does a good job of here -
https://www.woodfordviews.com/...
By the way, I'm not interested in people's judgement on his character or career. If I find interesting commentary, I'll mention it here - which this is.
Regards, Paul.
If you create £400bn you should expect inflation.
Qinetiq QQ. was ( as I understand it) originally formed by ex MoD employees. It is a defence company specialising largely in higher end defence development and testing focussed on AUKUS (Oz, UK & US) but with significant and growing business from the Middle East/EMEA. I own the shares which are beginning (I hope!) to come to life. Roughly 18 months ago QQ made two acquisitions, in respectively the US and Australia, which seem now to have been integrated with their local businesses. There was an excellent presentation this morning which should now or shortly be available on the website. A 'must see' if you have interest. The short term target for f27 (to Mar 27) is sales £2.5bn and a 12% operating margin. This currenty appears a pretty modest aim in my opinion. Last year was (statutory) sales £1.9bn OP £192mn eps 24p. The balance sheet is improving (net debt is down 25% yoy), the dividend has been raised 7% (2% historic yield at the lunchtime price today) and there is a share buyback under way. RoCE has been consistently over 10 but appears to be closer to 15 last year.
Qinetiq (LON:QQ.) is held by Lord John Lee but he’s written very little about his investment rationale
They do great dinners apparently - the MOD that is.
Nice extra earnings on retirement for the Admirals, Colonels, Air Marshalls etc - and fair dues their senior experience and connections can add to the companies growth.
Qinetiq (LON:QQ.) was formerly DERA, part of the MoD. The Q is a play on the Bond character. :-)
Re Paul's comments I'd strongly suspect there would be very few companies allowed to take them over. Perhaps even the DoD wouldn't be keen on a US contractor taking them over, as they tend to be a lot more expensive than UK defence contractors.
Thanks WDW and Paul for your quick summaries. Very useful. I bought Qinetiq (LON:QQ.) back in Jan 2023 and have stubbornly held on since then. I also have them in my version of Paul/Graham's 2024 Top 20, to which I've added an estimated Target Price for each entry (just based on fundamental metrics). My TP (as of 04/12/23) was 368p, so was pleased to see it eventually hit that level recently. Using the currently available metrics gives me a TP of 493p, so if I'm going to trust my own calcs, I've got to hang onto them a while longer yet!
Great updates from Bloomsbury Publishing (LON:BMY) and Cohort (LON:CHRT) , two of the shares I'm holding in my portfolio. Up over 30% on both of them and I reckon both could be candidates for a take over
AJ Bell (LON:AJB) is a pain in the backside with frequent problems loading data . Presently, I cannot trade at all using the platform and I am told it’s an issue they are working at !! As soon as I am able, I shall be working at selling my portfolio with them and switching to a more reliable competitor
AJ Bell (LON:AJB)
Curious, clearly an on going problem for you. I'm been a long term user and very rarely have I had any problems. Both mobile and laptop machines both on android. Hope you get sorted soon.
It’s now working OK on my IPhone but not IPad . Bizarre really and get little response from so called customer support .
AJ Bell
Caper4
having trouble with AJ Bell?
I moved to ii and it is a great platform with some free trading credit every month and occasionally free US trade too.
I have a multi currency account but I am not sure you can have that facility with ISA or SIPP.
Regarding ii, it's against ISA rules to support multicurrency but ii do support it in a SIPP.
For anyone who is complaining about content not being completed to their satisfaction in these reports by Paul and Graham, here's your litmus test:
Did you acknowledge the days when Paul and Graham produced a huge amount of content for that day?
Thought not. I rest my case.
Just ignore him/her/they/them/it! (edited so as not to offend)
Why have you automatically assumed I'm a him...? Typical, maybe ask so as not to offend please.
Chri55, take a few minutes to read over your own comment history, it will only take 5 mins. I actually encourage all readers to have a look at what you have written in your last 20 or so posts and they can make up their own mind as to they type of person you might be.
Ask yourself, are any of your comments kind, thought provoking or interesting? Or are they predominantly personal attacks on the writers for not covering the stocks you hold.
I can only imagine that you are a very unhappy or frustrated person, I hope how you interact with people on here is not a reflection of how you interact with people in real life, as that would be very sad indeed.
Benhazz I am struck by your suitably pious tone But would note Kind comments rarely if ever add value with respect to investment decision making.
Personally would welcome more non consensus views being expressed here
By far the best thing is to ignore these trolls - the one thing they want is for people to react and unfortunately we've got that today with about 30 comments relating to this post. I would suggest everyone just ignore this unpleasant individual in future (ideally Stocko can just filter them).
Eneraqua Technologies (LON:ETP)Full years. Not a small cap favourite in the latest reports admittedly.Not great results! adjusted £6 million loss against an adjusted £10 million pbt last year with main adjustments this year for redundancies.Net cash £1.2 at end of year.
For any interested seems a longer term admittedly operational leveraged play with rather fixed staff costs.If/when building supplies inflation comes down and public bodies stop delaying contracts...... it could bag?The company has confirmed that no public body has cancelled any contracts but a lot of the domestic energy work has been pushed out to FY26.Order book of £101 million of which 88% of it is expected to be delivered during FY25.Expecting a return to profit in H2.But who knows?Nice to be optimisitic.And the new acquisition, Mathewson, which they bought to get an in with NHS work i think if i remember correctly, had got them their first NHS contract.I'm kinda impressed that councils and public bodies trust them enough to give them a fair whack of work compared with current market's value!And i do know how many councils have gone bust lately!!
The current mcap/previous earnings (although adjusted) seems' a bargain!Half wish the shares had tanked.Maybe i shouldn't wish too much for that as no doubt they will before a potential recovery!! ha.I know Paul didn't like how the ceo presented the results and the large receivables i think.But admittedly he did seem stressed at the time, soon after IPOing having a major cyclical downturn in his business.And owns a fair whack of the shares.Anyway it's a punt as usual with me, but longer term.So more risky i guess and obviously needs patience.
Good morning. I thought I would let the 'new-news' get out of the way before I re-posted something I posted late yesterday and which many will have missed for that reason. I hope that doesn't imply I am hogging too much space for a very small company, definitely not in the realms of the Hargreaves Lansdown (LON:HL.) of this world!
ridavies Joined 2014 762 posts Yesterday 5:44 pm
Hello commentators on Warpaint London (LON:W7L) and the US listing. I cannot comment on the success or otherwise of other UK companies doing the same though Indivior (LON:INDV) I believe did add a listing in the US market in 2021 if my memory serves me correctly. It stays with because I remember reading the RNS at 7.30 on the fateful morning of the announcement, and I almost bought at the mid 880s....but didn't. It moved pretty quickly up to the2000 mark. That hurt...hence the memory.
Of course, the difference in product offering and scale between the two companies is stark. Indivior (LON:INDV) is a major player in the fight against the spread of the drug ketamin (again from memory) and it has also had some legal issues in the meantime which have hit profits, and it has moved its primary listing to the US recently..........but back to Warpaint London (LON:W7L) and what the future may hold.
I listened intently to the CEO of the company at his recent presentation to a Mello Monday evening recently. I had previously examined the company's performance in detail and especially following the major sale by two directors of a large number of shares at a discount - SP down to 450. Why if the demand was so high, was the sale at a discount - they increased the volume sold because the brokers said demand exceeded supply and persuaded Sam and co to up the volume. (I should add that they still remain major shareholders and I added to my holding at the lower SP which ensued)......but I digress a little.
The final figures for the year showed that the major share of sales and sales growth was into the EU which was a surprise, a pleasant surprise, given the deep distribution in the UK. It had passed me by. However, in answer to the question as to where the company's future focus will be, it was very clearly - in the US. He even had a chart which showed the potential and similarities - market 10 x the size vs UK, but also similar characteristics in terms of consumer attitudes to value etc. In other words, do in the US what we have done in the UK and the sky is the limit was my interpretation.
Three other things that struck me from this and previous 'meetings' with the CEO and his team.
In the US, the company acquired the distributor some little time ago. As a small player, at the bargain end of a very fragmented market, owning your distributor must be worth its weight in gold. Gives .your products pride of place in any discussions with trade buyers instead of a maybe mention.
Additionally, some time ago they really took a knife to the items in the ranges, I guess what marketeers call the 80:20 principle. It has clearly worked, increasing focus on what sells, and reducing overhead costs.
Finally, the message from last week's Mello Monday was that the US was the No 1 target, and this was before the announcement today about additional listing in the US. No mention was made of this at that presentation. I don't know what the additional costs of this listing will be - others may, and it would be good to know. However, if this gives more power to the distributor's arm, then all well and good.
I look forward to any comments from followers and fellow holders /admirers. If the company succeeds in the US as in the UK and EU, then the SP could go forward in leaps and bounds from here.......and then there is Asia. New listings have been achieved recently in the Philippines, and in answer to my question about potential in Japan and South Korea, the CEO said they already have a distributor in Japan. Exciting times!
The only thing that concerns me a little as someone who has spent his whole career in FMCG companies with brand leaders and significant reputational moats supporting significant price premia, Warpaint London (LON:W7L) is at the other end of the spectrum. Another chart at the presentation showed the price comparisons versus premium brands of I forget what he called the items - I would call them special occasion items e.g. for the Xmas trade. For the same quality said Sam - and the products were clearly very good look-alikes - the price 'discount' for the Warpaint p;product vs the premium brand ranged from something like 60% to 80%!! The CEO said this always impressed the potential trade buyers. Given my years of experience, this level of discount says this product can't be very good in quality terms........but what do I know about the cosmetics market and the target audience? Sam and his team do, the SP trend and key performance figures are living proof, and this is good enough for me.
Warpaint London (LON:W7L) I heard them at Mello yesterday, they were great. I'm up 140% on my first tranche and the US does seem ripe. I have added on dips. But according to morningstar, as shown on the ii platform, they are at an 18% premium to fair value.
Warpaint London (LON:W7L) Competitor elf Beauty (NYQ:ELF) up 20% at the moment on results announced of sales up 71% y-o-y and eps of $0.53 vs analyst est. of $0.32. Both companies took a share price hit in April on the announcement of Ulta Beauty (NSQ:ULTA) of poor first quarter demand. Bulls climb a wall of worry!
Hi ridavies "Given my years of experience, this level of discount says this product can't be very good in quality terms" This is the key point of Warpaint. The industry is based on a few large businesses which use advertising and marketing to place their brand. Warpaint don't o this and this cuts out a very expensive element of the cost each year allowing Warpaint to discount. Their products I understand from the ladies I know that use them are every bit as good.
The cheaper ‘copies’ are known as ‘dupes’ (for duplicate) and an established model in the cosmetics field.
My daughter is typical of many her age, not an investor etc. but could tell me all about dupes, how successful some brands are that sell these items and her joy at finding dupes that are “better than the expensive version it copies”.
I’m not an holder of Warpaint London (LON:W7L) , having felt like I’ve missed the boat, but I’m wondering if there is still a decent upside in this.
Re Warpaint London (LON:W7L), thanks for all the comments today - and the 30 ticks today and 17 yesterday. Must be saying something right?
Really enjoyed today's SCVR so far. Super interesting and insightful stuff, with some very exciting companies and updates. Thank you Paul and Graham.
How kind, thanks Thomas :-)
Just had a scan of National Grid (LON:NG.) who today announce a rights issue to fund a 2x Capex programme for the next 5 years. 50% will go into the UK and mainly electricity transmission network. The RAB (Regulatory Asset Base) is £30bn and if Im reading it right they expect this to grow 10% per year ....so after 5 years this will be £48bn but at some cost ... £30bn. My main interest is where does all this money flow ... it creates 60,000 jobs ... and mainly digging up roads and laying pipe, improving overhead cabling too ... Morgan Sindall Infrastructure are a listed partner as are former listed vehicle WSP. I think equipment hire, engineering consultancy, construction management et al all stand to benefit. It's interesting timing just after the election announcement...There are a host of companies that may benefit either directly or indirectly from this ... off the top of my head I came up with 15.... Hill & Smith (LON:HILS), Ashtead (LON:AHT) Ferguson (NYQ:FERG) Galliford Try Holdings (LON:GFRD) Balfour Beatty (LON:BBY) John Wood (LON:WG.) Morgan Sindall (LON:MGNS) Renew Holdings (LON:RNWH) Costain (LON:COST) Speedy Hire (LON:SDY) Breedon (LON:BREE) Kier (LON:KIE) VP (LON:VP.) James Fisher And Sons (LON:FSJ) Severfield (LON:SFR.
More importantly Id expect more of the same in EU and US and therefore this to be a theme that ages well over the next 5 years.
Hi RDHOWARTH,
There's a huge amount going on in the UK and European energy infrastructure industry in the next 20 years, let alone 5 years. The biggest national grid (the physical infrastructure rather than the company) upgrade since the 60s in the UK, and equivalent works in Germany, the Netherlands , Belgium etc.. Then there are the interconnecters between countries (and multi-purpose interconnectors connecting multiple countries, windfarms), the energy islands (think artificial islands in the middle of the North Sea, Baltic Sea etc.), the hydrogen networks, new nuclear plants, that will be a huge part of the construction industry over the next 20 / 30 years.
A lot of the big obvious manufacturing, construction, or consultancy beneficiaries are privately owned or listed in other countries (Prysmian SpA (BIT:PRY) NKT A/S (CPH:NKT) Nexans SA (EPA:NEX) Sumitomo Electric Industries (TYO:5802) Siemens Energy AG (ETR:ENR) Hitachi (TYO:6501)). The offshore contractors who own all the specialist vessels (aside from the first three above) are generally privately owned, and business is booming - Jan De Nul, Van Oord, Deme etc.).
I think the UK listed beneficiaries is slightly narrower than who you listed, maybe Ashtead Technology Holdings (LON:AT.) (which might be who you meant), John Wood (LON:WG.) Balfour Beatty (LON:BBY) (although BB recently did not make the design / civil contractor framework for National Grid which was a big surprise to me at least), Morgan Sindall (LON:MGNS) Renew Holdings (LON:RNWH) Costain (LON:COST) ITM Power (LON:ITM) Ceres Power Holdings (LON:CWR). Petrofac (LON:PFC) is getting some great contracts, despite it's seriously precarious financial situation, which also surprises me. Maybe it could get itself into a more stable situation, get unsuspended, and become a good turnaround story. A space to be watched.
Some of the others you listed just aren't (currently) in the picture, and/or are more in commercial property / roads / water etc.. This could obviously change as companies dash for cash. Steel will always be needed, for example, so a general steel supplier might do well, but guessing which suppliers for good relations with the right clients / contractors is tricky.
We're in a period of big (and hopefully positive) change, so this is only the picture at what is (nearly) the outset of this period.
Cheers
Chris
v interesting thank you...
You could also add Gulf Marine Services (LON:GMS) - I hold
Gulf Marine Services PLC ("GMS" or the "Company"), a leading provider of advanced self‐propelled, self‐elevating support vessels serving the offshore oil, gas and renewables industries
Given the current high levels of utilisation secured, combined with higher day rates, the Group expects the financial performance to continue to improve.
Hi PoT,
I was about to say no, and make a smarmy comment about the 'Gulf' in their name being the clue, but from their annual results:
So yes, they could be a beneficiary of all the work in Europe, on support services rather than the big stuff. Picks and shovels to the picks and shovels.
Cheers
Chris
Leaving aside the race to the bottom with the Netzero religion, there is going to be opportunities for investors to tune into. The transition to a net-zero energy system will require a significant workforce. "National Grid's Net Zero Energy Workforce Report" highlights the need to recruit 400,000 jobs by 2050 to support the UK's energy sector. This includes roles in the operation, generation, transmission, distribution, and retail of energy and in the supply chain related to building and upgrading infrastructure. Increasing the electric national grid capacity will likely be a priority to support the forced transition from ICE to EVs, the so-called green utopia. It is anything but. Political Utopia v Bleak Reality
Bloomsbury Publishing (LON:BMY) results are interesting. With all the Maas/Potter spotlights it's easy to miss the growth in digital. But can anyone explain the strategy to get from
"Bloomsbury Digital Resources increased sales to £27m and remains on course to achieve its target of c.£37m turnover in 2027/28" ...
..with a (current) 2% growth rate? Am I missing something? Also Academic seems down YOY.... Surely a book company should be able to craft an interesting narrative about why? Otherwise I'm a big fan of BMY holding intermittently. Great SCVR summary!
Bloomsbury Publishing (LON:BMY)
Some very good questions. I don't have the answers but you may like to ask them at the IMC presentation on Wednesday 5 June at 12 noon. Register here.
Bloomsbury Publishing (LON:BMY)
"Bloomsbury Digital Resources... remains on course to achieve its target of c.£37m turnover in 2027/28...with a (current) 2% growth rate? Am I missing something?"
Spot on. I asked myself the same question this morning, especially as the company said that they'd get to £37m organically and I'm not quite sure how they would do that given the BDR slowdown evidenced over the last 18 months.
3 counterpoints to the above:
(For context it was 37% in 2021-22 and 45% last year, so there's a continued positive trend.)
As a result the more sought after Subscription revenues increased by +13% YOY, in contrast to the Non-Subscription revenues, which declined -8%.
I personally think that the above is a good thing in the long term - I want that stickier revenue.
There's more detail on the size of the market in the presentation published today.
---
I'm unsurprised by the share price reaction today and think the company is fairly valued.
However I still see positives for FY25.
For further context, she had 1 to 3 books in the list for most of last year.
If they're not returning some of that enormous cash balance, then my hope is that they are looking to buy something. For me the long term upside here comes from acquisitions.
Hopefully there'll be more insight provided on the call in 2 weeks.
Good digital insights and extra clarifications. Thanks! Also Harry Potter being (still) no.1 seems incredible. Magical.
I'm unable to log in to A J Bell today from my iPhone app or using Firefox on my iMac, though Safari on my iMac logs in OK. Is anyone else having this problem?
No problems here. Just tried from my PC with Chrome.
I’ve just used the app. No apparent issues.
Mines fine.
Yes and me. See my post above. Frequent problems with them
Hi Paul, missing you at Mello.
Zane stand in the exhibition room and having some interest and selling a few raffle tickets. Missing you as well Graham. Attendance here is good and it is going well. Strangely Leon was presenting Hargreaves Lansdown in the BASH as the news came through of the bid and rejection. Created a bit of hillarity.
Hi Charles!
Well done for flying the ZANE flag at Mello, and sorry I couldn't join you :-)
Best wishes, Paul.
Hi Paul, so sorry to hear you were unwell and unable to be at Mello. Wishing you a speedy recovery and I think it’s amazing that you have still kept up with all your output here whilst under the weather. I for one very much appreciate it.
I also visited the Zane stand to make a donation for a great cause that I know is close to your heart.
How kind, thanks shopping365, and sorry I can't share a glass of red wine again with you (not the same glass of course) this year! On the mend (nothing serious) here in Gozo, and listening in to a webinar from Intercede (LON:IGP) which is fascinating actually. (I hold).
Best wishes, Paul.
Nexxen International (LON:NEXN)
Just wanted to thank Davidjhill, Yiannos and BnB for your words of wisdom re Nexxen, all noted and appreciated. As compelling as the numbers are I decided not to buy, given the question marks over integrity of management and did instead spread this little pool of cash into existing holdings Pressure Technologies (LON:PRES) Journeo (LON:JNEO) MPAC (LON:MPAC) .
Better the devil you know and all that.
Have been adding Pressure Technologies (LON:PRES) last 2-3 weeks as well.
If they manage to sell the division for 1x earnings this should double.
I ll appreciate any news or feedback
All the best
Pressure Technologies (LON:PRES) That's interesting and pleasing to hear because you've been on excellent form of late with your calls on Mcbride & Ig Design.
I went to the Pres AGM this year and my takeaway was the new CFO is really on the ball (I think he may have been a Rockwood suggestion) and the Board were quite relaxed, dare I say even confident about the prospects for the Chesterfield business but they didn't really give anything away, just my read on the tone of the meeting.
Re: the sale of PMC I think in a past Staveley/Paul Hill interview he has quoted a spread of between £3m -£7m? Who knows, but we will find out sometime in the quarter ending June.
Apparently Staveley is presenting at Mello today and has been referring to PRES as Chesterfield Special Cylinders, shades of Crestchic? make of that what you will....
A small mention of Pressure Technologies (LON:PRES) from Staveley in this podcast recently:
https://www.trustintelligence....
Last review from Paul was Amber/Green. Search in discussions to read it
And another good call from Yiannos on Afentra (LON:AET)
Afentra (LON:AET)
Crazy valuation when trading around 30p with the same management that successfully driven a company (same sector) in the past.
Will take my money off the table at 64p+ (as a personal rule when they double in price) and leave the remaining (for at least 2 years).
All the best
Afentra (LON:AET) thanks for discussing this one. I looked into it and it does seem very well priced and most particularly with exponential potential (I hold, now)
Superb update from Sabre(SBRE) insurance. Seems largely ignored by the market but really good growth.
Hi Wolf, good to have you back, you’ve been missed. I enjoyed your thread on technical analysis and would recommend to other subscribers, Wolf is a top performer.
Too many wolfs here Mr B.
Maybe a name change is in order. Mole with a bowl?
lol, just realised my mistake, please don’t be offended Wall Street, it was Small Street who I’ve missed.
Yes please rebrand, mole with a bowl works for me :)
Nah stick with Wolf loving your stage 2 thread, I will say without blowing smoke up a---- even if Paul and Graham chucked it in I would be here for the daily bulletin board so many top table posters hanging out here which is great to see.
Henry Boot (LON:BOOT)
confirmation they are on track this year - expectations £30.7 mill pre tax - stock has £23.4 mill net profit this year with jump to £28.5 mill expected next year. market conditions not briliant but ticking over ok.
at £273 mill market cap thats pe under 10 on next year - bit more this year - very conservative balance sheet historically.
however there is the dreaded h2 weighting - they describe it as heavily weighted
"We have begun the year well, trading in line with market expectations*
Whilst we expect our performance to be heavily weighted to H2 24, as flagged at our results in March, our focus on high quality land and development in prime locations, along with a renewed banking facility, leaves the Group in a position to deliver full year performance as expected."
ref economy - roll on the old tony blair related tune "things can only get better" (brian cos was in that band did ya know?)
We have started to see signs that the economy has turned a corner, with inflation falling and interest rates likely to fall, which has improved sentiment in our three key markets.
with constructiojn taking time to delver risk this year has to be slightly on down side - they are grounded folk here so i have zilch reason to worry here and they are confident ref future even if they arent delivering record levels of profits.
Oh bonus here is that company trading at chunky discount to tangible book value and that book value is normally done on conservative basis ref investments / work in progress.
Final mention is that they have made decent profits every year for last 10 years - clear bottom line profits for last 10 years probably exceed current market cap - so good history of ploddijng deliverance here even if share price has done didly squat.
Henry Boot (LON:BOOT) I think the main value here is in all the housing plots, which are held at cost and therefore probably understated. You therefore have a double discount here - a discount on the published book value, plus another discount to reflect their true value. Not too bothered about year-to-year earnings which will always be a bit lumpy - see this very much as an asset play.
Henry Boot (LON:BOOT)
i have slightly more hope than this simply being an asset play - i think they have plans to up housebuilding volume - hopefully thats slightly less hard work ref regular income strream than their more complicated stuff. Its a tricky one though as over the medium term to increase assets they have to deliver the earnings. Some may say company has been standstill or gone backward ref profits last 10 years - that is probably good point but i am happy to have this little plodder in my portfolio even if it hasnt delivered great returns to date . Its not the end of the world getting the 4% dividend with the hope that some shareprice appreciation m,ay come along later - kinda twin of £NXR here - both seem to be well stuck ref shareprice going nowhere.
With the caveat in advance that no one has a crystal ball and that Labour seem fairly centrist currently... and this isn't a political football, but merely a question as it pertains to future Henry Boot (LON:BOOT) profits....
Is anyone concerned re extra / super normal taxes on the house builders / land developers under the next administrative please?
I don't currently hold , but like the prospects ...
Henry Boot (LON:BOOT)
Is anyone concerned re extra / super normal taxes on the house builders / land developers under the next administrative please?
imho the practice that currently goes on of hoarding land should not be encouraged - i think its in the interests of all major parties to find a solution that ensures land hoarding is penalised - in that regard it could be done in fair and reasonable manner. In summary yes i could easily see companies like boot and housebuilders being billed a % of the undeveloped land value affer a period of time - imho i would be massively in favour of that even though it may be bad news ref my investment here. Note this is probably two way street - one shouldnt penalise company trying to delevlop site if all the holdups are coming from the end of the planners/council/government. I would expect change coudl be matyerial one off hit - after that i would expect either sales or purchase prices or both would self adjust so factor in the extra costs - at the end of the day most of these companies simply make normal comercial margins - so at the ouset if there are extra costs that should reduce purchase price or increase sales price - hopefully faster turnonver of works overall would be more of a plus point than the negative of these added costs - boot could be partly shafted here at one of level i must admit. i would actually guess that having fixed % tax each year might even be less overall costs if changes do there job and change 5 year rpocess into 3.5 year speeded up process - in that regard i have zero faith in ability of councile planners and tehn powers taht be to get that job done - imho next people who try cant do much worse than current lot who have allowed theer to be shortfall in basic housing for your average people in many parrts of the country - note i understand the solution isnt easy.
I would be interested in Paul or Graham's take on Braemar (LON:BMS) this morning. Shares superficially look very cheap on these numbers, with a positive outlook to boot. However, I suspect that the weak cash flow and level of exceptionals is putting investors off.
Ouch! That's a bit below the belt isn't it CHRI55? Do you not realise the extraordinary efforts Paul & Graham go to already?
£CHRT FY TU: Order intake up 77%; closing order book of £518m vs FY sales of c £188m (Eq Devs number), and net cash ahead of expectations. A well managed business in a great sector, but is it all in the price - 20x ED forecast for 4/25?
Cohort (LON:CHRT)
Amortization of acquired intangibles is quite high for Cohort. I tend to write off all of this. Unusually, I find that EBITDA minus tax (and maintenance capex, when I can get a meaningful number for this) is a better way to value this company. My back-of-an-envelope estimates for FY24 minus acquired intangibles (admittedly based on averages/brokers’ current estimates/wild guesses) bring down the PE to c.17. In normal times for UK-based defence companies, a PE of 14 or 15 is fairly standard. Under current circumstances, and in consideration of Cohort’s long-term growth rates, the PE looks reasonable to me.
I hold.
Gusbourne (LON:GUS) FY23 overview by the new CEO, Jonathan White and CFO, Katherine Berry video & podcast. If you're near Ashford, Kent, I highly recommend going here for a wine tour, it is absolutely beautiful. Full Year 2023 shows strong net revenue growth, up 13% to £7.1m, gross profit up 30% at £4.8m and Adjusted EBITDA loss narrowed to £0.7m, a 41% reduction from the prior period. Outlook in line with expectations.
I see this line in the outlook statement for Gusbourne (LON:GUS) as potentially warning for softer growth / profit warning later this year. As key sparkling wine consumption are the summer months, as well as Christmas.
"We expect to continue seeing good momentum in our D2C, Corporate, Global Travel Retail and International channels, while trade sales in the UK are likely to remain cautious in the short-term."
Trade sales were just under 50% of total sales volume for the year.
For a share still negative profit and trading at 5x revenue, the market cap is supported mainly through future rosy growth assumptions.
I do think there are storm clouds on the horizon this year and next year for the English sparkling wine sector. For two reasons:
So for now, I am firmly keeping Gusbourne as well as Chapel Down (LON:CDGP) on my watchlist. I think structurally they are interesting plays over the next 5-10 years.
Boon-I hold both having bought Chapel Down (LON:CDGP) before the AIM listing to get the 30% discount available to shareholders. The shares have performed OK. I have a tiny holding in Gusbourne (LON:GUS) just for interest. It is entirely possible we may see some corporate activity in the sector- maybe not GUS as Lord Ashcroft has a 66% stake. Having followed the English ( and to a lesser degree Wales) wine sector on and off for a few years it does feel like some major changes are taking place amongst consumers both in the UK and abroad. The untaxed dividend from CDGP ( i.e the 30% discount) is a real benefit- if you buy champagne/ english sparkling wines anyway. In my opinion CDGP vintage sparkling wine is up there with some much pricey wines- both English and many French.
I too concur that the quality is getting good with English sparkling wines - especially Chapel Down (LON:CDGP) . That was what attracted me, in the long term, for my initial buy in 2022. I had sold out though (admittedly too early at 36-38p) in 2023.
However, the general consumer perception of English sparkling wine vs more established types (champagne, prosecco, etc) will take years for the industry to build that equity, home and abroad. For a share to buy and hold till 2030 - absolutely should see some good capital appreciation. Will it have a wobble in 2025-2027? Potentially, due to the tsunami glut of supply trying to come on the market... or will the major players all coordinate and hold back inventory?
Cohort (LON:CHRT) - Trading update: performance ahead of expectations (link to research: https://www.equitydevelopment....)
In an Update for the year to 30 April 2024 Cohort reports overall performance slightly ahead of market expectations. We note that the Group reports very strong order intake of c.£387m (compared to £218m in FY23) resulting in a closing order book which stood at c.£518m (FY23: £329.1m), inclusive of the March SEA Royal Navy £135m Ancilia contract.
The group notes strong H2 performance, with overall growth in the Sensors & Effectors division, notably Chess and SEA, outpacing the Communications & Intelligence division where, as expected, UK MOD orders decreased from the 2022/23 peak, and Portugal continued to experience some contract delays.
Cohort reports good demand from both domestic customers and for exports, noting increased attention to defence spending spurred by conflict in Ukraine and the Middle East, and ongoing tension in the Indo-Pacific region.
The order book now covers c.£180m, i.e. 90%, FY 25 revenue market expectations (FY24 was 84% covered at £145m). We see the momentum established in FY24 continuing into FY25.
At this stage we maintain our outlook to FY25 and a Fair Value of 725p / share.
I see that Hargreaves Lansdown (LON:HL.) has received a bid at 985p that has been rejected. It's a company that's been on my radar as a possible buy, although I never pulled the trigger, alas. It is a company that Nick Train holds, I believe. So it's quite a good company, with returns on capital of 60%. Nice!
The forward PE is around 15 based on a current price of 979p. Personally, I think the board are right to reject the proposal. If I were a shareholder, I would not be happy with the offer.
Asset managers are having a rum time of it lately. For example, Jupiter Fund Management (LON:JUP) is on a P/FCF of 5.4, which is exceptionally low. Likewise for its EV/EBITDA, which is 1.7, You really have to think prospects are dire to warrant that kind of rating.
I really don't like the whole takeover developments in the market of late. Some really good companies have disappeared off the market. It's a crying shame. If you're the kind of patient investor that likes to hold quality companies and watch them grow, takeover bids are a disaster; even if the valuation is slightly rich, which in HL's case it is not.
Bit of read across from the Hargreaves Lansdown (LON:HL.) bid to St James's Place (LON:STJ) & Abrdn (LON:ABDN) on the open this morning too. I wonder if the shorts will be running for cover? (6.5% ABDN, 2.27% SJP).
Completely echo the sentiments above re. Hargreaves Lansdown (LON:HL.) . What an outrageously opportunistic bid. Should it succeed you can see PE taking a scythe to the arguably bloated cost base and refashioning this into the ‘cash machine’ of old. Still, it does warm the heart to see the Shorts getting singed here. The geniuses at Marshall Wace were actually adding to their position as recently as the 21st May according to shorttracker. I have to say that shorting unloved but fundamentally quality businesses strikes me as a dangerous sport in the current market
That reminds me of a position I had in Pace Micro many moons back. The share price was reasonable and the fundamentals kept getting better and better. Some hedgie was increasing their shorts and everyone was laughing that they didn't know what they were doing. Anyway, not too long after Pace was taken over by a US company. so the fund must have lost a packet.
HL Maybe the shorts in this case caught wind of the deal and gambled that the deal wouldn't go through. If that's the case then the shares are likely to fall back, so they might actually make money. For everyone else, it's possibly a wake-up call that there's value here.
I grant you it’s possible. But surely even in a failed bid scenario the shares are not retesting the lows here. The cat is out the bag on the value locked up in the business. So barring some exogenous macro catastrophe or Starmer going full on Chavez day 1 this is not falling back all the way. And in the interim the shorts will be having to post more collateral and take the pain in the hope of an unwind. I suspect that most will be covering in a bid situation. We shall see on shorttracker how it plays out. Personally I hope the bid fails. Not to spare the shorts blushes but because as you say this is exactly the sort of business we should not be losing to the buy side. It will be a sorry day if (hopefully not when) the only option for private investors to invest in most parts of the economy will be via the buy side leeches. The only people winning will be the insiders taking 2 and 20. And yet if you look at allocations at pension funds, family offices, etc, this is exactly the direction of travel. And the more it happens the more it becomes a self-fulfilling prophecy. Sorry. Don’t mean to be overly negative here. For long suffering HL shareholders it’s a welcome development. But each takeover is another blow for those of on here (most of us on here!?) who do our own research, are happy to make our own investment decisions and enjoy the ‘game’. At the current rate of de-equitisation there will be no game in 10 years time…
Morning.. Is the small cap report from yesterday going to get finished?
Or do we just plough onto the next one now and probably leave a few off that??
Just saying as its a bit annoying on a paid for service... Have a great day
Oh my !
Hi CHRI55.
Can I suggest maybe seeing if Avon Protection (LON:AVON) have an online portal and maybe seeing if you can get one of their helmets delivered ASAP....................... I think your message maybe interpreted as being a bit harsh as Paul & Graeme slog their guts out in producing material and high quality discussions.
As they always point out, anyone can do their own research, post their comments and get a discussion going - they only have limited time and do what they can.
I pay my sub for the service of the data - the SCVR and a large number of intelligent commentators are a bonus for which we should be grateful. Paul might (if he can be bothered - I know I wouldn't) point out that he (and Graeme) have researched over 500 companies YTD.
Well said I was going to respond similarly, Paul and Grahame put in a lot of effort which is greatly appreciated by the vast majority I’m sure.
Caused by illness
I don't quite understand your point. Paul, Graham, and the rest of the team provide an amazing service. I've learned a lot from their reports. Due to the volume of companies they cover, they can't always get to every company they would like to. Perhaps there was a specific share you wanted their commentary on, but they didn't have the chance to cover it this time. I don't think there are any guarantees.
Why not read it again, it's fairly self explanatory, and I'd be confident in saying there would be many that agree with me..
They get paid, and we pay... Maybe understand how this commercial merry go round works, and that would equally help you to understand my comment.
You’ll find no one agrees with you Chri55, try being polite and maybe even suggest why Paul / our lovely Graham should revisit something from yesterday.
People are entitled to a hoilday/rest?!
They get paid, and we pay... Maybe understand how this commercial merry go round works, and that would equally help you to understand my comment.
CHRI55
Whoops!
Have you read and understood the terms of service that you signed up to? It doesn't sound much like it to me?
As a registered user and a subscriber you have paid for the provision of data and data analysis/screening tools.
You have not paid for 'content' - see definition of content.
Worth also reading the section on Warranties. Here's what it says regarding content
'As we provide Stockopedia Content as a free service to all our users,
we offer no warranties in respect of the preparation and publication of
this content.
That seems very clear to me.
In my personal opinion - I think the data and screening/analysis tools are worth the subscription. But in addition I feel privileged to be a part of the community that has developed and is still developing here. That Graham, Paul, and sometimes Roland and Mark et al as well as many investors spend so much time discussing and debating here is something I can't place a value upon. We can each or subtract from that by how we choose to interact with the community,
cheers
Mark
well said sir
Excellent post Mark.
Thank you.
Well I for one don't agree with you, and I suspect I am not alone, stockpedia is essentially a data service . The work the of likes of Paul and Graham do is icing on the cake and I for one think they do a great job and paul's weekly podcast summarises the whole week output which is essential listening.
Hi Chri55... did you perhaps have 1 company in mind that you would like the chaps to cast an eye over please?
We are getting a rolls Royce service here for the price of a fiat uno - it feels like you are complaining the RR doesn’t have floor mats!
Err leave it out. This is best stock analysis service going
Your sense of entitlement CHRI55 is hilarious!
That’s a bit acerbic for first thing in the morning....and a bit patronising. Put the kettle on, take a deep breath and relax.
Thats a little rude imo
It's a paid for service, but if like me you're paying £295 for 250 trading days of commentary, that works out at £1.18 per day.
If the team chose not to bother turning up at all a few days a year I can't say I'd be too bothered!
Yes and of course you're not just paying for the commentary - you get all the Stockopedia tools as well.
Spot on Michael.
I wish we didn’t get comments like CHRI55’s here. Reading it makes me feel nauseous, so god knows how it makes Paul and Graeme feel. If it was me I would shut up shop for the day or maybe the rest of the week.
Regards
Michael
They have a history of similar comments.
They?
Yes, he or she. If gender unknown, they usually don't like being called it.
Ah thanks for clarification. I see what you mean.
I wish I understood why they do it. What they gain from comments like this. Indeed why they even show up here.
Regards
Michael
CHRI55
That is such an insensitive comment and I’m struggling to believe I am reading here.
I have never cease to be amazed at Paul and Graeme’s output and actually cannot comprehend the efforts that they must go to, on our behalf, to analyse the news flow, gather their thoughts, put it down on “paper” and then come to an opinion. All for about a £1 a day, with the rest of Stocko thrown in for free.
I really think an apology is in order.
Regards
Michael
Couldn’t agree more Michael FBS….I totally agree that a an apology is needed …preferably a genuine one….But on the positive side an insensitive and rude comment made by someone who obviously got out of bed the wrong side this morning has generated so many ‘ Thanks and appreciation ‘ messages from the board members (and thumbs up) that hopefully Paul and Graham feel really positive about their much read ,comprehensive and detailed daily articles ……Lets face it if you don’t like it you don’t have to be a member or pay the subscription….you always have the option of DYOR….. Enjoy your day everyone…Penny
@CHRI55: Seeing as how you appear to be extremely value conscious, might I suggest that trolling on X or ADFN, which are both free, would give you far more bang for your buck than paying a subscription to an extremely high quality data platform like Stocko and then wasting your valuable time and effort trolling such a relatively small community?
FWIW, I'd like to concur with all the other respondents here who recognise that the paid subscription is for the immensely useful data resources (screens, folios, stock reports, rankings etc.) and that the superb contributions of Paul, Graham and the whole SCVR community are simply the icing on top of an already wonderful cake
Hi CHI55,
You may believe you have a point, but would it hurt to simply ask in a more polite manner?
Which company report are you waiting for? Is there anything regarding this company that you would like to discuss?
The quality and quantity that Paul and Graham produce is top notch. Occasionally they may miss something, albeit rarely.
Good manners, I’ve been told, cost nothing.
A couple of points from National Grid (LON:NG.) announcement, firstly it's a decent infrastructure investment programme, approx half in the UK ... so £30bn over 5 years is meaningful and positive. Someone benefits. For National Grid (LON:NG.) holders it is effectively a dividend / share cut ....since the £value will be held but diluted by the increased share count... which is worthy of thought versus other similar plays. I note BT (LON:BT.A) (which I own) have already executed their investment plan.... so in theory less immediate dilution risk...
Bytes Technology (LON:BYIT) TU slightly below forecasts for FY 2/24.Outlook statement characteristically vague. While mildly disappointing, trading is in line with peers’ results. Shares have run up a little lately expecting a good report so I would anticipate a bit of a pullback this morning.
Eneraqua Technologies (LON:ETP) Full Year 2024 (yr end Jan24) results overview video & podcast. As anyone knows who follows ETP, it's been a challenging year. Revenue was only down 2.4% to £53.8m but adj EBITDA -£3.3m v FY23 £11.8m, the adj EBITDA margin -6.2% due to project delays due to inflationary pressure on budgets and the government announcing an intention to change legislation governing development in nitrate-sensitive areas, since resolved. Cost savings of £1m implemented. Cash generation £7.7m. The outlook: non-domestic Energy projects are exciting with a first major NHS Trust contract of £11.3m with Kingston NHS Trust,; Water grows strongly, including the first nutrient neutrality contract with Ashford Borough Council, Kent. In Energy the local authority domestic growth is not expected till FY26.
There's an Eneraqua webinar at 11.30 today. Register here.
Ah missed this Tamzin!All much more succintly posted than me.N.B. to self.Should read more carefully next time!
An interesting morning - 2 big discounted rights issues. National Grid (LON:NG.) and Great Portland Estates (LON:GPE) along with a bid for Hargreaves Lansdown (LON:HL.). The GPE rights issue is at 230p versus net asset value of 624p, effectively forcing holders to take it up or be diluted. The National Grid rights issue is also at a very big discount. At least the LSE is serving a purpose - fundraising!
The discount doesn't matter much. This is because the rights issue is announced when the stock is trading cum rights (before the rights have come into effect).
You need to calculate the Theoretical Ex-Rights Price (TERP).
I've explained rights issues in detail here. They offer some good trading opportunities as they aren't well understood.
https://www.shiftingshares.com...
Bloomsbury #BMY Preliminary Results
Success of portfolio of portfolios strategy leads to exceptional sales up 30% and profits up 57% with full year dividend up 25%
Revenue and profit for 2024/25 upgraded
https://www.voxmarkets.co.uk/r...
It will very interesting to see if the SP moves today and if so by how much. I think a lot of this was in the price after the recent upgrade, and there were very high expectations of further beats. I was a little underwhelmed by the guidance for 24/25 and although Bloomsbury Publishing (LON:BMY) tend to be conservative in their guidance I was hoping for a little more. No mention on the three body problem after the Netflix adaptation and a slight decrease in higher education numbers, although solid future projections there. (I hold, largest position)
BMY Flipping 'eck. I've seen the shares down over 8% this morning. Let's see if it can do an RS1 and turn itself around by the end of the day.
Seems like one where a dip is a bit of a gift if willing to just wait another year! S J Maas not releasing a book in FY end 2/25 seems to be the only reason for lower profits.
A silly bid for Hargreaves Lansdown (LON:HL.) and an election to get things started.
Sterling hasn't moved, since a change of government is expected, and is a somewhat uncontroversial centrist shift rather than a lurch to an extreme right or left candidate.
Should the board of Hargreaves Lansdowne not have disclosed the bid in April to the market ?
Hargreaves Lansdown (LON:HL.) offer of 985p made by a consortium rejected by the HL board on the basis that it undervalued the company in the boards view. Perhaps another bid may be forthcoming? I hold. Would be interesting to hear Grahams view on where this could go.
It's a cheeky low ball bid from outside the UK looking at buying up decent British companies on the cheap. It's time the UK grew a pair and to coin a phrase ' got on its bike' .
Hargreaves Lansdown (LON:HL.) In depth piece from Roland on May 8.
Thanks for flagging it up RDHOWARTH :-) My recent thoughts on Hargreaves Lansdown (LON:HL.) here:
https://www.stockopedia.com/co...
Braemar #BMS Final Results
"Strong trading performance building resilience and sustainable returns for shareholders, with a platform for future growth"
Dividend UP 8%
Aviva #AV. Quarter1 Trading Update
"Excellent first quarter results
Strong growth across the Group. Another quarter of consistent delivery
Capital position strong and resilient"