Small Cap Value Report (Tue 8 October 2019) - BOWL, AIR, YOU, ARB

Good morning! Let’s see what’s in Tuesday‘s RNS.
We have updates from:
- Hollywood Bowl (LON:BOWL)
- Air Partner (LON:AIR)
- YouGov (LON:YOU)
- Argo Blockchain (LON:ARB)
Hollywood Bowl (LON:BOWL)
- Share price: 231.6p (+2%)
- No. of shares: 150 million
- Market cap: £347 million
Hollywood Bowl Group, ("Hollywood Bowl" or the "Group"), the UK's largest ten-pin bowling operator, is pleased to announce another strong performance for the year to 30 September 2019.
PBT is set to come in "slightly ahead of market expectations".
The prior forecast for PBT was £20.9 million.
Like-for-like revenue growth is 5.5% - not bad. It's easy to forget that like-for-like expenses tend to increase as well, perhaps by 3% or so. So the LfL revenue growth should be more than enough to offset that.
Checking the archives, I see that rival company Ten Entertainment (LON:TEG) reported LfL sales growth of 7.4% in H2. As a sector, bowling is clearly doing rather well this year!
Capital return
I wonder if management of BOWL read this report? Either way, they seem to agree with my view that the company is stable enough to carry a smaller equity cushion (e.g. see my remarks here and here and here).
The company's net debt at March 2019 was just £5.3 million, versus operating profit of £16.8 million in the previous six months. That debt figure was after payment of special dividends. So it was virtually debt-free, relative to profits.
Therefore, I can support this stance:
The Board remains committed to investing in the business while considering the appropriate use of surplus capital to enhance shareholder returns... Therefore, in line with the Group's capital allocation policy, the Board is considering returning additional capital to the Group's shareholders.
It's a cash-generative, successful business. So long as its sites remain well-invested, and there is no financial stress, I don't see why anything left over shouldn't be sent back to shareholders.
BOWL management have already demonstrated their shareholder focus by paying a couple of special dividends, but maybe they can push the boat out a little bit with their next move?
I suppose we do have to take the recession risk into account. The question is whether the company would be able to weather an economic storm, even if it was carrying a larger debt load?
Checking the historic figures, I see that it was unprofitable from 2013 to 2014, which was before the company listed.
My instincts are that the company would be OK in a recession, since bowling trips are a cheap form of family entertainment and are easily justified if foreign holidays becomes less affordable. But this is a judgement call.
My overall stance is that I continue to view the company positively, and the StockRanks agree, calling it a High Flyer.
Quality metrics are great:
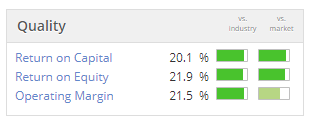
Note however that these mertics are before the implementation of IFRS 16 in the company's financial statements. I expect that these metrics (ROC, ROE) will deteriorate for BOWL and for all other companies with substantial leases, after the implementation.
At the H1 results, the company confirmed there will be a big impact:
"IFRS 16 [is] expected to have a significant impact on reported assets, liabilities and the income statement of the Group..."
While the value of the company won't change, the capital-intensive nature of what it does will become more apparent, as it will for all companies which lease property.
Air Partner (LON:AIR)
- Share price: 83.6p (-9%)
- No. of shares: 52.9 million
- Market cap: £44 million
Half year results for six months to 31 July 2019
Thanks to Tamzin for posting this video (and all her other videos) in the comments.
Air Partner providers charter aircraft and a host of related services.
These results show that "underlying" PBT is down 29.5%, while statutory PBT (i.e. the PBT without any adjustments) is up 6.8%.
Let's unpack this.
- gross profit is only slightly down, at £17.2 million
- In relation to the fall in underlying PBT, the CEO says in the PiWorld interview:
"one of our suppliers in Europe, which was a one-off for this year, was unable to advance with capacity, and that meant we had to look at alternatives for supply".
I've been searching the RNS for more detail on this supply factor, and this is the best I can do. Under "Risk Factors", the CFO says:
Economic uncertainty affects corporate, government and individual customers and affects the quality of supply of aircraft as operators consolidate or leave the market. These trends are outside the Group's control, but the strategy remains to diversify the addressable market and broaden the customer mix.
In addition to the "lack of supply", we also have higher expenses from recruiting activity (Board and management team) and new offices in Singapore and Houston. The company is bullish that these higher expenses will in turn drive growth, in future periods.
Charter
This had a "mixed performance", with some bright spots but also some negatives:
- "a drop in tour operations activity in France, a reduction in flying by a key customer in the UK, as well as small decreases in activity in the US and Italy".
As a result of these challenges, gross profits in Charter fall from £8.4 million to £7.2 million.
Other sources of gross profit:
- Ptivate jets increased to £6 million.
- Freight increased to £1.9 million.
- Consulting and Training increased to £2.1 million.
Statutory PBT increased, and this is due to the absence of all the exceptional costs incurred last year - mainly accounting review costs and abortive acquisition costs.
This gives us a much cleaner result for underlying PBT, which is always something that I like to see.
I think it's fair to say that the accounting problems are behind AIR now.
Outlook statement
The company outlook is in line with expectations although the market doesn't fully agree, having marked the shares down by over 5%:
We are encouraged by the progress we have made in what has been a difficult first half of the year for the aviation industry. In particular, the growth in Consulting & Training and the success of our US business clearly demonstrate that we are delivering on our strategy to diversify revenues across the Group.
Acquisitions are being assessed, and the company has net cash of £4.3 million, so it should be in a position to make a purchase.
I note however that the company had drawn down £5.5 million under its RCF, as of the balance sheet date. This suggests to me that it needs to use a lot of cash to fund its daily operations (since otherwise there is little reason to use an RCF which also being in a net cash position).
My view
On valuation it does look cheap:
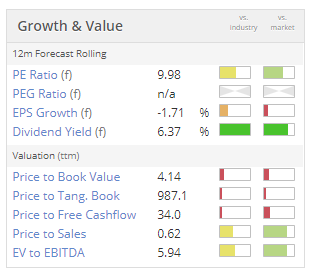
But I don't have a strong view on its prospects or its competitive positioning. As regular readers will know, I tend to avoid airlines and I also tend to avoid companies in the "support services" space.
Air Partner is arguably in both of these categories.
Having said that, the profits and dividends are real and it's showing a lot of ambition for the future.
To me, this situation is finely balanced and I'm neutral.
YouGov (LON:YOU)
- Share price: 535.5p (-0.5%)
- No. of shares: 105 million
- Market cap: £561 million
Full year results for the year ended 31 July 2019
Larger than we normally cover, but I do find this one intriguing.
It has always looked very expensive, but the high rating turns out to have been justified by excellent earnings momentum.
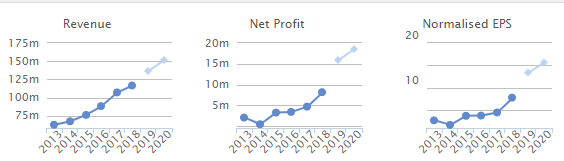
Today's results show statutory PBT up by an amazing 65% to £19.5 million.
The company has benefited from very few "exceptional" items this year, only £1 million of them versus almost £5 million last year.
Net cash is an admirable £38 million.
Outlook is more important than historical results:
Trading since the year end has continued positively. While Brexit continues to create uncertainty in the economic and political environment, especially for UK and European businesses, the international spread of our revenues, with a significant and growing US weighting, cushions us from volatility. In the context of both the macro-environment and our own plans to accelerate our investment in technology and geographic expansion, we remain confident in our growth prospects for the year and beyond.
Business plan
The company has succeeded in its five-year plan to treble profits, and it has done this by focusing on scalable products with good operational leverage, rather than the custom research projects it traditionally focused on.
Scalability is a feature we should be looking out for in our investments - businesses and products which can grow without any additional fixed overheads.
In YouGov's case, it worked on creating products which many different customers could use, rather than continuing to focus on the one-off projects which had to be delivered on a case-by-case basis.
In its own words:
"The strategy was to focus on growing our Data Products and Data Services divisions, which have operational leverage, even though it meant withdrawing from custom research projects that, while profitable, did not benefit from the strengths of our unique connected-data system. Our investment in technology and products during the last five years has created a platform for scalable profit generation and has enabled our business to consistently deliver results ahead of the market."
Looking ahead, the company's new growth plan is again very challenging. The strategic pillars t will focus on are:
- integrating and adapting its huge data bank to allow it to be used as a research tool in lots of new and different ways.
- creating audiences for advertisers and selling to these audiences ("ethical activation")l.
- building resources which can be used by the general public, thereby turning its own website into an internet destination.
Cash flow has improved (this was previously a bit of a concern, due to the buildup of intangibles, if I recall correctly).
Net cash generated from operating activities is an impressive £30.75 million.
Scrolling down to the footnotes, I see that the company capitalised £4.8 million of internally developed software, while writing off £4.6 million through an amortisation charge.
Similarly, it spent a bit more on developing its "consumer panel" (the people who respond to surveys) than it wrote off.
The discrepancies aren't huge, so I'm inclined to give the company the benefit of the doubt.
Balance sheet - the company does have a little bit of balance sheet value: £108 million in net assets, or £10 million if you exclude intangibles, PPE and other non-current assets.
My view
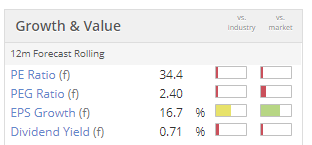
I'll probably still be watching this company from the sidelines when it has a £1 billion market cap, rather than participating in the rise.
It's just too hard to pay up for a company at this sort of rating, without a huge amount of conviction:
Argo Blockchain (LON:ARB)
- Share price: 8.5p (+2%)
- No. of shares: 294 million
- Market cap: £25 million
Revenues increase 75% in Third Quarter
This quirky little bitcoin operator changed its strategy from one which made no sense ("mining-as-a-service") to something much more reasonable (mining for its own account). Under this new strategy, it might actually succeed!
This update confirms £3.6 million of revenue from crypto mining in Q3, "at a mining margin of approximately 73%" (I guess this is the gross margin).
It is seeking to double the number of machines being used for production, adding 6,000 on to the current fleet.
Tactical change - it is going to regularly exchange crypto for fiat from now on, "to avoid additional exposure to Bitcoin pricing". Sounds reasonable. This will (marginally) reduce the volatility of its results.
My view - with its new strategy, and this tactical change, I think it's possible that this is a decent vehicle for PIs to gain crypto exposure (if that's what they're looking for).
For those who already trade shares, it might be simpler to buy a stake in this, versus using some other online wallet or trading facility.
If crypto coins turn out to be the investing equivalent of rat poison (Buffett) or "turds" (Munger), then shares in Argo can't be worth much less than the coins themselves will turn out to be.
Companies saved for later in the week, if things quieten down: Time Out (LON:TMO), Franchise Brands (LON:FRAN) Stock Spirits (LON:STCK), Motorpoint (LON:MOTR).
Thanks for all the comments and suggestions, as always.
Best regards
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Graham: "I expect that these metrics (ROC, ROE) will deteriorate for BOWL and for all other companies with substantial leases..."
Is that right? I understand how ROC will be impacted, but don't see why ROE should be.
I don't claim any expertise and am happy to be schooled on this, but as far as I understand it, although the details of the calculation will change, there is nothing to say that "R" will work out lower, or "E" will be higher. So why would ROE deteriorate?
Hi cmpeckham. Good observation. ROC takes the big hit, not ROE. But ROE also gets affected because in the early years, the interest + depreciation combo is bigger than the flat lease expense. This unwinds in later years.
Air Partner (LON:AIR) here's a video interview with the CEO, talking through the results.
Main features: in line with expectations for the full year, and ahead of where they'd anticipated at the AGM. Investment hit PTP, but an exceptional lessens the drag. Previous investment in the US is bearing fruit in Private Jets, so hopefully the recent investment will pay hansomly too. Consultancy and Training looks positive, which helps diversify away from the lumpiness of Charter. The 2021 order book is looking very strong, so expect to achieve this year's forecasts, and a very good 2021.
Finncap (LON:FCAP) TU today, expect to report rev £14.2m PBT not less than £1.3m (period on period £9.1m £1.4m). Challenging mkt conditions, so resilient performance. Here's a recent investor presentation by CEO & CFO.
(Progressive Equity Research have a new Finncap (LON:FCAP) note out today.)
Robert Walters (LON:RWA)
Trading statement, first table demonstrates the cyclicality of their earnings, with the UK -11% and the rest of world growing.
I think RWA is well run. The founder is the CEO and my own experience with RWA has been positive. In Asia, I’ve heard good things about their branches and they seem to be expanding successfully. Balance sheet is strong with net cash.
Recruitment is cyclical so RWA swoons in downturns and then recovers. So you must have a view as to where we are in the cycle.
Air Partner (LON:AIR)
Bit difficult to read through the results. There is a lot of commentary from the CEO about investments and upskilling, i.e. higher costs.
Group Charter is the weak area with segment result down from 2,932k to 2,033k partially offset by Private Jets up from 1,384k to 1,724k. In Charter, customer revenues look lumpy and prone to micro shifts. The UK and Europe weak. The USA and their JetCard are the bright spots. There were high exceptions last period of 1,400k falling out this quarter, hence underlying has dropped.
At least net cash (ex JetCard) grew from 9,236k to 9,822k so the 6.3% dividend is covered for now.
Air is a Lord Lee holding. Suspect holding Air is a long-term affair, air travel should expand over time albeit at some point carbon tax could change the whole industry. Air’s long term price chart shows quite extreme oscillations, with a long-term floor around 50p a recent floor around 75p and reaching a high of 150p only last year.
For me, it’s a buy the deep dips and hold, if you can withstand earnings fluctuations.
Air Partner (LON:AIR)
I too found the results difficult to go through. A few thoughts to add to the comments above:
If you strip out Depreciation and Amortisation. the Group Charter results actually showed a Year-on-Year Increase from £3,119k to £5,002k. I'm not sure why this wasn't highlighted as I had to work it out for myself from the notes in today's accounts. If anyone can see what I'm missing your thoughts would be appreciated.
The decrease in Underlying Profit before tax from £4.2m to £3.0m is therefore (in my opinion) primarily coming from a £0.9m increase in central costs, which is being justified by new offices being opened. A good foundation for future growth perhaps?
Air Partner (LON:AIR) has a current EV of around £44m so to be generating just under 10% of your EV in just the first 6 months of trading, with the expectation of a stronger H2, makes me view this as very undervalued and with a secure 7% dividend.
Cautious holder for now (I seem to be saying that a lot these days).
Cheers
A
'The decrease in Underlying Profit before tax from £4.2m to £3.0m is therefore (in my opinion) primarily coming from a £0.9m increase in central costs, which is being justified by new offices being opened. A good foundation for future growth perhaps?'
Or maybe it's the CEO's en suite putting green.
Air Partner (LON:AIR)
Yes, higher depreciation charge in H1’19. Looking at the two cost lines they load depreciation into, between half years:
Cost of sales from 8,448k to 5,073k and Admin from 5,467k to 5,154k. So the admin costs stayed flat and cost of sales reduced, but this makes sense as revenues reduced from 16,847k to 12,260k. While we don’t have the full detail to unpick it, I would go with the commentary that Group Charter segment is weak, with revenues down.
Refocusing on the cash flow.
The cash flow statement is mixed as it includes customer deposits for the JetCard. So looking at the movement on the non-JetCard cash balance between half-years, cash moved from 9,236k to 9,822k an increase of 586k. This was after paying the final 3.85p dividend of 2,011k. They are still to pay the interim dividend of say 1.75p which will cost around 900k.
So Air generate enough cash to pay the full 6.3% dividend which costs about 2.9m a year and leaves a surplus which should be north of 1m in a year. Also, they have net cash of 4.3m on the books.
So for now I own as a long term hold, as Air generates cash, holds net cash, pays a good dividend, has some prospects for growth albeit management need to be on their toes with the Charter weakness. Given their international revenue streams some protection from UK domestic travails as well.
Air Partner (LON:AIR)
Hi JWebster
Agreed that one can't split out depreciation between COS and Admin but there is certainly a big movement between the years, which makes it look like Group Charter, on an operating cash basis is doing much better this year. Any idea why?
Completely agree with you on the cash. Air Partner (LON:AIR) seems to make a lot of it! As for the Jetcard cash, I assumed this would be within working capital, so my comment above is looking at cash before working capital movements (the 6,862k figure below). Reducing this by £2.8m to account for the lease representations gives a true representation of c £4m from the first 6 months of trading.
Cheers
A
Air Partner (LON:AIR)
The large increase in depreciation was this…
“The reclassification of lease payments from operating expenses to depreciation, interest and repayments of finance lease liabilities has resulted in an increase in cash generated from operating activities of GBP2.8 million. The increase is offset by a matching increase in net cash used in financing activities.”
For the cash position less JetCard I looked at this
Hi Graham,can you take a look at MOTR if time permits,buying back 10% of their equity,David Shelton took full advantage of last buyback to offload 8m shares.
Hollywood Bowl (LON:BOWL) any chance of a ramble on Hollywood Bowl Graham seems to be holding up well given the high street carnage but have they reached maximum growth potential and maybe turning more into an income type stock moving forward.
re: Hollywood Bowl (LON:BOWL)
Hi - I agree, they need to probably increase the income payout now, since it looks to be mature and cash-generative. Just my view. Cheers. G
Air Partner (LON:AIR) half year results - seems ok, CEO talking about diversifying revenue streams and hires to strengthen team. Finally getting the 2018 monkey off its back?
I would like to request Air Partner (LON:AIR) (I have a long position).
Half year report out today. To me it seems like a miss off the last broker expectations and needs a strong H2.
Share price was up 7% yesterday on its new partnership to provide emergency services but has given it all back today.
Hi Graham,
If you have time to cover £AGFX trading update from yesterday / comments on the IPO that'd be much appreciated, given your sector knowledge!
Thanks
My morning smallcap tweet: RWA sprays the blame
Hollywood Bowl (LON:BOWL), £C21, Robert Walters (LON:RWA)
Hollywood Bowl (BOWL) guides FY pretax up over 10%, slightly ahead of market expectations. May return capital to the Group's shareholders.
21st Century Technology (C21) Edinburgh expected to award contract worth c.£2.9m over 5 years.
Robert Walters (RWA) Q3 net fee income up only 2%. Guides FY profit flat YoY. Blames Brexit, Hong Kong protests, US-China tariff war, gilets-jaunes, solar eclipses and cats-playing-pianos strike.
£BOWL are in my tuck away and forget category. They are being very astutely run by management and continue to both grow modestly and bring in great cash flow. The wild card for me is how their golf concept works and whether they are then able to grow a new income stream in that.