The Week Ahead (9-13 Nov): AI sell off, Middle East war, KNOS, SMWH, VLX, TAM

Welcome back to The Week Ahead. The Bank of England raised interest rates to 4% on Thursday, but this was largely expected and passed as a footnote to the week’s main news: the electoral Blue wave that gave Democrats full control of the US Congress.
It’s clear that two of the main issues driving the vote were inflation (especially fuel prices) and the Middle East conflict.
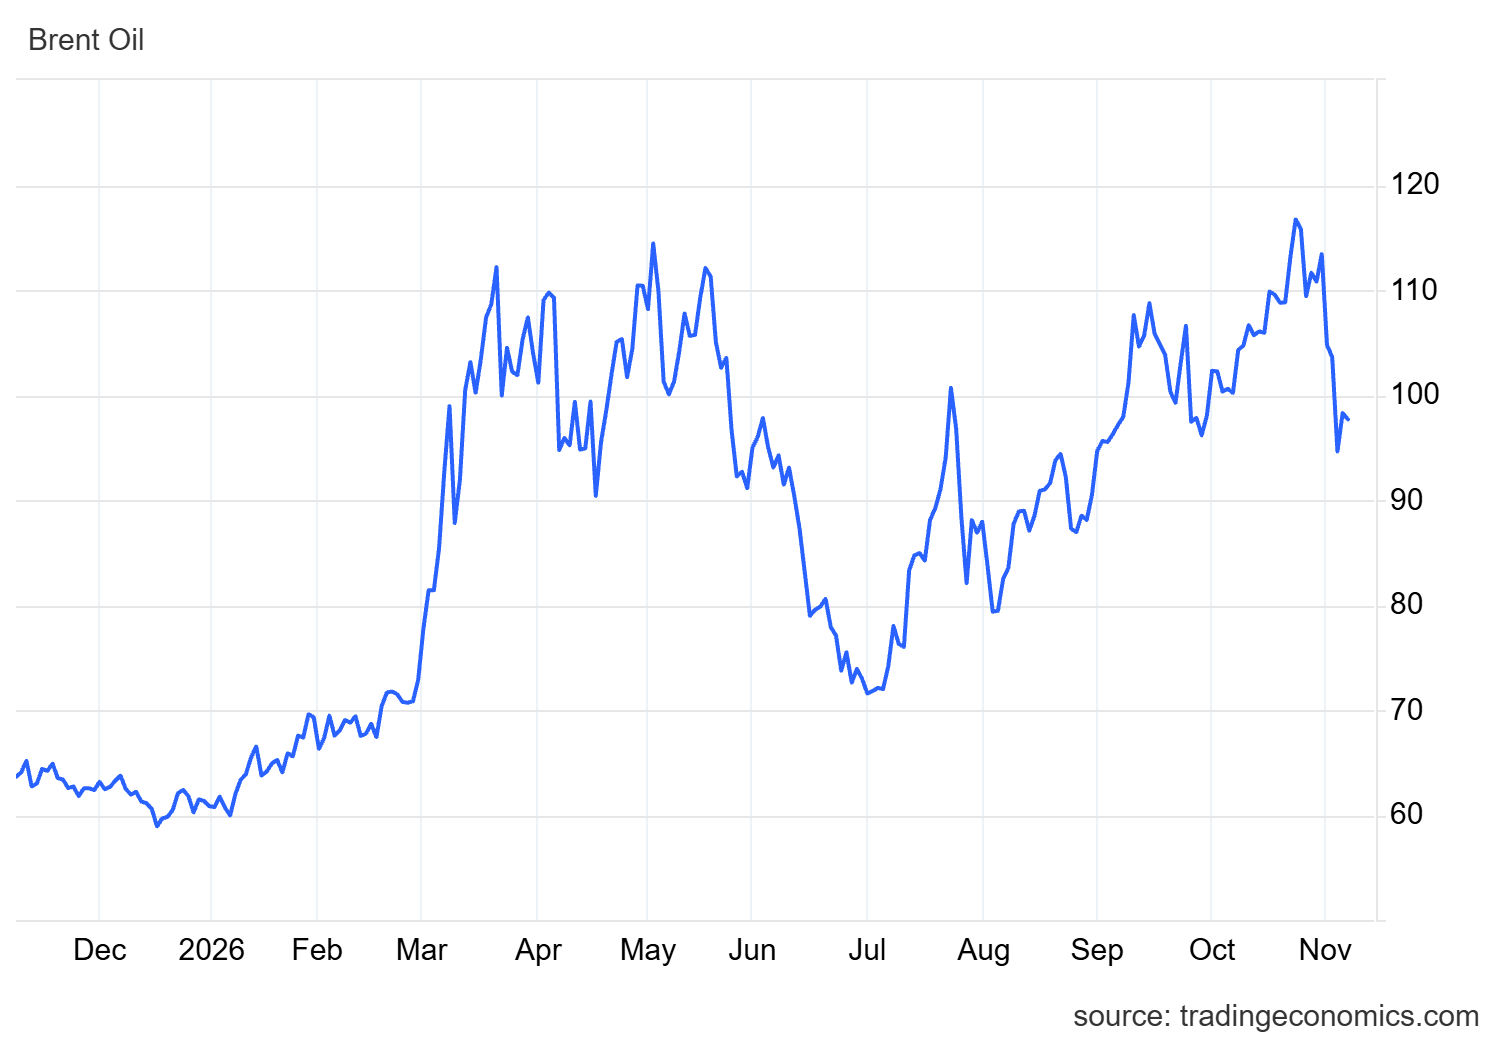
Oil prices climbed steadily ahead of last week’s midterms, as traders priced in a return to a hot war. Much of this price premium has unwound since Tuesday. My reading is that this suggests that the market now expects the Trump administration to seek an exit from the conflict:
The price of oil isn’t the only big number that headed south this week. As Graham has discussed already, US tech stocks were hit by a sharp sell off on Thursday. Investors appeared to be asking if the current pace of the AI rollout is sustainable and if the Democrats will tighten oversight of the tech sector and slow data centre construction.
The Nasdaq Composite index closed down 5.5% on Thursday, while and Philadelphia Semiconductor index lost more than 12%.
I’ve used an ETF as a proxy for the chip index in the chart below. The way semiconductor stocks are unwinding April’s crazy gains looks very much like the start of a major correction to me:
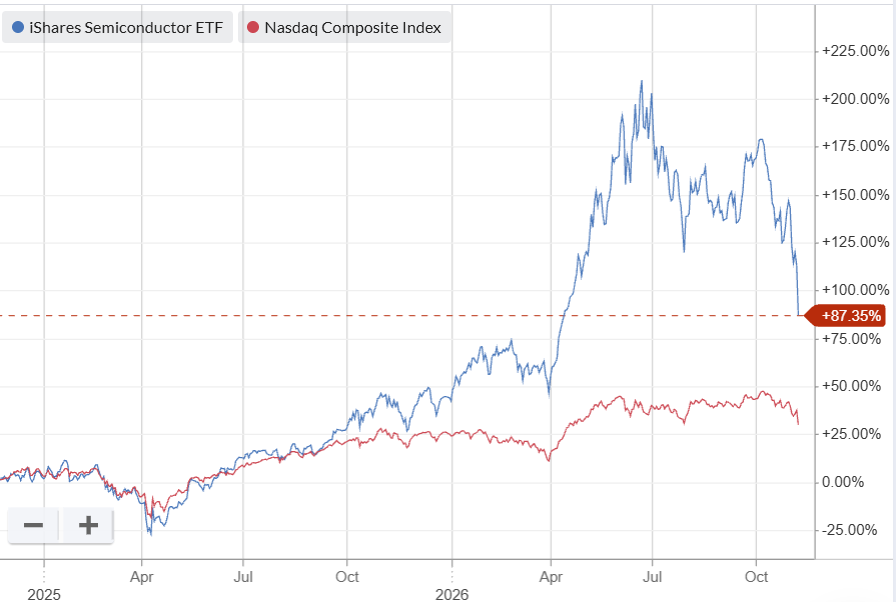
Some big names suffered remarkable drops on Thursday. For example, Advanced Micro Devices (NSQ:AMD) and Micron Technology (NSQ:MU) both closed down by more than 17%, while SanDisk (NSQ:SNDK) lost 22%. The common factor here is the potential for a rapid reduction in demand to reflect a reduction in data centre construction.
What might come next is a more severe reckoning for AI providers, as investors demand evidence of the returns being generated from these services. Anthropic’s planned IPO could also become more difficult; news reports are already suggesting the company may need to cut its target valuation.
Economic news
After this week’s Bank of England rate rise and US elections, next week looks relatively quiet for economic data on both sides of the pond.
Here in the UK, the latest GDP figures are expected to show a 0.2% increase in September, supporting a year-on-year growth rate of 1.7%.
In the US, annual inflation is expected to have remained unchanged at 3.7% in October, ahead of the midterms.
Company news
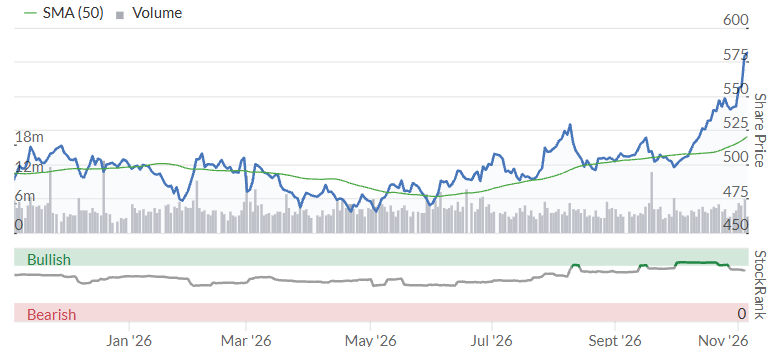
Investors looking for weekend reading may want to check out Berkshire Hathaway’s Q3 figures, which are due to be released on Saturday. Berkshire shares have put on an impressive spurt recently, perhaps as an antidote to anxiety about tech stocks:
Also in the US, Q3 results from neocloud firm CoreWeave (NSQ:CRWV) may be worth watching. Coreweave is one of a number of companies engaged in debt-fuelled data centre construction on the strength of commitments by hyperscalers to rent future capacity.
Third-party data centre operators are seen as more likely casualties from an initial slowdown in AI spending, as hyperscalers cut external commitments while maintaining their own in-house infrastructure.
Here in the UK, the flow of company news is likely to pick up as the week progresses. Here are some of the scheduled results that have caught my eye for the week ahead.
Kainos (LON:KNOS)
This IT services provider is a major provider to the UK public sector and is also one of the world’s leading accredited partners to Workday, an HR and finance platform.
I covered Kainos in a Stock Pitch earlier this year and admired the company’s quality metrics. However, while I think the business may deserve a premium valuation, the stock has already re-rated this year following August’s reassuring trading update and broker upgrade:
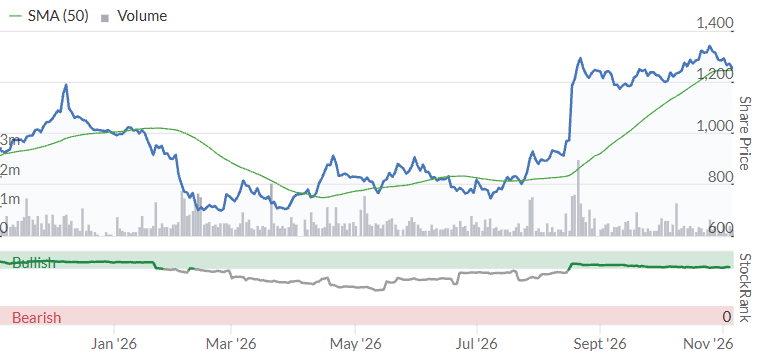
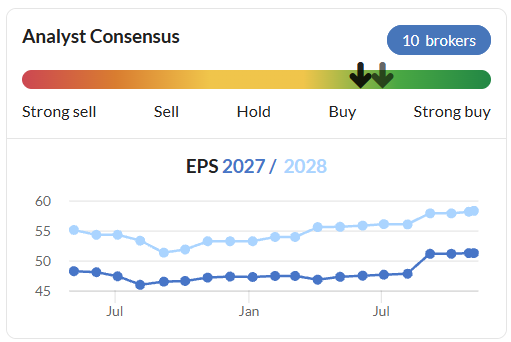
I can’t help feeling that the valuation is probably up with events unless this week’s results support a further upgrade to expectations:
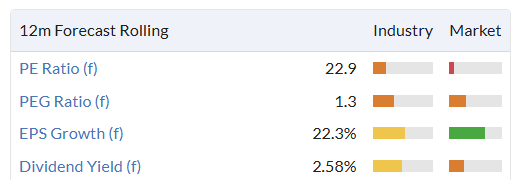
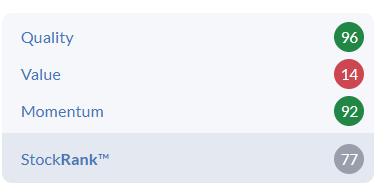
My view is reflected in Kainos’s High Flyer status and StockRank. While the shares score well for Quality and Momentum, the ValueRank is weak:
Tatton Asset Management (LON:TAM)
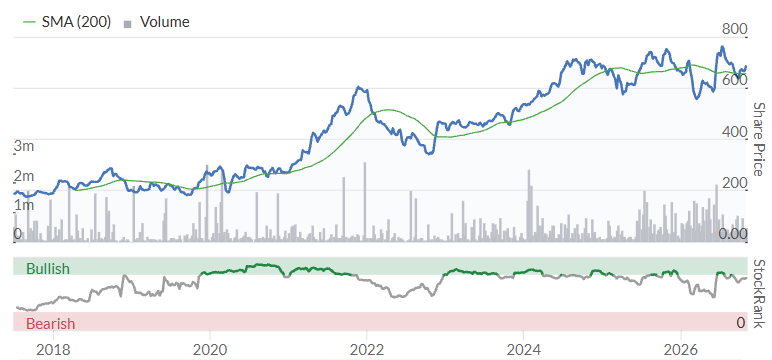
Tatton’s business model is built around the provision of model portfolios to financial advisers – a fast-growing market. Tatton shares have risen by around 250% since the company’s flotation in 2017 and I’ve been consistently impressed with its growth and profitability:
My only niggling doubt is over the performance of the company’s model portfolios. I can’t help wondering if the flagship Global Equity model portfolios have simply ridden the coat tails of the US tech boom without adding much extra value over an index tracker.
When I looked at the performance of these portfolios in June, I found that several of these strategies had delivered results that were very close to the FTSE All-World index over the last three years.
Tatton has outperformed most conventional fund managers since its IPO. In my view, the next test of the business may be how it performs – and whether it can retain funds – during a US-led market slowdown.
Volex (LON:VLX)
We covered this cabling specialist regularly in the DSMR. Over the last year or so, it’s become clear that Volex has been a big winner from the AI boom thanks to its ability to supply the complex cabling required for new data centres.
In the year to 31 March 2026, revenues in the company’s Complex Industrial Technology division rose by 56% to $383m. Management said that a key driver behind this growth was “strong data centre demand from a leading hyperscale customer”.
October’s half-year update nudged earnings guidance towards the top end of broker expectations.
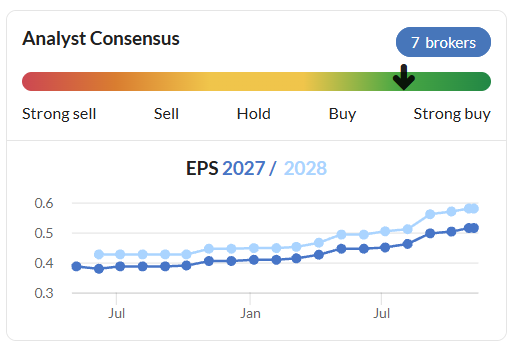
Despite this, the market reaction on the day was negative, perhaps because the company acknowledged that revenue growth was normalising after last year’s exceptional performance.
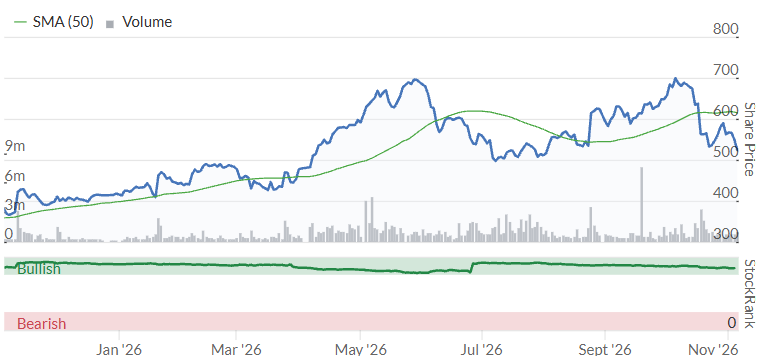
This week’s US tech sell-off hasn’t helped sentiment towards Volex either, so it will be interesting to see what the company has to say about its order pipeline and outlook in next week’s interim results.
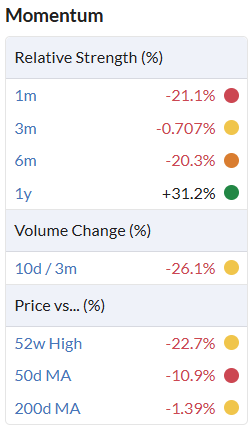
Volex’s technical momentum has weakened recently, suggesting investor buying appetite may be waning:
WH Smith (LON:SMWH)
Shares in travel retailer WH Smith remain more than 80% below their pre-Covid peak.
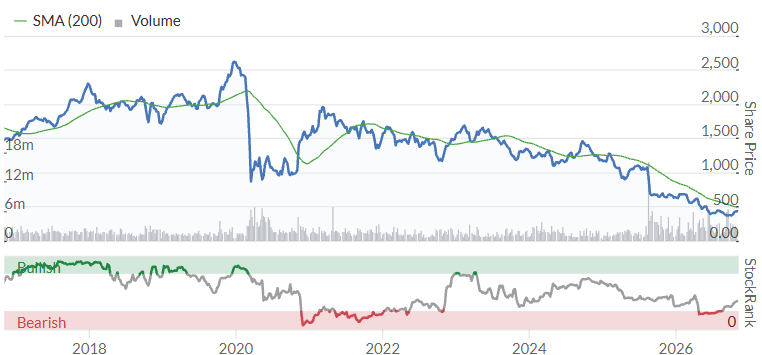
While the business has faced a number of problems in recent years, I think it’s fair to suggest that the primary reason for its fall from grace has been its aggressive US expansion. My impression is that this acquisition-led effort was both highly priced and badly executed – an unfortunate combination.
The company’s woes left it uncomfortably indebted and Graham maintained our view at RED in June, blaming ”the horrific balance sheet”. Since then, the business has raised £106m in new capital and issued an in-line trading update.
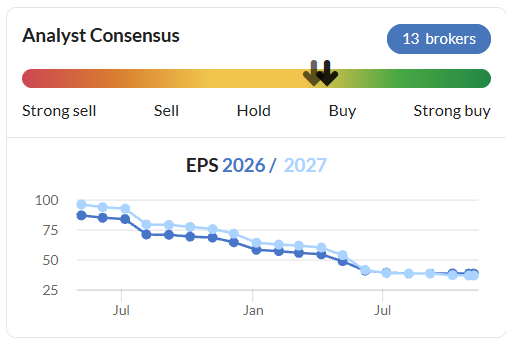
If next week’s results show sales stabilising and a reduction in leverage, then perhaps we will be able to move our view back to AMBER/RED before too long. WH Smith might even become an attractive turnaround situation.
My personal view is that there should be a path to recovery for this business. As far as I can see, the future of travel retail is likely to remain resilient, if only because such stores tend to benefit from a captive and relatively affluent customer base.
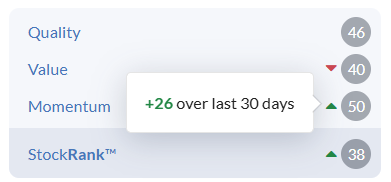
I note that in recent weeks, the company’s StockRank has risen and WH Smith has shed its Sucker Stock styling with a promotion to Neutral!
Have a good weekend!
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
9 Nov | ||
07:00 | Germany | Exports |
07:00 | Germany | Balance of Trade |
10 Nov | ||
00:01 | UK | BRC Retail Sales Monitor |
13:15 | US | ADP Employment Change Weekly |
13:30 | US | Inflation |
21:30 | US | API Crude Oil Stocks |
11 Nov | ||
10:00 | US | OPEC Monthly Report |
12:00 | US | MBA 30-year mortgage rate |
12 Nov | ||
00:01 | UK | RICS House Price Balance |
07:00 | UK | GDP |
07:00 | UK | Industrial Production |
13:30 | US | Initial Jobless Claims |
15:00 | US | Existing Home Sales |
17:00 | US | EIA Crude Oil Stocks |
13 Nov | ||
10:00 | EU | Employment Change |
13:30 | US | Producer Price Index |
18:00 | US | Baker Hughes Rig Count |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 9 Nov | Nothing of note. | Beximco Pharmaceuticals (LON:BXP) Kainos (LON:KNOS) SRT Marine Systems (LON:SRT) | Berkshire Hathaway (NYQ:BRK A) / Berkshire Hathaway (NYQ:BRK B) Constellation Energy (NSQ:CEG) Ferguson Enterprises (NYQ:FERG) KKR & Co (NYQ:KKR) NRG Energy (NYQ:NRG) Occidental Petroleum (NYQ:OXY) |
Tuesday 10 Nov | Dunelm (LON:DNLM) Rainbow Rare Earths (LON:RBW) Watches of Switzerland (LON:WOSG) | Ab Dynamics (LON:ABDP) Caledonia Investments (LON:CLDN) Dialight (LON:DIA) Oxford Instruments (LON:OXIG) Tatton Asset Management (LON:TAM) Tpximpact Holdings (LON:TPX) Vodafone (LON:VOD) Zoo Digital (LON:ZOO) | CoreWeave (NSQ:CRWV) Infineon Technologies AG (ETR:IFX) Petroleo Brasileiro SA Petrobras (NYQ:PBR) Softbank (TYO:9984) Sony (TYO:6758) TransDigm Incorporated (NYQ:TDG) |
Wednesday 11 Nov | GreenX Metals (LON:GRX) ITV (LON:ITV) Newmark Security (LON:NWT) Panthera Resources (LON:PAT) Spirax (LON:SPX) Taylor Wimpey (LON:TW.). | Castings (LON:CGS) James Cropper (LON:CRPR) Fuller Smith & Turner (LON:FSTA) ICG (LON:ICG) Motorpoint (LON:MOTR) | Corteva (NYQ:CTVA) Siemens Energy AG (ETR:ENR) E.ON SE (ETR:EOAN) HONDA MOTOR (TYO:7267) RWE AG (FRA:RWE) Swiss Life Holding AG (SWX:SLHN) |
Thursday 12 Nov | Burberry (LON:BRBY) Endeavour (ASX:EDV) Galliford Try Holdings (LON:GFRD) Kier (LON:KIE) Premier Foods (LON:PFD) Qinetiq (LON:QQ.). Quantum Helium (LON:QHE) Strategic Equity Capital (LON:SEC) | 3i (LON:III) WH Smith (LON:SMWH) United Utilities (LON:UU.). Volex (LON:VLX) Wise (LON:WISE) Wizz Air Holdings (LON:WIZZ) Young & Co's Brewery (LON:YNGA) | Allianz SE (ETR:ALV) Applied Materials (NSQ:AMAT) Arrowhead Pharmaceuticals (NSQ:ARWR) Cisco Systems (NSQ:CSCO) Enel SpA (BIT:ENEL) JD.com (NSQ:JD) Muenchener Rueckversicherungs-Gesellschaft in Muenchen AG (ETR:MUV2) Williams-Sonoma (NYQ:WSM) |
Friday 13 Nov | DFS Furniture (LON:DFS) Fiske (LON:FKE) Pensana (LON:PRE) Seed Innovations (LON:SEED) Talisman Metals (LON:TLM) | Land Securities (LON:LAND) | Nothing of note. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
MTEC AGM 11th
Conduit Holdings (LON:CRE) Q3 TU also on Wednesday