SIF folio Q3 review: making steady progress

The third quarter of 2026 seems to have been dominated by talk about AI capex, energy markets, public sector spending and government bond yields. Plus takeovers.
Several of these themes were reflected among the top performers in my rules-based Stock in Focus (SIF) portfolio over the last three months:
Company | Q3 share price rise | Business activity |
Harbour Energy (LON:HBR) | +22% | Oil and Gas |
Galliford Try Holdings (LON:GFRD) | +34% (up 15% since SIF buy) | UK infrastructure construction (water, roads, etc) |
Shell (LON:SHEL) | +22% | Oil and Gas |
Keller (LON:KLR) | +26% | Geotechnical engineering, especially US infrastructure and data centres |
However, a look at the FTSE 350 shows that the top performers among UK mid and large caps came from an entirely different mix of sectors:
FTSE 350 Company | Q3 share price rise | Business activity |
Hays (LON:HAS) | +103% | Recruitment |
Michael Page (LON:PAGE) | +98% | Recruitment |
Asos (LON:ASC) | +75% | Online fashion retail |
Oxford Nanopore Technologies (LON:ONT) | +75% | Healthcare (DNA sequencing) |
Pinewood Technologies (LON:PINE) | +68% (takeover) | Automotive dealership software |
Rotork (LON:ROR) | +66% (takeover) | Industrial flow control solutions |
Victrex (LON:VCT) | +61% | Specialty chemicals - PEEK polymer |
Kainos (LON:KNOS) | +60% | IT services and software |
WPP (LON:WPP) | +60% | Advertising/marketing |
Harworth (LON:HWG) | +56% (takeover) | Land and property development |
Looking down this list, I’d suggest the main themes were turnarounds and takeovers. Perhaps this is a reminder that outsized short-term gains often need a catalyst of some kind.
Of course, focusing on the top performers from an index or a portfolio doesn’t tell the whole story. Despite what the numbers above might suggest, SIF actually outperformed the FTSE 350 during the third quarter.
In the remainder of this piece, I’ll take a look at the performance of the whole SIF portfolio in Q3 and review my trading activity from the quarter.
First, here’s a brief reminder of how the strategy works:
I select new shares from my SIF stock-buying screen* in a weekly review, adding new shares when possible, while taking into account diversification by sector and the number of existing holdings;
Shares are held for a minimum of nine months. However, if a stock issues a profit warning or falls by more than 25% below the portfolio’s cost price, it’s sold at the next weekly review;
After nine months, I test shares against my SIF stock-selling screen*. If they pass all the rules, they remain in the portfolio subject to a rolling monthly review. If they fail, they’re sold.
SIF is a model portfolio, but I invest a portion of my own real-money portfolio in the same shares.
SIF Q3 2026 performance: easing ahead
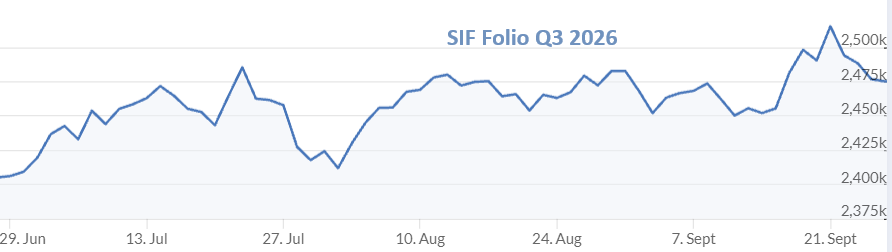
The only performance that really matters in investing is portfolio performance. The third quarter was a positive but unexciting period for SIF that left the value of the portfolio modestly higher, having generated income and capital gains slightly ahead of the market.
To put some numbers on this, SIF generated a total return of 3.1% during the quarter, compared to 2.4% for the FTSE All Share index (capital gains + dividends).
My SIF buying screen remained well stocked with new stock ideas. This allowed me to add a number of new positions to the portfolio and reduce my cash weighting to a more comfortable level:
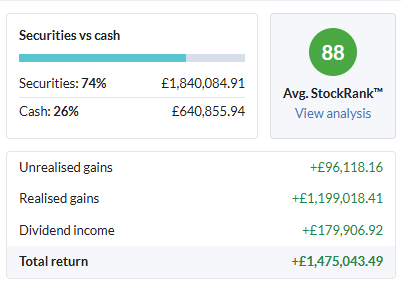
As I discussed in my half-year review, the portfolio’s cash weighting rose to uncomfortable levels earlier this year, impinging on income performance. I’m much more comfortable with the current situation, which still provides plenty of headroom for buying in the event of a market slowdown.
Here’s a more detailed overview of the portfolio’s performance for both the third quarter and the first nine months of 2026:
Q3 2026 | Price Return | Income | Total Return |
SIF Folio | 2.1% | 1.0% | 3.1% |
FTSE All-Share | 1.7% | 0.7% | 2.4% |
9M 2026 | |||
SIF Folio | 4.8% | 2.4% | 7.2% |
FTSE All-Share | 7.1% | 2.7% | 9.8% |
Taking a longer view, here’s how SIF has performed against the All-Share TR index since the start of 2025:
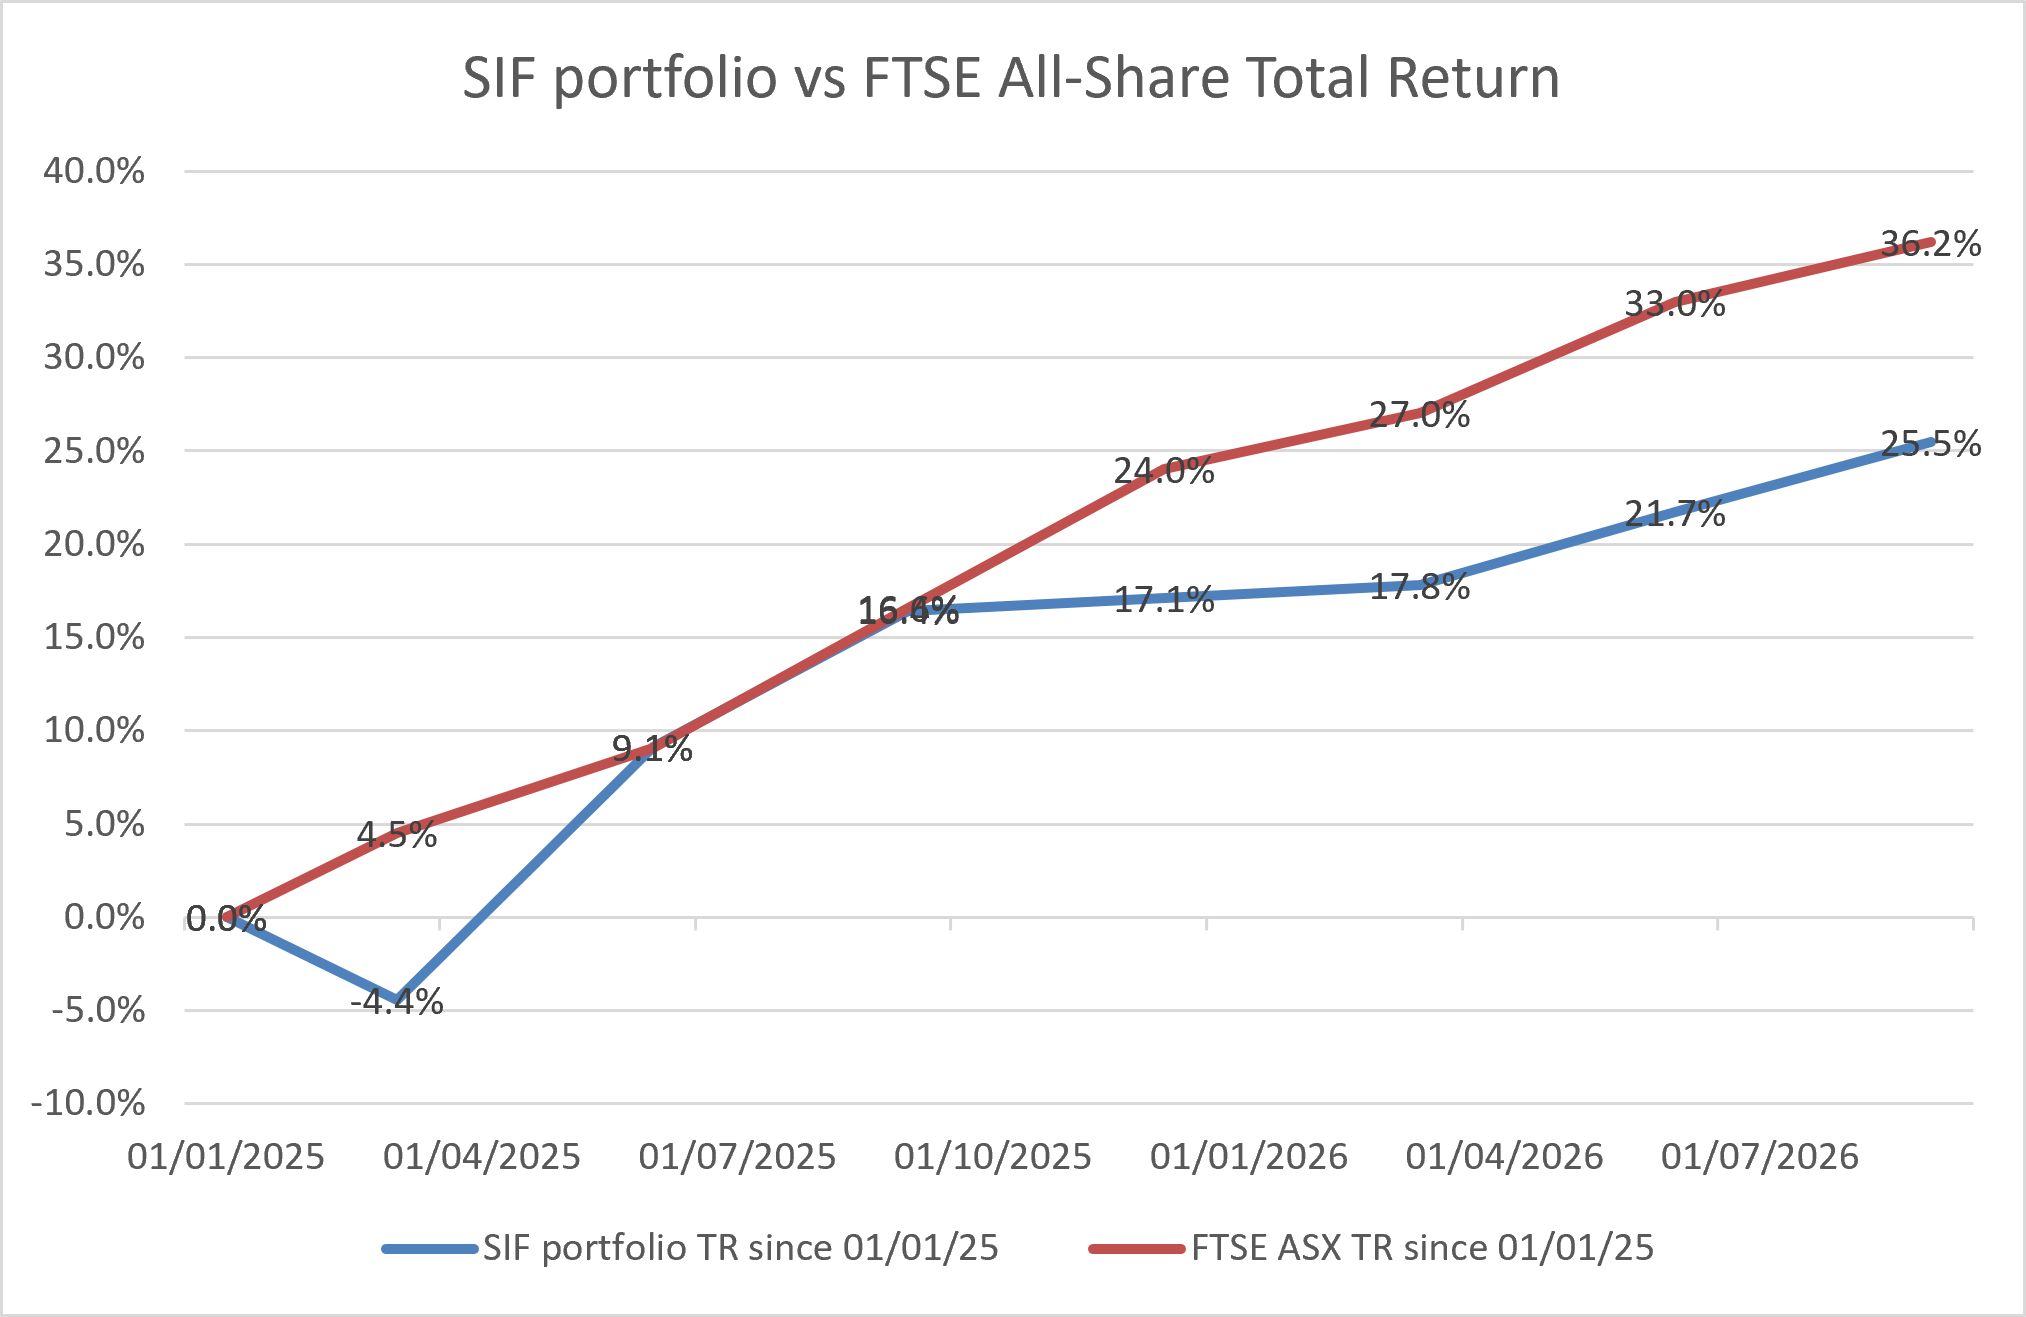
Note: I’ve presented performance from the start of 2025 because that’s when I switched the portfolio’s strategy to include dividend returns. Prior to 2025, I didn’t include dividends, so performance was measured differently. I’ll produce a blended chart showing the portfolio’s full history at the end of this year.
SIF Q3 portfolio review
The portfolio is sized to support c.20 equal-sized holdings, with a cash buffer to preserve liquidity in the event of a market crash.
The actual number of holdings at any one time is dictated by the output of my buying and selling screens, not by me.
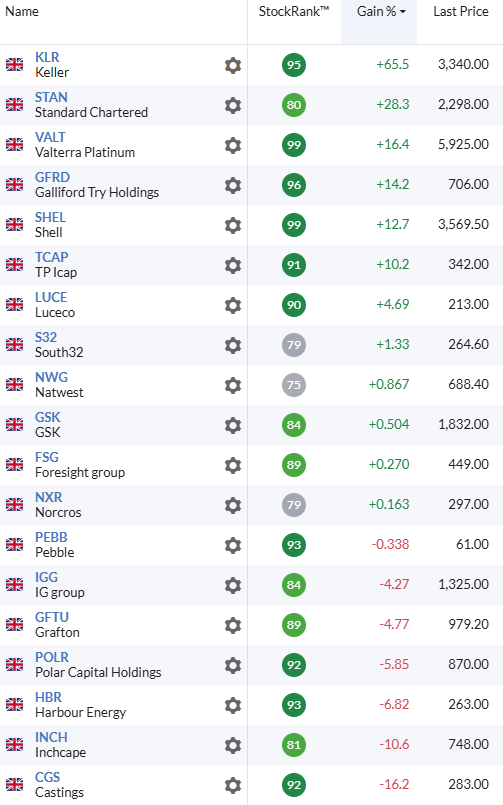
My buying screen remained well populated during the third quarter and the last three months have been another period of net buying for the portfolio. At the end of September, SIF had 19 holdings, up from 14 at the end of June:
Q3 Buys: 8
Q3 Sales: 3
Portfolio snapshot
Here’s how the portfolio looked after market close on 30 September 2026:
Portfolio metrics
The evolution of the portfolio over the last 21 months can be seen more clearly with the aid of this table below. I started tracking this set of metrics at the start of 2025 to give me a clearer understanding of how the aggregate characteristics of the portfolio were evolving:
Period | P/E rolling 1y | Div yield rolling 1y | PEG rolling | Cash weighting | No. holdings |
Q1 2025 | 9.7 | 5.3% | 1.0 | 13% | 18 |
Q2 2025 | 10.2 | 5.0% | 1.9 | 5% | 21 |
Q3 2025 | 10.3 | 4.8% | 0.8 | 13% | 20 |
Q4 2025 | 9.8 | 5.3% | 0.9 | 30% | 16 |
Q1 2026 | 8.6 | 6.1% | 0.8 | 56% | 9 |
Q2 2026 | 10.6 | 4.8% | 0.9 | 33% | 14 |
Q3 2026 | 10.2 | 4.6 | 1.1 | 26% | 19 |
The change in these metrics largely reflects the change in the mix of the portfolio, with a slight reduction in average yield as the number of holdings has risen. One-year rolling dividend yields for SIF stocks range from 2.5% to 7%, with a median of 4.2%, so the bias is still firmly towards income.
In the remainder of the article, I’ll provide a summary of the changes to the portfolio during Q3 2026.
New stocks in Q3 2026
Polar Capital Holdings (LON:POLR)
After a strong H1, I added this tech-focused fund manager to SIF just when its share price levelled out!
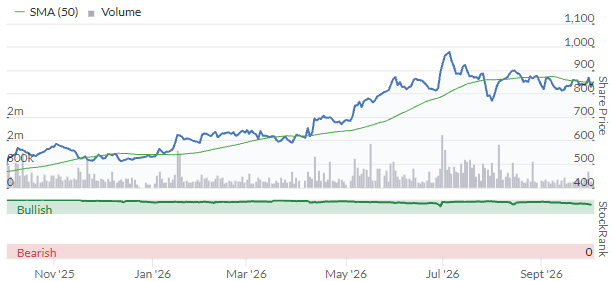
I’m not too concerned, though. I think the valuation remains appealing and am cautiously optimistic that Polar’s strong inflows and AUM growth will mean it remains a decent performer.
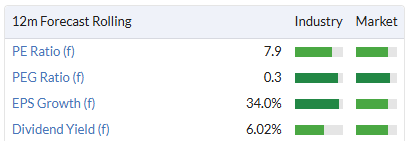
Graham maintained our GREEN view on Polar Capital in July (here and here), while flagging up that the main risk could be the company’s outsized exposure to the Tech sector.
I note that the stock also currently qualifies for the Jim Slater ZULU screen – historically one of our top-performing Guru screens:
I added Polar Capital Holdings to SIF at 924p on 8 July 2026.
Valterra Platinum (LON:VALT)
Valterra is the former platinum mining arm of FTSE 100 group Anglo American. It was spun out into a standalone unit last year as Anglo sought to divest a business seen as non-core and potentially low growth; the main industrial application for platinum is catalytic converters.
However, after a long period in the doldrums, platinum prices have enjoyed a resurgence since Valterra’s IPO:
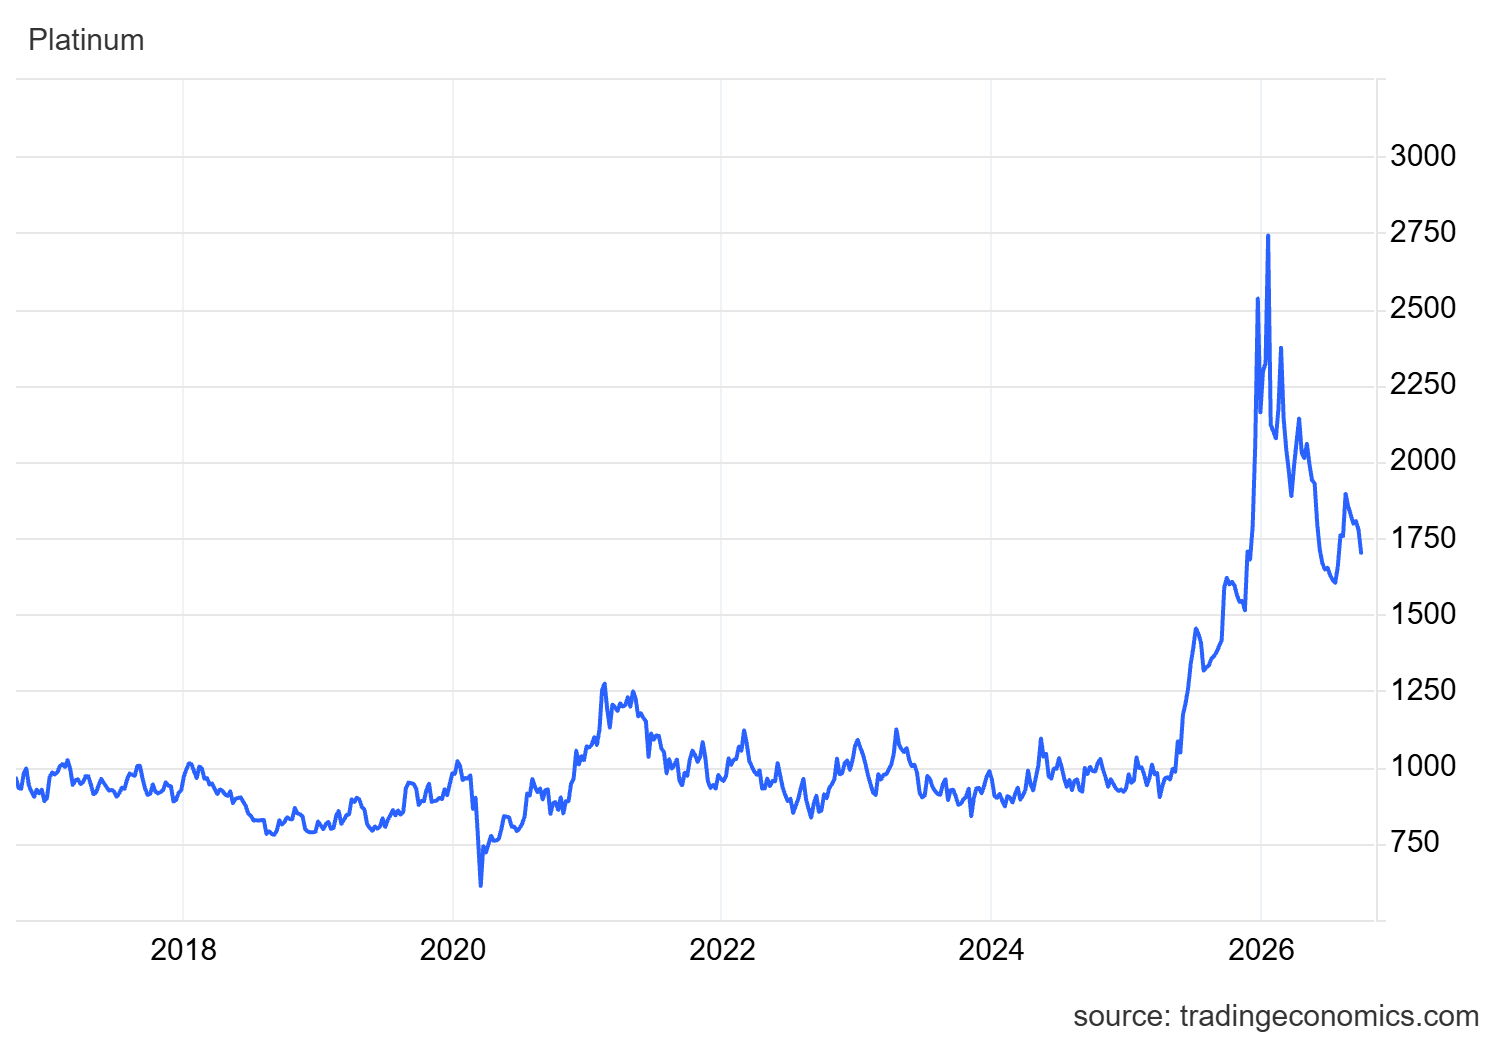
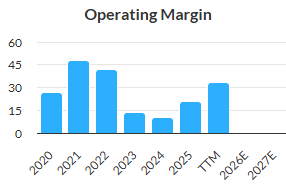
Miners are leveraged plays on the underlying commodity. The rising price of platinum has had an impressive effect on Valterra’s profit margins:
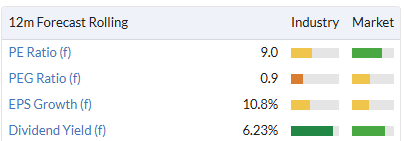
With prices at current levels, Valterra’s valuation doesn’t look too demanding, especially as the group ended last year with a net cash position:
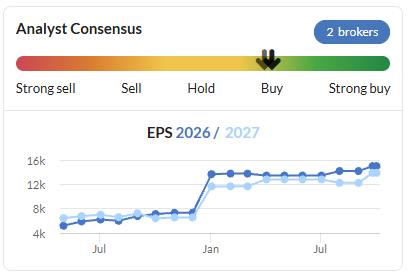
I don’t have any real insight into the outlook for platinum, but I’m encouraged by the recent trend in forecasts and Valterra's continuing Super Stock styling:
I added Valterra Platinum to SIF at 5,090p on 14 July 2026.
Galliford Try Holdings (LON:GFRD)
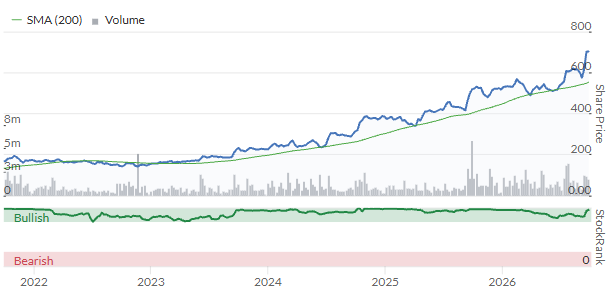
This construction group is one of several in this sector that appear to have broken free of their inconsistent track records to enjoy strong growth and improving profitability. Shareholders who spotted the opportunity early have enjoyed a three bagger:
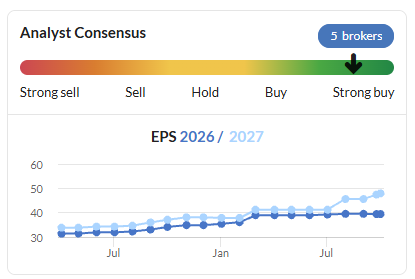
Galliford’s focus on UK infrastructure projects has left it well positioned to benefit from an overdue uptick in spending by water utilities. Earnings forecasts have been upgraded a number of times over the last year:
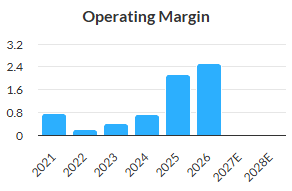
The main risk I can see here is that this remains a very low-margin construction business, with all the risk that entails.
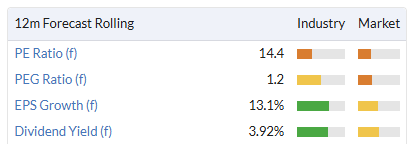
I would generally be reluctant to pay a mid-teens P/E for businesses in this sector, but SIF is a systematic strategy. Sometimes that means buying shares despite feeling unsure about doing so.
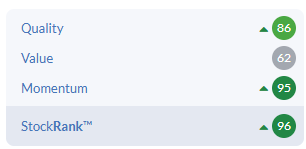
I took an AMBER/GREEN view on Galliford Try in January and would do the same today. The StockRanks also remain positive:
I added Galliford Try to SIF at 615p on 28 July 2026.
Inchcape (LON:INCH)
I’ve been a closet fan of this automotive distribution business for some time, but haven’t found the right opportunity to buy the shares. I’m not sure if this will be the right opportunity either. I guess the outcome will depend at least partly on geopolitics and macroeconomic conditions in the countries where Inchape operates.
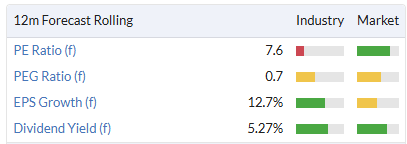
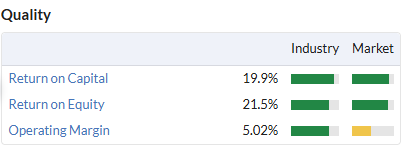
The market has remained relatively cautious about this business, despite a modest valuation and decent quality metrics:
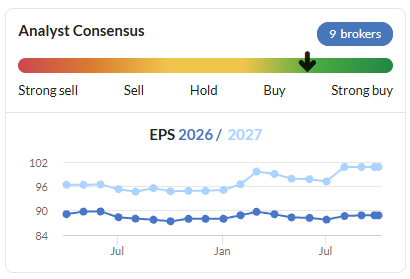
The outlook for earnings is also relatively strong:
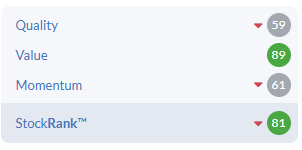
… but the StockRanks are more cautious, applying Neutral styling:
I added Inchcape to SIF at 832p on 4 August 2026.
IG group (LON:IGG)
Ouch. I’m writing this on Friday 2 October, after digesting IG’s unexpected profit warning earlier in the day. For anyone not familiar with the story, Graham’s DSMR coverage is worth reading; he highlights some operational changes that may have contributed to this setback.
My view on IG Group hasn’t changed all that much since I reviewed the shares in July, but I certainly agree with Graham’s decision to move to a neutral view following the profit warning.
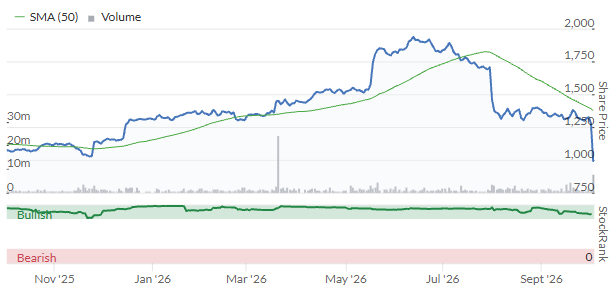
In line with SIF’s profit warning and 25% stop-loss rules, I will be closing this position shortly, although it remains open at the time of publication.
I added IG Group to SIF at 1,377p on 11 August 2026. It will be sold shortly due to my stop-loss rule.
Grafton (LON:GFTU)
This Ireland-based building supplies group is trading well in its home market, where house market conditions are buoyant. The UK is currently placing a drag on performance, but the outlook for earnings growth is still fairly positive:
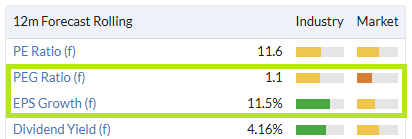
I don’t have a strong view either way here, as I explained in May’s DSMR coverage. However, Grafton seems to be a steady business with reasonable scale, so I’m quite happy to follow my system and see how this position works out for SIF.
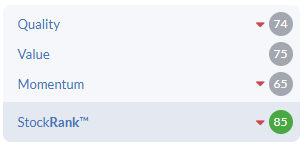
The StockRanks suggest a similar combination of positivity and low conviction:
I added Grafton to SIF at 1,023p on 18 August 2026.
Natwest (LON:NWG)
Have I left it too late to join the interest rate party? The big high street banks have had a terrific run since interest rates returned to more normal levels, as I discussed last week.
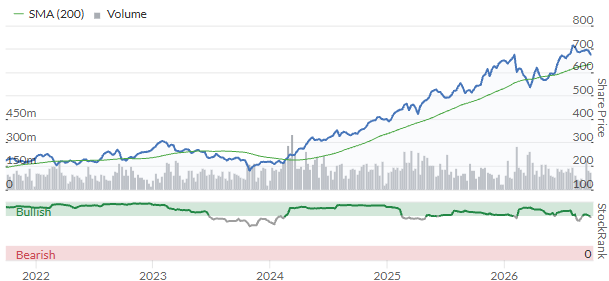
Analysts covering the stock continue to take a positive and improving view of the outlook for earnings:
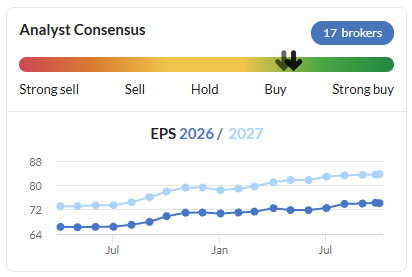
I don’t have the in-depth knowledge required for a detailed review of the business. But as a simplistic yardstick, I would say the current valuation looks either fair or slightly cheap to me:
Trailing 12-month return on equity: 14.1%
Price to book value: 1.3x
Implied return on cost of equity (for new buyers): 10.8%
In theory, I like to target a c.10% return on equity (or better) when buying shares, so I’m comfortable enough holding this FTSE 100 bank at current levels.
NatWest’s 5.7% dividend yield looks fairly safe to me and the bank could benefit from any upturn in the housing market.
On the downside, any major weakness in the UK economy could trigger interest rate cuts and have an adverse impact on both margins and loan performance.
I added NatWest to SIF at 679p on 1 September 2026.
South32 (LON:S32)
South32 is the second big mining spin-off I’ve added to the portfolio in recent months (South32 was originally spun out of BHP). There’s limited overlap with Valterra, though. South32’s focus is on copper, zinc, silver, manganese and alumina – industrial metals for which demand is fairly strong.
The company’s recent full-year results (y/e 30 June 2026) showed an impressive 55% rise in underlying earnings, thanks to commodity price tailwinds:
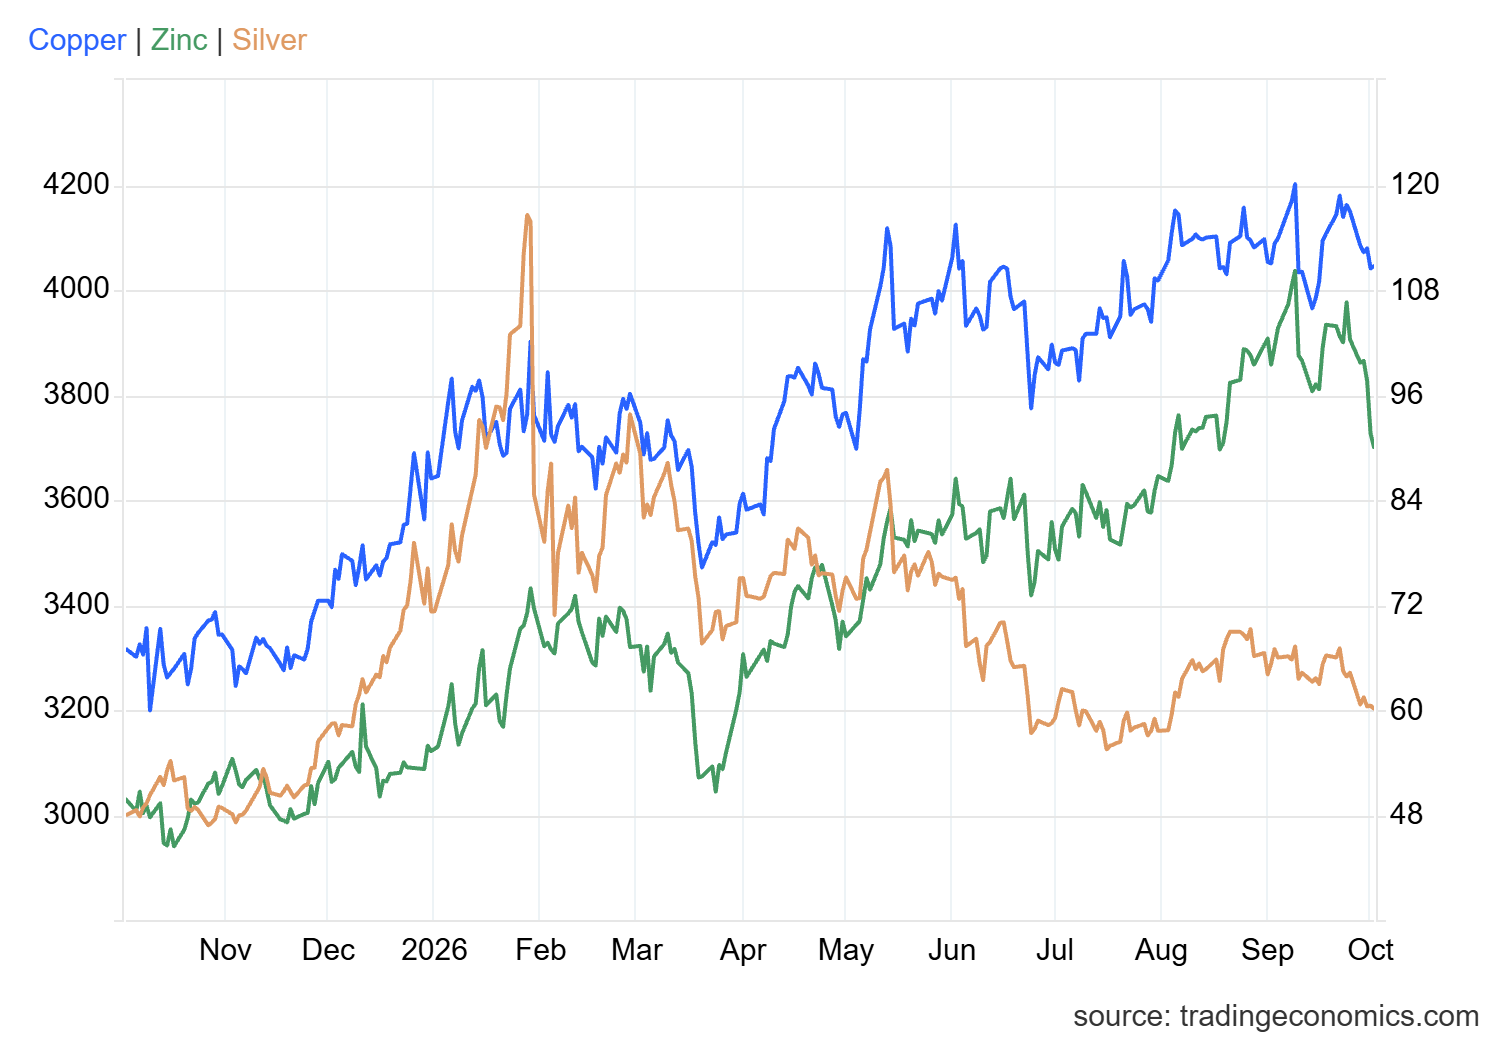
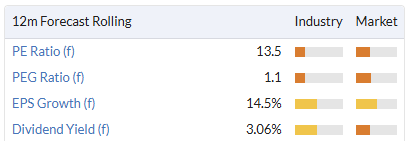
South32’s valuation is probably at the upper end of what I’d want to pay for such a business, but I’m happy to follow the system for now and see what the coming months hold. As I understand it, the supply-demand balance for copper remains fairly tight:
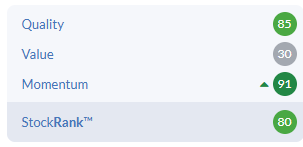
The StockRanks view South32 as a High Flyer, which I think is a fair summary of the situation:
I added South32 to SIF at 2,598p on 22 September 2026.
Sold Stocks in Q3 2026
Here’s a summary of the stocks I sold from SIF during Q3 2026:
Name | Bought / Sold | Income Return | Total return | Reasons for sale |
Endeavour Mining (LON:EDV) | 2,090p on 22 May 25 | 5.2% | 75.3% | Failed momentum rules (price vs moving average, EPS downgrade) |
Personal group (LON:PGH) | 255p on 1 Apr 25 | 13.1% | 71.5% | Failed momentum rules (1yr relative strength & EPS downgrade). |
S&U (LON:SUS) | 1,875p on 20 Nov 25 | 4.3% | 8.7% | Failed F-Score rule and EPS downgrade rule. |
(You can see the rules I use in my selling screen here. To stay in the portfolio, stocks need to pass all of these rules).
Disclosure: At the time of publication, Roland owned all the shares shown in the 30 September 2026 portfolio snapshot.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
the shareprice of Inchcape (LON:INCH) has nosedived recently and there doesn't seem to be any company specific news, just the usual economic headwinds. At some point this will become fantastic value, just don't want to catch a falling knife at this point.
Hi Roland, Just to let you know the links for both the Buying Screen and Selling Screen both show a "410 Gone" error when clicked through.
# SIF screen links #
Unfortunately we're having technical issues including the links to my SIF stock screens in the article, so I have included them here instead:
SIF Buying screen: https://www.stockopedia.com/a/screens/buy-stock-in-focus-sif-113218
SIF Selling screen: https://www.stockopedia.com/a/screens/sell-stock-in-focus-sif-983048
Apologies for any inconvenience, I will update the article when this is resolved.
Roland
link to SIF stock-buying screen just produces a 410 error... try re-linking