Small Cap Value Report (Thu 6 Sep 2018) - MCB, BOTB, FDEV

Good morning!
It's a very quiet day for interesting news today. For newcomers who may not be aware, we normally only cover interesting trading updates & results announcements in these reports.
In response to reader requests, I'll also circle back to yesterday's announcement from Frontier Developments (LON:FDEV) . Searching the archive, I see that Graham has written about it 3 times in the last year. I last looked at it in Sep 2017, and it didn't float my boat then, on valuation grounds mainly. So, once I've got up to speed by reading that lot, and read the accounts, I'll post my latest thoughts here.
Firstly, let's have a quick look at today's trading updates & results in the small caps space.
McBride (LON:MCB)
Share price: 132.5p (up 1.6% today, at 14:30)
No. shares: 182.6m
Market cap: £241.9m
McBride plc, the leading European manufacturer and supplier of Co-manufactured and Private Label products for the Household and Personal Care market, announces its results for the year ended 30 June 2018.
This is another share which has wilted over the spring/summer this year.
Recap - which I might as well type up, as I'm doing the work anyway);
7 Sep 2017: (191p) My review of results y/e 30 Jun 2017. In line results. I disliked: debt & pension-deficit on balance sheet, and H2-weighting comments in outlook section for the new year. It looked decent value though, and had a high StockRank of 95. Seemed a very good turnaround in performance (and share price).
24 Oct 2017 (213p) - I reviewed another trading update, confirming in line with expectations, but again mentioning H2-weighting expected for FY 06/2018. I concluded that it was probably not a bargain, on PER of 14.
We didn't report on it here at the SCVR after that for a while, probably because the company just doesn't interest Graham nor myself. It's desperately dull having to write about companies that you can never see yourself owning. The share price turned south from 8 Jan 2018, falling from a peak of 230p in Dec 2017 to a low of 121p in May 2018.
The chart suggests that the rot set in from 8 Jan 2018, with a lurch down, then establishing a downtrend.
8 Jan 2018 - profit warning, says that cost inflation, margin pressure, and weak trading in one division, means that profits will be "broadly in line with the prior year", instead of growing.so a bit below then. Still saying that new business wins should be positive for H2.
22 Feb 2018 - poor H1 results. Adj operating profit down 31%. No change to full year outlook.
3 Jul 2018 - Graham reported on another profit warning. He's not convinced that the share is yet into value territory, due to heavy debt, and weak performance.
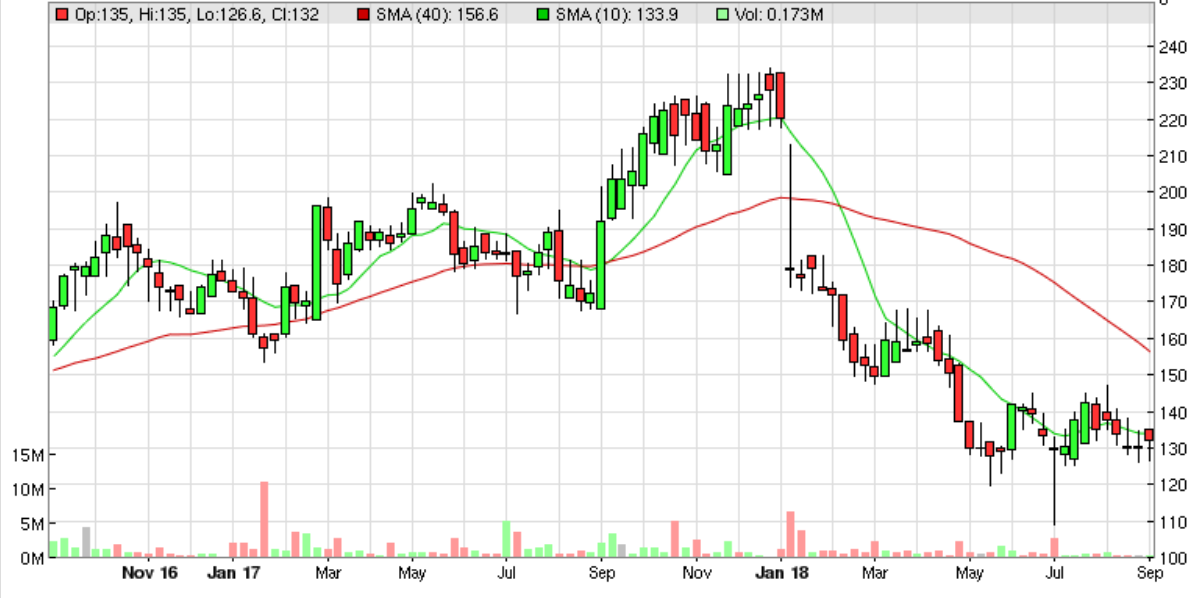
Interestingly, this chart is another good example of where selling on the opening bell after a profit warning would have been the best strategy. That was of course the key message from the brilliant Stockopedia "Profit Warning Survival Guide"
Results today - The above sounds very negative, with the company repeatedly disappointing. So I've been expecting today's results to be dire. Actually, they're nowhere near as bad as I had been warmed up to expect. This is for y/e 06/2018 (continuing operations only);
- Revenues up 9% to £690m (of which only 1.3% is organic growth)
- Adjusted operating profit down 10.2% to £37.7m
- Adjusted profit before taxation down 5.4% to £33.2m
- Adjusted diluted EPS down 4.5% to 12.7p - a PER of 10.4
Hardly a disaster! I'd better check to see if the adjustments look reasonable. Adjustments comprise reversing out amortisation of acquired intangibles of £1.4m, which looks fine, and is not material anyway. Plus £4.8m in exceptional items (see note 4), relating to an acquisition, and re-organisation (closure costs of Hull factory). Overall then, adjustments seem reasonable. Although you could argue that the group is almost constantly reorganising.
Balance sheet - as mentioned above, this has been an area before where I'm not entirely comfortable. Looking at it again today, it's a little thin for a group this size, but overall not too bad.
NAV: £67.6m
NTAV: £37.7m - after deducting goodwill of £20.4m and Other intangibles of £9.5m
Working capital isn't great, with a current ratio of 1.05, and the company relies on bank debt, but I cannot see any reason to think that bank facilities would be under threat.
I've checked the last Annual Report (for 2017), and McBride had £58.6m in land & buildings on the balance sheet, which is usually freeholds. I don't know what the open market value is, but at least the book value of property supports about half the net debt of £114.3m, lowering risk as far as the bank, and investors, are concerned.
Cashflow statement - a few things jump out at me. Firstly, how cash generative the group is - operating cashflow after changes in working capital was £46.0m this year, and £66.3m last year.
The pension deficit consumed £3m in recovery payments each year. The deficit shown on the balance sheet has come down from £42.2m to £30.9m. Progress, but it's still a drain on cashflow.
Interest costs reduced considerably this year, after a refinancing, which is good.
Capex is high though, as this is a capital-intensive business, and has risen to £22.4m (up from £15.2m last year). Unfortunately, this consumes most of the post-tax cashflow, leaving little free cashflow this year, well down on last year. I make free cashflow 2.6p this year, versus 10.7p last year. That's a concern. A mature business like this should be throwing off buckets of free cashflow, but it's not.
Outlook - I was tempted to say that we can't rely on management assurances here, given the consistently too optimistic outlook comments over the last year. Whilst results today may have looked quite reasonable, remember that the forecasts were steadily revised down.
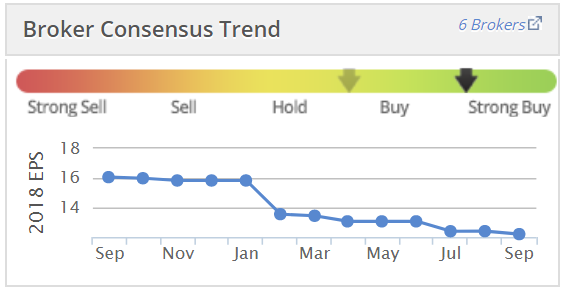
As you can see from the Stockopedia broker consensus chart below, the 12.7p delivered today is well short of the c.16p that forecast this time last year;
I sympathise with management though. Running a group like this must be a nightmare - lots of moving parts, and so many things that could give unpleasant surprises. Plus ruthless customers (supermarkets) constantly trying to squeeze every drop of profit out of their supply chains. The capex planning must take years, to build and fit-out factories. Then anything could change to render those decisions problematic. Yet what's the alternative? If production was outsourced, it would probably cost a lot more, hence profit would disappear.
Anyway, this is what the company says today on outlook;
In the current year we remain focused on the profitable delivery of our anticipated volume growth whilst continuing to take actions to mitigate strong input cost inflation, including commercial price recovery from our customers.
We will also maintain close control of overheads whilst investing in key focus areas that will enable McBride to fully exploit its scale and cost advantage within its supply chain.
Revenues in the first few months of the new financial year have been satisfactory and whilst certain cost pressures persist, at this stage the Board remains confident the Group will achieve its full year expectations.
I view that rather sceptically. The words "at this stage" always ring alarm bells to me. I read that as saying that the risk of disappointment is quite high. Therefore I am minded to take forecasts with a pinch of salt.
Dividends - this looks a bit odd. The company seems to use a convoluted way of distributing dividends. I think we discussed it once before, but I won't do any digging on this, as time has run out today.
In line with the policy on payments to shareholders, the Group expects to distribute adjusted earnings to shareholders based on a dividend cover range of 2x-3x progressive with earnings of the Group, taking into account funding availability.
Following the interim payment of 1.5 pence declared in February 2018, the Board recommends a final payment of 2.8 pence (2017: 2.9p) to shareholders such that the full year payment remains unchanged at 4.3 pence (2017: 4.3p). It is intended this will be issued using the Company's B Share scheme.
That looks to be a yield of 3.2%. Although the "taking into account funding availability" doesn't instil much confidence that the divis are safe!
My opinion - I'm reasonably OK with the balance sheet overall, although there is considerable debt.
Free cashflow is weak, so that's a concern.
Rather than expecting an EPS increase from 12.7p last year, to 14.6p this year (current consensus forecast), I'd be happier working on a range of say 8p to 15p, being my guess of worst to best case scenario. In reality, I have no way of knowing what the outcome is likely to be, it's pure guesswork.
McBride has been restructuring for several years now. At first that seemed to go well, but performance has been less impressive (but far from bad) in the last year. It seems to me that, if management can get the restructuring working again, then the shares could have another run up.
In normal market conditions, I would be tempted to have a little nibble here, opening a small long position. However, with so much macro uncertainty around right now, I'm not interested in taking on new positions unless they're a complete no-brainer. Whereas this one could go either way, in my view.
Generally, I try to avoid suppliers to supermarkets, as they struggle to eke out a living given how cost-conscious the supermarkets are (and have to be, given their own wafer thin operating margins).
So McBride looks potentially interesting, but it's not for me at this point in time.
Best Of The Best (LON:BOTB)
Share price: 260p (up 2% today, at 10:36)
No. shares: 10.1m
Market cap: £26.3m
(at the time of writing, I hold a long position in this share)
AGM Statement (trading update)
This share is very illiquid, due to being tightly held, mainly by management.
BOTB organises weekly competitions to win supercars, and more recently "lifestyle" prizes such as fancy watches, consumer electronics, motorbikes, etc.
Airports - this is traditionally what built widespread public awareness of the company. However, these have become uneconomic, and a hassle to manage. So the company is transitioning to online only. It now just has 1 physical site left, at Birmingham Airport. The declining revenues from physical sites has masked its online growth, which is a potential opportunity for investors.
Current trading - this is for year to date, FY ending 30 Apr 2019, so we're about a third of the way through this FY;
The Group is pleased to report that the positive momentum to the start of the year, reported at the time of the full year results, has been maintained and the Company has continued to make good progress and is trading in line with market expectations for the current financial year.
FinnCap (house broker) notes are available on Research Tree, so I can quantify things easily. We're looking at forecast adjusted EPS of 11.8p. Therefore the PER is 22 times.
Online growth businesses don't lend themselves particularly well to the PER as a valuation measure (which is more appropriate for mature businesses). The reason being that marketing spend is usually the biggest variable cost. That's great because it can be dialled up or down to whatever level management want. Therefore profit could be seen as little more than a policy decision by management.
There's a trade-off between spending more on marketing to generate growth, but lower short-term profits. Or, run the business lean on marketing spend, to generate profits & cash, but see slower growth. The latter seems to be the route favoured by BOTB management in recent years.
I sometimes get frustrated that a business with such great potential isn't growing faster. On the other hand, I have been a grateful recipient of some terrific dividends & special divis in recent years, some of which I have recycled back to the company, playing its surprisingly fun spot-the-ball game online (usually when I get home from the pub!)
The game is cleverly designed so that you almost always get close to where the ball is deemed to be by the expert judges, hence win some of your money back. That keeps you playing.
I interviewed the personable CEO here in Jan 2016, a lot of which is still relevant. I must ask him back for an update interview when the next results come out.
My opinion - a reassuring update today. Based on current growth, I think that at the moment, the valuation looks about right.
It's the upside potential that is more exciting. If the growth rate accelerates, now that management is freed up to concentrate on the online operation only, then the share could re-rate upwards. Being online only can only help in that regard, in terms of market perception.
Maybe management caution, in keeping marketing spend moderate, in order to maintain profits, has allowed them to learn which digital marketing strategies work best, and therefore avoid wasting money with a more profligate approach might have entailed.
I am hoping that a more turbocharged marketing approach, once effectiveness is proven, could at some point transform the scale of this business. It's a global competition remember, not just UK, so BOTB is really only scratching the surface of the potential market.
Overall then, I'm happy to hold for the foreseeable future, and am fairly confident that, at some point my patience should be rewarded - with either faster growth & a re-rating, and/or eventually a trade sale at a premium. There's obvious upside from a bigger gambling company buying BOTB, and then pushing millions of existing customers towards BOTB. Each new customer is almost pure profit, so the commercial logic is very strong.
This share is not for traders, or the impatient!
Frontier Developments (LON:FDEV)
Share price: 915p (up 3% today)
No. shares: 38.7m
Market cap: £354.1m
Frontier Developments plc (AIM: FDEV, 'Frontier', the 'Group' or the 'Company'), a leading developer and publisher of video games based in Cambridge, UK, has published its full year results for the 12 months to 31 May 2018 ('FY18').
These results came out yesterday.
To recap on our previous commentary on the company here, and to get me up-to-speed, here's a review of our previous reviews!
Almost exactly a year ago, I looked at this company, reviewing the year's results, I was impressed by profit growth, but concerned that 76% of EBITDA was spent on capitalised development costs. Hence the operating cashflow of £3.4m looked very poor for the then market cap of £464m. I didn't make a judgement on the business model, but just looked at the numbers.
Graham chipped in with some interesting comments, and a comparison with a US games company, the next day, here on 8 Sep 2017.
Graham wrote about a trading update here on 12 June 2018. He focused on what seems to be the main reason for this share being so expensive - hopes for its new game launch due in summer 2018, called Jurassic World Evolution. Revenue & profit expectations were increased, but still at very low levels considering the huge market cap.
Graham reported here on 3 Jul 2018, on another positive trading update - upgrading expectations again, for the current year (ending 31 May 2019). It's becoming clear to me that investors have very high expectations for future growth in revenues and profit, hence why the share is so richly valued (on historic numbers). Graham also pointed out the huge operational gearing if games publishers hit the jackpot with a successful game, as the gross margin is so high, at over 70%.
That was really useful in improving my understanding of things to date. Remember that Stockopedia members can easily search our archive for previous comments on any company, just by clicking on the "Discuss" tab near the top of any company's StockReport. I don't know if that is available to non-subscribers or not, I imagine not, as obviously this website wouldn't exist without paying subscribers, so they have to charge for something!
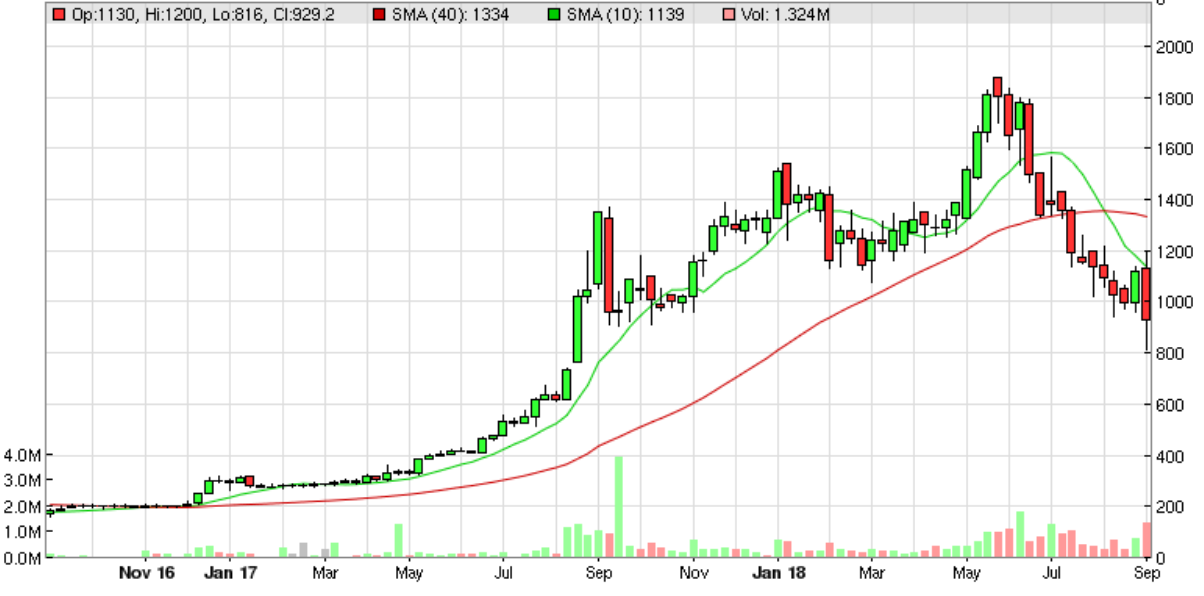
I see that the share price has almost halved from its peak in June. To be fair, lots of highly rated growth companies have had similar sell-offs this summer. There are a lot of punters following momentum-based strategies, and using stop-losses right now. This exacerbates volatility. It has probably also stretched valuations more than usual on the upside (since many buyers didn't care about valuation, as long as the price kept going up).
The problem comes when all those people using the same momentum strategy decide to sell - they're all trying to sell at the same time, creating big moves downwards from the peak. I'm seeing a lot of this at the moment, with loads of shares. Selectively, it's creating some nice buying opportunities. We have to be so careful though, not to catch falling knives, where the share price fall is happening for a good reason (which may not always be apparent until later).
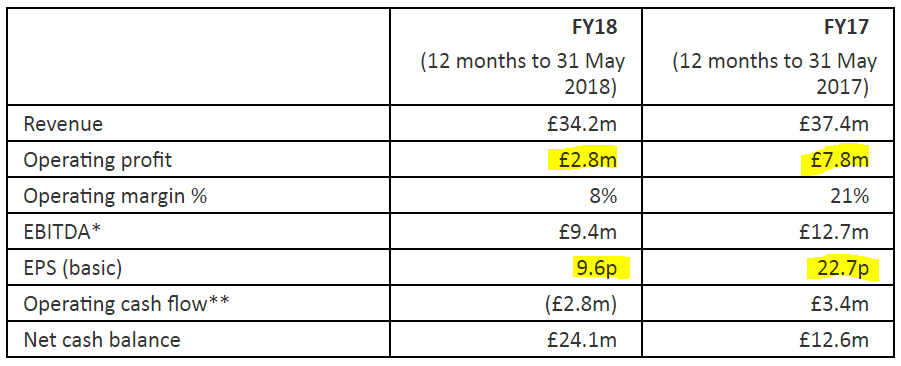
Latest results - the financial highlights look awful, with a big plunge in profit. However, this was as expected, actually it looks better than expected - the update on 12 June 2018 indicated operating profit would be c.£2m. Therefore £2.8m looks a beat. It's still a huge fall from last year, so I'm struggling to see this beat against forecasts in a positive way.
The company says that the fall in profit was due to;
... no new franchise launch in FY18 and our planned increased investment in development and marketing saw operating profit reduce to £2.8 million (FY17: £7.8 million) and EBITDA reduce to £9.4 million (FY17: £12.7 million).
Remember this company is valued at £354m, so these numbers only justify a small fraction of that valuation. The value is obviously more in future expectations, so let's move on to that.
Current trading & outlook - the company makes positive noises about its latest big games release;
The launch of Jurassic World Evolution in June 2018 has led a record trading performance during the period from the year end (31 May 2018).
Digital sales of Jurassic World Evolution have been substantial across all three platforms, (PC, PlayStation 4 and Xbox One) and physical disc sales on PlayStation 4 and Xbox One have also been significant.
On 19 July 2018 Frontier announced that cumulative sales on all formats had passed 1 million units, just 5 weeks after the digital launch on 12 June 2018.
I don't know what level of sales was expected, so cannot assess this unless I manage to find some broker coverage.
More specific guidance is given, which is very helpful;
Although it is still early in terms of both Frontier's financial year and the life-cycle ofJurassic World Evolution, the Board is comfortable with the current range of analyst revenue projections of £75 million to £88 million for FY19 (the year ending 31 May 2019), a substantial increase over the £34 million achieved in FY18.
Directorspeak - self-explanatory;
"Jurassic World Evolution has achieved our biggest launch to date, and we are now very well positioned with three successful revenue generating franchises. We will continue to support and enhance all three of our existing franchises (Elite Dangerous, Planet Coaster and Jurassic World Evolution), and we'll be making a number of exciting announcements about each franchise in due course.
Franchise four, which is based on our own un-announced IP, is now in full development and targeted for release in FY20, and two more new franchises are in earlier stages of development."
I'm starting to understand why this share appeals to some investors here. The company seems to be establishing a good track record at creating games franchises. They're called franchises because a series of new versions are subsequently released, hence games companies can generate multi-year profits from constantly putting out newer versions of popular games.
Valuation - the historic numbers are not really of much relevance, so I think it would be a mistake to over-analyse them. This is often the case with growth companies. People complain that they're ridiculously expensive on historic numbers, but investors are buying the future, not the past. That's completely different to conventional value investing. The big problem with growth company investing, is that we don't know what the future holds, and it can turn out radically better or worse than expected. So high valuations are extremely dangerous if anything goes wrong. Whereas repeated upside surprises can fuel multi-baggers.
Forecasts - there's an excellent update note available on Research Tree (thank goodness we have RT, as without it, post the disastrous MiFID II, we would be almost completely in the dark). I hope people are writing to your MPs, to express your disgust at MiFID II shutting down PI access to a lot of research.
FY 05/2019 is now forecast for a huge jump in EPS from 12p to 43p. There's a difference between the broker's FY18 EPS figure of 12p, to the company's (in the table above) of 9.6p. So it looks like the broker is making some adjustments. Generally I find that most adjustments are reasonable, but I usually check to be sure, before making a purchase.
Assuming that the 43p forecast is achieved, then at 915p per share, the current year PER is 21.3 - which looks fairly reasonable for a growth company.
The only trouble is that computer games have a huge surge initially, and then tail off quite quickly, in sales and profits (until a new version comes out, if the franchise is successful). So my worry is that we could be valuing the shares on peak year earnings, and thereby over-valuing the company?
Forecast EPS for FY20 actually drops quite sharply to 26p, then back up again to 48p in FY21. That makes me nervous. I wouldn't want to be holding the share when investor attention switches from the bumper profits year, to the quieter following year.
My opinion - I've seen enough to feel that it's not for me, as I don't have enough knowledge of this sector to make the accurate estimates which are vital in valuing the shares. Also, I'm really not looking to buy any new positions at the moment, due to uncertain macro conditions, unless I find something absolutely exceptional and/or dirt-cheap.
I can understand why bulls like this stock - it's all about buying into what looks like a talented team, building a track record of creating successful games franchises. This could work out very well long-term, if they continue to execute well.
It's likely to be a bumpy ride though, as valuation is so tricky, and dependent on large, lumpy projects where the costs are all up-front, then sales are difficult to predict. Any company creating a blockbuster franchise could do very well indeed for shareholders. So that's obviously what bulls here are betting on. It might also become a bid target for a larger player?
Given that the share price has almost halved in recent months, then this is probably as good a time as any to get involved, if you missed the original huge bull run. I haven't seen anything in this results announcement to justify the big price drop yesterday.
Could be an interesting punt for the brave and sector-knowledgeable investor?
Right, that's all I can manage for today.
See you in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
(thank goodness we have RT, as without it, post the disastrous MiFID II, we would be almost completely in the dark). I hope people are writing to your MPs, to express your disgust at MiFID II shutting down PI access to a lot of research.
Well, if broker research was always accurate and useful, there would never be any profit warnings as profits would always be 'in line with expectations'.
I reckon a lack of broker research is probably better for PIs -- encourages more independent thinking/research, thus developing your own investing skills, and provides more pricing anomalies.
Just a personal view though.
Paul. Many thanks from me too, for covering Frontier Developments (LON:FDEV)
Been quite a bumpy ride these past two days, to say the least !
The closing SP this week so far (Mon-Thu) has been 1175p, 1060p, 888p and 1010p
More by luck than anything else, my <850p purchase this morning has done ok, and now just about in profit overall.
I'm now hoping we'll have some news before the interims are released early next year - more JWE franchise figures, Tencent distribution, further details on new franchise etc - else this could just drift along (or down).
Thanks to Paul for covering Frontier Developments (LON:FDEV). I would agree that the historic numbers may not be of great relevance but it is worth confirming that the company's track record does show that it has the capability to develop multiple games franchises. Before I bought the shares I also checked management's record and senior management does seem to have plenty of experience and a decent record and the CEO still retains a huge stake in the company. I think the investment from Tencent also helps to validate the competence of the company as well as helping facilitate access to overseas markets. With so few major products, this company is likely to produce a bumpy ride for investors, but providing the next couple of games developed are reasonably successful, then I think the rewards are likely to be substantial.
Sorry for the politics, but if I hear one more call for Boris for PM, I think I may explode!
Hi Trident,
We don't do politics here, this is about small caps.
Let's keep the politics rants on Twitter!
P.
Yes, wrong place, I know for politics! Will stick to howling at the mooooon!
Paul. An interesting article in The Times T2 section by a girl who went to Eton some years back, commenting on a certain swathe of Etonians, who had unerring self-belief and entitlement, a distant sense of what life was like for what the less fortunate, and scathing put down culture for non u types. As she says the ready smirk of BJ arguably betrays his membership of this particular clique. George Osborne also a strong candidate. Also BJ is manifestly useless, but can only hear the clarion call for PM from his arguably deluded promotors.
Late 3pm trading statement from EI (LON:EIG), a very heavily leveraged pubs group at a significant discount to tangible book value. Positive like for likes over the summer, probably unsurprisingly due to the world cup and good weather. Market seems to like the statement - up a few percent following the release. Stocko computers like the stock - SR 97 at present. I hold.
EI (LON:EIG) also mentioned that they are exploring ways to get benefit from the freeholding property which may include selling some or all of the properties.
I think this is the reason for the jump, this is one I have held for several years now in the hope someone will come in with an offer or the NTAV will be realized through a sale
"There are a lot of punters following momentum-based strategies, and using stop-losses right now."
I have doubts about this. My feeling is that most individual investors don't use stop losses. Has there been a survey?
Paul,
Just to expand a little on your Frontier Developments (LON:FDEV) comment:
"They're called franchises because a series of new versions are subsequently released, hence games companies can generate multi-year profits from constantly putting out newer versions of popular games."
Rather than new versions of existing games, FDEV provide DLC (DownLoadable Content) and PDLC (Paid DownLoadable Content). Basically bug-fixes/minor additions for the DLCs and larger upgrades/additions for the PDLCs. They still sell the original game as a stand-alone, but as these PDLCs become available they'll also do a bundle (Deluxe Edition) for gamers to buy both.
Although not a gamer, I'm impressed by their ongoing (social media/forum) rapport with their customers, AND taking onboard their comments/requests. One example being dinosaur sizes on the Jurassic World Evolution (JWE) franchise. Gamers had complained that if they 'created' a PaulyScottySaurus, it would be full size as soon as hatched/born, so they've now upgraded this so the gamer can see it grow to adulthood. The request(s), if viable, can be added to the next PDLC, thereby pleasing the customer(s), who can proudly say "Frontier have created the winged dinosaur range I suggested" etc.
Although now 4 years old, they made this comment in the finals:
"It is worth noting that Elite Dangerous achieved its highest annual revenues to date in FY18 following a successful launch on PlayStation 4 in June 2017."
Yesterday's drop seemed to be partially due to the confusion over if the franchise that should be been their 4th (a licenced franchise), has been delayed or cancelled. An investor who seems quite knowledgeable on FDEV has asked them to clarify this.
£ FDEV
This one seems very interesting, one has to say its a risky business having to continually churn out titles on a regular basis and hope they will deliver. I kind of liked where FDEV were going in that everyone seemed to think it was one new title per year with ongoing income from previous titles etc etc. They seem to have proved they could go up a gear with the latest release.
However as ever the market hates uncertainty and a delay in what was previously planned for so soon into this new plan of attack doesn't help. If it was known this was bond title and release had slipped to match film release (or similar with say Toy story / other known film etc) then that would be neither here no there. The absence of news is not a great sign in this regard as a neutral bod looking in. In some respects delay could keep original schedules going with next one coming along as same time as originally planned so no overall impact other than cashflow etc.
Ok if they have now reverted to "finding" a soon to be released own IP title they didn't previously consider releasing that may work but it deffo sounds more of a plan d type move than plan A.
As a non holder this may be good news as there is short term uncertainty at the same time headline figures aren't great, causing subdued shareprice - great if you want to buy. The financials should show much improved comparatives over the next 6-12 moths so that should help the market perception soon - however thats probably no good if there isnt reasonably good probabability their own IP biggie will delver something decent income wise in the expected timescales.
In summary i can see why the stock is currently rerating from nice growth dependable cash cow deserving premium rating to something with reasonable promise of such but much to prove with possible wobbles on the way - say 12-15 * average expected pe over next 3 years - although i would always be wary about over reliance on projected future growth in earnings over 18 month timeframe unless there is obvious reasons why - eg if they could expand to two big releases per year rather than one.
I would be interested to know what the prospects are for next 3 years if they dont have a biggie in one year - the known for me is what is the bare minimum "tickover" profit can they expect
I have to say having held BOTB shares for at least 4 years I too am frustrated at the liquidity of the shares and although the dividends and special dividends have been good in the past they seemed to have dwindled and better value and liquidity is available else where. I guess this may be due to the ongoing VAT and gambling tax court case. My biggest fear with this company is now that they are a very well established company and have lots of customers who are now nearly solely online as they have been able to dispense with physical sites, the next money saving step may be to take the company private as most of the shares belong to the directors some 74.35% they could just buy back the rest of the company at current prices for about £6.6million pounds, with that in mind I off loaded 30% of my holding last month after the special dividend was paid.
Yes I agree which is why I sold mine some time ago.
Paul, aren't you worried that if the directors thought they could sell the business for a good price to a gambling company they would first delist and buy back the last 25% before doing so?
Re Best Of The Best (LON:BOTB) my worry is different. I think the owners have created a very comfortable lifestyle business for themselves with a good income (especially salary plus controllable divis) and a pleasant working environment - looks fun to run!! I think (fear) they will simply bumble along in a low risk, low key kind of way.
If they sell, then this 'purpose' disappears. Even if they can life on a beach resort for ever this is a bit dull once you have run a business. So only if they get a shockingly large offer they feel they have to accept will they act - nice thought but in my view unlikely.
Risk then is complacency. How big is the moat if a big gambling company or a more drive entrepreneur set up from scratch a rival competitor and spent the money on organic growth vs buyout? Then suddenly a lot of value could be lost. As an ex FMCG marketeer, I am not convinced by the marketing savvy of the company - it has dabbled in a lot of media and is still a bit clunky.
Net, I have held BOTB for several years now as I can see the business potential but I am not sure management's interests are aligned with mine.
Not everything is about maximising profit for SME business owners.
Hi Paul. Welcome back and thanks for all the great analysis already. I too would be very grateful if you were able to take a look back over Frontier Developments (LON:FDEV). I see this as a potentially great long term investment but I'm trying to understand if the SP drop yesterday is a great entry opportunity or simply the market getting realistic about the next few years of potentially reduced margins and operating profit as a result of increased development and marketing spend on the upcoming franchises.
Avation (LON:AVAP) issued their prelims this morning. My diatribe can be read here: https://www.stockopedia.com/content/avation-prelims-30-june-2018-396679/
Prelims: https://www.investegate.co.uk/avation-plc--avap-/rns/prelim-financial-results-for-2018-year/201809060700019215Z/
Bottom line. No surprises. NAV increased to 276p. Share price 229p
As always thanks Carcosa for your in depth and valuable contribution.
I am a long time holder of AVAP and added more earlier this week as it's long term prospects continue to look good.
MPAC (LON:MPAC) H1 Resuts.
The emphasised profitability metric is "underlying profit before tax" which is breakeven. This underlying figure excludes pension operating costs that recur each year and so I don't think it is a suitable metric (but not as bad as Beeks Financial Cloud (LON:BKS) emphasising EBITDA the other day).
It seems that problems with two "legacy" contracts are unresolved and ongoing with no end in sight.
They have an IAS19 pension surplus on their UK scheme, but different assumptions used by the pension fund mean the triennial valuation currently being carried out is likely to produce a deficit in the order of £40m. This is more than 10 years of recovery payments and so I can't see these being reduced in the near term. After much consideration it is my view that the triennial valuation is much more relevant than the IAS19 one.
The cash / enterprise value shown on Stockopedia won't have been updated with the new figures that are £25m, down £4m. (To be clear, very little of this is cash "burn", most is likely one-off working capital changes and pension payments).
With cash of £25m, little in the way of other assets, a pension deficit in the order of £40m UK + £5.8m US, and no profitability in sight, for me they are currently uninvestable. However the situation could start to look very different in 3-4 years time with next triennial pension valuation, potentially reducing pension recovery payments and underlying profitability. I wish them well.
Paul, if it is a quiet down for announcements is there any chance of circling around to yesterday and reviewing the results of Frontier Developments (LON:FDEV) and the dramatic share price fall. I was researching them yesterday and added them to my watchlist. I don't normally look for bounce back shares but I wonder if this could be a golden buy opportunity for a 2-3 year horizon?
Wildshot, Certainly the Frontier Developments (LON:FDEV) Director who bought £50k yesterday must think so. ADVFN speculation is that the franchise that was replaced by an in-house title for 2019-20 was Bond, given that the film has apparently been pushed back. If true, of course they'll never beat Goldeneye on the old N64! :-) I hold.
Hi Wildshot,
OK, there seems to be reader interest in Frontier Developments (LON:FDEV) so I'll circle back to it today, as very little interesting results/trading updates were put out this morning.
Regards, Paul.
Many thanks Paul.
Another 'Thanks Paul' :o)
I'll be interested to read your analysis, and see if your views have changed (for better or worse) as you've covered Frontier Developments (LON:FDEV) before.
I doubled up yesterday morning, then put a limit buy-order in when the SP continued to drift down, expecting it to expire at market close, but instead it continued for today and got dealt this morning. So I've now 3x my initial July purchase. Doh !
My morning smallcap tweet:
Aquis Exchange (LON:AQX)
Aquis Exchange (AQX) wins contract for trading technology for an institutional-grade crypto exchange. Launches H1 2019. No numbers.
Morning, just read about Immotion (LON:IMMO) in your deadly rival Shares magazine. VR experiences in malls etc. Could they be the new Escape Rooms or is it just another puff piece? Certainly I seem to have missed the post-IPO 40% odd spike and it's down near launch price of 12p. I wondered if any readers had opinions on this. Might pop into the Manc one next week. Cheers! https://www.sharesmagazine.co.uk/article/immotion-looks-to-put-some-magic-into-leisure-and-shopping-centres
whats your general take on the markets at the moment. Emerging markets seem to be in a lot of trouble with South Africa markets now entering a official recession.
One thing I noticed is the Russell 2000 (US small cap) is holding up well with US small caps doing extremely well compared to rest of market.