Daily Stock Market Report (Wed 24th December 2025) - GMS, LIT, RGL

Good morning and Happy Christmas Eve. This is likely to be an abbreviated report, with markets closing at 12.30 today for Christmas.
Recommended reading: the end of the year is always a good time to take a look at what's worked over the last 12 months -- and what hasn't. Ed and Mark have already been publishing on this topic in recent days. I'd recommend taking a look at these articles if you haven't already seen them:
- StockRank Review of 2025: Ed looks at the winners and losers from the year
- My biggest mistakes of 2025: Mark takes a critical look at his investing results from the last 12 months
- A year in value: was 2025 (finally) the year when buying the cheapest stocks proved to be a winning strategy?
Looking ahead, our 12 Stocks of Christmas series will kick off on Christmas Day with the first of 12 Super Stocks we think look interesting for 2026. You can read my recap of last year's selection and learn why we're changing the rules slightly here.
Today's report is now complete (11.30).
The DSMR will take a break now and will return on Monday 29th, when markets reopen. Happy Christmas!
Spreadsheet accompanying this report (updated to 24th November): link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
BP (LON:BP.) (£66.8bn | SR87) | Agreed sale of a 65% shareholding in Castrol at an enterprise value of $10bn (EV/EBITDA of 8.6x). Net proceeds to BP will be c.$6bn, will be “fully utilised to reduce net debt”. | ||
Supermarket Income REIT (LON:SUPR) (£993m | SR81) | Three UK supermarkets at an average net initial yield of 5.5%. One from each of Tesco, Sainsbury’s and Waitrose, all with 10-year+ unexpired leases. | ||
Gulf Marine Services (LON:GMS) (£209m | SR73) | Agreed contract for Large-Class vessel in Middle East, spanning two years inc. options. Correction to yesterday’s contract details: duration should have been 1,624 days inc options, not 985. Zeus broker forecasts unchanged. | AMBER/GREEN (Roland) GMS seems to be gaining new momentum on contract awards after a slower spell this year that was perhaps partly due to geopolitical pressures. I’ve updated my chart showing the development of the group’s order backlog and estimate that it’s now close to previous highs once more. Continued deleveraging could support a return to shareholder returns next year and has de-risked the equity in the meantime. With a c.30% discount to book value even after this week’s gains, I’m happy to maintain a moderately positive view. | |
Regional REIT (LON:RGL) (£162m | SR58) | 3yr extension to debt facility that was due to mature in Aug ‘26. Outstanding balance reduced from £128m to £72.4m through debt reduction. Cost will rise from 3.4% to 4.1% when existing hedge expires. | AMBER (Roland) [no section below] Today’s news from this commercial property REIT appears broadly positive, as do recent disposals and revised management fee levels. However, November's Q3 update flagged up occupancy in RGL’s portfolio of just 76.8%, suggesting to me that further progress on disposals and/or new lettings remains a priority. For now, the dividend supports a 10% yield and appears to be covered by forecast earnings. With the stock also trading at c.50% below book value, I can see there could be an opportunity here. I don’t have the insight into RGL’s portfolio needed to form a strong view, but I do think it could be worth further research for investors with an interest in this sector. I’m taking a neutral view today to reflect this. | |
Roadside Real Estate (LON:ROAD) (£103m | SR33) | £17.8m acquisition of Gardner Retail, a portfolio of six petrol stations in south-west England. Purchase valuation is 8.5x EBITDA. | ||
Defence Holdings (LON:ALRT) (£40m | SR18) | Has agreed the appointment of a CEO subject to checks. The appointee is not yet being named. | ||
Tungsten West (LON:TUN) (£21m | SR16) | Completion of updated feasibility study. Begun project financing process. Cash reserves of £1m at 30 Sept, material uncertainty regarding going concern. | ||
Celsius Resources (LON:CLA) (£19m | SR24) | Has received interest in financing MCB Project from several international mining groups. Appointed financial advisory firm to assist with process. | ||
essensys (LON:ESYS) (£10m | SR24) | Bid discussions with Mark Furness remain ongoing (see here). PUSU deadline has been extended to 5pm on 23 Jan 26. | PINK | |
Litigation Capital Management (LON:LIT) (£10m | SR23) | Following an unsuccessful claim, an Australian court has awarded costs totalling AUD32.4m to against LIT [corrected]. The company has an exposure of AUD12.9m following insurance and investor contributions. LCM is appealing against the judgement. | RED (Roland) This litigation funder has suffered a(nother) significant adverse cost award. Given that the June 2025 accounts already included a material uncertainty warning relating to the group’s debt situation, I see this as particularly bad news. While the June balance sheet showed net assets of over AUD100m, this figure is stale now and relies on these investments (legal cases) generating positive outcomes. I have no way to know how likely this might be nor which investments have now been realised through recent rulings. While the company is still holding out some hope of finding a buyer, I think there’s a risk this could be a zero for equity holders. In my view, the most likely outcome of the ongoing strategic review might be that LIT’s lenders take control of the business in order to secure maximum value from the company’s current run-off strategy. |
Roland's Section
Gulf Marine Services (LON:GMS)
Up 4% at 19p (£216m) - Contract (and correction to yesterday’s contract RNS) - Roland - AMBER/GREEN
Today’s contract award RNS is the second contract update in two days from jackup rig operator Gulf Marine Services. There’s also a correction to yesterday’s RNS.
You can see my comments on yesterday’s update here. However, as bohenie has pointed out in the comments this morning, these updates haven’t been written as clearly as they might have been.
Here’s my summary of the news, as I’ve understood it:
23 Dec: 2x Large-Class vessels hired in Europe for 1,624 days, including optional extensions (approximately 26 months per vessel). This was incorrectly stated as 985 days in yesterday’s RNS.
24 Dec: 1x Large-Class vessel hired in the Middle East for two years, including options (730 days)
These two hires take the total additional contracted backlog announced this week to 2,354 days.
In effect, this means that three of the company’s five Large Class (formerly E Class) vessels are now on contract for at least the next two years, including options.
Order backlog: yesterday we learned that the group’s contract backlog had recovered to $540m.
The company hasn’t provided a further update today, but based on the $35k average day rate reported in H1 (across all vessel types), I estimate a further addition of at least $25m is likely today – presumably more, given this latest contract is for the largest class of vessel.
Updating the chart I’ve shared previously using yesterday’s company-reported figure and my conservative $25m estimate shows that Gulf Marine’s order backlog is now approaching new highs again:
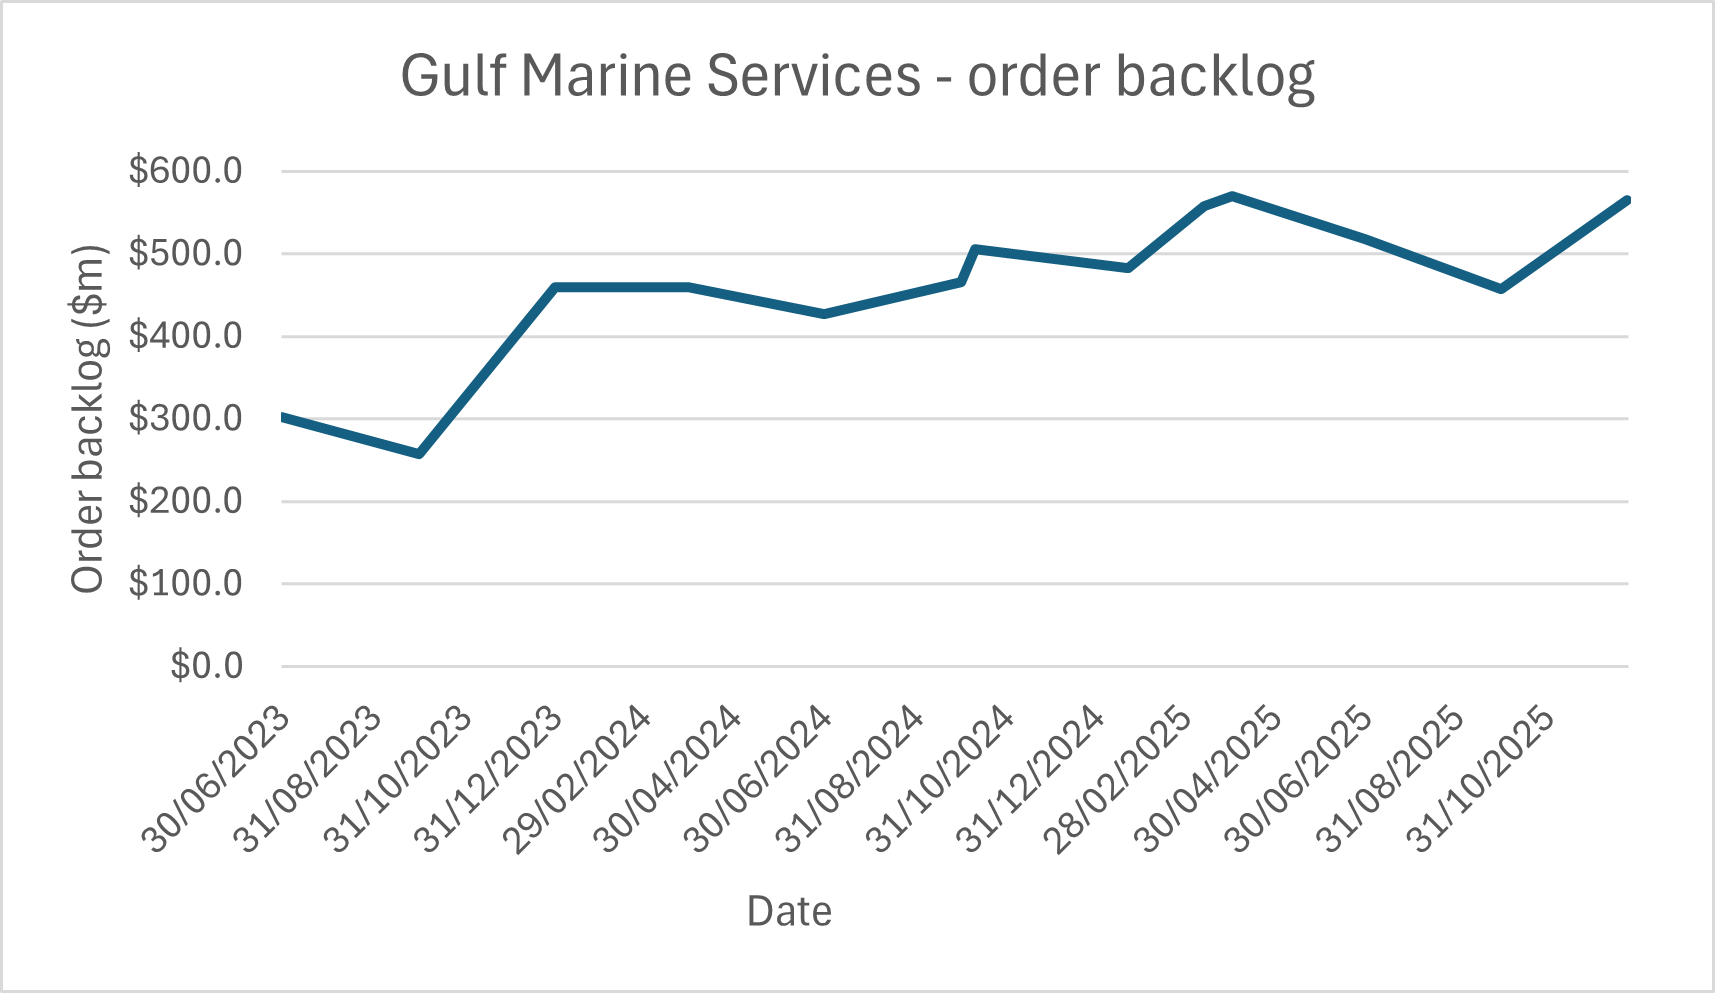
I’ve previously commented on the declining backlog reported between February and September, but this no longer seems to be an issue. I wonder if it might have been due to geopolitical factors rather than any weakness in underlying demand.
Broker forecasts: house broker Zeus has left forecasts unchanged once again today. This perhaps suggests that these contracts are largely within its existing estimates for 2026, which already show a significant recovery in earnings after a cut to expectations earlier this year:
FY24 actual adj EPS: 3.4c
FY25E adj EPS: 3.3c
FY26E adj EPS: 3.9c
Roland’s view
The obvious question here – so far unanswered by the company – is over its plans for fleet replacements or expansions. GMS took one leased vessel onto its books this year to meet additional demand, but other than this there’s been no change.
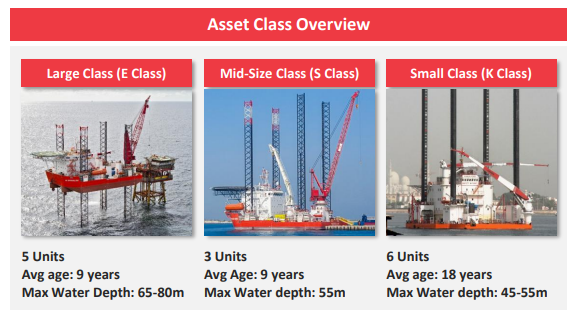
In fairness, replacements are probably not a pressing issue yet. The company’s two largest classes of vessels have an average age of under 10 years. It’s only at the smaller end of the fleet where the average age is higher, at 18 years. This snapshot is taken from the Q3 2025 update:
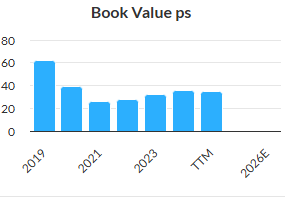
For now, the focus remains on deleveraging, with a return to dividend payments and/or share buybacks planned when net debt/EBITDA falls to 1.5x. That’s expected to happen in 2026. Deleveraging in this way has supported a recovery in book value and de-risked the investment.
I upgraded my view from neutral (AMBER) to moderately positive (AMBER/GREEN) on the strength of yesterday’s update.
Gulf Marine’s share price has now risen by around 15% this week, reducing the scale of the discount to book value on offer:
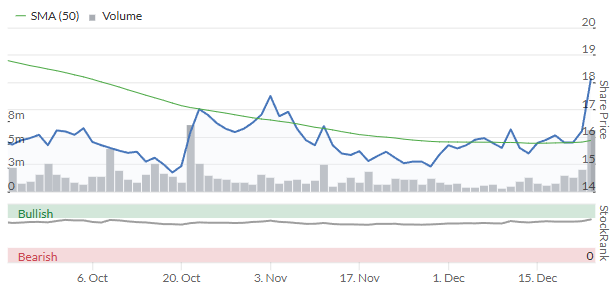
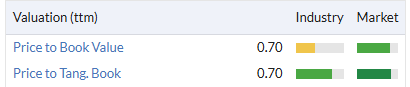
However, at 18p the shares are still well within the 15-20p range where they’ve traded for much of the last two years and are around 30% below their last-reported book value of 26p per share.
With evidence of improving momentum and continued deleveraging, I think there’s probably some value here and am maintaining my AMBER/GREEN view on this stock.
Litigation Capital Management (LON:LIT)
Down 16% at 7.2p (£8.6m) - Adverse Costs in Class Action Investment - Roland - RED
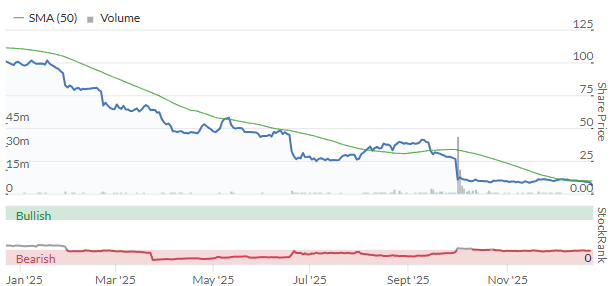
This Australia-based litigation financing specialist has had a bad year:
Litigation financing is not a sector we cover very often, due partly to the difficulty in understanding the prospects or likely value of a company’s investment assets – the legal claims that it’s funded.
When Graham last covered Litigation Capital Management in February, he noted that the stock might be trading at a discount to book value but commented that “it’s not easy for me to trust the valuations of legal cases”.
Events since then have proved the wisdom of this view. Litigation Capital Management has reported a number of adverse legal rulings this year, leaving it exposed to significant cash outflows and investment losses.
Strategic review: the company launched a strategic review in September to consider the possibility of a sale and confirmed that in the meantime, it was transitioning to a run-off model “to realise value for shareholders”.
Material uncertainty: unfortunately, October’s full-year results also included a material uncertainty warning that prompted house broker Cavendish to withdraw its forecasts:
Given the number of adverse case outcomes in recent months, which have impacted cash inflows and increased indebtedness, the Directors have considered a range of scenarios, including plausible downside scenarios, and note that in certain circumstances, further case losses could lead to a breach of LCM's debt covenants.
In its results, the company noted that it was in discussion with its lenders, whose current intention was to remain supportive while LIT completed its strategic review.
Further adverse rulings: today’s update seems likely to add significantly to the financial pressures on the group.
The company’s claimants have been unsuccessful in another Australian legal case known as the QLD Electricity Claim.
The Federal Court of Australia has required the claimant to meet the costs of the defendants, which total AUD32.4m.
LIT has insurance in place which will reduce this liability to AUD19.9m.
This case was co-invested with investors in LIT’s Fund 1, who will cover a further AUD7m.
This leaves LIT exposed to a payment of AUD12.9m.
The company is appealing this judgement and is also considering the possibility of a separate appeal “against the quantification of these costs”. According to CEO Patrick Moloney, this was a very complicated situation:
This is a very expensive and complicated piece of litigation which has resulted in large cost orders in favour of the respondents. This quantification was of ordinary and not indemnity costs orders and so are not a reflection of the conduct of the claimant or LCM or of the strength of the claim.
The comment above only highlights why I personally avoid this type of business. There is simply no way I can understand the potential value or likelihood of success of any of LIT’s investments. It’s entirely a black box, requiring me to trust management judgement.
Roland’s view
Litigation Capital appears to be in a difficult situation. I think there’s a risk shareholders could end up with a zero if the company isn’t able to generate some positive cash flow fairly soon.
While the company reported a balance sheet net asset value of AUD114m at the end of June, this was supported by investments (legal cases) valued at AUD172.8m. These were offset by AUD77.7m of borrowings.
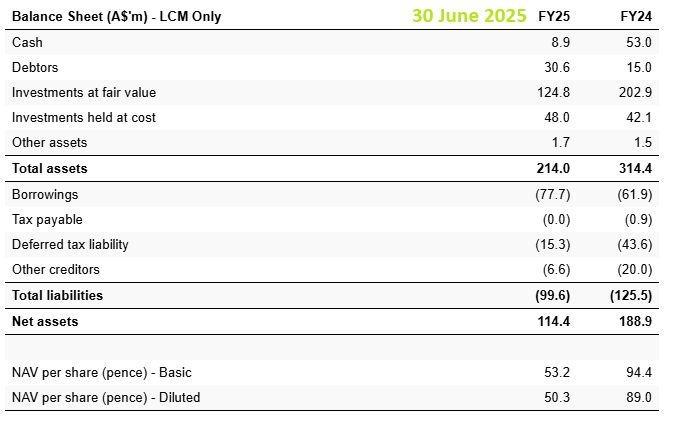
Although these accounts are now nearly six months old and therefore quite stale, the figures do suggest a big discount to book value.
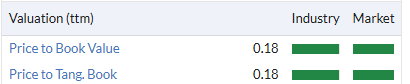
In reality, I suspect any discount is much smaller and may be difficult to realise.
The reason for this is that LIT’s investments are illiquid and subject to a wide range of valuation uncertainty.
The group’s debt, on the other hand, is very certain and subject to lending covenants. If the company can’t generate a positive cash flow from its overall investment portfolio, it’s left at risk of being unable to service its debts. That seems to be what has happened this year.
The shares have now fallen by over 90% this year. Today’s drop means the market cap has fallen below our £10m limit.
I also note that interim results for the six months to 30 June 2025 haven’t been published yet. If LIT doesn’t issue these results by the end of December, its shares will be suspended.
Our coverage will probably terminate here unless LIT delivers a surprise recovery.
In my view, the opaque nature of the group’s assets and its mounting debt liabilities means the most likely outcome now may be that LIT’s lenders assume control of the business, wiping out shareholders. I see this as a stock to avoid.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Happy Christmas everyone.
https://youtube.com/shorts/nrz...
Not a xmas review by me (although I have underperformed the indices since the new tax year).
I took a look through an old notebook, and came across a note I made in 2013:
Joel Greenblatt: Apple and Google are bargains. The biggest bargains are in large cap. Short JC Penney because they're eating cash. Based on free cashflow yields we're in the 68th percentile of cheap over 25 years, from which year-forward returns have averages 13-15% for large caps. The small cap is towards the 33rd percentile, implying a return of about 8%.
I found that note quite interesting, because he spelled out how it all played out. US large caps are now at the very high end of valuations. You'll see many fund managers showing that, historically, implied future returns on US large-cap are about -2% to 2%, maybe a little higher depending who you ask.
I pointed out to my mate Dave that Apple's net revenues in 2021 was $365b. 2025 was $416b. That's a growth rate of 3.3% pa. It's not a rapid-grower. Yet it trades on a PE of 37.
Good company, but can anyone seriously it's undervalued?
I took a look at what I considered 10 high-quality UK mid-caps, and compared them to 5 years ago. There's arguably a lot of statistical problems with my approach, but bear with me. You would have returned 66% over 5 years (exc. divvies), compared to the FT250 of a meagre 7.8%.
It gets better, though. If you invested in the companies that had less than the median P/FCF, that return would have jumped to 126%.
P/FCF now looks to be about 60% of 5 years ago (on a median basis), or about half on a mean basis. So valuations are more compelling now than 5 years ago.
To give some context, if you had invested in ALFA 5 years ago, you'd be up 103%. Its P/FCF was 23.4 then, and 24.2 now. MGNS returned a whopping 208%. It had a P/FCF then of 8.5, now 17.4. On the "disappointing" end is IGG, which is up 49%, which drags the mean down a little, but still beat the FT250.
Some disappointers where KNOS (down 19%), GAMA (down 44%), and AJB (down 2%). What is notable about them is that there were on high initial P/FCF. KNOS of 74, GAMA on 48, and AJB at 74.
Anything that caused them to wobble saw their valuations, and hence share price, punished.
Their multiples are much more sensible now, so they're in with a shout wrt future performance.
So there we have it. Buy quality and growth at reasonable prices. You should be in a better position to do it now than you could have 5 years ago.
Merry xmas!
Morning folks. I posted a platinum market summary from my substack here: The Platinum Setup: A Classic Asymmetric Trade Hiding in Plain Sight | By jamesalastair | Stockopedia
The Managing Partner of US Real Asset hedge fund Massif Central, Will Thomson, has agreed to let me publish some of their research on my Substack (Alastair Kendall | Substack). Will wrote two really deep and insightful pieces on TSE-listed Lundin Mining who are developing what I consider the World's most exciting copper mine in a JV with BHP on the Argentinian-Chilean border. Will also sent me an interview he did with the CEO which I will publish a link to. Lundin Mining (TSE:LUN) is a big holding in my portfolio.
Will has also offered an interview, but I am still thinking about it as it is not really my gig ... I am just a dilettante farmer living up a wet and windy glen. I am wondering if I should reach out to Paul Hill who does a fine professional interview.
My plans are to research and publish something in the New Year on:
1. Drone market
2. Space and satellite market
3. Modernising the Grid
4. Rare Earth metals and European and US critical mineral supply chains
5. Deep dives into some of the individual real asset and mining stocks I hold.
If any of this is useful, consider reaching out to your local SSAFA, or Erskines branch to give some time or even a small Christmas donation. My branch is here: Inverness-Shire & Western Isles | SSAFA but it is always better to reach out to your local branch. They will be delighted to hear from you.
Finally, thanks to all the staff at Stockopedia and everyone who contributes to discussions. The work ethic and reliability of the Stockopedia team are extraordinary. I read everything every day and the Stocko community is a regular part of my daily routine.
Happy Christmas to you and yours.
Alastair
Hi James and thanks for the work you are doing and making available - it's where the greater profits will be coming in the future. And thanks also to the whole Stocko community.
Re SSAFA I worked with them for well over 10 years as a volunteer visiting ex service families to provide funds where needed. Was very rewarding for me also, only retiring this year as I felt it needed a younger generation to take over and cope with the increasing bureaucracy, which has taken over.
Thank you Bohenie. I am finding writing injects some discipline and structure into my investing and I am hoping, the deeper understanding it forces upon me will help improve my investment performance.
The strategic changes at SSAFA have certainly generated differing views. My own view is that if the RO handle the almonisation process, it frees up more time for me and my colleagues to spend time in the community of veterans and serving men and women and their families which is where we add the most value. For example, we are now working more closely with 3 Scots and are in the process of opening a part time manned office at Fort George which all requires resource which all charities are struggling to find and retain. I am 62, so won't be doing this for ever, but I would like to think, God willing, they get another 8 years out of me!!
Thank you for your hard work on this. I will be investigating platinum this week.
Good luck Epitychia.
I think Platinum has a long way to run given the squeeze the Chinese have put on the market. It is one of the few markets where the miners and refiners are integrated and the Chinese do not control the supply chain. Instead you get to invest in miners in a country which produces 80% of platinum concentrate and where AK47 armed gangsters control the electricity and water supply.
The Chinese launched a new platinum futures market in Guangzhou last month .
Trading on the GFEX is expanding at an explosive pace, with contract volumes now large enough to influence global platinum prices and help drive the metal to multi‑year highs. COMEX remains the international benchmark, but GFEX has rapidly become a price‑moving venue in its own right, fuelled by industrial hedging demand and the ability to discover and hedge prices in Yuan. Physical delivery is restricted to Chinese‑registered entities. The opportunities for arbitrage between Guangzhou and COMEX is limited due to the differing structure of the platinum contracts.
Crucially, this is China’s first platinum futures contract that permits delivery in sponge form — the powdered, porous material produced through chemical refining and used directly by catalyst and industrial manufacturers. That feature alone explains why industrial buyers are flooding into the market.
I always follow the futures markets on COMEX, Chinese markets like Guangzhou and the Shanghai Gold market and of course dear old LME. You also need to follow the development of new mines because as we all know the cure for high prices is high prices. I am thinking Ivanhoe's new Platreef mine in South Africa which is forecast to supply 10% of all PGMs at full belt, will be the pin to prick the platinum price bubble.
Good luck.
Thanks, this is very useful.
Wow! Mr Alastair and Mr Charles can move markets. Will need to pay more attention.
Haha ... that made me laugh Harry!
Roland, shouldn’t your summary say costs were awarded against LIT?
Morning FREng,
Thank you for pointing this out, it's corrected now.
Roland
Roland,
When you publish the 12 Stocks of Christmas, please could you also suggest some that would be of interest for 2026? Ho ho ho!
Morning John O'Gaunt,
You're right, that would probably be a good idea!
Roland
Does City of London Investment (LON:CLIG) invest in silver, gold, precious metals, defence, energy, power?
Don't mean to be negs, just need focus on 'momentum' sectors, something have interest in, and maybe knowledge. Pharma is hot but between regulation, lawyers, scams, have no idea unless someone inside. Finance will be disrupted by blockchain so banks etc are no no.
I think the US will have a good 2026 up to Q3 (Trump will make it so) then "get the hell out". Whether I keep to that 'rule' unlikely - the biggest problem to an investor is him/herself.
Merry Christmas to all at the Stocko team! I am a new subscriber this year and have immensely enjoyed the daily commentary. Looking forward to what the new year brings.
Pleased to see the conclusion of the major loan refinancing at Regional REIT (LON:RGL) on reasonable terms. Hopefully this will be reflected in the share price this morning. RGL is a recent buy for me locking in a near 10% yield.
And if you haven't, do check out the Investment Trust thread, where Charles Mitchell and I have commented on Regional REIT (LON:RGL) . We believe it has bottomed out, and I'm glad to see it's lenders appear to have too. Added 27% to our family holdings yesterday, so I would say that!
Thanks raggedtp. I do look in from time to time but haven’t contributed.
Gulf Marine Services (LON:GMS) - Can anyone make sense of the RNS today and was that really a typo yesterday or what ?
Only in that maybe the 985 day figure was the previous cumulative figure before this contract award, and that this figure was out by 639 days and should have read 1,624 days. (Some typo!). Because when you add this new contract of 2 years including options (i.e. 2 x 365 days = 730 days) on to the previous total of 1,624 days this equals the 2,354 days (1624 +730) they state for the additional days they have announced recently.
Whatever we just have to accept they made a mistake and that they are still picking up useful contracts which augers well for the future.
Thanks Marcus - well the Mkt has accepted this with small rise today and also SRT Marine Systems (LON:SRT) another company with specialist vessels Ho ho
So that's another vessel in the middle east, in addition to yesterday's two in Europe. Yes, odd typo, it's not like they transposed two figures!
Merry Christmas to one and all. I’ve had a very good year in the market and I’m looking forward to 2026 with confidence.
Thanks to all at Stocko and to all contributors on here for making this such an excellent source of information and helpful opinion.