Small Cap Value Report (Wed 25 Sept 2019) - SOS, BOO, TMMG, UNG, HRN, NET, CAR, SDI, CARD

Good morning, it's Paul here today.
Estimated completion time - probably about mid-afternoon. Update at 15:36 - as usual, it's taking longer then expected, so I'll keep going until early evening.
Update at 18:09 - today's report is now finished.
Sosandar (LON:SOS)
(I follow this company closely, as it's by far my largest holding in my SIPP. Obviously just skip this section if it doesn't interest you)
Digital ads - I wasn't able to get any photos of Sosandar's digital ads in selected tube stations in London (see Monday's SCVR). So I contacted the company's PR, to ask for some photos, and more info, see below.
Sosandar's digital ads are shown at selected tube stations in London, during commuter hours, morning & evening, on weekdays. I visited a couple of tube stations at around 3:30 pm, hence why their ads would not have been showing at that time.
Here are a couple of photos sent to me by the PR co at my request;
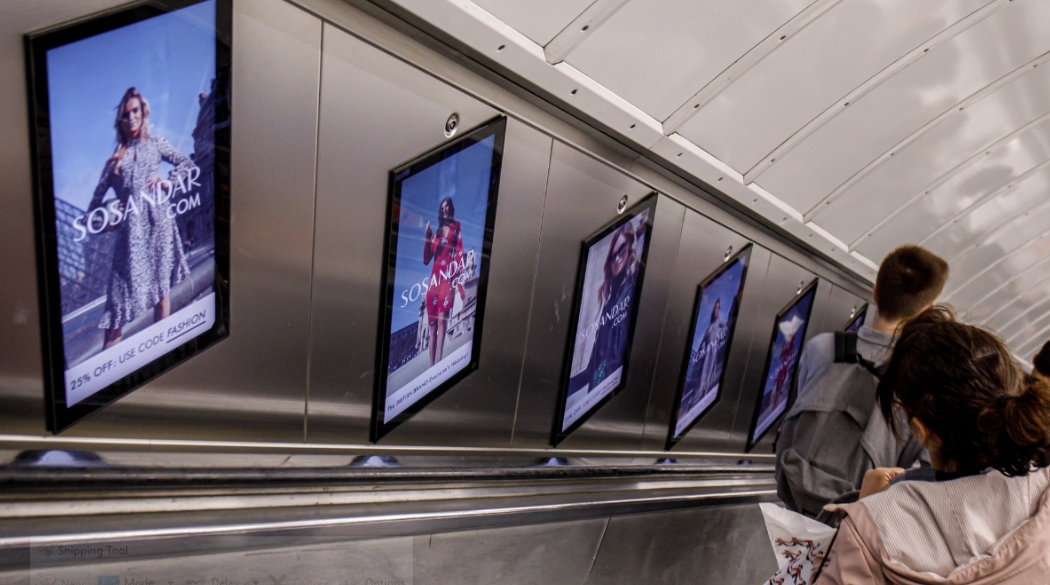
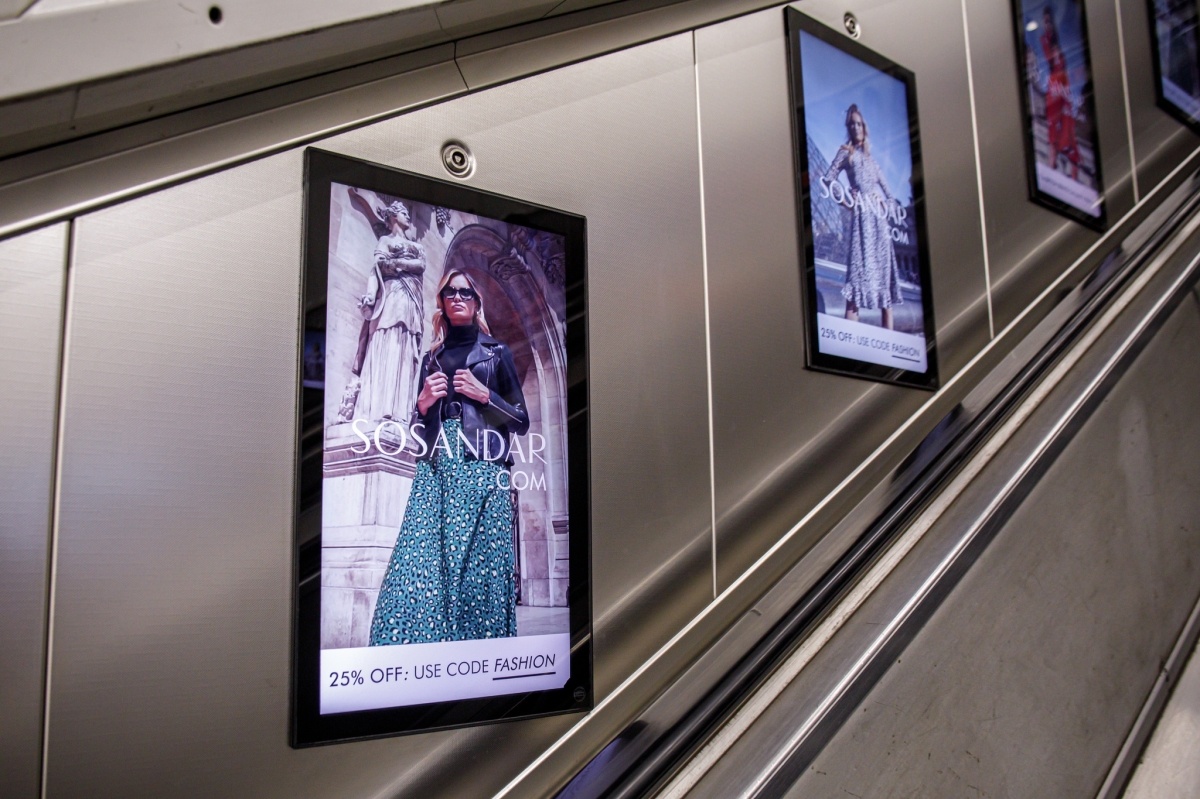
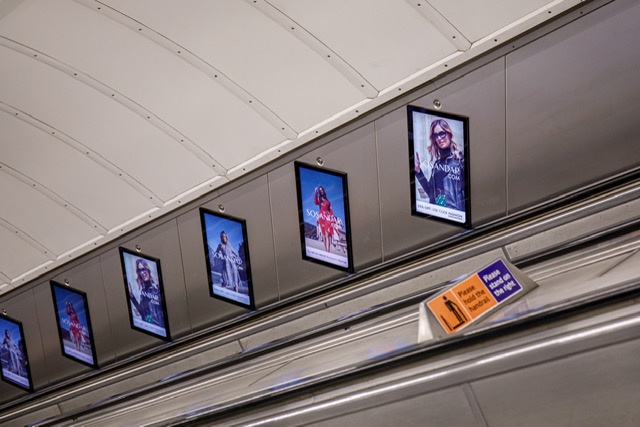
TV advertisement - There's also a Sosandar TV ad, which is being trialled. Here's the link to that short video.
The background of Sosandar's founders was in fashion magazines. You can see that in the quality of the company's photography & video imagery. It looks like a proper brand.
On to Wednesday morning's trading updates & results statements....
Readers like us to comment here on BooHoo, even though it's now a mid-cap:
Boohoo (LON:BOO)
Share price: 266p (pre-market open)
No. shares: 1160.7m
Market cap: £3,087.5m
Terrific figures today, from this multi-brand online fashion retailer.
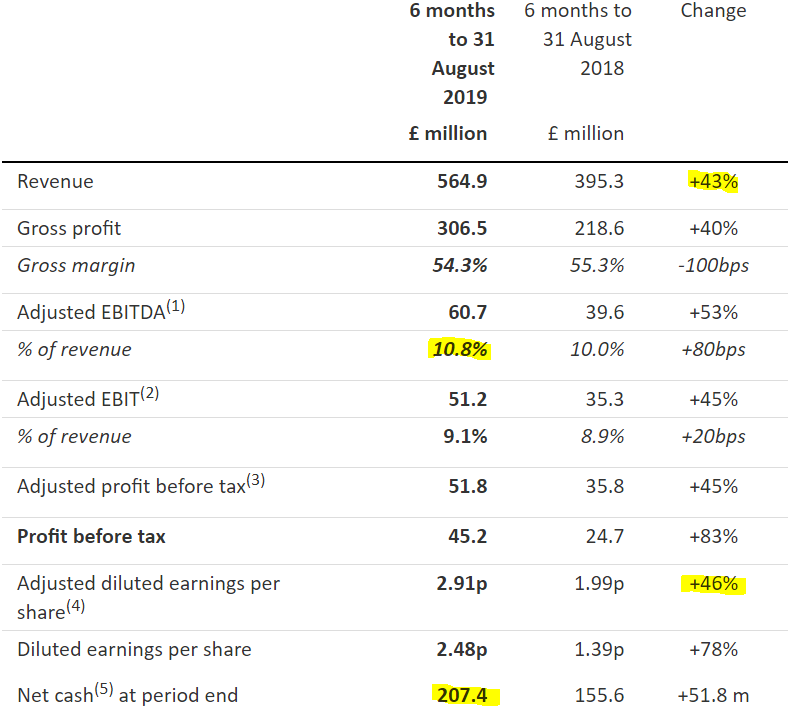
Graham covered its ahead of expectations update here on 5 Sept 2019. As you would expect, with such a recent update, today's figures & outlook are consistent with it.
Here's today's outlook guidance;
Group revenue growth for the year to 29 February 2020 is expected to be 33% to 38%, with adjusted EBITDA margin for the year to remain at around 10%, reflecting anticipated investments across the financial year into the three brands acquired by the group in the first half year.
We reiterate our medium term guidance to deliver revenue growth of at least 25% per annum and adjusted EBITDA margin of around 10%.
Given that H1 revenue growth was 43$, then the 33-38% full year forecast growth looks realistic - and could even be beaten, perhaps?
Valuation - the medium term guidance is very interesting. With ongoing growth of 25%, that almost doubles the size of the business in just 3 years. For that reason, the forward PER of 45 is really not expensive at all, in my view. Such strong growth, globally, easily justifies such a rating, in my view.
My opinion - things are going amazingly well for BooHoo. Every time it looks as if the growth rate is slowing, and the business is reaching maturity, it has a fresh burst of growth! Bolting on new brands (3 more added recently), and applying the BooHoo group's sourcing, logistics & marketing skills, adds another phase of growth after a time lag. For example, Nasty Gal reports 148% revenue growth as part of today's results.
BooHoo really is the stand-out online fashion retailer, and has completely eclipsed Asos in my view (which doesn't generate any free cashflow - indeed Asos is spending far more on capex than it's actually making in profit - a lousy business model).
With multiple brands, and global sales, BOO has plenty of scope for future growth. This is heading towards being a significant global business. As mentioned last time I reported on this company, it's very tempting to buy back in. The valuation looks perfectly reasonable to me, given that it's an absolutely exceptional, and still fast-growing group.
It's starting to look likely that BOO could join the FTSE 100 in the next year or two. Looking at the constituents here on Stockopedia's "Browse Indices" function, the lowest FTSE 100 market cap (Centrica) is £4.1bn, with Kingfisher next at £4.2bn. BOO is currently about £1bn short of that. Therefore next year we could see tracker funds being forced to buy BOO, taking the valuation up further, which is a nice catalyst.
EDIT: thanks to MrContrarian, who points out in the comments below, that BOO would have to transfer to a full listing, to get into the FTSE 100, as AIM companies can't join it.
Mission Marketing (LON:TMMG)
Share price: 82p (down 2.4% today, at 11:55)
No. shares: 85.3m
Market cap: £69.9m
The Mission Group plc ("MISSION", "the Group" or "the Company") is pleased to announce its unaudited interim results for the six months ended 30 June 2019 and sets out its new positioning.
Readers have asked me to look at this. It's a share I've covered a lot before, but not recently.
To bring us up to speed, Graham commented on its in line with expectations H1 trading update here on 15 July 2019.
I commented here on 25 Jan 2019 on its FY 12/2018 positive trading update. If you look at the chart, this is the update which triggered a rise from c.55p to c.80p.
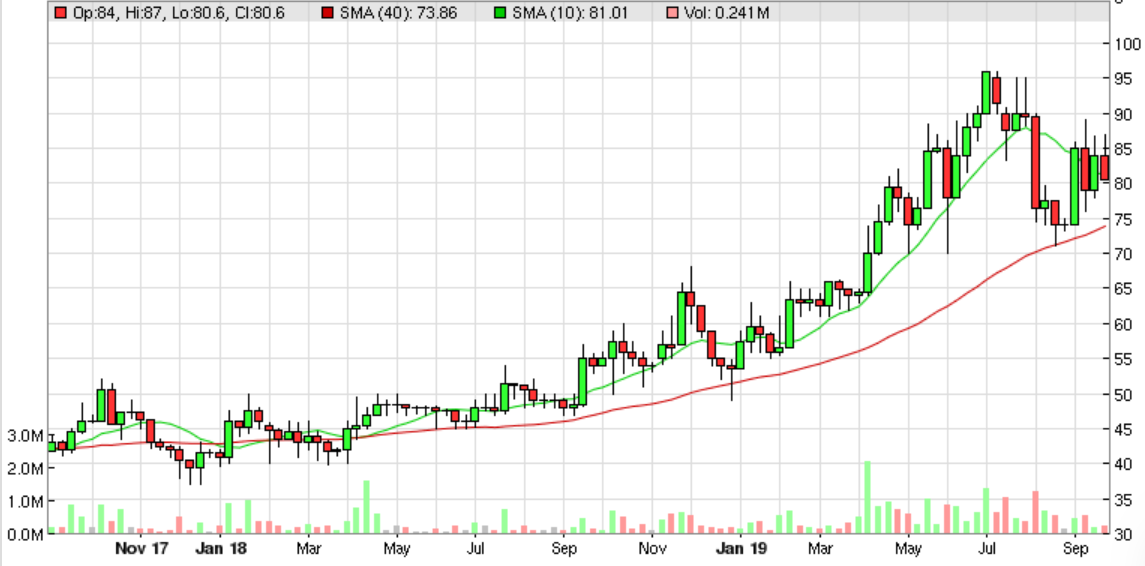
Here is the company's highlights section today;
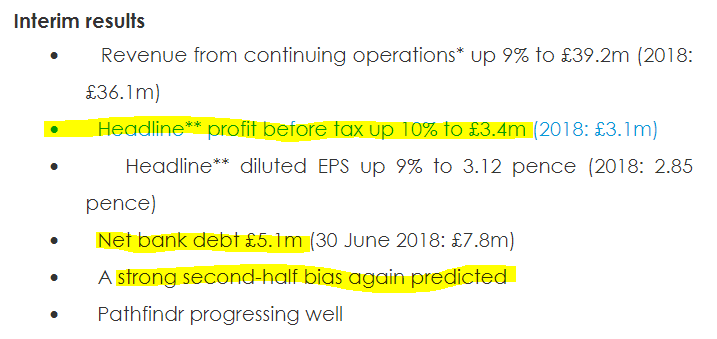
The 10% reported profit growth is consistent with the last trading update.
Are the adjustments to profit reasonable? The company says;
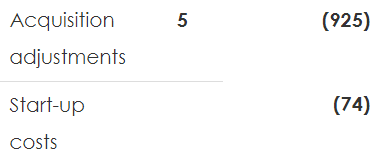
Adjustments to headline profits in 2019, at £1.0m, were higher than the prior year (2018: £0.6m) due to an increase in the estimate of future contingent consideration obligations. After these adjustments, reported profit before tax was £2.4m (2018: £2.5m).
Here are the adjustments this year;
Note 5 gives more detail;
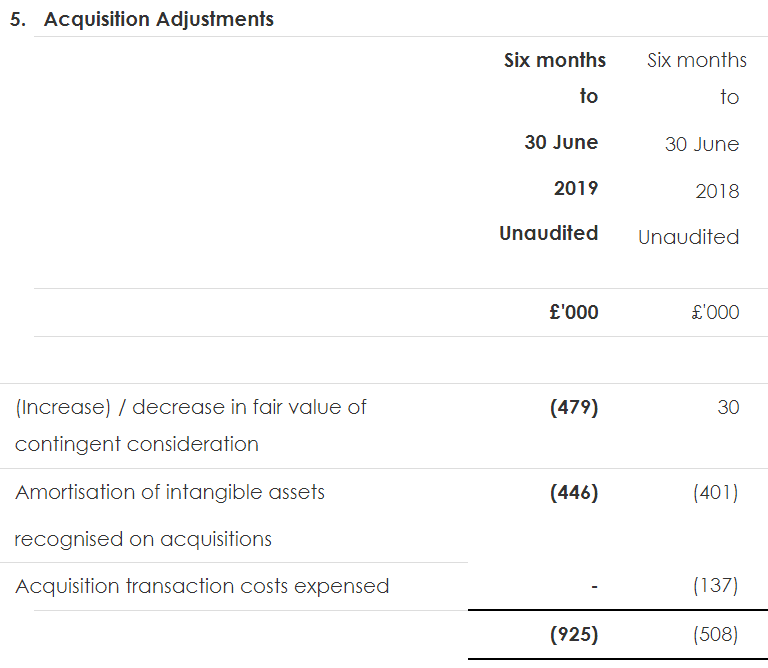
I think those items look fine to strip out, in providing an adjusted profit figure which more accurately reflects the underlying performance of the business.
It's standard practice for analysts to ignore amortisation relating to acquisitions, because it's just a book entry that has no cash effect on how the business is performing, or how it should be valued. It's only of passing historical interest.
Equally, any change in the creditor relating to contingent consideration (for acquisitions) is of interest, but it's not a trading cost. Investors do however need to check the balance sheet, and ensure that an acquisitive group can actually afford to pay out the contingent consideration that it's on the hook for.
Balance sheet - I've had reservations about TMMG's balance sheet in the past. How does it look now?
NAV is £89.9m, this is very overweight with intangibles, of £95.6m which seems to all relate to acquisitions.
NTAV: not good, it's negative, at -£5.7m - all I've done here is write off all intangible assets, so that the balance sheet would be comparable with an otherwise identical group which had grown organically, rather than through acquisition.
Working capital - adequate, but not good, with a current ratio of 1.10 (that's total current assets, divided by total current liabilities).
Acquisition liabilities - this is a significant issue. The company has to pay £2.4m within the next 12 months, and a further £5.9m in the following year. These are highly material figures, which are likely to push up net debt, if these sums cannot be generated in free cashflow (which looks unlikely to me).
Therefore the net debt of £5.1m (obviously I've ignored the irrelevant IFRS 16 lease liabilities) looks set to rise in the next 2 years by potentially quite a lot. Investors need to be fully aware of this point, and not get too comfortable with the current apparently low level of net debt. This matters because it means the company has little scope to pay out decent divis. I can't see the c.2.8% dividend yield going much higher, unless & until the substantial acquisition liabilities are paid off. I'm not sure if they have to be paid in cash, or shares, but the effect is fairly similar on existing shareholders - either less cash for divis, or dilution from the issue of new shares.
Bank loan - also, there is an £8m bank loan (within the £5.1m net debt total) which needs to be paid off or refinanced in 2-3 years. Put that together with the contingent acquisition liabilities, and the group needs to generate a lot of cashflow over the next 3 years, to clear these debts. It might be able to refinance with fresh bank facilities, but if we're going into a recession, then you can't count on that being certain. Remember how credit dried up in 2008.
Cashflow statement - the business looks genuinely cash generative. However, as mentioned above, this cash is being consumed mainly on paying for previous acquisitions, and repaying bank debt, plus a relatively modest amount for dividends.
Therefore, I feel that the divis are not necessarily safe, if the economy takes a downturn.
My opinion - the crucial issue here, is where are we in the economic cycle? The last thing investors should be doing, is buying into marketing companies if we're about to go into a downturn. They tend to be hit very hard, and early, in recessions, as clients cut back on discretionary spend. I don't know whether a recession is coming or not, but there are certainly storm clouds out there. So why take the risk?
Balance sheet risk is quite high too, because of the need to continue repaying the bank loan, and substantial deferred consideration liabilities falling due in the next couple of years.
Conventional marketing companies really don't interest me, as so much is moving online these days. The word "digital" is not mentioned once in today's commentary from the company. I would have expected to hear lots of stuff about what they are doing to expand into that exciting growth area.
Overall then, I can't get excited about this share at all. Sorry if that's not what you wanted to hear!
Stockopedia completely disagrees, and rates it a Super Stock, and has a super-high StockRank:
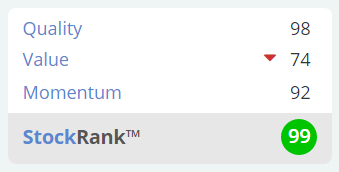
EDIT: please see the excellent reader comments below, which point out this company has one of those awful growth company share schemes.
Afternoon tea at Claridges
Some time ago, a very generous reader bought me a ticket for 2, to have afternoon tea, with a glass of champagne, at Claridges. I've booked it for 5:30pm this Friday, 27 Sept.
Would you like to join me? I've decided to auction the one guest place, to raise money for my favourite charity, ZANE, which I visited earlier this year, and saw at first hand what superb work they do to alleviate the suffering of about 4,000 destitute pensioners with simple food & medication micro grants, plus partnering in other projects such as curing club foot in babies, a women's refuge for victims of political violence in the townships, and other projects of great humanitarian good in Zimbabwe.
It's a remarkable little charity, of terrifically dedicated staff, and makes a relatively small amount of money go a long way. The situation in Zimbabwe is absolutely dire, with another bout of hyper-inflation having further destroyed living standards this year. Electricity is rationed to 10pm to 4am only, and running water doesn't work any more in lots of the country. Many people cannot afford to eat, let alone have any decent quality of life. So money donated to ZANE really does save lives - I met about 200 of the recipients earlier this year, and it's an unforgettable, very moving experience to have a wizened pensioner clasping your hands, and asking you to say thank you to the donors in the UK on their behalf.
If anyone fancies joining me for a very civilised afternoon tea (and then quite possibly a less civilised pub crawl afterwards!) this Friday, then message me through Stockopedia (or via email) with your bid (all the money to go directly to ZANE), within 24 hours please.
I'll then contact the highest bidder, and ask them to donate the agreed amount via ZANE's website & email me the receipt email from ZANE, then we're good to go.
I got this idea from another reader here, who contacted me and asked if I would meet him for lunch, if he donated £100 to ZANE. He wanted to pick my brains on various topics, and discuss financial stuff of interest to him (e.g. several shares, balance sheet concepts, etc). Of course I agreed to do it, and it went brilliantly - so much so that he's asked me to do 4 more such lunches, at £100 a pop for ZANE.
That got me thinking, that maybe someone would like to join me for afternoon tea & have me at your disposal to discuss anything you want, or just have a general natter, this Friday? If nobody's interested, that's fine, as I'll just invite a mate instead. But it would be nice to raise a bit for ZANE. Also, I enjoy meeting other investors & chatting about shares stuff.
So, anyone who is interested, please message me with the donation you're prepared to make to ZANE. The highest, hopefully generous, bid wins!
What else is on the agenda? A couple of brief comments;
Universe (LON:UNG)
5p per share, about £12.5m market cap, so too small to interest me unless there's something really exciting happening.
Interim figures today look OK, but not madly exciting. Balance sheet looks adequate, but not strong.
Why is this company listed? It looks too small, and not really generating much in the way of organic growth.
Hornby (LON:HRN)
A reassuring AGM trading update - H1 sales & margins are said to be up on last year, and in line with internal budgets. Warns about possible Brexit disruption, as heavily dependent on Xmas trading, which could be disrupted, maybe, if the ports experience disruption. Although why that would be the case, when authorities on both sides have already & repeatedly said that the flow of traffic will be paramount, I don't quite understand.
With such a poor track record, I find it too much of a stretch to see a worthwhile turnaround here, hence this share doesn't interest me.
Nice quip re Brexit from Hornby today;
We regret not producing a Brexit themed model. Our new grasp of social media has shown us that people are passionate about sharing their views on the topic. If the situation persists, we have plans for a locomotive that reliably gets stuck between stations. Please subscribe to our exciting new YouTube channel, "Signal Box" for updates: YouTube - Hornby Signal Box
This got me thinking about what other companies could do to innovate on the theme of Brexit? Looking at my watchlist for ideas;
Revolution Bars could do "The Brexit" cocktail - guaranteed to make you see red, rant incoherently about things you don't really understand, and fall out with most of your friends! Although their existing products arguably achieve that already!
Card Factory could start a range of greetings cards, to sympathise for Brexit Derangement Syndrome, as the UK has a collective mental breakdown.
Dart Group - their jet2holidays division could do mystery Brexit tours, ultimate destination unknown, but promising to fly you round in circles for 3 years+
LoopUp could launch a new Brexit service, the Endless LoopUp
That's probably enough of that for now!
Netcall (LON:NET)
This is another small cap that I struggle to understand. It spent a lovely cash pile on an acquisition which looks a questionable decision at this stage.
The share price has more than halved in the last year, from c.60p to only 25p today.
I've had a quick look through today's final accounts for FY 06/2019, and am left unimpressed. Adjusted EBITDA fell considerably, from £5.4m last time, to £3.4m this time.
The apparent near-doubling in operating profit doesn't stand up to scrutiny, as it benefits from one-off impairment costs in the previous year (providing a soft comparative for this year), and a favourable £865k benefit from favourable movement in contingent consideration liability this year but not last year, again flattering this year's figure.
The balance sheet is now weak, with NTAV negative, at £-7.3m
Hence the £36.5m market cap, at 25p per share, doesn't look a bargain to me. But there again, I don't really understand the business, nor its prospects. A brief review just confirms to me that it's probably not worth the time to dig any deeper.
Carclo (LON:CAR)
Some signs of life here;
The Technical Plastics ("CTP") and Aerospace Divisions have both performed ahead of expectations for the first five months of the current financial year, with CTP operating profits well ahead of the same period last year.
However, the deal-breaker for me is that the group has far too much debt still, and we don't know how much the problem Wipac division is going to be sold for (if it can be sold at all?)
Therefore, it's impossible to value this share. There's a very real risk of a 100% loss here for shareholders, hence I think risk:reward looks awful, and I wouldn't risk any money on it.
Alarmingly, the Group FD Designate, who only joined on 3 Sept 2019, has decided to leave on 27 Sept. That tells me everything I need to know. Hence this share seems uninvestable to me.
Scientific Digital Imaging (LON:SDI)
A reassuring update from this group;
The Group has made a good start to the new financial year. Despite the potential for economic headwinds, the Board is comfortable with current trading and in delivering financials in line with market expectations for the year. The Group continues to perform well and we look forward to updating the market further with our half year results in December 2019.
Forward PER of 13.9 looks good value.
Worthy of a closer look, in my opinion.
Card Factory (LON:CARD)
Share price: 180p
No. shares: 341.5m
Market cap: £614.7m
These figures were published yesterday, when Graham was on duty, but he ran out of time, and wasn't able to cover it. As retail is my sector specialism, I'll circle back to it. This share has been on my favourites list (although I don't personally hold any) as a sustainable high dividend yielding share, for some time, see my previous positive comments here about the company.
Card Factory, the UK's leading specialist retailer of greeting cards, dressings and gifts, announces its interim results for the six months ended 31 July 2019.
Graham reported on the company's H1 trading update here on 13 Aug 2019. Ah, I've just realised that I wrote that section for inclusion in Graham's article - I thought it sounded familiar!
Interim figures - I can't see any surprises here;
Revenue up 5.5% to £195.6m - most of the growth is coming from new store openings
Underlying profit before tax in H1 is down 7.9% to £22.0m - note the high profit margin of 11.2% of revenues, way above most retailers these days.
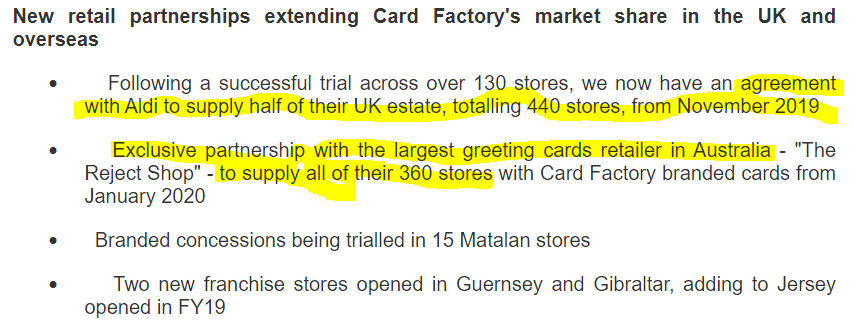
New retail partnerships - this strikes me as very pleasing (although no figures are given) - and this could trigger a re-rating, from CARD being seen as purely a retailer, to something altogether bigger, and more international maybe? That could be what has triggered a nice rise in share price yesterday and today, possibly? I'm guessing there.
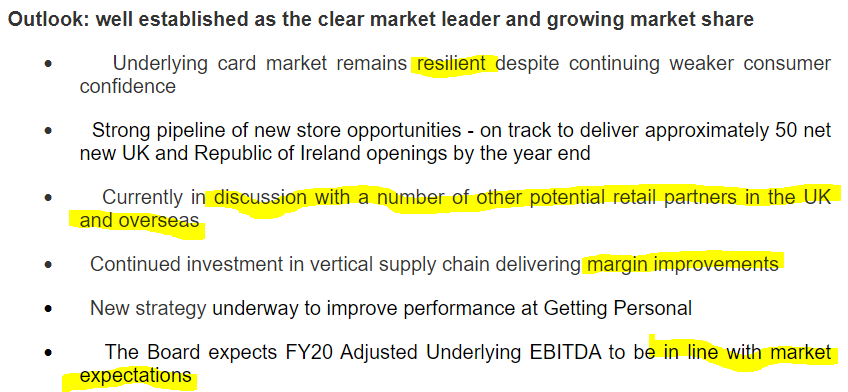
Outlook comments also sound pretty good, for a business that some investors seem to have almost written off as in terminal decline;
Dividends - I remain of the view (indeed probably strengthened after this RNS) that the high dividend yield looks safe. Interim of 2.9p is maintained, plus a 5.0p special divi declared.
There's more detail on dividend policy in the RNS.
Net debt - IFRS 16 has made a nonsense of the figures. I think the share price rise this week has demonstrated that investors are clearly ignoring IFRS 16 adjustments for the absurdity that they are. For example, here is the revised net debt for CARD;
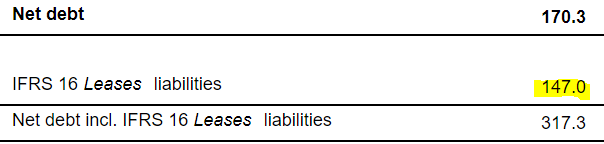
Tell me why any rational investor would treat future rental payments, on profitable shops, as a liability to be recognised now on the balance sheet? The leases are an asset, not a liability, if a company is trading profitably from that site. It's just ridiculous.
Also, if we're including contractual rent payments, then why not also include the business rates that will also be payable? Whilst we're at it, why not include all the utilities too? How about putting all future staff wages costs onto the balance sheet as a future liability too?
IFRS 16 just doesn't make any sense at all, and it should be scrapped. The old system of making a provision for onerous leases, when a company is trading at a loss from a particular site, was perfect. After all, it's only in that situation where the lease on a loss-making site is a commercial liability.
For my purposes, IFRS 16 doesn't exist. Just like the Supreme Court's treatment of the Government's proroguing of Parliament, I am simply going to treat IFRS 16 as if it hadn't happened, and reverse out all the entries relating to it, in my analysis.
Clearly the people who dream up accounting standards, need to open up their communication channels, and consult more widely with those of us who actually use accounts, and ask our opinions before implementing utterly ludicrous rules like IFRS 16. That said, I cannot say that accounting standards generally are bad, just this one instance where things have clearly gone badly wrong.
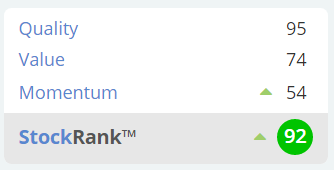
My opinion - is positive. This looks an excellent share for income seekers, e.g. SIPPs which are in drawdown. I think the divi yield looks long-term sustainable. The growth from new partnerships seems most encouraging, and may help improve perception of the company amongst investors. Therefore, as well as a cracking dividend yield, there's a good chance of a re-rating to give some capital growth as well, maybe.
A big thumbs up from Stockopedia too;
All done for today. Many thanks for dropping by, and for interesting reader comments.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Not sure if this is the correct place to put this so in case any others are following/interested in/own Boohoo (LON:BOO) :-
https://www.ft.com/content/ff604a6e-fb28-11e9-a354-36acbbb0d9b6
Update on Brady (LON:BRY) today - this sounds like it's finished - existing equity worth little to nothing, probably, in my opinion.
Why would anyone want to put £15m of fresh equity into this crock? If you've got shares in Brady, I would sell on the opening bell tomorrow, for anything you can get.
Great report yesterday Paul, excellent coverage, thank you.
cheers
Francis
Thanks Francis (and InvestorJohn above).
We're all human, so it's nice to get some positive feedback.
Equally, negative feedback just makes me want to down tools & not bother doing any more writing. Maybe the couple of idiots who like to give thumbs downs most days, might like to think about that?
Best wishes, Paul.
I’m afraid You’re on your own with that one
However I’m sure you’ll be out the weekend!
Thanks Paul for all your effort today top job!
Before IFRS 16 companies were selling and leasing back properties to inflate profits in the current year - also to meet executive bonus targets amongst other things.
IFRS16 requires the company to recognize the Right of use Asset as well as the RoU (PV) liability of the lease. This was the treatment for finance leases before the new standard too - it just applies to all leases now. This is the other reason they changed it as companies used to incorrect classify them.
The net effect on the balance sheet of the RoU asset and liability should provide a more true view.
I though the SOS advertising very strong, and their target market is underserved with an increasing propensity to buy online. (I work for a sort of competitor and see our key stats).
It’s an execution play on their ability to deliver relevant product to that base and based on what I see they are on the right path.
Partly due to Ed's profit warning webinar ( www.youtube.com/watch?v=YayTZn... ) when Coral Products (LON:CRU) issued a warning at 14 48 on Friday 12/1/18 I sold my entire holding. Pity I hadn't seen the webinar before the first warning on 27/1/17.
On 26th March this year we had PW no. 3: "... results for the year ending 30 April 2019 to be materially below both Management and Market Expectations".
Today we have number 4: "With four months of the current financial period completed, sales and profits are below management's expectations".
With net debt greater than MCap this is now in bargepole territory. Glad I got out when I did - thanks Ed.
No problem @sharw glad it's helped.
Maybe next summer we'll update the profit warning research again - we do an internship program and it helps with data gathering. It was a big project !
Ed,
I think a refresh on the Profit Warning Survival Guide would be an excellent addition. However I would really like to see it done in a different "market phase" so perhaps you could consider the timing against the state of the market.
At the time you published the PWSG I had just completed a similar analysis (mine was probably less robust, but covered a much longer period) which at face value gave almost diametrically opposed conclusions.
I assumed that my results were flawed, but when I tried to drill down I discovered that my results appeared to be unduly influenced by big gains at the start of a bull market.
At the time I did not really have the data resources to test this further but it would be useful hypothesis to follow up on.
Gromley
Keep up the good work
Try this
https://www.valuewalk.com/wp-content/uploads/2015/02/document-1043195371.pdf
Awesome thanks Taff,
That looks like a fascinating paper - can you explain to my kids why I won't be taking them out at the weekend? ;-)
hey Paul, I think it a wonderful idea to auction the afternoon at Claridges. Well done.....and good luck to ZANE
Paul
Re Sosandar (LON:SOS) tube advertising. It is impotrant to remember that the vast majority of the population and the target market do not commute on the London underground.
Richard
RichardK,
Re Sosandar (LON:SOS) tube advertising. It is impotrant to remember that the vast majority of the population and the target market do not commute on the London underground
Yes, that's a valid, if rather obvious point!
SOS is targeting its marketing spend into areas which are already proven as working. There's a lot of online fashion expertise in & around the Manchester area, due to BooHoo, MissGuided and other online fashion companies working there. Hence SOS has been able to tap into that expertise, to identify that tube adverts work well, which is why they are being trialled by Sosandar, along with other new marketing (such as targeted TV ads in regions, not national TV).
Regards, Paul.
True but from a Marketing perspective, if doesn't matter if only 0.000005% of the target audience walk past (or any tiny number to avoid discussion on this specific figure!).
What matters is: if they spend spend £10K on (London) tube adverts, do they get an incremental £50K of revenue from doing so. That will generate (simplifying again) at +/-50% gross margin , an incremental £25K gross profit less some (marketing) overhead to organize --> an extra $20K of profit.
They will also do the same for digital (national), the new regional TV advert (regional) etc, emails to bought address lists etc to reach the maximum people most efficiently. The Marketing art being to get the message and marketing right to reach and persuade at the lowest cost - used to be AIDA (awareness, interest, desire, action, with the ultimate action being a (re-)purchase!
Overall, I hope/expect £SOS are going to spend up to £2Mn this year on all forms of Marketing and generate revenues >£10Mn, using the money from the recent raise. As the revenue goes up, the spend should get more efficient eg £2Mn to generates >£18Mn in 2020 and after that stays at <10% of revenue whilst growing the business.
This is what will create a brand and scale to pull them out of the main pack to join other profitable and well known brands.
My experience was that Tube adverts work well - also ticket gates at mainline stations. TV worked well also but it's a short term thing - good boost while the ads run but you can get hooked on keeping them going.
I wasn't so keen on each SOS ad including a 25% off code - Fashion. That seems a bit needy to me?
The other issue with going to TV is that it lifts the customer expectations. You're saying you're one of the big grown up brands now, so you had better be ready to meet the customer service and quality levels that implies.
This is a very random, off-topic question, but does anyone know what the Companies House equivalents are in Canada and Australia? i.e. where can I check accounts in those countries? Wanting to look at non-public listed companies accounts for some research purposes.
For Aus this should be the starting point:
https://asic.gov.au/online-services/search-asics-registers/
Cheers
Andrew
https://www.gov.uk/government/publications/overseas-registries/overseas-registries
This may be helpful from UK Companies House?
For Canada, start here:
https://www.ic.gc.ca/app/scr/cc/CorporationsCanada/fdrlCrpSrch.html
1pm (LON:OPM)
Results today. Some marginal increase in revenue. Price edging up this morning. I hold a small number.
The thing that strikes me is their point about their brokering of a large proportion of deals originated.
"Of this origination, given the flexibility afforded by the hybrid lending and broking model and prevailing market conditions, 35% was funded on balance sheet and 65% was broked-on, compared with 44% and 56% respectively in the prior year. The Group's policy is to not carry residual balance sheet risk in respect of light commercial vehicles and cars and so 100% of all finance deals originated for such assets are broked-on. Excluding vehicle finance origination, 53% of new business was funded on balance sheet and 47% broked-on, compared with 60% and 40% respectively in the prior year illustrating the 'hybrid' operating model in action."
As a result of the high proportion of brokering the lending book actual fell slightly, from 141.7m compared with 143.9m in the prior year.
On one side, I see this as smart, they are only booking the deals that meet their criteria onto their own balance sheet and earn some commission from the declines. On the other side, it tells me they can't originate enough quality deals to grow their own book. Or, they think there is an SME recession coming in the UK and are waiting for that to pass over before growing again.
At a PER ratio of 4.6x much of the above is already priced in. So regardless I still hold, albeit a small position.
With regards to £SOS - you are investing in the ability of the management and their capability to grow revenues at pace, manage costs and keep churning out stylish clothing that will be in-demand. I had a small flutter recently when the price dipped below the placing price of 15p. However, I note that people in their target demographic who i have asked about buying clothes online have dismissed it and have given reasons such as 'difficult to return clothes', 'want to see and touch the fabric first' etc. I haven't spoken to many people but perhaps they will find it tougher going than the likes of BOOHOO whose target market have grown up buying clothes online?
(PS> how do you get the ticker to come up with the company name - it used to be put a £ in front?!)
Re £SOS - key here is the combination of their scale and core target market. As an ex-Mkting Dir, I think their strategy is a very smart one and has a good chance to succeed over time .
As a fully online company, logistics and distribution (and returns handling!) are outsourced to a specialist. They only need to get a turnover of only say £30mn pa to be very profitable by my calculations (albeit still small in the grand scheme of things). Margins are good and central costs outside Marketing are modest
They are focused on a specific niche of 'post fast fashion, above ave income 45-55 women'. Market size of this 45-55 group is bigger at £1.9Bn as women aged 16-24 (that BooHoo chase) as they have more spare cash. These women are completely happy to buy online and are doing it already, for range and convenience, given often long-hours, professional working lives. Think of top end of Next and its customer base. Indeed, I expect them to be selling on the Next platform in the coming 12months.
Given sufficient Marketing weight of spend and the right product range they should be able to get that £30mn pa turnover easily with the target audience who spent a lot per head and tend to be loyal and less price sensitive (if the product is any good).
Key risk IMHO is if a deep pocketed competitor with logistics & marketing muscle targets the same space either with their own or a bought in brand. £BOO 's moves towards a multi-brand, multi-lifestage business are a threat here (eg purchase of Karen Milen & Coast brands). Hence the sooner they establish the brand the better - so it was good news they took the extra equity sales for cash offer recently to help them drive scale.
I hold and am optimistic on a 24-36month basis.
Interested in your views on the Card Factory (LON:CARD) results from yesterday if you have time please. Market has reacted well.
Many thanks,
BIACS
Safestay SSTY half year report RNS today. Last commented SCVR by Paul Tues 5 Feb 2019. Thoughts?
Boohoo (LON:BOO) can't join the FTSE100 if it remains on AIM, which I think is quite likely. Would the founders want to give up the massive IHT benefit of being on AIM?
Saved me the trouble of pointing this out. Ultimately it constricts the market cap it can reach as there is limited capital that will go in to AIM. The lax regulations for large companies eventually becomes a red flag.
Perhaps AIM should have a maximum market cap above which companies are forced to convert to a main listing?
Perhaps they will look to split Pretty Little Thing off as part family owned and keep on AIM and let the majority of Boohoo eventually move to the main market
Hi MrContrarian,
Boohoo (LON:BOO) can't join the FTSE100 if it remains on AIM, which I think is quite likely. Would the founders want to give up the massive IHT benefit of being on AIM?
Thanks, that's a really good point. I'll mention this in the main article, with an edit.
Best wishes, Paul.
Immotion PLC (IMMO) released their interim results today.
Very exciting opportunity here. It’s a highly speculative investment as the stock ranks indicate, but the rewards if they get it right are significant. The company is loss making but on course to break even in Q1 2020. They provide “Out of Home” Virtual reality experiences. The market cap is £19.27 million.
After experimenting with various different business models, the company have settled on a partnership model. This model is extremely attractive to both parties. Immotion provide the hardware; the content; training and support at their cost. The partner provides the staff; space and footfall at their cost, with the revenue being shared 50/50.
This is a very attractive model for the partner because they are able to add a relevant VR visitor attraction to their site for no upfront capital cost, with an immediate exposure to new revenues. For Immotion the model is attractive because it enables them to have their VR experiences placed in areas of high footfall. Since the marketing and operation of the experience is carried out by the partner, there are very little costs for Immotion once the experience is in place. This affords exceptional operation gearing and profitability potential. Trading has been very promising. Year to date, the average gross revenue per headset per week was £320. This figure averaged £402 per week during the 6 week school holiday period. The partnership estate averaged £381 per week.
The model has attracted some very prestigious partners including the 02, Blackpool Tower, Madame Tussauds and Lego land. The company currently have a total installed base of 256 headsets with a further 33 to install in the next few weeks. They remain confident of reaching 400 installed headsets necessary to meet their short-term monthly objective of monthly EBITDA break-even in Q1 2020. The company have the goal of reaching 1000 headsets by the end of 2020. At an average revenue per headset of £320 that’s a weekly turnover of £320,000. The company have indicated that once they have 400 headsets in the field the revenue from each extra headset goes straight to the bottom line. If they achieve the milestone of 1000 headsets by Q4 2020 whilst maintaining their average revenue per headset, the numbers and profitability look very attractive indeed.
The company did a placing in August where they raised £2.4 million. They currently have £2.3 million in cash. The CEO has indicated they will not need to return to the market to raise more money. All further expansion will be funded from their cash flows.
I have a long position in this company. I think it offers an excellent opportunity to multi bag. I love the business model which is truly a win win for both Immotion and the partner. More importantly the business model makes it a very easy sale for the company. As an owner of a visitor attraction, why wouldn’t you want a VR experience installed at your site at virtually no cost? To achieve their goal of 1000 headsets the company’s strategy is to continue to focus their efforts on signing new partners, especially in the “Edutainment” sector, in both Europe and the USA. They have divided the market into 4 sectors: Aquariums, Zoos, Science Centres (“Edutainment”) and Entertainment. To date their focus has been on Entertainment and the Aquarium destinations within the Edutainment sector. Given the initial performance of the Aquarium offering this will be their focus for the remainder of 2019. I have taken a look at various reviews of their experiences on websites such as trip. They are very good. Here is a review of their offering in the O2 https://www.tripadvisor.co.uk/Attraction_Review-g186338-d17804644-Reviews-ImmotionVR-London_England.html
Another potential source of revenue could be in the sale of their ever-growing library of content to third parties. Immotion go to great lengths to provide high quality VR experiences. For their Aquarium experience they hired the “shark whisperer” who without the use of an oxygen tank filmed 2 experiences. One where he swam with sharks and another where he swam with humpback whales!
This is intended as just a quick introduction into the company. For further research, as a starting point, its well worth watching this recent video https://www.youtube.com/watch?v=9ymk2eDp7Rg
You should also visit their excellent website here: https://immotion.co.uk/
Re Mission Marketing (LON:TMMG)
If you want a lesson in how some companies tread a very fine line between being economical with the truth and deliberately misleading the market, compare Note 8 ('Earnings per share') in this year's Interim Report with the same note in 2018's Interim Report and then consider what's missing in the light of the RNS released by the company on 4 June regarding the company's Growth Share Scheme for senior management.
Ha ha ha. Great spot. I knew about the company's Growth Share Scheme, and didn't like it because they're issuing 5.7m Ordinary Shares to management based on the share price being above 75p. It did make me wonder how much I could trust management.
And now they have left out the number of shares in the EPS calculation this year ???
:-)
Mission Marketing (LON:TMMG)
I'm a fan. On the surface a good report today, price rose this morning but is falling back now. MM has had a good run and the chart looks like taking profits now, which I've done.
I'd be happy to buy again after the sellers have cleared out.
Yep - I'm interested in £TMMG too. Been a multi bagger, but nervous about the exposure to cut back in marketing spend when there's a downturn. Stockranks are giving many cyclical stocks a high rating at the moment, so useful to know thoughts on when to sell high stock rank firms.
Tremor International (TRMR) H1 19 results webcast by Ofer Druker, who runs through H1 results, operational update and outlook.
https://www.piworld.co.uk/2019/09/25/tremor-international-trmr-h1-19-results-webcast/
Tremor International (LON:TRMR) H1 19 results webcast, following results yesterday.
Here, Ofer Druker, CEO, runs through H1 results, operational update and outlook.
Hi Paul,
£OPM (are other finding the tickers are hit and miss?) announced FY results which on first skim look pretty good. Graham thought is was "fairly" priced back in Jan at 46p. It's 32.76p as I write and to me appears to offer good value, and today adds a nicely raised dividend. Theres's 1% write off's and raised provision for future bad debts to 1.9%. Too low?
hi Paul, if you have time would you be able to circle back to £trmr and £flo (they issued updates yesterday, which resulted in their share prices diving and the recovering (especially £trmr)
Paul, please can you cover Ergomed (LON:ERGO) interim results? Turnover is up 36.8% and order backlog up 27%, EBITDA of £6m (vs £0m), improved gross margin, and basic eps of 7.8p (without too much adjusting going on) all looks quite good to me and hardly pushing the valuation too far IMHO
Hi andrea34l,
Apologies, I didn't get round to looking at Ergomed (LON:ERGO)
On a very quick skim of the figures, it does look like a remarkable turnaround in profitability, from previous losses. It's not a company I've ever looked at before here in the SCVRs, and being a pharmaceutical sector (which is not a sector I normally look at), don't feel confident that I could write anything worthwhile about it.
The balance sheet looks OK, and the cashflow statement seems OK too - e.g. very little development spend being capitalised (only £276k).
All in all, for subscribers that have some sector expertise, I think ERGO looks worthy of a closer look. Key questions might include: are these greatly increased profits sustainable? What's driving them? What can this company do that competitors can't?
Regards, Paul.
Hi Paul,
Congratulations on your (and Graham’s) excellent narratives in these Small Cap reports.
Like you I also contacted Sosandar yesterday. I had to use their general email address as I could not find a dedicated investor relations email address anywhere.
My message to Sosandar was to find out whether they are using (or planning to use) a “Smart Tag” system - such as the one featured in the Daily Mail of 21 September - to fight back against serial returns of clothes after they have been used.
Unlike you I did not get a reply to my query.
Positive trading update from Halma (LON:HLMA). None of the words recession, macro-economic, headwinds, or political uncertainty are used. A lesson there?
A second for Mission Marketing (LON:TMMG) please Paul
Can we please have your views on Mission Marketing (LON:TMMG) (soon to be the mission group) please? Profits up reasonably, dividend too, but debt drastically reduced _ a reorganisation in the works. I hold a bit. Thanks Paul!
My morning smallcap tweet: Coral eroding.
Coral Products (LON:CRU), Carclo (LON:CAR), Hornby (LON:HRN)
Coral Products (CRU) 4 months trading: sales and profits are below management's expectations. "New business is expected to impact during the second half together with the management action taken, leads us to expect to still report a satisfactory outcome for the year."
Carclo (CAR) trading: Technical Plastics and Aerospace divs performed ahead of expectations. Still trying to get shot of Wipac following the mess they made of it. FD designate changes his mind and scarpers. Finds replacement.
Hornby (HRN) AGM stmt : "We regret not producing a Brexit themed model...If the situation persists, we have plans for a locomotive that reliably gets stuck between stations."
Sounds like SOS is apt considering the share performance and the Stock Rank!
SOS share price has perked up since the recent update, and is now back above the IPO price (and more recent placing price) of 15p. It's a speculative, early stage share, I think everyone understands that - so volatility is the name of the game. High risk, but potentially high reward, if they succeed in reaching scale & profitability.
You're right though that the StockRank system hates this type of loss-making, speculative share, with a dismal StockRank of only 3. That's a useful reminder that this type of share is high risk.